
 Global TV Analytics Market | 2026-2036
Global TV Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global TV Analytics Market Foresight
The gap between linear television measurement and digital attribution is narrowing as automatic content recognition and real-time bidding protocols merge into unified data fabrics. The Nielsen Company leverages its panel-based heritage to sustain credibility among broadcasters seeking currency-grade metrics. Comscore anchors its competitive stance through set-top box integrations that span traditional and streaming environments. Google dominates cross-platform ad measurement by extending its DV360 and YouTube data pipelines into living room screens.
TV Analytics encompasses the collection, processing, and interpretation of viewership data across broadcast, cable, satellite, and internet-delivered television platforms, employing technologies such as audio fingerprinting, pixel tracking, and return path data aggregation to correlate content exposure with audience behavior and advertising outcomes. The primary commercial purpose is to optimize media planning, inventory pricing, and content investment decisions for programmers and advertisers operating in fragmented consumption environments. Cloud-based deployment leads solution architecture as broadcasters abandon capital-intensive on-premise infrastructure, while ad effectiveness solutions capture margin pools by proving return on ad spend across converged TV and digital video campaigns. Audience segmentation tools are gaining structural importance as addressable advertising scales beyond early adopters into mainstream network sales.
FCC guidelines on privacy and data consent shape how U.S.-based measurement firms collect household-level viewing information, while GDPR and the EU AI Act impose strict boundaries on automated profiling and cross-border data flows for European operations. Brazil's ANVISA and the country's national data protection authority add compliance layers for Latin American expansions. Stakeholders must monitor how regulatory fragmentation between the United States, Europe, and emerging markets affects the portability of analytics models and the viability of global measurement standards.
Market Dynamics
Automatic content recognition technology is collapsing the latency between linear broadcast and digital attribution, forcing measurement vendors to rebuild data pipelines around real-time signal processing rather than delayed panel reporting.
Growth Catalysts
- Addressable advertising infrastructure:Connected TV penetration in Brazil, India, and the United States creates deterministic household-level targeting capabilities that legacy panel methods cannot replicate.
- GDPR compliance frameworks:European broadcasters are investing in privacy-preserving measurement architectures that aggregate viewership without individual profiling, opening new vendor categories.
- Return path data aggregation:Set-top box and smart TV telemetry streams now capture second-by-second engagement signals that correlate content exposure with purchase behavior.
Market Restraints
- Cloud infrastructure concentration:AWS, Google Cloud, and Microsoft Azure dominate data processing capacity, creating single-point-of-failure risk for analytics platforms handling petabyte-scale viewership feeds.
- Cross-border data friction:The EU AI Act restricts automated profiling for audience segmentation, forcing measurement firms to maintain separate technical stacks for European operations.
- Linear panel cost rigidity:Nielsen's people-meter infrastructure requires fixed-cost field operations that resist the variable-cost economics of digital-first competitors.
Strategic Opportunities
- Retail media convergence:Walmart, Amazon, and Tesco are building closed-loop attribution systems that link CTV exposure to in-store and online purchase data.
- India's TRAI mandate:The country's broadcast regulator is pushing standardized audience measurement frameworks that favor transparent, algorithmic methods over opaque panel systems.
- Audio fingerprinting + AI:The convergence of acoustic content identification with generative AI enables real-time creative optimization and competitive ad intelligence.
Industry Challenges
- Data engineering talent scarcity:The intersection of streaming video protocols, distributed systems architecture, and statistical inference requires skill sets concentrated at major technology platforms.
- Legacy system integration:Broadcast sales teams operate on decades-old inventory management platforms that resist API connections to modern analytics dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global TV Analytics Market |
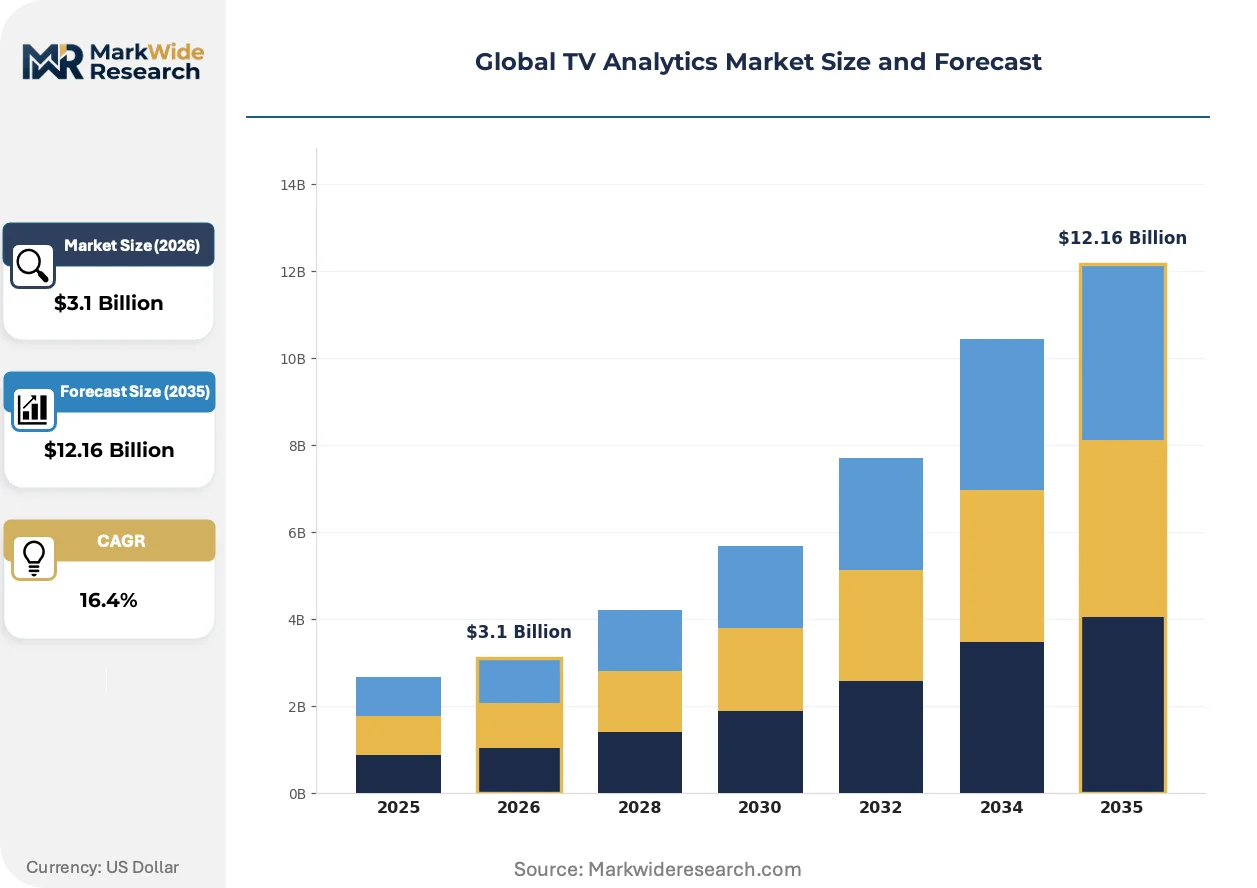
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $12.16 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing, SaaS Solution Type: Viewership Measurement, Ad Effectiveness, Content Recommendation, Sentiment Analysis, Audience Segmentation Use Case: Broadcast Monitoring, Subscriber Analytics, Advertising Optimization, Programming Strategy, Customer Retention Customer Type: Broadcasters, TV Networks, OTT Platforms, Advertising Agencies, Market Researchers |
| Companies Covered | The Nielsen Company, Comscore, Samba TV, iSpot.tv, IBM, Google, Alphonso, TVSQUARED, Amobee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global TV Analytics Market Shifts & Advancements
Real-time bidding protocols are migrating from desktop and mobile video into connected television environments, compressing the planning cycle from weeks to milliseconds and demanding new infrastructure investments.
Automatic content recognition is digitizing the relationship between content exposure and commercial outcomes by matching audio signatures across live broadcast, time-shifted viewing, and streaming platforms. Programmatic buyers at major agencies are adopting ACR-verified audiences as currency for cross-screen campaigns. The technology is digitizing how advertisers value inventory, collapsing the premium historically assigned to live linear into parity with addressable streaming.
The EU AI Act imposes strict documentation requirements for algorithmic audience segmentation used in programmatic advertising. European broadcasters must maintain audit trails for training data and model decisions affecting ad targeting. French and German publishers are responding by building first-party data cooperatives that reduce dependence on probabilistic inference.
Agency holding companies are consolidating measurement vendor relationships around fewer partners capable of unified linear-digital reporting. The traditional separation between TV buying desks and digital trading teams is dissolving as procurement mandates single-source accountability for reach and frequency. This consolidation is most visible in the United States, where the largest advertisers now require cross-platform verification for all video investments exceeding defined thresholds.
Global TV Analytics Market Segmentation
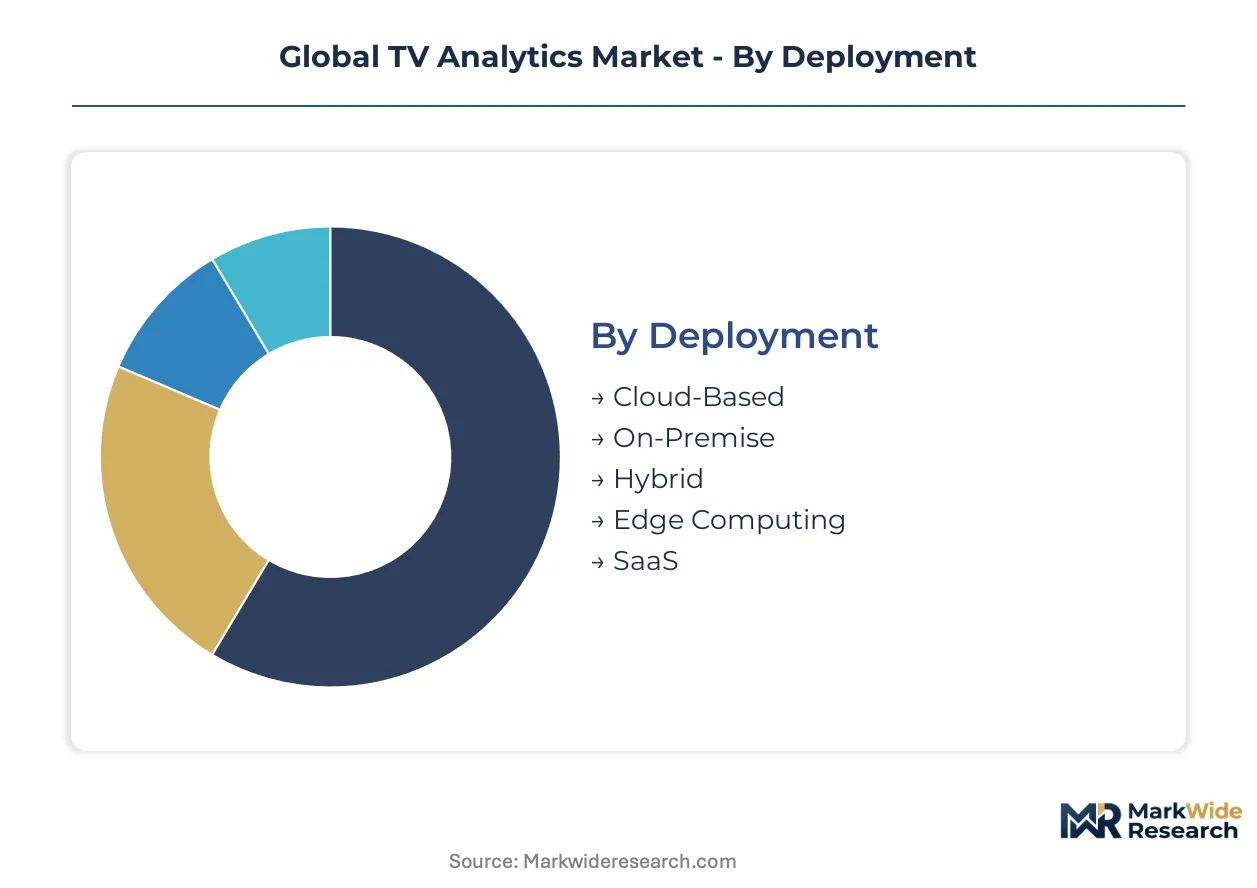
TV Analytics vendors structure their offerings around distinct operational architectures, analytical functions, and buyer profiles. Each segmentation axis reveals different margin pools, integration requirements, and competitive dynamics across the value chain.
Deployment:
After-sales service intensity varies dramatically by deployment model, with cloud-native architectures demanding continuous platform updates and edge computing requiring field-level hardware maintenance.
- Cloud-Based:Multi-tenant SaaS architectures enable broadcasters to offload infrastructure management to hyperscale providers. Demand concentrates among mid-tier networks in India and Brazil seeking to bypass capital expenditure cycles while scaling connected TV measurement.
- On-Premise:Dedicated server installations within broadcaster facilities retain full data sovereignty. Major U.S. networks with legacy Nielsen integrations favor this model to satisfy FCC audit requirements and maintain panel data control.
- Hybrid:Split architectures process sensitive viewership data locally while pushing aggregated analytics to cloud dashboards.
- Edge Computing:Real-time processing units deployed at cable head-ends or smart TV firmware layers.
- SaaS:Pre-configured software subscriptions with standardized API connections to ad servers and content management systems.
Cloud-Based deployments hold the largest share; momentum sits with Edge Computing as latency requirements tighten for real-time bidding applications.
Solution Type:
Cost tier differentiation separates premium algorithmic solutions from standardized reporting tools, with pricing scaling according to data granularity and predictive capabilities.
- Viewership Measurement:Panel calibration, set-top box aggregation, and automatic content recognition systems quantify audience exposure across linear and streaming platforms. European broadcasters under GDPR and EU AI Act constraints are driving demand for privacy-preserving aggregation methods.
- Ad Effectiveness:Attribution models correlate CTV exposure with downstream purchase behavior through retail data partnerships. Walmart and Amazon are building closed-loop systems that bypass traditional measurement vendors entirely.
- Content Recommendation:Machine learning engines personalize programming guides and streaming interfaces based on viewing history.
- Sentiment Analysis:Natural language processing of social media and second-screen commentary to gauge audience emotional response.
- Audience Segmentation:Algorithmic clustering of households by viewing patterns, purchase propensity, and demographic proxies.
Viewership Measurement commands the deepest buyer relationships; Ad Effectiveness is expanding most quickly as retail media networks validate cross-channel attribution.
Use Case:
Application maturity determines vendor selection criteria, with broadcast monitoring representing established practice and customer retention analytics still proving ROI.
- Broadcast Monitoring:Real-time signal quality, competitive ad tracking, and content compliance verification. TRAI-mandated transparency requirements in India favor algorithmic monitoring over opaque panel systems.
- Subscriber Analytics:Churn prediction, lifetime value modeling, and content affinity scoring for streaming services.
- Advertising Optimization:Inventory pricing, yield management, and programmatic deal construction.
- Programming Strategy:Content acquisition decisions, scheduling optimization, and franchise extension planning.
- Customer Retention:Intervention triggers, personalized promotion delivery, and win-back campaign targeting.
Broadcast Monitoring retains the most standardized procurement; Advertising Optimization shows the steepest expansion trajectory as real-time bidding protocols migrate to connected television.
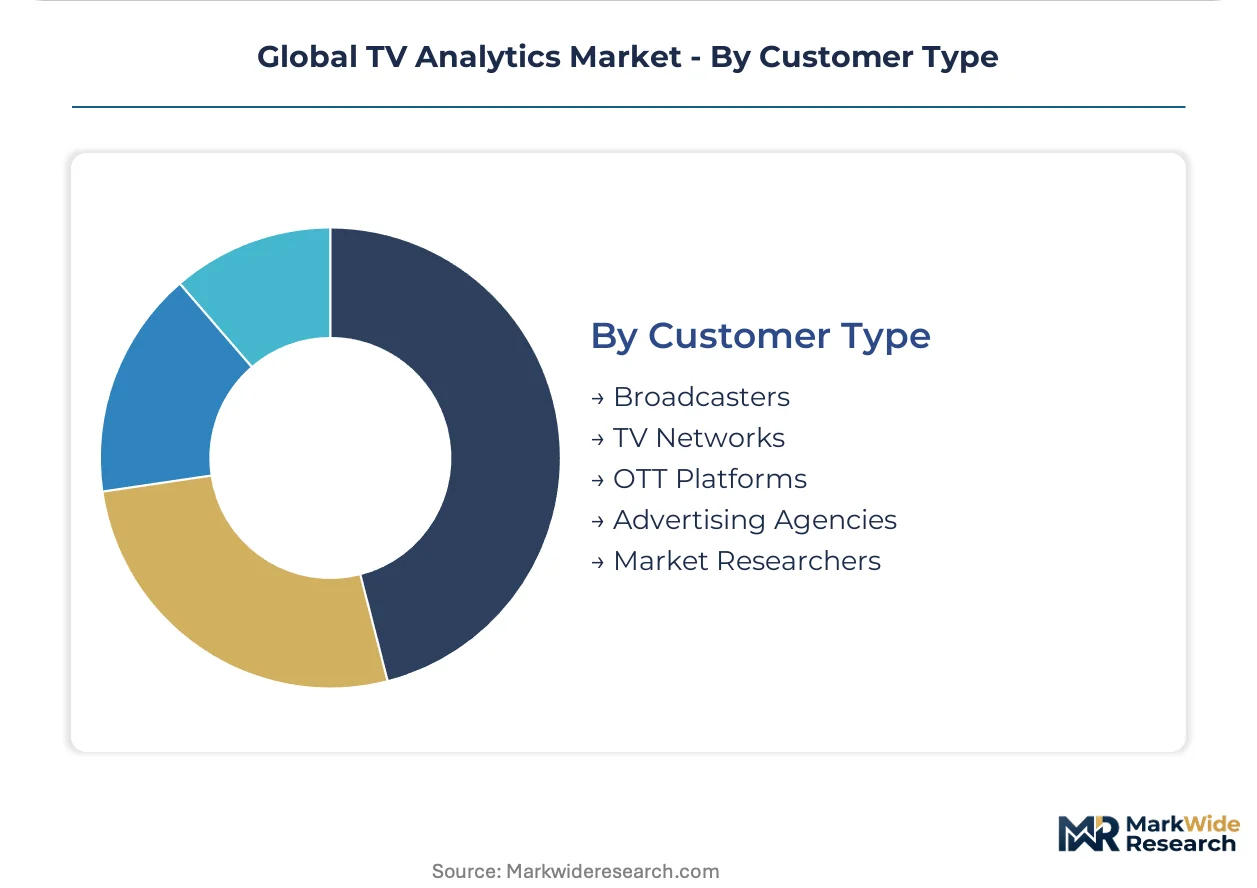
Customer Type:
Volume concentration among streaming platforms is restructuring vendor account management, with OTT buyers demanding faster implementation cycles than traditional broadcasters.
- Broadcasters:National and regional television stations requiring currency-grade measurement for ad sales. U.S. broadcasters maintain the most complex requirements spanning linear, digital, and addressable inventory.
- TV Networks:Multi-channel programmers with portfolio-wide analytics spanning entertainment, news, and sports verticals.
- OTT Platforms:Subscription and ad-supported streaming services operating without legacy infrastructure constraints.
- Advertising Agencies:Media buying groups consolidating around unified measurement vendors for cross-platform verification.
- Market Researchers:Syndicated data providers and academic institutions accessing anonymized viewership datasets.
Broadcasters represent the most entrenched vendor relationships; OTT Platforms are gaining share fastest as connected TV penetration scales in Brazil and India.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial analytics services trade surplus as domestic platforms export measurement methodologies to broadcasters in Brazil and India. European operators import privacy-preserving architectures from Israeli and U.S. engineering centers. Asian markets remain net importers of core analytics infrastructure while building localized data processing capacity.
United States
Connected TV penetration exceeds eighty percent of broadband households, driving deterministic addressable advertising at scale. The FCC mandates strict audit trails for household-level viewing data collection under cable privacy rules. New York and Los Angeles anchor the vendor ecosystem, with measurement firms clustering near major broadcast network headquarters and advertising agency holding companies.
Brazil
Smart TV adoption accelerates through retail financing programs, creating addressable inventory pools previously unavailable to national advertisers. ANVISA and the national data protection authority impose layered consent requirements for cross-screen measurement. São Paulo concentrates the domestic analytics vendor base, with local integrators building middleware between global platforms and regional broadcasters.
India
TRAI mandates algorithmic transparency in audience measurement, displacing legacy panel methodologies with deterministic set-top box aggregation. The regulator's push for standardized metrics favors vendors with real-time data processing capabilities. Mumbai and Bengaluru host competing engineering centers, with the latter specializing in machine learning pipelines for content recommendation engines.
Germany
Broadcasters invest heavily in privacy-preserving measurement architectures to satisfy GDPR and EU AI Act documentation requirements for algorithmic ad targeting. The CSRD extends audit obligations to data supply chains used for audience segmentation. Munich and Cologne house measurement engineering clusters serving public and private broadcasters across German-speaking Europe.
United Kingdom
Agency consolidation around unified measurement vendors accelerates as procurement mandates single-source accountability for cross-platform video investments. Ofcom reviews broadcast measurement licenses with emphasis on streaming inclusion. London dominates vendor account management functions, with technical development distributed across engineering centers in Manchester and Edinburgh.
Global TV Analytics Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers as agency procurement mandates reduce vendor fragmentation. Panel-based incumbents with currency-grade credentials anchor broadcaster relationships, while digital-native platforms capture streaming-first budgets. Technology conglomerates with cloud infrastructure and advertising exchange assets represent a third force. Competitive moves center on M&A to acquire automatic content recognition capabilities and strategic partnerships with retail media networks for closed-loop attribution.
Within the panel heritage tier, The Nielsen Company exemplifies the currency-grade positioning that broadcasters require for upfront sales negotiations. Comscore occupies a position bridging traditional set-top box aggregation with streaming measurement, reflecting the hybrid infrastructure demands of U.S. cable operators. Google anchors the platform-native archetype, leveraging DV360 and YouTube data pipelines to dominate cross-platform ad verification for programmatic buyers.
| Leading Market Players |
|---|
| The Nielsen Company |
| Comscore |
| Samba TV |
| iSpot.tv |
| IBM |
| Alphonso |
| TVSQUARED |
| Amobee |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure in the United States concentrates upstream processing capacity for TV Analytics platforms, directing margin pools toward vendors with direct API integrations to AWS, Google Cloud, and Microsoft Azure rather than middleware-dependent competitors.
Pricing Analysis
Advertising agencies anchor pricing structures around outcome-based contracts that tie vendor fees to verified cross-platform reach metrics. Three-tier pricing separates currency-grade measurement from mid-market analytics and self-serve dashboard tiers, with differentiation driven by data granularity and panel calibration depth. Pricing pressure stems from retail media networks building closed-loop attribution in-house, bypassing traditional vendor relationships entirely. Mid-tier broadcasters in India and Brazil exhibit highest price sensitivity due to capital constraints, while U.S. network upfront buyers accept premium tiers for Nielsen currency validation.
Supply Chain Analysis
Extended payment terms from advertising agency holding companies compress working capital for analytics vendors, forcing reliance on supply-chain finance facilities. Processing hardware concentrates in Taiwan, South Korea, and the United States, while specialized ACR sensor components draw from Israeli and German engineering centers. Single-source vulnerability runs through smart TV firmware partnerships that gate access to return path data streams. Distribution runs through direct enterprise sales teams for broadcasters and self-serve platforms for emerging OTT buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TV Analytics is approaching a platform-economics inflection as interoperability mandates from India's TRAI and Europe's GDPR force vendor consolidation around unified data fabrics rather than proprietary measurement silos.
For Market Incumbents: Entrench currency-grade credibility through automatic content recognition patent acquisitions and exclusive set-top box integration renewals with U.S. cable operators. The threat of Google and Amazon building closed-loop retail media attribution demands defensive partnerships with Walmart and Tesco to preserve third-party measurement relevance. Vertical integration into edge computing hardware at cable head-ends reinforces technical moats against cloud-native challengers.
For New Entrants and Emerging Players: Build out privacy-preserving aggregation architectures for European broadcasters navigating EU AI Act documentation requirements, as established vendors maintain separate legacy stacks for compliance. Brazil's addressable advertising infrastructure expansion offers the most penetrable geography, with local integrator partnerships providing regulatory navigation and broadcaster relationships. A direct-to-broadcaster SaaS model bypasses agency procurement consolidation.
For Investors and Strategic Acquirers: Capital is best deployed toward algorithmic measurement specialists with deterministic set-top box data pipelines and transparent audit methodologies favored by India's TRAI mandates. Long-term viability hinges on interoperability certification across converged linear-digital environments. The signal to watch is agency holding company procurement consolidation around single-source verification vendors, which will determine which measurement platforms achieve scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Automatic Content Recognition Patent Acquisition | Secures technical differentiation as ACR becomes currency for cross-screen campaigns. |
| Retail Media Network Partnership | Preserves third-party measurement relevance against Amazon and Walmart closed-loop systems. |
| Privacy-Preserving Architecture Development | Opens European market access under GDPR and EU AI Act algorithmic documentation requirements. |
| Edge Computing Hardware Integration | Reduces latency for real-time bidding protocols migrating into connected television environments. |
| TRAI-Compliant Algorithmic Certification | Captures share in India's mandated transition from opaque panel to transparent measurement systems. |
Research Methodology
Operator-level perspectives from broadcast network CTOs, advertising agency trading desk heads, streaming platform data science directors, and regulatory affairs leads anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from TRAI consultation papers, FCC cable privacy rulemakings, EU AI Act implementation guidance, and hyperscaler capex disclosures. Bottom-up triangulation across deployment models, solution types, and customer segments converged with top-down market sizing from connected TV penetration databases and set-top box shipment records.
Scenario-bracketing around regulatory implementation timelines and retail media network buildout rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution function, use case maturity, and customer infrastructure heritage. CAGRs derived from elasticity analysis of connected TV ad spend against measurement vendor contract values, with inputs from automatic content recognition adoption curves and addressable advertising inventory expansion in Brazil and India.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Amazon and Google to internalize measurement functions would shift outcomes. Macroeconomic contraction in advertising spend, regulatory fragmentation between GDPR and FCC regimes, or breakthroughs in differential privacy could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Social Media Analytics
Social Media Analytics Market
Social Media Analytics
Social Media Management Market
Social Media Analytics
Social Media Listening Market
Social Media Analytics
Media Monitoring Tools Market
Social Media Analytics
Germany Social Media Management Market
Social Media Analytics
US Social Media Management Market
Social Media Analytics
Social Advertising Tools Market
Social Media Analytics
Audience Intelligence Platforms Market
Social Media Analytics
Global Audience Analytics Market
Social Media Analytics
China Social Media Management Market
Social Media Analytics
Italy Social Media Management Market
Social Media Analytics
Social Media Records Management Market
Social Media Analytics
Brazil Social Media Management Market
Social Media Analytics
Europe Social Media Management Market
Social Media Analytics
Europe Social Media Analytics Market