
 Hydrocarbons Accounting Solution Market | 2026-2036
Hydrocarbons Accounting Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbons Accounting Solution Market Foresight
Subscription-based revenue for cloud-native allocation engines is pivoting how vendors monetize hydrocarbon accounting, shifting from perpetual licenses to recurring consumption models tied to well-count or barrel throughput. SAP leverages its S/4HANA oil and gas module to anchor enterprise-wide hydrocarbon accounting for supermajors with complex downstream integration. EnergySys specializes in configurable allocation formulas for North Sea operators navigating joint-venture equity splits. P2 Energy Solutions dominates the on-premises installed base among Permian independents seeking direct database control over production data.
Hydrocarbons accounting solutions are software platforms that automate the measurement, allocation, and valuation of crude oil, natural gas, and natural gas liquids across upstream production, midstream gathering, and downstream processing boundaries, employing standardized volume balancing algorithms and API gravity correction factors to ensure custody transfer accuracy. Cloud-based deployment leads in new bookings as operators prioritize remote accessibility for geographically dispersed assets, while AI-powered anomaly detection represents the fastest-expanding technology segment by addressing revenue leakage from misallocated commingled streams. On-premises installations retain margin concentration among national oil companies with stringent data sovereignty requirements.
The US EPA greenhouse gas reporting program and the EU methane emissions regulation impose auditable measurement and reconciliation obligations that directly shape software procurement criteria for operators in both jurisdictions. ISO 14064-1 greenhouse gas accounting standards and the WTO Agreement on Technical Barriers to Trade further influence cross-border platform interoperability requirements. Stakeholders must monitor how evolving carbon border adjustment mechanisms will force integration of emissions data directly into hydrocarbon valuation workflows.
Market Dynamics
Upstream operators are abandoning spreadsheet-based allocation methods en masse as auditable measurement infrastructure becomes non-negotiable under tightening emissions regulations. The shift toward cloud-native platforms is compressing deployment cycles and forcing legacy vendors to rearchitect their delivery models around recurring consumption rather than perpetual licenses.
Growth Catalysts
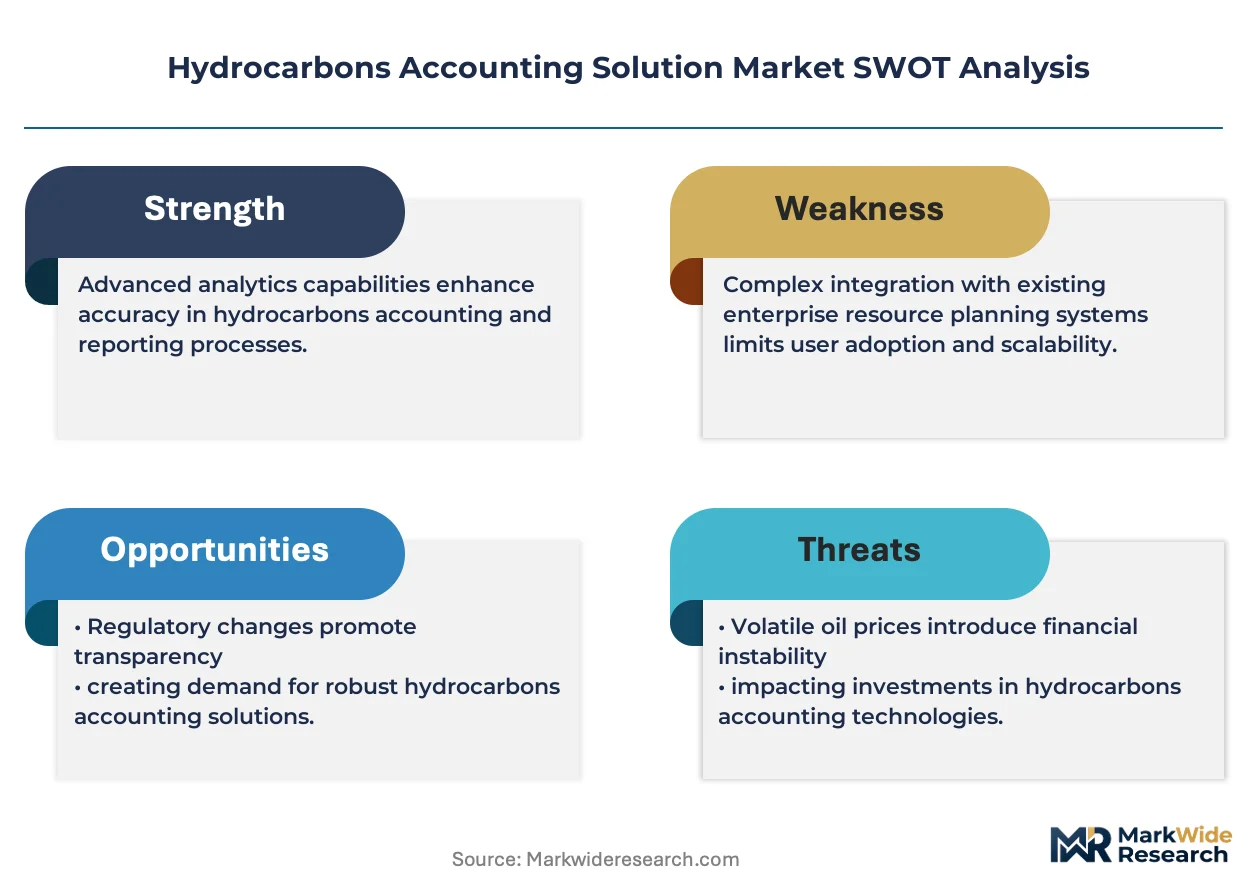
- US EPA methane reporting mandates:Operators must install auditable measurement systems that automatically reconcile production volumes against emissions data, driving replacement of manual reconciliation workflows.
- Multi-basin consolidation:Permian independents acquiring assets across Texas, New Mexico, and Oklahoma require unified allocation platforms that standardize equity splits and custody transfer calculations.
- API gravity correction automation:Real-time density sensors integrated with allocation engines eliminate revenue leakage from NGL misclassification at processing plant boundaries.
Market Restraints
- Data sovereignty requirements:National oil companies in Saudi Arabia, Brazil, and Mexico mandate on-premises deployment, blocking cloud-native vendors from capturing state-controlled production volumes.
- Joint-venture governance complexity:North Sea and Gulf of Mexico projects require unanimous partner approval for system changes, extending sales cycles by 18-24 months.
- Legacy system entrenchment:Decades of custom allocation formulas embedded in SQL Server and Oracle databases create switching costs that anchor operators to incumbent vendors.
Strategic Opportunities
- Carbon border adjustment integration:The EU's CBAM mechanism will force exporters to embed emissions intensity data directly into hydrocarbon valuation workflows, creating demand for combined carbon-accounting platforms.
- AI-powered anomaly detection:Machine learning models trained on historical allocation patterns can identify commingling errors in real-time, opening premium pricing tiers for predictive accuracy guarantees.
- Midstream operator expansion:Gathering and processing companies in the Permian and DJ Basin seek standalone allocation modules independent of upstream enterprise suites.
Industry Challenges
- Petroleum engineering talent scarcity:Vendors struggle to hire allocation specialists who understand both reservoir engineering principles and software configuration, delaying implementation timelines.
- Joint-venture equity dispute resolution:Discrepancies between partner-calculated volumes require manual arbitration processes that erode trust in automated systems and trigger contract renegotiations.
- Legacy database migration complexity:Decades of production history stored in proprietary formats must be cleansed and validated before cloud migration, consuming professional services capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbons Accounting Solution Market |
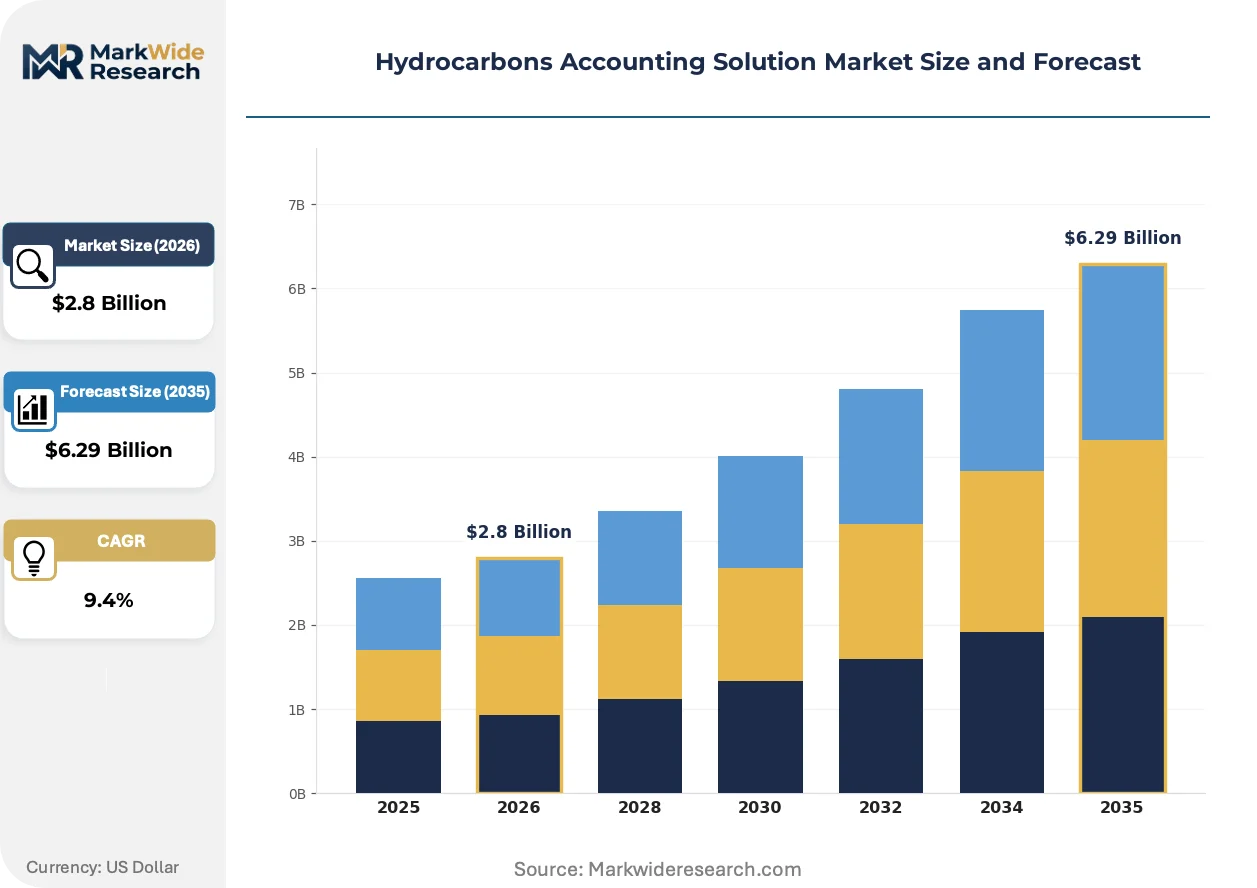
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud-Based, On-Premises, Hybrid, Managed Services Technology: Blockchain, AI, Machine Learning, Data Analytics End User: Oil & Gas Companies, Asset Managers, Regulators, Exploration Firms Deployment Model: Public Cloud, Private Cloud, Multi-Cloud, Others |
| Companies Covered | SAP, Infosys, P2 Energy Solutions, Quorum Business Solutions, Schlumberger, EnergySys, Adept Solutions, TietoEVRY, CGI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbons Accounting Solution Market Shifts & Advancements
Blockchain-anchored measurement records and edge-computing architectures are redrawing how custody transfer data flows between field devices and enterprise systems. Vendors are racing to embed emissions tracking directly into core allocation engines rather than bolting on carbon modules as afterthoughts.
Edge computing nodes deployed at wellpad sites are decentralizing allocation processing by running volume-balancing algorithms locally before transmitting aggregated results to central systems. Smaller Permian independents with limited IT infrastructure are adopting these ruggedized devices fastest, compressing their reliance on centralized data centers and reducing latency for real-time production optimization decisions.
The EU methane emissions regulation and the US EPA greenhouse gas reporting program are forcing vendors to redesign audit trails around immutable timestamping and cryptographic verification. Supermajors operating across both jurisdictions now require platforms that satisfy both regulatory schemas simultaneously, driving consolidation toward vendors with dual-compliance certification rather than regional specialists.
Subscription pricing tied to well-count or barrel throughput is displacing perpetual license models among capital-constrained independents. Private-equity-backed operators in the Permian and Bakken prefer this opex treatment for allocation software, while national oil companies with sovereign balance sheets continue purchasing perpetual licenses to avoid recurring vendor dependencies.
Hydrocarbons Accounting Solution Market Segmentation
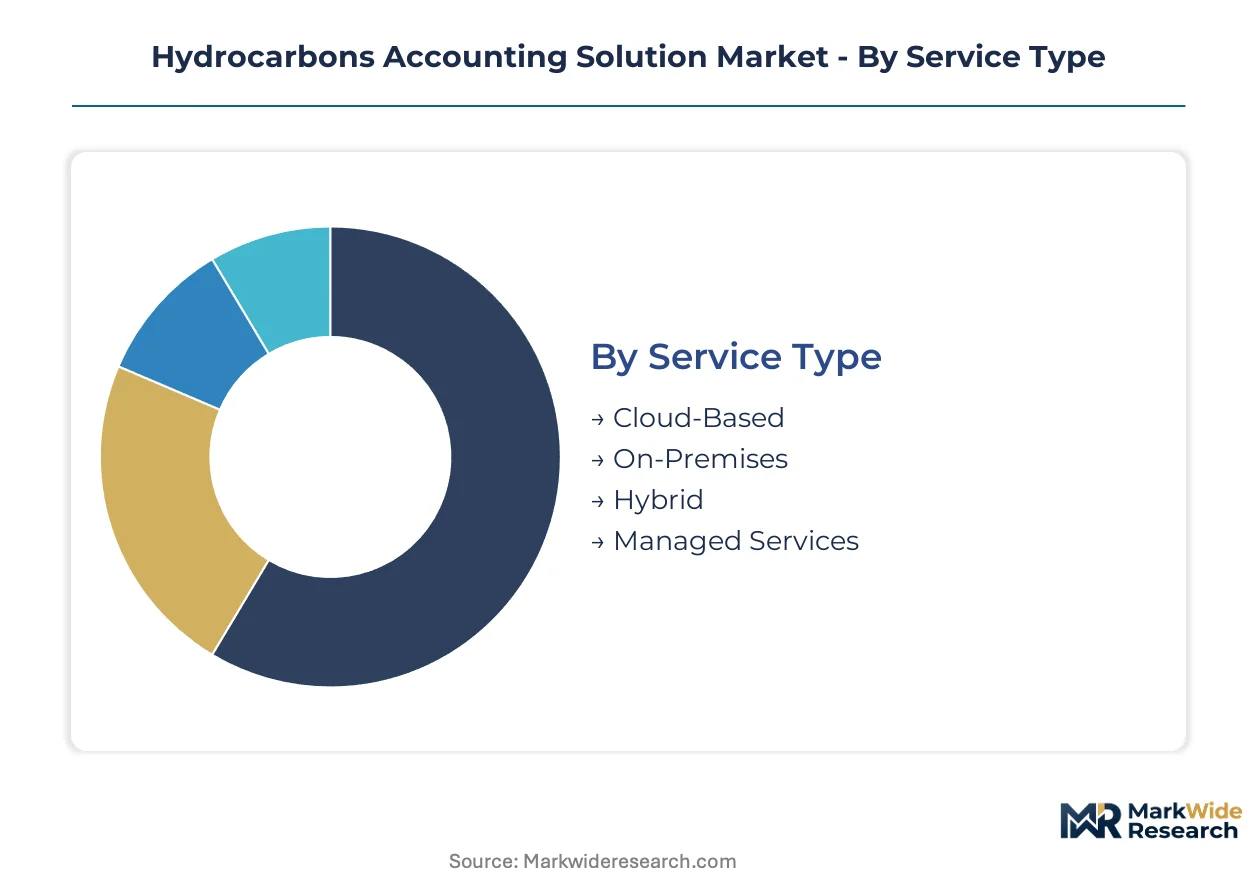
Segmentation in hydrocarbons accounting solutions reveals how deployment flexibility, computational methods, customer sophistication, and infrastructure ownership reshape procurement patterns. Vendors must align product architecture with the regulatory intensity and capital structure of each buyer cohort.
Service Type:
Customization intensity spans from fully managed outsourcing to rigid on-premises control, with hybrid models occupying the middle ground where operators retain sensitive data locally while leveraging cloud scalability for analytics.
- Cloud-Based:Multi-tenant architectures enable operators to scale allocation processing without capital infrastructure commitments. Permian independents with private-equity backing favor this opex model for rapid well-count expansion across Texas and New Mexico.
- On-Premises:Dedicated hardware installations satisfy data sovereignty mandates from national oil companies in Saudi Arabia, Brazil, and Mexico. These deployments demand specialized petroleum engineering talent for database administration and custom formula maintenance.
- Hybrid:Split architectures isolate production volume data on local servers while pushing emissions reconciliation workloads to cloud environments. This configuration appeals to supermajors navigating dual US EPA and EU methane compliance regimes.
- Managed Services:Third-party operators assume full responsibility for allocation engine maintenance and joint-venture reporting. North Sea joint ventures with complex equity splits frequently outsource to reduce internal petroleum accounting headcount.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
Technology:
Computational sophistication determines pricing tiers, with basic data visualization anchoring entry-level offerings and autonomous anomaly detection commanding premium multiples.
- Blockchain:Immutable ledger architectures create cryptographically verifiable audit trails for custody transfer disputes. The EU methane regulation's timestamping requirements accelerate pilot deployments among exporters facing carbon border adjustment scrutiny.
- AI:Neural networks trained on historical allocation patterns flag commingling errors in real-time before revenue leakage compounds. Supermajors operating across multiple basins deploy these systems to standardize detection thresholds.
- Machine Learning:Predictive models forecast NGL yield variations based on API gravity fluctuations and separator operating conditions. Midstream processors in the Permian and DJ Basin apply these tools to optimize plant inlet allocation.
- Data Analytics:Visualization dashboards aggregate production metrics across dispersed wellpads for executive reporting. Smaller independents with limited IT staff rely on these tools for rapid deployment without specialized configuration.
AI commands the highest pricing premiums. Machine Learning is expanding most quickly among midstream operators.
End User:
Buyer sophistication ranges from integrated supermajors requiring enterprise-wide standardization to specialized regulators demanding jurisdictional audit capabilities.
- Oil & Gas Companies:Integrated operators and independents alike require allocation engines spanning upstream production through downstream refining. US EPA greenhouse gas reporting obligations force these buyers to prioritize auditable measurement infrastructure over cost minimization.
- Asset Managers:Private-equity and infrastructure funds holding diversified energy portfolios need consolidated visibility across non-operated working interests. These users prioritize standardized equity split calculations across multiple operator systems.
- Regulators:Environmental agencies and revenue authorities mandate direct access to production data for verification and tax assessment. The US EPA and EU methane enforcement bodies increasingly require API-integrated reporting formats.
- Exploration Firms:Early-stage operators with single-basin concentration seek lightweight allocation tools for farmout negotiations and reserve certification. These buyers favor subscription pricing tied to well-count rather than enterprise licensing.
Oil & Gas Companies dominate procurement volume. Asset Managers are gaining share fastest as private-equity consolidation accelerates.
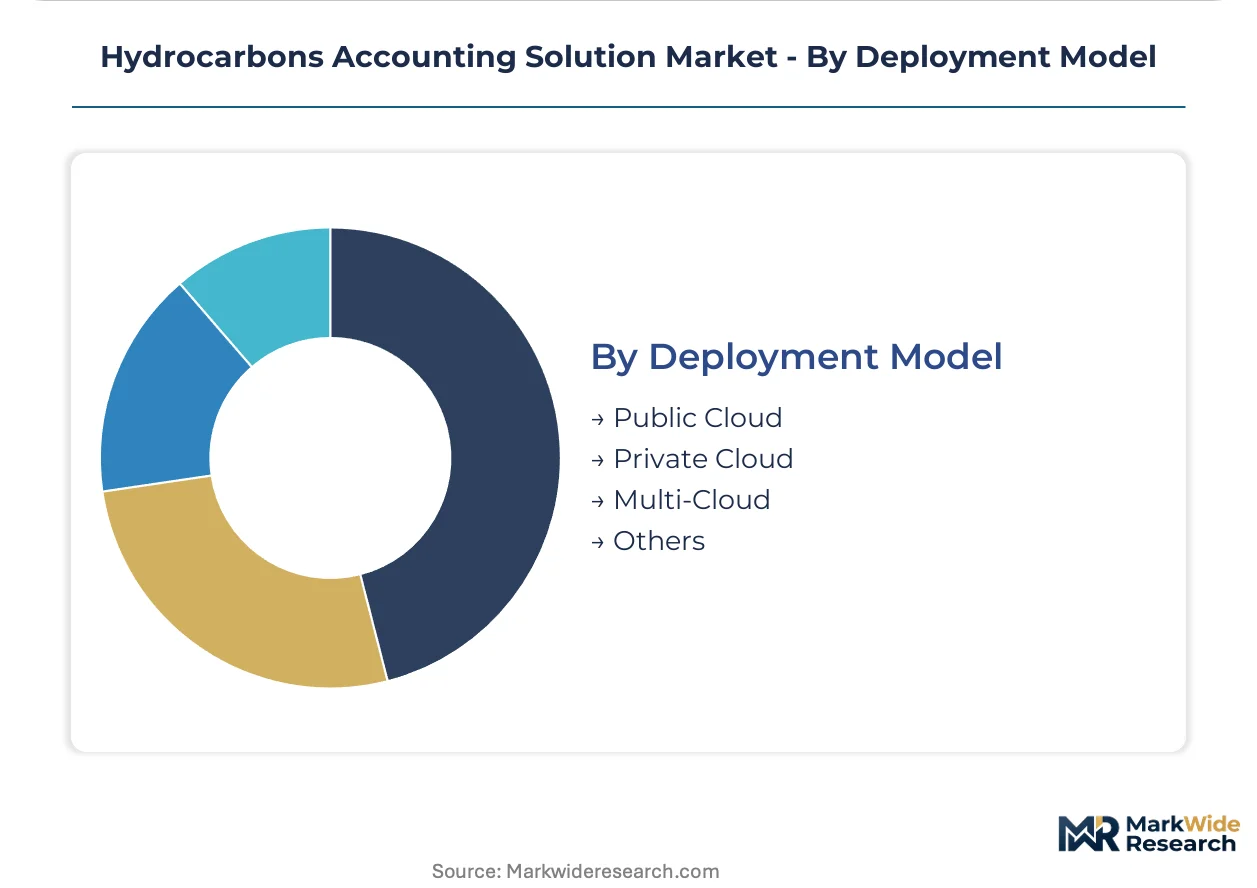
Deployment Model:
Infrastructure ownership structures reflect risk tolerance for vendor lock-in, with single-cloud simplicity competing against multi-cloud redundancy strategies.
- Public Cloud:Shared infrastructure from hyperscale providers delivers lowest unit economics for variable workloads. Permian independents with geographically dispersed assets leverage this model for remote accessibility without dedicated data centers.
- Private Cloud:Dedicated cloud environments within operator-controlled facilities satisfy stringent security requirements. National oil companies in Saudi Arabia and Brazil mandate this architecture for state-controlled production volumes.
- Multi-Cloud:Distributed workloads across competing hyperscale providers eliminate single-vendor dependency. Supermajors with global footprints adopt this strategy to optimize latency and regulatory compliance across jurisdictions.
- Others:Edge-computing nodes at wellpad sites and specialized high-performance computing clusters for complex reservoir simulation. Smaller Permian operators deploy ruggedized edge devices to reduce centralized data center reliance.
Public Cloud leads by deployment volume. Multi-Cloud is climbing the fastest among international operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces hydrocarbons at scale unmatched by consumption markets, while import-dependent economies in Europe and Asia drive cross-border allocation complexity. This production-consumption asymmetry shapes where accounting solution vendors concentrate engineering resources and compliance expertise.
United States
Permian Basin operators in Texas and New Mexico deploy cloud-native allocation engines to unify production accounting across dispersed wellpads. The US EPA greenhouse gas reporting program mandates auditable measurement infrastructure that automatically reconciles volumes against emissions data. Midland-Odessa independents favor subscription pricing tied to well-count expansion.
Norway
North Sea joint ventures require granular equity-split calculations for commingled streams crossing multiple production licenses. The country's petroleum regulator enforces strict measurement uncertainty thresholds for custody transfer points. Stavanger-based operators outsource allocation maintenance to reduce internal petroleum accounting headcount.
Saudi Arabia
State-controlled production volumes mandate on-premises deployment architectures satisfying stringent data sovereignty requirements. The national oil company maintains dedicated hydrocarbon accounting infrastructure across its Eastern Province fields. Aramco's Ghawar and Safaniya complexes anchor regional demand for high-availability allocation systems.
Brazil
Pre-salt development drives demand for allocation platforms handling complex subsea tiebacks and floating production systems. The national petroleum regulator requires local data residency for production measurement systems. Rio de Janeiro operators navigate joint-venture governance with international partners across Santos Basin blocks.
United Kingdom
North Sea decommissioning timelines compress remaining field economics, forcing operators to minimize allocation system overhead. The North Sea Transition Authority imposes declining basin production reporting requirements. Aberdeen service companies specialize in managed allocation services for aging offshore infrastructure.
Hydrocarbons Accounting Solution Market Competitive Landscape
Top-tier vendors anchor enterprise-wide deployments for supermajors, while mid-tier specialists capture basin-specific joint-venture workflows. The market structure concentrates around three strategic archetypes: ERP-integrated suite providers, configurable allocation engine specialists, and legacy on-premises incumbents. Competitive moves center on cloud migration acceleration and carbon-accounting module bundling.
Within the ERP-integrated tier, SAP exemplifies enterprise-scale hydrocarbon accounting anchored to S/4HANA oil and gas modules. EnergySys occupies a position among configurable specialists serving North Sea equity-split complexity. P2 Energy Solutions represents the on-premises incumbent archetype dominating Permian independents seeking direct database control.
| Leading Market Players |
|---|
| SAP |
| Infosys |
| P2 Energy Solutions |
| Quorum Business Solutions |
| Schlumberger |
| EnergySys |
| Adept Solutions |
| TietoEVRY |
| CGI Group |
| Others |
Supply & Pricing Matrix
Petroleum engineering talent concentration in Houston and Calgary compresses implementation timelines and widens pricing-tier spreads between premium AI-enabled platforms and basic data-analytics configurations. Labor-cost differentials between North American specialists and offshore configuration teams feed directly into subscription pricing for managed services versus self-hosted deployments.
Pricing Analysis
Margin tightening in cloud-native tiers reflects hyperscale infrastructure passthrough costs and customer concentration among Permian independents with limited IT budgets. Three-tier pricing structure across premium AI-anomaly detection, standard allocation engines, and economy visualization dashboards differentiates primarily by well-count scalability and emissions-module bundling. Cost-down pressure on on-premises perpetual licenses accelerates as national oil companies demand open-database architectures to reduce vendor lock-in. Private-equity-backed operators exhibit highest price sensitivity, while supermajors with sovereign-scale balance sheets prioritize compliance certification over cost minimization.
Supply Chain Analysis
Edge-computing hardware supply rests on semiconductor fabrication capacity in Taiwan and specialized ruggedized-device manufacturing in Germany and the United States. Allocation-engine software development draws from petroleum engineering labor pools concentrated in Texas, Norway, and the United Kingdom, with cloud infrastructure sourcing from hyperscale providers across multiple jurisdictions. Single-source vulnerability in GPU supply for AI-powered anomaly detection creates procurement risk for vendors promising real-time processing guarantees. Distribution runs through direct enterprise sales teams for supermajors and channel partners serving Permian independents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where petroleum engineering talent scarcity props pricing for implementation services and sustains vendor margins against cloud-infrastructure cost compression.
For Market Incumbents: Deepen vertical integration into edge-computing hardware to secure allocation-processing capacity against semiconductor supply volatility. Anchor enterprise relationships through carbon-accounting module bundling ahead of EU carbon border adjustment enforcement. Prioritize certification investment for dual US EPA and EU methane compliance to lock out regional specialists. For New Entrants and Emerging Players: Begin with midstream gathering operators in the Permian and DJ Basin seeking standalone allocation modules independent of upstream enterprise suites. Target managed-services delivery to North Sea joint ventures outsourcing petroleum accounting headcount. Lead with AI-powered anomaly detection as a wedge capability against legacy on-premises incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with configurable-allocation specialists given carbon-accounting integration catalysts and supermajor procurement consolidation. Long-term viability favors vendors with dual-jurisdiction compliance certification and recurring-revenue bases exceeding perpetual-license dependencies. Watch EPA methane enforcement intensity as the signal indicating acceleration in replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Accounting Module Integration | Positions vendors for EU carbon border adjustment compliance requirements affecting export-bound production. |
| Edge-Computing Deployment Architecture | Reduces latency for Permian operators optimizing real-time production decisions across dispersed wellpads. |
| AI-Powered Anomaly Detection Launch | Commands premium pricing tiers through predictive accuracy guarantees against revenue leakage. |
| Managed Services Expansion | Captures North Sea joint-venture outsourcing demand while reducing customer petroleum accounting headcount. |
| Dual-Compliance Certification Investment | Consolidates procurement toward vendors satisfying simultaneous US EPA and EU methane regulation schemas. |
Research Methodology
Document review covered SEC filings from hydrocarbon accounting vendors, EPA greenhouse gas reporting program technical documentation, and EU methane regulation implementation guidance, complemented by interviews with petroleum accounting directors at Permian independents, software configuration specialists in Houston, and joint-venture equity administrators in Stavanger. Secondary validation drew from EIA production databases, North Sea Transition Authority measurement standards, and Aramco supplier qualification protocols. Bottom-up triangulation across deployment-model unit economics and top-down reconciliation against aggregate vendor revenue disclosures anchored market sizing.
Market value outputs reflect a segmented analytical framework spanning deployment model, customer scale tier, and regulatory jurisdiction intensity across the projection horizon. CAGRs were derived from regression analysis of historical vendor booking data against well-count expansion trajectories and emissions-regulation enforcement timelines. Forecast inputs incorporated private-equity drilling budget disclosures and national oil company capital allocation patterns for digital infrastructure.
Underlying measurement precision varies by segment; cloud-based and hybrid deployments carry tighter precision than on-premises national oil company contracts with opaque procurement terms. Forecasts reflect documented assumptions around methane-regulation enforcement pacing and petroleum engineering labor market elasticity. Supply-chain disruption in edge-computing components, joint-venture governance delays, and carbon-border adjustment scope expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Accounting and Taxation Services
Corporate Tax Service Market
Accounting and Taxation Services
Tax Advisory Services Market
Accounting and Taxation Services
India Accounting Professional Services Market
Accounting and Taxation Services
Europe Forensic Accounting Market
Accounting and Taxation Services
UAE Accounting Software Market
Accounting and Taxation Services
Bookkeeping Services Market
Accounting and Taxation Services
China Forensic Accounting Market
Accounting and Taxation Services
US Accounting Software Market
Accounting and Taxation Services
US Auditing Services Market
Accounting and Taxation Services
Germany Forensic Accounting Market
Accounting and Taxation Services
Italy Forensic Accounting Market
Accounting and Taxation Services
Global Fund Accounting Software Market
Accounting and Taxation Services
Global Sales Tax Compliance Software Market
Accounting and Taxation Services
India Accounting Software Market
Accounting and Taxation Services
Italy Accounting Software Market
Accounting and Taxation Services
South Korea Accounting & Budgeting Software Market