
 Dihydrocitronellol Market | 2026-2036
Dihydrocitronellol Market Size, Share, and Industry Trends Forecast 2026-2036
Dihydrocitronellol Market Analysis
Modular fragrance ingredient bundling is broadening buyer choice as compounders assemble pre-validated aroma kits rather than sourcing single molecules. Takasago International Corporation leverages its captive terpene supply chain to secure raw material continuity. Privi Speciality Chemicals Limited anchors its position through dedicated fragrance ingredient manufacturing at Indian sites. Kunshan Odowell Co., Ltd. competes on cost-efficient batch production for Asian cosmetic houses.
Dihydrocitronellol is a saturated acyclic terpene alcohol produced via catalytic hydrogenation of citronellal, featuring a fresh floral odor profile with melon and citrus facets valued in perfumery for its stability and blending versatility. The fragrance application segment dominates value capture as luxury and masstige perfume brands prioritize long-lasting top-note ingredients, while the personal care product type segment records the fastest expansion driven by Asian skincare and haircare launches. Industrial chemical applications remain mature with thinner margins, though detergent-grade volumes sustain baseline throughput for hydrogenation assets.
REACH registration requirements in Europe and IFRA standards govern permissible concentrations in consumer-facing formulations, compelling suppliers to maintain analytical documentation and purity thresholds above technical-grade specifications. China's SAMR and GB standards for cosmetic safety further fragment compliance obligations across export destinations. Stakeholders must monitor regulatory divergence between fragrance self-regulation and emerging chemical hazard classifications that could restrict formulation flexibility or trigger substance replacement cycles.
Market Dynamics
Catalytic hydrogenation capacity concentration in China's Yangtze River Delta is tightening feedstock access for European compounders, forcing fragrance houses to requalify supply chains around captive terpene streams rather than spot market citronellal.
Growth Catalysts
- REACH registration thresholds:ECHA's escalating data requirements for >1 ton annual tonnage are disqualifying marginal producers and consolidating volume among compliant hydrogenation specialists.
- Asian skincare formulation intensity:Domestic cosmetic brands in China are expanding fine fragrance lines, pulling saturated terpene alcohols into premium lotion and serum bases previously dominated by simpler odorants.
- Citronellal hydrogenation yield improvements:Continuous-flow reactor designs are reducing catalyst deactivation rates, improving atom economy for manufacturers operating dedicated terpene derivative trains.
Market Restraints
- Feedstock geographic lock-in:Natural citronellal extraction concentrates in Indonesian and Chinese citronella oil processing, exposing hydrogenators to plantation yield volatility and weather-driven supply shocks.
- Palladium catalyst cost exposure:Platinum-group metal price swings directly compress margins for batch hydrogenation operators without long-term catalyst supply agreements.
- IFRA 51st Amendment concentration limits:Revised dermal sensitization thresholds for acyclic terpene alcohols are restricting formulation flexibility in leave-on cosmetic applications.
Strategic Opportunities
- Saudi cosmetic manufacturing localization:SFDA's streamlined cosmetic ingredient notification pathways and giga-project industrial zone incentives are attracting fragrance compounders to establish regional blending operations.
- Bio-based citronellal fermentation routes:Microbial production from sugar feedstocks is nearing cost parity with botanical extraction, offering hydrogenators a defensible ESG narrative for EU Green Deal-aligned buyers.
- Modular aroma kit bundling:Pre-validated ingredient sets combining dihydrocitronellol with complementary fixatives and modifiers are displacing single-molecule procurement for mid-tier perfume houses.
Industry Challenges
- Cross-jurisdiction analytical documentation:Maintaining REACH-compliant safety data sheets alongside China's GB/T cosmetic raw material standards and US EPA TSCA filings strains regulatory affairs teams at mid-size suppliers.
- Hydrogenation asset repurposing rigidity:Dedicated citronellal-to-dihydrocitronellol reactors lack flexibility to pivot toward alternative terpene derivatives during demand troughs, trapping capital in single-product configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dihydrocitronellol Market |
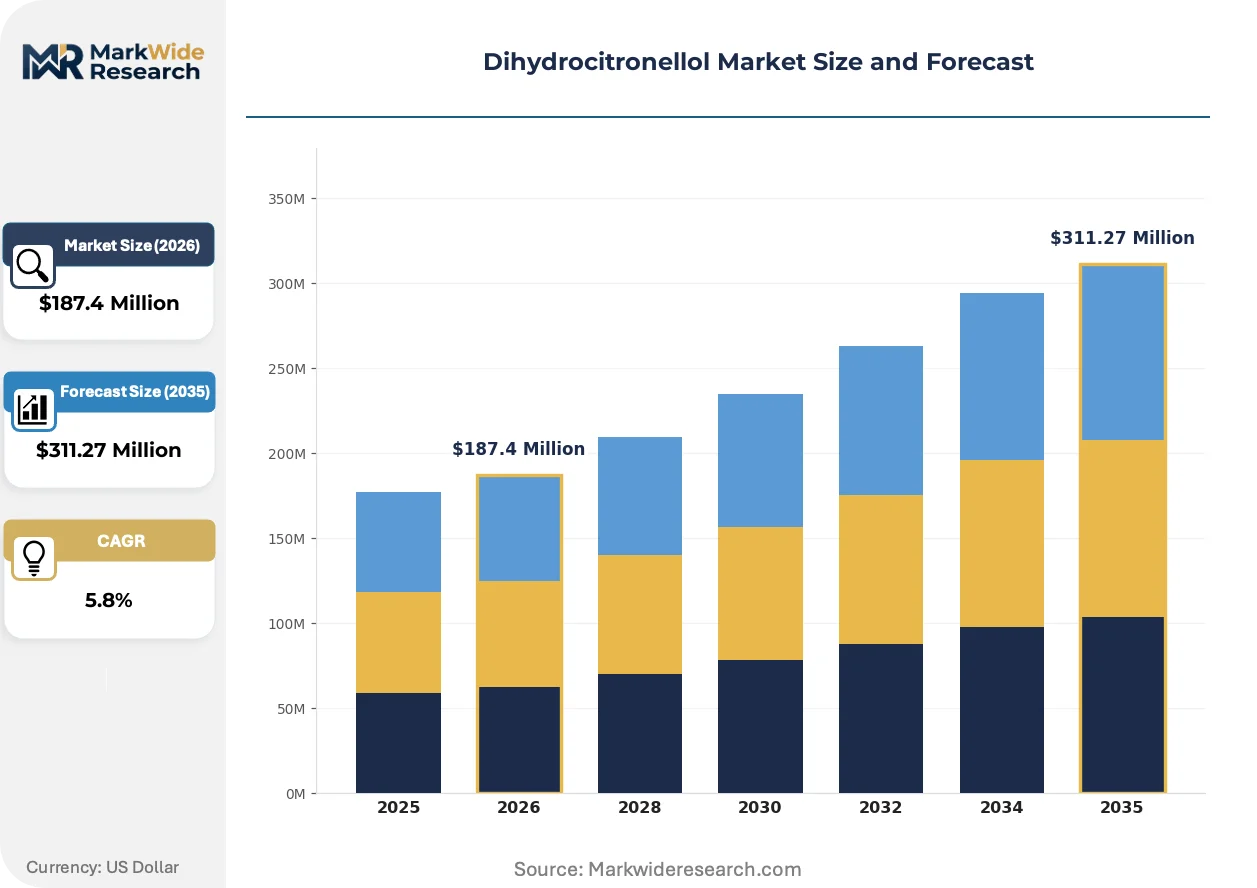
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fragrance, Flavoring Agent, Personal Care, Industrial Chemical Application: Cosmetics, Household Cleaners, Food & Beverage, Detergents End User: Manufacturers, Retailers, Consumers, Distributors Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Takasago International Corporation, Kunshan Odowell Co., Ltd., Privi Speciality Chemicals Limited, Sigma-Aldrich, Chemical Bull Pvt. Ltd., Ataman Kimya Ltd., Aurora Fine Chemicals, BOC Sciences, Biosynth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dihydrocitronellol Market Emerging Trajectories
Fragrance ingredient supply chains are fragmenting into specialized tiers as regulatory documentation burdens and formulation complexity outpace the capabilities of undifferentiated commodity distributors.
Continuous-flow hydrogenation microreactors are modularizing production economics for dihydrocitronellol. Specialty chemical divisions at Japanese and German engineering firms are installing skid-mounted units at customer sites, enabling fragrance houses to toll-manufacture saturated terpene alcohols without building captive hydrogenation infrastructure. This distributed production model is compressing minimum efficient scale thresholds and enabling regional supply security for mid-volume compounders.
EU F-Gas Regulation phase-down schedules are indirectly tightening solvent recovery requirements at hydrogenation facilities, pushing operators toward closed-loop catalyst separation systems. ECHA's updated guidance on persistent, bioaccumulative and toxic substance classification is forcing re-evaluation of downstream co-products from citronellal processing. Fragrance ingredient manufacturers with integrated waste treatment capabilities are capturing volume from competitors facing extended environmental permitting timelines.
Chinese domestic cosmetic brands are consolidating supplier relationships around compounders offering integrated regulatory dossier packages rather than raw material certificates alone. This bundling of compliance documentation with physical supply is squeezing independent traders and driving procurement concentration toward hydrogenation specialists with in-house toxicology and registration capabilities. The shift is most visible in Shanghai and Guangzhou, where local skincare houses are launching premium fragrance-adjacent product lines requiring full REACH-grade substance documentation.
Dihydrocitronellol Market Segmentation
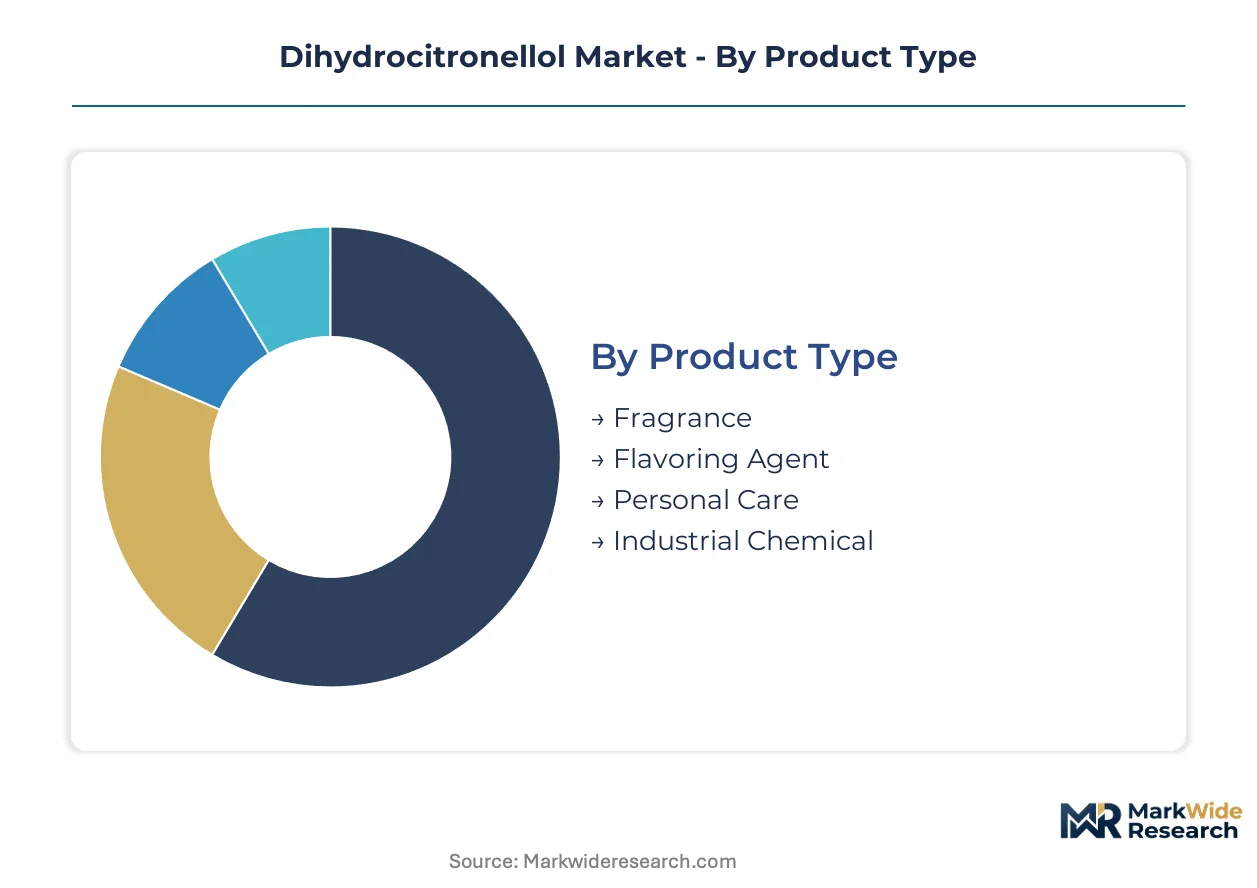
Segmentation in the dihydrocitronellol market exposes how hydrogenation capacity concentration and regulatory compliance burdens reshape competitive positioning across value tiers. Buyers now select suppliers based on bundled documentation capabilities rather than molecular purity alone.
Product Type:
Supply concentration in China's Yangtze River Delta hydrogenation clusters dictates which product grades achieve cost-competitive scale for export markets.
- Fragrance:Saturated acyclic terpene alcohol with fresh floral odor profile featuring melon and citrus facets. Demand concentrates in Shanghai and Guangzhou where domestic cosmetic brands launch premium fragrance-adjacent skincare lines requiring REACH-grade substance documentation.
- Personal Care:Fine fragrance formulations for lotion and serum bases previously dominated by simpler odorants. Asian skincare houses in China are pulling saturated terpene alcohols into premium product lines at the fastest clip of any product tier.
- Flavoring Agent:Food-grade specifications governed by FSSAI thresholds in India and FDA flavoring substance lists in the US.
- Industrial Chemical:Mature demand segment with thinner margins sustained by detergent-grade volumes for baseline hydrogenation asset throughput.
Today's leader: Fragrance. Tomorrow's challenger: Personal Care.
Application:
Cost tier differentiation separates premium fragrance compounders from commodity detergent blenders based on analytical documentation depth and purity thresholds.
- Cosmetics:Leave-on applications face IFRA 51st Amendment dermal sensitization thresholds restricting acyclic terpene alcohol concentrations. Formulation flexibility constraints are tightening most acutely in EU-exporting cosmetic houses.
- Detergents:Rinse-off applications permit higher loading levels with less stringent purity documentation. Industrial chemical applications here sustain baseline throughput for hydrogenation assets during fragrance demand troughs.
- Household Cleaners:Functional odor masking with moderate stability requirements.
- Food & Beverage:Flavoring applications requiring compliance with national food additive registers.
Cosmetics commands premium pricing. Detergents anchors volume scale.
End User:
Procurement patterns bifurcate between compounders seeking bundled regulatory dossiers and traders offering raw material certificates alone.
- Manufacturers:Fragrance houses and cosmetic formulators requiring REACH-compliant safety data sheets alongside China's GB/T cosmetic raw material standards. These buyers consolidate relationships around hydrogenation specialists with in-house toxicology capabilities.
- Distributors:Independent traders facing squeeze as Chinese domestic brands bypass intermediaries for direct supplier relationships with integrated compliance documentation.
- Retailers:Private-label personal care brands with limited formulation expertise.
- Consumers:Niche artisan perfumers sourcing small-batch saturated terpene alcohols.
Manufacturers drive specification intensity. Distributors face margin compression.
Distribution Channel:
Volume concentration favors wholesale procurement for hydrogenation specialists while specialty stores serve fragmented artisan demand.
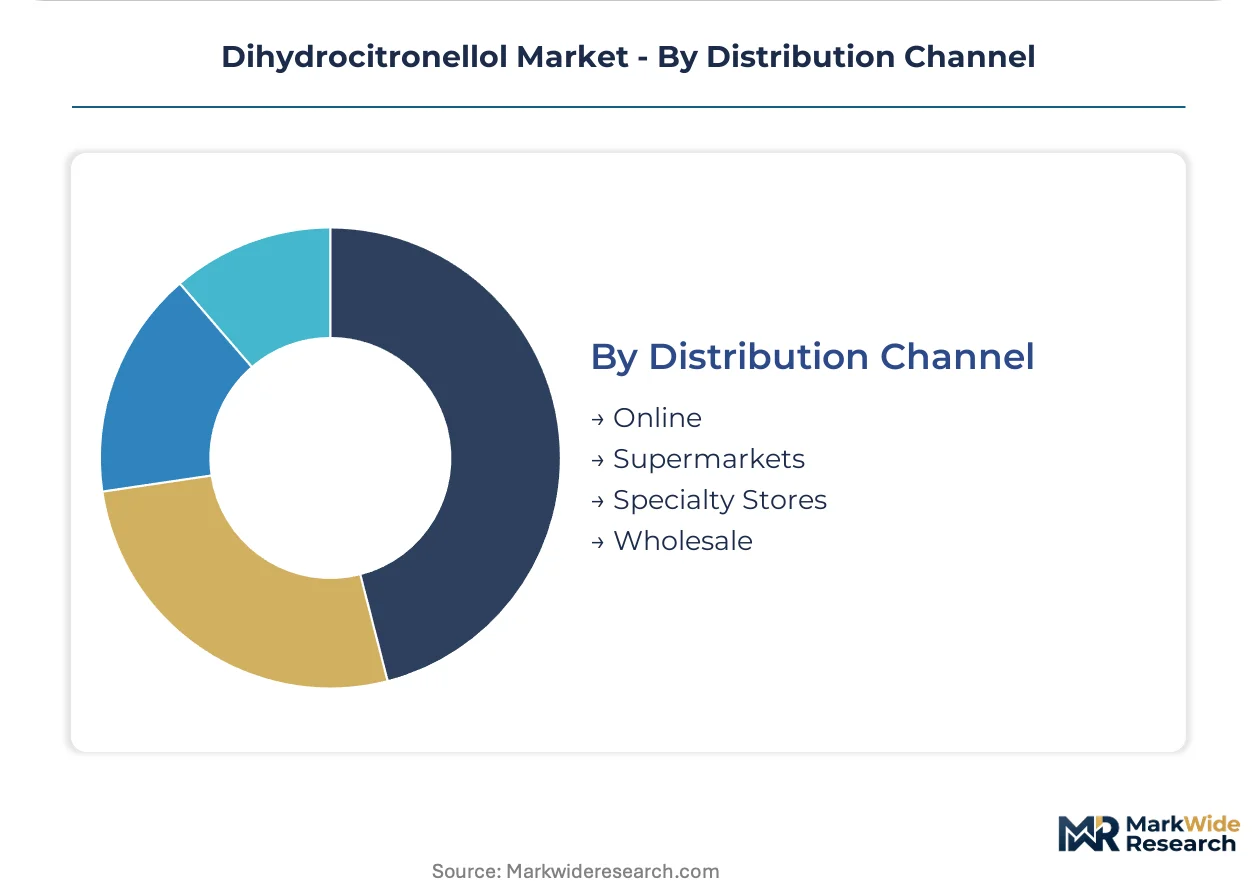
- Wholesale:Bulk procurement by fragrance compounders and cosmetic manufacturers with validated supplier qualification programs. This channel captures the majority of tonnage moving through dedicated terpene derivative supply chains.
- Online:Digital platforms enabling mid-tier perfume houses to access pre-validated aroma kits combining dihydrocitronellol with complementary fixatives.
- Specialty Stores:Regional chemical distributors serving smaller compounders without direct hydrogenator relationships.
- Supermarkets:Limited penetration given industrial-grade specifications and bulk packaging requirements.
Wholesale dominates tonnage. Online gains share fastest among mid-tier buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European perfumery houses pioneered catalytic hydrogenation of terpene alcohols during the mid-twentieth century, establishing quality benchmarks that now govern global trade. Today, manufacturing gravity has shifted toward Asian hydrogenation clusters while regulatory compliance obligations fragment across export destinations.
China
Domestic cosmetic brands in Shanghai and Guangzhou are launching premium fragrance-adjacent skincare lines that pull saturated terpene alcohols into lotion and serum bases. SAMR's GB standards for cosmetic safety impose documentation requirements that favor hydrogenation specialists with in-house toxicology capabilities. The Yangtze River Delta concentrates catalytic hydrogenation capacity, tightening feedstock access for European compounders seeking spot market citronellal.
Germany
Fragrance houses headquartered in the Cologne-Düsseldorf corridor maintain formulation leadership despite manufacturing cost disadvantages. ECHA's escalating REACH registration thresholds for tonnage bands above one ton annually are disqualifying marginal producers and consolidating volume among compliant hydrogenation specialists. The country's engineering firms are installing skid-mounted continuous-flow microreactors at customer sites across Europe, enabling toll-manufacturing without captive infrastructure.
United States
Mid-tier perfume houses are accessing pre-validated aroma kits through digital procurement platforms, displacing single-molecule sourcing patterns. EPA TSCA filings for fragrance ingredient imports require analytical documentation that strains regulatory affairs teams at mid-size suppliers. New Jersey and California host the primary blending operations serving North American cosmetic formulators, with both states enforcing distinct state-level chemical disclosure requirements beyond federal baselines.
India
Domestic fragrance compounders are expanding dedicated manufacturing sites to serve Asian cosmetic houses seeking cost-efficient batch production. FSSAI thresholds govern food-grade specifications for flavoring applications, creating a parallel compliance track distinct from cosmetic-grade requirements. Privi Speciality Chemicals Limited anchors dedicated fragrance ingredient manufacturing at Indian sites, capturing procurement relationships from brands consolidating supplier bases around integrated regulatory dossier packages.
Saudi Arabia
SFDA's streamlined cosmetic ingredient notification pathways are attracting fragrance compounders to establish regional blending operations within giga-project industrial zones. The kingdom's push to localize manufacturing offers hydrogenation specialists tariff advantages and proximity to emerging Gulf cosmetic markets. Jeddah and Riyadh are developing as distribution hubs for saturated terpene alcohols serving Middle Eastern personal care brands.
Dihydrocitronellol Market Vendor Landscape
Premium-margin players sit above commodity-margin players across documentation depth and purity certification tiers. The vendor base stratifies into hydrogenation specialists with captive terpene supply chains, toll-manufacturing operators leveraging continuous-flow reactor technology, and undifferentiated commodity distributors facing procurement bypass. Three archetypes dominate: integrated terpene derivative producers, regional compounders with regulatory bundling capabilities, and engineering-led technology licensors. Competitive moves concentrate on strategic partnerships for feedstock security and portfolio diversification into pre-validated aroma kits.
Among Japanese and Chinese fabricators, Takasago International Corporation exemplifies the integrated terpene derivative archetype through its captive supply chain positioning. Kunshan Odowell Co., Ltd. occupies a cost-efficient manufacturing role serving Asian cosmetic houses. Privi Speciality Chemicals Limited anchors the regional compounder tier with dedicated Indian manufacturing infrastructure. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Takasago International Corporation |
| Kunshan Odowell Co., Ltd. |
| Privi Speciality Chemicals Limited |
| Sigma-Aldrich |
| Chemical Bull Pvt. Ltd. |
| Ataman Kimya Ltd. |
| Aurora Fine Chemicals |
| BOC Sciences |
| Biosynth |
| Others |
Supply Flow & Price Mechanics
Premium fragrance compounders in Shanghai and Guangzhou anchor pricing power through bundled REACH-grade documentation, compressing margins for spot-market suppliers lacking integrated toxicology capabilities. Three-tier pricing structure across premium, standard, and economy levels separates compounders with captive terpene streams from batch hydrogenators exposed to palladium catalyst volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs dihydrocitronellol transactions, with differentiation driven by REACH registration completeness and citronellal hydrogenation yield consistency. Price differentiation intensifies between fragrance-grade and detergent-grade specifications as IFRA 51st Amendment compliance costs concentrate in premium tiers. Cost compression in standard-grade batches is intensifying because Chinese domestic brands consolidate procurement around hydrogenation specialists with in-house regulatory dossier capabilities. Detergent blenders exhibit highest price sensitivity, while luxury perfume houses absorb documentation premiums for supply security.
Supply Chain Analysis
Saudi Arabia's giga-project localization mandates and China's SAMR cosmetic safety requirements are reshaping sourcing patterns for fragrance compounders seeking tariff-advantaged regional blending. Geographic supply concentration centers on China's Yangtze River Delta, Indonesia's citronella oil processing belts, and India's dedicated fragrance ingredient manufacturing zones. Raw material dependencies draw from natural citronellal extraction, platinum-group metal catalysts, and hydrogen feedstock. Single-source vulnerability in Indonesian plantation yields exposes hydrogenators to weather-driven supply shocks. Distribution runs through wholesale procurement channels with validated supplier qualification programs capturing majority tonnage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in dihydrocitronellol concentrate on continuous-flow reactor yield improvements and premium-tier shifts toward bundled aroma kits with integrated compliance documentation.
For Market Incumbents: Anticipate bio-based citronellal fermentation routes displacing botanical extraction cost structures within the analysis window. Defensive consolidation should prioritize backward integration into captive terpene supply chains and capacity addition in Saudi giga-project zones capturing SFDA notification advantages. Certification investment in REACH-compliant safety data sheet automation protects against mid-size supplier attrition from ECHA tonnage band escalations.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Asian personal care applications offers the most penetrable white-space target, specifically Chinese domestic skincare brands launching fragrance-adjacent serum lines. Toll-manufacturing partnerships with Japanese engineering firms deploying skid-mounted continuous-flow microreactors provide capital-efficient entry without captive hydrogenation infrastructure. Direct digital procurement platform presence enables mid-tier perfume house access bypassing established distributor relationships.
For Investors and Strategic Acquirers: Fragrance compounders with integrated regulatory dossier capabilities are the most active acquirer in this space, consolidating hydrogenation specialists to secure terpene derivative supply chains. Long-term viability over the coming decade hinges on ESG-aligned bio-based feedstock positioning for EU Green Deal procurement preferences. Acquisition target archetype: regional compounders with SAMR GB/T certification and established relationships with Shanghai cosmetic houses. The inflection indicator to monitor is ECHA persistent bioaccumulative toxic substance reclassification guidance affecting citronellal processing co-products.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Terpene Supply | Takasago International Corporation secures raw material continuity against Indonesian plantation yield volatility. |
| Continuous-Flow Reactor Technology Licensing | German engineering firms compress minimum efficient scale thresholds for mid-volume fragrance compounders. |
| Regional Blending Operations in Saudi Giga-Projects | SFDA streamlined notification pathways attract compounders seeking Gulf market proximity advantages. |
| Bio-Based Citronellal Fermentation Scale-Up | Microbial production from sugar feedstocks offers defensible ESG narrative for EU Green Deal-aligned buyers. |
| Pre-Validated Aroma Kit Bundling | Modular fragrance ingredient sets displace single-molecule procurement for mid-tier perfume houses. |
Methodological Framework
Multiple input streams — hydrogenation plant manager interviews, downstream fragrance house procurement lead consultations, distribution channel partner discussions, and regulatory affairs director exchanges — were reconciled against secondary validation from customs/trade data, SEC 10-K filings, ECHA registration databases, and ACC/Cefic chemical industry reports. Bottom-up capacity utilization assessments and top-down end-use demand modeling were triangulated to cross-validate volume estimates across the analysis window.
Data-stream reconciliation applied analytical framework segmentation across product grade tier, end-use industry vertical, packaging format, and regional production hub dimensions throughout the forecast period. CAGRs were derived from hydrogenation asset deployment timelines, citronellal feedstock cost trajectories, and IFRA amendment implementation schedules affecting formulation loading limits. Continuous-flow reactor adoption curves and bio-based fermentation route cost-parity milestones served as industry-specific forecast sensitivity inputs.
Caveats apply where ECHA persistent bioaccumulative toxic substance reclassification, Indonesian plantation weather shocks, or palladium price spikes could materially shift the outlook. Forecasts reflect documented assumptions regarding REACH registration threshold escalations and SAMR GB standard harmonization timelines. A small set of named triggers — EU F-Gas Regulation solvent recovery mandates, SFDA localization incentive revisions, and IFRA dermal sensitization threshold updates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavor and Fragrance Chemicals
Natural Fragrance Ingredients Market
Flavor and Fragrance Chemicals
Middle East and Africa Aroma Chemicals Market
Flavor and Fragrance Chemicals
Spearmint Oil Market
Flavor and Fragrance Chemicals
Global Natural Cinnamic Aldehyde Market
Flavor and Fragrance Chemicals
Coumarin Market
Flavor and Fragrance Chemicals
Anisic Aldehyde Market
Flavor and Fragrance Chemicals
Natural Fragrance Chemicals Market
Flavor and Fragrance Chemicals
India Aroma Chemicals Market
Flavor and Fragrance Chemicals
Immortelle Oil Market
Flavor and Fragrance Chemicals
Ethylidene Norbornene Market
Flavor and Fragrance Chemicals
Global Terpene Market
Flavor and Fragrance Chemicals
United States Aroma Chemicals Market
Flavor and Fragrance Chemicals
Tannic Acid Market
Flavor and Fragrance Chemicals
Aromatics Market
Flavor and Fragrance Chemicals
Deodorant Market
Flavor and Fragrance Chemicals
4-Allylanisole Market