
 General Medicine Education Publishing Market | 2026-2036
General Medicine Education Publishing Market Size, Share, and Industry Trends Forecast 2026-2036
General Medicine Education Publishing Market Analysis
Market Overview
Cloud-based authoring platforms is rewriting how medical publishers assemble and distribute curriculum materials, collapsing production cycles from months to weeks. Elsevier leverages its ScienceDirect infrastructure to anchor digital subscription revenue across North American medical schools. RELX plc sustains dominance in clinical decision support through tight integration of textbook content with point-of-care tools. Springer Nature Switzerland AG competes on open-access journal volume, capturing researcher attention in European markets.
Segmentation Analysis
General medicine education publishing encompasses the creation, peer review, production, and distribution of curriculum materials, reference works, and scholarly communications intended to train or update physicians in non-specialized clinical practice, typically requiring ISBN registration or DOI assignment for cataloging. Digital delivery mode now leads revenue contribution as medical programs mandate tablet-based coursework, while hybrid formats retain margin strength where institutions maintain print library budgets. Textbooks command the largest absolute dollar pool among content types, though case studies represent the fastest-growing category as problem-based learning expands in undergraduate medical education.
Regulatory Environment
Accreditation bodies including the Liaison Committee on Medical Education in the United States, the General Medical Council in the United Kingdom, and the National Medical Commission in India each specify textbook and journal requirements that directly determine publisher procurement eligibility. These frameworks shape demand by mandating evidence-based content updates, peer-review rigor, and alignment with national competency standards. Stakeholders must monitor how accreditation shifts toward competency-based medical education reshape content format requirements and assessment integration.
Market Dynamics
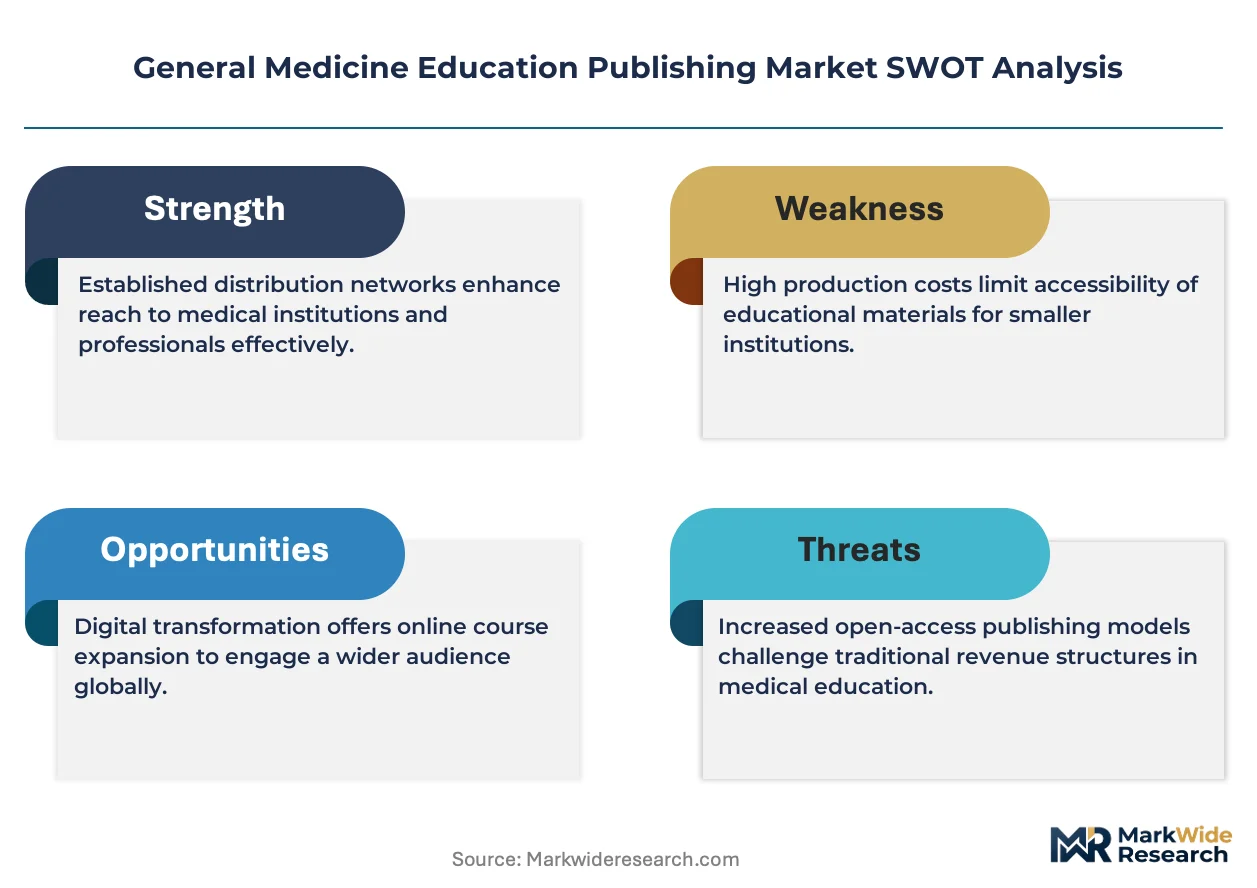
Cloud-based authoring platforms are collapsing production cycles from months to weeks, forcing legacy publishers to restructure editorial workflows around real-time collaboration tools or surrender market position to agile competitors.
Growth Catalysts
- Competency-based medical education mandates:The Liaison Committee on Medical Education now requires integrated assessment tools, pulling adaptive learning platforms into core curricula at US medical schools.
- India's physician shortage response:Government medical colleges are scaling annual enrollment targets, creating sustained procurement demand for standardized textbook series and digital coursework bundles.
- Point-of-care tool convergence:Clinical decision support systems now embed textbook content directly into diagnostic workflows, expanding publisher revenue per user beyond traditional library subscriptions.
Market Restraints
- Peer-review labor scarcity:Qualified physician reviewers command premium consulting fees, compressing margins on rapid-update digital products requiring frequent validation cycles.
- Platform dependency risk:Major medical schools increasingly mandate exclusive learning management system contracts, locking smaller publishers out of institutional procurement channels.
- Open-access substitution pressure:PubMed Central and institutional repositories now host peer-reviewed clinical guidelines, eroding demand for traditional reference textbook purchases.
Strategic Opportunities
- Southeast Asia digital infrastructure gaps:Medical schools in Vietnam and Indonesia lack integrated coursework platforms, creating first-mover advantage for publishers offering bundled tablet-based curricula.
- Continuing medical education credit integration:The FDA's tightened licensure renewal requirements create demand for accredited content modules that track completion automatically.
- AI-assisted personalization:Machine learning algorithms tailoring case study difficulty to individual student performance represent unclaimed white space in undergraduate medical training.
Industry Challenges
- Instructional designer recruitment:Publishers face acute shortages of professionals who combine clinical domain expertise with user experience design for interactive digital formats.
- Legacy print-to-digital migration:Backlist conversion requires substantial capital outlay for rights clearance, multimedia enrichment, and platform engineering without guaranteed subscription uptake.
Report Scope
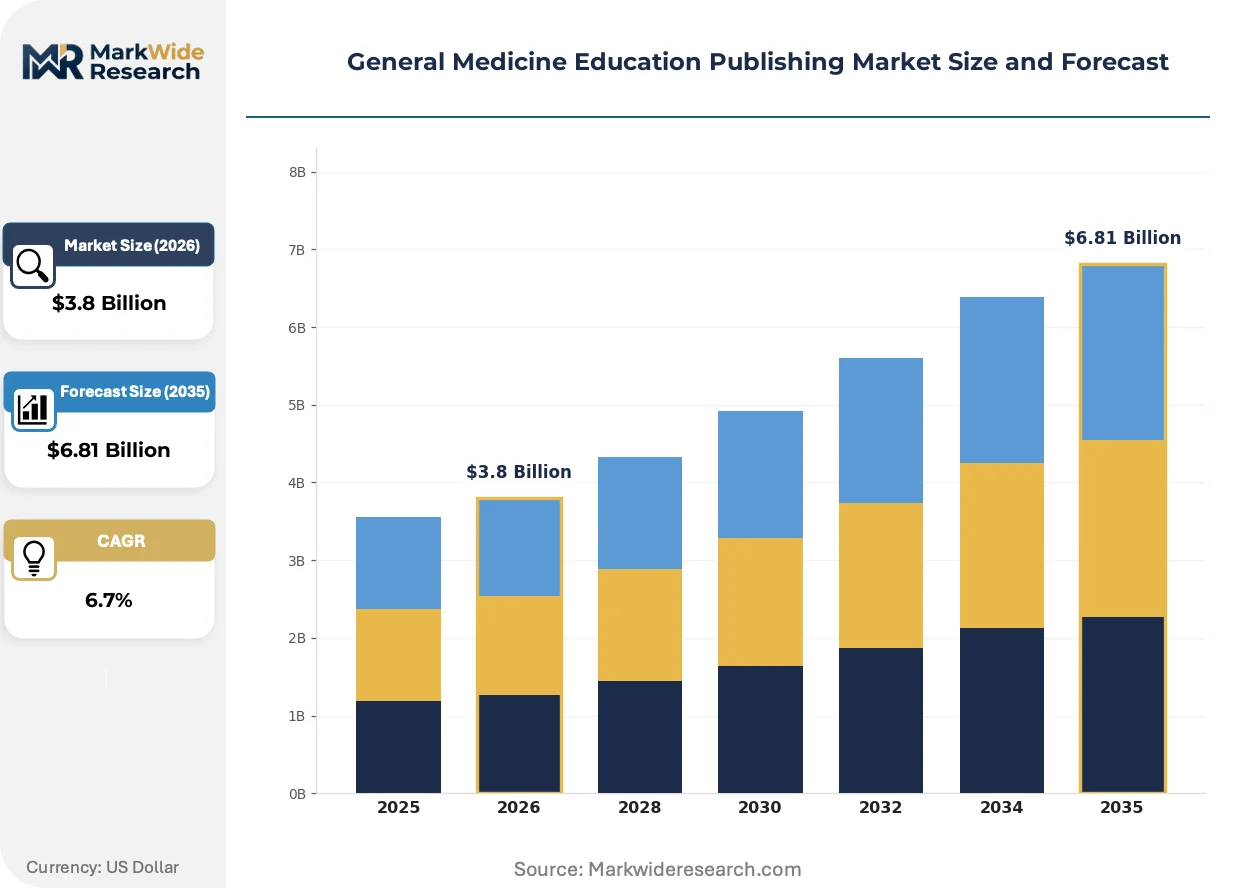
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Medicine Education Publishing Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Textbooks, Journals, E-books, Case Studies Delivery Mode: Print, Digital, Hybrid, Online Courses Target Audience: Medical Students, Educators, Practitioners, Researchers Publication Format: Peer-reviewed Articles, Review Papers, Educational Material, Reference Guides |
| Companies Covered | RELX plc, Wolters Kluwer N.V., McGraw-Hill Education, Springer Nature Switzerland AG, Thieme Medical Publishers, John Wiley & Sons, Inc., Kaplan, Inc., Elsevier, Pearson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Medicine Education Publishing Market Emerging Trajectories
Generative AI tools are infiltrating content development pipelines, forcing publishers to redefine authorial roles and quality assurance protocols while medical educators experiment with synthetic case generation.
Immersive virtual patient simulations are rendering obsolete static paper-based case studies in problem-based learning curricula. Medical schools in Australia and the United Kingdom are piloting these platforms at scale, compressing the clinical reasoning training timeline from semester-long rotations into concentrated modular experiences.
The European Union's Medical Device Regulation now classifies certain clinical decision support tools as medical devices, imposing conformity assessment requirements on publishers integrating diagnostic algorithms with textbook content. German and French medical schools are demanding CE-marked courseware, pushing vendors to restructure product development around notified body engagement.
Subscription fatigue among medical residents is fragmenting purchasing authority toward individual learners rather than institutional libraries. Residents in urban training programs now favor micro-payment access to specific chapters over comprehensive textbook purchases, forcing publishers to unbundle content and experiment with usage-based pricing models in North American markets.
General Medicine Education Publishing Market Segmentation
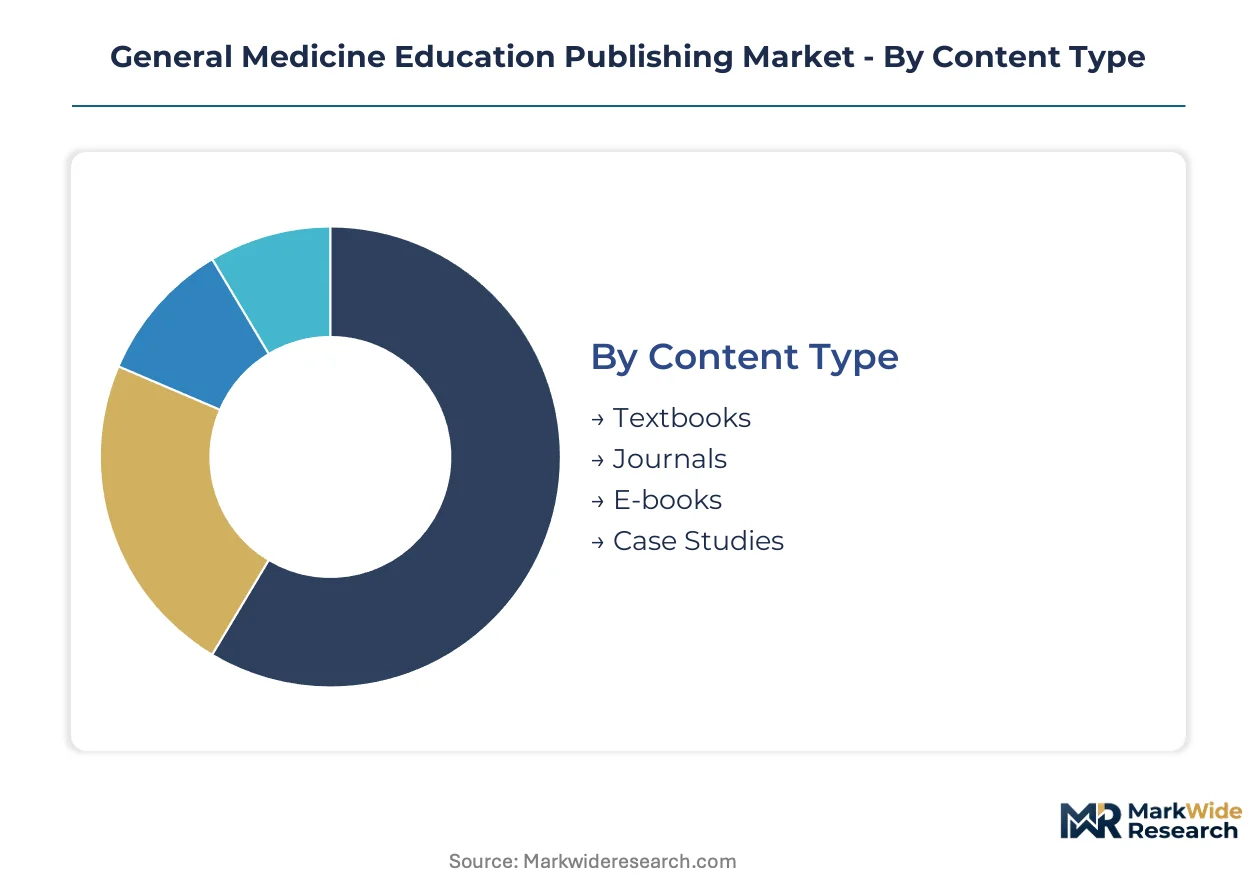
Content format and delivery channel choices in medical education publishing directly determine production economics, update cadence, and institutional procurement eligibility. Publishers structure their portfolios around accreditation body requirements that favor certain combinations of medium and audience.
Content Type:
Update cycles vary dramatically across formats, with clinical guidelines requiring quarterly revisions while foundational textbooks refresh on multi-year horizons.
- Textbooks:Comprehensive curriculum anchors spanning pre-clinical sciences through clerkship rotations, typically requiring ISBN registration and alignment with national competency frameworks. Medical schools in India and Southeast Asia drive procurement volume as government colleges scale enrollment to address physician shortages.
- Journals:Peer-reviewed periodicals with DOI assignment for scholarly indexing, commanding premium subscription pricing where impact factor thresholds determine library acquisition budgets. Research-intensive institutions in the United Kingdom and Germany sustain demand for specialty review titles.
- E-books:Digital-first reference works optimized for tablet-based coursework, offering searchable annotation and multimedia integration.
- Case Studies:Problem-based learning modules expanding fastest as medical schools adopt interactive clinical reasoning training.
Textbooks anchor the volume base while case studies gain share at the steepest rate.
Delivery Mode:
Cost structures stratify sharply between legacy print infrastructure and cloud-native distribution platforms.
- Digital:Cloud-hosted coursework with real-time content updates and usage analytics, now mandated by leading medical schools for tablet-based instruction. The FDA's tightened continuing medical education requirements favor digital modules with automatic completion tracking.
- Hybrid:Bundled print-digital offerings retaining margin strength where institutions maintain physical library budgets and students prefer annotated hard copies for examination preparation.
- Print:Traditional textbook manufacturing with inventory carrying costs and longer revision cycles.
- Online Courses:Structured learning pathways with embedded assessment, often accredited for licensure renewal credits.
Hybrid formats dominate current procurement while pure digital delivery climbs fastest toward parity.
Target Audience:
Customer type shapes pricing architecture from institutional site licenses through individual micro-payments.
- Medical Students:Core curriculum purchasers with concentrated demand during examination periods and rotation transitions.
- Practitioners:Licensed physicians requiring continuing medical education credits for licensure renewal, increasingly favoring point-of-care integrated tools over comprehensive references.
- Educators:Faculty selecting course materials with accreditation compliance as primary selection criterion.
- Researchers:Scholarly authors and readers driving open-access journal volume in European markets.
Medical students generate the highest absolute revenue while practitioners show the steepest shift toward subscription-fatigue-driven unbundling.
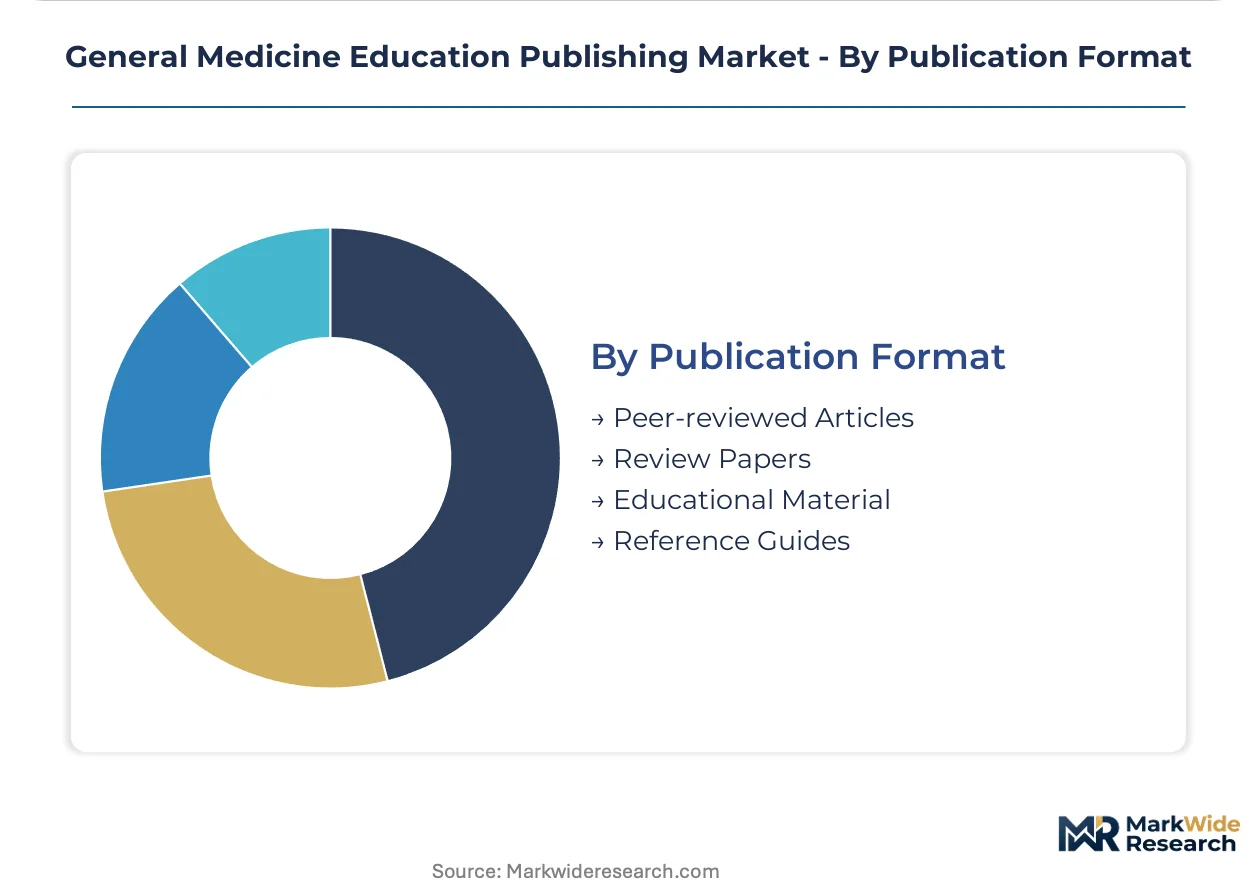
Publication Format:
Maturity gradients separate established peer-review infrastructures from emerging educational material categories.
- Peer-reviewed Articles:Gold-standard scholarly communications with rigorous validation cycles, essential for faculty promotion and tenure decisions.
- Educational Material:Curriculum-integrated content including syllabi, assessment banks, and instructional guides, expanding as competency-based medical education mandates integrated evaluation tools.
- Review Papers:Synthesized evidence summaries for clinical decision support integration.
- Reference Guides:Rapid-access formats for point-of-care consultation.
Peer-reviewed articles sustain the institutional subscription base while educational material broadens fastest into adaptive learning platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical school procurement officers and residency program directors concentrate purchasing power across five national markets where accreditation requirements and enrollment expansion create distinct demand profiles.
United States
The Liaison Committee on Medical Education mandates integrated assessment tools, pulling adaptive learning platforms into core curricula at institutions from Harvard Medical School to the University of California system. The FDA's tightened continuing medical education requirements for physician licensure renewal favor digital modules with automatic completion tracking. The Boston-Cambridge corridor anchors publisher development activity, with Wolters Kluwer and McGraw-Hill maintaining editorial operations there.
India
Government medical colleges are scaling annual enrollment targets to address physician shortages, creating sustained procurement demand for standardized textbook series and digital coursework bundles. The National Medical Commission specifies textbook and journal requirements that directly determine publisher procurement eligibility. Maharashtra and Karnataka host the largest concentrations of medical schools, with Mumbai and Bangalore emerging as regional distribution hubs for curriculum materials.
Germany
The European Union's Medical Device Regulation now classifies certain clinical decision support tools as medical devices, imposing conformity assessment requirements on publishers integrating diagnostic algorithms with textbook content. German medical schools demand CE-marked courseware, pushing vendors to restructure product development around notified body engagement. Heidelberg and Berlin medical faculties pilot immersive virtual patient simulations at scale.
United Kingdom
The General Medical Council specifies textbook and journal requirements that shape publisher procurement eligibility through mandates for evidence-based content updates and peer-review rigor. Research-intensive institutions sustain demand for specialty review titles with impact factor thresholds determining library acquisition budgets. The Oxford-Cambridge-London triangle concentrates medical school purchasing authority and publisher sales operations.
Australia
Medical schools pilot immersive virtual patient simulations at scale, compressing clinical reasoning training timelines from semester-long rotations into concentrated modular experiences. The Therapeutic Goods Administration influences continuing medical education content standards through alignment with national competency frameworks. Melbourne and Sydney medical faculties drive adoption of tablet-based coursework platforms.
General Medicine Education Publishing Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three tiers. Consolidation characterizes the upper tier where diversified information services groups leverage infrastructure scale, while fragmentation persists among niche medical publishers serving single specialties. Strategic archetypes include platform-integrated conglomerates, open-access volume leaders, and clinical decision support specialists. Dominant competitive moves center on cloud-based authoring platform deployment and point-of-care tool convergence with diagnostic workflows.
Within the platform-integrated tier, RELX plc and Elsevier exemplify channel-controlling strategies through tight integration of textbook content with point-of-care tools and ScienceDirect infrastructure. Springer Nature Switzerland AG occupies a position as open-access volume leader capturing researcher attention in European markets. These three entities represent the dominant archetypes: infrastructure-leveraged conglomerates, open-access specialists, and clinical workflow integrators.
| Leading Market Players |
|---|
| RELX plc |
| Wolters Kluwer N.V. |
| McGraw-Hill Education |
| Springer Nature Switzerland AG |
| Thieme Medical Publishers |
| John Wiley & Sons, Inc. |
| Kaplan, Inc. |
| Elsevier |
| Pearson |
| Others |
Supply Flow & Price Mechanics
Boston-Cambridge corridor editorial clusters concentrate high-value content development capacity, translating into premium pricing power for integrated publishers serving North American medical schools while compressing margins for regional competitors without comparable platform infrastructure.
Pricing Analysis
Cost-plus contracts with physician reviewer fee indexation dominate digital product development, embedding labor inflation directly into content production economics. Three-tier pricing structure across premium, standard, and economy levels separates enterprise site licenses from individual practitioner subscriptions and student micro-payments. Pricing pressure stems from open-access institutional repositories eroding reference textbook demand. Medical residents exhibit highest price sensitivity, favoring chapter-level purchases over comprehensive subscriptions.
Supply Chain Analysis
Upstream feedstock of peer-reviewed clinical data draws from United States, United Kingdom, and Indian research institutions, with each geography contributing distinct validation standards and regulatory alignment. Content development rests on qualified physician reviewers, instructional designers, and cloud-native authoring platforms. Single-source vulnerability concentrates in exclusive learning management system contracts locking smaller publishers out of institutional channels. Distribution runs through direct institutional procurement, aggregator platforms, and clinical decision support integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection demands interoperability investment as medical schools mandate integrated assessment tools and automatic completion tracking for FDA licensure renewal requirements.
For Market Incumbents: Entrench ScienceDirect-style infrastructure dominance through exclusive learning management system partnerships that lock out agile competitors. Deepen backward integration into cloud-native authoring platforms to collapse production cycles and capture margin from legacy editorial workflows. Counter open-access substitution pressure by embedding textbook content directly into clinical decision support diagnostic workflows.
For New Entrants and Emerging Players: Build out tablet-based curricula bundles targeting Vietnam and Indonesia medical schools lacking integrated coursework platforms. Southeast Asia digital infrastructure gaps offer first-mover positioning before RELX plc and Elsevier extend regional coverage. Pursue competency-based medical education mandates requiring integrated assessment tools as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clinical decision support specialists with CE-marked courseware capabilities as EU Medical Device Regulation tightens conformity requirements. Five-to-ten year viability hinges on AI-assisted personalization algorithms for case study difficulty adaptation. Monitor FDA continuing medical education requirement tightening as inflection signal for accredited content module demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ScienceDirect infrastructure anchors digital subscription revenue across North American medical schools. |
| CE Marking Pathway | EU Medical Device Regulation conformity assessment enables German and French medical school procurement eligibility. |
| Hospital System Partnership | Clinical decision support tool convergence expands publisher revenue per user beyond traditional library subscriptions. |
| Software Companion Development | Adaptive learning platforms satisfy Liaison Committee on Medical Education integrated assessment mandates. |
| Reimbursement Strategy | Automatic completion tracking aligns with FDA tightened continuing medical education licensure renewal requirements. |
Methodological Framework
Cross-validation between publisher procurement databases and medical school enrollment records anchors the qualitative findings across the analysis window. Primary interviews with medical school deans, curriculum directors, hospital purchasing committee members, and instructional technology officers combine with secondary validation against National Medical Commission accreditation filings, FDA continuing education guidance documents, Liaison Committee on Medical Education standards, and institutional repository usage statistics. Bottom-up enrollment-driven demand modeling and top-down publisher revenue aggregation enable triangulation.
Calibration against historical procurement cycles and accreditation mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include content type, delivery mode, target audience, and regional regulatory cluster. CAGRs derive from enrollment expansion trajectories, digital adoption curves, and point-of-care tool integration rates. Forecast inputs incorporate physician shortage response scaling in India and competency-based medical education mandate rollout patterns in the United States.
Sensitivities concentrate around open-access substitution acceleration, learning management system exclusivity contract expansion, and generative AI content generation disruption. Forecasts reflect assumptions on accreditation body format requirements and institutional budget allocation shifts. Cross-checking against National Medical Commission procurement eligibility specifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Education & Training
Virtual Reality in Education Market
Education & Training
Student Response System Market
Education & Training
France Outplacement Services Market
Education & Training
University Management System Market
Education & Training
Smart Education System Market
Education & Training
Publishing Consulting Services Market
Education & Training
Global Digital Education Market
Education & Training
US Life Coaching Market
Education & Training
Europe Soft Skills Training Market
Education & Training
Global Social and Emotional Learning (SEL) Market
Education & Training
Academic Scheduling Software Market
Education & Training
North America K12 Education Market
Education & Training
Test Preparation Market
Education & Training
Personal Development Market
Education & Training
US Higher Education Market
Education & Training
Global K-12 Software Market