
 Geotourism Market | 2026-2036
Geotourism Market Size, Share, and Industry Trends Forecast 2026-2036
Geotourism Market Analysis
Volcanic destination infrastructure across Iceland is hardening as geothermal trail networks expand capacity ahead of peak season flows. Natural Habitat Adventures leverages its polar and volcanic expedition architecture to anchor premium positioning in remote geosite access. Abercrombie & Kent competes through heritage-integrated volcanic itineraries that combine geologic interpretation with luxury logistics. G Adventures differentiates via youth-focused geothermal trekking programs that sustain price-accessible entry points.
Geotourism encompasses travel to geological features—volcanic formations, fossil beds, caves, mineral springs, and active tectonic zones—where interpretation services explain geologic time scales, rock composition, and landform genesis to visitors. The practice serves conservation funding, rural economic development, and science literacy objectives through visitor fees and educational programming. Adventure tourism segments within guided tours command premium pricing due to specialized safety protocols and certified interpreter scarcity, while virtual tours represent the fastest-growing service type as immersive digital replicas expand access to fragile or remote geosites. Heritage tours retain mature demand among academic and family segments, though margin pools increasingly shift toward specialty workshops that combine field collection with laboratory analysis components.
UNESCO Global Geoparks criteria govern site certification standards across European territories, mandating management plans that tie visitor capacity to conservation outcomes. The EU Green Deal's sustainable tourism directives shape operator carbon accounting requirements for geosite transport and lodging. Iceland's national geopark authority and New Zealand's Department of Conservation enforce track maintenance and thermal feature protection protocols that limit daily visitor volumes. Stakeholders must monitor evolving geopark designation criteria and carbon border adjustments that could restructure long-haul geotourism economics.
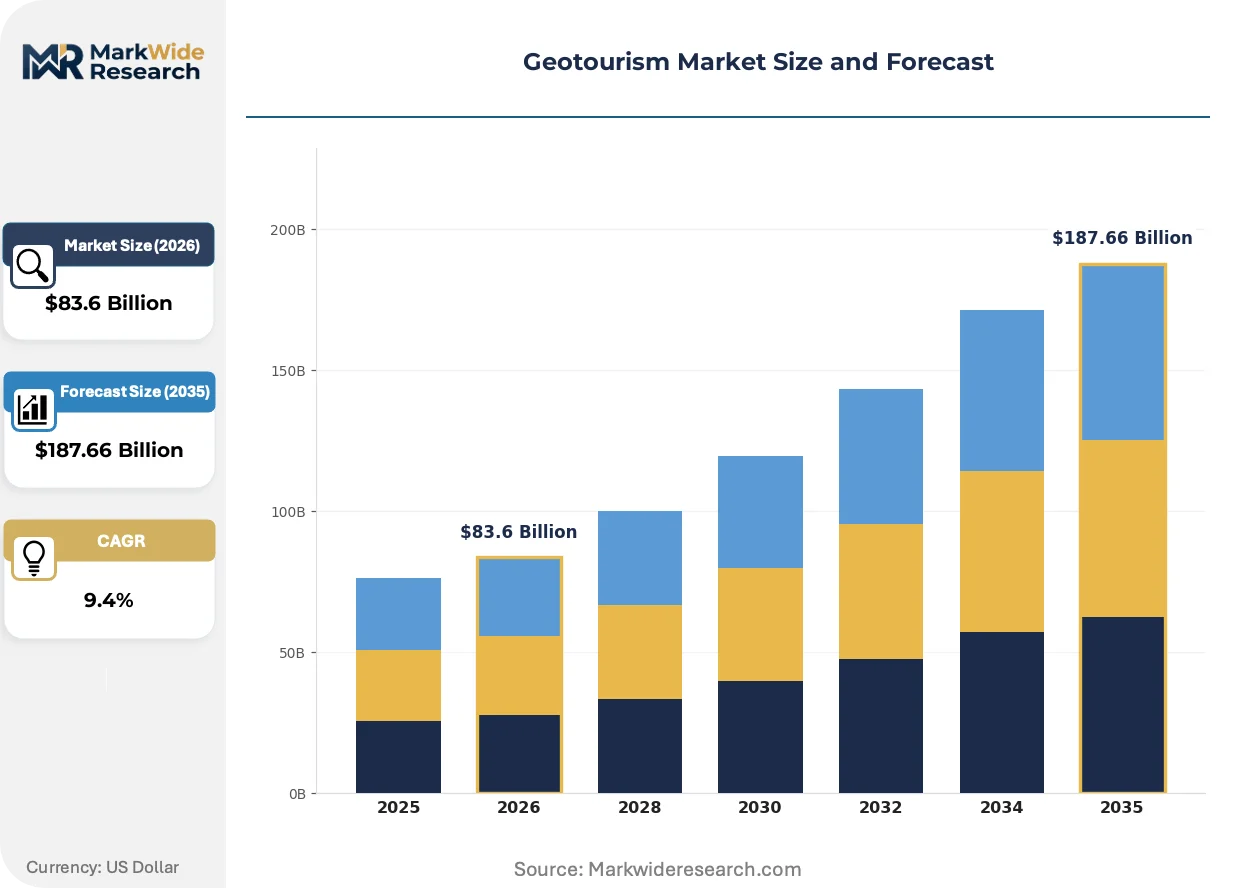
Market Dynamics
UNESCO Global Geoparks certification mandates are restructuring operator compliance costs and site access economics across European territories, forcing capacity limits that reshape revenue models.
Growth Catalysts
- EU Green Deal carbon accounting:Transport and lodging operators now embed emissions tracking into package pricing, creating premium tiers for low-carbon volcanic circuit access.
- Educational institution procurement:Universities and K-12 systems are expanding structured field program budgets, generating recurring demand for interpreter-led fossil bed and tectonic zone modules.
- Icelandic geothermal infrastructure:Trail network hardening and visitor center expansion ahead of peak flows is lifting daily capacity ceilings at volcanic destination clusters.
Market Restraints
- Certified interpreter scarcity:Specialized safety protocol training and geologic interpretation credentials create talent bottlenecks that constrain guided adventure segment expansion.
- Remote site access costs:Helicopter and small-vessel logistics to fragile geosites impose fixed cost structures that resist scaling below premium price points.
- Daily visitor volume caps:Iceland's national geopark authority and New Zealand's Department of Conservation enforce hard limits that compress revenue per site.
Strategic Opportunities
- Virtual tour channel expansion:Immersive digital replicas of fragile or remote geosites are opening access to mobility-limited and cost-constrained segments without physical capacity constraints.
- Laboratory-integrated workshops:Field collection combined with specimen analysis components commands margin premiums from academic and family segments seeking hands-on science literacy outcomes.
- Carbon border adjustment preparation:EU Green Deal compliance frameworks position early-adopter operators to capture long-haul visitor flows if aviation emissions pricing reshapes travel economics.
Industry Challenges
- Geopark designation timeline compression:Management plan development and conservation outcome documentation requirements strain operator administrative capacity.
- Track maintenance labor shortages:Seasonal workforce gaps in remote volcanic terrain regions delay infrastructure readiness ahead of peak visitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geotourism Market |
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $187.66 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eco-Tours, Adventure Tourism, Heritage Tours, Educational Tours End User: Individuals, Families, Educational Institutions, Corporate Groups Service Type: Guided Tours, Self-Guided Tours, Virtual Tours, Specialty Workshops Booking Channel: Online Platforms, Travel Agencies, Direct Booking, Social Media |
| Companies Covered | Natural Habitat Adventures, Mountain Travel Sobek, Abercrombie & Kent, G Adventures, National Geographic Expeditions, Intrepid Travel, Expedia Group, TUI AG, Earthwatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geotourism Market Emerging Trajectories
Digital replication technologies and emissions transparency requirements are fragmenting traditional guided tour economics while opening parallel revenue channels.
Immersive virtual reality capture systems are decentralizing geosite access by creating photorealistic digital twins of lava tubes, fossil quarries, and active fumarole fields. Academic institutions and family segments are adopting these platforms at accelerating rates for pre-trip planning and post-trip reinforcement. The technology is decentralizing interpretive service delivery from physical site dependency toward distributed digital subscription models.
EU Green Deal sustainable tourism directives are mandating granular carbon accounting for transport and lodging components across geopark-adjacent supply chains. Tour operators must now document emissions per passenger-kilometer and thermal feature visit. Adventure tourism segments face the steepest compliance costs, while virtual tour providers capture regulatory arbitrage by eliminating transport emissions entirely from their value propositions.
Visitor preference is fragmenting toward modular, self-assembled itineraries that unbundle traditional package components. Independent travelers are combining direct-to-site transport booking, freelance interpreter hiring, and dispersed lodging arrangements through digital platforms. New Zealand's geothermal corridor and Iceland's volcanic circuits display the most visible shift, with legacy tour operators losing pricing power to platform-mediated, componentized purchasing.
Geotourism Market Segmentation
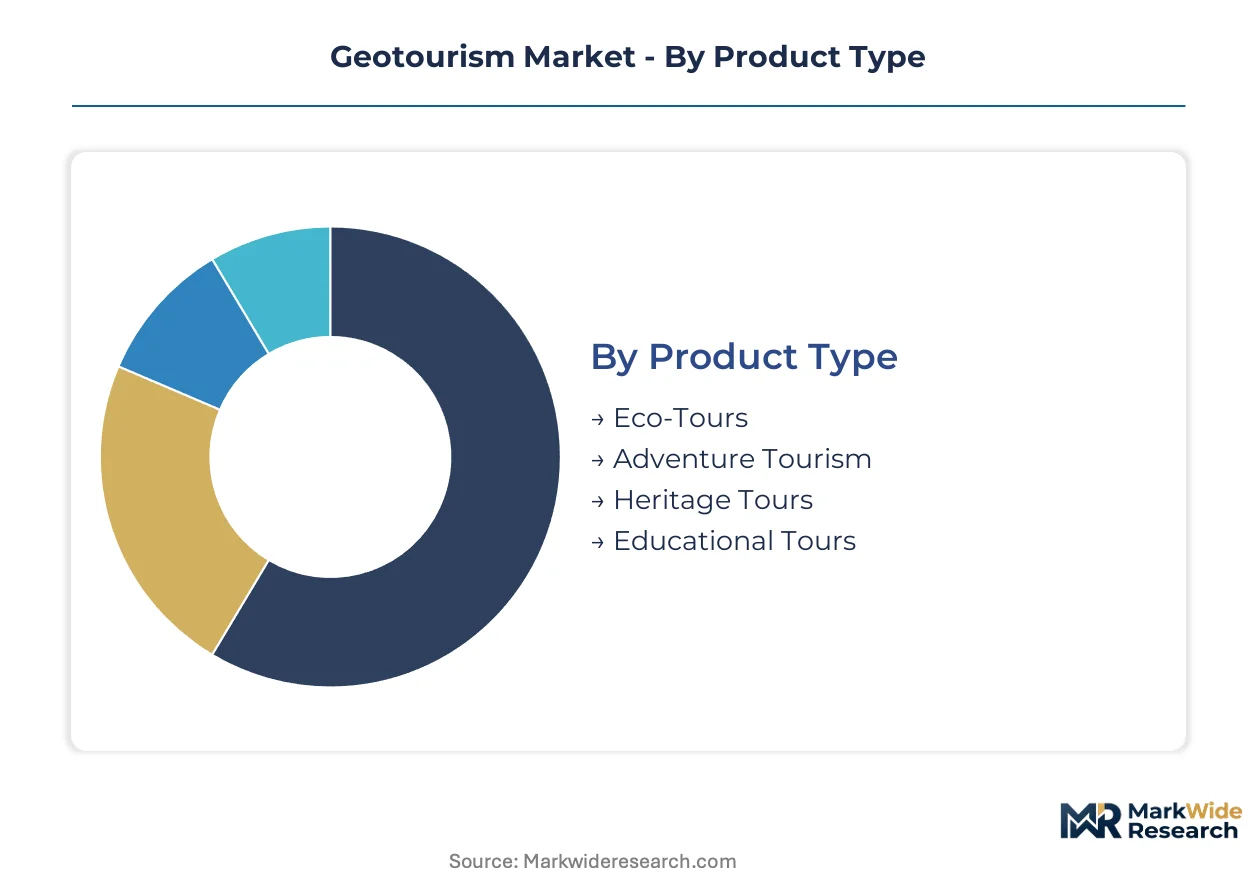
Geotourism operators structure product portfolios around certification requirements, visitor capacity constraints, and interpretation service economics. Segmentation reveals how UNESCO Global Geoparks compliance costs concentrate in guided adventure formats while digital channels capture regulatory arbitrage.
Product Type:
UNESCO Global Geoparks certification mandates reshape operator economics unevenly across product formats, with adventure segments absorbing steepest safety protocol burdens while heritage formats leverage pre-existing site designations.
- Adventure Tourism:Volcanic terrain circuits and active geothermal trekking require certified interpreter accompaniment and specialized equipment protocols under Iceland's national geopark authority regulations. Demand concentrates in Iceland's volcanic clusters and New Zealand's geothermal corridors where trail hardening investments expand daily capacity ceilings.
- Heritage Tours:Fossil bed and stratigraphic interpretation programs leverage existing UNESCO World Heritage designations without incremental certification overhead. Academic procurement drives recurring demand for field-based geologic time scale instruction at European and North American sites.
- Eco-Tours:Conservation-integrated itineraries emphasize low-impact access to fragile geosites with carbon offset bundling under EU Green Deal directives.
- Educational Tours:K-12 and university field programs require curriculum-aligned interpretation modules with laboratory specimen collection components.
Leading the category by volume: Heritage Tours. Growing fastest: Adventure Tourism.
End User:
Customer economics fragment sharply between institutional procurement cycles and leisure booking patterns, with educational segments generating recurring revenue streams that offset seasonal leisure volatility.
- Educational Institutions:Universities and K-12 systems operate on structured field program budgets with multi-year curriculum integration timelines. Procurement concentrates in European and North American institutions with established geology and earth science departments.
- Families:Multi-generational bookings prioritize hands-on science literacy outcomes and safety-assured volcanic or geothermal experiences during school holiday windows.
- Individuals:Solo travelers favor modular itinerary assembly through platform-mediated component booking in Iceland and New Zealand corridors.
- Corporate Groups:Team-building and executive retreat segments demand premium logistics with exclusive site access arrangements.
Volume leadership: Educational Institutions. Steepest expansion trajectory: Families.
Service Type:
Service format selection determines exposure to interpreter scarcity constraints and transport emissions accounting requirements under EU Green Deal frameworks.
- Guided Tours:Certified interpreter-led volcanic and geothermal excursions command premium pricing due to specialized safety credential scarcity and small-group capacity limits enforced by New Zealand's Department of Conservation.
- Virtual Tours:Immersive digital replicas of lava tubes and fossil quarries eliminate physical capacity constraints and transport emissions entirely. Academic and mobility-limited segments adopt these platforms for pre-trip planning and distributed access.
- Self-Guided Tours:Platform-mediated itinerary assembly enables independent travelers to unbundle transport, lodging, and interpretation components.
- Specialty Workshops:Field collection combined with laboratory analysis commands margin premiums from academic and family segments seeking specimen-based science literacy outcomes.
Dominant by volume: Guided Tours. Climbing the fastest: Virtual Tours.
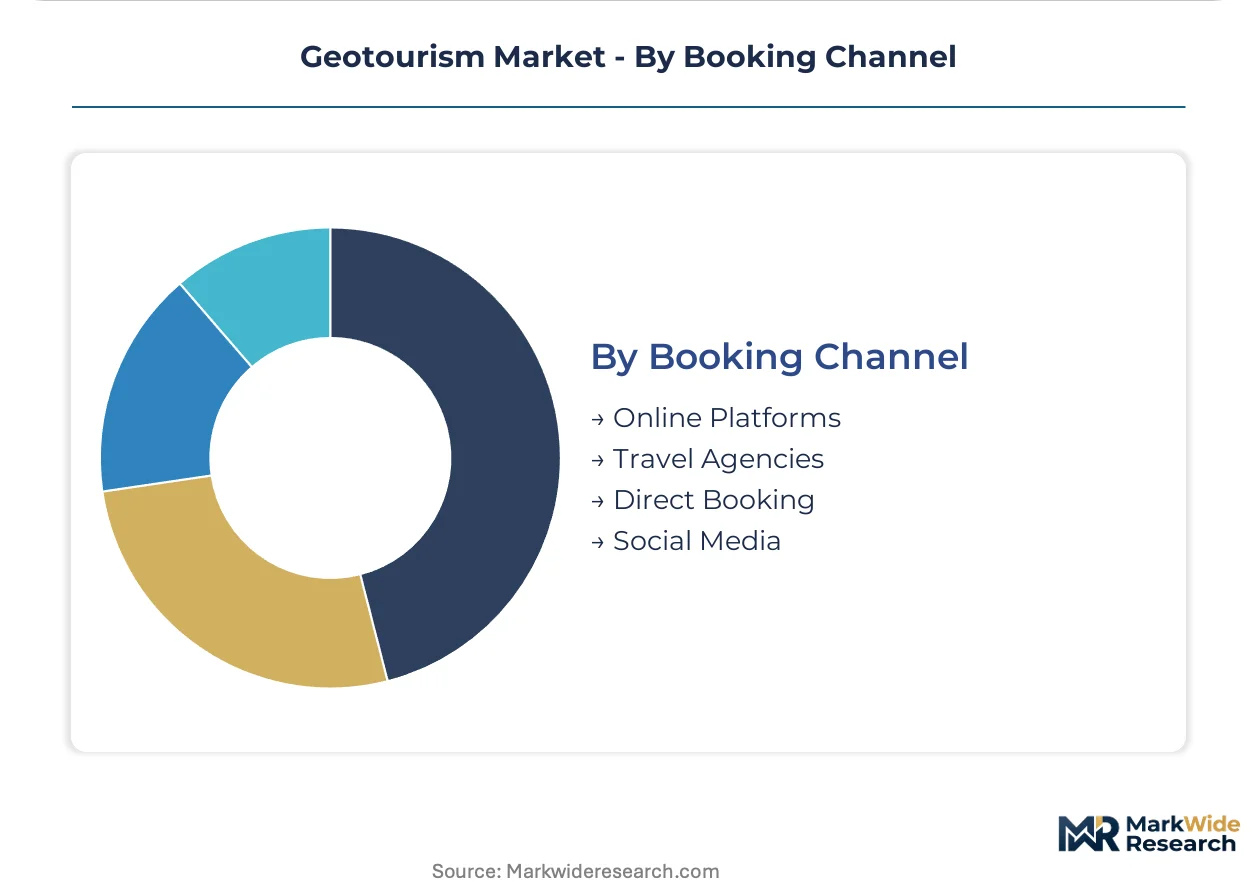
Booking Channel:
Channel economics reflect shifting preference toward componentized purchasing and regulatory transparency requirements that favor direct emissions documentation.
- Online Platforms:Digital marketplaces enable modular itinerary assembly with granular carbon accounting visibility per component under EU Green Deal compliance frameworks.
- Travel Agencies:Traditional intermediaries retain positioning in corporate and luxury heritage tour segments with consolidated logistics management.
- Direct Booking:Operator-owned channels capture margin and emissions data integrity for geopark-adjacent supply chains.
- Social Media:Influencer-mediated discovery drives impulse booking for visual-centric volcanic and geothermal destination content.
Volume concentration: Online Platforms. Gaining share fastest: Direct Booking.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Volcanic basalt formations and geothermal reservoir zones anchor geotourism demand across distinct national corridors. UNESCO Global Geoparks certification density and trail infrastructure maturity determine visitor throughput economics.
Iceland
Geothermal corridor development and volcanic terrain trekking sustain inbound tourism flows. The national geopark authority enforces daily visitor caps at thermal features and lava tube sites. Reykjanes Peninsula and Vatnajökull region operators expand trail hardening investments ahead of peak season capacity pressures.
New Zealand
Rotorua geothermal attractions and Tongariro Alpine Crossing circuits concentrate domestic and international visitation. The Department of Conservation mandates certified interpreter accompaniment for active volcanic zone access. Waikato and Bay of Plenty regions host expanding laboratory-integrated educational workshop infrastructure.
United States
Yellowstone caldera interpretation programs and Hawaii Volcanoes National Park lava viewing sustain heritage and adventure segment demand. National Park Service capacity management protocols limit daily entries at high-traffic geothermal features. Wyoming and Hawaii island economies depend on geosite visitor fee revenue streams.
Italy
Vesuvius archaeological-geologic integration and Etna active crater circuits anchor Mediterranean geotourism positioning. Regional park authorities in Campania and Sicily enforce track maintenance standards and eruption monitoring-based access suspensions. Sicilian operators develop carbon-accounted transport bundling under EU Green Deal compliance timelines.
Japan
Mount Fuji volcanic heritage designation and Kyushu onsen thermal traditions drive domestic and inbound visitation. The country's national geopark network coordinates with prefectural tourism boards on interpreter certification standards. Hakone and Beppu sub-regions expand virtual tour platform deployment for mobility-limited access segments.
Geotourism Market Vendor Landscape
Global expedition operators compete with regional heritage tour specialists across certification compliance and remote site access economics. Market structure fragments between premium polar-volcanic integrators, mass-market youth segment platforms, and academic field program contractors. Three archetypes dominate: certified interpreter-dependent adventure specialists, digital-virtual channel pure-plays, and institutional procurement contractors. Competitive moves concentrate on geopark designation acquisition and carbon accounting technology integration.
Within the premium expedition tier, Natural Habitat Adventures and Abercrombie & Kent occupy positions anchored in polar and volcanic remote access logistics. G Adventures exemplifies price-accessible youth segment positioning through platform-scaled geothermal trekking programs. These three entities represent divergent strategic bets on interpreter scarcity premiums versus volume-scaled digital distribution.
| Leading Market Players |
|---|
| Natural Habitat Adventures |
| Mountain Travel Sobek |
| Abercrombie & Kent |
| G Adventures |
| National Geographic Expeditions |
| Intrepid Travel |
| Expedia Group |
| TUI AG |
| Earthwatch |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon accounting mandates gate qualified supply and premium-tier pricing access by forcing transport and lodging operators to document emissions per passenger-kilometer and thermal feature visit. Compliance costs concentrate in guided adventure segments where certified interpreter scarcity props pricing power, while virtual tour providers capture regulatory arbitrage through zero-emission digital delivery.
Pricing Analysis
Service-bundling differentiation separates all-inclusive packages with certified interpreter accompaniment, equipment provision, and carbon offset credits from unbundled component pricing where travelers assemble transport, lodging, and freelance interpretation separately. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and group size, with premium tiers commanding scarcity rents at Iceland's capped volcanic sites. Cost compression in the standard tier intensifies as platform-mediated component booking erodes legacy operator margins. Educational institutions exhibit lowest price sensitivity due to multi-year curriculum integration budgets, while independent leisure travelers drive aggressive price comparison across modular itinerary assembly platforms.
Supply Chain Analysis
Seasonal workforce availability constraints in Iceland and New Zealand volcanic terrain regions limit interpreter certification pipeline throughput and trail maintenance crew deployment. Supply concentrates in these two countries for premium geothermal and volcanic circuit access, with Italy and Japan hosting secondary certified interpreter pools. The supply chain draws from specialized safety equipment manufacturers, immersive capture technology providers, and academic laboratory networks for specimen analysis components. Single-source vulnerability runs through helicopter and small-vessel logistics operators serving remote geosites. Distribution runs through direct operator channels, online platforms enabling modular assembly, and traditional travel agencies retaining corporate and luxury heritage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified interpreter scarcity constrains daily visitor capacity at prime geosites, propping pricing power for compliant operators and creating acquisition premiums for credential-holding assets.
For Market Incumbents: Acquire certified interpreter networks and geopark designation rights to consolidate scarce compliance assets before EU Green Deal enforcement tightens. Backward integration into immersive capture technology secures virtual tour channel positioning against digital pure-plays. Capacity addition in Iceland's Reykjanes Peninsula and New Zealand's Waikato region captures trail hardening investment returns ahead of peak season demand surges. For New Entrants and Emerging Players: Capture virtual tour platform white space serving mobility-limited and academic pre-trip planning segments where physical capacity constraints do not apply. Laboratory-integrated educational workshops targeting K-12 systems offer the most penetrable entry point given recurring procurement cycles and specimen-based differentiation. Go-to-market execution should prioritize direct institutional sales bypassing leisure travel platform intermediation. For Investors and Strategic Acquirers: Accelerating geopark designation timeline compression is the leading indicator that administrative capacity bottlenecks will drive rollup opportunities among smaller operators. Long-term viability across the analysis window favors entities combining physical site access rights with digital replication capabilities. Watch for carbon border adjustment implementation signals that would restructure long-haul visitor economics and reposition early EU Green Deal compliance adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Geopark Designation Acquisition | UNESCO Global Geoparks certification locks in visitor capacity rights and carbon accounting compliance frameworks. |
| Immersive Capture Technology Investment | Photorealistic digital twins of lava tubes and fossil quarries open parallel revenue channels beyond physical constraints. |
| Certified Interpreter Pipeline Development | Safety credential scarcity creates defensive moats around guided adventure segment pricing power. |
| Laboratory-Integrated Workshop Expansion | Specimen analysis components command margin premiums from academic and family procurement segments. |
| Carbon Accounting Platform Integration | Granular emissions documentation per passenger-kilometer satisfies EU Green Deal compliance and enables premium tier positioning. |
Methodological Framework
Document review covered geopark management plans, EU Green Deal sustainable tourism directives, and national conservation authority protocols, complemented by interviews with geotourism operators, certified interpreters, educational institution procurement officers, and immersive technology developers. Secondary validation drew from UNESCO Global Geoparks network documentation, Department of Conservation access permits data, and Iceland national geopark authority capacity reports. Bottom-up triangulation across operator revenue models and top-down validation against national tourism statistics anchored market sizing.
Cross-reference between historical visitor flow patterns and expert panel input on certification timeline and carbon pricing scenarios shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product type, end user procurement cycle, service format, and booking channel dimensions alongside geopark designation status and interpreter availability constraints. CAGRs derived from capacity-constrained demand curves and virtual tour adoption elasticity parameters, with inputs from trail hardening investment schedules and educational field program budget trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment implementation, geopark designation criteria evolution, and immersive technology substitution rates. Forecasts reflect assumptions on interpreter certification pipeline throughput, conservation authority capacity enforcement consistency, and platform-mediated itinerary assembly adoption curves. Material deviation in EU Green Deal enforcement timing or virtual tour technology cost curves warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Destination Management and Attractions
China Culinary Tourism Market
Destination Management and Attractions
Saudi Arabia Hajj Tourism Market
Destination Management and Attractions
Industrial Tourism Market
Destination Management and Attractions
Golf Tourism Market
Destination Management and Attractions
Hawaii Tourism Market
Destination Management and Attractions
Rural Tourism Market
Destination Management and Attractions
USA Casino Tourism Market
Destination Management and Attractions
Philippines Culinary Tourism Market
Destination Management and Attractions
Brazil Culinary Tourism Market
Destination Management and Attractions
Art Tourism Market
Destination Management and Attractions
Middle East Amusement Parks Market
Destination Management and Attractions
APAC Museums, Historical Sites, Zoos, and Parks Market
Destination Management and Attractions
Desert Island Tourism Market
Destination Management and Attractions
Heritage Tourism Market
Destination Management and Attractions
Italy Culinary Tourism Market
Destination Management and Attractions
MICE Tourism Market