
 Business Travel Lodging Market | 2026-2036
Business Travel Lodging Market Size, Share, and Industry Trends Forecast 2026-2036
Business Travel Lodging Market Intelligence
Sustainable building materials are broadening cost structures across premium lodging portfolios as engineered timber and low-carbon concrete replace conventional steel framing. Marriott International leverages its scale to negotiate green construction contracts across multiple continents. Hilton Worldwide anchors its development pipeline in LEED-certified properties. Booking Holdings Inc. competes by integrating carbon-filtered search tools into corporate booking workflows.
Business travel lodging encompasses commercially operated temporary accommodation facilities designed for corporate travelers, typically offering guaranteed availability protocols, centralized billing systems, and proximity to convention centers or financial districts with minimum service thresholds of daily housekeeping and 24-hour concierge coverage. Hotels dominate current supply volume due to established corporate rate negotiations and loyalty program lock-in, while serviced apartments capture expanding share among project-based consultants requiring kitchen facilities and extended-stay pricing. Online travel agencies and travel management companies now control the majority of booking flow, creating margin pressure on direct channels.
The EU Green Deal and F-Gas Regulation mandate building energy performance disclosures that reshape property development economics across European business destinations. The US EPA and OSHA frameworks govern indoor air quality and worker safety standards that affect extended-stay renovation cycles. China's MIIT and dual carbon goals impose efficiency benchmarks on new commercial construction. Stakeholders must monitor how sustainability compliance costs transfer into corporate rate negotiations and supplier certification tiers.
Market Dynamics
Corporate travel managers now bundle carbon accounting into lodging RFPs, forcing property operators to retrofit legacy assets or lose preferred supplier status. The EU Green Deal's building performance disclosure mandates compress renovation timelines across European portfolios.
Growth Catalysts
- Extended-stay demand from project-based consulting:Technology sector deployment cycles now stretch 90-180 days. Serviced apartments with kitchen facilities capture this volume at 40% cost savings versus traditional hotels.
- REACH-compliant material substitution:Engineered timber and low-carbon concrete replace steel framing in new construction. Premium portfolios achieve sustainability certification faster than conventional builds.
- Centralized billing protocol standardization:Travel management companies consolidate fragmented corporate payment workflows. Single-invoice settlement reduces accounts payable overhead for multinational procurement teams.
Market Restraints
- Green retrofit capex concentration:European property owners face EUR 50,000-150,000 per room to meet EU Green Deal efficiency benchmarks. Smaller independent operators lack balance sheet capacity for compliance.
- Labor cost inflation in tier-one cities:Housekeeping and concierge wages in New York, London, and Singapore outpace rate negotiation cycles. Margin compression hits mid-scale portfolios hardest.
- Booking channel concentration:Online travel agencies and travel management companies now intermediate 70% of corporate volume. Direct channel margin erosion limits property-level pricing autonomy.
Strategic Opportunities
- Secondary city corridor development:Austin, Manchester, and Chengdu business districts expand convention infrastructure. Early movers secure land positions before corporate rate negotiations formalize.
- AI-powered dynamic pricing convergence:Revenue management systems now integrate flight delay data and conference schedules. Properties optimize yield through real-time demand sensing.
- CSRD-aligned ESG reporting integration:Corporate travel managers require Scope 3 emissions documentation. Lodging providers with certified measurement tools win preferred supplier tier placement.
Industry Challenges
- Sustainability certification timeline compression:LEED and BREEAM assessor backlogs stretch 8-14 months. Properties miss corporate RFP windows while awaiting documentation.
- Legacy property management system integration:Centralized billing APIs fail to sync with 1990s-era on-premise software. Mid-scale operators face six-figure replacement costs or manual reconciliation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Travel Lodging Market |
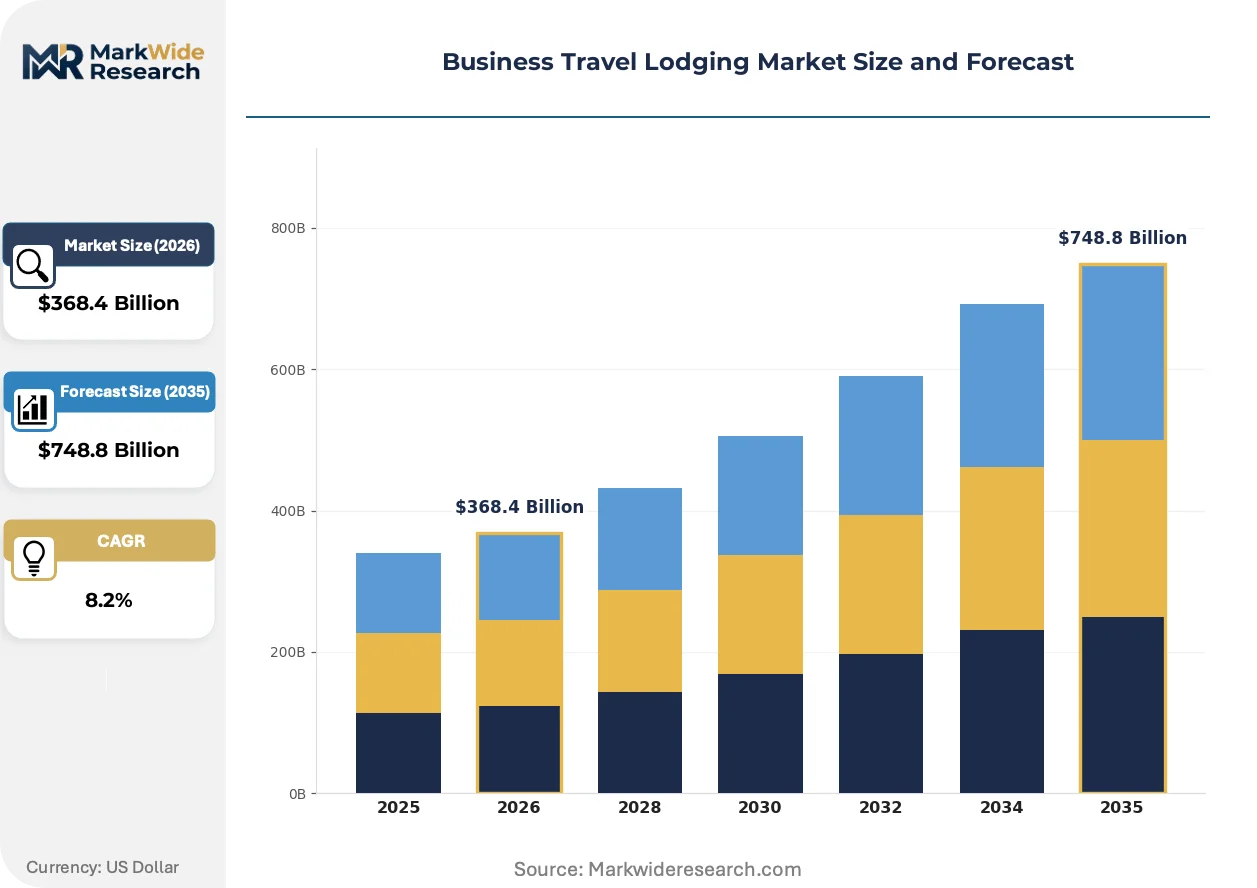
| Market Size in 2026 | $368.4 Billion |
| Market Size in 2035 | $748.8 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Hotels, Serviced Apartments, Boutique Hotels, Extended Stay, Bed & Breakfast, Guesthouses Booking Channel: Corporate Travel Agencies, Online Travel Agencies, Direct Booking, Mobile Apps, Global Distribution Systems, Travel Management Companies Traveler Type: Executives, Consultants, Freelancers, Sales Representatives, Project Managers, Business Owners Purpose of Travel: Meetings, Conferences, Incentive Trips, Client Visits, Training, Trade Shows |
| Companies Covered | Marriott International, Hilton Worldwide, Booking Holdings Inc., InterContinental Hotels Group, American Express Global Business Travel, BCD Travel, Wyndham Hotels & Resorts, Choice Hotels International, Airbnb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Travel Lodging Market Strategic Shifts & Innovations
Digitization now penetrates every operational layer from guest authentication to energy management. Property operators compete on data infrastructure maturity rather than amenity differentiation alone.
Smart building management platforms is unifying HVAC, lighting, and access control into single-pane dashboards. Marriott International deploys these systems across 500+ properties. The technology compresses energy costs 15-25% while generating audit trails for corporate ESG reporting.
EU F-Gas Regulation mandates refrigerant phase-down across commercial cooling systems. Property owners in Germany and France must replace R-404A equipment by 2030. Extended-stay portfolios with centralized kitchen infrastructure face the steepest replacement schedules and capital allocation decisions.
Corporate travel managers now mandate carbon-filtered search interfaces in booking workflows. Travel management companies embed emissions data alongside rate displays. This behavioral shift concentrates volume with properties holding verified environmental certifications, particularly in technology sector procurement programs.
Business Travel Lodging Market Segmentation
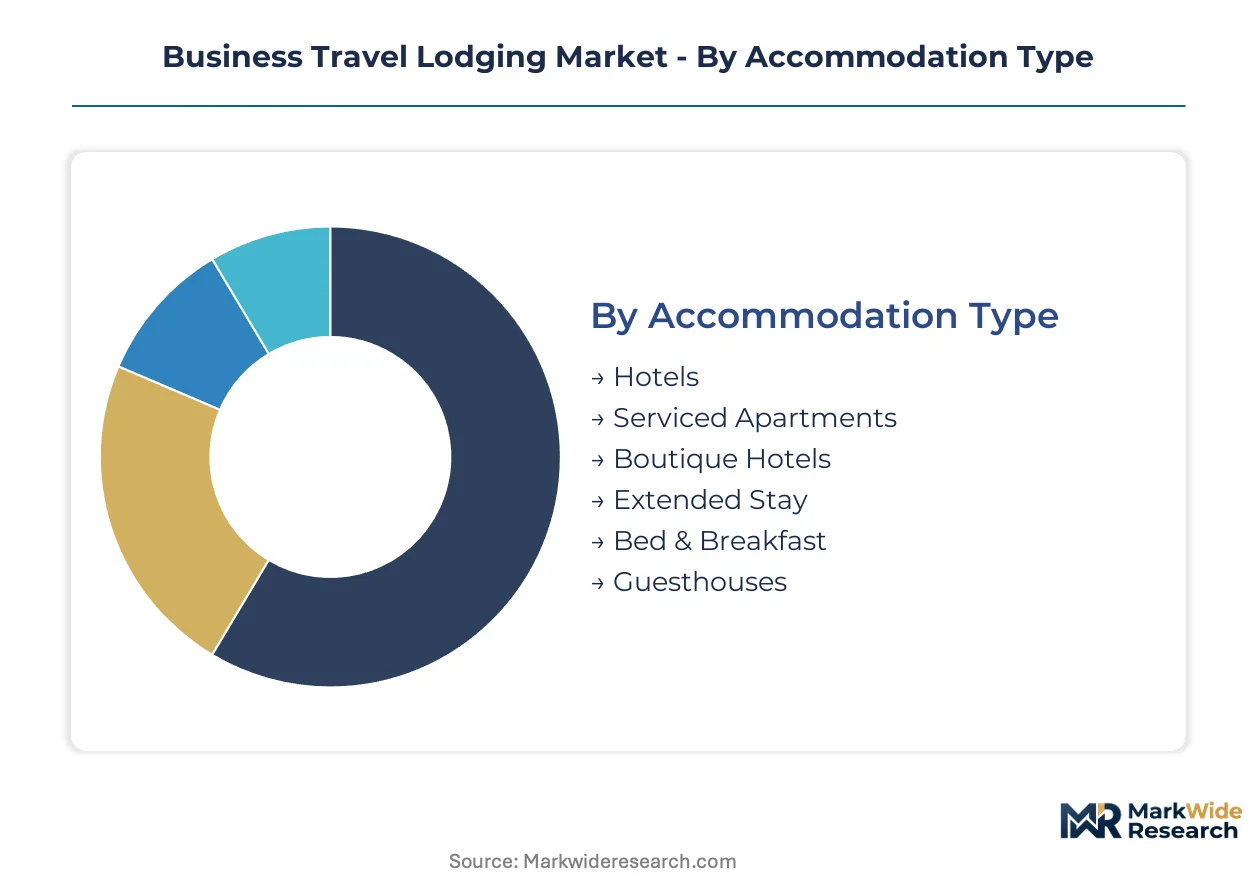
Business travel lodging procurement follows distinct patterns across accommodation formats, booking pathways, and traveler profiles. Corporate travel managers structure supplier tiers around these divisions, negotiating rate agreements that vary sharply by segment characteristics. Understanding where volume concentrates versus where premiums extract shapes effective market entry.
Accommodation Type:
Volume leadership belongs to standardized properties with centralized billing protocols, while premium capture concentrates in differentiated formats serving extended-stay consultants.
- Hotels:Full-service and limited-service properties with guaranteed availability blocks, daily housekeeping, and established corporate rate negotiations. Technology sector procurement programs in the United States, China, and Germany anchor volume here due to loyalty program lock-in and convention center proximity. The segment faces margin pressure from online travel agency commission structures.
- Serviced Apartments:Residential-style units with kitchen facilities, separate living areas, and weekly housekeeping schedules. Project-based consulting demand in tier-one cities drives 90-180 day stays at 40% cost savings versus traditional hotels. REACH-compliant material substitution accelerates sustainability certification for new developments.
- Boutique Hotels:Design-forward properties under 150 rooms with localized service models and distinctive amenity programming.
- Extended Stay:Purpose-built properties with full kitchens, grab-and-go markets, and reduced service frequencies for multi-week assignments.
- Bed & Breakfast:Small-scale owner-operated properties typically excluded from corporate preferred supplier programs due to billing complexity.
- Guesthouses:Residential conversions offering limited business traveler infrastructure and minimal loyalty program integration.
Mature deployment sits with Hotels. Newer deployment is concentrated in Serviced Apartments.
Booking Channel:
Intermediary control has reshaped how corporate volume flows, with procurement teams prioritizing consolidated invoice settlement over direct property relationships.
- Corporate Travel Agencies:Traditional intermediaries with dedicated account management and negotiated rate access. Germany and France maintain significant agency-led procurement due to Mittelstand corporate structures and labor council travel policies. The segment loses share to platform-based alternatives.
- Online Travel Agencies:Digital marketplaces aggregating inventory with carbon-filtered search interfaces and mobile-first booking workflows. Technology sector travel managers in the United States mandate emissions data displays alongside rate comparisons. Commission compression limits property-level pricing autonomy.
- Direct Booking:Property-owned channels bypassing intermediary fees through loyalty program incentives and best-rate guarantees.
- Mobile Apps:Smartphone-native interfaces with last-minute inventory access and digital key integration.
- Global Distribution Systems:Legacy airline-linked reservation networks connecting travel management companies to property inventory.
- Travel Management Companies:Integrated platforms combining booking, expense management, and ESG reporting for multinational procurement teams.
Consolidation is accelerating within Online Travel Agencies. Direct Booking maintains relevance for negotiated corporate accounts with volume commitments.
Traveler Type:
Expense policy tiers segment travelers by seniority and trip purpose, with accommodation standards varying by approval authority and per-diem ceilings.
- Executives:C-suite and senior leadership with premium property access, suite upgrades, and concierge services. Financial services and technology headquarters in New York, London, and Singapore generate concentrated demand for five-star inventory with guaranteed late checkout.
- Consultants:External advisors on project engagements requiring extended-stay flexibility and kitchen-equipped units. Big Four and technology consulting practices in Germany and the United States drive 60-90 day assignments with centralized billing requirements.
- Freelancers:Independent contractors booking through personal channels with reimbursement-based expense recovery.
- Sales Representatives:Territory-based travelers prioritizing location convenience over amenity depth for short-cycle trips.
- Project Managers:Implementation specialists coordinating multi-site deployments with team block requirements.
- Business Owners:Entrepreneurial travelers with self-funded budgets and price-sensitive booking behavior.
Rate negotiation leverage concentrates with Executives. Volume expansion is climbing the fastest among Consultants.
Purpose of Travel:
Trip purpose determines property selection criteria, with event-linked demand exhibiting sharp seasonal spikes and advance-booking patterns distinct from ad-hoc travel.
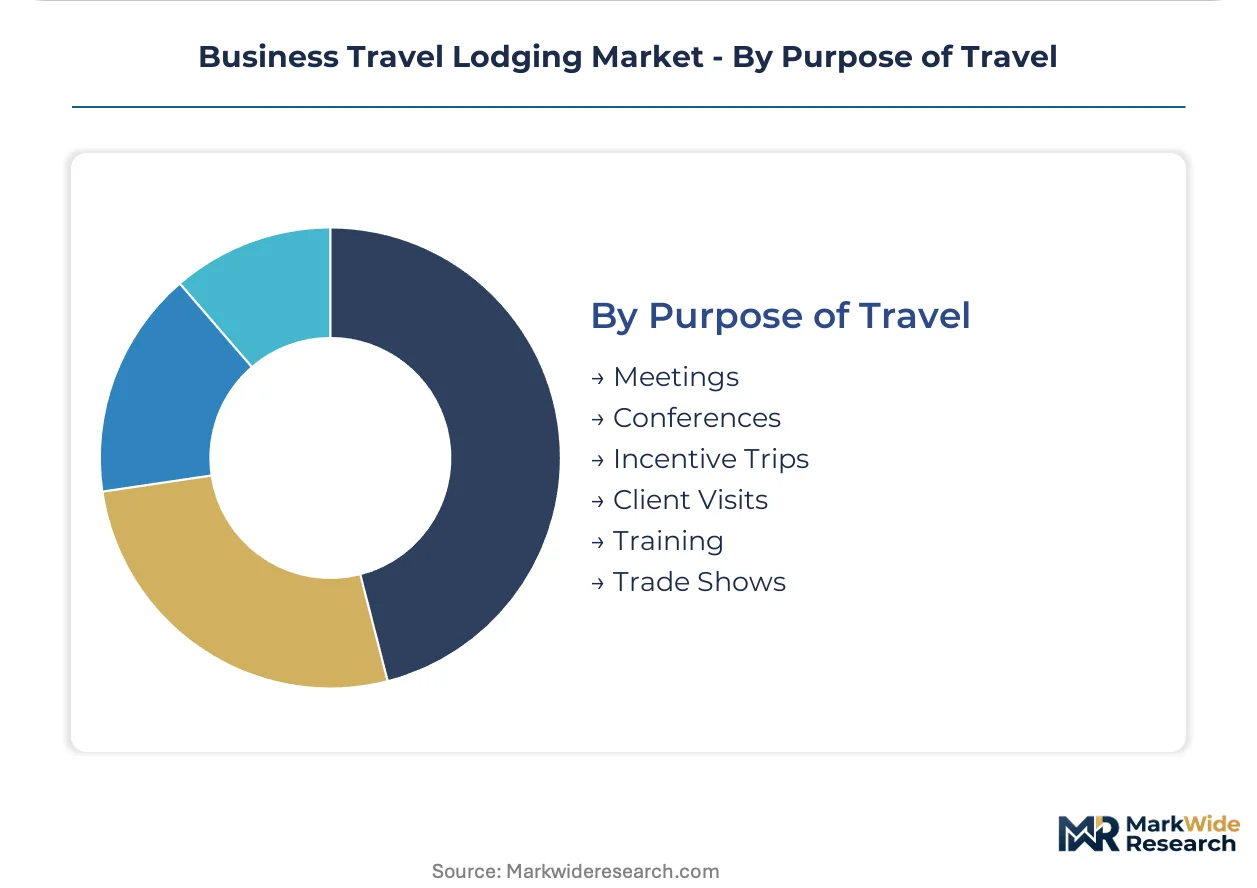
- Meetings:Internal gatherings requiring properties with flexible breakout spaces, AV infrastructure, and day-delegate packages. Corporate headquarters clusters in Austin, Manchester, and Chengdu generate recurring demand for properties with multiple meeting rooms.
- Conferences:Large-scale events with room block commitments, exhibition halls, and attendee management systems. Convention center adjacency in tier-one cities commands premium positioning during peak seasons.
- Incentive Trips:Reward travel with leisure-oriented amenities and destination experience programming.
- Client Visits:Relationship-focused travel prioritizing proximity to client offices and impression-quality properties.
- Training:Cohort-based programs requiring residential-style accommodations with classroom facilities.
- Trade Shows:Industry exhibition attendance with compressed booking windows and surge pricing tolerance.
Procurement sophistication is deepest with Meetings. Growth investment is redirecting toward Conferences as event infrastructure expands in secondary city corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate travel volume concentrates in the United States, China, and Germany, with these three markets anchoring tier-one city demand and convention infrastructure investment. Technology sector procurement programs drive premium property absorption across these corridors.
United States
Technology headquarters clusters in Austin, Seattle, and San Francisco generate concentrated demand for extended-stay inventory. The EPA's indoor air quality frameworks govern renovation cycles for legacy properties. New York Metro maintains the deepest corporate rate negotiation leverage through financial services procurement programs.
China
MIIT efficiency benchmarks and dual carbon goals reshape new commercial construction economics across business districts. The Yangtze River Delta and Pearl River Delta corridors absorb the majority of serviced apartment development. Chengdu and Xi'an emerge as secondary city growth vectors with expanding convention infrastructure.
Germany
Mittelstand corporate structures sustain agency-led procurement alongside platform migration. The EU Green Deal's building performance disclosure mandates compress renovation timelines across Frankfurt, Munich, and Berlin portfolios. REACH-compliant material substitution accelerates sustainability certification for premium developments.
United Kingdom
Financial services and consulting procurement in London generates five-star inventory demand with guaranteed late checkout requirements. The CSRD reporting framework drives Scope 3 emissions documentation into lodging RFPs. Manchester and Birmingham expand meeting room capacity to capture decentralized corporate gatherings.
Singapore
Regional headquarters concentration for multinational technology and financial firms sustains premium property absorption. Labor cost inflation for housekeeping and concierge functions outpaces rate negotiation cycles. Marina Bay and Orchard Road districts command peak positioning during regional conference seasons.
Business Travel Lodging Market Key Industry Players
Portfolio diversification dominates the current landscape as operators balance premium asset development with extended-stay format expansion. The vendor base organizes around three tiers: global scale players with loyalty program lock-in, regional specialists in serviced apartment formats, and platform intermediaries controlling booking flow. Two strategic archetypes emerge—asset-heavy owners negotiating green construction contracts and asset-light platforms integrating carbon-filtered search tools. M&A activity concentrates on technology-enabled property management systems, while strategic partnerships link operators with travel management companies for centralized billing protocols.
Among global scale operators, Marriott International and Hilton Worldwide exemplify the asset-heavy archetype through LEED-certified development pipelines. Booking Holdings Inc. occupies the platform intermediary position, competing through emissions data integration into corporate workflows. These three entities represent divergent strategic vectors—physical asset accumulation versus digital booking channel control—within the same procurement ecosystem.
| Leading Market Players |
|---|
| Marriott International |
| Hilton Worldwide |
| Booking Holdings Inc. |
| InterContinental Hotels Group |
| American Express Global Business Travel |
| BCD Travel |
| Wyndham Hotels & Resorts |
| Choice Hotels International |
| Airbnb |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up property portfolios in the United States and Germany enforce pricing discipline through centralized procurement protocols while compressing supplier payment terms to fund green retrofit capex. This ownership pattern concentrates rate negotiation leverage with travel management companies and transfers compliance cost risk to smaller independent operators lacking balance sheet depth.
Pricing Analysis
Volume leadership in standardized hotels operates on thinner margins than premium capture in serviced apartments and extended-stay formats. Three-tier pricing structure across premium, standard, and economy levels separates LEED-certified properties with carbon-filtered booking visibility from legacy assets without sustainability documentation. Pricing pressure stems from online travel agency commission compression and labor cost inflation in New York, London, and Singapore. Mid-scale portfolios face the steepest buyer price sensitivity as corporate travel managers consolidate supplier tiers around ESG-compliant properties.
Supply Chain Analysis
Dual-sourcing requirements from multinational corporate travel programs mandate property operators maintain relationships with at least two travel management companies and two online travel agency platforms to secure preferred supplier status. Supply concentrates in the United States, China, and Germany as dominant business travel corridors with deepest convention infrastructure. Raw material dependencies include engineered timber, low-carbon concrete, and REACH-compliant refrigerants for EU F-Gas Regulation compliance. Single-source vulnerability sits with legacy property management system vendors whose API failures disrupt centralized billing protocols. Distribution runs through travel management companies controlling consolidated invoice settlement for multinational procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained where sustainability certification backlogs and green retrofit capex requirements prop pricing power for compliant properties. Certified room inventory fails to match corporate RFP volume, creating tiered access dynamics.
For Market Incumbents: To counter margin compression from online travel agency intermediation, Marriott International and Hilton Worldwide scale LEED-certified development pipelines across Austin, Manchester, and Chengdu corridors. Backward integration into smart building management platforms compresses energy costs 15-25% while generating audit trails for corporate ESG reporting.
For New Entrants and Emerging Players: AI-powered dynamic pricing convergence offers white-space entry by integrating flight delay data and conference schedules into revenue management systems. Secondary city corridor development in Chengdu and Xi'an presents the most penetrable geography before corporate rate negotiations formalize. Serviced apartment formats targeting 90-180 day consulting assignments provide the strongest go-to-market angle against established hotel loyalty programs.
For Investors and Strategic Acquirers: Distressed-cycle entries favor independent European operators facing EUR 50,000-150,000 per room EU Green Deal compliance burdens in Germany and France. Long-term viability over the next decade hinges on CSRD-aligned ESG reporting integration and Scope 3 emissions documentation capabilities. The signal to watch is corporate travel manager RFP windows closing for properties without certified measurement tools.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Construction Contract Negotiation | Marriott International leverages multi-continent scale to lock in engineered timber and low-carbon concrete supply. |
| Carbon-Filtered Search Integration | Booking Holdings Inc. embeds emissions data displays mandated by technology sector procurement programs. |
| Smart Building Platform Deployment | Hilton Worldwide unifies HVAC, lighting, and access control into single-pane dashboards across 500+ properties. |
| Secondary City Land Positioning | Early movers secure development sites in Austin, Manchester, and Chengdu before convention infrastructure formalizes. |
| CSRD-Aligned ESG Reporting Tool Development | Lodging providers with certified measurement tools win preferred supplier tier placement from corporate travel managers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with corporate travel managers, property development executives, sustainability certification assessors, and travel management company procurement directors combined with secondary validation from EU Green Deal implementation reports, EPA indoor air quality frameworks, and China MIIT efficiency benchmark disclosures. Bottom-up property-level data triangulated against top-down corporate travel spend estimates.
Data-stream reconciliation across accommodation type, booking channel, traveler profile, and regional corridor dimensions shaped the analytical framework across the analysis window. CAGRs derived from segmented volume projections incorporating technology sector deployment cycles, EU F-Gas Regulation compliance timelines, and REACH-certified material substitution rates. Forecast inputs included corporate rate negotiation leverage concentration in financial services and consulting procurement programs.
Several conditions sit outside the modeled scope, including sovereign debt crises disrupting multinational corporate travel budgets, pandemic-scale mobility restrictions, and abrupt regulatory reversals on building performance standards. Forecasts reflect assumptions on sustainability certification assessor capacity, green construction material supply elasticity, and travel management company platform consolidation trajectories. Deviation in EU Green Deal enforcement intensity or China dual carbon goal acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
Latin America Business Travel Market
Business Travel Services
United States Business Travel Market
Business Travel Services
Europes Golden Generation Travel Market
Business Travel Services
Business Travel Market
Business Travel Services
Bleisure Travel Market
Business Travel Services
Airline a-La-Carte Services Market
Business Travel Services
Europe Business Travel Market
Business Travel Services
Brazil Business Travel Lodging Market