
 Business Travel Market | 2026-2036
Business Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Business Travel Market Intelligence
Subscription-based travel management platforms is pivoting how corporations procure business travel services, shifting from transactional commissions to recurring software fees. BCD Travel leverages its global agency network to sustain service depth across fragmented regional markets. Navan differentiates through embedded expense automation that reduces reconciliation overhead for finance teams.
Business travel encompasses the commercial movement of personnel for meetings, training, client engagement, and events, typically involving negotiated corporate rates, duty-of-care protocols, and centralized billing through enterprise resource planning integrations. Transportation and accommodation segments anchor revenue volume, while online platforms and corporate travel management channels capture expanding margin pools as self-service adoption rises among SMEs. Events management remains structurally smaller but commands premium pricing due to complex logistics coordination and vendor consolidation requirements.
FDA oversight of health-related travel, EU GDPR constraints on passenger data handling, and the EU Green Deal emissions disclosure mandates collectively reshape platform architecture and supplier certification requirements. Corporate procurement teams now face dual compliance pressures from financial regulators and sustainability frameworks. Stakeholders must monitor how carbon accounting standards evolve to determine whether offset integration becomes a table-stakes feature or a premium differentiator.
Market Dynamics
Corporate travel managers now face pressure from the EU Green Deal's emissions disclosure mandates, forcing platform architecture redesigns that embed carbon accounting into every booking workflow. This regulatory compression is accelerating consolidation around integrated suites that combine transportation, lodging, and expense automation.
Growth Catalysts
- EU CSRD carbon reporting:European firms must track travel-related emissions, creating mandatory demand for embedded sustainability dashboards within booking platforms.
- SME self-service adoption:Mid-market companies are abandoning traditional agency relationships for software-first platforms that reduce per-trip management overhead.
- API-first distribution:Transportation and accommodation inventory is consolidating through open connectivity standards, enabling real-time corporate rate access across fragmented supplier bases.
Market Restraints
- Aviation fuel cost volatility:Jet fuel price swings compress negotiated corporate rate stability, forcing frequent contract renegotiations between enterprises and carriers.
- GDPR passenger data constraints:Cross-border data handling restrictions create friction for platforms attempting to deliver seamless multi-country itineraries.
- Video conferencing substitution:Persistent remote collaboration tools capture share of internal meetings and training events that previously required physical travel.
Strategic Opportunities
- India's PLI scheme for hospitality tech:Domestic software development incentives could spawn regional platforms serving Asia-Pacific corporate travel procurement.
- Rail electrification corridors:High-speed rail networks across France, Germany, and Spain offer lower-carbon alternatives for intra-European business mobility.
- ISO 14064 carbon verification:Third-party emissions certification is emerging as a procurement differentiator for sustainability-focused enterprise buyers.
Industry Challenges
- Legacy ERP integration complexity:Established finance systems require custom middleware development to ingest real-time travel spend data from modern platforms.
- Duty-of-care protocol fragmentation:Jurisdictional variations in employer liability create compliance overhead for multinational travel programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Travel Market |
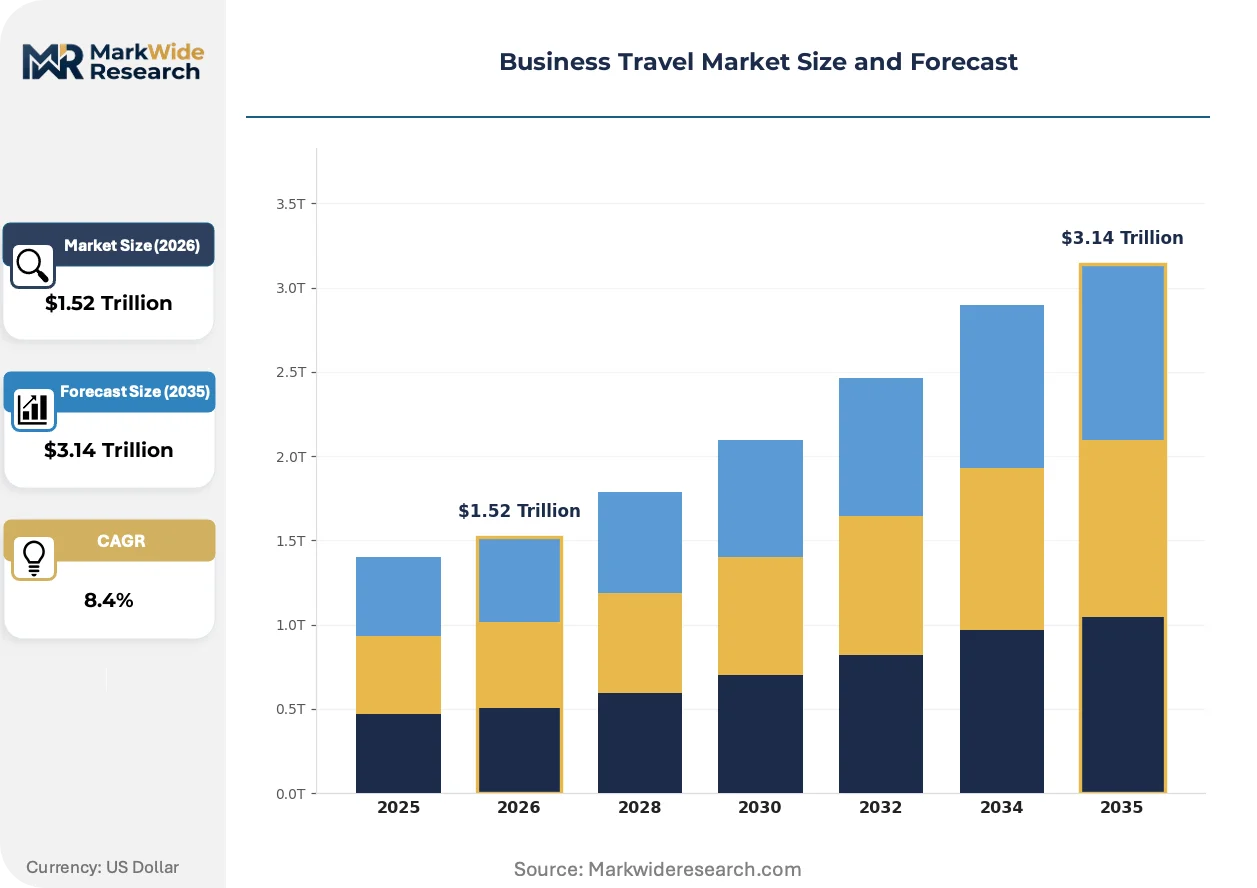
| Market Size in 2026 | $1.52 Trillion |
| Market Size in 2035 | $3.14 Trillion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Accommodation, Events Management, Travel Insurance Customer Type: Corporates, SMEs, Freelancers, Government Agencies Booking Channel: Travel Agency, Direct Booking, Online Platforms, Corporate Travel Management Travel Purpose: Meetings, Conferences, Training, Client Visits |
| Companies Covered | American Express Global Business Travel, BCD Travel, CWT, Flight Centre Travel Group, Expedia Group, Corporate Travel Management, FCM Travel Solutions, TravelPerk, Navan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Travel Market Strategic Shifts & Innovations
Distributed ledger architectures and embedded finance capabilities are reconfiguring how corporate travel services are procured, priced, and reconciled. These shifts compress intermediary layers while expanding data transparency.
Blockchain-based settlement protocols are decentralizing payment flows between corporations, travel management companies, and individual suppliers. Large pharmaceutical and professional services firms are piloting smart contracts that automate invoice reconciliation upon trip completion. This architecture eliminates float periods and reduces disputes over corporate rate applicability.
The EU AI Act's risk classification framework is reshaping how algorithmic pricing engines operate within European markets. Automated fare prediction tools must now disclose training data provenance and decision logic to corporate procurement auditors. German and French travel platforms are investing in explainable AI documentation to maintain enterprise contract eligibility.
Finance teams are consolidating travel and expense workflows into unified software categories, displacing standalone point solutions. Procurement committees now evaluate platforms on real-time spend visibility rather than negotiated discount depth alone. This behavioral pivot is most pronounced in United States technology sector verticals where finance automation maturity outpaces other industries.
Business Travel Market Segmentation
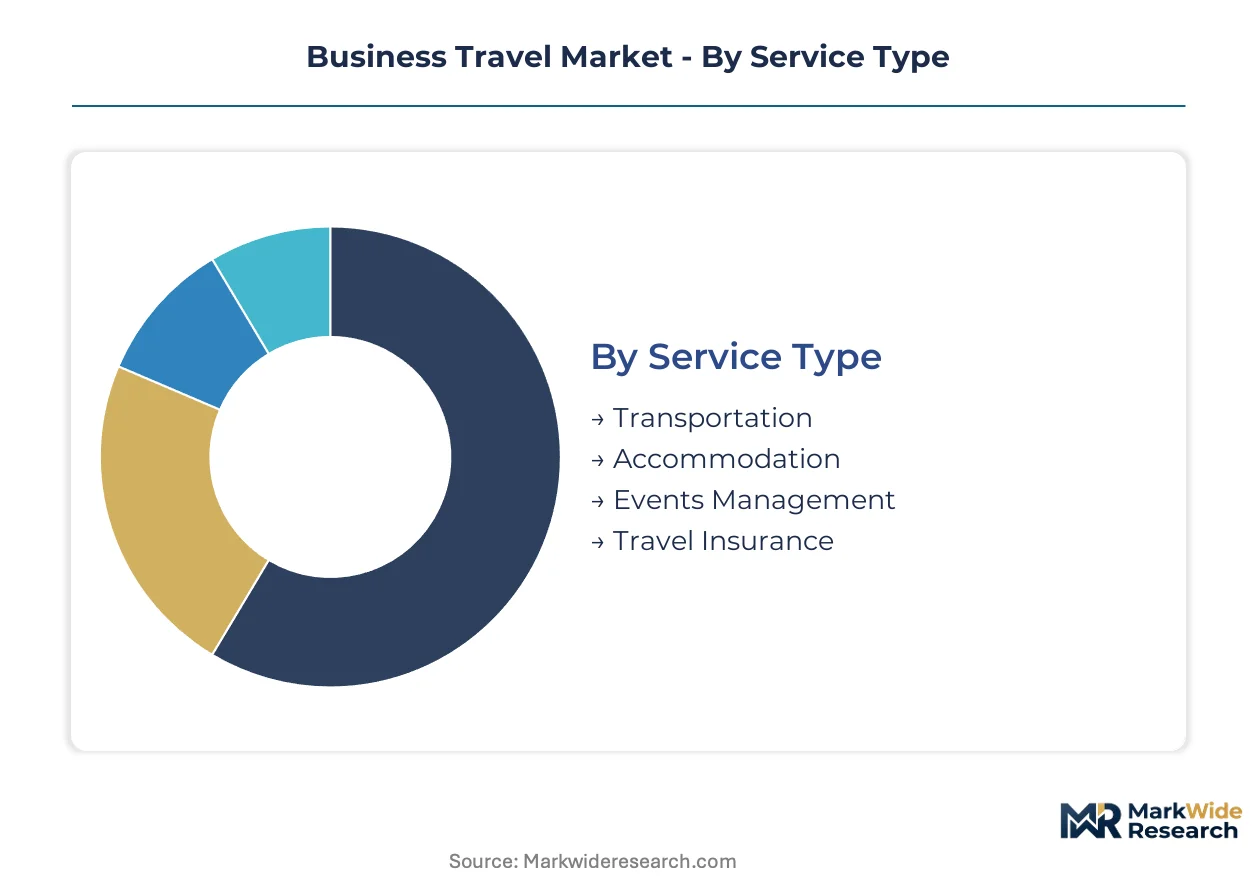
Business travel procurement divides sharply across service delivery models, customer scale, and booking infrastructure. Each segmentation axis reveals distinct margin structures and technology requirements that shape vendor strategy.
Service Type:
Transportation and accommodation segments demand the heaviest capital deployment in inventory systems and supplier contract portfolios.
- Transportation:Encompasses commercial aviation, rail networks, ground transport, and emerging mobility services under negotiated corporate rate frameworks. Airlines concentrate capacity investment in hub-and-spoke configurations serving United States technology corridors and European financial centers. Corporate buyers prioritize direct API connectivity to bypass global distribution system fees.
- Accommodation:Covers hotel properties, serviced apartments, and extended-stay facilities contracted through centralized procurement programs. Property management system integration determines rate visibility and availability accuracy for enterprise travel managers. Sustainability certification tiers increasingly filter supplier eligibility under EU Green Deal disclosure mandates.
- Events Management:Complex logistics coordination spanning venue sourcing, attendee registration, and vendor consolidation for corporate gatherings. Premium pricing reflects bespoke service delivery and liability management requirements.
- Travel Insurance:Duty-of-care coverage products bundled with booking platforms or procured separately through risk management departments. Policy automation reduces claims processing overhead for multinational programs.
Transportation absorbs the bulk of installed capacity; events management is expanding most quickly as in-person corporate gatherings rebound.
Customer Type:
Procurement sophistication varies dramatically by organizational scale and budget authority concentration.
- Corporates:Large enterprises with dedicated travel managers, negotiated global rate agreements, and ERP-integrated expense workflows. United States technology sector verticals outpace other industries in platform automation adoption.
- SMEs:Mid-market companies abandoning traditional agency relationships for self-service software platforms that reduce per-trip management overhead. Subscription pricing models displace transaction-based commissions.
- Freelancers:Independent professionals booking through consumer-facing platforms with limited corporate rate access. Reimbursement friction drives demand for embedded expense capture tools.
- Government Agencies:Public sector procurement subject to competitive bidding requirements and domestic carrier preference regulations. Budget approval cycles extend booking lead times significantly.
Corporates dominate current spend volume; SMEs are gaining share fastest as platform economics improve for mid-market segments.
Booking Channel:
Channel selection determines data ownership, rate transparency, and reconciliation automation potential.
- Travel Agency:Traditional intermediaries maintaining service depth through global networks and emergency support capabilities. BCD Travel sustains relevance via regional office density.
- Direct Booking:Supplier-native reservations bypassing intermediary fees but fragmenting spend visibility across corporate programs. Airlines and hotel chains invest in corporate portal development.
- Online Platforms:Consumer-grade interfaces adapted for business use with limited policy enforcement and duty-of-care features. Price transparency attracts cost-conscious segments.
- Corporate Travel Management:Integrated suites combining booking, expense automation, and sustainability tracking. Navan differentiates through embedded finance capabilities that reduce reconciliation overhead.
Corporate travel management channels capture margin expansion; online platforms face pressure to add enterprise-grade compliance features.
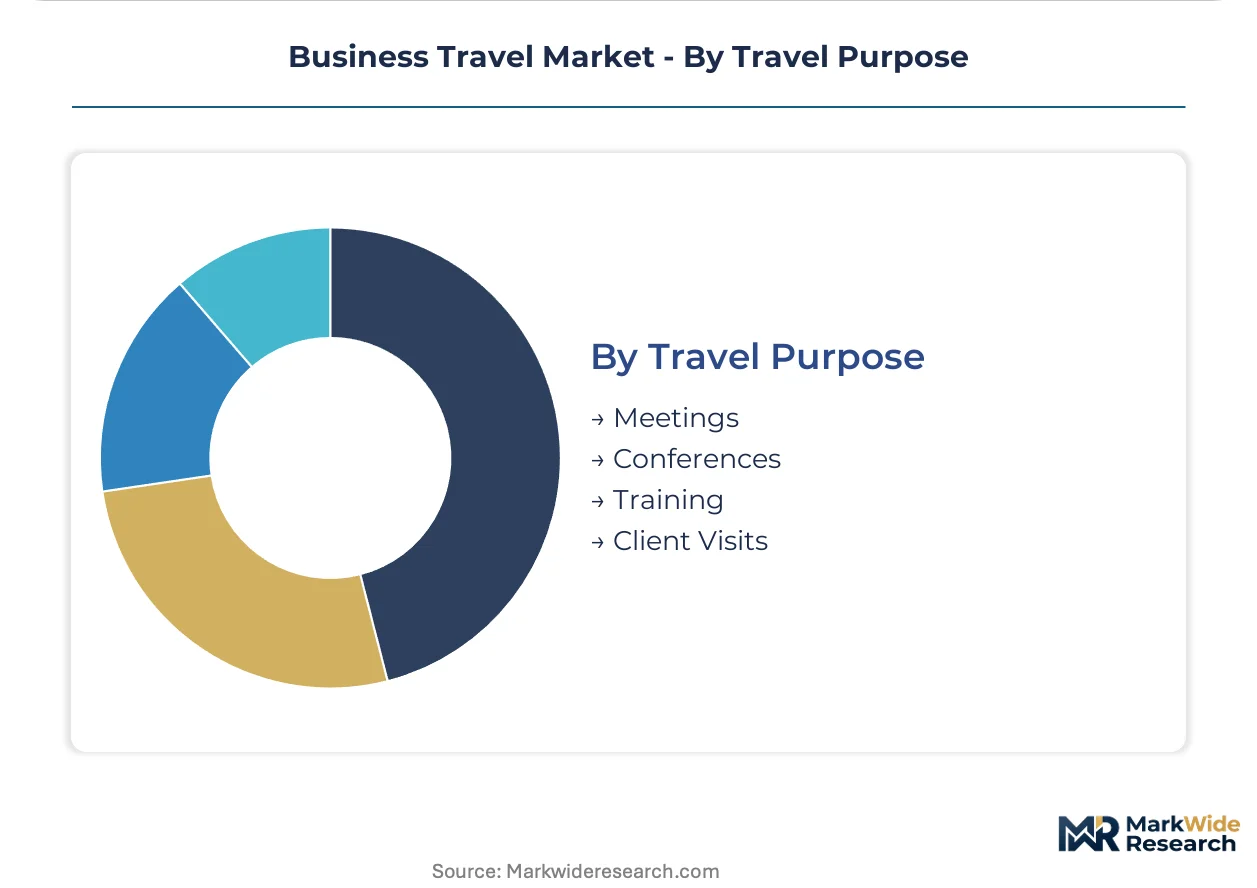
Travel Purpose:
Purpose classification shapes duty-of-care protocols, advance booking requirements, and carbon accounting treatment.
- Meetings:Internal team gatherings most vulnerable to video conferencing substitution. Persistent remote collaboration tools capture share of routine face-to-face interactions.
- Conferences:Industry events commanding premium pricing due to fixed-date constraints and group logistics complexity. Venue availability drives early commitment requirements.
- Training:Employee development travel subject to budget scrutiny and virtual alternative evaluation. Compliance-heavy sectors maintain in-person requirements.
- Client Visits:Revenue-generating travel with highest authorization priority and flexible booking policies. Relationship maintenance justifies premium cabin and accommodation tiers.
Client visits sustain rate resilience; conferences are climbing the fastest as deferred events return to physical formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology corridors generate the highest per-capita business travel expenditure among metropolitan zones worldwide, with corporate travel managers prioritizing integrated booking platforms that consolidate transportation, accommodation, and expense workflows.
United States
Technology sector verticals in Seattle, Austin, and Boston outpace other industries in platform automation adoption. FAA regulations govern aviation safety standards while EPA emissions tracking requirements influence corporate sustainability procurement criteria. Dallas-Fort Worth and Atlanta serve as dominant aviation hubs where carriers concentrate capacity investment in hub-and-spoke configurations.
Germany
Industrial manufacturing clusters in Bavaria and Baden-Württemberg sustain high-volume business mobility for supplier negotiations and quality audits. EU Green Deal disclosure mandates force platform architecture redesigns embedding carbon accounting into booking workflows. Frankfurt and Munich anchor continental Europe's financial and technology travel demand.
United Kingdom
Professional services firms in London's Square Mile and Canary Wharf generate concentrated demand for premium cabin international routes. GDPR constraints on passenger data handling create friction for platforms delivering multi-country itineraries. Manchester and Edinburgh emerge as secondary corporate travel origination points with growing technology sector presence.
India
Domestic software development in Bangalore and Hyderabad spawns regional platform serving Asia-Pacific corporate procurement. PLI scheme incentives for hospitality tech accelerate indigenous booking platform development. Mumbai and Delhi-NCR concentrate financial services and consulting firm travel expenditure.
France
Luxury goods headquarters in Paris drive high-frequency client visit protocols requiring flexible booking policies. EU AI Act risk classification frameworks reshape algorithmic pricing engine operations for automated fare prediction tools. Lyon and Toulouse host aerospace and satellite industry clusters with specialized international travel requirements.
Business Travel Market Key Industry Players
Capital-heavy producers compete with asset-light designers as legacy travel management companies maintain global agency networks while software-native platforms capture mid-market segments through subscription pricing. The vendor base stratifies across three tiers: integrated suite providers combining booking, expense, and sustainability tracking; traditional intermediaries sustaining service depth through regional office density; and consumer-adapted platforms with limited policy enforcement. Consolidation accelerates around embedded finance capabilities and carbon accounting automation as primary competitive differentiators.
Among established travel management companies, BCD Travel, CWT, and Navan occupy distinct archetype positions. BCD Travel exemplifies the global network model sustaining relevance through regional office density. CWT represents the traditional intermediary structure serving large enterprises with negotiated rate agreements. Navan anchors the software-first platform category differentiating through embedded expense automation that reduces reconciliation overhead for finance teams.
| Leading Market Players |
|---|
| American Express Global Business Travel |
| BCD Travel |
| CWT |
| Flight Centre Travel Group |
| Expedia Group |
| Corporate Travel Management |
| FCM Travel Solutions |
| TravelPerk |
| Navan |
| Others |
Cost & Logistics Intelligence
EU Green Deal emissions disclosure mandates gate qualified supplier access and premium-tier pricing eligibility for corporate travel platforms. Carbon accounting certification tiers separate vendors eligible for enterprise procurement contracts from those relegated to price-sensitive SME segments.
Pricing Analysis
Outcome-based pricing anchored to per-trip reconciliation savings dominates software-first platform monetization. Subscription tiers stratify across premium, standard, and economy levels based on ERP integration depth and sustainability dashboard sophistication. Cost compression in the mid-market tier is intensifying because SME self-service adoption erodes traditional agency commission structures. Freelancers and government agencies exhibit highest price sensitivity; technology sector corporates demonstrate lowest sensitivity due to finance automation budget prioritization.
Supply Chain Analysis
India's PLI scheme for hospitality tech and domestic software development incentives are reshaping regional platform sourcing strategies. Inventory feeds from United States aviation hubs, German rail networks, and Indian technology corridors anchor transportation and accommodation supply. API connectivity protocols, property management system integrations, and carbon verification standards constitute critical input dependencies. Single-source vulnerability concentrates around global distribution system intermediaries for legacy carrier content. Distribution runs through corporate travel management suites, direct supplier portals, and residual agency networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business travel procurement is becoming a vertical-integration race as platforms pursue captive control over expense automation and carbon accounting modules. Embedded finance capabilities represent the decisive downstream lever separating integrated suite providers from fragmented point solutions.
For Market Incumbents: To counter software-native platform erosion of mid-market share, BCD Travel and CWT must accelerate proprietary expense automation development and secure ISO 14064 certification for sustainability tracking. Backward integration into carbon verification services and upstream control over rail electrification corridor partnerships will defend enterprise contract renewals against Navan's embedded finance differentiation.
For New Entrants and Emerging Players: AI-powered fare prediction tools with explainable AI documentation compliant with EU AI Act risk classifications offer a technology-first wedge into German and French procurement committees. India's PLI scheme incentives present the most penetrable geography for regional platform development serving Asia-Pacific SME segments. A channel partnership strategy with domestic hospitality tech developers accelerates market entry without legacy ERP integration burden.
For Investors and Strategic Acquirers: Consolidation of expense automation and sustainability tracking capabilities into unified suites is the leading indicator that margin pools are shifting from transactional commissions to recurring software fees. Long-term viability favors asset-light platforms with API-first distribution architectures over capital-heavy agency networks dependent on regional office density. Acquisition target archetypes include mid-market expense automation specialists lacking carbon accounting modules. The signal to monitor is EU CSRD enforcement depth determining whether offset integration becomes table-stakes or premium-tier differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Integration | Reduces reconciliation overhead for finance teams adopting Navan-style automation. |
| Carbon Accounting Certification | ISO 14064 verification qualifies platforms for EU Green Deal procurement mandates. |
| API-First Distribution | Bypasses global distribution system fees for direct carrier and hotel connectivity. |
| Rail Electrification Partnerships | Secures lower-carbon alternatives for intra-European business mobility corridors. |
| Explainable AI Documentation | Maintains enterprise contract eligibility under EU AI Act risk classification frameworks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this business travel market analysis. Primary interviews with corporate travel managers, finance automation directors, sustainability procurement leads, and hospitality technology developers combined with secondary validation from EU CSRD implementation guidelines, FAA aviation safety standards, EPA emissions tracking protocols, and SEC filings from publicly traded travel management companies. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of demand estimates across transportation, accommodation, and events management service types.
Reconciliation of booking volume data, subscription pricing disclosures, and corporate procurement survey responses shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service delivery model, customer scale tier, booking channel infrastructure, and travel purpose classification. CAGRs derived from historical trajectory analysis and regulatory catalyst timing incorporate aviation fuel cost volatility, GDPR data handling constraints, and video conferencing substitution effects as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including black swan pandemic disruptions, sudden aviation regulatory overhauls, and protectionist trade measures restricting cross-border platform operations. Forecasts reflect assumptions about EU CSRD enforcement consistency, SME software adoption curves, and carrier capacity restoration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
Airline a-La-Carte Services Market
Business Travel Services
Latin America Business Travel Market
Business Travel Services
Brazil Business Travel Lodging Market
Business Travel Services
Europe Business Travel Market
Business Travel Services
Europes Golden Generation Travel Market
Business Travel Services
Bleisure Travel Market
Business Travel Services
Business Travel Lodging Market
Business Travel Services
United States Business Travel Market