
 Europes Golden Generation Travel Market | 2026-2036
Europes Golden Generation Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Europes Golden Generation Travel Market Foresight
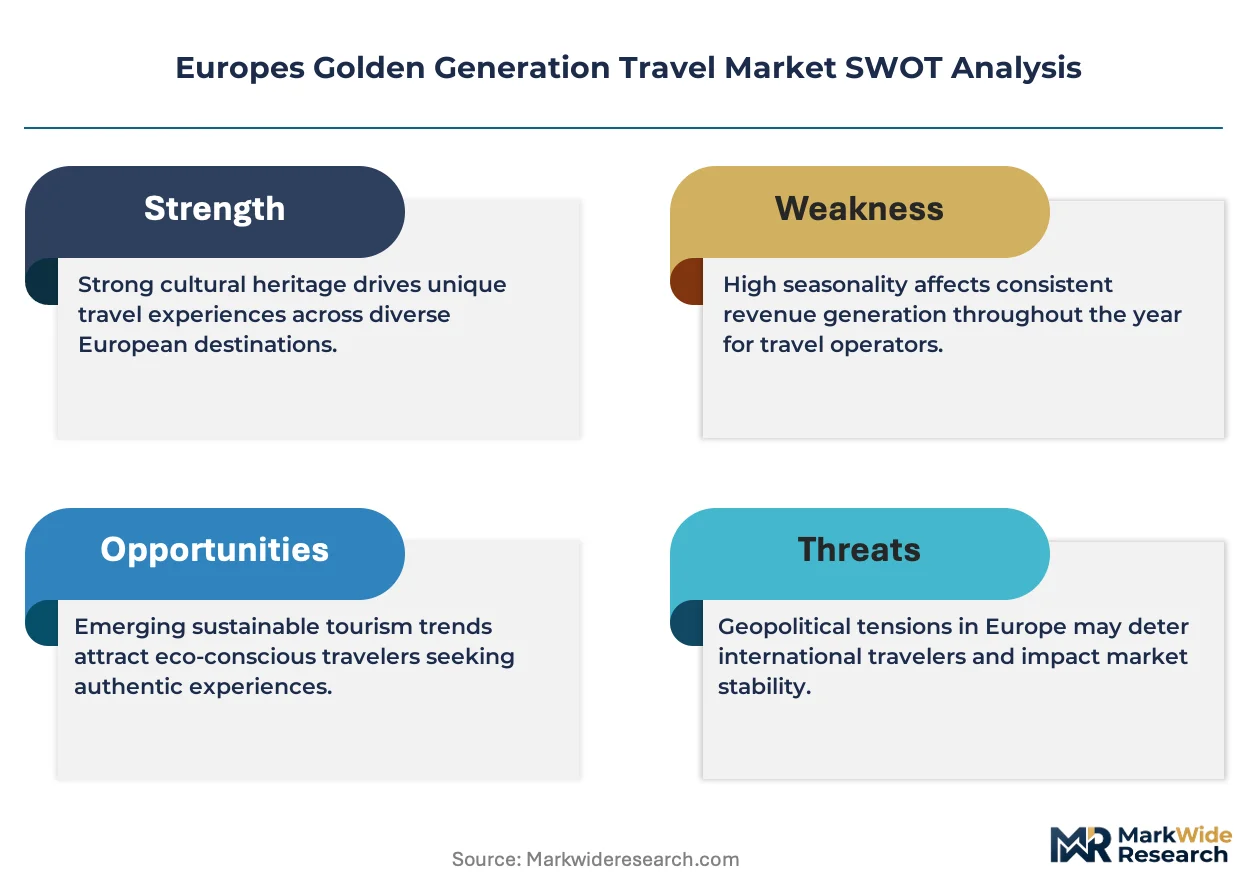
Modular itinerary bundling is repositioning how European seniors construct travel experiences, shifting from fixed-package dependency toward mix-and-match components combining transport, accommodation, and guided excursions. TUI Group leverages its vertically integrated resort network to sustain price competitiveness across Mediterranean destinations. Saga Holidays anchors its brand identity in age-curated medical support and slower-paced scheduling. Tauck differentiates through high-touch concierge services and exclusive cultural access arrangements.
Europes Golden Generation Travel encompasses structured leisure mobility services engineered for travelers aged 55 and above, incorporating accessibility-compliant transport, medical contingency protocols, and paced activity scheduling with maximum daily walking thresholds of approximately 5 kilometers. Package Type segmentation reveals guided tours commanding premium pricing due to embedded guide expertise and group risk management, while self-guided formats gain traction among digitally confident couples seeking flexible departure timing. Activity Preference data shows wellness retreats generating superior margin pools through extended average length of stay and ancillary spa revenue capture.
EU Package Travel Directive enforcement through national regulators in Germany, France, and Italy mandates financial protection and transparent pricing disclosures for all bundled offerings sold to European residents. EMA guidelines on travel-related medical device portability and GDPR compliance for health data transmission during cross-border trips constrain operator platform architecture. Stakeholders must monitor evolving accessibility certification standards under the European Accessibility Act and assess whether direct booking channel investments outpace intermediary dependency for customer relationship control.
Market Dynamics
AI-powered itinerary platforms are compressing booking friction for European seniors, enabling real-time customization of transport, accommodation, and guided components without traditional package dependencies.
Growth Catalysts
- European Accessibility Act compliance deadlines:Operators retrofitting fleets and properties ahead of mandatory certification create differentiated inventory for mobility-limited travelers.
- Wellness corridor clustering:Alpine thermal destinations in Austria and Switzerland report extended average stays through integrated medical spa protocols.
- Digital confidence among couples aged 60-70:Self-guided platform adoption accelerates as this demographic masters mobile booking interfaces.
Market Restraints
- GDPR health data transmission constraints:Cross-border medical device portability requires encrypted platform architecture that elevates development costs.
- Specialized guide talent scarcity:Certified geriatric care companions command premium wages in Germany and France, compressing operator margins.
- Coastal property concentration:Mediterranean circuit accommodation ownership clusters among Spanish and Italian family operators, limiting chain-scale procurement leverage.
Strategic Opportunities
- Portugal's underpenetrated Atlantic wellness circuit:Thermal springs in the Azores and mainland interior remain undeveloped relative to Spanish competitor destinations.
- EU Green Deal transport incentives:Rail operator subsidies for accessibility-compliant rolling stock enable carbon-positioned product differentiation.
- Voice-enabled booking interfaces:Convergence of natural language processing with legacy reservation systems reduces digital friction for visually impaired travelers.
Industry Challenges
- Medical contingency protocol standardization:Divergent national requirements for guide first-aid certification complicate cross-border tour staffing.
- Legacy property retrofit timelines:Historic Mediterranean accommodation stock requires extended renovation cycles to meet elevator and doorway width mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europes Golden Generation Travel Market |
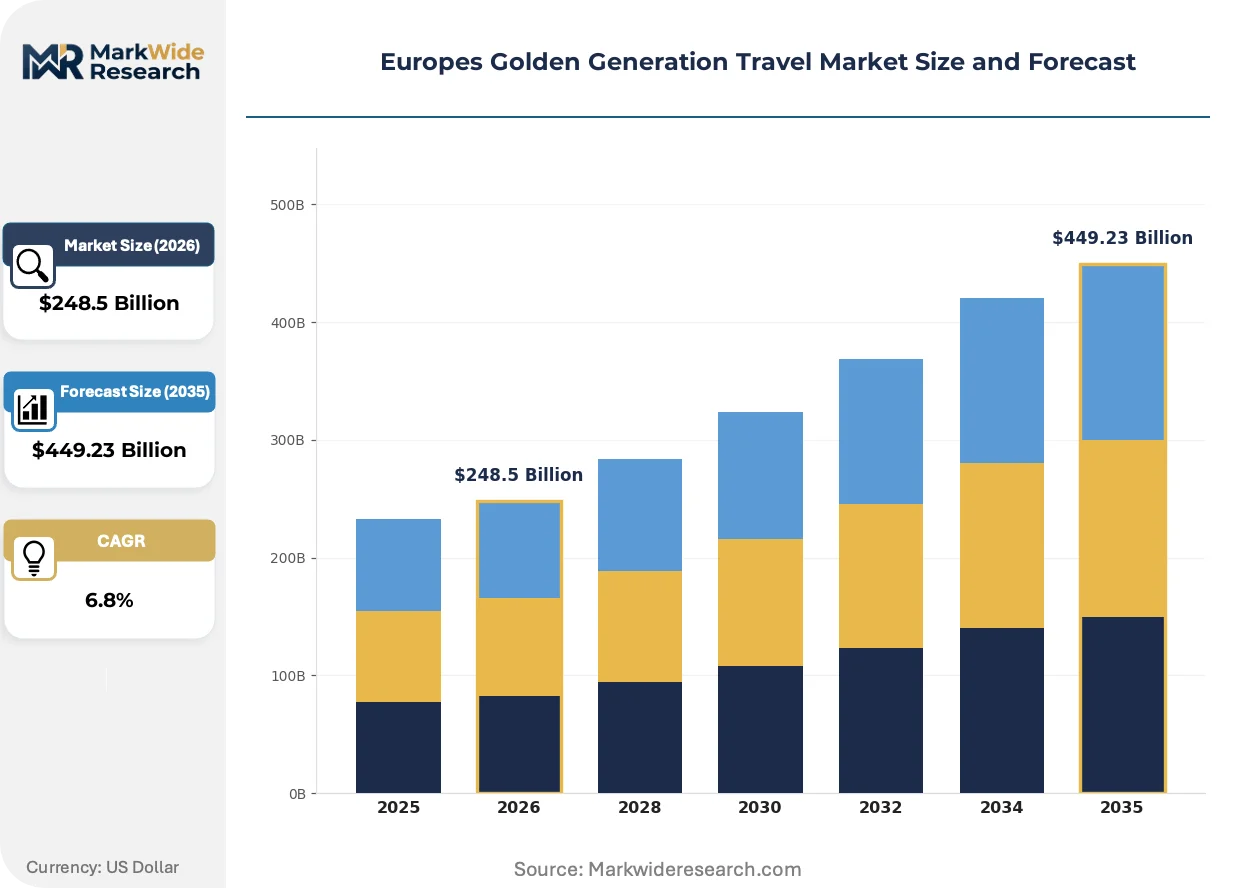
| Market Size in 2026 | $248.5 Billion |
| Market Size in 2035 | $449.23 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Solo Travelers, Couples, Family Groups, Luxury Travelers Package Type: All-Inclusive, Guided Tours, Self-Guided, Adventure Packages Activity Preference: Cultural Experiences, Nature Activities, Wellness Retreats, Urban Exploration Booking Channel: Online Travel Agencies, Direct Booking, Travel Advisors, Phone Reservations |
| Companies Covered | TUI Group, Saga Holidays, Trafalgar, DERTOUR Group, Insight Vacations, Cox & Kings, G Adventures, Tauck, Expat Explore Travel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europes Golden Generation Travel Market Shifts & Advancements
European senior travel is pivoting from fixed-duration packages toward fluid, componentized experiences where travelers assemble itineraries across multiple specialist providers rather than accepting bundled defaults.
Predictive health monitoring wearables are integrating into escorted tour operations, transmitting real-time biometric data to guide tablets and enabling proactive pacing adjustments before cardiac or mobility incidents occur. Tauck and Riviera Travel deploy these systems across Alpine walking programs. The technology is integrating medical risk management directly into daily scheduling decisions, compressing insurance premiums and guide liability exposure.
France's CNIL and Germany's BfDI intensify scrutiny of health data processing in travel platforms, mandating explicit consent chains for biometric information shared between operators, insurers, and medical facilities. This enforcement elevates compliance architecture costs. Small and mid-size tour providers in Italy and Spain face particular strain, accelerating consolidation toward operators with captive legal and IT security functions.
Direct booking channel investment by seniors is displacing traditional travel agency intermediation, particularly among digitally confident couples seeking departure flexibility. TUI Group and Saga Holidays redirect commission savings into loyalty program enhancements. Germany and the Netherlands exhibit the most pronounced channel shift, where mature online banking habits translate to travel platform comfort.
Europes Golden Generation Travel Market Segmentation
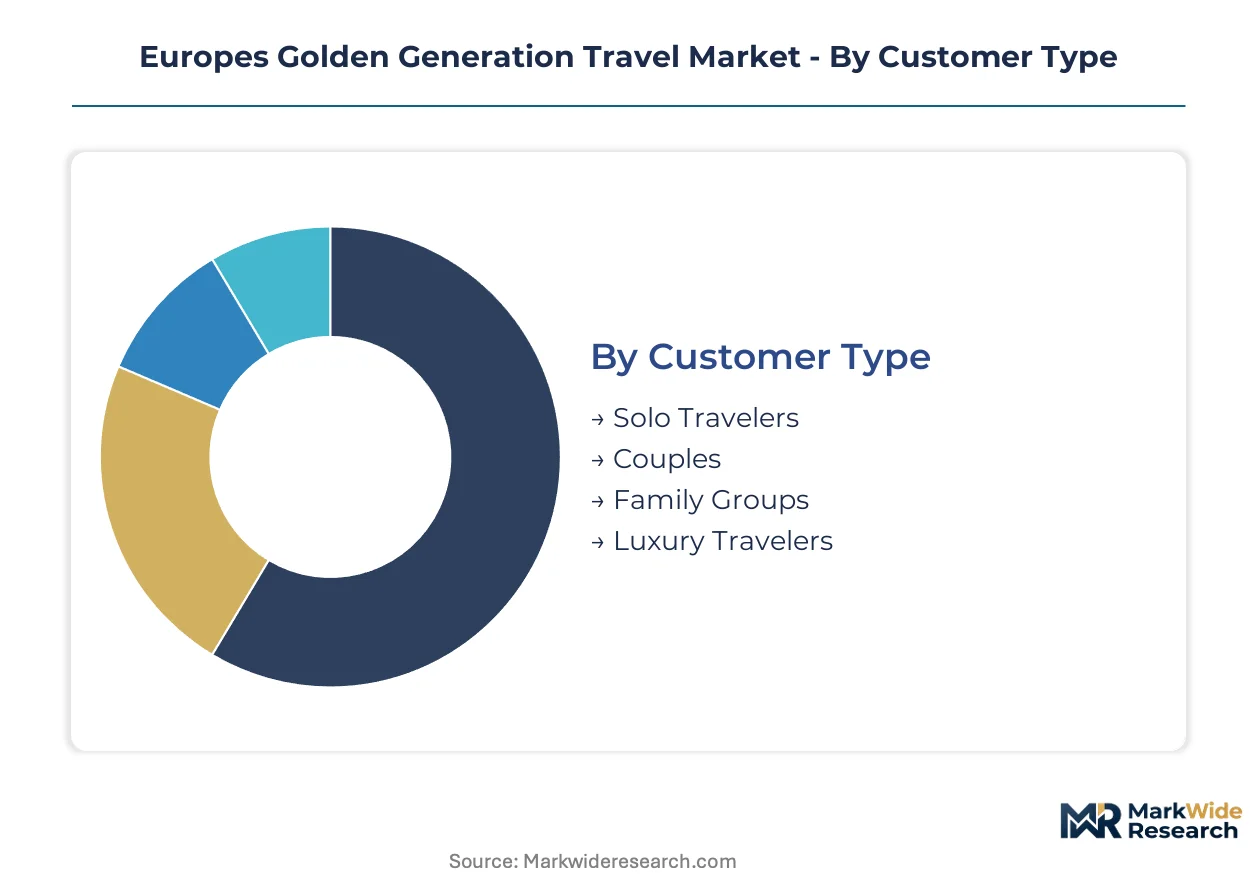
Segmentation in Europes Golden Generation Travel Market reveals divergent service requirements across mobility profiles, digital confidence levels, and health contingency needs. Operators configure staffing ratios, pacing protocols, and insurance coverage based on these distinctions.
Customer Type:
Travel party composition dictates accommodation specifications, guide-to-guest ratios, and cancellation flexibility terms.
- Solo Travelers:Single-occupancy room inventory with reduced supplements attracts this segment across German and Dutch source markets. Dedicated companion-matching services and 24-hour concierge access address isolation concerns and emergency response requirements.
- Couples:Double-occupancy configurations dominate Mediterranean cruise bookings and Alpine wellness circuits. This segment drives direct channel adoption as shared digital literacy enables collaborative itinerary customization without intermediary involvement.
- Family Groups:Multi-generational bookings spanning three age cohorts require activity tiering and separate dining arrangements. Spanish and Italian operators report extended planning cycles for these complex party structures.
- Luxury Travelers:Premium positioning demands private transport, exclusive venue access, and dedicated medical escort availability. French and Swiss operators capture superior margins through bespoke concierge layering.
Volume sits with Couples; growth tilts toward Solo Travelers.
Package Type:
Bundle architecture determines margin structure, supplier dependency, and regulatory protection scope under EU Package Travel Directive enforcement.
- All-Inclusive:Fixed-price provisioning of meals, excursions, and transfers appeals to budget-conscious retirees seeking cost certainty. Austrian thermal resort operators leverage this format to maximize occupancy during shoulder seasons.
- Guided Tours:Embedded guide expertise and group risk management justify premium positioning. Certified geriatric care companions in Germany and France command wage premiums that compress operator margins.
- Self-Guided:Componentized transport and accommodation selection attracts digitally confident travelers aged 60-70. Real-time mobile customization reduces traditional package dependencies.
- Adventure Packages:Moderate physical challenge itineraries with medical monitoring integration target active retirees. Alpine walking programs in Switzerland deploy predictive health wearables for proactive pacing adjustments.
Guided Tours anchor current revenue; Self-Guided formats are climbing the fastest as platform adoption accelerates.
Activity Preference:
Experience category selection correlates directly with average length of stay and ancillary revenue capture potential.
- Cultural Experiences:Museum access, heritage site visits, and performing arts attendance concentrate demand in Italian cities and French chateau regions. Slower-paced scheduling accommodates maximum daily walking thresholds of approximately 5 kilometers.
- Nature Activities:Coastal circuits and Alpine corridors attract mobility-capable seniors seeking physical engagement. Portugal's Atlantic wellness circuit remains underdeveloped relative to Spanish competitor destinations.
- Wellness Retreats:Extended-stay medical spa protocols generate superior margin pools through ancillary treatment revenue. Austrian and Swiss thermal destinations report lengthened average stays through integrated health programming.
- Urban Exploration:City-break formats with accessibility-compliant transport appeal to repeat visitors prioritizing cultural density. GDPR health data transmission constraints elevate platform development costs for cross-border medical device portability.
Wellness Retreats command the steepest expansion trajectory; Cultural Experiences retain the largest participant base.
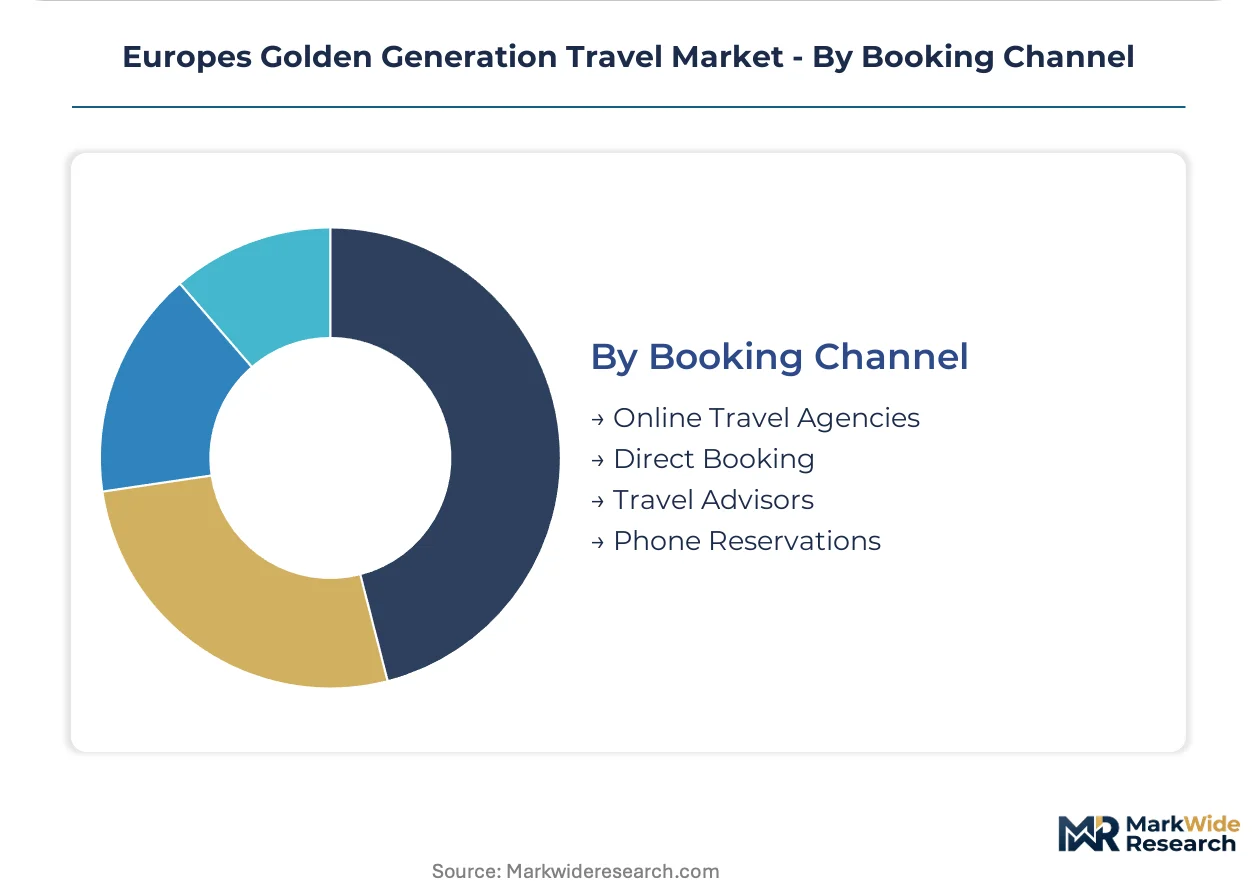
Booking Channel:
Channel selection reflects digital confidence gradients, price sensitivity, and relationship preference across national markets.
- Online Travel Agencies:Aggregator platforms provide price transparency and comparison functionality. Commission structures pressure operator margins while reducing customer relationship control.
- Direct Booking:Operator-owned channels capture commission savings for loyalty program reinvestment. Germany and the Netherlands exhibit the most pronounced shift toward this format.
- Travel Advisors:Human intermediaries retain relevance for complex medical contingency planning and insurance navigation. Spanish and Italian seniors demonstrate persistent preference for face-to-face consultation.
- Phone Reservations:Voice-enabled interfaces reduce digital friction for visually impaired travelers and those with limited mobile literacy. Legacy reservation system integration remains incomplete across mid-size operators.
Direct Booking is gaining share fastest; Travel Advisors defend position among risk-averse segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Côte d'Azur tax-advantaged zone concentrates luxury senior hospitality investment, drawing thermal resort operators and cruise port infrastructure development across Mediterranean coastal municipalities.
Germany
Robust pension fund liquidity and extended retirement durations drive demand for Alpine wellness circuits and Baltic Sea coastal packages. KBA accessibility mandates for coach fleet retrofitting accelerate operator compliance investments. Bavarian thermal towns like Bad Wörishofen anchor medical spa clustering with integrated geriatric care protocols.
France
CNIL health data enforcement shapes platform architecture for cross-border medical device portability in senior travel booking systems. ANSM guidelines on travel companion certification elevate guide training requirements. Provence-Alpes-Côte d'Azur concentrates luxury escorted tour operations with dedicated senior concierge layering.
Italy
Cultural heritage density in Tuscany and Umbria sustains slower-paced itinerary demand with sub-5-kilometer daily walking thresholds. EU Package Travel Directive enforcement through national regulators mandates financial protection disclosures. Mediterranean cruise ports in Civitavecchia and Venice anchor embarkation infrastructure for senior-dedicated vessel deployments.
Spain
Coastal property concentration among family operators limits chain-scale procurement leverage for Mediterranean circuit accommodation. GDPR compliance architecture costs strain mid-size Andalusian and Valencian tour providers. Canary Islands thermal infrastructure remains underdeveloped relative to mainland competitor destinations.
Switzerland
Alpine wellness corridor clustering generates extended average stays through integrated medical spa protocols. Swissmedic guidelines on travel health device certification constrain cross-border platform development. Thermal destinations in Graubünden and Valais deploy predictive health wearables for proactive pacing adjustments in walking programs.
Europes Golden Generation Travel Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across package architecture and channel strategy dimensions. TUI Group leverages vertically integrated resort networks to sustain price competitiveness, while Saga Holidays anchors brand identity in age-curated medical support. Three archetypes dominate: vertically integrated hospitality conglomerates, medical-specialist tour operators, and digitally native self-guided platforms. Competitive moves concentrate on direct booking channel investment and predictive health technology integration.
Within the vertically integrated tier, TUI Group exemplifies scale-driven resort network control, while Saga Holidays occupies the medical-specialist position with embedded care protocols. Tauck represents the high-touch concierge archetype through exclusive cultural access arrangements. These three companies illustrate how operator positioning diverges across bundled dependency, health contingency depth, and experiential exclusivity vectors.
| Leading Market Players |
|---|
| TUI Group |
| Saga Holidays |
| Trafalgar |
| DERTOUR Group |
| Insight Vacations |
| Cox & Kings |
| G Adventures |
| Tauck |
| Expat Explore Travel |
| Others |
Supply & Pricing Matrix
Certified geriatric care companion concentration across Germany and France compresses operator margins while widening spreads between premium guided tours and economy self-guided formats. Labor-cost differentials between these specialized medical-escort markets and lower-wage Mediterranean guide pools create tiered pricing architecture that rewards proximity to Alpine wellness corridors.
Pricing Analysis
Short lead-time bookings command premium positioning as mobility-limited travelers require guaranteed accessibility-compliant inventory with minimal cancellation flexibility. Three-tier pricing structure across premium concierge, standard guided, and economy self-guided levels stratifies by embedded medical support depth and guide-to-guest ratios. Cost compression in the standard tier intensifies because certified geriatric companion wages in Germany and France outpace revenue per available room growth. Solo travelers exhibit highest price sensitivity due to single-occupancy supplement avoidance, while luxury travelers demonstrate minimal elasticity for dedicated medical escort availability.
Supply Chain Analysis
Direct-to-consumer platforms handle digitally confident couple demand while traditional travel advisors manage complex medical contingency bookings for risk-averse segments. Accommodation supply concentrates in Spain, Italy, and Austria where family-owned coastal properties and Alpine thermal resorts dominate inventory. Fleet procurement draws from German coach manufacturers for accessibility-compliant rolling stock, while wellness programming sources from Swiss and Austrian medical spa protocol licensors. Single-source vulnerability runs through specialized guide talent pools in France and Germany where certified geriatric companion certification creates bottleneck conditions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over accessibility-compliant accommodation inventory determines pricing power and customer relationship ownership.
For Market Incumbents: Cement captive supply of thermal resort inventory through long-term lease structures in Austrian and Swiss Alpine corridors before EU Green Deal rail subsidies attract competitor fleet deployments. Defend guide talent pipelines by underwriting geriatric care companion certification programs with Bavarian and Baden-Württemberg vocational institutes. Channel control through direct booking platform investment outpaces intermediary commission savings as German and Dutch digital confidence accelerates. For New Entrants and Emerging Players: Begin with Portugal's Atlantic wellness circuit where thermal spring infrastructure remains undeveloped relative to Spanish competitor destinations. Target digitally confident solo travelers aged 60-70 through voice-enabled booking interfaces that reduce friction for visually impaired market subsets. Componentized itinerary assembly platforms offer lowest competitive density against incumbent bundled-package dominance. For Investors and Strategic Acquirers: The window for entry favors medical-specialist tour operators with embedded predictive health wearable integration and captive legal functions for GDPR compliance architecture. Long-term viability hinges on direct channel ownership and proprietary wellness programming rather than intermediary-dependent volume. Watch for consolidation acceleration among Italian and Spanish mid-size providers facing CNIL and BfDI enforcement cost strain as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Health Wearable Integration | Tauck and Riviera Travel deployment across Alpine programs compresses insurance premiums through real-time biometric monitoring. |
| Direct Booking Channel Investment | TUI Group and Saga Holidays redirect commission savings into loyalty program enhancements for German and Dutch markets. |
| Accessibility-Compliant Fleet Retrofit | KBA mandates in Germany accelerate operator compliance investments ahead of European Accessibility Act deadlines. |
| Medical-Specialist Guide Certification | ANSM guidelines in France elevate training requirements that constrain supply and justify premium positioning. |
| Voice-Enabled Booking Interface Development | Natural language processing convergence with legacy reservation systems targets visually impaired traveler segments. |
Research Methodology
Independent corroboration across tour operator executives, accessibility compliance officers, and thermal resort management underwrites the qualitative findings in this analysis. Primary interviews with geriatric care companion certification bodies in Germany and France, combined with secondary validation from EU Package Travel Directive enforcement filings and Alpine wellness corridor occupancy databases, established demand-side parameters. Bottom-up triangulation across customer type segmentation and top-down reconciliation against Mediterranean cruise deployment schedules anchored volume estimates.
Comparable historical reference periods spanning pre-pandemic baseline through post-recovery normalization informed the projection horizon calibration. The analytical framework models package type evolution, activity preference clustering, and booking channel migration across the forecast period. Segmentation dimensions include travel party composition, digital confidence gradients, and health contingency need intensity. CAGRs derive from elasticity-adjusted demand curves incorporating EU Green Deal transport incentive phase-ins and European Accessibility Act compliance deadline effects.
Underlying measurement precision varies by segment; wellness retreat and guided tour categories carry tighter precision than emerging self-guided platform adoption curves. Forecasts reflect assumptions about digital literacy diffusion rates among couples aged 60-70 and regulatory enforcement intensity from France's CNIL and Germany's BfDI. Periodic stress-testing of base assumptions against medical contingency protocol standardization progress and legacy property retrofit timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Business Travel Services
United States Business Travel Market
Business Travel Services
Airline a-La-Carte Services Market
Business Travel Services
Europe Business Travel Market
Business Travel Services
Business Travel Market
Business Travel Services
Bleisure Travel Market
Business Travel Services
Business Travel Lodging Market
Business Travel Services
Latin America Business Travel Market
Business Travel Services
Brazil Business Travel Lodging Market