
 Baby Changing Station Market | 2026-2036
Baby Changing Station Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Changing Station Market Intelligence
ASTM F2388 qualification for baby changing stations is bifurcating the competitive landscape between certified commercial-grade suppliers and uncertified entrants. Koala Kare leverages its vertical integration into antimicrobial surface manufacturing to sustain dominance in airport and healthcare channels. Foundations anchors its position through exclusive distribution agreements with major restroom fixture distributors across North American facilities. Delta Children competes on brand recognition by extending its consumer nursery expertise into commercial specification markets.
Baby changing stations are wall-mounted or free-standing fixtures engineered to support infant weight loads of 50 pounds or more, incorporating antimicrobial surfaces, gas-assisted hinge mechanisms, and ADA-compliant deployment heights for universal accessibility in public restrooms. Wall-mounted units occupy the largest installed base due to space efficiency in high-traffic commercial buildings, while portable and foldable configurations represent the fastest-growing category as event venues and temporary facilities prioritize flexible hygiene infrastructure. Stainless steel and high-density polyethylene materials command premium positioning in healthcare and food service environments where sanitation protocols exceed standard commercial requirements.
FDA guidelines on surface antimicrobial claims intersect with EPA registration requirements for public health pesticides, creating dual compliance obligations for manufacturers incorporating silver-ion or copper-alloy treatments. The ADA Standards for Accessible Design mandate specific reach ranges and operable force limits that shape product engineering decisions for any station sold into federally funded facilities. Stakeholders must monitor evolving municipal green building codes, as LEED v4.1 credits for low-emitting materials are beginning to appear in restroom renovation specifications across state-level procurement frameworks.
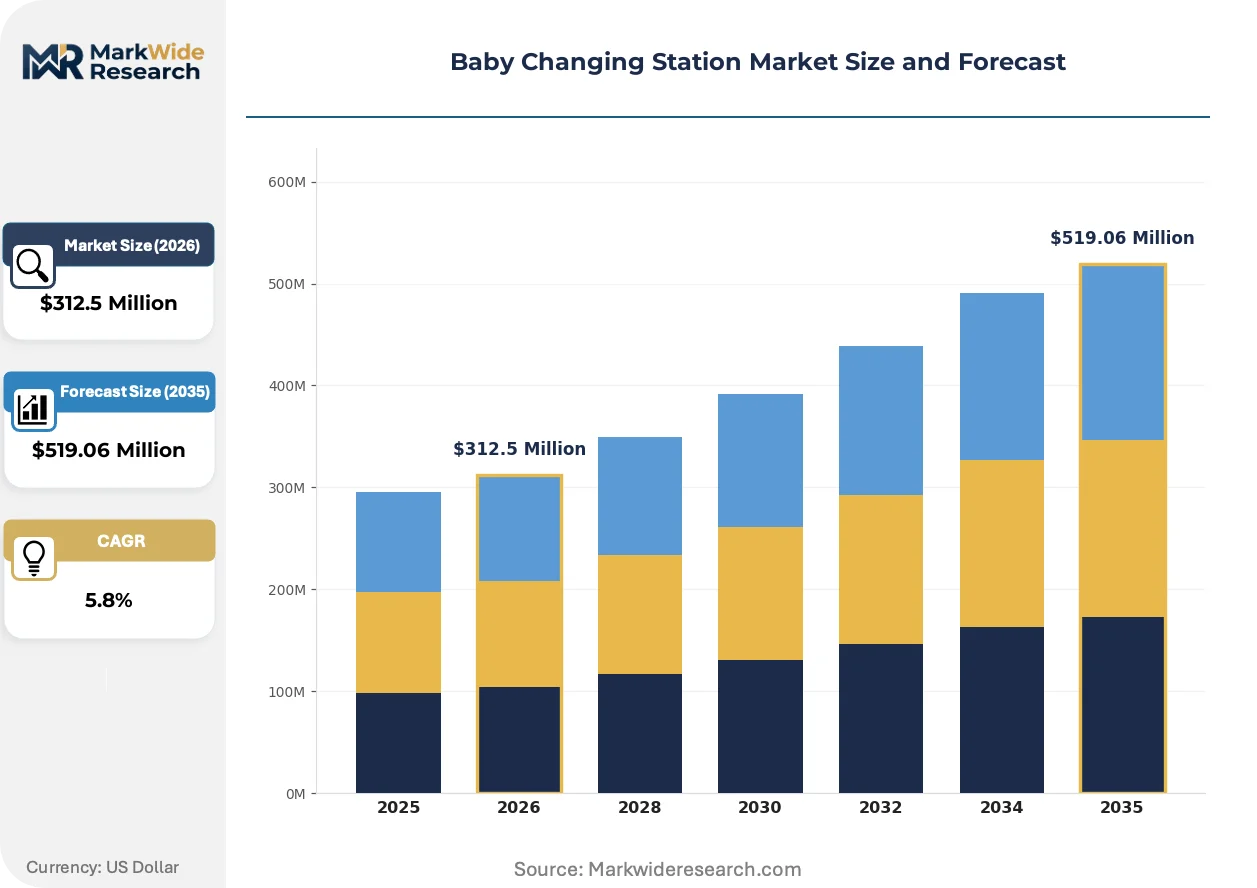
Market Dynamics
ASTM F2388 certification requirements are compressing supplier margins while bifurcating procurement pools into certified and uncertified vendor tiers across municipal, airport, and healthcare facilities.
Growth Catalysts
- ADA Standards for Accessible Design:Federal reach-range mandates for federally funded buildings are forcing restroom renovation cycles in airports, hospitals, and municipal facilities across the United States.
- Antimicrobial surface engineering:Silver-ion and copper-alloy treatments are penetrating healthcare and food service specifications where sanitation protocols exceed standard commercial thresholds.
- Family traveler accommodation:Hospitality venues are retrofitting restrooms to capture parent demographic spending, particularly in airport terminals and hotel chains.
Market Restraints
- High-density polyethylene resin volatility:Petrochemical feedstock price swings compress margin stability for manufacturers dependent on polymer injection molding.
- Dual EPA-FDA compliance burden:Surface antimicrobial claims require pesticide registration while medical device adjacent positioning triggers FDA oversight, lengthening time-to-market.
- Wall-mount space constraints:Legacy restroom footprints in aging commercial buildings limit installation feasibility without structural modification.
Strategic Opportunities
- Portable and foldable configurations:Event venues and temporary facilities are creating demand for flexible hygiene infrastructure outside permanent installation channels.
- LEED v4.1 low-emitting materials credits:Green building code adoption across state procurement frameworks is opening specification pathways for compliant manufacturers.
- Gas-assisted hinge mechanism convergence with IoT sensors:Smart restroom integration enables usage monitoring and predictive maintenance contracts in facility management.
Industry Challenges
- ASTM F2388 certification timeline compression:Third-party testing bottlenecks delay product launches as accredited labs face queue congestion.
- Antimicrobial claim substantiation:EPA registration requirements for public health pesticides demand extensive efficacy documentation, straining R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Changing Station Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Free-Standing, Portable, Foldable Material: Plastic, Stainless Steel, Wood, Aluminum, Composite End User: Shopping Mall Facilities, Airports, Educational Institutions, Hospitality Venues Installation Type: Permanent Fixing, Temporary Setup, Modular Units, Integrated Design |
| Companies Covered | Delta Children, Foundations, Koala Kare, Leander, ASI, Clafbebe, Babyletto, Cam Cam Copenhagen, Vectair Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Changing Station Market Strategic Shifts & Innovations
Material science advances and regulatory precision are redefining competitive differentiation, with certification grade and surface technology becoming primary selection criteria over legacy price-based procurement.
Copper-alloy surface treatments are supplanting standard polymer finishes in healthcare and food service environments where kill-rate documentation determines vendor selection. Hospital procurement committees and airport authorities are accelerating specification shifts toward these materials. The transition is compressing market share for conventional high-density polyethylene suppliers lacking metallurgical processing capabilities.
LEED v4.1 credits for low-emitting materials are appearing in restroom renovation specifications across state-level procurement frameworks in the United States. Facility managers must document volatile organic compound emissions to capture building certification points. This regulatory tailwind favors manufacturers with in-house testing infrastructure and Environmental Product Declarations already on file.
Specification-driven purchasing is consolidating buyer decision authority within facilities engineering departments rather than general procurement offices. Certified product databases and pre-approved vendor lists are displacing open bidding for baby changing station contracts. Airport authorities and hospital networks exhibit the most pronounced centralization, with multi-site standardization reducing vendor fragmentation.
Baby Changing Station Market Segmentation
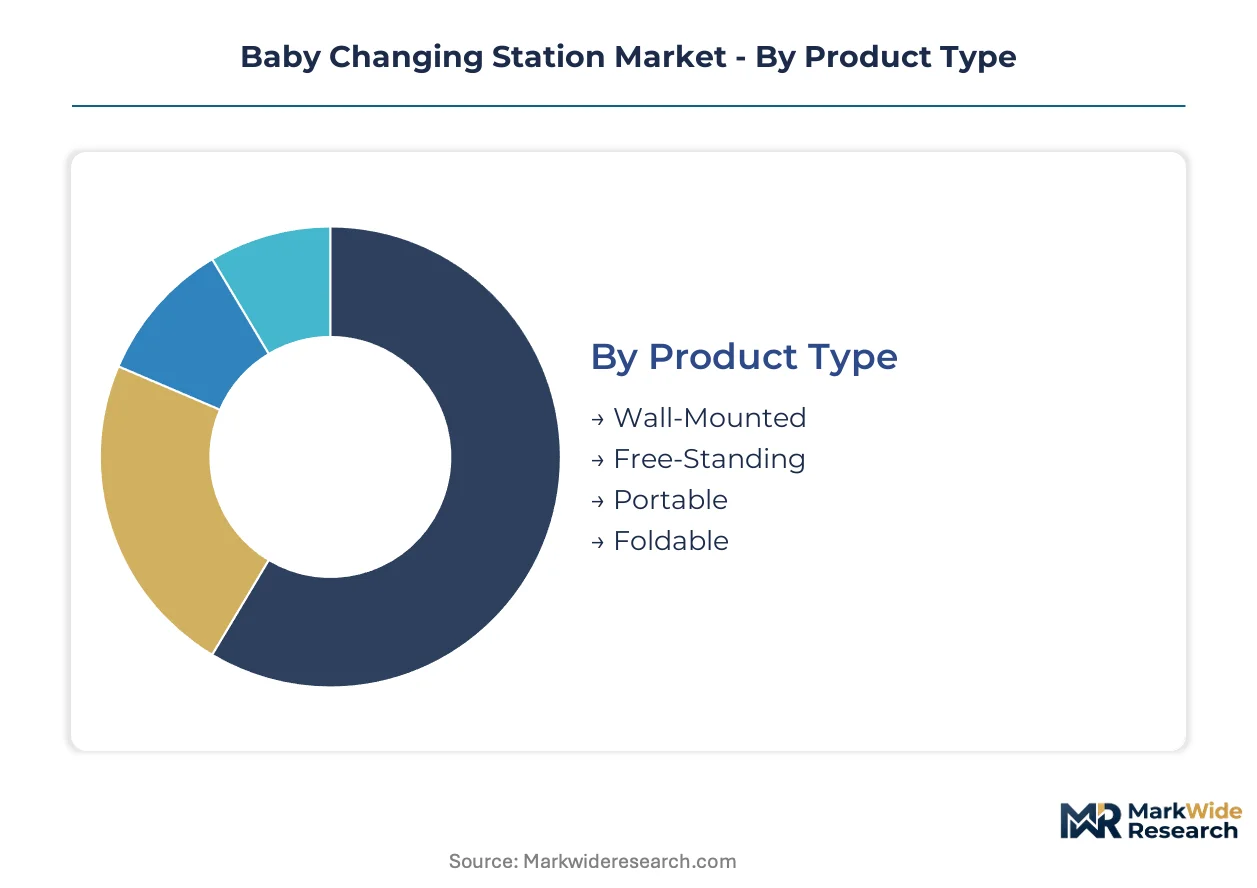
ASTM F2388 certification tiers and antimicrobial surface specifications are fragmenting procurement pools across product categories, creating distinct margin architectures that favor certified suppliers in healthcare and airport channels. Material selection and installation flexibility now determine specification access more than unit economics alone.
Product Type:
Margin pools concentrate in configurations that balance space efficiency with ADA compliance engineering, particularly where gas-assisted hinge mechanisms add technical differentiation.
- Wall-Mounted:Horizontal platforms fold against restroom walls, incorporating 50-pound load ratings and antimicrobial polyethylene surfaces. Airport authority procurement cycles in the United States favor these units for terminal retrofit programs where space constraints dominate specification decisions.
- Free-Standing:Vertical pedestal designs support dual-height deployment for ADA reach-range compliance without structural wall modification. Hospitality venues in high-traffic hotel lobbies are rotating toward these units to capture family traveler spending without restroom reconstruction.
- Portable:Lightweight frames with collapsible legs enable deployment at outdoor events and temporary facilities. Event management contractors specify these for festival and convention hygiene infrastructure.
- Foldable:Compact storage profiles suit mobile caregiver kits and emergency response vehicles. Municipal family services departments procure these for field deployment.
Wall-mounted units hold installed capacity. Foldable configurations are rotating up the share rankings.
Material:
Cost tier stratification separates healthcare-grade metallurgical processing from commodity polymer injection molding, with EPA-registered antimicrobial treatments commanding specification premiums.
- Plastic:High-density polyethylene dominates volume production through injection molding of seamless, non-porous surfaces. Food service environments specify these for corrosion resistance and chemical cleaning protocol compatibility.
- Stainless Steel:AISI 304 and 316 grades deliver kill-rate documentation for hospital infection control committees. Healthcare procurement in the United States requires these alloys for operating suite and neonatal unit adjacency.
- Wood:Sealed hardwood finishes serve boutique hospitality and heritage building renovations where aesthetic integration overrides sanitation protocols. Historic hotel properties in New England specify these for landmark compliance.
- Aluminum:Anodized extrusions reduce weight for portable and foldable configurations without sacrificing structural load ratings. Outdoor event equipment suppliers favor these for corrosion resistance.
- Composite:Engineered mineral-polymer blends combine thermal stability with low-emission profiles for LEED v4.1 credit capture. State-level green building procurement in California specifies these for public facility renovations.
Plastic retains volume leadership. Stainless steel is climbing the fastest in specification priority.
End User:
Customer type determines compliance burden intensity, with federally funded facilities triggering ADA Standards for Accessible Design mandates that compress supplier qualification pools.
- Shopping Mall Facilities:Retail property managers prioritize rapid-install wall-mounted units during tenant improvement cycles to maintain foot traffic flow. Mall operators in Texas and Florida specify these for family restroom retrofit programs.
- Airports:Terminal authorities enforce ASTM F2388 certification and multi-site standardization across hub networks. The FAA-funded Airport Improvement Program drives renovation cycles at Hartsfield-Jackson Atlanta and Dallas-Fort Worth International.
- Educational Institutions:K-12 districts and university facilities departments balance child safety liability with maintenance budget constraints. California State University system procurement standardizes across 23 campuses.
- Hospitality Venues:Hotel chains retrofit guest room floors and lobby restrooms to capture parent demographic spending. Marriott and Hilton specification committees drive brand-standard deployment.
Airports hold installed capacity. Hospitality venues are gaining share fastest.
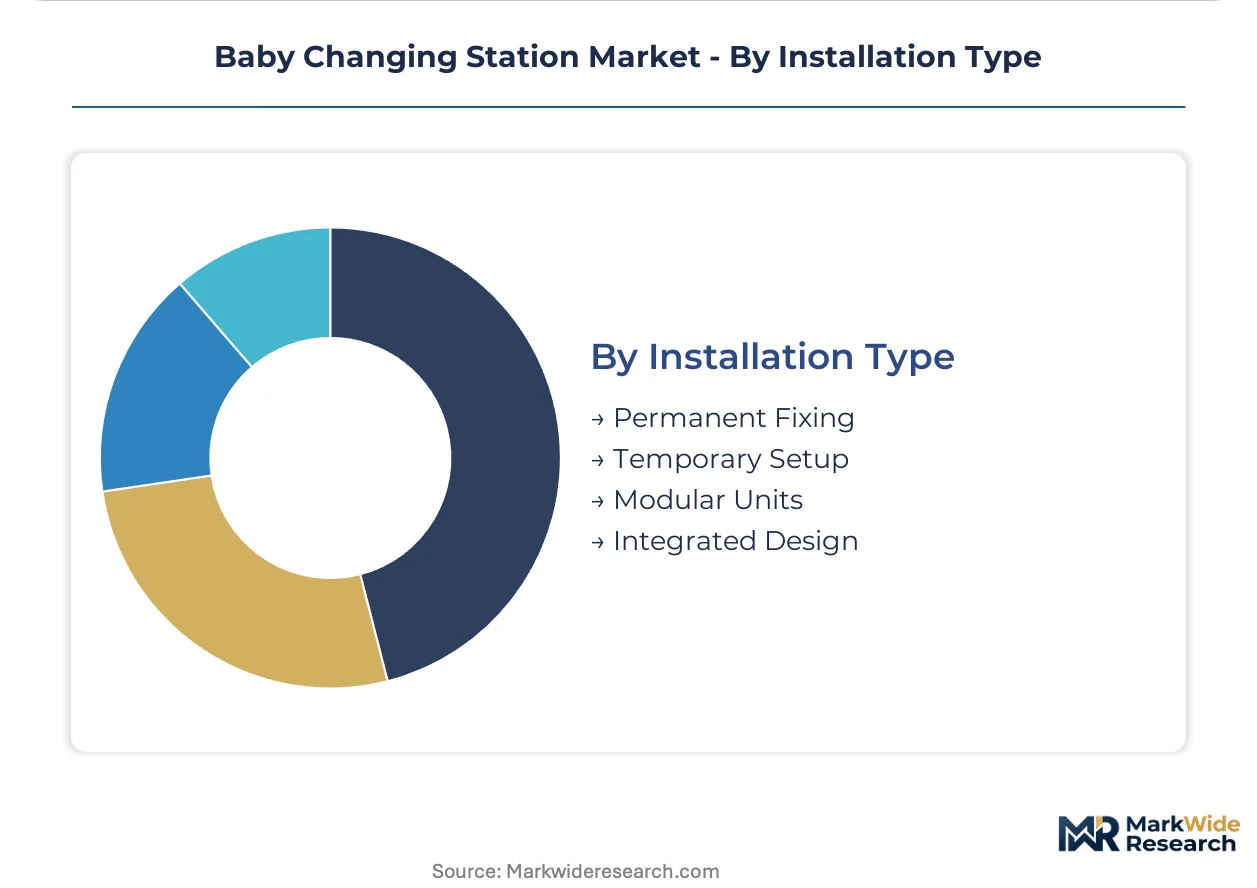
Installation Type:
Application flexibility separates permanent infrastructure from adaptive deployment, with modular systems capturing facility management contracts that prioritize reconfiguration speed.
- Permanent Fixing:Wall anchors and floor bolts secure units for 15-year service life expectations in high-traffic commercial buildings. Municipal building codes in Chicago and New York require these for public restroom compliance.
- Temporary Setup:Suction mounts and weighted bases enable deployment without structural modification. Convention centers in Las Vegas and Orlando specify these for trade show hygiene infrastructure.
- Modular Units:Pre-fabricated restroom pods integrate changing stations with plumbing and electrical rough-ins. Healthcare construction contractors favor these for hospital expansion projects.
- Integrated Design:Custom millwork conceals changing platforms within vanity and storage systems. Luxury hotel properties specify these for suite bathroom renovations.
Permanent fixing holds installed capacity. Modular units are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal procurement mandates and municipal building code updates are steering specification decisions toward certified suppliers across major commercial construction markets. Airport authorities and healthcare systems in select countries are consolidating vendor pools through multi-site standardization programs.
United States
The FAA-funded Airport Improvement Program drives terminal renovation cycles at Hartsfield-Jackson Atlanta and Dallas-Fort Worth International, where ASTM F2388 certification gates supplier qualification. ADA Standards for Accessible Design enforce reach-range compliance in federally funded facilities, compressing eligible vendor pools. California State University system procurement standardizes across 23 campuses, consolidating specification authority within facilities engineering departments.
Germany
Healthcare construction contractors prioritize infection-control-grade materials for hospital neonatal units and maternity wards, where kill-rate documentation determines vendor selection. REACH regulation compliance shapes surface treatment chemistry for antimicrobial coatings entering European commercial markets. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate manufacturing capacity for restroom fixture systems serving Central European facility management contracts.
United Kingdom
Heathrow Airport Authority and NHS Trust procurement frameworks enforce multi-site standardization across terminal networks and hospital estates, reducing vendor fragmentation. Building Regulations Part M accessibility mandates shape product engineering for public restroom installations. London and Southeast England concentrate specification-driven purchasing within facilities engineering departments of major retail and hospitality property portfolios.
Japan
Tokyo Metro and major railway station operators retrofit family restrooms to accommodate inbound tourism growth and domestic parent demographics. METI guidelines on public facility accessibility intersect with JIS standards for child care equipment, creating dual compliance obligations for market entrants. Kanto region manufacturing clusters supply antimicrobial surface technologies to healthcare and food service specification channels across East Asia.
Australia
Airport terminal renovations at Sydney Kingsford Smith and Melbourne Tullamarine incorporate ADA-equivalent accessibility standards through building code harmonization. Healthcare procurement committees in New South Wales and Victoria require kill-rate documentation for infection control adjacency in maternity and pediatric units. Sydney and Melbourne metropolitan construction markets concentrate demand for modular restroom pod systems in hospital expansion projects.
Baby Changing Station Market Key Industry Players
Listed leaders compete with private specialists across certification tiers and distribution channel control. The vendor base stratifies between ASTM F2388-certified commercial-grade suppliers and uncertified regional fabricators serving price-sensitive renovation segments. Three archetypes dominate: vertically integrated surface technology specialists, exclusive distribution network holders, and brand-recognition-driven consumer crossover entrants. Capacity expansion and strategic certification investments constitute the dominant competitive moves, as third-party testing bottlenecks compress product launch timelines.
Within the certification-led tier, Koala Kare and Foundations exemplify divergent strategic positioning around channel control and distribution architecture. Delta Children occupies a position bridging consumer nursery expertise with commercial specification markets. ASI and Vectair Systems represent European and Asia-Pacific-based fabricators respectively, anchoring regional supply relationships with facility management contractors and restroom fixture distributors. These five entities collectively illustrate the competitive tension between antimicrobial surface engineering capabilities and procurement consolidation authority across airport, healthcare, and hospitality verticals.
| Leading Market Players |
|---|
| Delta Children |
| Foundations |
| Koala Kare |
| Leander |
| ASI |
| Clafbebe |
| Babyletto |
| Cam Cam Copenhagen |
| Vectair Systems |
| Others |
Cost & Logistics Intelligence
ASTM F2388 certification gates supplier qualification and price differentiation simultaneously, compressing uncertified fabricators into commodity tiers while elevating antimicrobial-capable manufacturers into premium specification channels. Certified commercial-grade units command substantial markups over uncertified alternatives as airport authorities and hospital procurement committees enforce pre-approved vendor lists.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with ASTM F2388-qualified units positioned at premium levels against uncertified regional fabricators. Three-tier pricing structure across certified antimicrobial, certified standard, and uncertified economy levels reflects surface technology and compliance documentation intensity. Cost compression in the uncertified tier is intensifying because municipal procurement offices face budget constraints on renovation cycles. Shopping mall facilities exhibit the highest price sensitivity due to tenant improvement cycle pressures, while hospital infection control committees prioritize kill-rate documentation over unit economics.
Supply Chain Analysis
Inventory cycles for antimicrobial surface treatments extend lead times beyond standard polymer injection molding, creating procurement bottlenecks during airport terminal renovation surges. Manufacturing concentration rests on the United States, China, and Germany, with North American producers dominating airport authority contracts and Chinese fabricators supplying cost-optimized polymer components. High-density polyethylene resin, copper-alloy sheet stock, and gas-assisted hinge mechanisms constitute critical input dependencies. Single-source vulnerability characterizes EPA-registered antimicrobial coating suppliers, where registration timelines create captive relationships. Distribution runs through restroom fixture distributors and facilities management contractors rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart restroom integration with IoT-enabled usage monitoring disrupts traditional specification criteria, creating competitive openings for sensor-embedded platform developers against incumbent mechanical hinge suppliers.
For Market Incumbents: Consolidate certification infrastructure and antimicrobial surface capabilities to defend against sensor-technology entrants. Expand captive production of silver-ion and copper-alloy treatments to offset EPA registration bottlenecks. Lock exclusive distribution agreements with major restroom fixture distributors before specification authority centralizes further within facilities engineering departments. For New Entrants and Emerging Players: Differentiate on portable and foldable configurations with embedded usage analytics to capture event venue and temporary facility demand outside permanent installation channels. Target municipal family services departments and emergency response vehicle fleets with lightweight aluminum-framed units. Pursue direct contracting with convention center operators in Las Vegas and Orlando bypassing traditional distributor networks. For Investors and Strategic Acquirers: LEED v4.1 credit eligibility reshapes the acquisition landscape toward manufacturers with Environmental Product Declarations and in-house volatile organic compound testing infrastructure. Long-term viability favors vertically integrated surface technology specialists with metallurgical processing capabilities over polymer-dependent assemblers. Monitor state-level green building code adoption rates as the signal for specification shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Surface Technology Investment | EPA-registered copper-alloy treatments unlock hospital and food service specification channels. |
| Smart Sensor Integration | IoT-enabled usage monitoring enables predictive maintenance contracts with airport facility managers. |
| LEED v4.1 Compliance Certification | Low-emitting materials documentation captures California and New York public procurement frameworks. |
| Exclusive Distribution Partnership | Locked agreements with major restroom fixture distributors block competitor access to specification channels. |
| Portable Configuration Development | Lightweight foldable designs penetrate event venue and emergency response vehicle white-space segments. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, procurement databases, and trade association disclosures across the baby changing station supply base. Primary interviews engaged facilities engineering directors, airport authority procurement managers, hospital infection control committee members, and restroom fixture distributor executives. Secondary validation drew from ASTM International certification records, EPA pesticide registration databases, GSA procurement schedules, and municipal building code updates. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across commercial verticals.
Segmentation dimensions modeled include product configuration, material grade, end-user vertical, and installation type across the projection horizon. CAGRs derive from regression analysis of historical specification penetration rates against regulatory mandate implementation timelines. Forecast inputs incorporate airport renovation cycle data from FAA Airport Improvement Program disbursements and healthcare construction permit flows from selected metropolitan statistical areas.
Material uncertainties — petrochemical feedstock volatility, EPA registration queue congestion, and municipal budget cycle delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and procurement centralization trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Japan Baby Care Product Market
Baby Products
Smart Pacifier Market
Baby Products
China Maternity Goods Market
Baby Products
Global Baby Play Mats Market
Baby Products
Baby Bottle Holder Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Italy Baby Care Products Market
Baby Products
Baby Walker Market
Baby Products
Baby High Chair Market
Baby Products
Breast Milk Storage Products Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Potty Training Seat Market
Baby Products
Maternity Products Market
Baby Products
Automatic Baby Swing Market
Baby Products
Feeding Bra Market