
 Baby Bedding Market | 2026-2036
Baby Bedding Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Bedding Market Analytics
Asset-light direct-to-consumer leasing and subscription-based nursery furnishing is fragmenting competitive barriers, enabling digital-native entrants to challenge legacy manufacturers without heavy inventory burdens. Naturepedic leverages its GOTS-certified organic supply chain to command premium positioning in specialty retail channels. Crown Crafts sustains mass-market relevance through longstanding private-label partnerships with major North American retailers. Delta Children anchors its position via integrated crib-to-bedding manufacturing scale that controls cost structures across the value chain.
Baby bedding encompasses all textile-based sleep accessories designed for infants, typically constructed from woven or knitted fabrics with thread counts ranging from 200 to 400, and engineered to meet flammability resistance standards while maintaining breathability to reduce suffocation risk. Cotton crib sheets dominate volume due to cost accessibility and laundering durability, though organic fabric segments capture disproportionate margin pools as certification premiums widen price bands. Bamboo material categories are expanding fastest among eco-conscious gift buyers seeking antimicrobial properties and moisture-wicking performance. Modern design styling now competes directly with classic motifs as minimalist nursery aesthetics displace traditional patterns in urban consumer segments.
The US Consumer Product Safety Commission enforces stringent flammability and dimensional safety standards that dictate mattress protector construction and bumper pad legality, while OEKO-TEX Standard 100 certification shapes European import requirements and consumer trust thresholds. China's GB national standards and the EU's REACH chemical restrictions collectively force material substitutions away from formaldehyde-based finishes and certain synthetic dyes. Stakeholders must monitor evolving crib bumper bans across multiple jurisdictions and decide whether to phase out contested product lines proactively or defend regional market presence through regulatory segmentation.
Market Dynamics
Regulatory divergence across jurisdictions is fragmenting product portfolios, forcing manufacturers to maintain parallel SKUs for crib bumpers, mattress protectors, and fitted sheets to satisfy incompatible flammability and chemical safety mandates.
Growth Catalysts
- REACH chemical restrictions:European ECHA enforcement against formaldehyde-based textile finishes accelerates substitution toward plant-derived binders and water-based coatings, expanding addressable premium segments.
- Smart nursery integration:Sensor-embedded mattress pads and climate-regulating fabrics attract tech-forward millennial buyers seeking biometric monitoring capabilities alongside sleep safety.
- China:Urban middle-class expansion in tier-1 cities drives certified organic bedding penetration as GB national standards tighten alignment with international chemical safety benchmarks.
Market Restraints
- Raw cotton price volatility:Weather-driven supply disruptions in major producing regions compress margin buffers for standard-grade sheet manufacturers lacking forward-contract coverage.
- Supply concentration:GOTS-certified organic fiber processing clusters in Turkey and India create single-source dependencies for brands positioning on chemical-free claims.
- Technical limitation:Breathability-flammability tradeoffs in synthetic barrier fabrics restrict performance advancement for waterproof mattress protectors targeting dual certification.
Strategic Opportunities
- Germany:Underdeveloped direct-to-consumer subscription channels for nursery textiles present white-space entry for digital-native operators against entrenched retail partnerships.
- EU Green Deal:Circular economy textile mandates and extended producer responsibility schemes favor leasing models and take-back programs over conventional ownership structures.
- Bamboo-cotton fiber blending:Converging antimicrobial processing with conventional weaving equipment opens mid-market positioning between commodity cotton and premium organic tiers.
Industry Challenges
- GOTS-OEKO-TEX dual certification:Parallel audit timelines and conflicting documentation requirements strain compliance teams, delaying product launches by 4-8 months.
- Legacy ERP integration:Batch-lot traceability requirements for organic supply chains clash with decades-old manufacturing software, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Bedding Market |
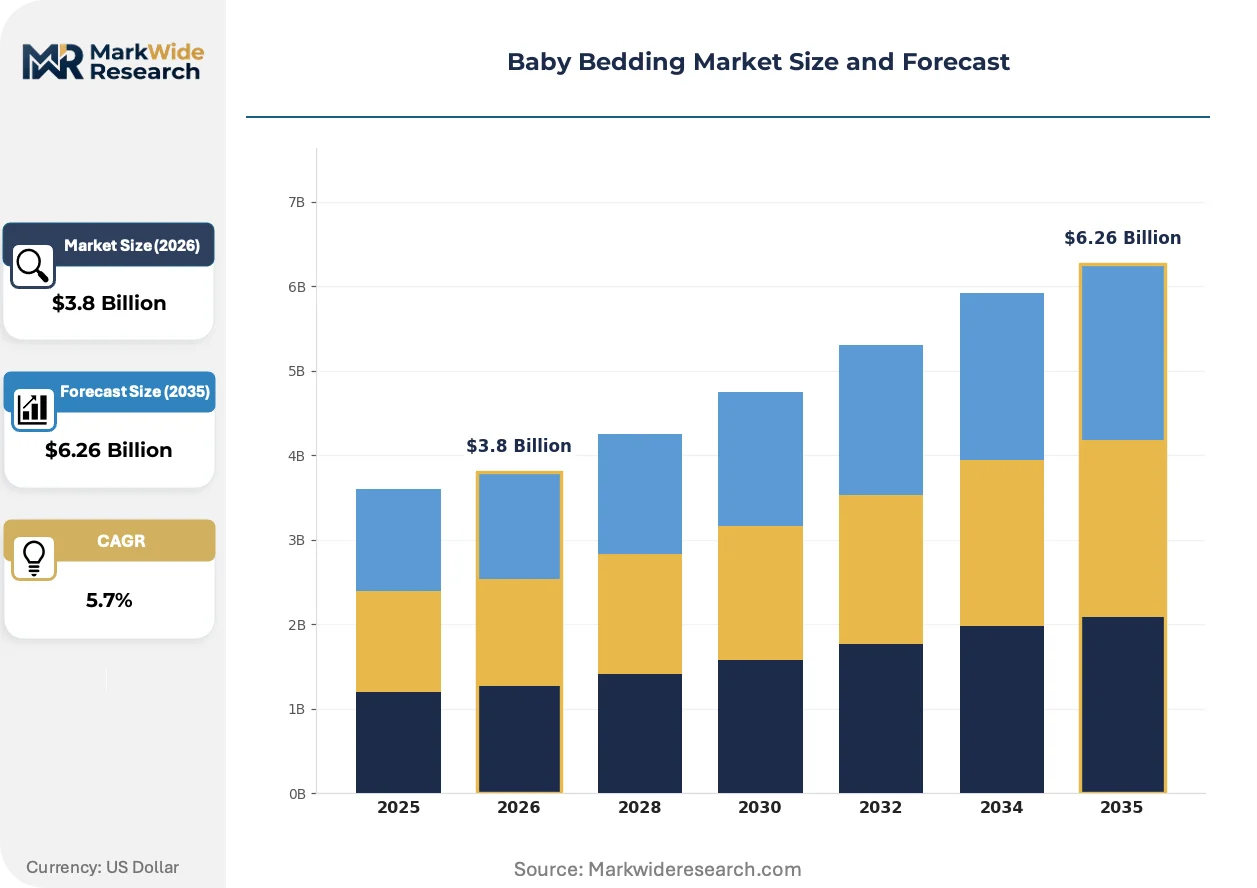
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crib Sheets, Blankets, Bumpers, Mattress Protectors Material: Cotton, Polyester, Bamboo, Organic Fabrics Design Style: Modern, Classic, Bohemian, Themed End User: Parents, Gift Buyers, Retailers, Online Shoppers |
| Companies Covered | Delta Children, Nestig, Crown Crafts, L.A. Baby, DaVinci Baby, Naturepedic, Storkcraft, Natart Juvenile, Burt’s Bees Baby, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Bedding Market Evolving Landscape
Material science advances and regulatory tightening are converging to redefine performance benchmarks, with breathability certification and chemical transparency displacing thread count as primary purchase criteria among informed buyers.
Phase-change material (PCM) microencapsulation is migrating from athletic apparel into infant mattress pads, where temperature-regulating gel beads embedded in polyurethane foam cores reduce overheating incidents. High-income urban parents in the United States and Germany are adopting PCM-equipped products at 3-5x premiums over standard foam. This migration from commodity polyurethane toward engineered thermal management is compressing volume share for legacy mattress manufacturers lacking materials science partnerships.
ECHA's 2023 restriction proposal on PFAS in textiles is forcing reformulation of waterproof breathable membranes used in crib mattress protectors. Industrial consequence includes accelerated R&D spending on bio-based alternatives such as polylactic acid coatings and plasma-treated natural fibers. Waterproof protector segments in the EU face 12-18 month reformulation cycles, with German and French retailers already delisting non-compliant SKUs ahead of enforcement deadlines.
Certification-driven preference shifts are restructuring wholesale relationships, with specialty boutiques and hospital gift shops prioritizing OEKO-TEX and GOTS documentation over traditional brand recognition. This displacement of legacy brand loyalty by third-party verification is most visible in California and New York, where municipal procurement guidelines for early childhood facilities mandate chemical disclosure thresholds exceeding federal minimums.
Baby Bedding Market Segmentation
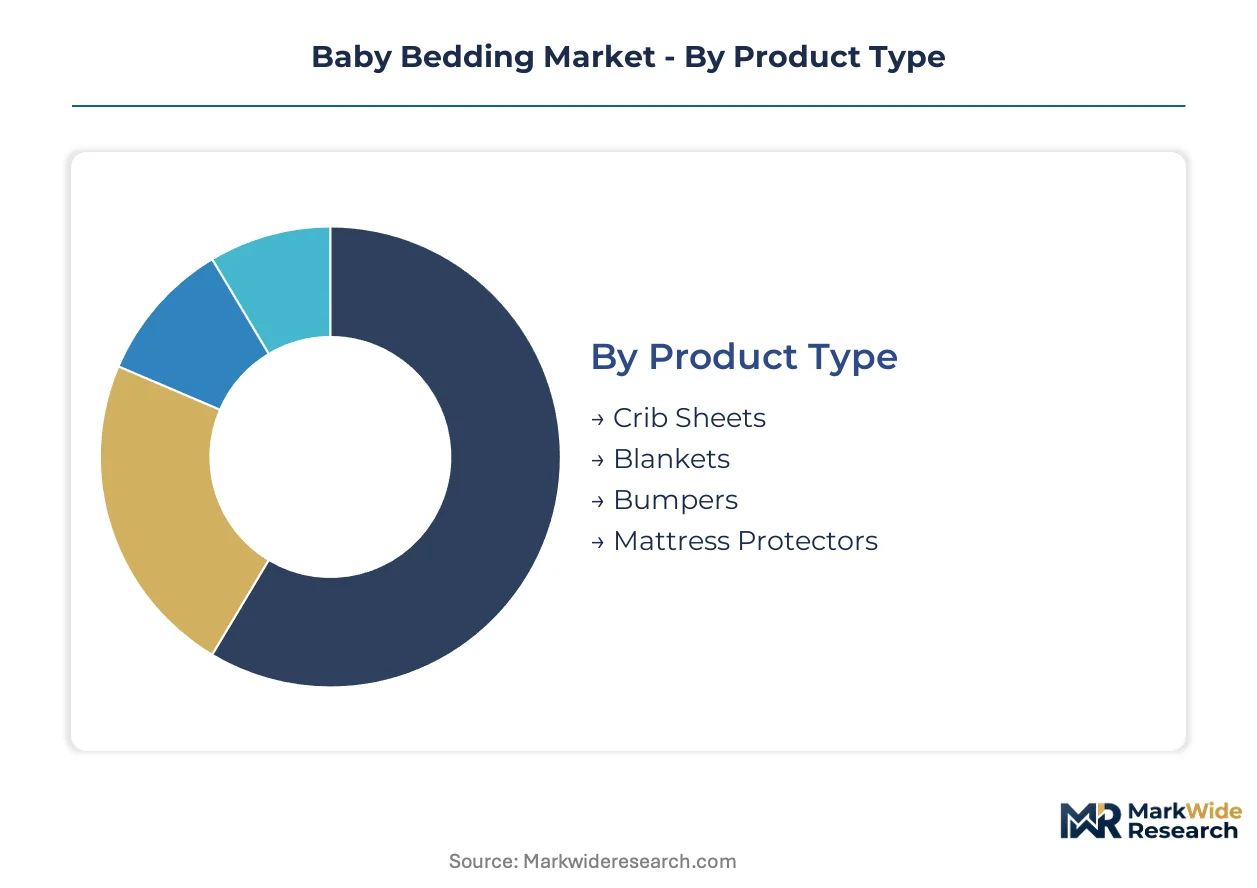
Baby bedding segmentation reflects divergent parental priorities across safety certification, aesthetic positioning, and procurement channel. Manufacturers must align SKU depth with distinct margin structures and compliance requirements that vary sharply by material grade and end-use context.
Product Type:
Mature volume categories dominate revenue concentration while emerging formats reshape regulatory exposure and shelf space allocation.
- Crib Sheets:Woven cotton or jersey-knit fitted sheets with elasticized corners secure the largest unit volumes due to repeat purchase frequency and laundering wear cycles. United States mass-market retailers prioritize 200-400 thread count SKUs with OEKO-TEX certification to satisfy municipal procurement guidelines in California and New York.
- Blankets:Multi-layer quilted or fleece constructions serve swaddling and stroller coverage functions, with demand clustering among gift buyers seeking heirloom-quality presentation packaging. German specialty boutiques favor GOTS-certified organic cotton batting to align with EU Green Deal circular economy mandates.
- Bumpers:Padded perimeter cushions face active regulatory phase-out across multiple US states and EU member countries, forcing inventory segmentation between compliant markets and restricted jurisdictions.
- Mattress Protectors:Waterproof breathable membranes with polyurethane barriers address spill protection and allergen containment, though ECHA PFAS restrictions are accelerating bio-based coating reformulation cycles.
Crib sheets handle the majority of throughput; mattress protectors are expanding most quickly as sensor-embedded smart nursery variants gain traction among millennial buyers.
Material:
Cost tier stratification separates commodity feedstocks from certified premium grades that command measurable price premiums and dedicated retail placement.
- Cotton:Standard upland and pima varieties constitute the baseline material for mass-market production, with sourcing concentration in India and Turkey creating vulnerability to climate-driven price spikes. Conventional cotton dominates volume in China and the United States where cost accessibility outweighs certification preferences for price-sensitive segments.
- Organic Fabrics:GOTS-certified cotton and wool fibers capture disproportionate margin pools through third-party verification of chemical-free processing, with demand concentrating in Germany and US coastal urban markets where municipal disclosure thresholds exceed federal minimums.
- Polyester:Microfiber and fleece constructions offer laundering durability and cost compression for value-tier positioning, though breathability limitations restrict adoption for direct infant skin contact applications.
- Bamboo:Viscose-derived rayon from bamboo pulp delivers antimicrobial properties and moisture-wicking performance that appeals to eco-conscious gift buyers, with processing clusters in China supplying raw fiber to global converters.
Cotton absorbs the bulk of production volume; bamboo is climbing the fastest on share as antimicrobial claims displace conventional cotton in premium gift segments.
Design Style:
Application context determines aesthetic priority, with nursery integration versus portable use driving divergent pattern and colorway strategies.
- Modern:Minimalist solids, geometric prints, and neutral palettes align with urban nursery renovation trends and Instagram-visible home staging priorities among millennial parents in tier-1 Chinese cities and US metropolitan areas.
- Classic:Pastel ginghams, toile patterns, and embroidered motifs retain loyalty among traditional gift givers and multi-generational households seeking continuity with childhood aesthetics.
- Bohemian:Macramé textures, tassel trim, and earth-tone botanical prints target design-forward parents in Brooklyn, Berlin, and Shanghai who treat nursery curation as interior design statement.
- Themed:Licensed character prints and seasonal motifs serve event-driven purchase occasions, with inventory risk concentrated around holiday replenishment cycles and entertainment franchise release windows.
Modern styling commands the dominant share of new product development investment; bohemian is gaining share fastest as design-forward positioning penetrates mid-market retail channels.
End User:
Customer type segmentation dictates pricing architecture, with procurement authority and usage expertise creating distinct service requirements and margin profiles.
- Parents:Primary decision-makers with direct safety responsibility drive certification-sensitive purchasing, prioritizing OEKO-TEX and GOTS documentation over brand recognition in California, New York, and Germany.
- Gift Buyers:Non-expert purchasers responding to visual presentation and price anchoring create demand for premium packaging and registry integration, with hospital gift shops and specialty boutiques serving as key activation points.
- Retailers:Private-label buyers and category managers at mass-market chains and specialty boutiques negotiate volume commitments against exclusive design and certification guarantees.
- Online Shoppers:Platform-native consumers discover and evaluate through algorithmic recommendation and review aggregation, with subscription and leasing models emerging as retention mechanisms.
Parents generate the majority of revenue volume; online shoppers are expanding most quickly as direct-to-consumer platforms fragment traditional wholesale relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circular economy mandates and extended producer responsibility schemes are redirecting procurement patterns toward certified organic supply chains and take-back programs across major consumer markets.
United States
Millennial parents in California and New York drive premium nursery investments with municipal procurement guidelines mandating chemical disclosure thresholds exceeding federal minimums. The US Consumer Product Safety Commission enforces stringent flammability standards that dictate mattress protector construction and crib bumper legality. Los Angeles and New York City anchor specialty retail and hospital gift shop distribution networks prioritizing OEKO-TEX documentation.
Germany
Urban middle-class households in Berlin and Hamburg prioritize GOTS-certified organic materials aligned with EU Green Deal textile mandates. ECHA REACH chemical restrictions against formaldehyde-based finishes accelerate substitution toward plant-derived binders. Bavaria hosts underdeveloped direct-to-consumer subscription channels presenting white-space entry for digital-native operators.
China
Tier-1 city expansion in Shanghai and Beijing drives certified organic bedding penetration as GB national standards tighten alignment with international chemical safety benchmarks. NMPA-equivalent regulatory bodies enforce evolving safety protocols. Yangtze River Delta processing clusters supply bamboo-derived viscose fiber to global converters.
India
Urban nuclear families in Maharashtra and Karnataka seek antimicrobial bamboo-cotton blends as BIS standards gradually harmonize with OEKO-TEX benchmarks. CDSCO-aligned regulators monitor textile chemical safety for infant products. Tamil Nadu weaving clusters specialize in organic cotton processing for export-oriented brands.
United Kingdom
London and Southeast England parents exhibit certification-sensitive purchasing prioritizing third-party verification over traditional brand recognition. Health England guidelines influence nursery safety expectations in early childhood facilities. Midlands manufacturing bases sustain private-label production for mass-market retail chains.
Baby Bedding Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans mass-market private-label fabricators, certified organic specialists, and integrated crib-to-bedding manufacturers. Three archetypes dominate: legacy retailers with longstanding wholesale partnerships, digital-native entrants leveraging asset-light subscription models, and materials-science-forward operators commanding premium positioning. M&A activity concentrates on certified supply chain acquisitions and technology licensing for smart nursery integration.
Within the certified organic tier, Naturepedic exemplifies premium positioning through GOTS supply chain anchoring. Crown Crafts occupies a position representing mass-market private-label relevance via entrenched North American retail partnerships. Delta Children anchors the integrated manufacturing archetype with captive production scale controlling cost structures across crib-to-bedding value chains.
| Leading Market Players |
|---|
| Delta Children |
| Nestig |
| Crown Crafts |
| L.A. Baby |
| DaVinci Baby |
| Naturepedic |
| Storkcraft |
| Natart Juvenile |
| Burt's Bees Baby |
| Others |
Value Network & Pricing Analysis
Single-source dependency on GOTS-certified organic fiber processing in Turkey and India compresses margin buffers for premium-tier manufacturers while forcing parallel inventory builds for dual-certification SKUs. This concentration dynamic widens price spreads between certified organic and conventional cotton tiers as audit timelines extend launch windows.
Pricing Analysis
Certification level creates the primary spread between premium and mass-market positioning, with GOTS and OEKO-TEX dual-certified products commanding measurable premiums over single-standard alternatives. Three-tier pricing structure across premium organic, certified standard, and economy conventional levels reflects material grade and compliance investment rather than brand equity alone. Pricing pressure stems from raw cotton volatility in major producing regions, compressing margins for manufacturers lacking forward-contract coverage. Mass-market retailers exhibit highest price sensitivity, while specialty boutiques and hospital gift shops prioritize documentation over cost.
Supply Chain Analysis
Tariff exposure between China and major Western consumer markets dominates supply chain risk calculus for bamboo-derived viscose processors. Production concentrates in India, Turkey, and China, with Tamil Nadu weaving clusters and Yangtze River Delta fiber processors anchoring global organic and bamboo supply respectively. Raw material dependencies rest on upland cotton futures, GOTS-certified organic fiber, and polylactic acid bio-coatings. Distribution runs through mass-market retail partnerships, specialty boutique networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart nursery integration and REACH chemical restrictions are accelerating material science R&D cycles, creating asymmetric opportunity for operators with certified supply chains and sensor-embedded product pipelines.
For Market Incumbents: Harden certified supply chain control through backward integration into organic fiber processing or exclusive GOTS-certified mill partnerships. Deepen regulatory compliance teams to compress dual-certification timelines from 8 months toward 4 months. Sensor-embedded mattress pad entrants threaten premium positioning; materials science partnerships with PCM microencapsulation specialists anchor thermal management differentiation. For New Entrants and Emerging Players: Germany's underdeveloped direct-to-consumer subscription channels present immediate white-space entry against entrenched retail partnerships. Tier-1 Chinese cities exhibit certification-sensitive purchasing growth as GB standards tighten. Target hospital gift shop procurement with OEKO-TEX documentation and registry integration as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified supply chain acquisitions over brand assets. Five-to-ten year viability hinges on circular economy compliance and smart nursery technology licensing. Acquisition target archetype: mid-cap operators with captive GOTS-certified processing and dormant sensor-embedded R&D pipelines. ECHA PFAS enforcement timelines signal inflection for waterproof membrane reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| GOTS Supply Chain Acquisition | Captive organic fiber processing locks in premium-tier margin pools against Turkish and Indian concentration risk. |
| Sensor-Embedded Product Launch | Biometric monitoring capabilities attract tech-forward millennial buyers in California and New York metro areas. |
| Direct-to-Consumer Subscription Launch | Asset-light leasing models fragment wholesale dependency and align with EU Green Deal circular economy mandates. |
| Bio-Based Coating Reformulation | Polylactic acid and plasma-treated natural fiber alternatives satisfy ECHA PFAS restrictions ahead of enforcement deadlines. |
| Extended Producer Responsibility Program | Take-back and recycling schemes preempt EU Green Deal textile mandates in Germany and adjacent member states. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs records, retail audit databases, and regulatory filing repositories. Conversations with brand managers at certified organic specialists, category buyers at mass-market chains, supply planners at integrated manufacturers, and channel partners at hospital gift shop distributors inform demand-side calibration. Secondary validation draws from CPSC safety standard updates, ECHA restriction proposals, GB national standard harmonization notices, and GOTS certification registry data. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates.
Forecast inputs include material cost indices, certification adoption curves, smart nursery technology penetration rates, and regulatory enforcement timelines across the projection horizon. Segmentation dimensions span product type, material grade, design style, and end-user archetype, with additional modeling of certification tier and distribution channel evolution. CAGRs derive from regression against historical premium-tier expansion and forward scenario weighting for regulatory phase-outs and technology substitution.
Macroeconomic conditions sit as an overlay; deviation in cotton futures volatility, tariff implementation schedules, or ECHA enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on certification timeline compression and sensor-embedded product adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Crib Mattress Market
Baby Products
North America Baby Bottle Market
Baby Products
Baby Detergents and Laundry Products Market
Baby Products
Luxury Baby Stroller Market
Baby Products
Pregnancy Products Market
Baby Products
Electric Baby Nail Trimmer Market
Baby Products
Baby Sleeping Bag Market
Baby Products
Baby Pacifier Market
Baby Products
Baby Feeding Accessories Market
Baby Products
Noise-Muffling Infant Hat Market
Baby Products
Baby Wet Wipes Market
Baby Products
Travel Pillow Market
Baby Products
Baby High Chair Market
Baby Products
Baby Tableware Market
Baby Products
Baby Bassinets Market
Baby Products
Baby Nipple/Teat Market