
 Amps & Effects Market | 2026-2036
Amps & Effects Market Size, Share, and Industry Trends Forecast 2026-2036
Amps & Effects Market Insights
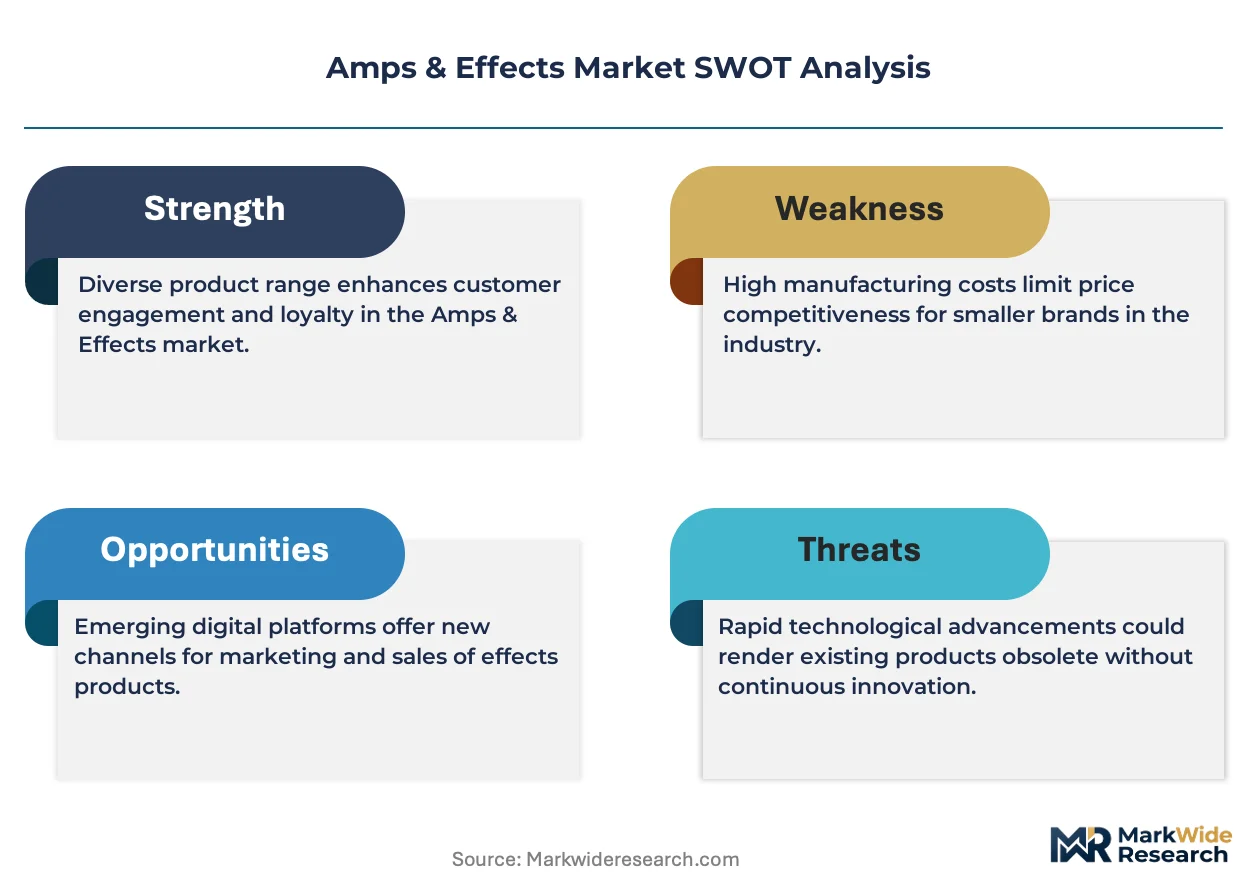
Home studio operators are unwinding the traditional dominance of touring professionals as the primary revenue archetype in the Amps & Effects Market. BOSS leverages its pedal manufacturing scale to occupy the mass-market tier across multiple continents. Electro-Harmonix sustains its Brooklyn-based production model to differentiate through analog circuit authenticity. Korg competes by extending its modeling technology from synthesizers into guitar processor architectures.
Amps and effects encompass electronic signal-processing hardware that modifies, amplifies, or shapes instrument audio through vacuum tube, solid-state transistor, or digital DSP architectures operating across frequency ranges from 20 Hz to 20 kHz. These devices serve commercial purposes in live performance reinforcement, studio recording chains, and practice environments where tonal manipulation defines artistic output. Guitar Amplifiers and Effects Pedals together constitute the mature revenue core, while Digital Processors represent the fastest-growing segment as software emulation achieves perceptual parity with analog circuitry. Modeling Technology commands expanding margin pools as semiconductor efficiency reduces hardware costs and subscription-based firmware updates create recurring revenue streams absent from tube-based alternatives.
The Federal Communications Commission governs electromagnetic emissions from digital processors and switch-mode power supplies sold in the United States, while the European Union's RoHS and REACH frameworks restrict hazardous substances in printed circuit boards and component soldering. California's Proposition 65 compounds compliance obligations for products containing lead in vacuum tube glass or cadmium-plated chassis hardware. Stakeholders must monitor whether emerging right-to-repair legislation in multiple states mandates schematic disclosure and spare parts availability that would erode proprietary firmware lock-in strategies.
Market Dynamics
Modeling technology is fragmenting the traditional tube amplifier supply base by collapsing the cost premium once commanded by analog circuitry, forcing legacy manufacturers to restructure R&D budgets toward firmware development while preserving heritage brand equity.
Growth Catalysts
- Home Studio Proliferation:Digital audio workstations and affordable interface hardware have expanded the addressable base of independent producers requiring compact signal chains. These operators prioritize footprint and versatility over absolute tonal purity.
- REACH Substance Restrictions:The European Union's phased restrictions on hazardous substances in electronics are accelerating reformulation of solder alloys and capacitor dielectrics, creating competitive advantage for early-compliant manufacturers in export markets.
- Semiconductor Efficiency Gains:Advances in DSP chip architecture are reducing power consumption and thermal load in digital processors, enabling pedalboard-friendly form factors previously impossible with earlier generation chipsets.
Market Restraints
- Vacuum Tube Supply Concentration:Three facilities in Russia and the Czech Republic produce the majority of premium audio-grade vacuum tubes, exposing amplifier manufacturers to geopolitical supply interruptions and price volatility.
- RoHS Compliance Costs:Reformulating lead-free solder joints to match the reliability of legacy tin-lead alloys requires capital-intensive process engineering and extended qualification timelines for military and aerospace crossover suppliers.
- Silicon Foundry Allocation:Consumer electronics and automotive sectors command priority access at TSMC and Samsung foundries, constraining production ramps for specialized audio DSPs during capacity-tight cycles.
Strategic Opportunities
- Subscription Firmware Models:Recurring revenue from impulse response libraries and algorithm updates offers margin expansion unavailable to tube-based competitors locked in one-time hardware transactions.
- Right-to-Repair Legislation:Pending state-level mandates in New York, Minnesota, and California requiring schematic disclosure and spare parts availability would advantage modular digital architectures over sealed analog designs.
- India Live Music Infrastructure:Venue construction and touring circuit expansion in Mumbai, Bangalore, and Delhi create first-mover opportunity for brands establishing authorized service networks before market saturation.
Industry Challenges
- Analog Circuit Design Talent Scarcity:Retirement of engineers trained in tube topology and discrete transistor design outpaces university pipeline output, compressing development timelines for heritage product refreshes.
- FCC Part 15 Certification Timelines:Electromagnetic emissions testing for digital processors with wireless connectivity features extends product launch windows by four to six months versus purely analog equivalents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amps & Effects Market |
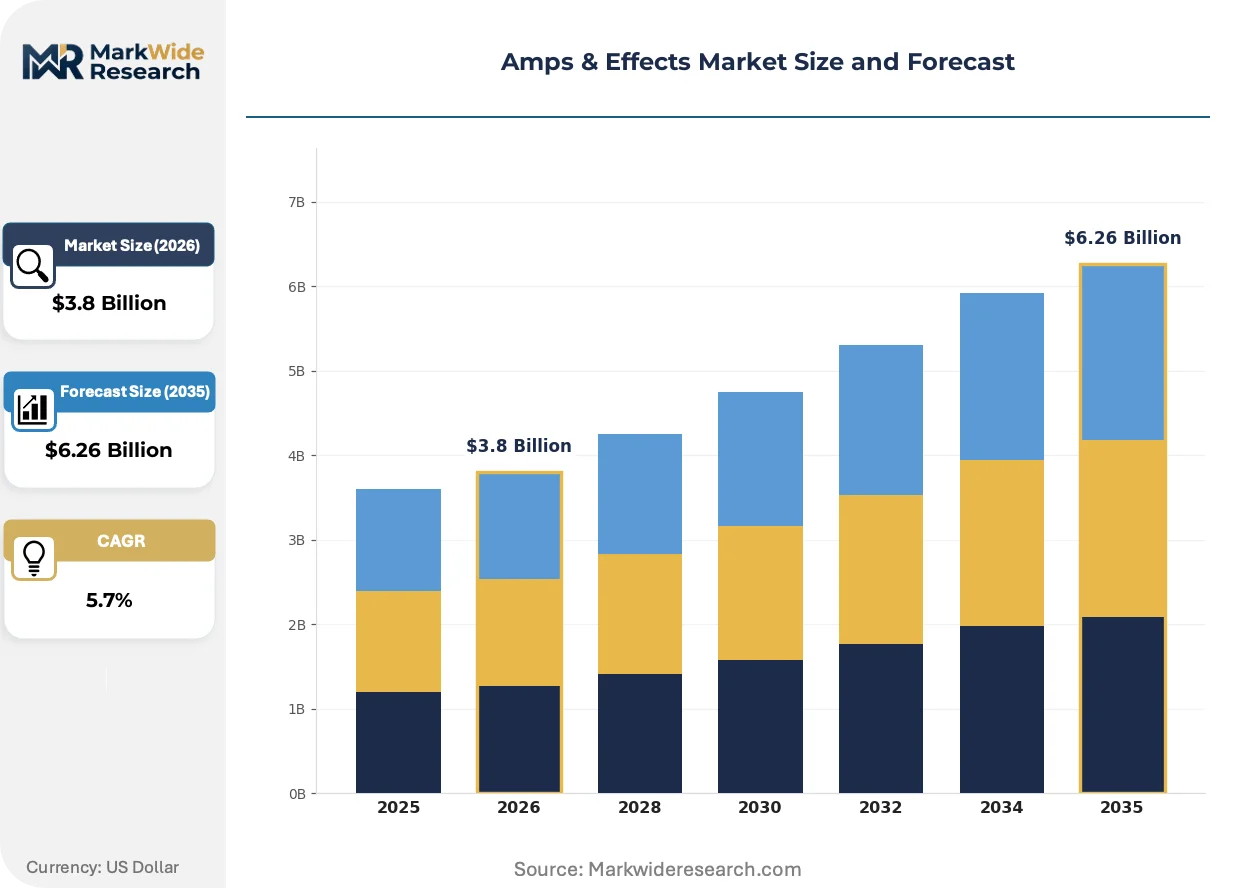
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Guitar Amplifiers, Effects Pedals, Digital Processors, Combo Amps End User: Professional Musicians, Hobbyists, Recording Studios, Live Venues Technology: Tube Amplification, Solid State, Modeling Technology, Hybrid Systems Distribution Channel: Online Retail, Music Stores, Direct Sales, Wholesale |
| Companies Covered | BOSS, Line 6, ZOOM, Digitech, Electro-Harmonix, TC Electronic, Dunlop Manufacturing, Inc., Behringer, Korg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amps & Effects Market Trends and Innovations
Convergence of machine learning inference with embedded DSP architectures is enabling real-time tone matching previously requiring studio post-production, reshaping how performers prepare signal chains for live deployment.
Neural network-powered amp modeling is fragmenting the competitive landscape by collapsing the historical trade-off between authenticity and portability. Bedroom producers and touring professionals alike are adopting floorboard units capable of profiling physical amplifiers in under thirty seconds. This capability is compressing the addressable market for mid-tier analog amplifiers while expanding total accessible volume through lower price points.
The European Union's Ecodesign for Energy-Related Products Directive is mandating standby power consumption limits below 0.5 watts for audio equipment sold in member states. Manufacturers are redesigning switch-mode power supplies and implementing true hardware bypass circuits to meet these thresholds. Guitar amplifier product lines with tube-based standby circuits face disproportionate engineering burden compared to fully digital architectures.
Direct-to-consumer channel expansion is disrupting the traditional dealer-distributor hierarchy that has dominated musical instrument retail for decades. Boutique pedal builders in Portland, Austin, and Berlin are leveraging social media demonstration content to bypass wholesale markup structures. This shift is most visible in the effects pedal segment, where limited-batch releases sell through proprietary webstores within hours of announcement, bypassing traditional inventory risk allocation.
Amps & Effects Market Segmentation
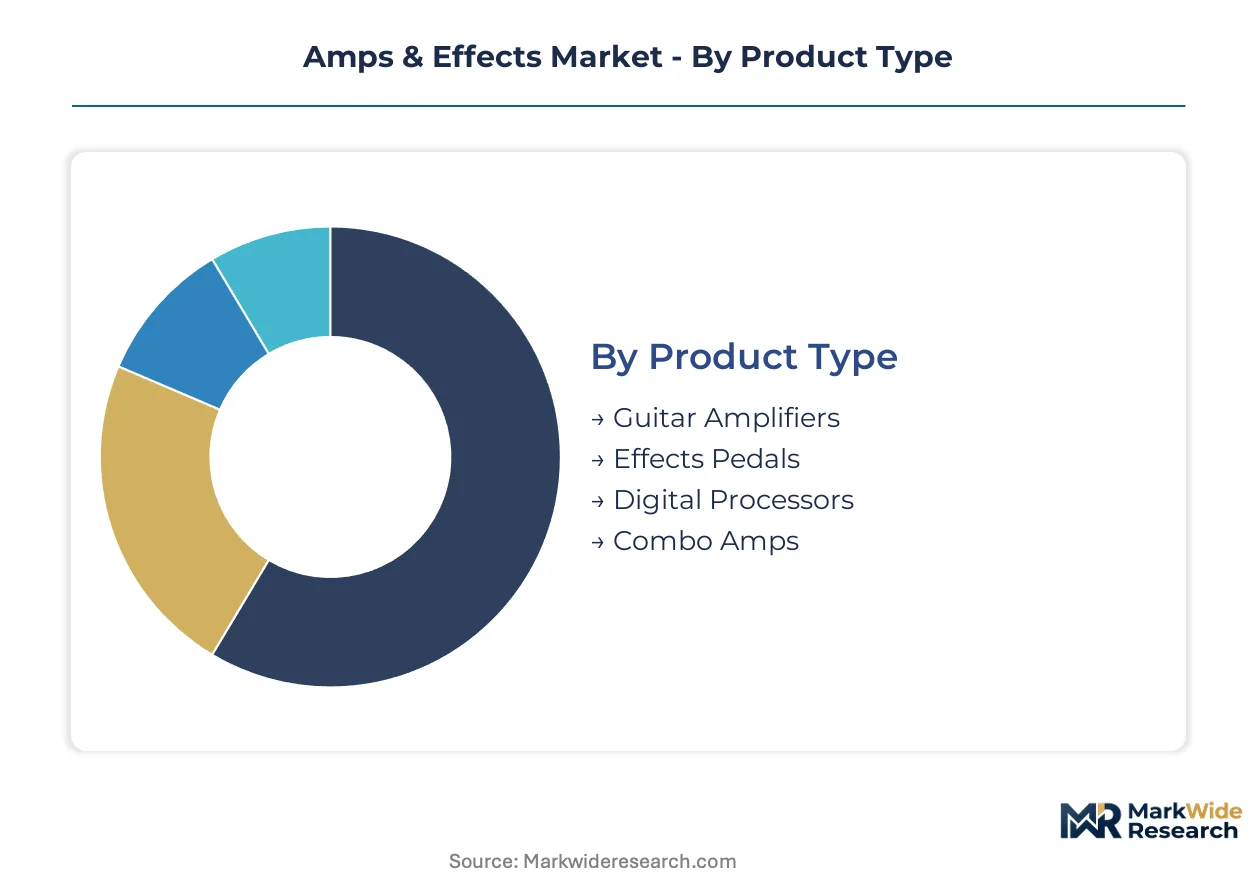
Segmentation in the Amps & Effects Market reveals divergent channel economics across product architectures. Tube-based equipment flows through specialized music retailers requiring audition infrastructure, while digital processors migrate toward direct-to-consumer platforms where firmware subscriptions drive lifetime value.
Product Type:
Channel mix varies sharply by product category, with effects pedals dominating online retail velocity and guitar amplifiers sustaining music store foot traffic through tactile evaluation requirements.
- Guitar Amplifiers:Vacuum tube and solid-state enclosures ranging from 5-watt practice units to 100-watt stage heads, with speaker configurations from single 8-inch to quad 12-inch arrays. Demand concentrates in the United States where vintage gear culture sustains premium pricing for hand-wired tube architectures.
- Effects Pedals:Compact stompbox units processing signal through analog bucket-brigade chips or digital DSP, typically housed in die-cast aluminum enclosures with true-bypass switching. Hobbyists in Germany and Japan drive volume through direct-to-consumer channels where limited-batch releases command collector premiums.
- Digital Processors:Floorboard and rackmount units executing convolution-based amp modeling and impulse response cabinet simulation.
- Combo Amps:Integrated amplifier-speaker systems targeting practice and small-venue applications.
Guitar Amplifiers dominate installed base. Digital Processors represent where expansion concentrates.
End User:
Customer type determines margin structure, with professionals accepting premium pricing for road-worthy construction and hobbyists prioritizing feature density per dollar spent.
- Professional Musicians:Touring and session players requiring redundant signal chains, road-case durability, and rapid repairability across international circuits. Concentration in Nashville, Los Angeles, and London drives demand for tour-grade tube amplifiers with modular preamp architectures.
- Hobbyists:Bedroom and home-studio operators prioritizing headphone compatibility, compact footprints, and preset recall for social media content creation. This segment is expanding most quickly as digital modeling collapses the cost barrier to professional-grade tone.
- Recording Studios:Commercial facilities maintaining diverse amplifier collections for client tonal variety.
- Live Venues:Clubs and theaters investing in house backline to reduce artist freight complications.
Professional Musicians anchor revenue per unit. Hobbyists are climbing the fastest in absolute volume terms.
Technology:
Cost tier stratification follows thermal and component economics, with tube architectures commanding material premiums and modeling systems benefiting from semiconductor scaling curves.
- Tube Amplification:Thermionic valve circuits utilizing 12AX7 preamp tubes and EL34/6L6 power sections, generating harmonic distortion through transformer saturation and output-stage compression. Supply concentrates in the Czech Republic and Russia for premium audio-grade valves, exposing manufacturers to geopolitical price volatility.
- Modeling Technology:DSP-based emulation executing real-time circuit simulation and impulse response convolution, with neural profiling capabilities enabling 30-second capture of physical amplifier behavior. Semiconductor efficiency gains at TSMC and Samsung foundries enable pedalboard-friendly thermal envelopes previously unattainable.
- Solid State:Transistor-based amplification utilizing MOSFET and bipolar junction topologies for clean headroom and reliability.
- Hybrid Systems:Architectures combining tube preamp stages with solid-state power sections.
Tube Amplification retains prestige positioning. Modeling Technology shows the steepest expansion trajectory.
Distribution Channel:
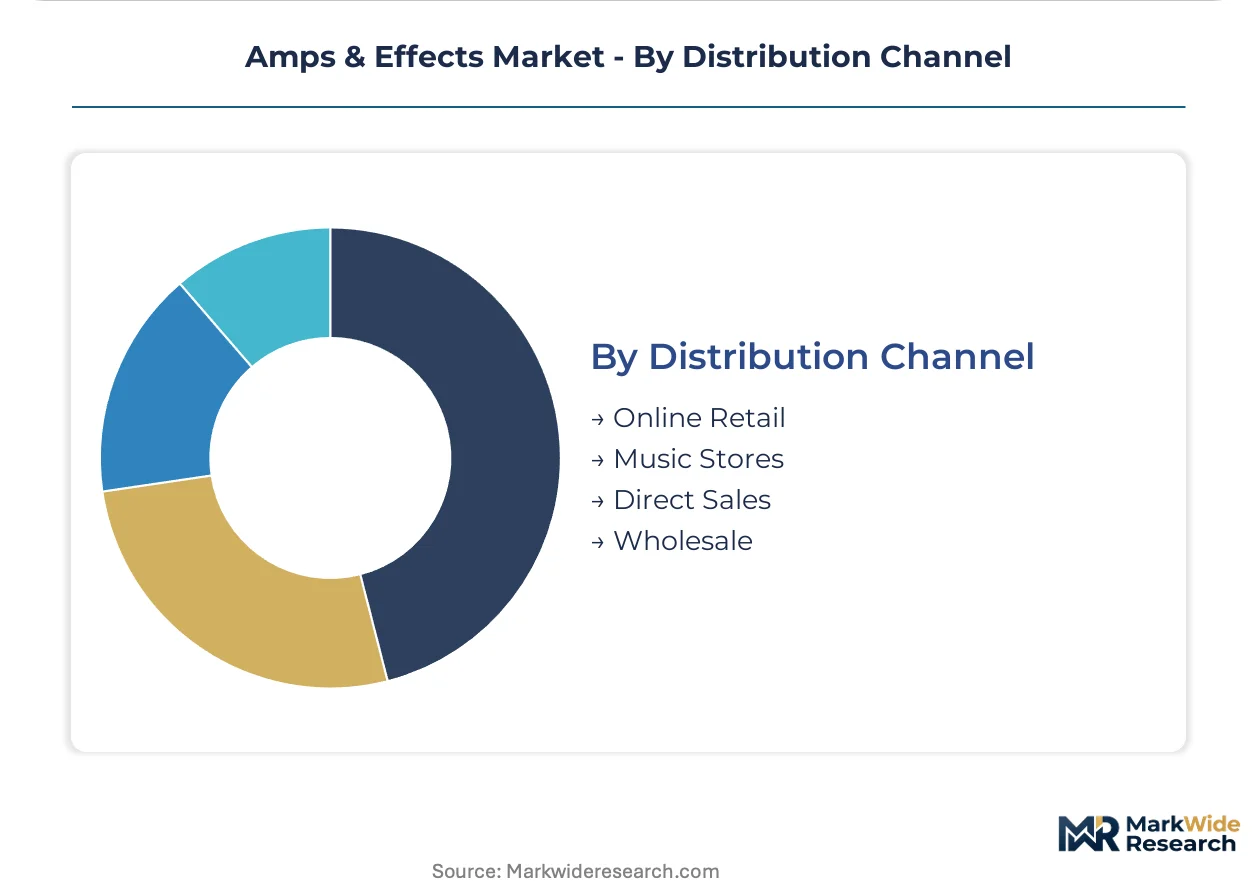
Geography shapes channel viability, with urban density in Japan and South Korea favoring specialized music retail while dispersed North American populations accelerate online migration.
- Online Retail:E-commerce platforms and proprietary direct-to-consumer webstores, dominant in effects pedals where demonstration videos substitute for physical audition. Portland and Berlin boutique builders leverage social media content to bypass wholesale markups entirely.
- Music Stores:Brick-and-mortar retailers with audition rooms and repair service desks, critical for guitar amplifiers where speaker interaction and tactile control response influence purchase decisions. Concentration in the United States, United Kingdom, and Japan sustains this channel despite digital encroachment.
- Direct Sales:Manufacturer-owned channels including factory showrooms and tour-based product demonstrations.
- Wholesale:Distributor networks serving secondary markets and institutional procurement.
Music Stores retain amplifier volume. Online Retail is gaining share fastest in effects and digital categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles handles containerized electronics imports that supply West Coast music retail distribution, while Germany's Rhine corridor rail network moves components between Czech tube factories and Hamburg export terminals.
United States
Vintage amplifier culture in Nashville and Los Angeles sustains premium tube amplifier demand alongside touring infrastructure. FCC Part 15 certification governs electromagnetic emissions from digital processors with wireless connectivity. Austin's boutique pedal builder cluster leverages direct-to-consumer channels to bypass traditional wholesale markups entirely.
Germany
REACH substance restrictions accelerate reformulation of solder alloys and capacitor dielectrics for export compliance. The country's central bank monitors currency stability for component import costs. Berlin's electronic music producer density drives demand for compact modeling processors in home studio configurations.
Japan
METI standards for electromagnetic compatibility shape product design specifications for domestic and export markets. Osaka's manufacturing heritage supports precision component fabrication for effects pedal enclosures. Tokyo's specialized music retail concentration sustains brick-and-mortar audition infrastructure for high-end amplifiers.
United Kingdom
London's session musician ecosystem generates professional-grade equipment demand for studio and touring applications. RoHS directives from Brussels constrain lead content in vacuum tube glass and chassis hardware. Manchester's live venue circuit expansion creates backline procurement opportunities for house amplifier installations.
South Korea
Seoul Capital Area's semiconductor foundry proximity enables rapid prototyping for DSP architecture iterations. MFDS regulations apply to electronics with medical-adjacent applications in hearing protection devices. Busan's port infrastructure handles component imports for domestic assembly and re-export to Southeast Asian markets.
Amps & Effects Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D agility, creating a tiered structure where scale-driven platforms face nimble boutique challengers. The vendor base clusters around three strategic archetypes: mass-market pedal manufacturers leveraging production scale, analog authenticity specialists preserving hand-wired heritage, and digital modeling innovators capturing semiconductor efficiency gains. Dominant competitive moves include direct-to-consumer channel expansion and subscription-based firmware monetization.
Within the mass-market tier, BOSS and Korg occupy positions defined by manufacturing scale and technology licensing breadth. Electro-Harmonix exemplifies the analog authenticity archetype through Brooklyn-based production differentiation. Line 6 anchors the digital modeling vector where neural profiling capabilities reshape competitive dynamics.
| Leading Market Players |
|---|
| BOSS |
| Line 6 |
| ZOOM |
| Digitech |
| Electro-Harmonix |
| TC Electronic |
| Dunlop Manufacturing, Inc. |
| Behringer |
| Korg |
| Others |
Pricing and Supply Chain Analysis
Component-scale economies at TSMC and Samsung foundries concentrate DSP manufacturing leverage among digital processor vendors, compressing per-unit silicon costs while vacuum tube production bottlenecks in the Czech Republic and Russia sustain premium pricing tiers for analog heritage brands.
Pricing Analysis
Volume-discount tiering structures separate boutique hand-wired tube amplifiers from mass-market solid-state units and economy-tier practice amplifiers. Price differentiation hinges on certification grade for electromagnetic compliance and brand heritage premiums accumulated through decades of artist endorsement. Cost compression in mid-tier analog amplifiers intensifies as neural profiling technology collapses the authenticity premium once commanded by tube circuitry. Hobbyists exhibit highest price sensitivity, while touring professionals absorb premium pricing for road-grade construction and rapid field repairability.
Supply Chain Analysis
Strait of Hormuz transit underwrites petroleum-derived capacitor dielectric and enclosure polymer feedstocks, exposing manufacturers to energy price volatility. Geographic supply concentration centers on China for printed circuit board fabrication, Taiwan for advanced DSP wafer production, and the Czech Republic for premium audio-grade vacuum tubes. Raw material dependencies span rare-earth magnets for speaker drivers, aluminum for die-cast pedal enclosures, and lead-free solder alloys reformulated for RoHS compliance. Single-source vulnerability concentrates in the three remaining tube production facilities. Distribution runs through specialized music retailers for amplifier audition requirements and direct-to-consumer platforms for effects pedals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modeling technology disruption compresses analog authenticity premiums while expanding accessible volume through semiconductor efficiency gains, creating asymmetric pressure on legacy manufacturers.
For Market Incumbents: Fortify proprietary firmware lock-in through subscription-based impulse response libraries and algorithm update ecosystems. Accelerate backward integration into DSP architecture design to reduce foundry allocation vulnerability at TSMC and Samsung. Preserve heritage brand equity through limited-production hand-wired tube lines that sustain collector premiums despite digital encroachment.
For New Entrants and Emerging Players: Firmware customization services represent the most penetrable white-space where incumbents under-serve bedroom producers seeking personalized tone-matching workflows. Target India's expanding live venue circuit in Mumbai and Bangalore before authorized service network saturation. Deploy direct-to-consumer social media demonstration content to bypass wholesale markup structures entirely.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among digital processor vendors with established firmware subscription bases, positioning these archetypes for superior cash-flow quality over the medium term. Prioritize acquisition targets with modular hardware architectures compatible with emerging right-to-repair mandates in New York and California. Monitor FCC Part 15 certification timeline extensions as an inflection indicator for digital processor launch velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Firmware Launch | Transforms one-time hardware transactions into recurring revenue streams absent from tube-based competitors. |
| Direct-to-Consumer Channel Expansion | Bypasses wholesale markups through social media demonstration content, visible in Portland and Berlin boutique clusters. |
| Right-to-Repair Compliance Investment | Positions modular digital architectures advantageously against sealed analog designs under pending state mandates. |
| India Service Network Establishment | Captures first-mover positioning in Mumbai and Bangalore venue expansion before competitor saturation. |
| Neural Profiling Capability Integration | Collapses the historical trade-off between tonal authenticity and portability across professional and hobbyist segments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, RoHS compliance filings, and semiconductor foundry capacity disclosures. Primary interviews engaged product managers at digital processor manufacturers, procurement leads at vacuum tube distributors, and channel buyers at specialized music retailers. Secondary validation drew from customs trade records for component imports, SEC filings of listed musical instrument manufacturers, and patent filings for DSP architecture innovations. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Segmentation dimensions modeled span product architecture, end-user archetype, technology platform, and distribution channel across the projection horizon. Guitar amplifiers, effects pedals, digital processors, and combo amps constitute product categories. Professional musicians, hobbyists, recording studios, and live venues define customer segments. Tube amplification, modeling technology, solid-state, and hybrid systems capture technology stratification. Online retail, music stores, direct sales, and wholesale channels complete the framework. CAGRs derive from trend extrapolation adjusted for technology substitution elasticities and regulatory compliance cost trajectories. Forecast inputs incorporate semiconductor scaling curves for DSP cost reduction and vacuum tube supply concentration risk premiums.
Underlying assumptions cover sustained semiconductor foundry allocation for specialized audio DSPs, with deviation risk concentrated in geopolitical supply interruptions for Czech and Russian tube production. Forecasts reflect these assumptions without predictive certainty. Practitioners should keep alternative scenarios live as REACH substance restriction timelines and right-to-repair legislative developments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Smart Audio System Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Guitar Head Amplifiers Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
Clip-On Headphones Market
Audio Equipment
Consumer Audio Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Audio Equipment Market
Audio Equipment
Professional Microphones Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Commercial Microphone Market
Audio Equipment
Global Networked Audio Products Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Hi-Fi Cartridges Market