
 Global Networked Audio Products Market | 2026-2036
Global Networked Audio Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Networked Audio Products Market Outlook
Modular speaker bundling is consolidating buyer choice around expandable ecosystems rather than standalone purchases. Sonos leverages proprietary mesh networking to sustain premium positioning across residential installations. Samsung Electronics anchors its strategy through SmartThings integration, competing with display-centric audio convergence. Bose Corporation differentiates via proprietary spatial audio algorithms, dominating the high-fidelity segment through acoustic engineering heritage.
Networked audio products comprise IP-connected devices that stream, process, and reproduce audio content across local area networks or the internet, typically supporting sampling rates from 44.1 kHz to 192 kHz and bit depths of 16 to 24 bits for lossless reproduction in commercial and residential environments. Wireless technology leads volume shipments due to consumer preference for cable-free installation, though Ethernet retains margin concentration in professional installations where latency below 5 milliseconds is mandatory. The residential end-user segment occupies the largest revenue pool, while the commercial segment registers the fastest structural expansion as hospitality and retail operators retrofit spaces with centralized audio management.
The Federal Communications Commission governs spectrum allocation for Wi-Fi and Bluetooth transmissions in the United States, while the European Telecommunications Standards Institute coordinates cross-border interoperability requirements for networked devices under the Radio Equipment Directive. China's Ministry of Industry and Information Technology certifies wireless audio equipment through compulsory GB standards, shaping market access for imported hardware. Stakeholders must monitor evolving Matter protocol certification timelines and regional spectrum reallocation decisions to align product roadmaps with compliance windows.
Market Dynamics
Protocol convergence around Matter and Wi-Fi 6E is dissolving ecosystem silos that previously locked consumers into single-vendor hardware stacks, forcing incumbents to compete on audio engineering rather than captive network effects.
Growth Catalysts
- Smart home penetration in premium US households:Residential installations above 5,000 square feet increasingly specify whole-home audio as a standard feature, driving bundled ecosystem purchases over standalone speaker sales.
- Matter protocol certification timelines:Cross-brand interoperability mandates from the Connectivity Standards Alliance reduce consumer switching costs and expand addressable market for secondary brands.
- Hospitality retrofit cycles in Germany:Hotel operators centralize audio management through IP-based systems to reduce on-site technical staffing and enable remote content scheduling.
Market Restraints
- Semiconductor supply concentration in East Asia:Wi-Fi and Bluetooth SoC fabrication depends on TSMC and Samsung Foundry capacity, creating vulnerability to regional disruption.
- Latency floor in wireless architectures:Bluetooth and Wi-Fi protocols cannot consistently deliver sub-5-millisecond transmission, excluding them from professional live-performance and broadcast monitoring applications.
- Spectrum reallocation uncertainty under FCC proceedings:6 GHz band access rules for unlicensed devices remain subject to ongoing rulemaking, complicating multi-year product roadmaps.
Strategic Opportunities
- Underpenetrated rental housing in South Korea:Multi-dwelling unit installations for high-rise developments represent a greenfield segment with centralized infrastructure and bulk purchasing economics.
- Convergence of spatial audio with wellness applications:Biometric-responsive soundscapes for sleep and focus are expanding networked audio into health-adjacent verticals beyond entertainment.
- Direct-to-installer channel development:Bypassing retail to serve custom integrators and AV consultants captures margin and builds specification loyalty in high-value residential projects.
Industry Challenges
- Acoustic engineering talent scarcity:DSP algorithm development and transducer design expertise concentrates in legacy audio hubs, constraining rapid team scaling for new entrants.
- Matter certification backlog:Testing queue delays at authorized laboratories extend time-to-market for interoperable product launches, compressing revenue windows.
- Legacy control system integration:Proprietary RS-232 and IR protocols in installed commercial bases require bridging hardware that adds cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Networked Audio Products Market |
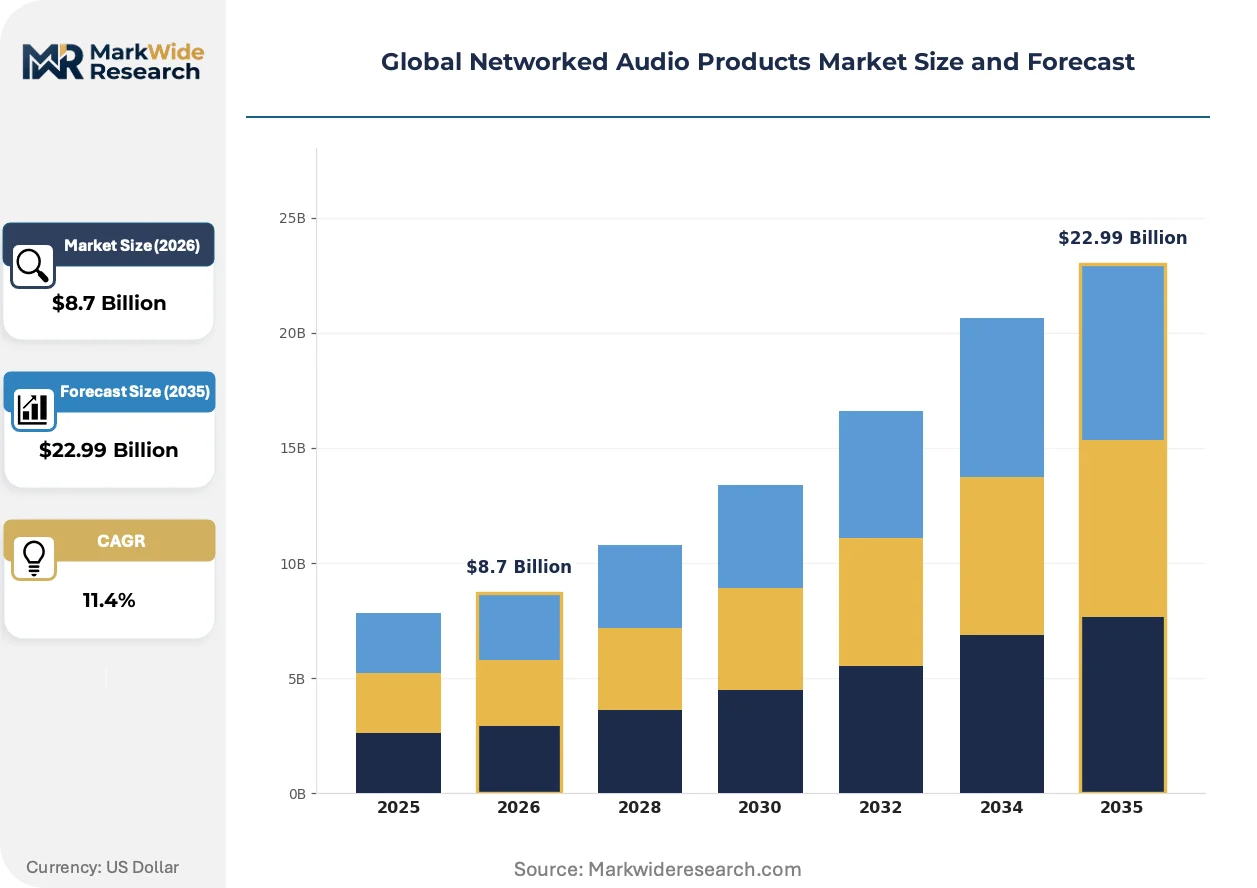
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Speakers, Microphones, Amplifiers, Audio Interfaces Technology: Wireless, Bluetooth, Wi-Fi, Ethernet End User: Residential, Commercial, Educational, Corporate Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Sonos, Samsung Electronics, Sony Group Corporation, Logitech, Yamaha, Denon, Bose Corporation, Roku, QSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Networked Audio Products Market Strategic Shifts
Audio reproduction technology is migrating from hardware-centric differentiation toward software-defined experiences, with algorithmic personalization and cloud-based content curation becoming primary value levers.
Spatial audio rendering through head-related transfer function processing is expanding into mainstream music streaming and gaming headsets, compressing the premium tier where such features once resided exclusively. Consumer adoption accelerates as Apple, Sony, and Amazon normalize three-dimensional sound in mass-market hardware. The technology is expanding into automotive cabins, where multiple seat positions and road noise profiles demand adaptive rendering algorithms.
REACH substance restrictions and EU Ecodesign requirements for standby power consumption are forcing hardware redesigns across supply chains serving European markets. Manufacturers must eliminate certain flame retardants and reduce vampire power draw below one watt to maintain market access. Professional installation segments face the steepest compliance costs due to longer product lifecycles and certification documentation burdens.
Subscription bundling of hardware and content services is displacing transactional purchase models in residential segments, locking consumers into recurring revenue relationships. Sonos, Amazon, and Apple increasingly lead with service-first propositions where speaker hardware functions as a delivery endpoint. This pattern concentrates most visibly in the United States, where streaming penetration and credit-based financing options enable low-entry-cost hardware distribution.
Global Networked Audio Products Market Segmentation
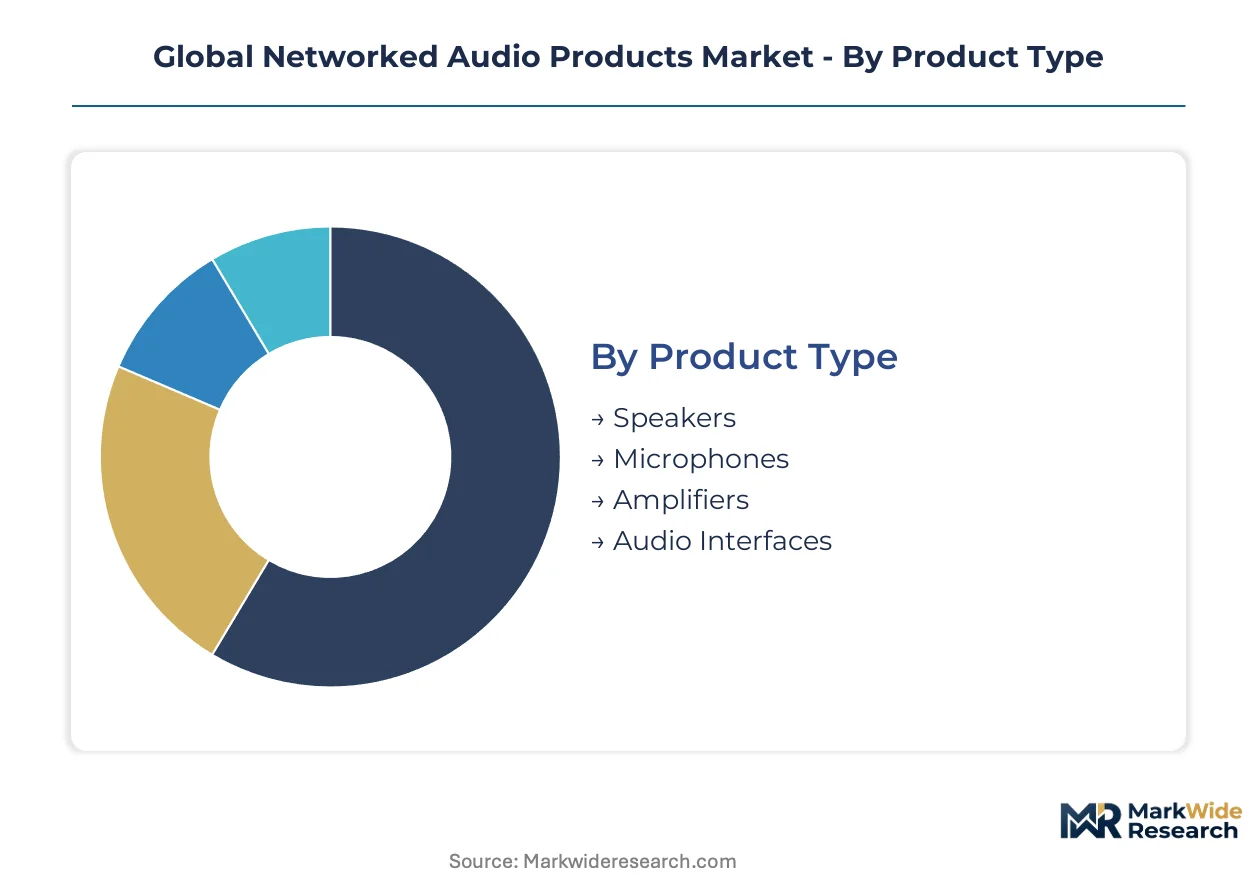
Networked audio markets fragment across four distinct dimensions that reshape procurement patterns and margin structures. Product type determines hardware lifecycle and replacement cadence. Technology choice locks in ecosystem compatibility and latency performance. End-user segmentation separates consumer entertainment spending from enterprise infrastructure budgets. Distribution channel selection reflects buyer sophistication and project scale.
Product Type:
Buyers differentiate by acoustic output requirements and installation complexity rather than price alone.
- Speakers:These transducer systems convert electrical signals to acoustic output across frequencies from 20 Hz to 20 kHz, with enclosure designs varying from sealed bookshelf units to ported floor-standing towers. Demand concentrates in United States premium residential developments above 4,000 square feet where whole-home audio specification is becoming standard. Multi-room installations favor expandable ecosystems over standalone purchases.
- Microphones:Capture devices with condenser, dynamic, or MEMS transduction elements sample acoustic pressure variations for network transmission, with polar patterns ranging from omnidirectional to shotgun configurations. Corporate conferencing installations in Germany drive specification volume as hybrid work policies permanently alter meeting room infrastructure. Beamforming arrays reduce ambient noise pickup in open-plan environments.
- Amplifiers:Power electronics delivering 20 to 500 watts per channel drive speaker transducers with Class D efficiency dominating networked implementations. Networked amplifiers enable centralized rack-mounted deployment with zone-based control.
- Audio Interfaces:Analog-to-digital and digital-to-analog conversion hardware bridge legacy sources to IP networks, supporting sampling rates up to 192 kHz. Professional installations require redundant clocking and low-jitter performance.
Volume sits with Speakers; growth tilts toward Microphones.
Technology:
Transmission protocol selection determines latency floor, range, and interoperability with existing infrastructure.
- Wireless:Radio-frequency transmission architectures encompassing proprietary mesh and broadcast protocols enable cable-free installation across residential and light commercial environments. United States consumer preference for aesthetic minimalism accelerates uptake despite bandwidth constraints compared to wired alternatives. Battery-powered portable units dominate outdoor and temporary deployment scenarios.
- Bluetooth:Short-range 2.4 GHz protocol standardized by the Bluetooth Special Interest Group supports point-to-point and broadcast audio with codec-dependent quality from SBC to aptX Lossless. South Korean mobile-first consumers treat Bluetooth as default connectivity for personal audio, with LE Audio specifications expanding multicast applications. Codec fragmentation creates compatibility verification burdens for manufacturers.
- Wi-Fi:IEEE 802.11-based transmission leverages existing infrastructure for whole-home coverage with 802.11ax and 6E variants expanding into 6 GHz spectrum. Wi-Fi enables high-resolution streaming without compression artifacts.
- Ethernet:Cabled IEEE 802.3 connectivity delivers guaranteed bandwidth and sub-millisecond latency for professional installations where synchronization across zones is mandatory. Dante and AVB protocols dominate commercial specification.
Wireless captures consumer volume; Ethernet commands professional margins.
End User:
Budget authority and technical staffing levels separate segments with fundamentally different procurement processes.
- Residential:Individual consumers and household decision-makers purchasing entertainment systems for private dwellings, with project scale ranging from single-room soundbars to whole-property distributed audio. Germany's renovation wave in existing housing stock creates replacement demand as owners modernize inherited installations. Streaming service integration now outweighs physical source compatibility in purchase criteria.
- Commercial:Hospitality operators, retail chains, and venue managers deploying centralized audio management for ambient music, paging, and event reinforcement. Hotel retrofit cycles in Germany accelerate as operators reduce on-site technical staffing through IP-based remote monitoring. Revenue per available room metrics now include guest satisfaction scores tied to audio environment quality.
- Educational:School districts and university facilities requiring campus-wide distribution with emergency notification override capabilities. Budget constraints favor phased deployment with future expansion provisions.
- Corporate:Enterprise IT departments standardizing conferencing infrastructure across distributed offices with vendor consolidation mandates. Procurement runs through centralized IT rather than facilities management.
Residential dominates revenue pools; Commercial shows steepest expansion trajectory.
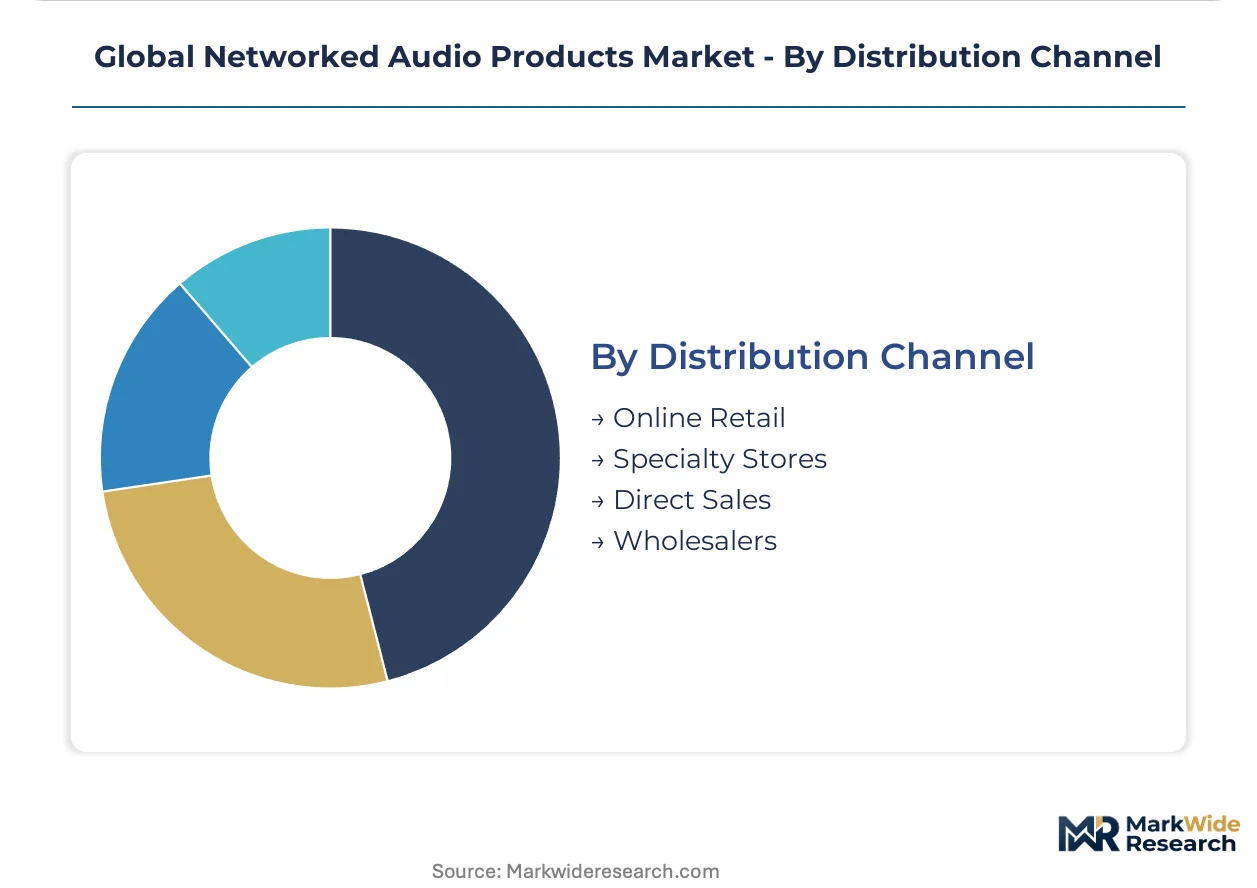
Distribution Channel:
Channel selection reflects project complexity and buyer technical sophistication rather than geographic convenience.
- Online Retail:E-commerce platforms including Amazon, manufacturer direct storefronts, and specialized audio retailers enable self-directed research and comparison purchasing. United States consumers increasingly complete entire speaker system purchases without physical audition, relying on return policies and review aggregation. Financing integration reduces purchase friction for bundled ecosystem transactions.
- Specialty Stores:Brick-and-mortar dealers with demonstration facilities and trained staff serve audiophile segments where subjective listening evaluation remains decisive. South Korea's high-rise retail clusters concentrate premium brand presence with personalized consultation.
- Direct Sales:Manufacturer-controlled channels bypass intermediary margin capture for enterprise and institutional contracts with custom configuration requirements. Specification loyalty programs reward repeat integrator engagement.
- Wholesalers:Distribution intermediaries serving contractor and installer networks with bulk pricing and staging logistics for large-scale deployment projects. Inventory financing supports project-based cash flow timing.
Online Retail leads transaction volume; Direct Sales captures specification margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabrication capacity supplies transducers and wireless SoCs to residential installers in North America and Europe, while consumption concentrates in affluent metropolitan zones with premium housing stock and smart home penetration.
United States
Whole-home audio specification in residential developments above 4,000 square feet drives bundled ecosystem purchases over standalone speakers. The FCC governs 6 GHz spectrum access for Wi-Fi 6E devices under ongoing rulemaking proceedings. Southern California's technology corridor hosts integrator networks serving entertainment industry professionals.
Germany
Hotel operators retrofit properties with IP-based centralized audio management to reduce on-site technical staffing. ECHA enforces REACH substance restrictions on flame retardants in electronics enclosures. Bavaria's industrial automation clusters supply precision transducer components to European audio manufacturers.
South Korea
High-rise multi-dwelling unit developments create bulk purchasing opportunities for centralized infrastructure installations. MFDS certification requirements apply to networked devices with biometric-responsive wellness features. Seoul Capital Area's dense urban fabric accelerates demand for space-efficient wireless audio solutions.
China
Domestic smart speaker volume scales through ecosystem integration with super-app platforms. MIIT certifies wireless audio equipment through compulsory GB standards governing electromagnetic compatibility. Shenzhen's electronics manufacturing base controls global supply of Bluetooth and Wi-Fi SoC modules.
Japan
Corporate conferencing infrastructure replacement cycles sustain demand for beamforming microphone arrays. METI coordinates industrial standards for spatial audio rendering in automotive applications. Kansai region's precision engineering heritage supports high-fidelity transducer development for premium residential segments.
Global Networked Audio Products Market Competitive Environment
The competitive structure tilts toward ecosystem-integrated hardware vendors with captive software platforms. Incumbents defend position through proprietary mesh networking protocols and streaming service bundling rather than acoustic engineering alone. Two strategic archetypes dominate: consumer electronics conglomerates leveraging display-centric convergence, and audio-specialist firms emphasizing spatial algorithm differentiation. M&A activity concentrates on software-defined audio processing startups, while capacity expansion targets Southeast Asian final assembly for cost-sensitive product lines.
Among ecosystem-integrated vendors, Sonos exemplifies the premium residential archetype through expandable multi-room installations. Samsung Electronics anchors the display-audio convergence strategy via SmartThings platform integration. Bose Corporation occupies the high-fidelity specialist position, differentiating through acoustic engineering heritage and proprietary spatial rendering algorithms. Each represents a distinct competitive vector rather than direct substitution.
| Leading Market Players |
|---|
| Sonos |
| Samsung Electronics |
| Sony Group Corporation |
| Logitech |
| Yamaha |
| Denon |
| Bose Corporation |
| Roku |
| QSC |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between Matter-certified ecosystems and legacy proprietary stacks bifurcates both margin structures and supplier qualification requirements. Premium residential installers command project-based pricing for interoperable multi-room deployments, while commodity Bluetooth peripherals compete on spot-market component costs with Shenzhen-sourced modules.
Pricing Analysis
Margin tightening in wireless speaker tiers reflects codec licensing burdens and Wi-Fi 6E chipset premiums. Three-tier pricing structure across premium, standard, and economy levels separates Dante-enabled commercial installations from mass-market consumer hardware. Cost-down pressure on entry-level SKUs accelerates because South Korean ODMs are absorbing royalty stacking for LE Audio implementations. Corporate IT buyers exhibit lowest price sensitivity due to vendor consolidation mandates, while rental housing developers in multi-dwelling units drive hardest bargain through bulk procurement economics.
Supply Chain Analysis
Dual-sourcing requirements from German automotive and hospitality integrators mandate qualified secondary suppliers for MEMS microphones and Class D amplifier modules. Component fabrication concentrates in Taiwan for Wi-Fi SoCs, South Korea for NAND memory, and China for transducer magnets and enclosure plastics. Raw material dependencies span neodymium for driver motors, FR-4 substrates for PCBs, and lithium-ion cells for portable units. Single-source vulnerability sits with TSMC's 7nm capacity for flagship DSP chips. Distribution runs through Shenzhen electronics marts for white-label procurement and regional AV integrator networks for specification-driven commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protocol convergence around Matter certification is consolidating vendor tiers, forcing acquisition strategies among mid-tier players lacking interoperability credentials.
For Market Incumbents: Acquire spatial audio algorithm portfolios to differentiate as hardware margins compress. Sonos and Bose already anchor premium positioning through proprietary mesh and acoustic engineering heritage; laggards must secure DSP talent in Bavaria's industrial clusters or Kansai precision engineering regions. Matter certification backlog at CSA-authorized labs threatens time-to-market for secondary brands, favoring incumbents with existing interoperability credentials. Channel control through direct-to-installer programs captures specification loyalty in high-value residential developments above 4,000 square feet. For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for flame-retardant-free enclosure designs that incumbent supply chains cannot pivot toward rapidly. South Korea's high-rise multi-dwelling unit segment presents the most penetrable geography, with centralized infrastructure decisions bypassing fragmented consumer retail. Wellness-adjacent biometric-responsive soundscapes for sleep and focus applications offer white-space positioning outside entertainment-saturated residential markets. Go-to-market execution should route through AV consultants and custom integrators rather than competing for Amazon search placement against established ecosystems. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined audio processing specialists given automotive cabin spatial audio adoption by Japanese OEMs. Long-term viability over the next decade hinges on algorithmic personalization capabilities rather than transducer manufacturing scale. Target acquisition archetype: DSP startups with head-related transfer function processing IP and automotive qualification timelines. Signal to watch: METI coordination of spatial audio standards for vehicle applications as inflection indicator for tier-1 supplier integration mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | CSA interoperability credentials unlock specification in whole-home residential projects across United States premium developments. |
| Spatial Audio Algorithm Acquisition | Head-related transfer function IP separates premium tier from commodity Bluetooth speaker competition in streaming service bundles. |
| Automotive Cabin Integration | METI standards coordination in Japan creates tier-1 supplier qualification pathway for adaptive rendering algorithms. |
| Direct-to-Installer Channel Development | Bypassing retail margin capture builds specification loyalty among custom integrators serving entertainment industry professionals. |
| Wellness Application Expansion | Biometric-responsive soundscapes extend addressable market beyond entertainment into health-adjacent verticals with MFDS certification requirements. |
Study Parameters
Document review covered FCC spectrum allocation proceedings, ECHA REACH substance restriction updates, and MIIT GB standard certifications, complemented by interviews with smart home platform engineers, commercial AV integrators, hospitality technology procurement officers, and semiconductor supply chain managers. Secondary validation drew from SEC filings of listed audio hardware vendors, Connectivity Standards Alliance certification databases, and customs records of transducer component trade flows. Bottom-up unit economics modeling triangulated against top-down market sizing from regional smart home penetration surveys.
Output projections reflect segment-level modeling across product type, transmission technology, end-user budget authority, and distribution channel sophistication dimensions. CAGRs derive from installation base growth rates, replacement cycle compression, and protocol transition timing assumptions. Industry-specific inputs include Wi-Fi 6E chipset availability forecasts, Matter certification queue durations at authorized laboratories, and hospitality retrofit cycle data from German hotel operator associations.
The model assumes a particular technology adoption path; alternative pathways for Bluetooth LE Audio multicast or proprietary mesh persistence would alter the outlook for interoperability-premium pricing. Deviation in FCC 6 GHz band rulemaking timelines or TSMC foundry capacity allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Gaming Headsets and Gaming Headphones Market
Audio Equipment
Global Audio Devices and Components Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Radio Headset Market
Audio Equipment
Mixing Console Market
Audio Equipment
India Gaming Headset Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Hi-Fi Cartridges Market
Audio Equipment
Professional Microphones Market
Audio Equipment
Global Wireless Audio Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Audio Interface Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Guitar Head Amplifiers Market
Audio Equipment
Wireless Audio Devices Market