
 United States Gaming Headsets Market | 2026-2036
United States Gaming Headsets Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gaming Headsets Market Insights
China is tilting its electronics manufacturing capacity toward gaming peripherals, creating ripple effects across component sourcing for US-bound headset brands. Logitech International S.A. leverages its Swiss-American engineering footprint to sustain dual-continent development pipelines. Razer Inc. anchors its brand identity in RGB-integrated industrial design that resonates with younger demographics. Turtle Beach Corporation specializes in console-optimized audio profiles that dominate living-room gaming setups.
A gaming headset constitutes an audio reproduction device engineered for interactive entertainment, combining circumaural or supra-aural transducers with a unidirectional or bidirectional microphone array and impedance ratings typically between 16 and 50 ohms for direct controller or motherboard drive. Its primary commercial purpose centers on delivering positional audio cues, voice communication clarity, and acoustic isolation that competitive and cooperative gameplay demands. Wireless headsets command the fastest expansion within the product type dimension as latency compression algorithms close the performance gap with wired alternatives. Professional gamers and esports teams within the end-user dimension concentrate margin pools through sponsorship-driven bulk procurement and customized tuning requirements. The technology dimension sees noise cancelling and surround sound configurations pulling premium pricing as streamers prioritize broadcast-grade audio separation.
The FCC governs radio frequency emissions for wireless gaming headsets operating in the 2.4 GHz and 5 GHz bands, while OSHA guidelines on occupational noise exposure influence headset volume-limiting firmware in commercial gaming venues. California's SB 327 IoT security legislation shapes firmware update requirements for Bluetooth-connected devices sold in the state. Stakeholders must monitor how state-level right-to-repair bills reshape warranty structures and aftermarket accessory ecosystems.
Market Dynamics
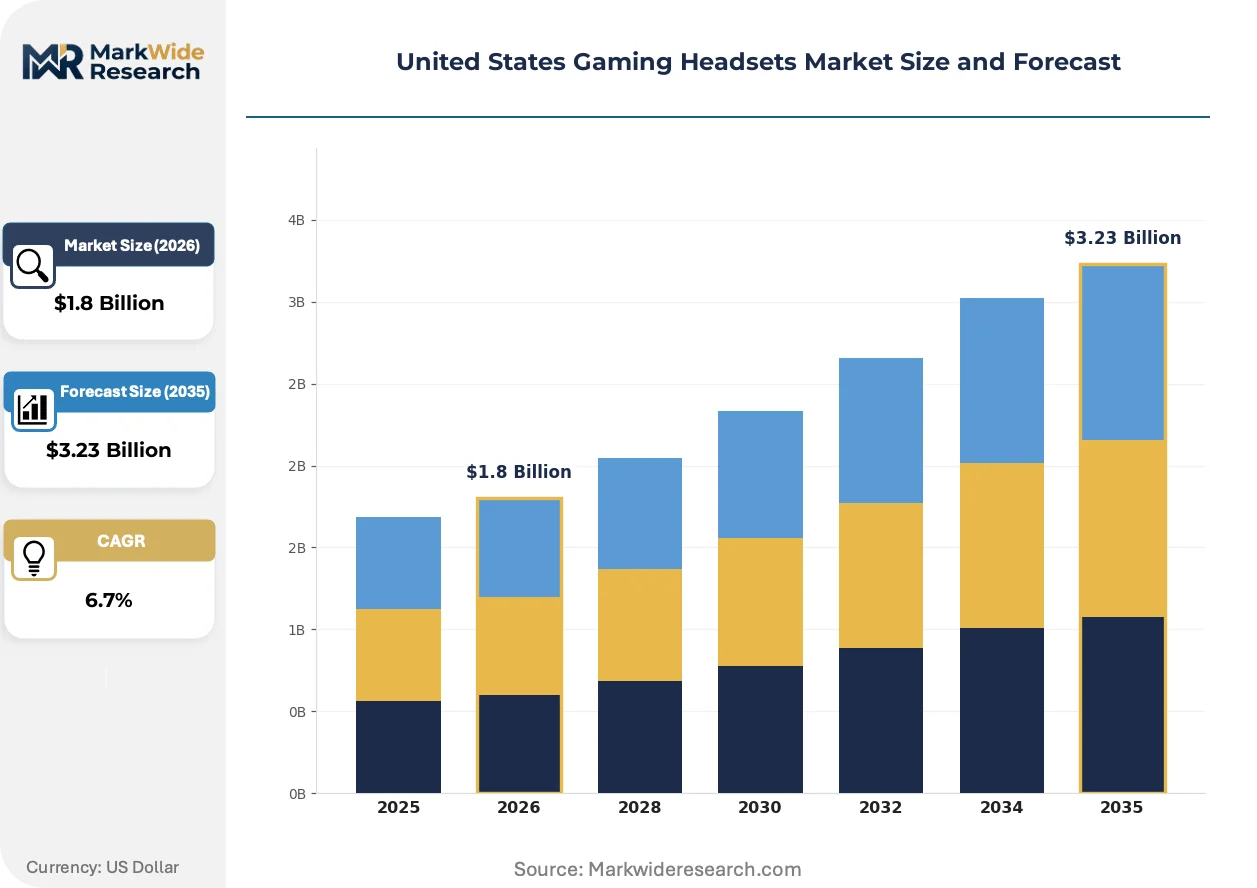
Spatial audio processing and low-latency wireless protocols are compressing product development cycles while pulling casual gamers toward premium equipment tiers. California's esports training complexes and Texas-based streaming creator studios concentrate demand pull, reshaping how manufacturers allocate R&D and inventory.
Growth Catalysts
- OSHA Guidelines:Federal occupational noise exposure standards drive volume-limiting firmware adoption in commercial gaming venues, expanding enterprise procurement pools.
- Live-Streaming Platforms:Broadcast-grade audio separation requirements pull streamers toward noise cancelling and surround sound configurations.
- California SB 327:State IoT security legislation mandates firmware update capabilities for Bluetooth-connected devices, accelerating product refresh cycles.
Market Restraints
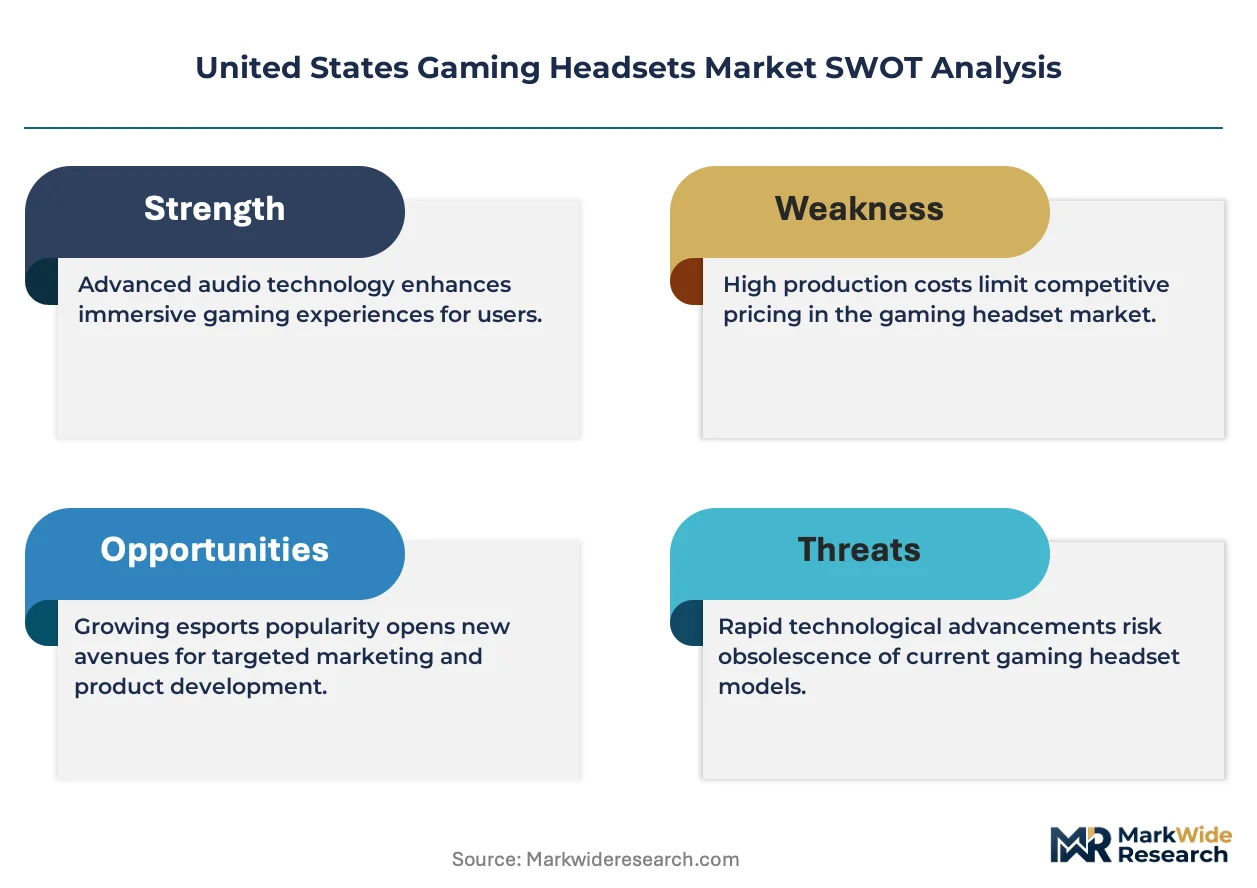
- Component Sourcing Concentration:China's electronics manufacturing capacity tilts toward gaming peripherals, creating single-source dependencies for US-bound brands.
- Radio Frequency Licensing:FCC emissions governance for 2.4 GHz and 5 GHz bands adds compliance friction and extends certification timelines.
- Right-to-Repair Bills:State-level warranty restructuring threats complicate aftermarket accessory ecosystem planning.
Strategic Opportunities
- Console-Optimized Audio Profiles:Living-room gaming setups remain underpenetrated for premium wireless configurations outside competitive multiplayer segments.
- RGB-Integrated Industrial Design:Younger demographic preferences for aesthetic differentiation create white space beyond pure audio performance.
- Esports Sponsorship Procurement:Professional team bulk purchasing and customized tuning requirements concentrate margin pools for vendors with direct B2B capabilities.
Industry Challenges
- Latency Compression Talent:Wireless protocol engineering expertise scarcity constrains roadmap execution speed for mid-tier manufacturers.
- Multi-Standard Certification:Simultaneous FCC, Bluetooth SIG, and state-level IoT compliance creates timeline fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gaming Headsets Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired Headsets, Wireless Headsets, Over-Ear Headsets, In-Ear Headsets End User: Casual Gamers, Professional Gamers, Streamers, eSports Teams Technology: Bluetooth, USB-C, Surround Sound, Noise Cancelling Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Logitech International S.A., Razer Inc., Corsair Gaming, Sony Interactive Entertainment, HyperX, Turtle Beach Corporation, SteelSeries, ASUS, Microsoft Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gaming Headsets Market Trends and Innovations
Audio reproduction architectures are converging with broadcast and telecommunication standards, forcing headset manufacturers to serve dual-use cases. This convergence compresses differentiation windows while elevating firmware and DSP capabilities as primary competitive moats.
Beamforming microphone arrays is hybridizing acoustic capture and noise suppression functions into single-chip solutions. Esports teams and streaming studios in California are adopting these configurations at compressed refresh cycles. The technology is hybridizing voice clarity benchmarks with broadcast separation standards, collapsing the historical gap between gaming and professional audio tiers.
California's SB 327 IoT security legislation mandates encrypted firmware update channels for all Bluetooth-connected devices sold in the state. Manufacturers must re-architect over-the-air delivery pipelines to satisfy state-specific requirements. Texas-based creator studios and national retail distributors are prioritizing compliant SKUs, tilting procurement toward vendors with established cybersecurity infrastructure.
Buying committees in commercial gaming venues now unbundle hardware procurement from ongoing firmware support contracts. Facility operators in Nevada and Illinois are negotiating multi-year service agreements separate from initial equipment purchases. This pattern concentrates purchasing power with national venue chains while fragmenting vendor relationships across installation and maintenance phases.
United States Gaming Headsets Market Segmentation
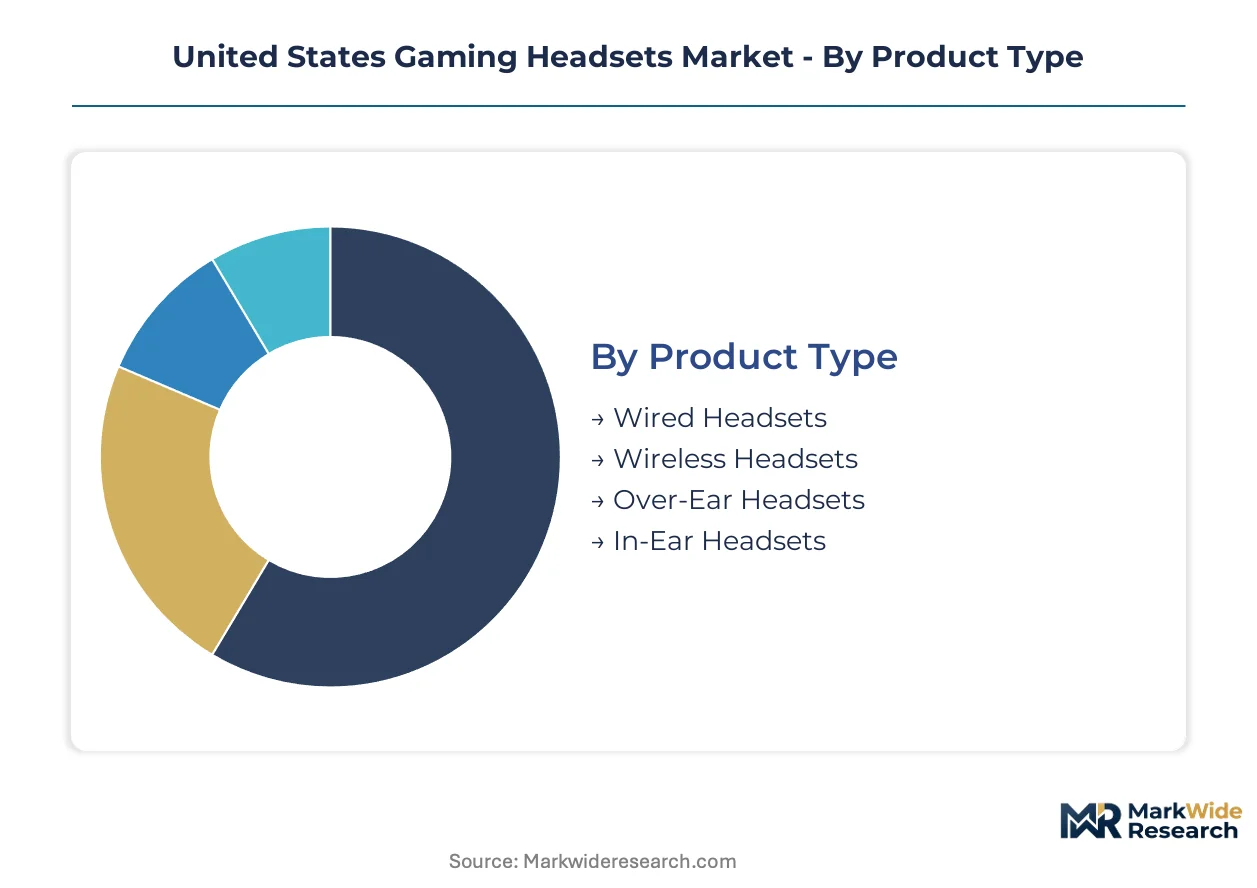
Gaming headset segmentation in the United States reflects divergent user workflows across competitive, casual, and broadcast environments. Each dimension—product form factor, user archetype, connectivity protocol, and price positioning—carries distinct procurement patterns and margin structures that manufacturers must navigate simultaneously.
Product Type:
Use-case spectrum spans tethered competitive play, unrestricted living-room gaming, immersive isolation, and portable mobile sessions.
- Wireless Headsets:Radio-frequency transmission architectures operating in FCC-governed 2.4 GHz and 5 GHz bands with sub-20ms latency compression. Demand concentrates in Texas-based streaming creator studios where cable-free movement during broadcast sessions is non-negotiable. Latency algorithm refinement remains the primary engineering constraint.
- Over-Ear Headsets:Circumaural acoustic isolation designs with 40-50mm dynamic drivers and closed-back enclosures for positional audio cue separation. California's esports training complexes drive procurement volume for tournament-grade soundstage precision. Weight distribution and clamping force optimization dominate industrial design tradeoffs.
- Wired Headsets:Analog or USB-connected configurations with direct controller or motherboard drive eliminating battery dependency. Tournament organizers in Nevada specify these for zero-latency reliability in prize-pool competitions.
- In-Ear Headsets:Supra-aural or canal-fit transducers with inline microphone arrays for mobile and handheld console gaming. Younger demographics in Florida and Georgia adopt these for commute-integrated play sessions.
Established volume favors Over-Ear Headsets; emerging adoption favors Wireless Headsets.
End User:
Customer archetypes range from price-sensitive occasional players to sponsorship-funded professional organizations with customized tuning requirements.
- Professional Gamers:Individuals deriving primary income from tournament prize pools and streaming revenue, requiring broadcast-grade microphone clarity and fatigue-resistant wear profiles. Esports training complexes in California negotiate bulk procurement with custom EQ tuning for specific game titles.
- eSports Teams:Organized competitive organizations with sponsorship-driven equipment standardization and logo-placement requirements. National venue chains in Illinois and Nevada specify uniform headset configurations across roster members for brand consistency.
- Casual Gamers:Recreational players prioritizing comfort and multi-device compatibility over specialized performance metrics. Suburban households in Texas and Ohio represent the volume base for retail channel distribution.
- Streamers:Content creators requiring acoustic separation between game audio and voice capture for audience clarity. Individual creator studios in Austin and Los Angeles drive demand for noise cancelling configurations with RGB visual integration.
Procurement concentration sits with eSports Teams; fastest expansion trajectory belongs to Streamers.
Technology:
Connectivity and audio processing standards determine compatibility matrices and firmware certification burdens across state jurisdictions.
- Surround Sound:Multi-channel virtualization through Dolby Atmos or proprietary DSP algorithms delivering positional audio cues in competitive first-person titles. California SB 327 compliance requirements add firmware encryption overhead to these processing-intensive configurations.
- Noise Cancelling:Hybrid active noise reduction combining feedforward and feedback microphones with real-time DSP inversion. Streamers in Texas creator studios adopt these for broadcast-grade acoustic isolation from HVAC and urban ambient intrusion.
- Bluetooth:Wireless protocol operating in 2.4 GHz ISM band with standardized pairing profiles for cross-device mobility. California's IoT security legislation mandates encrypted firmware update channels, tilting procurement toward vendors with established cybersecurity infrastructure.
- USB-C:Digital audio and power delivery through reversible connector standard with native compatibility across modern consoles and mobile devices. Tournament organizers prefer these for standardized connectivity eliminating adapter friction.
Technical complexity clusters in Surround Sound; regulatory tailwinds accelerate Bluetooth refresh cycles.
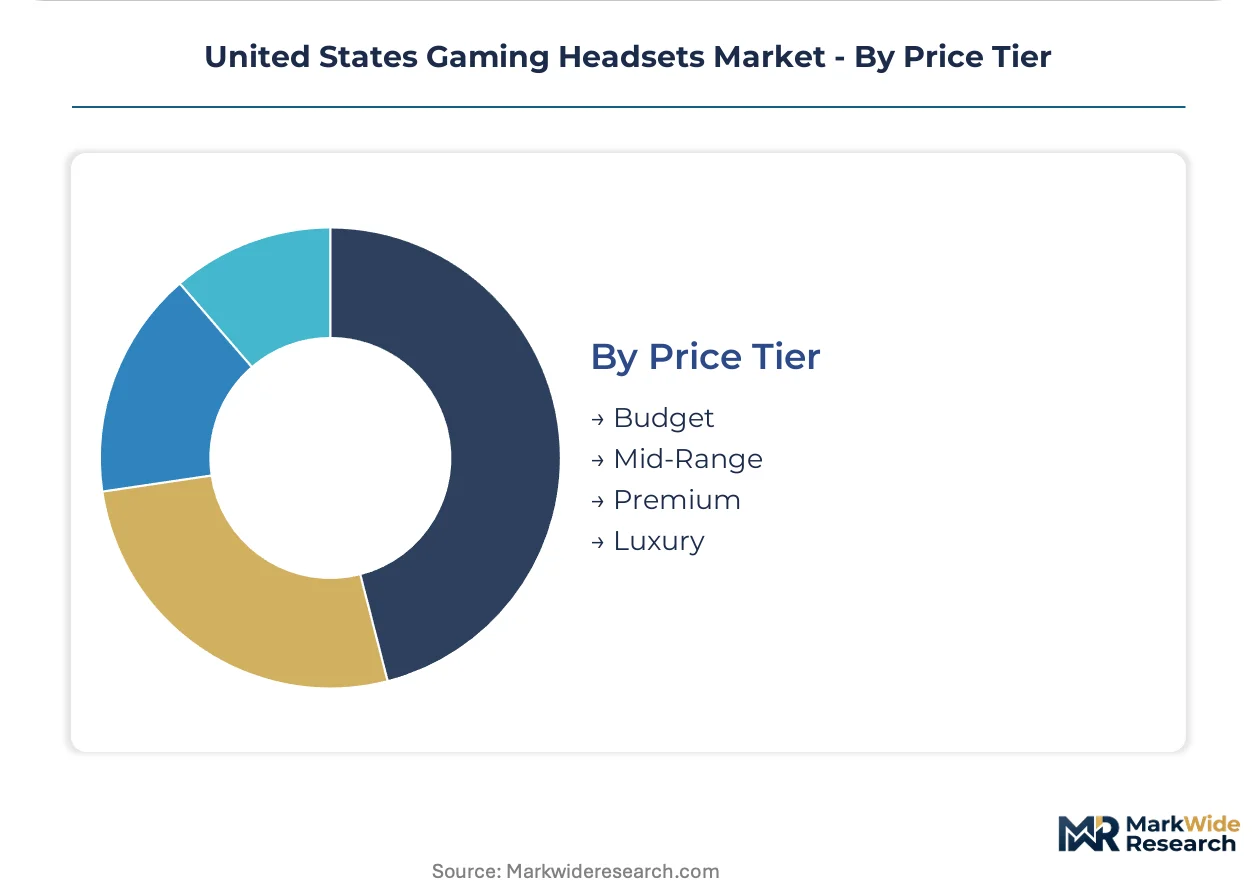
Price Tier:
Cost stratification aligns with performance tiering, brand premium extraction, and sponsorship subsidy models.
- Premium:Positioning above mass-market with dedicated DAC/amp integration, replaceable earpads, and extended warranty terms. Professional gamers and esports teams concentrate margin capture here through sponsorship-offset procurement.
- Mid-Range:Balanced feature sets with wireless connectivity and basic surround virtualization without broadcast-grade microphone arrays. Casual gamers in suburban markets drive volume through retail channel promotions.
- Budget:Entry-level wired configurations with plastic construction and fixed microphones for price-sensitive occasional use. Big-box retailers in Ohio and Pennsylvania use these as traffic drivers during holiday purchasing windows.
- Luxury:Ultra-premium positioning with exotic materials, limited edition collaborations, and concierge support services. Collector segments in California and New York sustain niche volume for status-signaling configurations.
Revenue concentration pools in Premium; volume expansion favors Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors California's position as the primary entry node for gaming peripherals, handling containerized electronics from Asian manufacturing hubs. Interstate 35 and Union Pacific rail corridors connect Texas distribution centers to coastal ports. These infrastructure assets concentrate headset inventory flows through West Coast and Southwest logistics nodes.
California
Esports training complexes in Los Angeles and Irvine drive enterprise-grade headset procurement with custom EQ tuning requirements. SB 327 mandates encrypted firmware update channels for all Bluetooth-connected devices sold statewide. Silicon Valley cybersecurity vendors supply compliance infrastructure to headset manufacturers seeking California market access.
Texas
Streaming creator studios in Austin and Dallas concentrate demand for wireless configurations with RGB visual integration. OSHA guidelines on occupational noise exposure influence volume-limiting firmware in commercial gaming venues across Houston and San Antonio. Dallas-Fort Worth distribution hubs serve as the primary inland consolidation point for retail channel fulfillment.
Illinois
National venue chains in Chicago negotiate multi-year service agreements separate from initial hardware purchases. The state's central location enables overnight ground shipping coverage to 80 percent of the continental population. Rockford and Peoria logistics parks host third-party fulfillment operations for direct-to-consumer headset brands.
Nevada
Tournament organizers in Las Vegas specify wired headset configurations for zero-latency reliability in prize-pool competitions. Nevada Gaming Commission regulations on electronic equipment certification create parallel compliance pathways for venue-deployed audio hardware. Reno distribution centers support West Coast e-commerce fulfillment with reduced last-mile costs.
New York
Collector segments in New York City sustain niche volume for luxury-tier limited edition collaborations. Metropolitan area retail density supports flagship showroom concepts for premium brand positioning. Buffalo and Albany serve as secondary distribution nodes for Northeast corridor market coverage.
United States Gaming Headsets Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in driver and transducer fabrication. The vendor base stratifies across three tiers: multinational peripherals conglomerates with cross-category R&D scale, gaming-native brands with esports sponsorship infrastructure, and audio heritage houses adapting broadcast technology for interactive entertainment. Dominant competitive moves include sponsorship-driven bulk procurement contracts and firmware-as-a-service monetization of over-the-air update channels.
Among Swiss-American engineering conglomerates, Logitech International S.A. occupies a position exemplifying dual-continent development pipeline architecture. Within the gaming-native tier, Razer Inc. and Turtle Beach Corporation represent contrasting archetypes: one anchored in RGB-integrated industrial design for younger demographics, the other specializing in console-optimized audio profiles for living-room deployment. These three entities collectively illustrate the competitive spectrum from component integration to platform-specific tuning.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Razer Inc. |
| Corsair Gaming |
| Sony Interactive Entertainment |
| HyperX |
| Turtle Beach Corporation |
| SteelSeries |
| ASUS |
| Microsoft Corporation |
| Others |
Pricing and Supply Chain Analysis
Interstate 35 freight corridors connecting Texas distribution hubs to West Coast ports impose differential logistics costs that amplify pricing power for coastal manufacturers while compressing margins for inland-assembled SKUs, creating geographic price stratification that overlays performance-tier differentiation.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement by esports training complexes from individual retail purchases, with sponsorship-bundled B2B contracts commanding 40-60 unit minimums. Price differentiation rests on firmware customization depth and California SB 327 compliance certification. Cost compression in mid-range wireless configurations is intensifying because Bluetooth SIG certification timelines extend vendor operating cycles. Casual gamers in suburban Texas and Ohio markets exhibit highest price sensitivity, while professional esports teams with sponsorship offset show lowest.
Supply Chain Analysis
Contract-manufacturing concentration sits with Foxconn, Pegatron, and Quanta Computer facilities across Dongguan and Shenzhen, with secondary capacity in Vietnam and Mexico. Component sourcing draws from rare-earth magnet suppliers in Inner Mongolia, DSP chip foundries in Taiwan, and lithium-polymer cell producers in South Korea. Single-source vulnerability concentrates in 2.4 GHz RF module supply. Distribution runs through Long Beach port entry, Union Pacific rail to Dallas-Fort Worth, and regional parcel networks to retail and direct-to-consumer endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through national venue chain consolidation in Illinois and Nevada, where multi-year service unbundling shifts procurement leverage toward facility operators with standardized specification authority.
For Market Incumbents: Pre-empt firmware-as-a-service monetization by esports-native entrants through accelerated over-the-air update infrastructure deployment. Secure exclusive sponsorship procurement contracts with California training complexes before custom EQ tuning becomes commoditized. Vertical integration into beamforming microphone array silicon reduces exposure to fabless audio DSP vendor acquisition by platform integrators.
For New Entrants and Emerging Players: Build out RGB-integrated industrial design capabilities targeting Texas creator studios where aesthetic differentiation commands premium positioning outside pure audio performance benchmarks. White space exists in console-optimized wireless configurations for living-room deployment outside competitive multiplayer segments. Direct-to-streamer subscription models with hardware refresh cycles align with Austin and Los Angeles creator economy procurement patterns.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational audio heritage houses with broadcast technology IP and underutilized gaming peripheral adaptation pipelines. Long-term viability hinges on firmware architecture ownership rather than transducer fabrication scale. Signal to watch is FCC certification backlog duration as proxy for regulatory friction favoring established cybersecurity infrastructure holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-as-a-Service Monetization | Over-the-air update channels generate recurring revenue from California SB 327 compliance mandates. |
| Esports Sponsorship Procurement | Bulk B2B contracts with Illinois and Nevada venue chains concentrate margin pools and brand standardization. |
| Beamforming Microphone Integration | Single-chip acoustic capture solutions collapse the gap between gaming and broadcast audio tiers. |
| RGB Industrial Design Differentiation | Visual aesthetic capabilities capture younger demographic segments in Texas creator economy clusters. |
| Console-Optimized Wireless Expansion | Living-room gaming setups remain underpenetrated for premium configurations beyond competitive multiplayer. |
Research Methodology
Desk research of FCC equipment authorization databases, OSHA technical guidance documents, and California SB 327 legislative filings preceded structured interviews with esports training complex procurement directors, streaming studio technical leads, retail category buyers, and firmware engineering directors. Secondary validation drew from Bluetooth SIG certification records, customs import manifests through Port of Long Beach, and venue chain service agreement disclosures. Bottom-up unit shipment estimates triangulated against top-down consumer electronics expenditure benchmarks.
Assumption sets held fixed the continuation of California IoT security legislation without federal preemption, stable FCC 2.4 GHz and 5 GHz band allocation, and sustained esports tournament prize pool growth across the projection horizon. Segmentation dimensions modeled include product form factor, end-user archetype, connectivity protocol, and price positioning tier. CAGRs derived from logistic adoption curves fitted to historical wireless headset penetration patterns, with latency compression algorithm advancement rates and RGB feature adoption velocity as gaming-specific forecast inputs.
Stress conditions across tariff exposure on Chinese-manufactured RF modules, right-to-repair bill passage in additional states, and streaming platform monetization policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions subject to revision from regulatory, technological, or demand-side disruptions. Quarterly review of FCC certification queue depths, esports sponsorship contract announcement velocity, and California firmware compliance audit outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Clip-On Headphones Market
Audio Equipment
Smart Audio System Market
Audio Equipment
Electronic Drums Market
Audio Equipment
Asia-Pacific Wireless Audio Market
Audio Equipment
Audio Equipment Market
Audio Equipment
Portable Audio Amplifier Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Professional Audio-Visual Systems Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
Amps & Effects Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Consumer Audio Market
Audio Equipment
Car Audio Market
Audio Equipment
Radio Headset Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Audio Kits Market