
 Saudi Arabia Event Management Market | 2026-2036
Saudi Arabia Event Management Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Event Management Market Insights
Government agencies are unwinding their historical dominance over event procurement as private corporations and high-net-worth individuals command larger shares of contracted event spend. MDLBEAST leverages its music festival infrastructure to anchor electronic entertainment culture across the Kingdom. SEVEN competes through giga-project entertainment venue development tied to Vision 2030 objectives. Live Nation Middle East positions its international artist network to capture inbound concert touring demand.
Event management encompasses the strategic planning, logistics coordination, vendor sourcing, and on-site execution required to deliver structured gatherings ranging from intimate corporate retreats to stadium-scale productions involving crowd engineering above ten thousand attendees. The discipline integrates audio-visual production systems, digital ticketing infrastructure, and real-time guest communication platforms to ensure seamless stakeholder experiences. Corporate Events and Mega Events command the deepest margin pools as government and multinational budgets sustain premium service tiers, while Weddings represents the most fragmented segment with dispersed family-based procurement. Technology Used segments show Event Apps and Virtual Platforms capturing growing share as hybrid attendance models normalize post-pandemic operational standards.
SFDA and MOHAP frameworks govern food safety, crowd density, and emergency medical preparedness at large-scale gatherings, with compliance costs rising for operators serving events above five thousand attendees. Giga-project developers must navigate SAGIA investment licensing and municipal permitting across Riyadh, Jeddah, and NEOM jurisdictions, creating uneven market access timelines. Stakeholders must monitor how Vision 2030 entertainment target revisions and municipal capacity expansion timelines reshape venue availability and pricing power across the Kingdom's three primary event corridors.
Market Dynamics
The concentration of giga-project development across Riyadh, Jeddah, and the Red Sea coast is compressing venue construction timelines while SFDA and MOHAP compliance mandates escalate operational overhead for large-scale gatherings.
Growth Catalysts
- Vision 2030 Entertainment Targets:Government-mandated tourism and leisure sector expansion is channeling sovereign capital into mega-event infrastructure across the Kingdom's three primary urban corridors.
- SFDA Food Safety Modernization:Standardized large-scale catering protocols are professionalizing vendor ecosystems and disqualifying informal operators from government and corporate procurement pools.
- Hybrid Event Technology Stack:Integrated virtual platform deployment is extending audience reach beyond physical venue constraints and creating recurring revenue attachments for event operators.
Market Restraints
- Technical Talent Scarcity:Certified crowd engineering and advanced audio-visual production expertise concentrates in Riyadh and Jeddah, leaving secondary cities dependent on fly-in specialists at premium cost.
- Regulatory Friction:SAGIA investment licensing and municipal permitting operate on divergent timelines across Riyadh, Jeddah, and NEOM jurisdictions, delaying venue activation schedules.
- Input Cost Volatility:Imported staging equipment and temporary structure materials face freight rate fluctuations and customs clearance variability at Saudi ports.
Strategic Opportunities
- Red Sea Coast Corridor:NEOM and AMAALA giga-projects are activating previously undeveloped territory for ultra-premium experiential programming with limited incumbent competition.
- MOHAP Safety Certification:Voluntary emergency medical preparedness accreditation is becoming a de facto bid requirement for government and multinational contracts, creating service bundling potential.
- Corporate In-House Capability:Multinational subsidiaries are building captive event teams rather than outsourcing, opening training and technology licensing channels for established operators.
Industry Challenges
- Certification Timeline Compression:SFDA food handler permits and MOHAP crowd safety credentials require renewal cycles that conflict with seasonal event staffing surges.
- Legacy System Integration:Established operators maintaining on-premise ticketing and guest management infrastructure face friction migrating to cloud-native hybrid event platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Event Management Market |
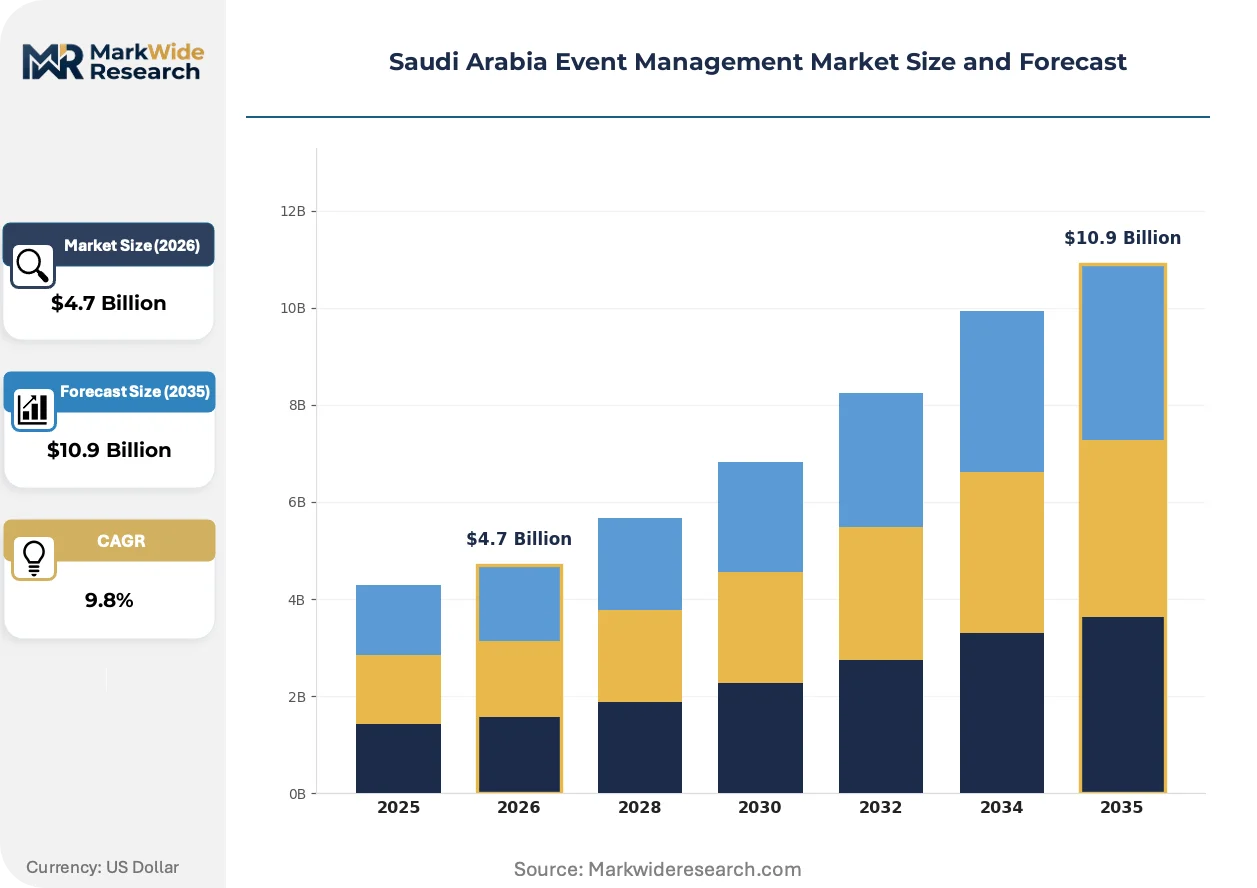
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $10.9 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Events, Weddings, Concerts, Exhibitions Client Type: Private Individuals, Corporations, NGOs, Government Agencies Event Size: Small Scale, Medium Scale, Large Scale, Mega Events Technology Used: Event Apps, Virtual Platforms, Audio-Visual Production, Ticketing Systems |
| Companies Covered | Saudi Entertainment Ventures (SEVEN), MDLBEAST, SELA, Rotana Live, Live Nation Middle East, Benchmark, Eventive, Tahaluf, TicketMX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Event Management Market Trends and Innovations
Event delivery models across Saudi Arabia are fragmenting between immersive physical spectacle and distributed digital participation, with regulatory frameworks and procurement preferences racing to catch operational reality.
Immersive extended reality production systems are bifurcating the corporate events segment. Multinational headquarters in Riyadh and Jeddah are deploying AR-enabled product launches and virtual venue twins at accelerating frequency. This technology compression is collapsing the distinction between physical attendance and remote participation, forcing venue operators to renegotiate space licensing models.
MOHAP crowd density and emergency medical preparedness protocols are tightening enforcement thresholds for gatherings exceeding five thousand attendees. Event operators now face mandatory on-site ambulance deployment and certified medical director presence. The mega-events segment bears the heaviest compliance burden, with several Riyadh stadium productions adjusting floor plans to reduce peak density metrics.
Corporate procurement departments are consolidating vendor rosters and demanding outcome-based event metrics rather than input-based billing. Preferred supplier agreements now tie payment release to attendee engagement scores and lead generation verification. This shift is most visible among technology and pharmaceutical multinationals operating across the Kingdom's three primary business districts.
Saudi Arabia Event Management Market Segmentation
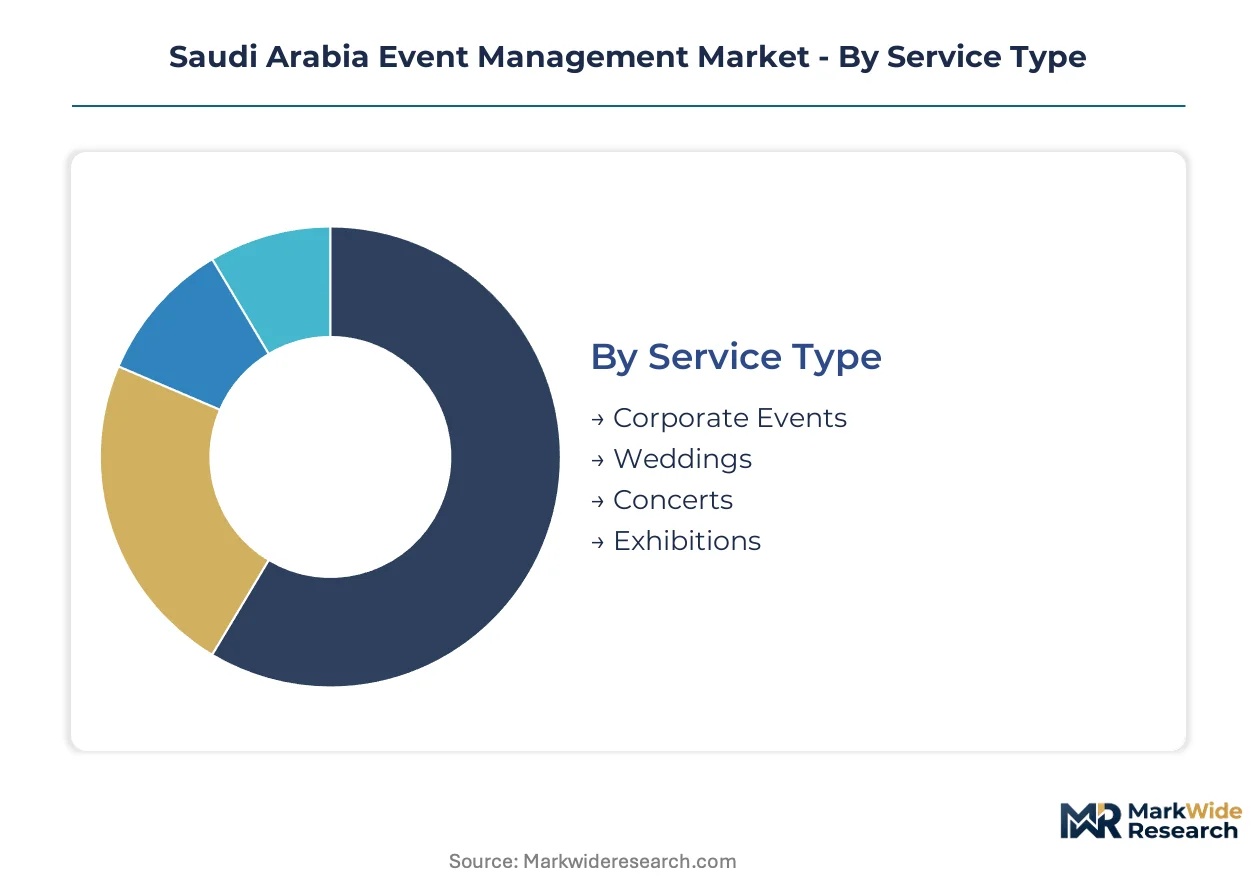
Saudi Arabia's event management market fragments across service specializations that face divergent substitution pressures from digital alternatives and captive in-house capabilities. Understanding segment-level dynamics reveals where pricing power concentrates and where margin compression threatens established operators.
Service Type:
Corporate Events and Weddings face the strongest substitution pressure as multinational subsidiaries build captive planning teams and families turn to informal coordination networks.
- Corporate Events:Structured business gatherings encompassing product launches, annual general meetings, and incentive travel programs. Demand concentrates in Riyadh's King Abdullah Financial District and Jeddah's corporate headquarters corridor, where SFDA food safety mandates and MOHAP crowd protocols professionalize vendor selection. Government procurement shifts toward outcome-based contracts tighten margin pressure on legacy operators.
- Weddings:Family-coordinated celebrations ranging from intimate gatherings to multi-day productions involving separate gender-segregated programming. Procurement remains dispersed across extended family networks, though high-net-worth households in Riyadh and Jeddah increasingly demand full-service event management with international design standards.
- Concerts:Live music and entertainment productions spanning indoor venues to stadium-scale outdoor festivals. MDLBEAST's infrastructure investments in Riyadh and Jeddah anchor electronic music culture while Live Nation Middle East routes international touring acts through the Kingdom.
- Exhibitions:Trade shows and consumer expos requiring specialized logistics for booth construction, freight handling, and attendee flow management. SEVEN's giga-project venue pipeline in entertainment cities creates captive demand for exhibition services tied to permanent infrastructure.
Weddings anchors the volume base while Corporate Events gains share at the steepest rate as multinational procurement professionalizes.
Client Type:
Cost tier stratification separates premium service providers serving high-net-worth individuals from volume operators handling government and NGO contracts.
- Private Individuals:Family-based procurement for weddings, milestone celebrations, and social gatherings. Riyadh and Jeddah households with disposable income above threshold levels increasingly contract full-service event management rather than fragmented vendor coordination.
- Corporations:Multinational subsidiaries and domestic enterprises purchasing structured event programming. Procurement departments in technology and pharmaceutical sectors now demand engagement metrics and lead generation verification as contract conditions.
- NGOs:Non-governmental organizations coordinating community programs, fundraising galas, and awareness campaigns. Budget constraints limit service tier access, though Vision 2030 social initiative funding expands contract availability.
- Government Agencies:State entities unwinding historical dominance over event procurement as privatization redirects spend toward private sector operators. Compliance with SFDA and MOHAP frameworks remains mandatory for contract eligibility.
Government Agencies historically dominated contract value while Corporations expands most quickly as procurement autonomy increases.
Event Size:
Regulatory burden scales non-linearly with attendance, creating margin cliffs at MOHAP-mandated density thresholds.
- Small Scale:Gatherings below five hundred attendees with minimal regulatory overhead. Family celebrations and corporate retreats in Riyadh's diplomatic quarter and Jeddah's coastal districts generate consistent demand for boutique operators.
- Medium Scale:Events between five hundred and five thousand attendees triggering initial MOHAP notification requirements. Regional hotel ballrooms and conference centers in Dammam and Khobar serve this segment alongside primary corridor venues.
- Large Scale:Productions between five thousand and ten thousand attendees requiring certified crowd engineering and on-site medical deployment. Stadium configurations in Riyadh and Jeddah adjust floor plans to reduce peak density metrics and comply with tightening enforcement.
- Mega Events:Gatherings exceeding ten thousand attendees with full MOHAP emergency medical preparedness mandates and SFDA large-scale catering protocols. Giga-project activations at NEOM and AMAALA concentrate ultra-premium programming with limited incumbent competition.
Small Scale generates transaction volume frequency while Mega Events commands the steepest expansion trajectory as giga-project infrastructure activates.
Technology Used:
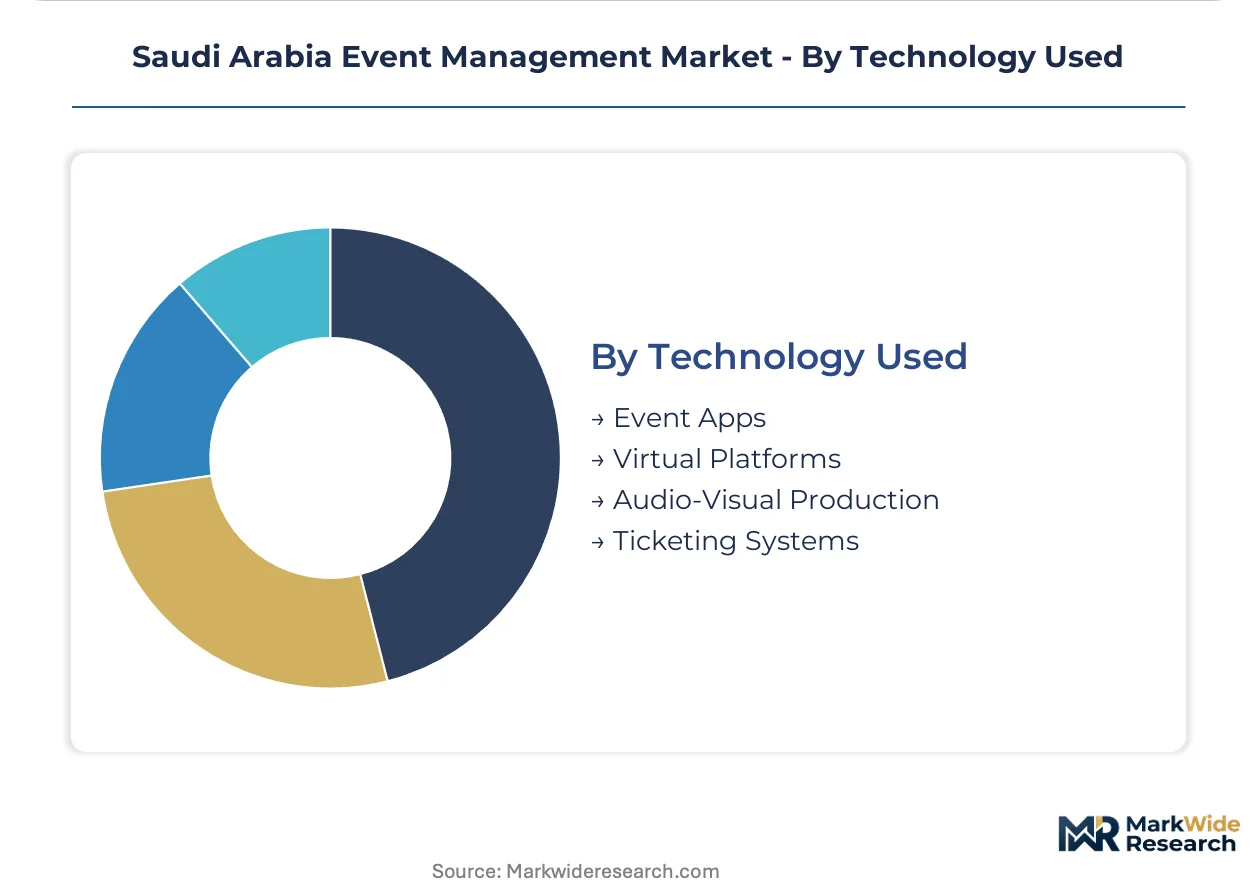
Application maturity separates legacy on-premise systems from cloud-native platforms enabling hybrid attendance models.
- Event Apps:Mobile-native platforms for real-time guest communication, wayfinding, and networking functionality. Corporate events in Riyadh's business district deploy white-label solutions as standard, extending physical engagement through digital touchpoints.
- Virtual Platforms:Web-based environments enabling remote participation alongside physical attendance. Post-pandemic normalization sustains hybrid model adoption, particularly for multinational corporate gatherings with distributed workforces.
- Audio-Visual Production:Staging, lighting, and sound systems requiring certified technical expertise. Talent scarcity concentrates in Riyadh and Jeddah, forcing secondary cities to import specialists at premium cost.
- Ticketing Systems:Digital infrastructure for access control, capacity management, and revenue collection. Legacy on-premise installations face migration friction as operators transition to cloud-native hybrid platforms.
Audio-Visual Production anchors technology spend while Virtual Platforms climbs the fastest as hybrid attendance models normalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate procurement departments and high-net-worth households concentrate event spend across Riyadh, Jeddah, and the Red Sea corridor, with regulatory compliance thresholds reshaping venue economics in each sub-region.
Riyadh
King Abdullah Financial District headquarters and government ministry clusters generate sustained corporate event demand. SFDA large-scale catering protocols and MOHAP crowd density mandates professionalize vendor selection for gatherings exceeding five thousand attendees. The Riyadh Boulevard and Diriyah Gate entertainment zones anchor mega-event infrastructure with giga-project backing.
Jeddah
Multinational corporate headquarters and Red Sea port logistics create dual demand streams for business events and maritime-themed experiential programming. Municipal permitting timelines diverge from Riyadh standards, compressing activation schedules for temporary venue installations. The Jeddah Season festival corridor concentrates international artist touring and luxury hospitality integration.
Eastern Province
Aramco-affiliated corporate events and industrial sector gatherings sustain mid-scale production demand in Dammam and Khobar. Technical talent scarcity forces reliance on fly-in specialists from Riyadh at premium cost. The Dhahran Expo center and emerging entertainment city developments expand venue inventory for trade exhibition formats.
NEOM Northwest
AMAALA and THE LINE giga-projects activate previously undeveloped territory for ultra-premium experiential programming with limited incumbent competition. SAGIA investment licensing operates on extended timelines distinct from municipal frameworks elsewhere. The Oxagon industrial zone and coastal leisure clusters concentrate experimental venue formats and sustainability-mandated event delivery.
Saudi Arabia Event Management Market Competitive Landscape
Player mix skews toward sovereign-backed entertainment developers and international touring operators, creating a bifurcated structure where capital-intensive venue builders compete against agile programming specialists. The market exhibits tiered concentration: giga-project developers anchor mega-event infrastructure, music festival operators capture youth demographic engagement, and boutique agencies serve high-net-worth household procurement. Dominant competitive moves include strategic partnerships with municipal authorities for venue licensing and portfolio diversification into hybrid event technology stacks.
Within the sovereign-backed developer tier, Saudi Entertainment Ventures and MDLBEAST exemplify divergent strategic archetypes—SEVEN occupies a position tied to permanent entertainment city infrastructure, while MDLBEAST anchors electronic music culture through festival IP and artist network development. Live Nation Middle East represents the international operator archetype, leveraging global touring relationships to capture inbound concert demand without fixed venue overhead.
| Leading Market Players |
|---|
| Saudi Entertainment Ventures (SEVEN) |
| MDLBEAST |
| SELA |
| Rotana Live |
| Live Nation Middle East |
| Benchmark |
| Eventive |
| Tahaluf |
| TicketMX |
| Others |
Pricing and Supply Chain Analysis
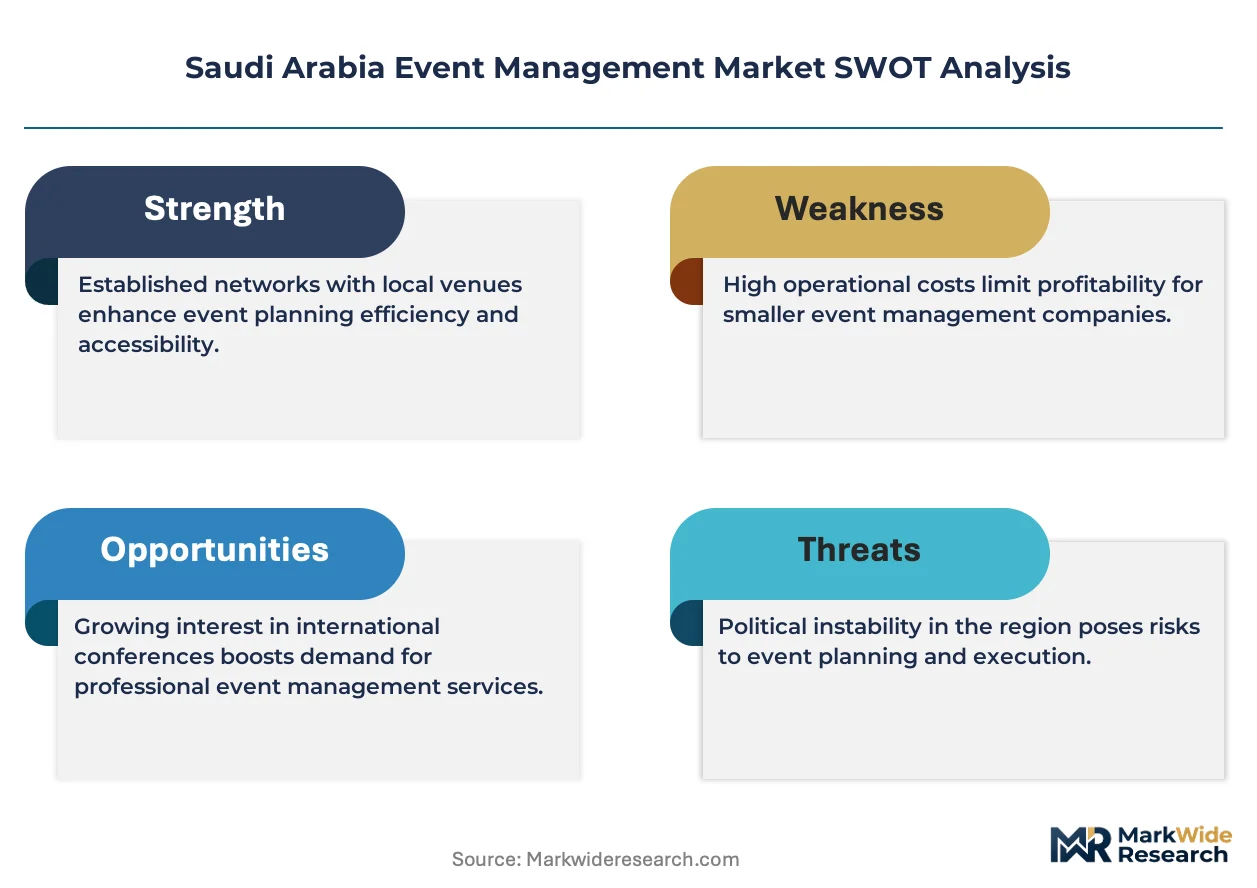
SFDA food safety certification and MOHAP crowd safety credentials simultaneously gate vendor qualification and enable price stratification across the Saudi event management landscape. Operators holding active permits command premium positioning for government and multinational contracts while uncertified competitors face exclusion from procurement pools above five thousand attendees.
Pricing Analysis
Legacy audio-visual production systems trade at steep discounts against cloud-native hybrid event platforms and immersive AR-enabled installations. Project-based billing dominates corporate events in Riyadh and Jeddah, with outcome-based contracts tying payment release to attendee engagement verification. Price differentiation rests on MOHAP certification tier and technical talent scarcity geography. Pricing pressure stems from multinational procurement consolidation demanding metric-verified performance. Small-scale family celebrations exhibit highest price sensitivity; mega-events at giga-project venues show lowest.
Supply Chain Analysis
Strategic stockpiling of temporary structure materials and staging equipment prevails among established operators navigating Saudi port customs clearance variability. Imported audio-visual hardware draws from Germany, South Korea, and the United States; temporary structure materials source from China and Turkey. Single-source vulnerability concentrates in certified crowd engineering talent pools anchored in Riyadh and Jeddah. Distribution runs through project-based logistics coordination with fly-in specialist deployment for secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate procurement consolidation among multinational subsidiaries and government agencies is shifting buyer power toward outcome-based contracting, fragmenting legacy vendor rosters and compressing margins for input-based operators.
For Market Incumbents: Fortify market position through backward integration into certified technical talent development and captive MOHAP safety training academies. Establish preferred supplier agreements with SEVEN and MDLBEAST for giga-project venue access. Defend against hybrid event platform substitution by bundling physical production with virtual platform licensing. For New Entrants and Emerging Players: MOHAP emergency medical preparedness fast-track certification opens white-space entry for government contract eligibility. Target the Red Sea coast corridor where NEOM and AMAALA giga-projects activate with limited incumbent competition. Pursue corporate in-house capability licensing as anchor go-to-market angle for technology and training revenue. For Investors and Strategic Acquirers: SFDA and MOHAP framework tightening reshapes the acquisition landscape toward certified operator consolidation. Five-to-ten year viability favors platforms with hybrid event technology stacks and giga-project venue relationships. Target acquisition archetype: mid-scale operators with active certification portfolios and established municipal permitting relationships. Signal to watch: Vision 2030 entertainment target revisions altering venue construction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Safety Certification Investment | Active credentials unlock government and multinational contract eligibility above five thousand attendees. |
| Hybrid Event Platform Integration | Cloud-native virtual infrastructure extends audience reach beyond physical venue constraints for corporate clients. |
| Giga-Project Venue Partnership | SEVEN and MDLBEAST relationships secure priority access to NEOM and AMAALA mega-event infrastructure. |
| Technical Talent Development Program | Certified crowd engineering and audio-visual expertise reduces fly-in specialist dependency and cost. |
| Corporate In-House Capability Licensing | Training and technology channels capture recurring revenue from multinational subsidiary captive team builds. |
Research Methodology
Desk research of SFDA regulatory filings, MOHAP safety protocols, SAGIA investment licensing records, and municipal permitting databases preceded structured interviews with event management executives, certified crowd engineers, government procurement officers, and giga-project development leads. Secondary validation drew from Vision 2030 policy documents, entertainment sector expenditure disclosures, and trade exhibition attendance records. Bottom-up segment sizing triangulated against top-down sovereign capital flow estimates.
Variance decomposition across service type, client type, event size, and technology used dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling weighted by venue activation timelines and regulatory compliance cost escalation. Industry-specific forecast inputs incorporated giga-project construction schedules and multinational subsidiary establishment patterns.
Decision-makers should treat outputs as directional under sustained Vision 2030 entertainment sector commitment and stable regulatory enforcement intensity; material deviation would warrant model refresh. Forecasts assume continued SFDA and MOHAP framework tightening without abrupt threshold changes. Revision becomes warranted when giga-project venue activation delays exceed eighteen months or sovereign entertainment expenditure reallocations cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Thailand MICE and Mega Event Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
France Event Services Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
India B2B Events Market
Events and Conferences
Europe Discount Events and Experiences Market
Events and Conferences
Event Tourism Market
Events and Conferences
MICE Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Italy Event Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
Asia-Pacific Wedding Services Market