
 Canada Wedding Services Market | 2026-2036
Canada Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Wedding Services Market Insights
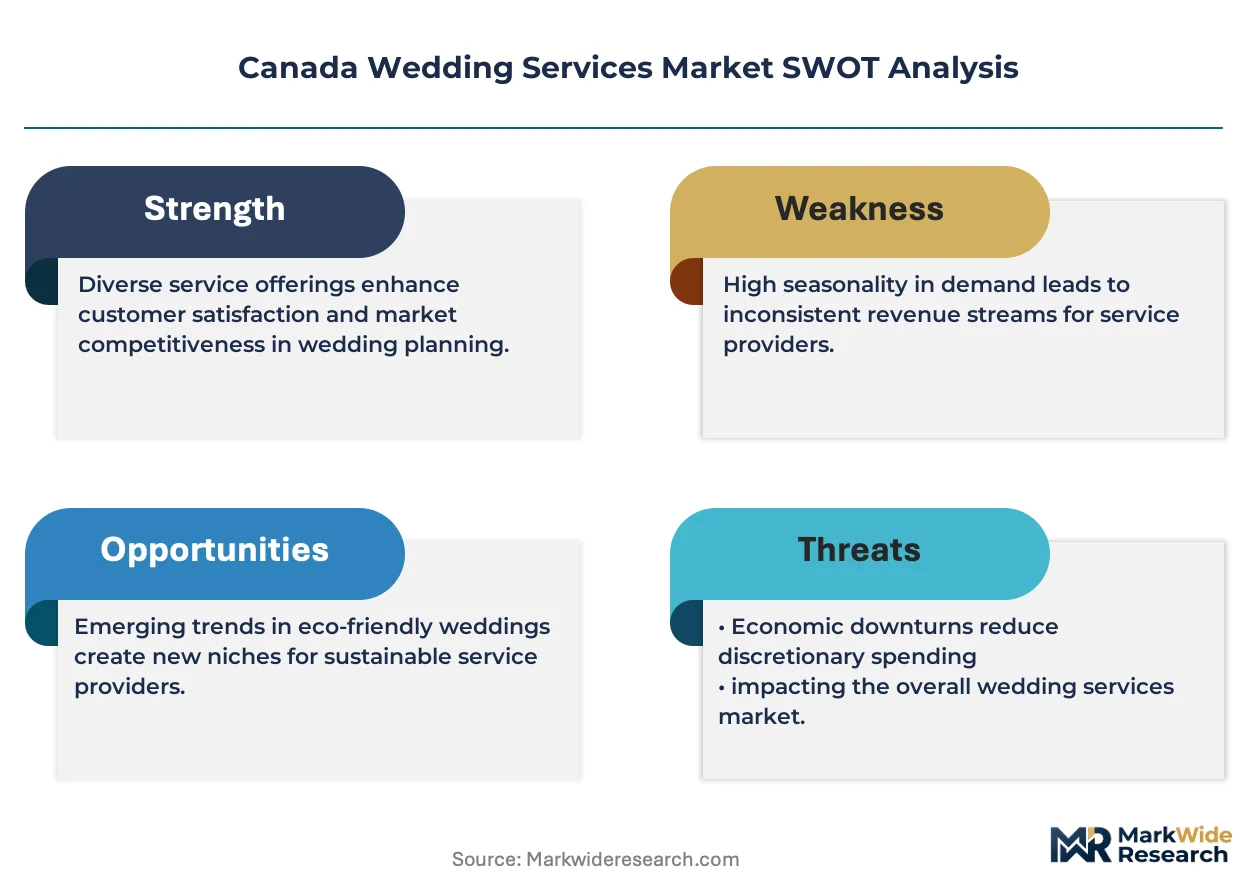
The Canada wedding services sector is consolidating around a widening gap between bespoke luxury coordination and standardized budget offerings. Dream Weddings Canada leverages its Ontario venue partnerships to anchor high-margin full-service contracts. The Wedding Company of Niagara competes through geographic specialization in destination ceremonies. Blissful Weddings & Co. differentiates via vendor curation strength in the Greater Toronto Area.
Wedding services encompass the professional coordination, aesthetic design, food preparation, and documentation of marriage ceremonies and receptions, typically requiring multi-vendor synchronization across 12-18 month planning cycles. Venue rentals and catering services command the largest share of contracted spend, while photography and floral design extract disproportionate margin through personalization intensity. Cultural preference segmentation shows contemporary and eco-friendly formats gaining share against traditional formats, particularly in Vancouver and Montreal where sustainability credentials influence vendor selection.
Health Canada oversees food safety compliance for catering operations, while provincial liquor boards regulate bar service licensing at reception venues. Municipal zoning bylaws in Toronto, Vancouver, and Calgary constrain venue capacity and operating hours, directly shaping service packaging and pricing architecture. Stakeholders must monitor evolving provincial consumer protection frameworks for deposit and cancellation terms, as these rules increasingly dictate contract structures and working capital requirements across the vendor base.
Market Dynamics
Millennial and Gen Z couples are consolidating vendor relationships around full-service planning packages, compressing the traditional fragmented procurement model into single-contract coordination. This structural shift is reconfiguring margin distribution across venue operators, caterers, and independent planners.
Growth Catalysts
- Provincial liquor licensing liberalization:British Columbia and Ontario reforms are expanding reception venue operating hours and outdoor service permissions, directly enlarging addressable event capacity for caterers and rental operators.
- Destination ceremony clustering:Niagara-on-the-Lake and Whistler are attracting cross-border couples from the US Northeast and Pacific Northwest, creating concentrated demand spikes that justify specialized vendor ecosystems.
- Digital planning platforms:Vendor management software is reducing coordination friction across 12-18 month planning cycles, lowering client acquisition costs for independent planners competing with established agencies.
Market Restraints
- Input cost volatility:Floral wholesalers face unpredictable cut-flower import pricing from Ecuador and Colombia, compressing margins on high-personalization arrangements that anchor luxury package pricing.
- Municipal zoning density:Toronto and Vancouver bylaws restrict venue capacity and noise ordinances, capping revenue per event and forcing geographic expansion into lower-density suburbs with weaker vendor infrastructure.
- Substitution by micro-weddings:Intimate ceremonies with under 20 guests are displacing traditional 150-person receptions, reducing per-event catering and rental spend by 40-60% in the segment.
Strategic Opportunities
- Atlantic Canada penetration:Halifax and Charlottetown exhibit supply scarcity relative to rising local demand and cruise-ship wedding traffic, offering first-mover positioning for full-service entrants.
- Health Canada food safety certification:Caterers achieving preventive control plan accreditation can access institutional venue contracts with universities and museums, opening non-traditional reception spaces.
- Hybrid physical-digital coordination:Planners combining in-person design with virtual guest management are capturing dispersed-family ceremonies, a format accelerated by persistent cross-border mobility constraints.
Industry Challenges
- Certified coordinator scarcity:The Wedding Planners Institute of Canada credential pipeline produces fewer than 200 certified professionals annually, constraining quality-assured labor supply as demand for complex multi-vendor events rises.
- Deposit protection compliance:Evolving provincial consumer protection frameworks in Alberta and Quebec mandate escrow-style deposit handling, forcing working capital restructuring for small independent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Wedding Services Market |
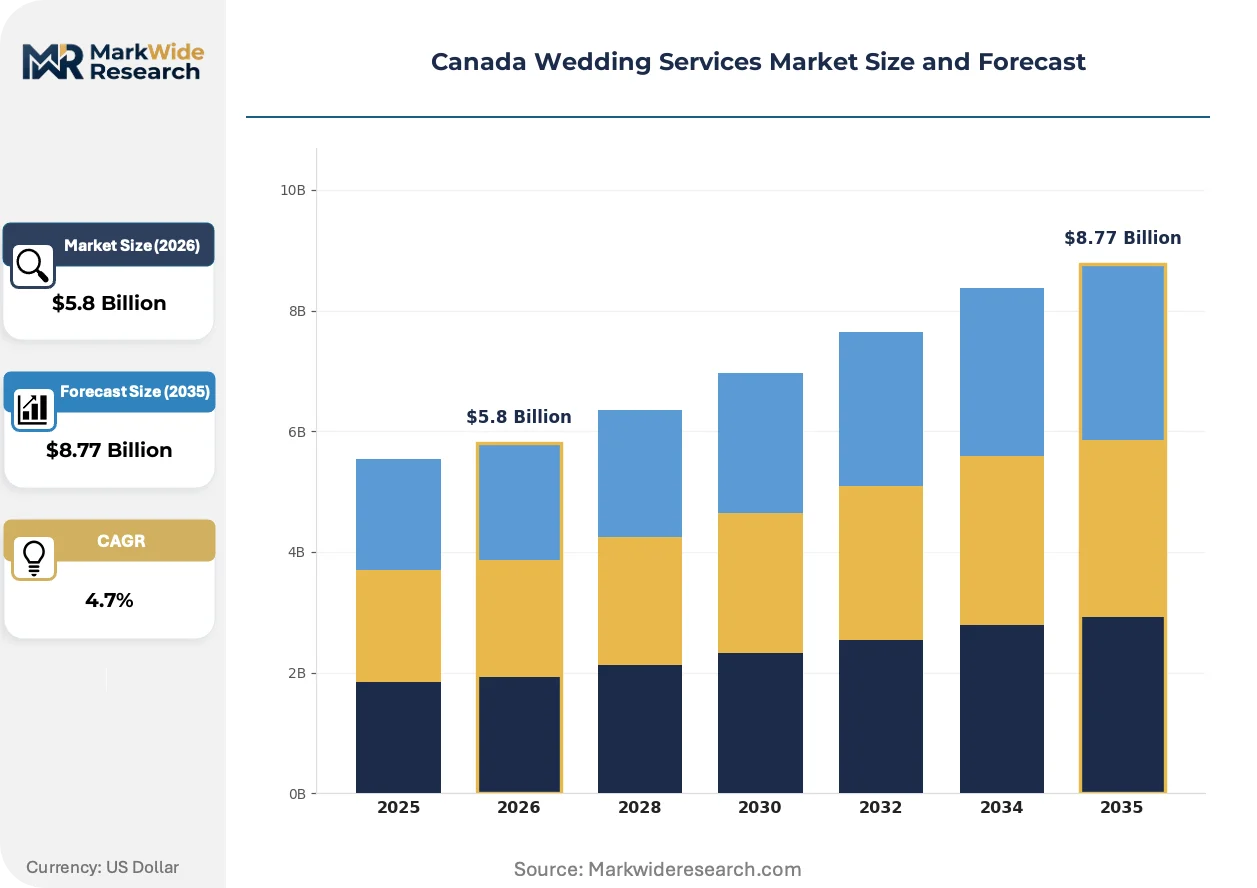
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Venue Rentals, Catering Services, Photography, Floral Design Client Type: Brides, Grooms, Wedding Planners, Event Coordinators Cultural Preference: Traditional, Contemporary, Destination, Eco-Friendly Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Wedding Planners, The Perfect Day, Dream Weddings Canada, Fusion Events, Weddings by Ardenian, A Lavish Affair, Blissful Weddings & Co., Fairytales Wedding & Event Planning, The Wedding Company of Niagara, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Wedding Services Market Trends and Innovations
Technology-enabled personalization is fragmenting the standardized wedding package into configurable components, while regulatory pressure on food safety and alcohol service reshapes vendor qualification requirements. Sustainability credentials are becoming a non-negotiable screening criterion in vendor selection, particularly among urban couples in Vancouver and Toronto.
Modular floral design systems are modularizing the traditional bespoke arrangement workflow. Toronto and Vancouver florists are adopting pre-designed component libraries that clients customize through digital visualization tools. This technology is modularizing labor allocation, allowing studios to serve 3-4 concurrent events with the same design staff previously dedicated to single weddings.
Health Canada's Safe Food for Canadians Regulations are tightening preventive control requirements for off-premise caterers serving events over 100 guests. Caterers must now document hazard analysis plans and supplier verification records. The regulation most affects independent operators in Ontario and British Columbia, who are consolidating into shared commercial kitchen cooperatives to distribute compliance costs.
Couples are unbundling the traditional all-inclusive venue package and procuring services through direct vendor relationships. This behavior disrupts the historic venue-caterer-photographer bundled referral model, replacing it with planner-mediated open procurement. The shift is most visible in Montreal and Calgary, where bilingual and energy-sector professionals exhibit higher price transparency tolerance and vendor direct-engagement confidence.
Canada Wedding Services Market Segmentation
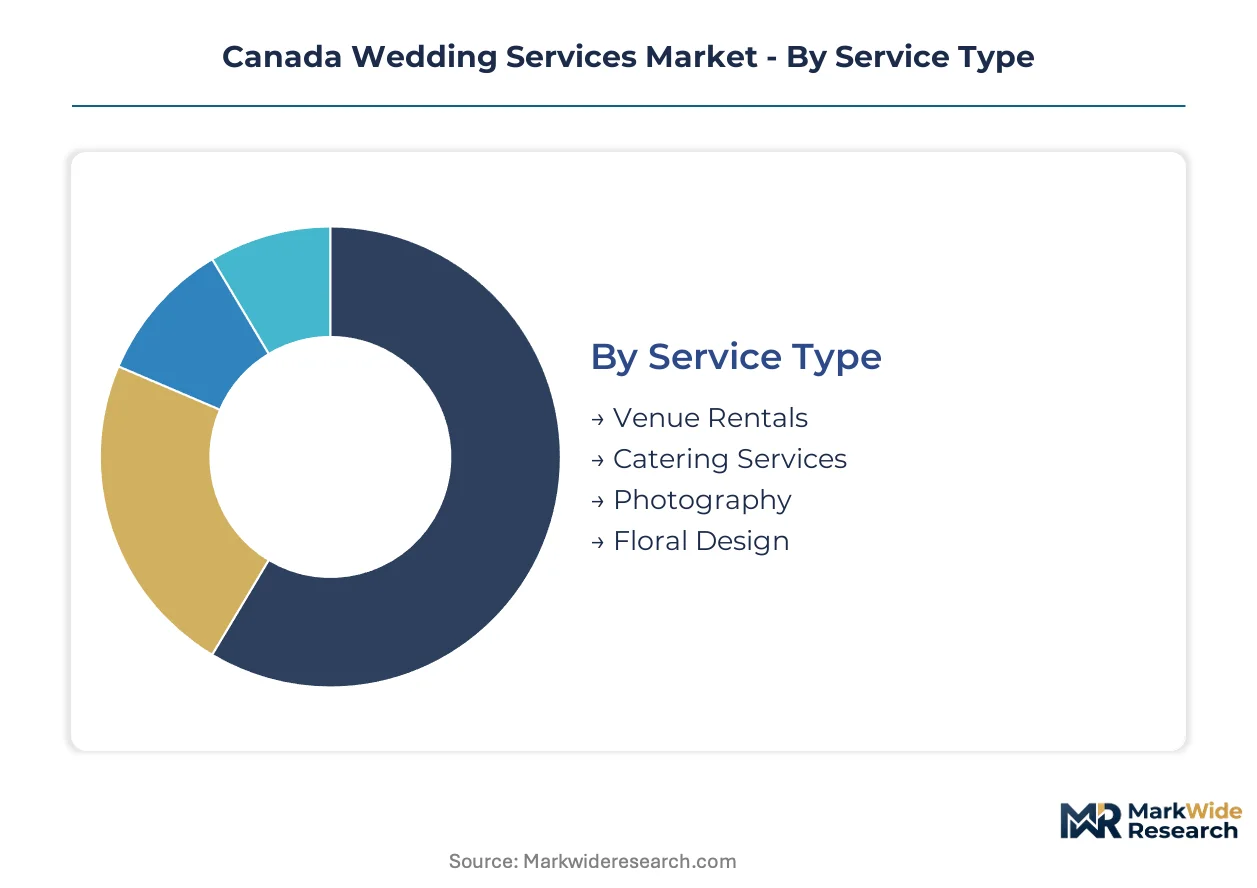
Vendor selection in Canada wedding services follows distinct procurement pathways that reshape margin distribution and contract structures. Each segmentation dimension reveals how couples prioritize trade-offs between convenience, personalization, and cost control across 12-18 month planning cycles.
Service Type:
Standalone service procurement dominates high-budget segments, while bundled coordination compresses vendor count in mid-market tiers.
- Venue Rentals:Physical spaces range from urban heritage buildings to rural barn conversions, with capacity constraints directly shaping guest list architecture. Ontario and British Columbia venues command premium deposits due to municipal zoning scarcity in Toronto and Vancouver core districts.
- Catering Services:Off-premise operators must document Health Canada preventive control plans for events exceeding 100 guests, forcing kitchen infrastructure investments that favor established players. Quebec and Alberta caterers face additional provincial liquor board compliance layers for bar service integration.
- Photography:Documentary-style capture with same-day editing capabilities anchors premium positioning.
- Floral Design:Ecuador and Colombian import dependency creates margin volatility for bespoke arrangements.
Venue rentals lead volumes today; catering services are gaining share fastest through full-service package bundling.
Client Type:
Procurement authority concentration determines whether vendors face fragmented individual negotiations or consolidated professional mediation.
- Brides:Primary decision-makers in 70% of Canadian wedding planning engagements, driving aesthetic and vendor selection priorities with direct Pinterest and Instagram platform research. Urban brides in Montreal and Calgary exhibit highest price transparency tolerance and vendor direct-engagement confidence.
- Grooms:Increasingly active in logistics-heavy segments including transportation coordination, entertainment booking, and technology infrastructure for hybrid ceremonies. Grooms in energy-sector hubs like Calgary prioritize vendor credential verification over aesthetic curation.
- Wedding Planners:Certified professionals from the Wedding Planners Institute of Canada mediate complex multi-vendor synchronization.
- Event Coordinators:Venue-employed staff managing day-of execution without full planning scope.
Brides retain dominant procurement authority; wedding planners are expanding their share of vendor relationship consolidation.
Cultural Preference:
Ceremony format selection increasingly filters vendor compatibility before price negotiation begins.
- Traditional:Religious venue requirements and multi-generational guest expectations demand vendors with established cultural competency protocols. Traditional formats concentrate in suburban Ontario and Quebec regions with lower vendor density.
- Contemporary:Secular ceremonies in non-traditional spaces require flexible vendors capable of rapid venue adaptation without institutional infrastructure support. Vancouver and Toronto contemporary couples prioritize sustainability credentials in vendor screening.
- Destination:Niagara-on-the-Lake and Whistler clusters attract cross-border US couples seeking concentrated vendor ecosystems.
- Eco-Friendly:Zero-waste catering and locally sourced floral requirements constrain vendor pools to certified sustainable operators.
Traditional formats anchor volume in established religious communities; eco-friendly ceremonies are climbing the fastest in Vancouver and Toronto urban cores.
Price Tier:
Service packaging architecture stratifies across four distinct spending thresholds with minimal vendor overlap between tiers.
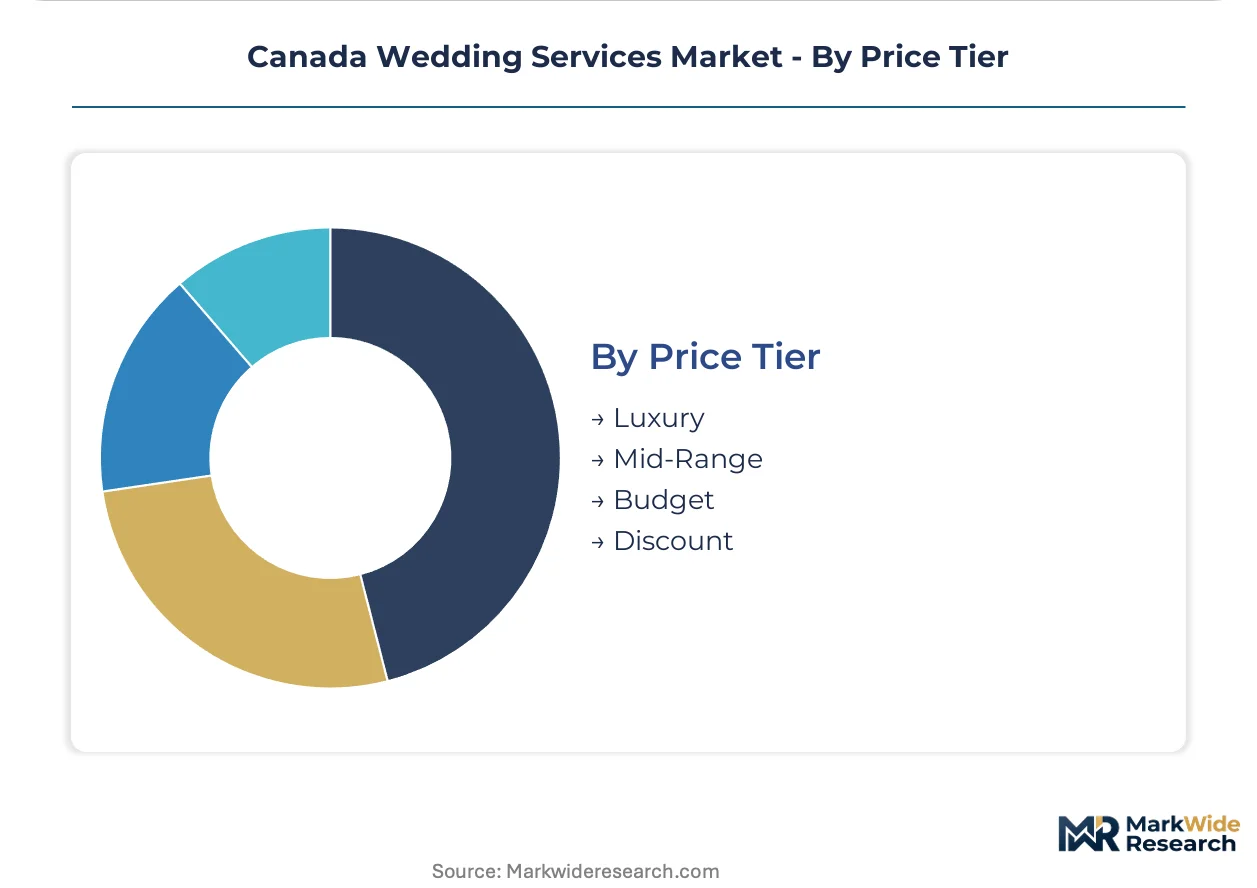
- Luxury:Full-service coordination with dedicated design teams and exclusive vendor access, typically requiring 18-month planning horizons and substantial non-refundable deposits. Luxury tier concentrates in Toronto, Vancouver, and Montreal where household discretionary income supports premium positioning.
- Mid-Range:Hybrid procurement combining professional planning with selective direct vendor engagement, representing the fastest-contracting segment as couples unbundle traditional packages. Mid-range demand is fragmenting between budget upgrades and luxury downgrades.
- Budget:Template-based packages with limited customization and compressed planning cycles.
- Discount:Off-peak scheduling and minimal service scope targeting price-sensitive couples.
Mid-range tier historically dominated contract volume; luxury segment is expanding most quickly as full-service consolidation reshapes procurement behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified wedding planners concentrate in Ontario and British Columbia, where urban density supports specialized vendor ecosystems and full-service coordination demand runs highest.
Ontario
Toronto's municipal zoning scarcity drives premium venue deposits and compressed capacity, while Health Canada food safety regulations tighten preventive control documentation for caterers serving events exceeding 100 guests. The Niagara-on-the-Lake cluster attracts cross-border US couples from the Northeast, creating concentrated demand spikes that justify dedicated destination wedding infrastructure.
British Columbia
Vancouver couples prioritize sustainability credentials in vendor screening, accelerating eco-friendly ceremony format adoption against traditional alternatives. Provincial liquor licensing reforms expand reception venue operating hours and outdoor service permissions, directly enlarging addressable event capacity. The Whistler mountain resort anchors Pacific Northwest cross-border destination demand with established vendor density.
Quebec
Montreal's bilingual professional base exhibits elevated price transparency tolerance and direct vendor engagement confidence, disrupting historic bundled referral models. Provincial liquor board compliance layers add regulatory complexity for integrated bar service caterers. Contemporary secular ceremonies in non-traditional spaces require rapid venue adaptation without institutional infrastructure support.
Alberta
Calgary's energy-sector professionals prioritize vendor credential verification over aesthetic curation in procurement decisions. Evolving provincial consumer protection frameworks mandate escrow-style deposit handling, forcing working capital restructuring for small independent operators. Municipal noise ordinances restrict venue capacity and operating hours, capping revenue per event.
Atlantic Canada
Halifax and Charlottetown exhibit supply scarcity relative to rising local demand and cruise-ship wedding traffic, offering first-mover positioning for full-service entrants. Health Canada preventive control plan accreditation opens institutional venue contracts with universities and museums. Vendor infrastructure remains underdeveloped compared to central Canadian density.
Canada Wedding Services Market Competitive Landscape
Top-tier vendors anchor luxury full-service coordination, while mid-market independents compete through selective vendor curation and compressed planning cycles. The vendor base stratifies across four distinct tiers with minimal overlap: exclusive design teams with 18-month horizons, hybrid procurement specialists, template-based budget operators, and off-peak discount providers. Three strategic archetypes dominate: geographic specialists leveraging destination clustering, sustainability-certified operators capturing urban eco-demand, and technology-enabled platforms reducing coordination friction. Consolidation through shared commercial kitchen cooperatives and planner-mediated open procurement are reshaping competitive positioning.
Within the geographic specialization tier, The Wedding Company of Niagara occupies a position exemplifying destination ceremony concentration, while Dream Weddings Canada anchors Ontario venue partnership strategies. Blissful Weddings & Co. represents vendor curation strength in the Greater Toronto Area. These three operators illustrate how regional density and full-service bundling create defensible positioning against fragmented independent competition.
| Leading Market Players |
|---|
| Wedding Planners |
| The Perfect Day |
| Dream Weddings Canada |
| Fusion Events |
| Weddings by Ardenian |
| A Lavish Affair |
| Blissful Weddings & Co. |
| Fairytales Wedding & Event Planning |
| The Wedding Company of Niagara |
| Others |
Pricing and Supply Chain Analysis
Millennial and Gen Z preference for full-service planning packages is compressing fragmented vendor procurement into single-contract coordination, forcing independent operators to consolidate or accept margin compression while full-service agencies capture pricing power through bundled convenience premiums.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the Canada wedding services sector. Three-tier pricing structure across premium, standard, and economy levels stratifies by planning horizon length and vendor exclusivity, with luxury full-service packages commanding substantial non-refundable deposits against compressed budget-tier margins. Price differentiation hinges on Health Canada preventive control certification status and geographic venue scarcity in Toronto and Vancouver core districts. Pricing pressure stems from micro-wedding substitution displacing traditional 150-person receptions, with budget-tier couples exhibiting highest price sensitivity while luxury buyers tolerate premium positioning for exclusive vendor access.
Supply Chain Analysis
Regional distribution centers in Toronto, Vancouver, and Montreal anchor hub-and-spoke patterns for floral wholesalers and catering equipment lessors serving dispersed venue networks. Supply concentrates in Ecuador and Colombia for cut-flower inputs, with Ontario and British Columbia hosting dominant vendor infrastructure. Raw material dependencies include Ecuadorian roses, Colombian hydrangeas, and imported specialty linens, while equipment leasing feeds from centralized commercial kitchen cooperatives. Single-source vulnerability in South American floral imports exposes margin volatility during harvest disruptions. Distribution runs through planner-mediated open procurement channels replacing historic venue-caterer bundled referral models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada wedding services market operates as a stable compounder anchored by demographic replacement demand as Millennial and Gen Z couples enter peak marriage ages, sustaining vendor ecosystem viability through cyclical refresh.
For Market Incumbents: To counter micro-wedding substitution eroding per-event revenue, established full-service agencies should deepen vendor exclusivity agreements in Toronto and Vancouver core districts while investing in Health Canada preventive control plan accreditation to access institutional venue contracts with universities and museums as defensive channel expansion. For New Entrants and Emerging Players: Begin with Atlantic Canada penetration targeting Halifax and Charlottetown supply scarcity against rising cruise-ship wedding traffic, leveraging digital planning platforms to reduce client acquisition costs and establish first-mover positioning before infrastructure matures. For Investors and Strategic Acquirers: Asymmetric upside sits with sustainability-certified operators capturing Vancouver and Toronto eco-friendly ceremony demand, with long-term viability hinging on regulatory compliance moats deepening through evolving provincial consumer protection frameworks; monitor Health Canada food safety enforcement intensity as inflection indicator for catering consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Certification Investment | Preventive control plan accreditation unlocks institutional venue contracts with museums and universities. |
| Atlantic Canada Geographic Expansion | Halifax and Charlottetown supply scarcity offers first-mover positioning against cruise-ship wedding traffic. |
| Digital Planning Platform Integration | Vendor management software reduces coordination friction and lowers client acquisition costs for independents. |
| Shared Commercial Kitchen Cooperative | Consolidation distributes Health Canada compliance costs across independent catering operators in Ontario. |
| Sustainability Credential Repositioning | Eco-friendly certification captures Vancouver and Toronto urban couples screening vendors on environmental criteria. |
Research Methodology
Bottom-up couple-budget modeling reconciled against top-down vendor-capacity tracking forms the analytical core of this study. Primary interviews with certified wedding planners, venue operators, catering executives, and floral wholesalers were validated against secondary sources including Health Canada regulatory filings, provincial liquor board licensing databases, municipal zoning records, and Wedding Planners Institute of Canada credential pipeline data. Triangulation across demand-side procurement behavior and supply-side infrastructure investments ensures coverage of both fragmented independent operators and consolidated full-service agencies.
Historical trendline analysis of venue deposit structures, vendor contract terms, and ceremony format preferences informs projection modeling across the analysis window. Segmentation dimensions include service type, client procurement authority, cultural preference format, and price tier, with CAGRs derived from coupling demographic cohort size projections with per-couple spending trajectory assumptions. Forecast inputs incorporate provincial liquor licensing reform timelines and municipal zoning density constraints.
Several conditions sit outside the modeled scope, including extreme weather disruptions to South American floral supply, abrupt provincial regulatory reversals on outdoor alcohol service permissions, and pandemic-scale mobility restrictions reviving virtual ceremony formats. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Corporate Event Planner Market
Events and Conferences
North America Event Services Market
Events and Conferences
Trade Show Services Market
Events and Conferences
Event Tourism Market
Events and Conferences
Europe Discount Events and Experiences Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Germany Event Services Market
Events and Conferences
North America Wedding Services Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
Asia-Pacific MICE Industry Market
Events and Conferences
MICE Market
Events and Conferences
Corporate Event Market
Events and Conferences
India B2B Events Market
Events and Conferences
Saudi Arabia MICE Market