
 France Event Services Market | 2026-2036
France Event Services Market Size, Share, and Industry Trends Forecast 2026-2036
France Event Services Market Insights
After-event content monetization is tilting margin pools away from pure logistics toward digital extension services. GL events leverages its venue ownership network across Lyon and Paris to sustain recurring revenue streams. Almea Event specializes in high-touch corporate programming for CAC 40 clients, while MARS EVENTS competes through immersive technology integration at flagship product launches.
France Event Services encompasses the planning, production, logistics, and technical execution of live gatherings ranging from intimate board meetings to stadium-scale public festivals, typically requiring audiovisual systems with lumen outputs exceeding 20,000 for large-format projection. Corporate Events command the largest share of contracted value, reflecting sustained enterprise investment in brand experience and stakeholder engagement. Trade Shows anchor venue utilization cycles, particularly at Paris Expo Porte de Versailles, while Social Gatherings represent the fastest-expanding client acquisition frontier as individual consumers professionalize milestone celebrations.
ANSM safety protocols for temporary food service installations and CNIL data governance requirements for attendee tracking systems shape operational compliance costs across the sector. The EU Green Deal's binding decarbonization targets for temporary structures are forcing material sourcing shifts toward reusable staging and low-emission transport fleets. Stakeholders must monitor how Paris 2024 legacy infrastructure repurposing alters venue economics and whether regional city clusters like Bordeaux and Lille can absorb overflow demand as Ile-de-France capacity tightens.
Market Dynamics
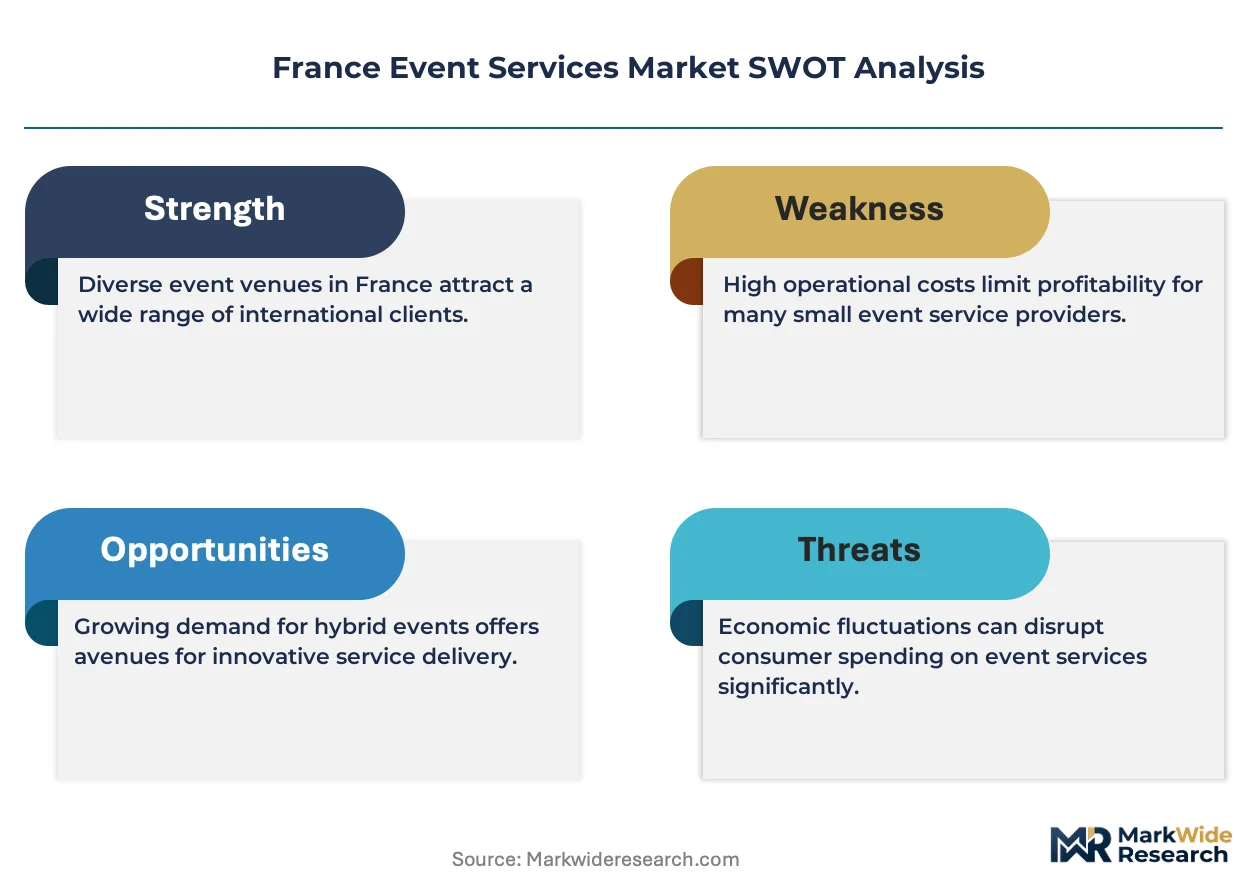
Venue scarcity across Paris-Ile-de-France is compressing event calendars and forcing service providers toward modular staging systems and regional satellite operations. This supply constraint is redistributing margin pools from fixed-venue rentals toward mobile technical production capabilities.
Growth Catalysts
- Sapin II compliance frameworks:Pharmaceutical and luxury sector procurement teams mandate third-party event oversight, expanding contracted agency relationships. This regulatory driver professionalizes spend categories previously managed in-house.
- Experiential marketing budgets:CAC 40 enterprises redirect above-the-line advertising funds into immersive stakeholder gatherings. Product launches now incorporate multi-sensory environments with integrated content capture.
- Paris 2024 legacy infrastructure:Permanent broadcast and connectivity installations at former Olympic venues reduce technical setup costs for recurring events. Operators can now bid more aggressively on annual contracts.
Market Restraints
- Specialized technical labor pools:Certified riggers and broadcast engineers concentrate in the capital region, creating wage pressure for Lyon and Marseille operations. Transport subsidies for crew mobilization erode project margins.
- Reusable staging material costs:EU Green Deal mandates for decarbonized temporary structures require upfront capital in aluminum truss systems and LED wall inventories. Amortization timelines extend across 7-10 year replacement cycles.
- Data governance friction:CNIL requirements for attendee biometric tracking and contact exchange create compliance overhead for registration platform vendors. Consent management workflows add 12-15% to digital infrastructure budgets.
Strategic Opportunities
- Bordeaux and Lille overflow absorption:Capacity constraints in Ile-de-France position secondary city clusters for corporate retreat and incentive travel segments. Regional venue operators are upgrading AV specifications to capture this displacement.
- After-event content monetization:Broadcast-quality capture packages transform single-day gatherings into multi-week digital engagement assets. Subscription models for edited highlight reels create recurring revenue streams.
- ANSM temporary food service protocols:Standardized mobile kitchen certification opens institutional catering contracts to event service providers. Hospital and university procurement channels now accessible for gala and conference adjacent dining.
Industry Challenges
- Legacy audio-visual integration:Venue-installed projection systems from 2015-2019 lack 4K signal path compatibility, forcing parallel rental infrastructure. Technical directors must maintain dual inventory for hybrid events.
- Carbon accounting verification:Scope 3 emission calculations for temporary structures lack standardized methodologies. Client sustainability reporting requirements outpace third-party audit availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Event Services Market |
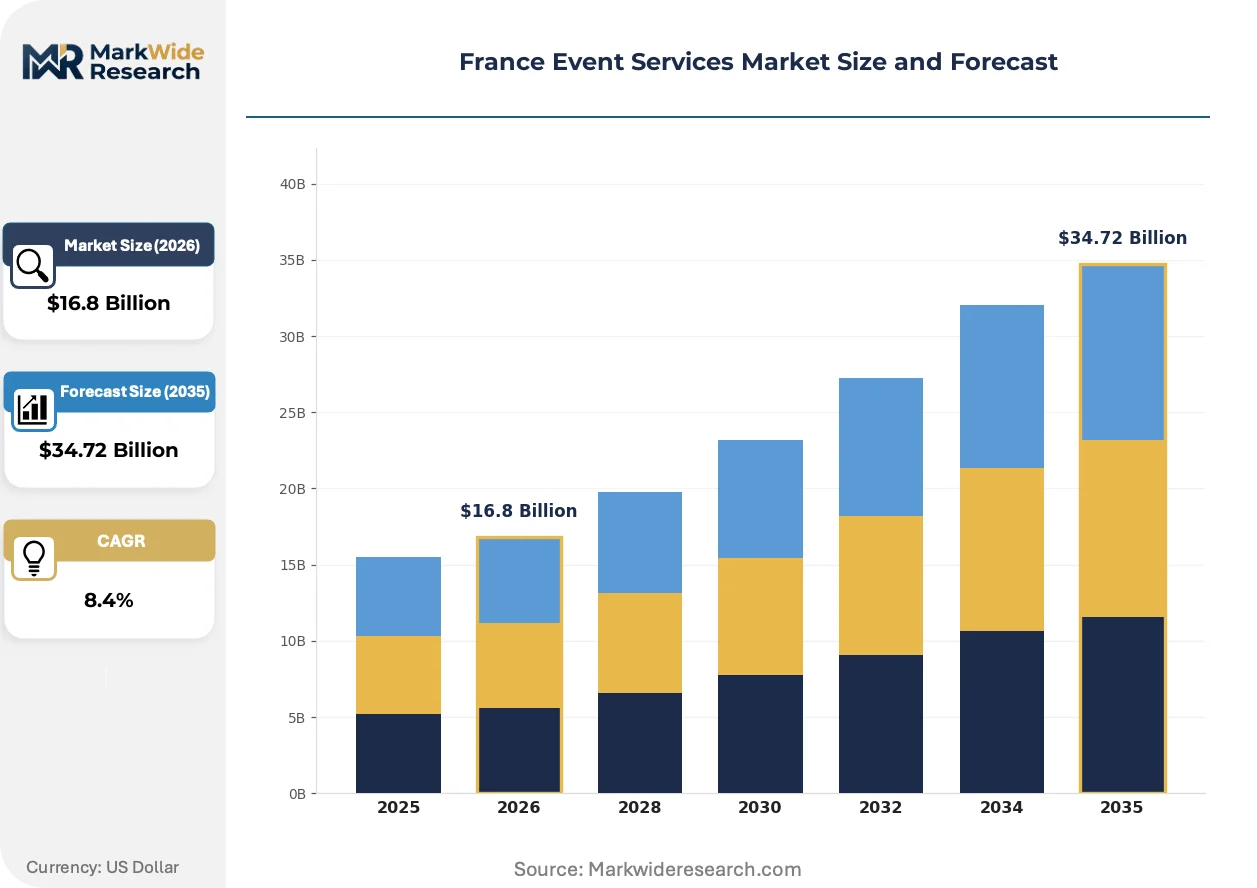
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Events, Social Gatherings, Trade Shows, Conferences Client Type: Businesses, Individuals, Non-Profits, Government Agencies Event Size: Small Scale, Medium Scale, Large Scale, Mega Events Venue Type: Indoor Venues, Outdoor Venues, Convention Centers, Unique Spaces |
| Companies Covered | Almea Event, WEEVUP, INNOV’EVENTS, Maison Opale Event, MARS EVENTS, Gold for Events, GL events, Happhapp Events, Moma-event, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Event Services Market Trends and Innovations
Digital extension services are capturing margin pools previously retained by pure logistics operators, while regulatory pressure on temporary structure sustainability reshapes material procurement. Technical production and content creation capabilities are converging within single-service contracts.
Extended reality staging is hybridizing physical and virtual audience participation for product launches and shareholder meetings. Pharmaceutical clients now require simultaneous broadcast to investigator sites and regulatory observers, compressing timelines between live execution and archived distribution. This convergence is collapsing the traditional separation between event agencies and broadcast production houses.
EU Green Deal binding decarbonization targets for temporary structures are mandating reusable aluminum staging and low-emission transport fleets. Event contractors must now document material lifecycle data for public sector procurement eligibility. Paris Expo Porte de Versailles operators have retrofitted electrical distribution to eliminate diesel generator dependency for medium-scale exhibitions.
Enterprise procurement teams are consolidating agency relationships under multi-year experiential marketing frameworks. Single-source contracts now span annual meeting calendars, incentive travel, and digital content series, displacing project-by-project vendor selection. This concentration is most visible in pharmaceutical sector RFP processes, where compliance documentation requirements favor incumbent relationships over competitive bidding.
France Event Services Market Segmentation
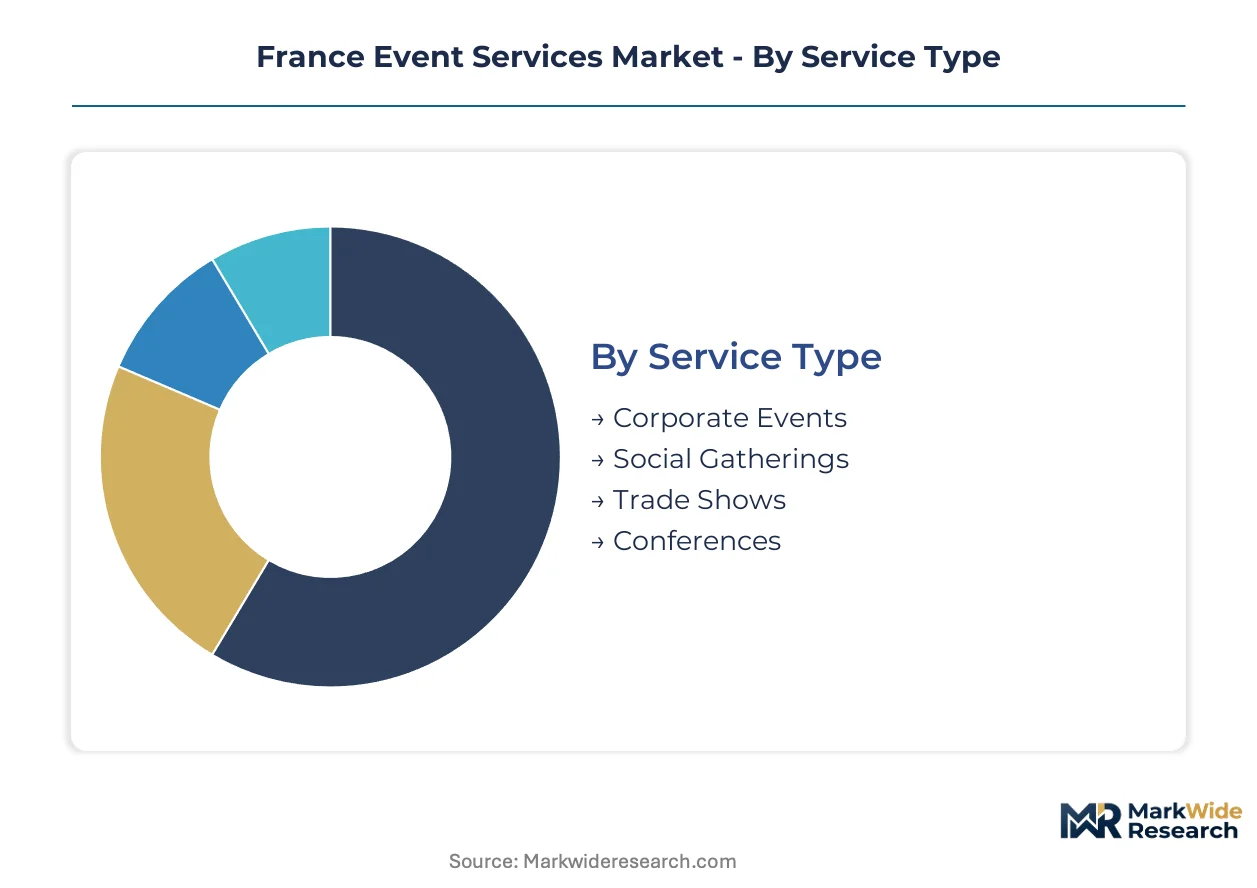
Service differentiation across the France Event Services Market follows contract velocity patterns, with high-frequency corporate programming sustaining baseline capacity utilization while episodic mega-events absorb disproportionate technical infrastructure investment. Procurement teams segment vendor selection criteria sharply between recurring calendar contracts and one-off flagship productions.
Service Type:
Corporate Events turn over fastest with quarterly or monthly cadences, while Mega Events stretch planning cycles across 18-24 month horizons with concentrated resource deployment.
- Corporate Events:Board meetings, shareholder assemblies, and incentive travel programs requiring integrated audiovisual capture for regulatory documentation. Pharmaceutical sector procurement under Sapin II mandates third-party agency oversight, professionalizing spend categories previously managed through direct venue relationships. Paris-Ile-de-France corridor concentrates demand, with venue scarcity compressing calendars toward modular staging solutions.
- Trade Shows:Exhibition floor management and booth construction services anchored by Paris Expo Porte de Versailles utilization cycles. Operators leverage Paris 2024 legacy electrical infrastructure to eliminate diesel generator dependency for medium-scale exhibitions, reducing technical setup costs for recurring contracts.
- Conferences:Multi-day knowledge programming with simultaneous interpretation and broadcast distribution requirements. CNIL data governance protocols for attendee biometric tracking add compliance overhead to registration platform specifications.
- Social Gatherings:Milestone celebrations and private functions where individual consumers professionalize production standards. Bordeaux and Lille clusters absorb displacement demand as Ile-de-France capacity tightens, with regional operators upgrading AV specifications to capture this segment.
Corporate Events anchors the volume base while Social Gatherings gains share at the steepest rate.
Client Type:
Contract structures vary sharply by procurement sophistication, from standardized RFP processes to informal vendor relationships.
- Businesses:CAC 40 enterprises and mid-cap companies consolidating agency relationships under multi-year experiential marketing frameworks. Single-source contracts now span annual meeting calendars, incentive travel, and digital content series, displacing project-by-project vendor selection.
- Non-Profits:Association congresses and fundraising galas with constrained budgets prioritizing venue access over production value. EU Green Deal carbon accounting requirements challenge sustainability reporting for temporary structure deployments.
- Government Agencies:Public sector procurement with mandatory material lifecycle documentation for reusable staging eligibility. ANSM safety protocols for temporary food service installations open institutional catering adjacent opportunities.
- Individuals:Private celebration hosts driving professionalization of wedding and anniversary production standards. After-event content monetization through broadcast-quality capture packages transforms single-day gatherings into multi-week digital engagement assets.
Businesses command the contracted value concentration while Individuals expand the addressable frontier most rapidly.
Event Size:
Technical crew mobilization and equipment depreciation schedules scale non-linearly across size thresholds.
- Large Scale:Stadium-capacity productions requiring certified riggers and broadcast engineers concentrated in the capital region. Transport subsidies for crew mobilization to Lyon and Marseille operations erode project margins, creating wage pressure differentials.
- Mega Events:Olympic-legacy infrastructure deployments with permanent broadcast and connectivity installations reducing technical setup costs for recurring events. Operators bid aggressively on annual contracts leveraging amortized capital expenditure.
- Medium Scale:Regional corporate retreats and incentive travel segments absorbing Ile-de-France overflow demand. Secondary city clusters upgrade AV specifications to capture displacement from Paris venue scarcity.
- Small Scale:Intimate board meetings and executive dinners with high-touch service requirements. Almea Event and comparable specialists target CAC 40 programming with compliance documentation capabilities.
Large Scale productions absorb the technical infrastructure investment while Medium Scale events climb the fastest as regional capacity expands.
Venue Type:
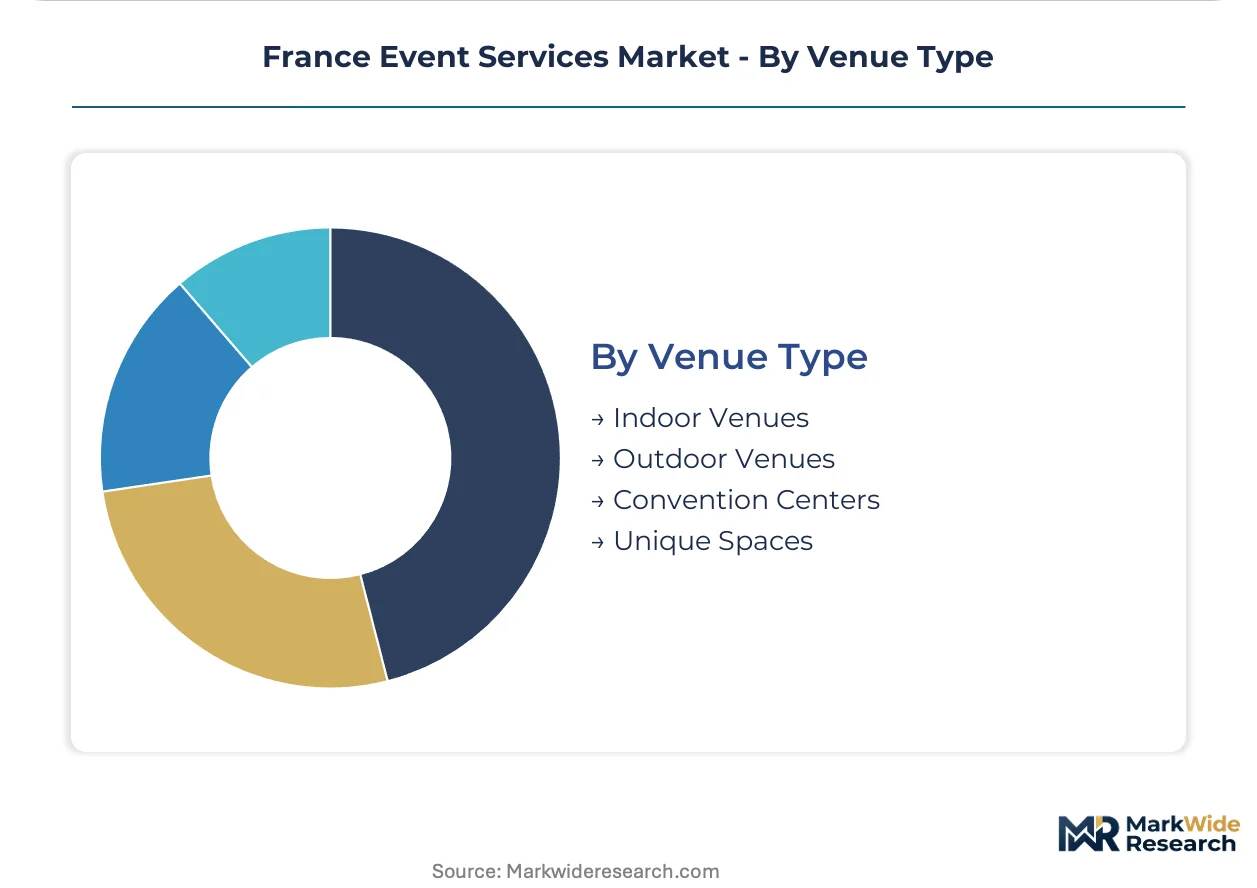
Ownership structures determine margin retention, with fixed-venue operators capturing rental yield and service providers extracting production fees.
- Convention Centers:Purpose-built exhibition halls with integrated electrical distribution and loading dock logistics. GL events leverages venue ownership networks across Lyon and Paris to sustain recurring revenue streams through captive technical service bundling.
- Indoor Venues:Hotel ballrooms and cultural institutions with legacy audiovisual infrastructure from 2015-2019 lacking 4K signal path compatibility. Technical directors maintain dual rental inventory for hybrid events.
- Unique Spaces:Châteaux, museums, and industrial conversions requiring bespoke temporary infrastructure deployment. EU Green Deal mandates for decarbonized temporary structures drive aluminum truss system and LED wall inventory capital requirements.
- Outdoor Venues:Festival grounds and temporary installations with weather contingency and power generation logistics. Reusable staging material costs extend amortization timelines across 7-10 year replacement cycles.
Convention Centers concentrate the contract value while Unique Spaces capture margin expansion from bespoke technical requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France concentrates the highest per-event spend on technical production and compliance documentation, while regional clusters absorb displacement demand through upgraded AV specifications and lower venue premiums.
Île-de-France
Paris corridor venues command premium positioning for pharmaceutical launches and CAC 40 shareholder assemblies under Sapin II third-party oversight mandates. CNIL data governance protocols for attendee biometric tracking add compliance overhead to registration platforms. Venue scarcity compresses event calendars toward modular staging solutions at Paris Expo Porte de Versailles and satellite locations.
Auvergne-Rhône-Alpes
Lyon anchors corporate retreat and incentive travel segments displaced from capital region capacity constraints. GL events leverages venue ownership networks to sustain recurring revenue through captive technical service bundling. Regional operators upgrade lumen output specifications for large-format projection to capture pharmaceutical sector overflow.
Provence-Alpes-Côte d'Azur
Cannes and Nice cluster luxury sector experiential programming with multi-sensory environment requirements for brand activations. EU Green Deal decarbonization targets for temporary structures drive aluminum truss system procurement from regional fabricators. Secondary venue operators bid on annual contracts leveraging amortized LED wall inventory.
Hauts-de-France
Lille absorbs medium-scale corporate displacement with convention center electrical distribution retrofitted for diesel generator elimination. ANSM safety protocols for temporary food service installations open institutional catering adjacent opportunities for hospital and university procurement channels. Regional technical crews mobilize with transport subsidies eroding project margins.
Nouvelle-Aquitaine
Bordeaux wine region châteaux convert to unique space venues requiring bespoke temporary infrastructure for pharmaceutical investigator meetings. After-event content monetization through broadcast-quality capture packages transforms single-day gatherings into multi-week digital assets. Local operators document material lifecycle data for public sector procurement eligibility under EU Green Deal mandates.
France Event Services Market Competitive Landscape
Capability concentration sits with boutique compliance specialists; scale advantage sits with venue-integrated operators. The market structures around three tiers: Paris-Ile-de-France corridor incumbents with Sapin II documentation expertise, regional venue owners bundling captive technical services, and immersive technology integrators serving flagship product launches. Consolidation pressures favor multi-year experiential marketing frameworks over project-by-project vendor selection. Dominant competitive moves include venue network expansion and digital extension service integration.
Within the venue-integrated tier, GL events anchors recurring revenue through ownership networks across Lyon and Paris. Boutique specialists exemplified by Almea Event occupy positions serving CAC 40 programming with high-touch corporate compliance capabilities. At the technology-forward vector, MARS EVENTS represents immersive integration archetypes for multi-sensory product launch environments.
| Leading Market Players |
|---|
| Almea Event |
| WEEVUP |
| INNOV'EVENTS |
| Maison Opale Event |
| MARS EVENTS |
| Gold for Events |
| GL events |
| Happhapp Events |
| Moma-event |
| Others |
Pricing and Supply Chain Analysis
Undercapacity across Paris-Ile-de-France venue infrastructure compresses supplier calendars toward premium positioning, while regional satellite operators absorb displacement demand through aggressive rate competition. This utilization differential fragments pricing power between capital-region incumbents and secondary-market challengers.
Pricing Analysis
Project-based contracts dominate the France Event Services Market, with multi-year experiential marketing frameworks displacing spot procurement among CAC 40 enterprises. Three-tier pricing structure across premium, standard, and economy levels differentiates by Sapin II compliance documentation depth and after-event content capture bundling. Cost compression in mid-scale corporate programming intensifies because regional operators absorb Ile-de-France overflow. Individual consumers driving social gathering professionalization exhibit highest price sensitivity, while pharmaceutical procurement teams under third-party oversight mandates show lowest elasticity.
Supply Chain Analysis
Extended payment terms from venue-integrated operators strain aluminum truss fabricators and LED wall manufacturers concentrated in Germany, Italy, and Spain. Reusable staging material procurement draws from regional metalworking clusters and East Asian display panel suppliers. Single-source vulnerability concentrates in certified rigging labor pools anchored in the capital region. Distribution runs through captive technical service bundling at GL events venues and independent agency subcontractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Event Services Market structures around defensive moats rooted in regulatory entrenchment: Sapin II compliance documentation creates switching costs that cement incumbent relationships with pharmaceutical and luxury sector procurement teams.
For Market Incumbents: Harden venue network control through exclusive technical service bundling at Paris Expo Porte de Versailles and Lyon satellite locations. Deepen backward integration into aluminum truss manufacturing to capture EU Green Deal material lifecycle documentation advantages. Emerging immersive technology integrators threaten flagship product launch margins; counter through broadcast-quality capture package development. For New Entrants and Emerging Players: Establish a beachhead in Bordeaux and Lille corporate retreat segments where Ile-de-France capacity constraints force displacement demand. Target medium-scale pharmaceutical investigator meetings at wine region châteaux requiring bespoke temporary infrastructure. Lead with ANSM-certified mobile kitchen offerings to unlock institutional catering adjacent revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among venue-integrated operators with captive technical service bundling. Long-term viability favors asset-light digital extension service providers over capital-intensive staging inventory holders. Acquisition target archetype: boutique Sapin II compliance specialists with CAC 40 relationship depth. Monitor Paris 2024 legacy infrastructure utilization rates as inflection indicator for venue economics reset.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Network Expansion | GL events leverages Lyon and Paris ownership to capture recurring technical service revenue. |
| Digital Extension Service Integration | Broadcast-quality capture packages transform single-day events into multi-week engagement assets. |
| Regulatory Compliance Certification | ANSM mobile kitchen certification opens hospital and university procurement channels. |
| Sustainable Material Transition | EU Green Deal mandates force aluminum truss system procurement with 7-10 year amortization. |
| Immersive Technology Partnership | Extended reality staging convergence collapses separation between event agencies and broadcast houses. |
Research Methodology
Cross-validation between primary interviews with event agency executives, venue operations directors, pharmaceutical procurement managers, and CNIL compliance officers anchors the qualitative findings. Secondary validation draws from ANSM safety protocol filings, EU Green Deal temporary structure guidelines, Paris Expo Porte de Versailles utilization reports, and CAC 40 annual meeting disclosures. Bottom-up segmentation modeling triangulates against top-down market sizing from service provider revenue aggregation.
Calibration against historical contract velocity patterns and venue capacity utilization rates shapes the analytical framework across the projection horizon. Segmentation dimensions span service type, client procurement sophistication, event size thresholds, and venue ownership structure. CAGRs derive from trend extrapolation of experiential marketing budget reallocation and regulatory compliance spend inflation. Industry-specific inputs include Paris 2024 legacy infrastructure depreciation schedules and Sapin II third-party oversight mandate penetration curves.
Sensitivities concentrate around EU Green Deal decarbonization timeline acceleration, CNIL biometric tracking consent requirement tightening, and regional venue cluster AV specification upgrade rates. Forecasts reflect documented assumptions on corporate event calendar compression and pharmaceutical sector procurement consolidation. Macroeconomic contraction, regulatory rollback, or immersive technology cost collapse would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
Trade Show Services Market
Events and Conferences
India B2B Events Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Germany Event Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
Event Tourism Market
Events and Conferences
GCC Event Management Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
Wedding Services Market