
 India Wedding Services Market | 2026-2036
India Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Wedding Services Market Insights
Market Context with Strategic Players
Capital-intensity divergence between asset-light digital platforms and full-service production houses is bifurcating competitive dynamics across the India wedding services landscape. WedMeGood leverages its vendor marketplace model to sustain national reach without fixed venue commitments. The Wedding Design Company anchors its position through in-house fabrication capabilities and exclusive property partnerships in Delhi and Jaipur. 7X Weddings competes by dominating ultra-high-net-worth destination executions across Udaipur and Goa.
Technical Definition and Structural Segments
India wedding services encompass end-to-end event production spanning logistics coordination, aesthetic design, culinary operations, audiovisual staging, and guest management, typically delivered through bundled packages ranging from single-day ceremonies to week-long celebrations involving 200–2,000 attendees. The sector functions as a coordination-intensive experiential industry where delivery quality depends on real-time supplier orchestration across fragmented local vendor networks. Photography and catering command the deepest margin pools within service type segmentation, given their irreplaceability and limited standardization. Luxury package tiers are expanding fastest as HNI families seek differentiated experiential positioning, while mid-range tiers remain volume-dominant across tier-two and tier-three cities.
Regulatory Framework and Forward Outlook
The GST Council's 18% rate on event management services and variable state-level entertainment taxes create compliance complexity that favors organized players with dedicated finance functions. BIS certification requirements for catering equipment and FSSAI food safety mandates for banquet operations establish baseline quality thresholds that informal vendors struggle to meet. The Ministry of Tourism's Incredible India wedding initiative and state-level heritage property leasing policies are reshaping destination venue access. Stakeholders must monitor evolving state excise policies on liquor permitting and emerging municipal noise ordinances in metropolitan jurisdictions.
Market Dynamics
The GST Council's 18% rate on event management services is compressing vendor margins and forcing a structural pivot toward organized players with dedicated compliance functions. This fiscal pressure is accelerating consolidation across the fragmented vendor ecosystem.
Growth Catalysts
- Heritage Property Leasing Liberalization:Rajasthan and Maharashtra state tourism boards have streamlined lease approvals for palace and fort venues, unlocking inventory previously trapped in bureaucratic clearance cycles.
- Affluent Tier-One Demand Concentration:Mumbai and Delhi high-net-worth families are expanding celebration duration from single-day events to week-long experiential packages, multiplying service touchpoints per booking.
- FSSAI Mandate Enforcement:The food safety regulator's compulsory licensing for banquet operations is disqualifying unorganized caterers and transferring volume to certified kitchen networks.
Market Restraints
- Seasonal Input Cost Volatility:Marigold and jasmine flower prices spike 300-400% during peak wedding season, eroding florist margins and forcing last-minute package renegotiations.
- Udaipur Venue Supply Concentration:Seventy percent of ultra-premium heritage inventory clusters in a single Rajasthan district, creating availability bottlenecks during October-December peak windows.
- Liquor Permitting Friction:State excise departments in Gujarat and Bihar maintain prohibition-era restrictions, eliminating beverage revenue streams that subsidize catering costs elsewhere.
Strategic Opportunities
- Kerala Backwater Undersupply:Houseboat and lakeside venue infrastructure remains underdeveloped relative to aspirational demand from Bangalore and Chennai families seeking alternatives to Rajasthan saturation.
- PLI Scheme Adjacency:Domestic LED and audiovisual equipment manufacturing incentives are reducing rental costs for staging technology, enabling mid-tier planners to offer production values previously reserved for luxury budgets.
- Hybrid Celebration Formats:Livestreaming infrastructure investments during pandemic years created permanent remote attendance capabilities, allowing NRI relatives to participate without travel expenditure compression.
Industry Challenges
- Fabrication Artisan Scarcity:Traditional pandal construction and floral installation skills are aging out as younger workers migrate to manufacturing and gig-economy platforms.
- BIS Certification Timelines:Catering equipment safety testing creates 90-120 day procurement lead times that conflict with compressed booking-to-event cycles common in contemporary planning.
- Vendor Payment Reconciliation:Cash-dominant supplier networks resist digital invoicing, complicating GST input credit claims and inflating effective tax burdens for compliant operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Wedding Services Market |
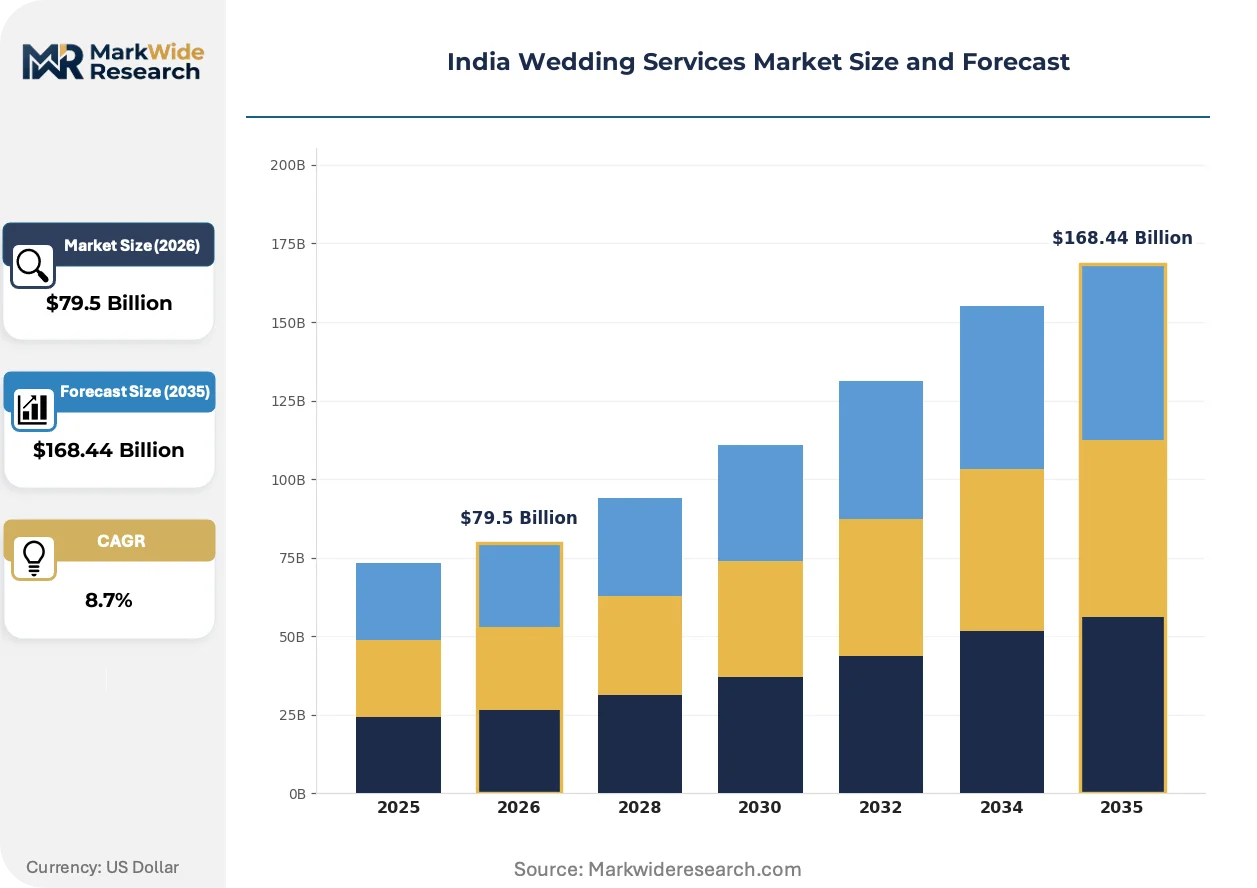
| Market Size in 2026 | $79.5 Billion |
| Market Size in 2035 | $168.44 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Photography, Catering, Decoration, Entertainment Client Type: Couples, Planners, Event Managers, Families Package Tier: Luxury, Mid-Range, Budget, Customized Venue Type: Indoor, Outdoor, Destination, Private |
| Companies Covered | Wedniksha, Weddingz.in, The Wedding Design Company, Devika Narain & Company, WedMeGood, Shaadi Squad, ADDY Events, 7X Weddings, Motwane Entertainment & Weddings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Wedding Services Market Trends and Innovations
Digital coordination tools are restructuring how fragmented vendor networks synchronize execution, replacing phone-based orchestration with real-time workflow platforms. This infrastructure shift is compressing planning timelines and enabling remote oversight of multi-site celebrations.
Drone photography and videography is supplanting traditional crane-mounted camera rigs for aerial coverage of outdoor ceremonies. Affluent families in Udaipur and Goa are mandating drone packages as standard inclusions rather than premium add-ons. This technology is compressing equipment logistics and enabling angles previously requiring helicopter charter expenditure.
FSSAI's 2022 hygiene rating mandate for food businesses is forcing kitchen infrastructure upgrades across the catering segment. The regulation is disqualifying home-based operators from large-format celebrations and transferring volume to centralized cloud kitchen networks. Tier-two cities are experiencing the fastest compliance-driven vendor replacement as enforcement intensifies.
Family procurement committees are fragmenting into specialized sub-groups handling distinct service categories rather than consolidating authority with a single elder coordinator. This diffusion is elongating vendor selection cycles and increasing demand for transparent digital pricing platforms. The pattern is most visible in Mumbai and Delhi where dual-income professional couples assert independent aesthetic preferences.
India Wedding Services Market Segmentation
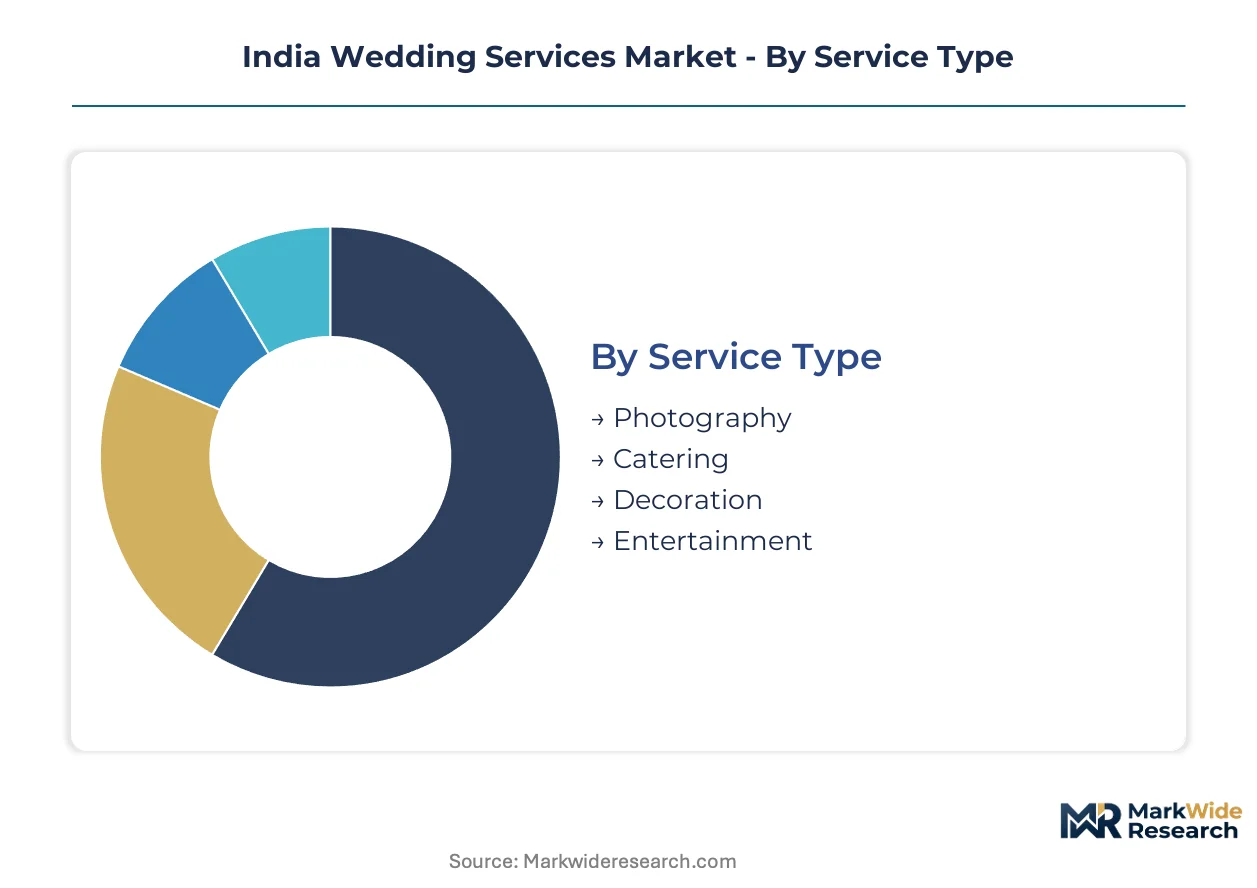
Wedding service procurement in India fragments across four distinct dimensions, each commanding different margin profiles and vendor specialization. Understanding substitution pressures and buyer migration patterns across these categories determines portfolio positioning for organized players.
Service Type:
Photography faces the most acute substitution threat as smartphone imaging quality and guest-generated content displace professional coverage at budget tiers. Catering remains the most defensible against substitution due to FSSAI compliance barriers and irreplaceable kitchen infrastructure.
- Photography:Drone-mounted aerial systems and same-day editing suites now constitute standard deliverables for Rajasthan and Goa destination events. Demand concentrates in Udaipur and Jaipur where heritage backdrops justify premium cinematography packages, though smartphone displacement erodes entry-tier bookings.
- Catering:Centralized cloud kitchen networks with FSSAI hygiene ratings are capturing volume from home-based operators disqualified by 2022 mandate enforcement. Maharashtra and Delhi NCR families prioritize certified vendors for multi-day celebrations with 500+ guest counts.
- Decoration:Fabrication-intensive pandal construction and floral installations depend on aging artisan networks in tier-two cities.
- Entertainment:Livestreaming infrastructure and DJ-led experiences are displacing traditional orchestra arrangements in metropolitan markets.
Catering retains volume leadership; drone-augmented photography holds the steepest expansion curve.
Client Type:
Procurement authority is migrating from unified family elders toward specialized sub-committees, fragmenting vendor selection across multiple decision nodes.
- Couples:Dual-income professionals in Mumbai and Delhi assert independent aesthetic preferences, elongating vendor comparison cycles and demanding transparent digital pricing platforms.
- Families:Multi-generational households in tier-two cities maintain consolidated procurement authority, enabling bundled package negotiations.
- Planners:Full-service production houses in Delhi and Jaipur leverage exclusive property partnerships.
- Event Managers:Independent coordinators face margin compression from GST compliance costs and digital platform disintermediation.
Families dominate transaction volume; couples are gaining share fastest in tier-one metros.
Package Tier:
Cost stratification is sharpening as HNI families seek experiential differentiation while mid-range tiers absorb platform-driven price transparency.
- Luxury:Week-long destination executions across Udaipur and Goa heritage properties command the deepest margin pools through exclusive vendor relationships and white-glove guest management.
- Mid-Range:Tier-two city families in Maharashtra and Gujarat drive volume through standardized 2-3 day packages with modular service add-ons.
- Budget:Single-day ceremonies in tier-three markets face platform-driven price compression.
- Customized:Hybrid formats combining livestreaming with physical attendance are emerging from pandemic infrastructure investments.
Mid-Range captures the widest booking volume; Luxury climbs fastest as destination adoption accelerates.
Venue Type:
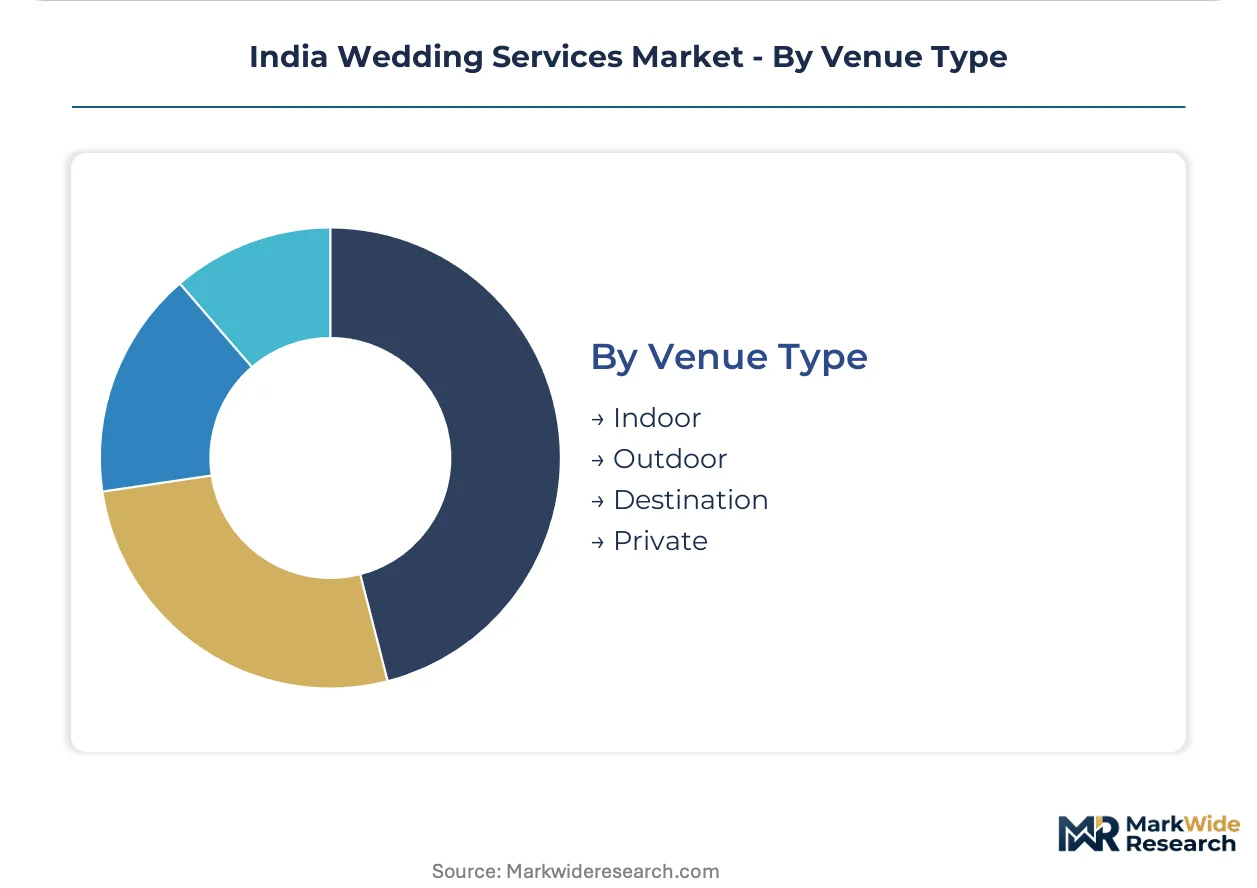
Supply concentration in Rajasthan palace inventory is creating availability bottlenecks that reshape geographic demand flows.
- Destination:Heritage fort and palace venues in Udaipur district command seventy percent of ultra-premium inventory, forcing advance booking windows exceeding 18 months for October-December peaks.
- Outdoor:Beachfront and garden settings in Goa face municipal noise ordinance constraints in metropolitan jurisdictions.
- Indoor:Banquet halls in Delhi NCR and Mumbai remain volume anchors for mid-range celebrations.
- Private:Residence-based events are declining as FSSAI catering mandates disqualify informal kitchen operations.
Indoor venues retain the largest booking base; Destination is expanding most quickly among affluent tier-one families.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
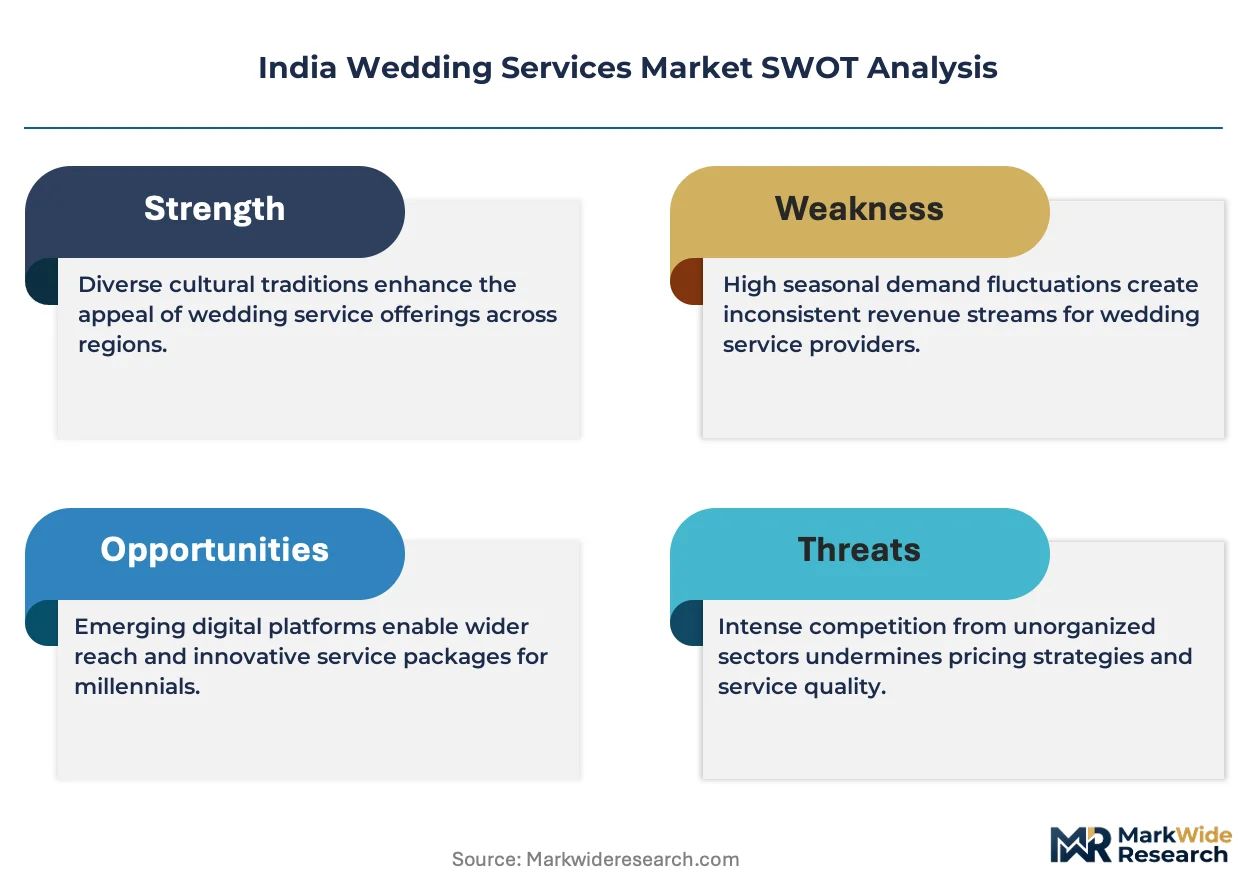
Tier-two city families in Gujarat and Madhya Pradesh demonstrate acute price sensitivity, compressing vendor margins through aggressive package negotiations. Affluent households in Mumbai and Delhi exhibit demand inelasticity, absorbing 40% premiums for heritage destination inventory.
Maharashtra
Mumbai's high-net-worth families drive week-long experiential celebrations multiplying service touchpoints per booking. The state tourism board's streamlined lease approvals for coastal and hinterland venues unlock inventory previously trapped in bureaucratic clearance cycles. Pune and Nashik emerge as secondary hubs where mid-range tier families consolidate procurement authority for bundled negotiations.
Rajasthan
Seventy percent of ultra-premium heritage inventory clusters in Udaipur district, forcing advance booking windows exceeding 18 months for October-December peaks. State-level heritage property leasing policies reshape destination venue access through liberalized long-term lease structures. Jaipur anchors fabrication-intensive pandal construction networks serving Delhi NCR demand migration.
Goa
Beachfront venue infrastructure attracts Bangalore and Hyderabad families seeking alternatives to Rajasthan saturation. Municipal noise ordinances in North Goa constrain outdoor celebration windows and compress viable event dates. Panjim and Margao serve as logistics coordination nodes for multi-site destination executions.
Delhi-NCR
Dual-income professional couples assert independent aesthetic preferences, elongating vendor comparison cycles and demanding transparent digital pricing platforms. The GST Council's 18% rate on event management services compresses margins and accelerates consolidation toward organized players with dedicated compliance functions. Gurgaon and Noida house centralized cloud kitchen networks capturing volume from FSSAI-disqualified informal operators.
Kerala
Houseboat and lakeside venue infrastructure remains underdeveloped relative to aspirational demand from Bangalore and Chennai families. The state's responsible tourism mission imposes carrying capacity limits on backwater celebrations that constrain supply expansion. Kochi and Alappuzha concentrate emerging vendor networks targeting NRI family segments with hybrid livestreaming capabilities.
India Wedding Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the India wedding services landscape. Digital coordination platforms achieve national reach without fixed venue commitments, while full-service production houses anchor positions through exclusive property partnerships and in-house fabrication capabilities. Three strategic archetypes dominate: asset-light marketplace operators, integrated destination specialists, and ultra-high-net-worth execution houses. Consolidation accelerates through vertical acquisition of artisan networks and strategic partnerships with heritage property lessors.
Among asset-light digital platforms, WedMeGood exemplifies the vendor marketplace model achieving scale without fixed infrastructure commitments. The Wedding Design Company occupies a position within the integrated production tier, leveraging exclusive Delhi and Jaipur property partnerships. 7X Weddings anchors the ultra-high-net-worth execution archetype, concentrating on destination celebrations across Udaipur and Goa heritage inventory. These three represent divergent strategic postures toward capital intensity and geographic coverage.
| Leading Market Players |
|---|
| Wedniksha |
| Weddingz.in |
| The Wedding Design Company |
| Devika Narain & Company |
| WedMeGood |
| Shaadi Squad |
| ADDY Events |
| 7X Weddings |
| Motwane Entertainment & Weddings |
| Others |
Pricing and Supply Chain Analysis
FSSAI hygiene rating mandates gate both vendor qualification and price stratification simultaneously, forcing kitchen infrastructure investments that separate certified cloud kitchen networks from disqualified home-based operators while enabling premium positioning for compliant players serving Maharashtra and Delhi NCR celebrations.
Pricing Analysis
After-sales service bundling across multi-day guest management and post-event content delivery drives lifetime value capture in luxury tier bookings. Three-tier pricing structure across premium, standard, and economy levels dominates, with certification grade and celebration duration as primary differentiation drivers. Cost compression in budget tier bookings is intensifying because platform-driven price transparency erodes negotiation leverage. Tier-two city families in Gujarat and Madhya Pradesh exhibit acute price sensitivity, while Mumbai and Delhi high-net-worth households absorb substantial premiums for heritage destination inventory.
Supply Chain Analysis
India and China anchor marigold and jasmine cultivation networks supplying floral installation demand, while domestic artisan clusters in Rajasthan and Uttar Pradesh fabricate pandal construction components. Raw material flows draw from seasonal flower harvests, imported audiovisual equipment, and aging skilled labor pools. Single-source vulnerability concentrates in Udaipur district heritage venue inventory, where seventy percent of ultra-premium properties cluster. Distribution runs through fragmented local vendor networks coordinated by digital platforms and full-service production houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity intensifies as family procurement committees dissolve into specialized sub-groups, creating niche openings for vendors targeting specific service categories rather than bundled packages.
For Market Incumbents: Fortify exclusive property partnerships in Delhi and Jaipur against digital platform disintermediation by deepening in-house fabrication capabilities and securing long-term heritage lease structures. Acquire aging artisan networks in tier-two cities before competitive bidding escalates labor costs. GST compliance complexity favors organized players with dedicated finance functions.
For New Entrants and Emerging Players: Differentiate on Kerala backwater venue infrastructure development, targeting Bangalore and Chennai families seeking alternatives to Rajasthan saturation. Penetrate the hybrid celebration format segment combining livestreaming with physical attendance, leveraging pandemic-era infrastructure investments. Pursue FSSAI certification early to capture volume from disqualified home-based caterers in tier-two cities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across destination specialist archetypes requiring exclusive venue commitments and in-house guest management capabilities. Long-term viability favors integrated production houses with property partnerships over asset-light marketplace operators facing margin compression. Target acquisition archetypes include certified cloud kitchen networks and drone-augmented photography studios. Monitor PLI scheme adjacency for domestic audiovisual equipment manufacturing incentives as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Property Lease Securement | Exclusive Udaipur and Goa venue access locks in eighteen-month advance booking pipelines from affluent tier-one families. |
| FSSAI Certification Investment | Hygiene rating compliance disqualifies informal competitors and transfers volume to certified kitchen networks in Maharashtra. |
| Drone Photography Capability Buildout | Aerial coverage packages displace crane-mounted rigs and command standard inclusion status in Rajasthan destination bookings. |
| Artisan Network Acquisition | Backward integration into pandal construction skills mitigates aging workforce migration to manufacturing sectors. |
| Livestreaming Infrastructure Retention | Hybrid format capabilities sustain NRI relative participation without travel expenditure compression post-pandemic. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with wedding planners, heritage property lessors, catering operations directors, and FSSAI compliance officers; and secondary validation through Ministry of Tourism policy documents, state excise department filings, GST Council circulars, and heritage property leasing records. Bottom-up vendor capacity assessments triangulated against top-down celebration spending pattern analysis.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service type, client procurement authority structure, package tier, and venue geography. CAGRs derived from historical booking volume trajectories and aspirational demand migration patterns. Forecast inputs incorporated seasonal flower price volatility curves and heritage venue availability bottlenecks.
Decision-makers should treat outputs as directional under sustained GST rate stability and FSSAI enforcement intensity assumptions; material deviation in regulatory posture or input cost spikes would warrant model refresh. Recalibration cycles align with material shifts in state-level heritage leasing policies and municipal noise ordinance evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Asia-Pacific Wedding Services Market
Events and Conferences
Canada Event Services Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Spain Event Services Market
Events and Conferences
China Wedding Services Market
Events and Conferences
Italy Event Services Market
Events and Conferences
Trade Show Services Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Corporate Event Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
North America Event Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
MICE Market
Events and Conferences
Event Tourism Market