
 Europe Event Logistics Market | 2026-2036
Europe Event Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Event Logistics Market Insights
Market Context
The capability gap between asset-heavy integrators and broker-dependent operators is rotating competitive advantage toward firms with owned European road networks and dedicated event warehouses. Deutsche Post DHL Group leverages its pan-European parcel infrastructure to offer last-mile precision for time-critical exhibition builds. Kuehne + Nagel anchors its position through controlled air and ocean freight corridors feeding into Rotterdam and Hamburg for inbound event cargo. DB Schenker competes on rail-modal flexibility, moving oversized stage equipment across borders with lower carbon intensity than pure trucking.
Technical Definition and Structural Segments
Europe event logistics encompasses the specialized planning, transportation, warehousing, and on-site coordination of temporary physical assets—stage systems, modular furniture, audio-visual rigs, and catering infrastructure—required for time-bound gatherings, with strict adherence to venue access windows and build-break schedules measured in hours rather than days. Transportation services command the largest revenue pool given the fragmentation of European road regulations and cross-border permit complexity, while event management software represents the fastest-expanding margin segment as clients demand real-time visibility into multi-vendor coordination. Trade shows generate the most concentrated end-user demand due to their predictable calendar cycles and high-value freight density, whereas corporate events offer premium pricing but irregular volume patterns.
Regulatory Framework
The EU Green Deal and accompanying CSRD disclosure mandates compel event logistics providers to document Scope 3 emissions across subcontractor fleets, reshaping procurement criteria for major exhibition organizers in Brussels, Paris, and Milan. Germany's KBA enforces strict commercial vehicle weight and safety standards that limit equipment trailer configurations, while REACH chemicals regulations govern the temporary flooring, adhesives, and coatings deployed at European venues. Stakeholders must monitor how the EU AI Act's risk classification rules will constrain automated routing and predictive demand algorithms in event planning software.
Market Dynamics
The EU Green Deal's carbon disclosure mandates are compressing competitive timelines for logistics providers, forcing rapid fleet electrification and Scope 3 documentation systems that separate asset-heavy operators from broker-dependent competitors.
Growth Catalysts
- CSRD Mandates:Corporate Sustainability Reporting Directive requirements are compelling exhibition organizers in Brussels, Paris, and Milan to select logistics partners with verified emissions tracking, creating procurement preference for providers with electric vehicle fleets.
- Trade Show Density:Germany's exhibition corridor around Messe Frankfurt and Messe München generates concentrated demand for integrated venue-to-stand delivery systems with predictable calendar cycles.
- Real-Time Visibility Platforms:Event management software with multi-vendor coordination dashboards is capturing premium pricing from corporate planners managing complex build-break schedules.
Market Restraints
- Diesel Price Volatility:Fuel cost swings compress margins for road freight operators serving time-critical exhibition builds where routing flexibility is limited.
- Permit Fragmentation:Cross-border commercial vehicle regulations across EU member states create administrative friction for oversized stage equipment movements.
- REACH Compliance Costs:Chemicals regulations governing temporary flooring, adhesives, and coatings at European venues impose testing and documentation burdens on inventory management.
Strategic Opportunities
- Eastern European Expansion:Underdeveloped event infrastructure in Poland and Czech Republic offers first-mover advantage for warehouse networks serving emerging trade fair venues.
- Rail-Modal Integration:DB Schenker's demonstrated model for moving oversized equipment across borders with lower carbon intensity than pure trucking can be replicated on underutilized European rail corridors.
- EU AI Act Positioning:Early compliance with risk classification rules for automated routing algorithms will secure preferred vendor status with risk-averse corporate event planners.
Industry Challenges
- Electrification Capex Burden:Fleet conversion to electric commercial vehicles requires substantial capital deployment while charging infrastructure remains sparse at rural exhibition venues.
- Multi-Vendor Integration Complexity:Corporate clients demand seamless coordination across freight, warehousing, and on-site installation contractors with incompatible legacy IT systems.
Report Scope
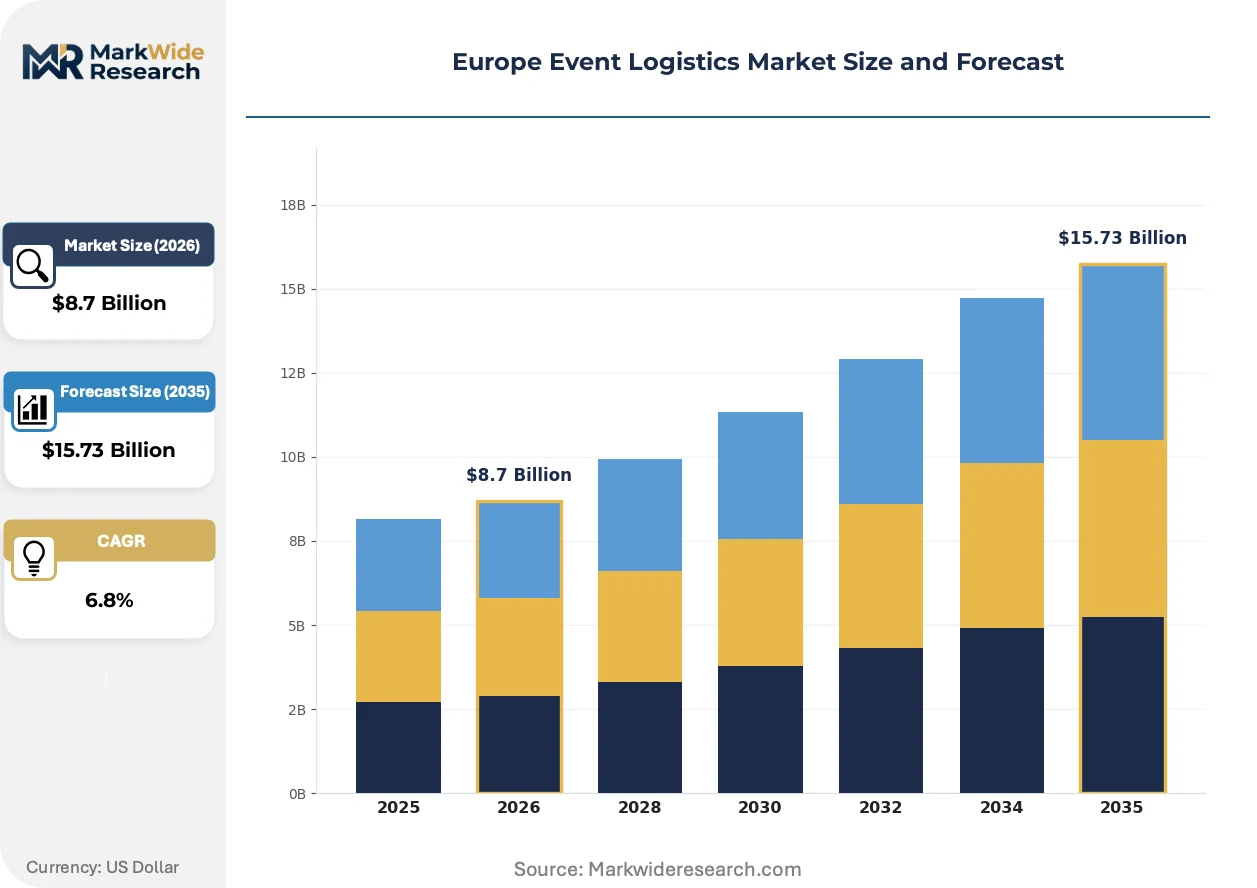
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Event Logistics Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Supplier Coordination, Venue Management, On-site Support End User: Corporate Events, Trade Shows, Concerts, Sporting Events Technology: Event Management Software, Audio-Visual Solutions, Registration Platforms, Tracking Systems Product Type: Furniture Rentals, Stage Equipment, Signage, Catering Supplies |
| Companies Covered | DB Schenker, Deutsche Post DHL Group, DSV, C.H. Robinson, Dachser, Kuehne + Nagel, CEVA Logistics, GEODIS, Rhenus Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Event Logistics Market Trends and Innovations
Digital coordination platforms and emissions accountability systems are restructuring how exhibition cargo moves across European borders, compressing the advantage window for traditional broker networks.
Blockchain-enabled cargo documentation is displacing paper-based customs clearance and proof-of-delivery workflows. Major trade fair operators in Germany and the Netherlands are piloting distributed ledger systems for high-value audio-visual equipment chains. This technology is displacing notary and courier intermediaries that previously handled cross-border certification.
EU AI Act risk classification rules are constraining automated routing algorithms in event planning software. Logistics providers must now document human oversight protocols for predictive demand systems. Exhibition software vendors in France and Belgium are restructuring development roadmaps to accommodate prohibited AI practices in high-risk categorization.
Corporate event planners are consolidating vendor relationships around outcome-based contracts with guaranteed build-completion windows. This model replaces hourly labor billing with fixed-fee performance agreements. The shift is most visible in the UK and German corporate event segments where procurement departments prioritize budget certainty over line-item transparency.
Europe Event Logistics Market Segmentation
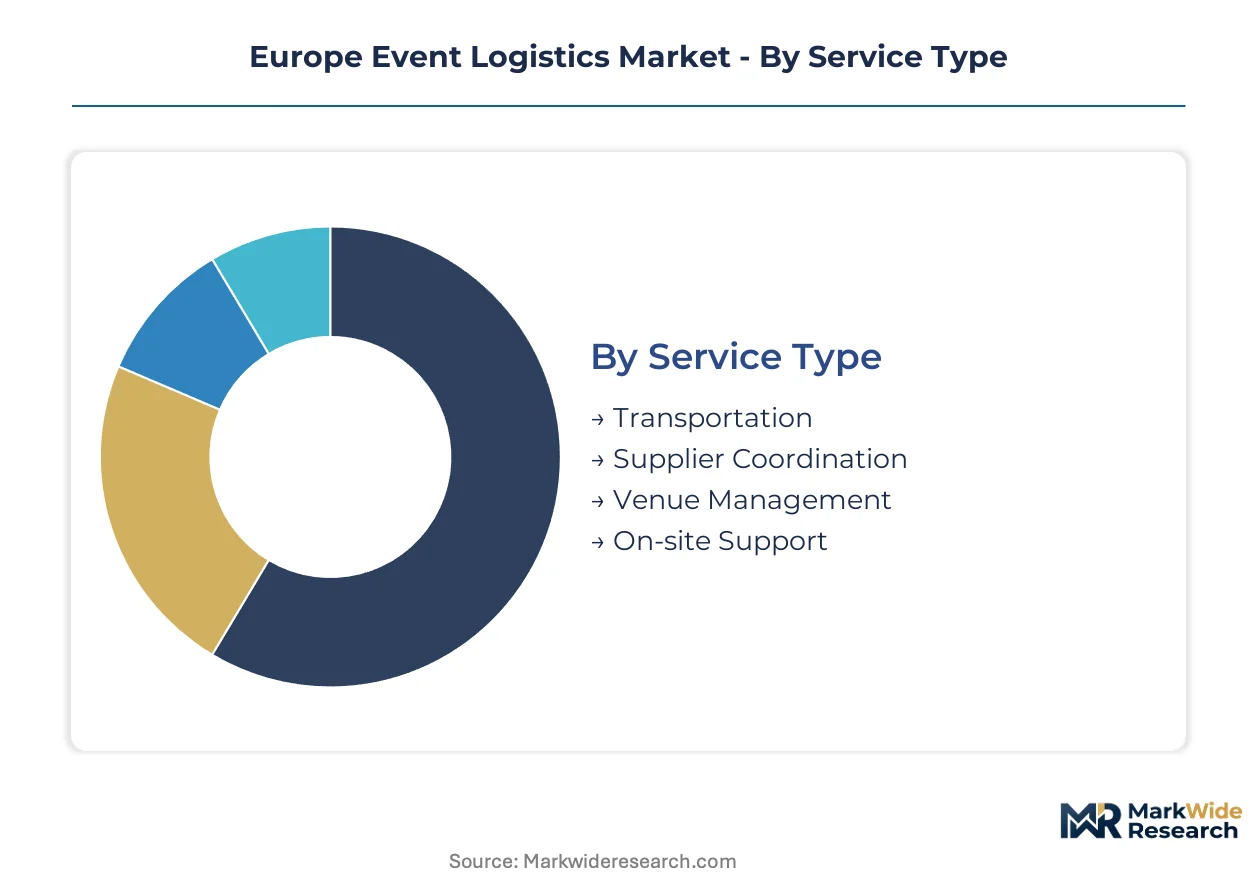
Europe event logistics providers structure service portfolios around distinct margin profiles, with transportation and software commanding premium pricing while physical rentals face commoditization. Segmentation reveals where asset-heavy operators extract value versus where broker networks compete on coverage breadth.
Service Type:
Transportation services capture the deepest margin pools given cross-border permit complexity and time-critical delivery windows that limit price competition.
- Transportation:Specialized freight for oversized stage systems and modular infrastructure across European road networks. Demand concentrates around Germany's exhibition corridor—Messe Frankfurt and Messe München—where venue access windows measured in hours create premium pricing power for owned-fleet operators.
- Supplier Coordination:Multi-vendor orchestration of freight, warehousing, and on-site installation contractors. Corporate planners in Brussels and Paris are consolidating procurement around outcome-based contracts with guaranteed build-completion windows, shifting revenue from hourly billing to fixed-fee performance agreements.
- Venue Management:Integrated warehouse-to-stand logistics controlling inventory flow within exhibition grounds. REACH compliance costs for temporary flooring and adhesives elevate operational complexity at major venues.
- On-site Support:Labor deployment for build-break schedules requiring precise coordination with venue technical crews. Irregular volume patterns compress margins compared to predictable trade show cycles.
Transportation holds installed capacity. Supplier Coordination is rotating up the share rankings.
End User:
Application concentration determines pricing architecture, with trade show density enabling scale economies that corporate events cannot replicate.
- Trade Shows:Predictable calendar cycles and high-value freight density generate the most concentrated demand. Germany's KBA commercial vehicle standards and the EU Green Deal's CSRD mandates are reshaping procurement criteria toward providers with verified emissions tracking and electric vehicle fleets.
- Corporate Events:Premium pricing potential offset by irregular volume patterns and fragmented decision-making across departmental budgets. UK and German procurement departments prioritize budget certainty, accelerating vendor consolidation.
- Concerts:Time-critical touring schedules demanding rapid load-in/load-out capabilities across multiple European cities. Rail-modal flexibility from operators like DB Schenker offers carbon advantage over pure trucking.
- Sporting Events:Single-occasion mega-projects with extreme peak capacity requirements. Eastern European expansion into Poland and Czech Republic offers first-mover positioning for emerging venue infrastructure.
Trade Shows anchor volume concentration. Corporate Events are climbing the fastest on margin contribution.
Technology:
Software layers command expanding margin share as real-time visibility becomes non-negotiable for complex multi-vendor coordination.
- Event Management Software:Multi-vendor coordination dashboards capturing premium pricing from planners managing compressed build-break schedules. EU AI Act risk classification rules now constrain automated routing algorithms, requiring documented human oversight protocols.
- Audio-Visual Solutions:Technical infrastructure for immersive presentation environments. Blockchain-enabled cargo documentation is displacing paper-based workflows for high-value equipment chains in Germany and the Netherlands.
- Registration Platforms:Attendee data management with GDPR compliance architecture. Integration friction with legacy freight IT systems limits deployment velocity.
- Tracking Systems:Real-time location visibility for time-critical exhibition builds. Diesel price volatility pressures hardware deployment economics for rural venue coverage.
Event Management Software owns the technology margin pool. Tracking Systems are gaining share fastest on electrification investment requirements.
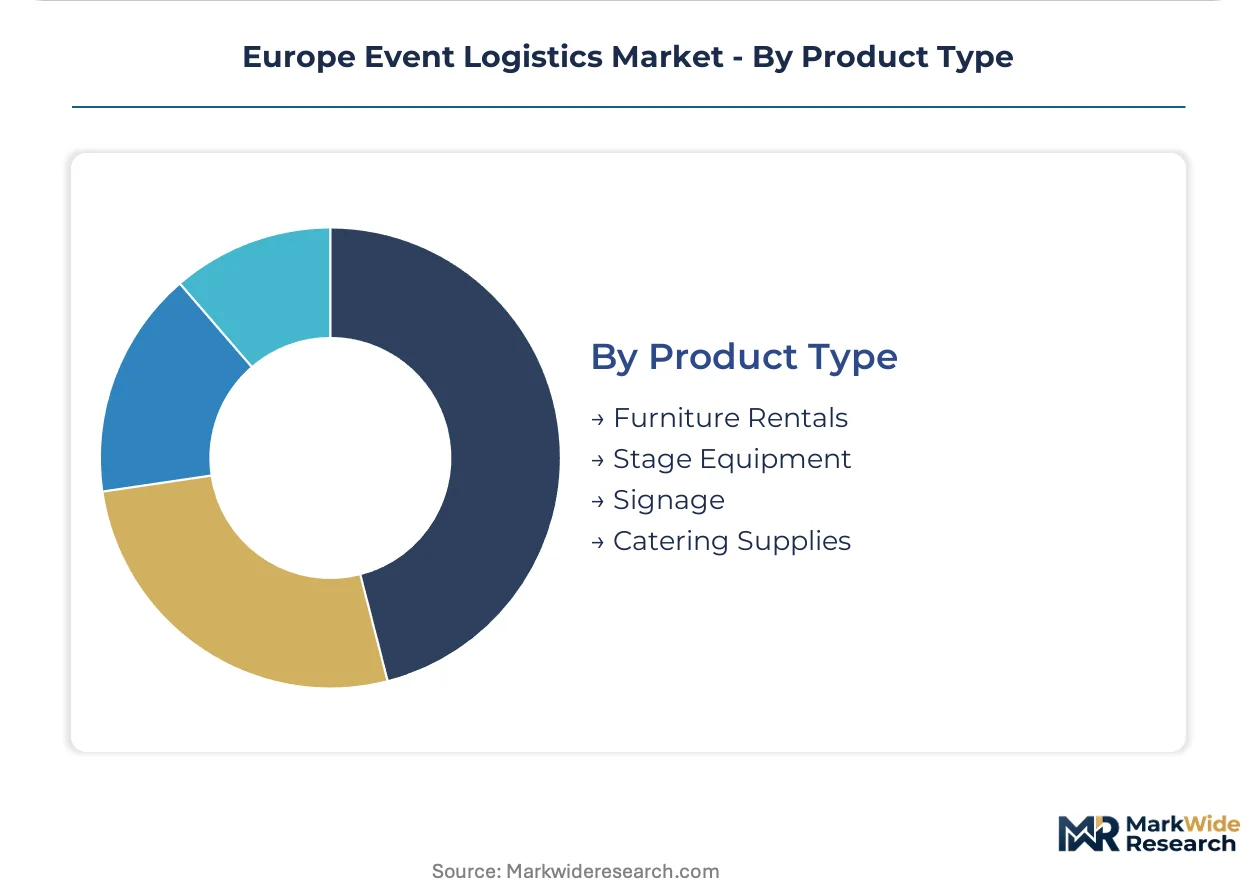
Product Type:
Physical asset rental tiers separate on depreciation velocity and inventory specificity, with stage equipment retaining value longest.
- Stage Equipment:Modular rigging and structural systems with multi-event reuse cycles. Oversized dimensions trigger Germany's KBA weight and safety configuration limits, favoring specialized trailer operators.
- Furniture Rentals:High-turnover inventory facing commoditization pressure from local suppliers. Eastern European warehouse networks offer cost arbitrage for emerging trade fair venues.
- Signage:Temporary branding infrastructure with rapid customization requirements. REACH chemicals regulations govern coatings and adhesives, imposing testing documentation burdens.
- Catering Supplies:Perishable-adjacent logistics with strict hygiene and temperature protocols. Lowest margin pool due to local sourcing preferences and short rental windows.
Stage Equipment commands asset durability. Furniture Rentals are rotating up on Eastern European demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's exhibition corridor consumes event logistics services through integrated venue-to-stand delivery systems, while the UK and France prioritize outcome-based procurement with guaranteed build-completion windows.
Germany
Messe Frankfurt and Messe München generate concentrated demand for time-critical freight services with venue access windows measured in hours. The KBA enforces strict commercial vehicle weight configurations that limit oversized stage equipment trailer designs. Bavaria's logistics clusters around Munich anchor specialized warehouse networks serving predictable trade show calendar cycles.
United Kingdom
Corporate procurement departments in London prioritize budget certainty through fixed-fee performance agreements replacing hourly labor billing. GDPR compliance architecture constrains attendee data management integration with legacy freight IT systems. The Southeast England corridor concentrates demand for real-time visibility platforms managing complex multi-vendor coordination.
France
Exhibition organizers in Paris select logistics partners based on verified Scope 3 emissions tracking under CSRD mandates. The EU AI Act's risk classification rules constrain automated routing algorithms in event planning software developed by French vendors. Île-de-France hosts the densest concentration of corporate event planners consolidating vendor relationships around guaranteed build-completion windows.
Netherlands
Rotterdam and Amsterdam serve as inbound air and ocean freight corridors feeding European exhibition cargo. Blockchain-enabled cargo documentation pilots for high-value audio-visual equipment chains concentrate in Dutch trade fair operations. REACH chemicals regulations governing temporary flooring and adhesives elevate operational complexity at Amsterdam RAI and Jaarbeurs Utrecht venues.
Poland
Emerging trade fair venues in Warsaw and Kraków offer first-mover positioning for warehouse networks serving underdeveloped event infrastructure. Eastern European expansion attracts cost arbitrage for furniture rental inventory facing commoditization pressure elsewhere. The country's central location enables rail-modal integration for oversized equipment movements across borders with lower carbon intensity than pure trucking.
Europe Event Logistics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with asset-heavy operators extracting premium pricing from time-critical exhibition builds while broker-dependent competitors compete on geographic coverage breadth. The capability gap between owned-fleet networks and subcontractor-reliant models is rotating procurement preference toward firms with controlled European road infrastructure and dedicated event warehouses. Two strategic archetypes dominate: pan-European integrators leveraging parcel infrastructure for last-mile precision, and rail-modal specialists competing on carbon intensity advantages. Competitive dynamics center on fleet electrification pace and multi-vendor software integration capabilities.
Within the integrated logistics tier, Deutsche Post DHL Group and Kuehne + Nagel occupy positions exemplifying divergent infrastructure strategies. Deutsche Post DHL Group leverages its controlled parcel network for compressed delivery windows at German exhibition hubs. Kuehne + Nagel anchors its presence through managed air and ocean corridors feeding Rotterdam and Hamburg. DB Schenker represents the rail-modal archetype, demonstrating carbon-efficient border-crossing capabilities for oversized stage equipment movements.
| Leading Market Players |
|---|
| DB Schenker |
| Deutsche Post DHL Group |
| DSV |
| C.H. Robinson |
| Dachser |
| Kuehne + Nagel |
| CEVA Logistics |
| GEODIS |
| Rhenus Group |
| Others |
Pricing and Supply Chain Analysis
Germany's exhibition corridor scale economies around Messe Frankfurt and Messe München compress per-unit logistics costs while elevating price floors for time-critical venue access windows. Asset-heavy operators with owned-fleet networks extract premium pricing from compressed build-break schedules, whereas broker-dependent competitors compete on geographic coverage at thinner margins.
Pricing Analysis
After-sales service contracts and extended warranty tiers for event management software drive lifetime value expansion beyond initial platform licensing. Three-tier pricing structure across premium, standard, and economy levels segments buyers by integration complexity and real-time visibility requirements. Cost compression in standard-tier freight brokerage is intensifying because diesel price volatility and permit fragmentation squeeze subcontractor margins. Corporate procurement departments in London and Paris exhibit lowest price sensitivity, prioritizing guaranteed build-completion windows over line-item transparency, while emerging trade fair venues in Eastern Europe drive hardest bargain negotiations.
Supply Chain Analysis
Germany and the Netherlands anchor specialized warehouse networks and inbound freight corridors feeding European exhibition cargo. Stage equipment fabrication draws from steel processing clusters in Poland and Italy, while electric vehicle fleet components source from battery assembly operations in Hungary and Czech Republic. Single-source vulnerability concentrates in Germany's KBA-certified trailer configurations for oversized rigging systems. Distribution runs through controlled road networks with venue-to-stand integration, compressing last-mile coordination into consolidated operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement departments in UK and German corporate segments, fragmenting vendor relationships as planners prioritize outcome-based contracts with guaranteed build-completion windows over hourly billing transparency.
For Market Incumbents: Shield margin position by accelerating electric vehicle fleet deployment ahead of CSRD disclosure mandates, creating procurement preference separation from broker-dependent competitors. Deepen backward integration into dedicated event warehousing around Bavaria's logistics clusters, capturing venue-to-stand coordination revenue that subcontractor networks cannot replicate. Counter rail-modal carbon efficiency advantages from DB Schenker by investing in multi-vendor software integration capabilities that corporate planners increasingly demand. For New Entrants and Emerging Players: EU AI Act compliance fast-track for event planning software with documented human oversight protocols opens preferred vendor positioning with risk-averse corporate planners in Brussels and Paris. Target underdeveloped trade fair infrastructure in Poland and Czech Republic for warehouse network establishment, capturing cost arbitrage on furniture rental inventory before asset-heavy incumbents extend coverage. Lead go-to-market through rail-modal integration partnerships, leveraging lower carbon intensity credentials against pure trucking competitors in sustainability-conscious procurement evaluations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-enabled logistics operators with multi-vendor coordination platforms over pure asset-heavy freight incumbents. Long-term viability across the projection horizon rests on electrification capex deployment pace and Scope 3 documentation system maturity. Acquisition target archetype: specialized event warehouse networks in Germany's exhibition corridor with integrated venue access relationships. Signal to watch: CSRD procurement preference shifts among Milan and Paris exhibition organizers toward verified emissions tracking capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Program | CSRD disclosure mandates from Brussels and Paris exhibition organizers elevate electric vehicle procurement preference. |
| Rail-Modal Integration Partnership | DB Schenker's carbon-efficient border-crossing model replicates across underutilized European corridors for oversized equipment. |
| Multi-Vendor Software Platform | Real-time visibility dashboards capture premium pricing from corporate planners managing compressed build-break schedules. |
| Eastern European Warehouse Expansion | Poland and Czech Republic emerging venues offer first-mover positioning before incumbent network saturation. |
| EU AI Act Compliance Certification | Documented human oversight protocols for automated routing secure preferred vendor status with risk-averse planners. |
Research Methodology
Initial hypotheses were tested against primary input from corporate event planners, exhibition organizers, logistics procurement officers, and fleet operations managers and refined through secondary validation across customs records, EU regulatory filings, trade association data, and venue operator disclosures. Bottom-up modeling of transportation, software, and rental revenue pools triangulated against top-down market sizing from exhibition industry association statistics.
Variance decomposition across service type, end user, technology, and product type dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory modeling incorporated electrification investment cycles, CSRD compliance adoption curves, and rail-modal capacity expansion patterns. Forecast inputs included venue access window compression trends, REACH chemicals testing documentation burdens, and blockchain cargo documentation pilot scalability from Dutch and German trade fair operators.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, stable diesel-electric vehicle cost parity progression, or predictable trade show calendar cycles would require recalibration. Forecasts reflect documented assumptions regarding fleet conversion timelines, software adoption rates, and Eastern European venue development velocity. Recalibration cycles align with material shifts in CSRD procurement mandate implementation, EU AI Act enforcement precedence, and rail infrastructure investment commitments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Canada Event Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
MICE Market
Events and Conferences
India B2B Events Market
Events and Conferences
Global Event Management Service Market
Events and Conferences
Event Tourism Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
India Wedding Services Market
Events and Conferences
Wedding Services Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
North America Wedding Services Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
GCC Event Management Market
Events and Conferences
Event Management Solutions Market