
 Wedding Services Market | 2026-2036
Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
Wedding Services Market Analysis
The EU Green Deal is pivoting European venue operators toward carbon-neutral certification requirements for event hosting. The Knot Worldwide leverages its digital platform dominance to control vendor discovery workflows across North America. David's Bridal anchors bridal retail with in-house alteration services that sustain repeat appointment traffic. Zola competes through integrated registry-planning tools that extend customer lifetime value beyond the ceremony date.
Wedding services encompass the coordinated delivery of ceremonial and celebratory functions, including venue provision, food preparation, image capture, and live performance management, typically executed through fixed-duration contracts with defined guest counts and service-level specifications. The primary commercial purpose centers on reducing coordination friction for time-constrained couples while standardizing quality expectations across fragmented local vendor markets. Venue and catering segments occupy the largest revenue pools given their fixed-capacity constraints and premium pricing power during peak seasonal windows. Photography and entertainment categories represent faster-growing margin opportunities as social media output requirements intensify content production demands.
The US Federal Trade Commission monitors wedding vendor advertising claims under consumer protection statutes, while the EU's GDPR framework constrains how European planning platforms process couple and guest data across marketing touchpoints. India's Consumer Protection Act empowers the country's national consumer disputes commission to adjudicate service failures in the wedding sector, creating compliance obligations for multi-day package providers. Stakeholders must monitor how AI-generated vendor matching algorithms reshape discovery economics and whether regulatory scrutiny of automated pricing systems follows similar patterns established in adjacent hospitality markets.
Market Dynamics
Destination wedding planners are consolidating demand for experiential multi-day celebrations, compressing traditional vendor fragmentation into curated package ecosystems that reshape commission structures across photography, catering, and venue segments.
Growth Catalysts
- Social Media Content Mandates:Instagram and TikTok algorithmic visibility requirements drive couples to prioritize videography and drone capture services, expanding per-wedding production budgets.
- EU Green Deal Certification:Carbon-neutral venue mandates across European Union member states create compliance-driven upgrade cycles for historic estates and barn conversions.
- India's Multi-Day Ceremonial Intensity:Regional traditions spanning 3-7 days sustain elevated service density per event, with separate vendor teams for mehndi, sangeet, and reception functions.
Market Restraints
- Peak Season Capacity Constraints:Fixed venue and catering infrastructure limits revenue capture to 16-20 high-demand weekends annually, compressing margin recovery windows.
- Floral Supply Volatility:Import-dependent rose and peony sourcing from Ecuador and Netherlands exposes decorators to freight cost spikes and climate-driven harvest variability.
- GDPR Data Processing Friction:European planning platforms face consent-layer complexity when managing guest RSVP flows and vendor data sharing across marketing touchpoints.
Strategic Opportunities
- AI-Driven Vendor Matching:Machine learning algorithms trained on couple preference data and past event outcomes are decentralizing discovery away from directory-style platforms toward predictive curation.
- Micro-Wedding Specialization:Sub-50 guest events in Portugal and Greece offer margin-rich alternatives to large-scale domestic celebrations, with lower coordination overhead per dollar.
- Integrated Registry-Planning Convergence:Digital platforms combining gift registry, budget tracking, and vendor booking extend customer lifetime value 18-24 months pre-ceremony.
Industry Challenges
- Specialized Coordinator Talent Scarcity:Destination logistics expertise and multilingual ceremony management skills command 40-60% wage premiums above general event planning rates.
- Legacy Booking System Integration:Venue management software from 2010-2015 era lacks API connectivity with modern payment processing and guest communication tools, forcing manual workflow bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wedding Services Market |
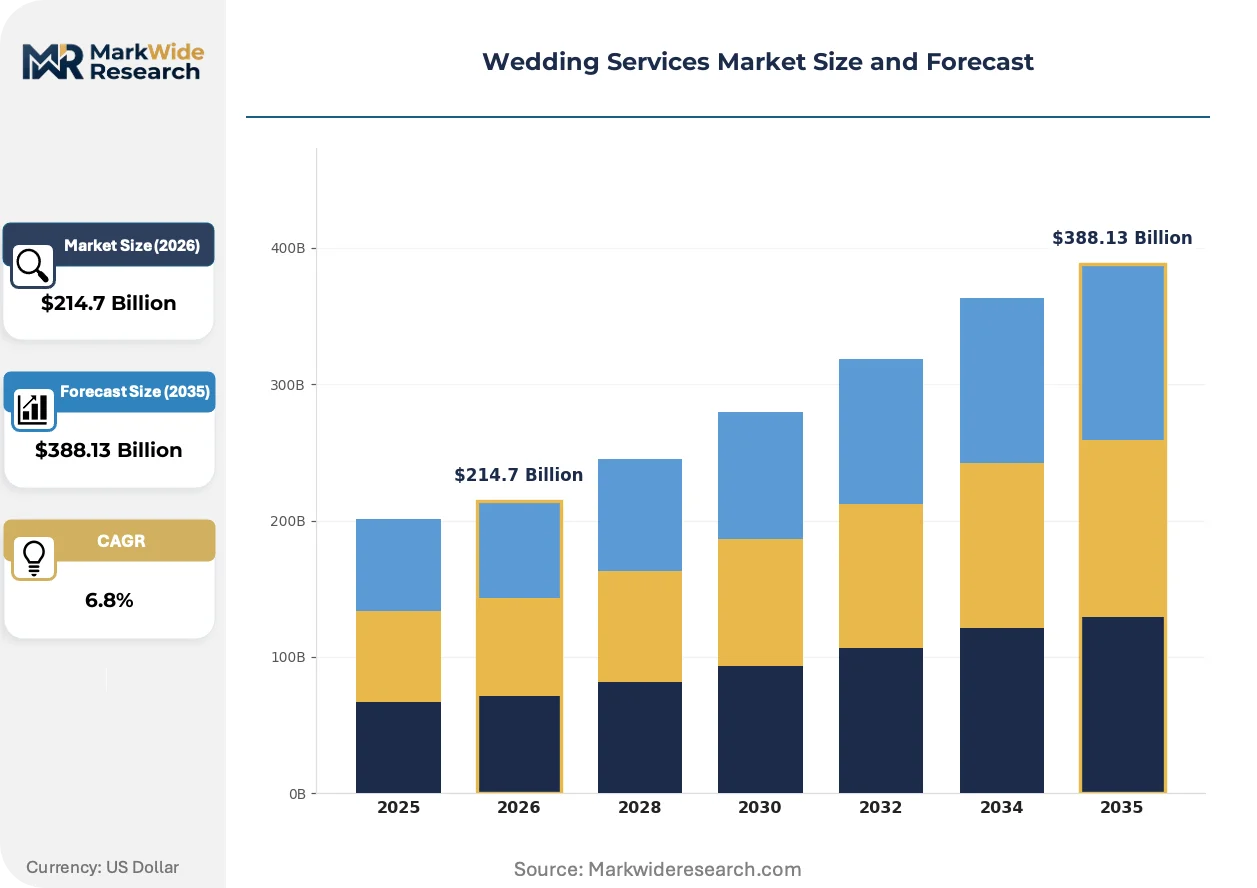
| Market Size in 2026 | $214.7 Billion |
| Market Size in 2035 | $388.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Venue, Catering, Photography, Entertainment Customer Type: Couples, Event Planners, Families, Friends Package Type: All-Inclusive, Customizable, Budget, Luxury Technology: Wedding Apps, Online Planning Tools, Virtual Tours, Payment Solutions |
| Companies Covered | The Knot Worldwide, Zola, WeddingWire, XO Group, David's Bridal, The Dockside Group, Easy Weddings, Zankyou, Style Me Pretty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wedding Services Market Emerging Trajectories
Artificial intelligence and immersive media technologies are restructuring how couples discover, visualize, and purchase wedding services, shifting competitive advantage from local reputation to data-driven personalization engines.
Generative AI moodboarding tools are decentralizing the design consultation process by enabling couples to produce photorealistic venue visualizations without iterative in-person meetings. High-income millennial buyers in California and New York are adopting these platforms 3-4x faster than national averages. The technology is compressing traditional florist and decorator discovery timelines from 8-12 weeks to 2-3 weeks, forcing vendors to front-load portfolio differentiation.
The EU AI Act's risk classification framework for automated decision-making systems is imposing algorithmic transparency requirements on European vendor-matching platforms. Planning services operating across Germany, France, and Italy must now document how recommendation engines weight price, availability, and style compatibility. Mid-sized platform operators are responding by hiring dedicated AI governance roles and publishing simplified explanation interfaces for couples.
Subscription-based planning assistance is displacing commission-only coordinator relationships in urban markets. Couples in London, Toronto, and Sydney now pay monthly retainers for ongoing vendor negotiation and timeline management rather than single-event fees. This model concentrates recurring revenue with planning boutiques that can sustain 12-18 month engagement cycles, squeezing transaction-dependent competitors.
Wedding Services Market Segmentation
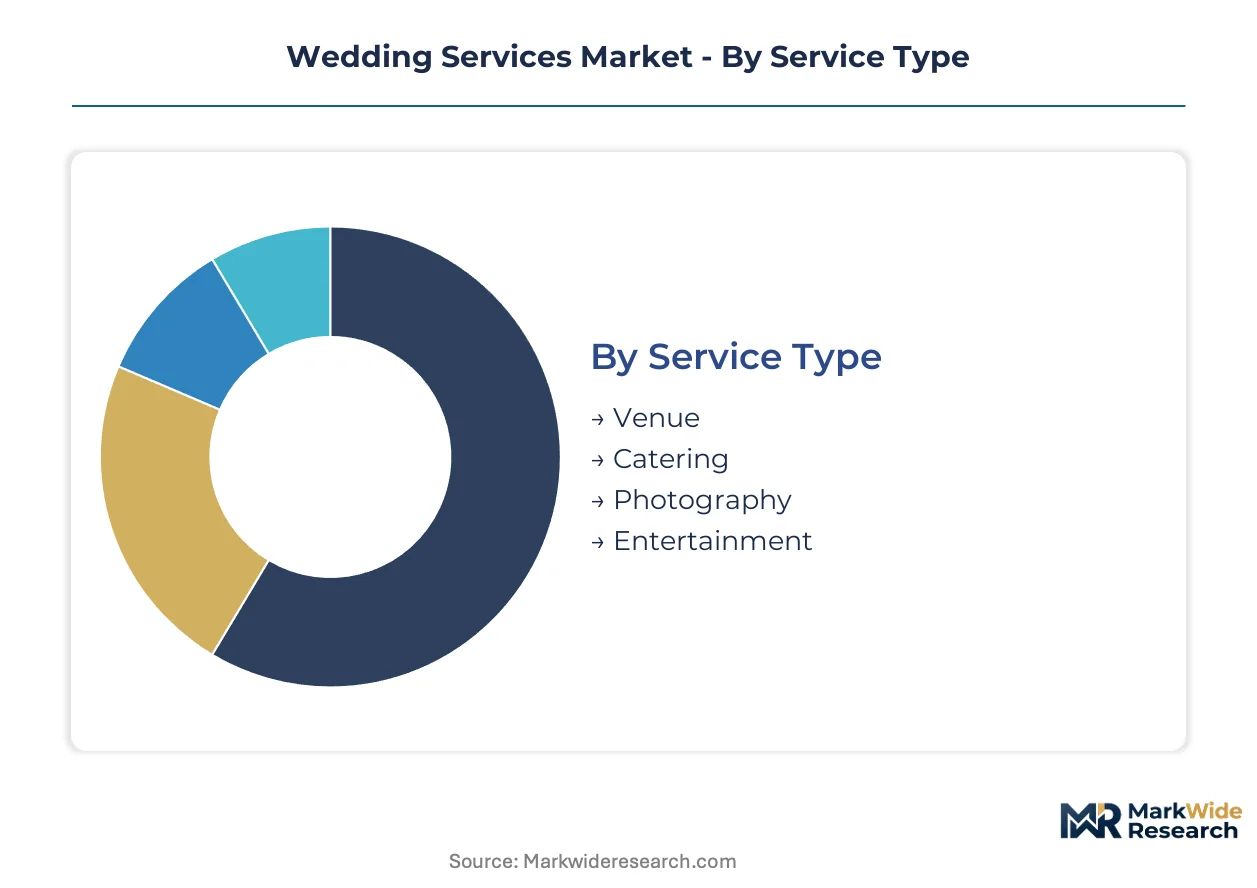
Wedding services segmentation reveals distinct procurement behaviors across service delivery modes and customer archetypes. Understanding these divides enables vendors to align capacity planning with margin profiles and seasonal demand concentration.
Service Type:
Venue and catering command the largest revenue pools through fixed-capacity scarcity, while photography and entertainment capture expanding margins from social media content mandates.
- Venue:Historic estates, barn conversions, and hotel ballrooms provide physical infrastructure with seasonal pricing power. India's multi-day ceremonial traditions sustain 3-7 day booking intensity per wedding, compressing available inventory.
- Catering:Multi-course plated service and buffet configurations dominate, with regional cuisine specialization commanding premiums in Indian and Middle Eastern celebrations. EU Green Deal carbon-neutral certification requirements are forcing kitchen equipment upgrades across European operators.
- Photography:Hybrid coverage teams combining still capture with cinematic videography.
- Entertainment:Live bands, DJs, and cultural performance troupes.
Mature deployment sits with venue and catering infrastructure. Newer deployment is concentrated in drone capture and same-day edit videography services.
Customer Type:
Procurement authority fragments across direct couple spending and intermediary-managed budgets, with destination wedding planners consolidating vendor selection power fastest.
- Couples:Direct purchasers prioritizing aesthetic alignment and social media output quality. High-income millennials in California and New York adopt AI moodboarding tools 3-4x faster than national averages, compressing discovery timelines.
- Event Planners:Professional coordinators managing multi-vendor logistics, now consolidating demand into curated package ecosystems. Destination specialists command 40-60% wage premiums for multilingual ceremony management.
- Families:Traditional budget holders in Indian and Middle Eastern markets funding multi-day celebrations.
- Friends:Peripheral contributors to bachelor parties and shower events.
Planner intermediation is displacing direct couple-vendor relationships in urban markets, with subscription-based retainers replacing commission-only structures.
Package Type:
Pricing architecture stratifies across experiential depth and coordination burden, with all-inclusive models capturing recurring revenue through extended engagement cycles.
- All-Inclusive:Bundled venue, catering, and coordination services reducing friction for time-constrained couples. London, Toronto, and Sydney planners now structure 12-18 month monthly retainers rather than single-event fees.
- Customizable:Modular service selection with à la carte vendor assembly. This segment gains share fastest as couples seek differentiated aesthetics without full luxury pricing.
- Budget:Essential service tiers prioritizing cost containment over experiential depth.
- Luxury:White-glove coordination with dedicated on-site teams and premium material specifications.
Volume concentration favors budget and all-inclusive tiers. Margin expansion concentrates in customizable and luxury configurations.
Technology:
Digital infrastructure is restructuring discovery workflows and payment flows, shifting competitive advantage from local reputation to data-driven personalization engines.
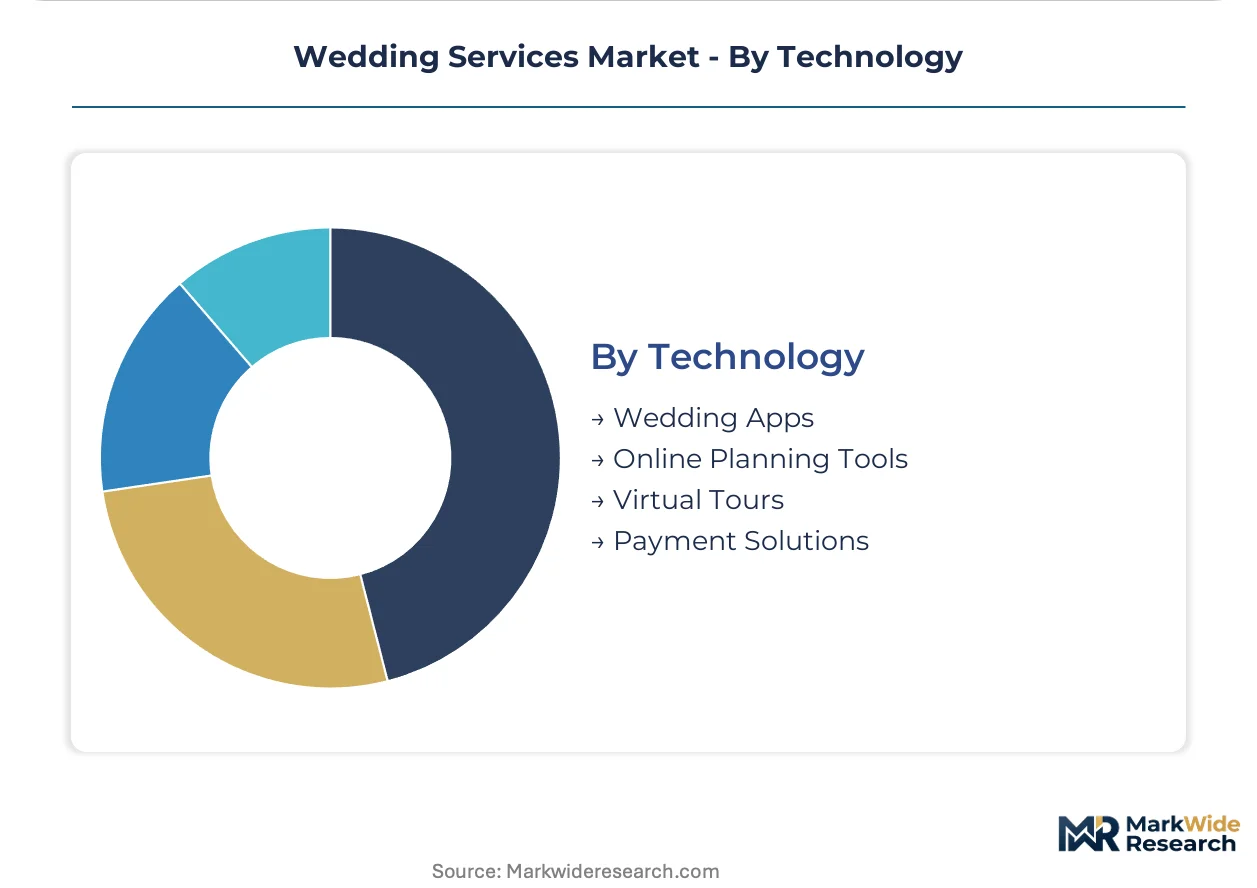
- Wedding Apps:Mobile-first platforms integrating timeline management, vendor communication, and guest logistics. GDPR consent-layer complexity constrains European operators managing RSVP data across marketing touchpoints.
- Online Planning Tools:Browser-based budget trackers and vendor directories. The EU AI Act imposes algorithmic transparency requirements on German, French, and Italian recommendation engines.
- Virtual Tours:Immersive venue visualization reducing in-person site visits.
- Payment Solutions:Installment financing and registry-integrated fund transfers extending customer lifetime value 18-24 months pre-ceremony.
Legacy deployment persists in basic directory and payment functions. AI-driven vendor matching and generative moodboarding represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of wedding services concentrates in experiential destination clusters while consumption spreads across dispersed metropolitan markets. India generates the highest per-event service intensity through multi-day ceremonial traditions. The United States and European Union markets drive platform-based vendor discovery innovation.
United States
High-income millennial couples in California and New York adopt AI moodboarding tools three to four times faster than national averages, compressing vendor discovery timelines from months to weeks. The Federal Trade Commission monitors vendor advertising claims under consumer protection statutes. Los Angeles and New York City anchor premium photography and videography production clusters serving domestic and destination wedding demand.
India
Multi-day ceremonies spanning three to seven days sustain elevated vendor density per event, with separate teams for mehndi, sangeet, and reception functions. The Consumer Protection Act empowers the national consumer disputes commission to adjudicate service failures, creating compliance obligations for package providers. Mumbai and Delhi-NCR concentrate luxury venue infrastructure and high-end catering operations for affluent family celebrations.
Germany
Historic estates and barn conversions face carbon-neutral certification mandates under the EU Green Deal, forcing kitchen equipment and energy system upgrades. The EU AI Act imposes algorithmic transparency requirements on vendor-matching platforms operating across German states. Bavaria and Baden-Württemberg host the densest concentrations of certified sustainable venues serving domestic and cross-border Austrian and Swiss clients.
United Kingdom
London couples increasingly pay monthly retainers for twelve to eighteen month planning engagements rather than single-event fees, concentrating recurring revenue with established boutiques. GDPR frameworks constrain how planning platforms process couple and guest data across marketing touchpoints. The Cotswolds and Scottish Highlands anchor destination wedding tourism serving international clients seeking rural estate experiences.
Australia
Sydney and Melbourne planners structure subscription-based assistance displacing commission-only coordinator relationships, squeezing transaction-dependent competitors. The country's privacy regulator enforces consent-layer requirements on guest RSVP data management. Byron Bay and Margaret River wine region concentrate boutique venue operators targeting micro-wedding specialization with sub-fifty guest configurations.
Wedding Services Market Vendor Landscape
The competitive structure tilts toward platform-based discovery intermediaries with fragmented local vendor execution. Digital aggregators control customer acquisition workflows while specialized boutiques capture margin through experiential curation. Three archetypes dominate: full-service planning agencies with destination logistics expertise, integrated registry-planning platforms extending customer lifetime value, and venue-anchor operators bundling catering and coordination. Consolidation concentrates among platform operators acquiring regional planning boutiques; vertical integration moves through in-house photography and floral production capabilities.
Within the platform-aggregator tier, The Knot Worldwide and Zola exemplify divergent strategic positions. The Knot Worldwide leverages digital platform dominance to control vendor discovery workflows across North America. Zola competes through integrated registry-planning tools that extend customer lifetime value beyond the ceremony date. David's Bridal anchors bridal retail with in-house alteration services that sustain repeat appointment traffic. These three occupy positions spanning discovery infrastructure, transaction extension, and physical retail touchpoints.
| Leading Market Players |
|---|
| The Knot Worldwide |
| Zola |
| WeddingWire |
| XO Group |
| David's Bridal |
| The Dockside Group |
| Easy Weddings |
| Zankyou |
| Style Me Pretty |
| Others |
Supply Flow & Price Mechanics
Captive in-house production of photography and videography services anchors pricing power for full-service planning agencies while compressing margins for transaction-dependent directory platforms. This integration choice insulates premium boutiques from seasonal rate volatility while forcing pure-play coordinators to absorb peak-season labor premiums without offsetting revenue streams.
Pricing Analysis
Margin tightening in mid-tier coordination reflects algorithmic discovery platforms commoditizing vendor matching and eroding traditional commission structures. Three-tier pricing structure across premium, standard, and economy levels stratifies by experiential depth and social media output requirements. Cost compression accelerates in directory-style platforms as AI-driven curation displaces manual search workflows. Budget-tier couples exhibit highest price sensitivity, while destination wedding planners demonstrate inelastic demand for multilingual ceremony management expertise.
Supply Chain Analysis
Carbon-neutral certification mandates under the EU Green Deal are gating venue access across Germany, France, and Italy while reshaping procurement requirements for floral imports. Ecuador and the Netherlands anchor rose and peony supply for European and North American decorators, with freight cost volatility exposing margin fragility. Single-source vulnerability concentrates in climate-dependent harvest cycles across Andean growing regions. Distribution runs through curated package ecosystems that compress traditional vendor fragmentation into consolidated commission structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wedding services market reads as a cost-of-compliance story where GDPR consent-layer complexity and EU AI Act algorithmic transparency requirements erect barrier-to-entry moats for compliant European platform operators.
For Market Incumbents: Lock in recurring revenue through subscription-based planning retainers that extend engagement cycles 12-18 months pre-ceremony, insulating against transaction-dependent competitors. Defend margin position by acquiring in-house photography and floral production capabilities that reduce vendor commission leakage. The Knot Worldwide and Zola illustrate divergent defensive paths: discovery workflow control versus registry-planning integration.
For New Entrants and Emerging Players: Destination wedding planners represent the most penetrable intermediary segment, with 40-60% wage premiums signaling acute talent scarcity. Micro-wedding specialization in Portugal and Greece offers white-space positioning with lower coordination overhead per dollar. A go-to-market angle targeting carbon-neutral certification consulting for historic European estates captures compliance-driven upgrade cycles.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-aggregator acquisitions of regional planning boutiques with established recurring revenue bases. Long-term viability favors operators with data-driven personalization engines over local reputation-dependent vendors. Watch AI governance role proliferation across European mid-sized platforms as an inflection indicator for regulatory compliance moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Vendor Matching Platform | Machine learning curation displaces directory-style discovery workflows across North American and European markets. |
| Carbon-Neutral Venue Certification | EU Green Deal compliance mandates force kitchen and energy system upgrades across German historic estates. |
| Integrated Registry-Planning Convergence | Zola's tool bundle extends customer lifetime value 18-24 months beyond ceremony dates. |
| Destination Logistics Boutique Acquisition | Consolidation captures 40-60% wage premiums for multilingual ceremony management expertise. |
| Generative AI Moodboarding Deployment | Photorealistic visualization compresses florist discovery timelines from 8-12 weeks to 2-3 weeks in California and New York. |
Methodological Framework
Trade association filings, customs import records for floral commodities, and venue operator licensing databases formed the secondary backbone for supply-side calibration. Primary interviews with destination wedding planners, venue procurement managers, and platform engineering leads combined with regulatory documentation from the FTC, EU AI Act implementation guidance, and India's Consumer Protection Act enforcement records. Bottom-up vendor capacity modeling and top-down household formation projections enabled triangulation across the analysis window.
Bottom-up segment sizing by service type, customer archetype, and package configuration fed into top-down macro validation against household disposable income and marriage rate trends. Modeled dimensions spanned venue-catering-photography-entertainment service splits, direct couple versus intermediary procurement authority, and technology adoption intensity across planning tool categories. CAGRs derived from regression against historical booking volume patterns and seasonal capacity utilization rates, with AI adoption curves and carbon-neutral certification penetration as industry-specific forecast inputs.
Caveats apply where GDPR enforcement intensity or EU AI Act risk reclassification could materially shift the outlook for European platform operators. Forecasts reflect assumptions about sustained social media content mandate intensity and destination wedding planner wage premium durability. A model refresh is warranted upon material change in algorithmic transparency regulatory scope or floral import tariff structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Mexico Event Services Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
GCC Event Management Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Asia-Pacific Wedding Services Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Germany Event Services Market
Events and Conferences
North America Event Services Market
Events and Conferences
Event Management Solutions Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
India B2B Events Market
Events and Conferences
Canada Event Services Market
Events and Conferences
Asia-Pacific MICE Industry Market