
 Event Management Solutions Market | 2026-2036
Event Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Event Management Solutions Market Foresight
Enterprise-grade platform consolidation is collapsing the legacy point-solution landscape as buyers demand unified stacks. Cvent dominates the cloud-based registration and venue-sourcing segment through deep hospitality network effects. Freeman leverages its exhibit-production heritage to anchor integrated experiential technology services. Opus Agency differentiates through high-touch strategic-event design for Fortune 500 technology and pharmaceutical clients.
Event management solutions encompass software and services that coordinate logistics, marketing, attendee engagement, and post-event analytics for gatherings ranging from ten-person corporate retreats to hundred-thousand-attendee trade shows. Core functional parameters include real-time capacity management, multi-channel communication orchestration, and GDPR-compliant data capture across touchpoints. Ticketing solutions and virtual event tools now capture disproportionate investment as organizers rebuild hybrid-format infrastructure. Cloud-based delivery models lead absolute revenue contribution, though hybrid solutions represent the fastest-expanding configuration as security-conscious enterprises retain on-premise identity management.
The EU AI Act and GDPR constrain automated attendee profiling and cross-border data flows, compelling vendors to architect privacy-by-default systems. The SEC's disclosure requirements for material corporate events indirectly shape demand for auditable event-spend tracking and attendee-influence documentation. Stakeholders must monitor how evolving accessibility standards and sustainability mandates rewrite procurement specifications before committing to multi-year platform contracts.
Market Dynamics
Enterprise procurement teams are consolidating vendor relationships around API-first platforms that unify registration, analytics, and engagement workflows, collapsing the legacy point-solution landscape as multi-year contracts favor integrated stacks over specialized tools.
Growth Catalysts
- Hybrid Work Normalization:Fortune 500 technology and pharmaceutical clients now mandate software infrastructure supporting simultaneous in-person and virtual attendee experiences, expanding addressable spend per event.
- GDPR-Driven Data Infrastructure:European enterprise buyers require privacy-by-default attendee profiling systems, accelerating replacement cycles for non-compliant legacy platforms.
- Cloud Migration:North American hospitality budgets are shifting from on-premise license models to subscription-based delivery, compressing procurement cycles from eighteen to six months.
Market Restraints
- Identity Management Fragmentation:Security-conscious enterprises retain on-premise authentication systems, forcing vendors to maintain hybrid architectures that increase engineering overhead.
- Cross-Border Data Friction:The EU AI Act constrains automated attendee scoring algorithms, limiting feature deployment across transatlantic event portfolios.
- Specialized Talent Scarcity:Platform engineering roles combining hospitality domain expertise with real-time capacity management experience command premium compensation in the United States.
Strategic Opportunities
- Sustainability-Linked Procurement:CSRD disclosure requirements in Western Europe are rewriting RFP specifications to prioritize carbon-accounting modules and venue emissions tracking.
- Accessibility Standards:ADA and WCAG mandates in the United States create white space for vendors offering real-time captioning and assistive-navigation integrations as standard features.
- API Ecosystem Expansion:Convergence between event management platforms and CRM systems via native connectors enables workflow automation that displaces manual data reconciliation.
Industry Challenges
- Legacy System Integration:Enterprise IT departments struggle to synchronize modern cloud platforms with decades-old on-premise financial and HR systems without custom middleware development.
- Certification Timeline Compression:SOC 2 Type II and ISO 27001 audit cycles now align with quarterly budget approvals, stretching vendor compliance teams across overlapping client deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Event Management Solutions Market |
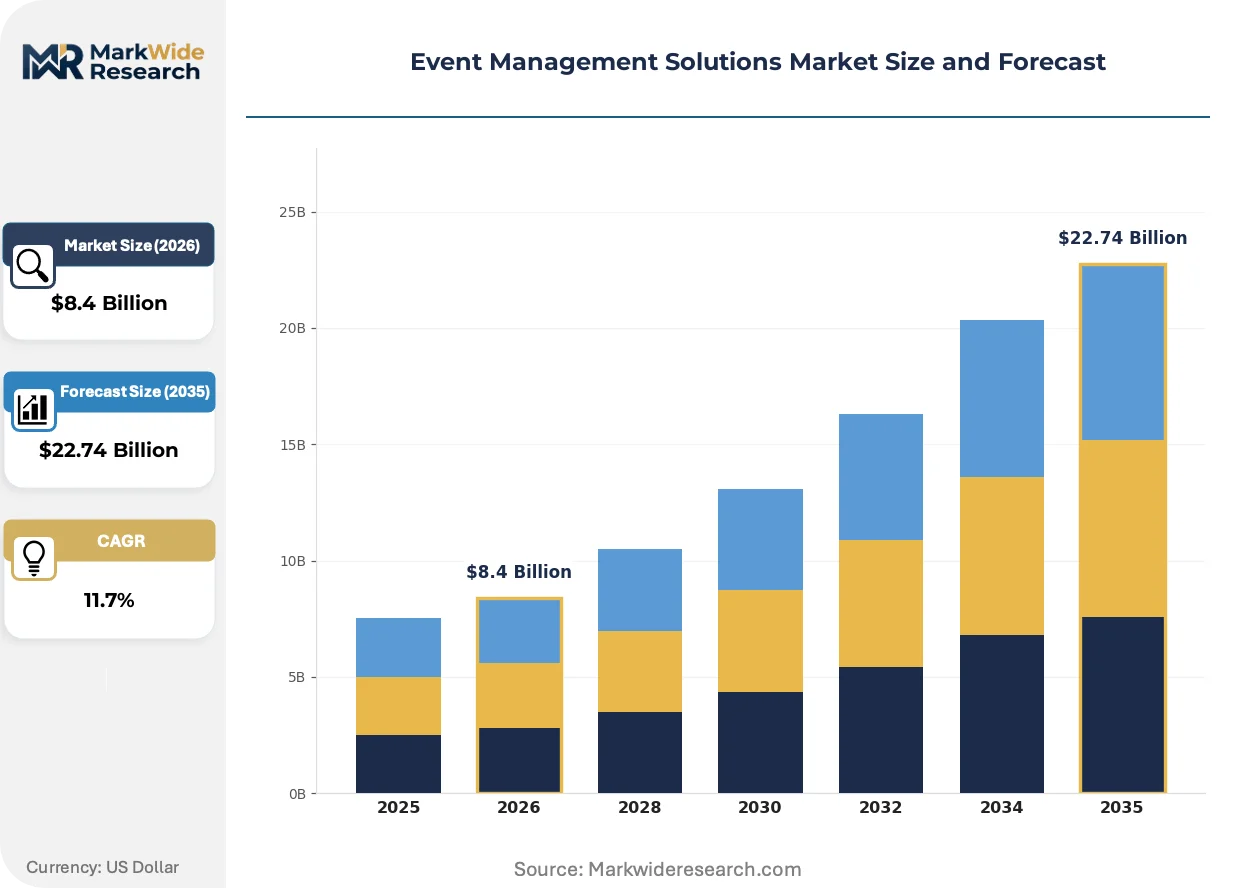
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-site Management, Event Marketing, Ticketing Solutions, Registration Services Application: Corporate Events, Trade Shows, Festivals, Weddings Technology: Online Platforms, Mobile Applications, RFID Solutions, Virtual Event Tools Delivery Model: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Software as a Service |
| Companies Covered | Maritz Global Events, Corporate Optics, GoGather, Cvent, Brightspot, Freeman, Opus Agency, ExpoPlatform, George P. Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Event Management Solutions Market Shifts & Advancements
Real-time engagement analytics and immersive virtual environments are restructuring how organizers justify event spend and design attendee journeys, with technology investments concentrating on measurable outcomes rather than experiential aesthetics alone.
Immersive virtual event platforms leveraging spatial computing and persistent digital venues are bifurcating the market between premium experiential deployments and stripped-down webinar substitutes. Pharmaceutical and financial services buyers in the United States are adopting these tools at the fastest pace, seeking to replicate trade-floor networking in distributed formats. This technology is compressing the addressable market for traditional video-conferencing licenses while expanding total software spend per event.
The SEC's disclosure requirements for material corporate gatherings are reshaping procurement specifications to demand auditable attendee-influence documentation and granular spend tracking. Vendors must now architect compliance modules that capture meeting purpose, participant seniority, and hospitality value in structured formats. Financial services and healthcare verticals in the United States are most affected, with procurement teams embedding these capabilities as non-negotiable evaluation criteria.
Buyer concentration among consolidated enterprise procurement functions is compressing vendor switching cycles and unbundling after-sales service expectations. Mid-market event agencies that previously self-managed technology stacks are now outsourcing platform operations to specialized managed service providers. This pattern is most visible in the United Kingdom and Germany, where procurement centralization has accelerated fastest among professional services and technology sectors.
Event Management Solutions Market Segmentation
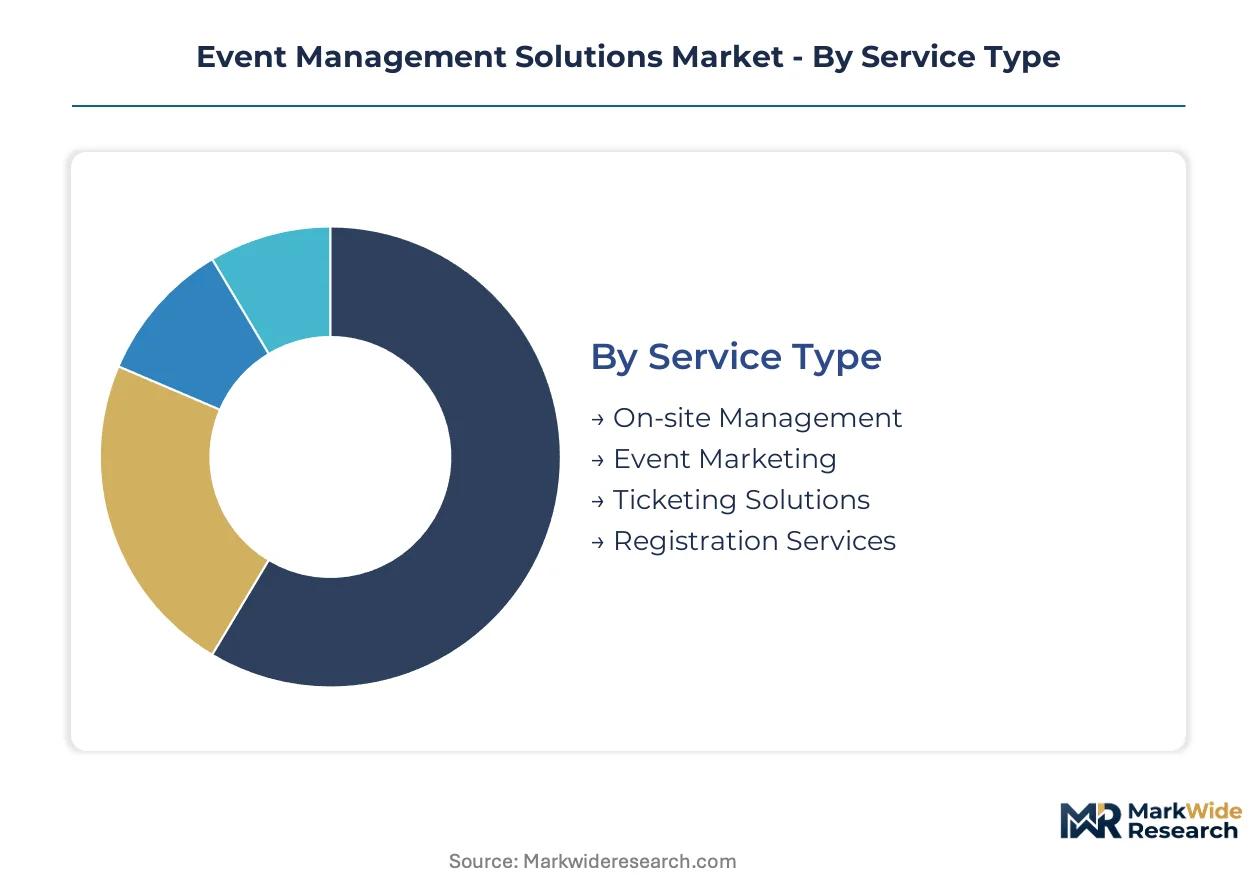
Event management solutions fragment across four functional dimensions that determine procurement priorities and vendor selection criteria. Each category reflects distinct buyer workflows, compliance requirements, and integration complexity that reshape competitive positioning across enterprise and mid-market accounts.
Service Type:
Domestic demand concentrates in registration and on-site execution services, while ticketing and event marketing solutions increasingly serve cross-border event portfolios requiring multi-currency and multilingual capabilities.
- On-site Management:Encompasses venue logistics coordination, vendor supervision, and real-time problem resolution during event execution. Fortune 500 pharmaceutical and technology clients in the United States drive premium demand for white-glove staffing models that embed dedicated account teams. The SEC's disclosure requirements for material corporate gatherings elevate documentation standards for this segment.
- Event Marketing:Covers multi-channel campaign orchestration, audience acquisition, and brand activation measurement. European buyers under GDPR and the EU AI Act constrain automated profiling capabilities, fragmenting feature deployment across transatlantic portfolios. CSRD disclosure requirements in Western Europe now mandate carbon-accounting integration for marketing spend.
- Ticketing Solutions:Real-time capacity management and fraud-resistant distribution systems.
- Registration Services:Attendee data capture with GDPR-compliant consent workflows.
On-site Management holds the largest share; momentum sits with Event Marketing as hybrid-format audience acquisition complexity climbs.
Application:
Cost tier differentiation separates enterprise-grade deployments with dedicated support from self-service platforms targeting independent planners and smaller agencies.
- Corporate Events:Internal meetings, product launches, and executive retreats requiring auditable spend tracking and attendee-influence documentation. Financial services and healthcare verticals in the United States embed SEC-compliant capture modules as non-negotiable procurement criteria. Procurement centralization among consolidated enterprise functions compresses vendor switching cycles.
- Trade Shows:Large-scale exhibitions with complex exhibitor management and lead retrieval systems. Freeman and Cvent anchor this segment through deep hospitality network effects and integrated experiential technology stacks. Pharmaceutical buyers adopt spatial computing tools fastest to replicate trade-floor networking in distributed formats.
- Festivals:Multi-day cultural and music events with mass attendee flows and security coordination.
- Weddings:Personal celebration planning with aesthetic customization and vendor marketplace integration.
Corporate Events command premium pricing; Trade Shows gain share fastest as hybrid-format infrastructure investment accelerates.
Technology:
Volume concentration tracks cloud migration velocity, with mobile and virtual tools expanding addressable spend per event while RFID solutions face replacement pressure from smartphone-based alternatives.
- Online Platforms:Browser-based event management dashboards unifying registration, analytics, and communication workflows. Cloud migration across North American hospitality budgets compresses procurement cycles from eighteen to six months. API-first architectures enable native CRM connectors that displace manual data reconciliation.
- Virtual Event Tools:Immersive environments leveraging spatial computing and persistent digital venues. These tools compress the addressable market for traditional video-conferencing licenses while expanding total software spend per event. Pharmaceutical and financial services buyers in the United States lead adoption velocity.
- Mobile Applications:Attendee-facing iOS and Android experiences with real-time agenda updates and networking features.
- RFID Solutions:Contactless access control and behavioral tracking hardware with on-premise data storage requirements.
Online Platforms dominate current revenue contribution; Virtual Event Tools climb the fastest as hybrid work normalization sustains distributed-format investment.
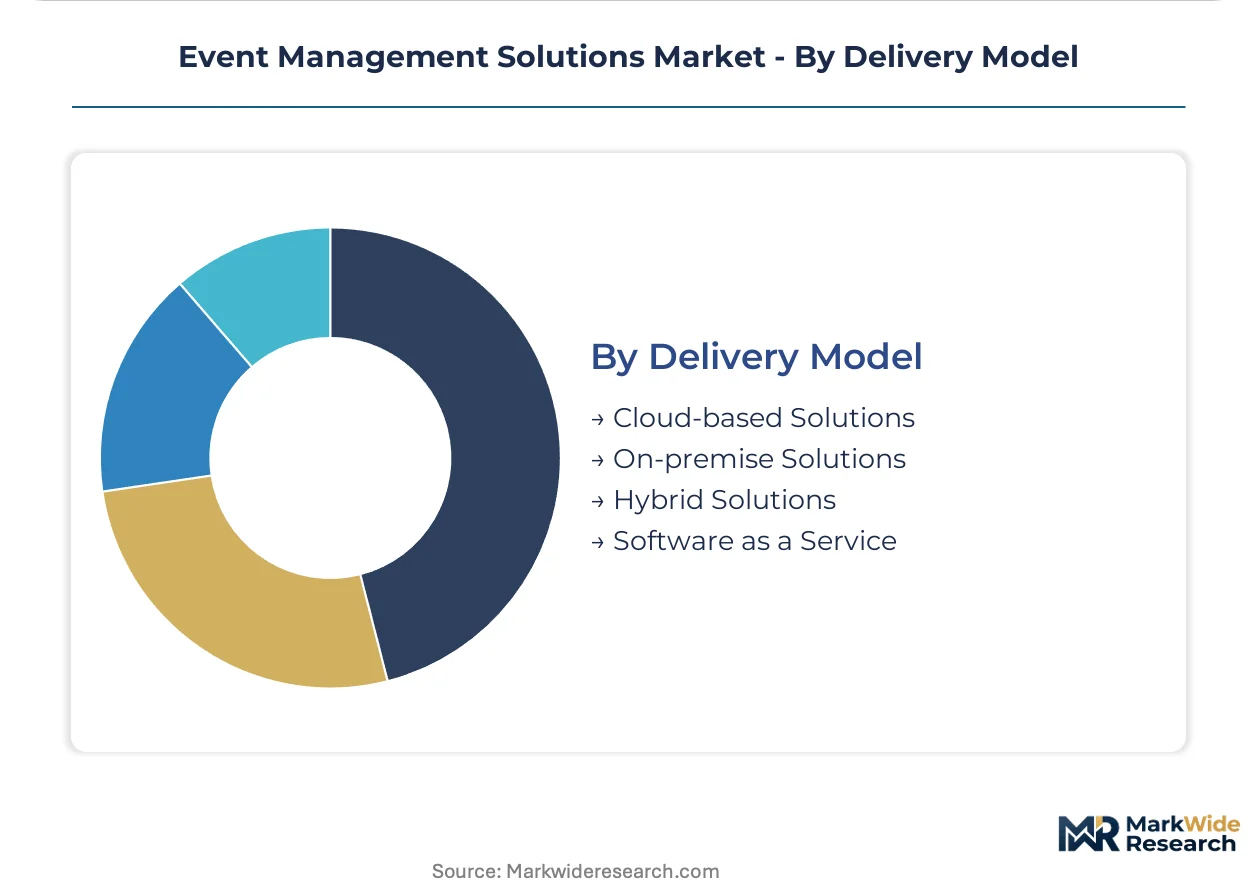
Delivery Model:
Customer type bifurcation separates security-conscious enterprises retaining authentication control from mid-market agencies outsourcing platform operations to managed service providers.
- Cloud-based Solutions:Subscription-delivered software with automatic updates and elastic infrastructure scaling. North American enterprise hospitality budgets sustain the fastest procurement cycle compression. SOC 2 Type II and ISO 27001 audit cycles now align with quarterly budget approvals, stretching vendor compliance teams.
- Hybrid Solutions:Architectures combining cloud-hosted functionality with on-premise identity management for sensitive authentication workflows. Security-conscious enterprises force vendors to maintain dual infrastructure, increasing engineering overhead. This configuration expands most quickly as GDPR-driven data infrastructure accelerates replacement cycles for non-compliant legacy platforms.
- On-premise Solutions:Licensed software deployed within client-controlled data centers with manual upgrade responsibility.
- Software as a Service:Pure subscription models with usage-based pricing and minimal client-side infrastructure.
Cloud-based Solutions capture the largest installed base; Hybrid Solutions represent the steepest expansion trajectory as cross-border data friction intensifies architecture complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering capacity clusters most heavily in the United States, where enterprise hospitality budgets and hybrid work policies sustain the deepest software investment. Cloud migration velocity and API-first architecture adoption compress procurement cycles from eighteen to six months across North American buyers.
United States
Fortune 500 technology and pharmaceutical clients mandate infrastructure supporting simultaneous in-person and virtual attendee experiences. SEC disclosure requirements for material corporate gatherings reshape procurement specifications to demand auditable attendee-influence documentation. New York and San Francisco anchor the densest concentration of event technology vendors serving financial services and healthcare verticals.
Germany
Professional services and technology sectors accelerate procurement centralization among consolidated enterprise functions. CSRD disclosure requirements rewrite RFP specifications to prioritize carbon-accounting modules and venue emissions tracking. Frankfurt and Munich host the largest managed service provider ecosystems supporting mid-market agency platform outsourcing.
United Kingdom
Mid-market event agencies increasingly outsource platform operations to specialized managed service providers. GDPR and the EU AI Act constrain automated attendee profiling capabilities, fragmenting feature deployment across transatlantic portfolios. London concentrates buyer decision-making for European corporate event portfolios requiring multi-currency and multilingual capabilities.
India
Domestic enterprise adoption of cloud-based registration and analytics platforms accelerates as IT services firms expand internal event portfolios. The country's national data protection framework shapes vendor selection criteria for cross-border attendee data management. Bangalore and Hyderabad emerge as engineering hubs for platform engineering roles combining hospitality domain expertise with real-time capacity management experience.
Japan
Corporate buyers adopt immersive virtual event platforms leveraging spatial computing to replicate trade-floor networking in distributed formats. METI guidelines on digital transformation influence enterprise software procurement evaluation criteria. Tokyo anchors demand for white-glove on-site management services embedding dedicated account teams within pharmaceutical and financial services verticals.
Event Management Solutions Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the event management solutions market. Enterprise-grade platform consolidation collapses the legacy point-solution landscape as multi-year contracts favor integrated stacks over specialized tools. Three archetypes dominate: cloud-native software vendors with deep hospitality network effects, exhibit-production heritage firms anchoring integrated experiential services, and high-touch strategic-event design specialists. Competitive dynamics center on API ecosystem expansion and sustainability-linked procurement capabilities.
Within the integrated platform tier, Cvent and Freeman occupy positions exemplifying divergent heritage advantages. Cvent represents the cloud-native archetype with subscription-delivered infrastructure unifying registration, analytics, and venue sourcing. Freeman exemplifies the production-heritage archetype, leveraging exhibit-production roots to anchor experiential technology services. Opus Agency sits within the high-touch specialist tier, serving Fortune 500 technology and pharmaceutical clients through strategic-event design capabilities. These three anchors illustrate how vendor selection increasingly bifurcates between scale-driven platform consolidation and relationship-intensive strategic partnerships.
| Leading Market Players |
|---|
| Maritz Global Events |
| Corporate Optics |
| GoGather |
| Cvent |
| Brightspot |
| Freeman |
| Opus Agency |
| ExpoPlatform |
| George P. Johnson |
| Others |
Supply & Pricing Matrix
Cloud-based subscription models displacing perpetual license arrangements are redistributing vendor engineering capacity toward United States and India while compressing customer procurement cycles from eighteen to six months. This substitution simultaneously concentrates platform development in low-cost engineering hubs and intensifies price competition across mid-market agency segments.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure by forcing privacy-by-default architecture investments that separate enterprise-grade deployments from stripped-down self-service offerings. Three-tier pricing structure across premium, standard, and economy levels reflects SOC 2 Type II certification status, dedicated account team allocation, and API ecosystem breadth. Cost compression in the mid-market tier is intensifying because managed service providers aggregate agency demand and negotiate volume discounts. Independent event planners exhibit highest price sensitivity, while Fortune 500 pharmaceutical and financial services clients prioritize compliance documentation over per-seat economics.
Supply Chain Analysis
Just-in-time provisioning dominates cloud infrastructure delivery, though hybrid architecture demand compels strategic stockpiling of on-premise identity management components for security-conscious enterprise accounts. Engineering talent supply concentrates in the United States, India, and Germany, with platform development resting on specialized hospitality domain expertise combined with real-time capacity management experience. Single-source vulnerability runs through concentrated cloud hyperscaler relationships for elastic infrastructure scaling. Distribution runs through direct enterprise sales teams, specialized managed service providers in the United Kingdom and Germany, and self-service digital channels for independent planners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise hospitality budget normalization following hybrid work policy stabilization positions this market for cyclical recovery as deferred event infrastructure investment resumes.
For Market Incumbents: Compound API ecosystem advantages by deepening native CRM connectors that displace manual data reconciliation workflows, while accelerating SOC 2 Type II certification velocity to match quarterly budget approval timelines. Cloud-native entrants with vertical-specific compliance modules threaten established positioning in financial services and healthcare segments. For New Entrants and Emerging Players: SOC 2 Type II fast-track programs unlock mid-market agency segments in the United Kingdom and Germany where procurement centralization has accelerated platform outsourcing to managed service providers. Accessibility standards including ADA and WCAG mandates in the United States represent the most penetrable white space, with real-time captioning and assistive-navigation integrations as standard features offering immediate differentiation against legacy platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform engineering teams combining hospitality domain expertise with compliance architecture capabilities. Long-term viability hinges on sustainability-linked procurement module development aligned with CSRD disclosure requirements. The signal to watch is carbon-accounting integration adoption velocity across Western European RFP specifications as inflection indicator for competitive positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Native CRM connectors displace manual data reconciliation for enterprise procurement teams. |
| Compliance Module Development | SEC-aligned attendee-influence documentation captures financial services and healthcare vertical demand. |
| Sustainability Integration | Carbon-accounting modules align with CSRD disclosure requirements rewriting Western European RFP specifications. |
| Hybrid Architecture Investment | On-premise identity management retention addresses security-conscious enterprise authentication requirements. |
| Managed Service Provider Partnership | Mid-market agency platform outsourcing concentrates in the United Kingdom and Germany procurement centralization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory databases, hospitality industry procurement records, and cloud infrastructure capex disclosures. Conversations with corporate event planners, IT procurement officers, platform engineers, and managed service provider executives informed demand-side validation. Vendor-side perspectives drew from product strategy leads and compliance officers at integrated platform providers. Bottom-up event spend tracking and top-down software market sizing were cross-referenced for triangulation.
Segmentation dimensions modeled include service type, application vertical, technology deployment, and delivery model across the projection horizon. CAGRs were derived from elasticity analysis of enterprise hospitality budget allocation patterns and replacement cycle compression observed in North American procurement data. Hybrid work normalization velocity and cross-border data friction intensity served as scenario-weighting inputs.
Underlying assumptions cover sustained cloud migration momentum and regulatory enforcement continuity, with deviation risk concentrated in EU AI Act implementation timeline variability and enterprise identity management architecture preference shifts. Revision becomes warranted when hybrid work policy reversals cross thresholds affecting per-event software spend allocation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Spain Event Services Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Germany Event Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Italy Event Services Market
Events and Conferences
Europe Discount Events and Experiences Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
North America Event Services Market
Events and Conferences
India Wedding Services Market
Events and Conferences
North America Wedding Services Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Vietnam MICE Market
Events and Conferences
MICE Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
Saudi Arabia MICE Market