
 Professional Speaker Market | 2026-2036
Professional Speaker Market Size, Share, and Industry Trends Forecast 2026-2036
Professional Speaker Market Outlook
Neodymium is expanding its share in professional speaker driver assemblies as manufacturers phase out ferrite magnets to cut weight and improve transient response. JBL Professional leverages its transducer manufacturing scale to control raw material costs across its touring and installation lines. Electro-Voice sustains dominance in the live sound rental channel through hardened enclosure designs purpose-built for repetitive load-in cycles. L-Acoustics differentiates via its integrated amplification and processing ecosystem, which locks in venue-level contracts across major festival circuits.
A professional speaker is an electroacoustic transducer system engineered to convert electrical audio signals into sound pressure levels exceeding 120 dB SPL, typically incorporating cone or compression drivers, waveguides, and passive or active crossover networks for deployment in concerts, corporate installations, and broadcast environments. The motivational and keynote speaker type segment commands premium booking fees due to C-suite demand for narrative-driven leadership content at annual meetings and shareholder events. The hybrid delivery mode segment is displacing pure virtual formats as enterprises demand simultaneous in-room and streaming accessibility without duplicate talent costs. The business and technology industry verticals anchor recurring revenue through retainer-based speaker bureaus serving SaaS companies and financial services firms.
The Federal Communications Commission governs wireless microphone and in-ear monitor spectrum allocations that constrain professional speaker system configurations in the United States, while the European Union's CE marking and RoHS directives restrict hazardous substance content in crossover components and cabinet finishes sold across member states. OSHA noise exposure regulations in the United States compel venue operators to specify speakers with precise directivity control to limit stage volume at monitor positions. Stakeholders must monitor spectrum reallocation proceedings and material compliance deadlines to avoid retrofit liabilities and secure long-term venue specification contracts.
Market Dynamics
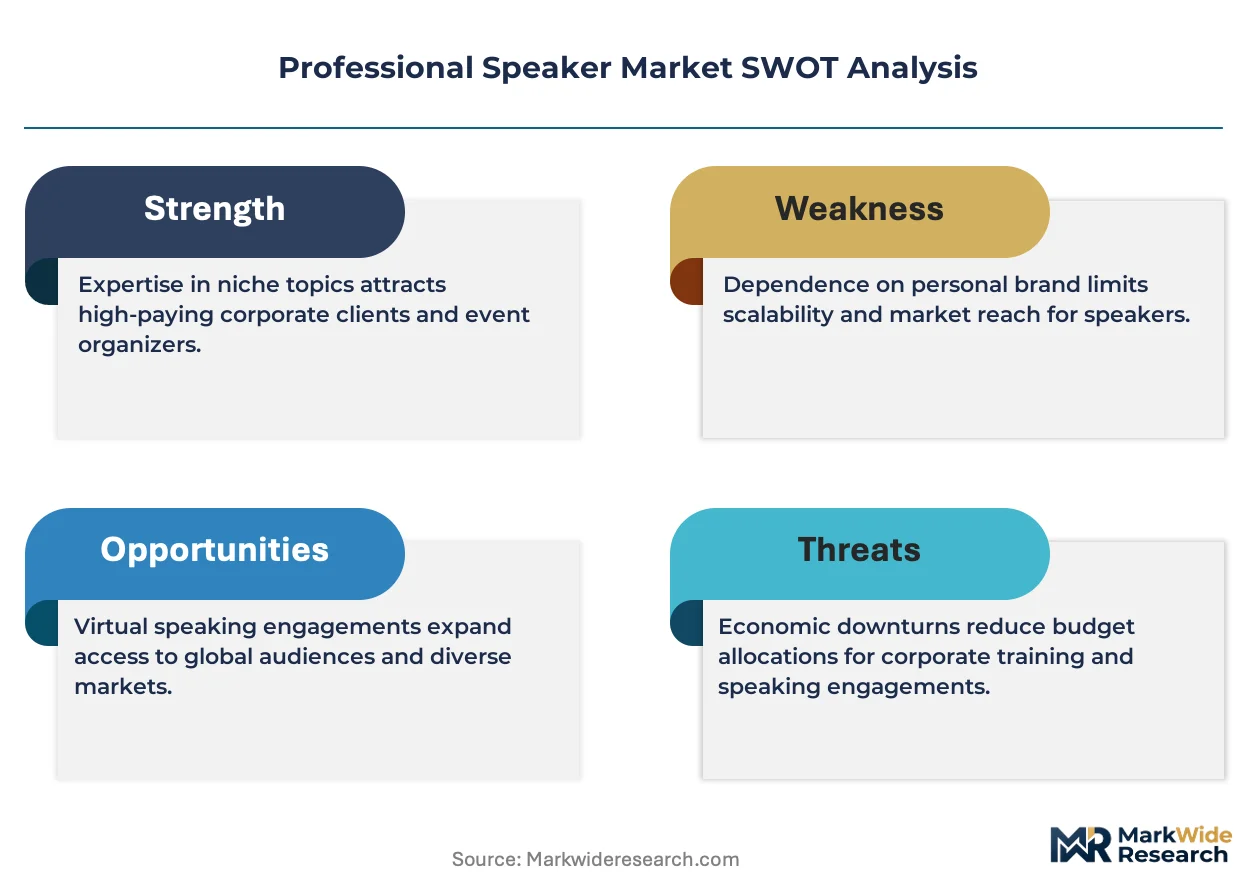
Corporate training budgets are redirecting toward live keynote engagements, compressing procurement cycles and elevating speaker bureau consolidation as the dominant structural force reshaping competitive positioning.
Growth Catalysts
- EU AI Act disclosure mandates:Synthetic voice labeling requirements in recorded content are accelerating demand for verified human speakers at live corporate events.
- Neodymium magnet adoption:Driver manufacturers are phasing out ferrite assemblies to reduce cabinet weight and improve transient response in touring rigs.
- Fortune 500 retention pools:Executive development programs in the United States sustain recurring procurement contracts for narrative-driven leadership content.
Market Restraints
- Rare earth supply concentration:Neodymium processing dependency on Chinese refining infrastructure creates input cost volatility for magnet assemblies.
- FCC spectrum reallocation:Wireless microphone and in-ear monitor frequency constraints limit system configuration flexibility in United States venues.
- RoHS material restrictions:Crossover component and cabinet finish compliance deadlines in the European Union force premature hardware refresh cycles.
Strategic Opportunities
- Hybrid delivery infrastructure:Simultaneous in-room and streaming accessibility without duplicate talent costs is displacing pure virtual formats in enterprise accounts.
- Retainer-based speaker bureaus:SaaS companies and financial services firms in the United States are anchoring recurring revenue through subscription-style talent access.
- OSHA noise compliance:Precise directivity control specifications for stage monitor positions are creating specification lock-in for compliant enclosure designs.
Industry Challenges
- RF engineering talent scarcity:Wireless frequency coordination expertise for interference-free multi-channel systems remains concentrated among veteran live sound technicians.
- CE marking timeline compression:Accelerated hazardous substance testing for crossover networks sold across European Union member states strains certification bandwidth.
- Legacy analog integration:Venue-installed passive speaker infrastructure resists seamless incorporation of networked amplification and processing ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Professional Speaker Market |
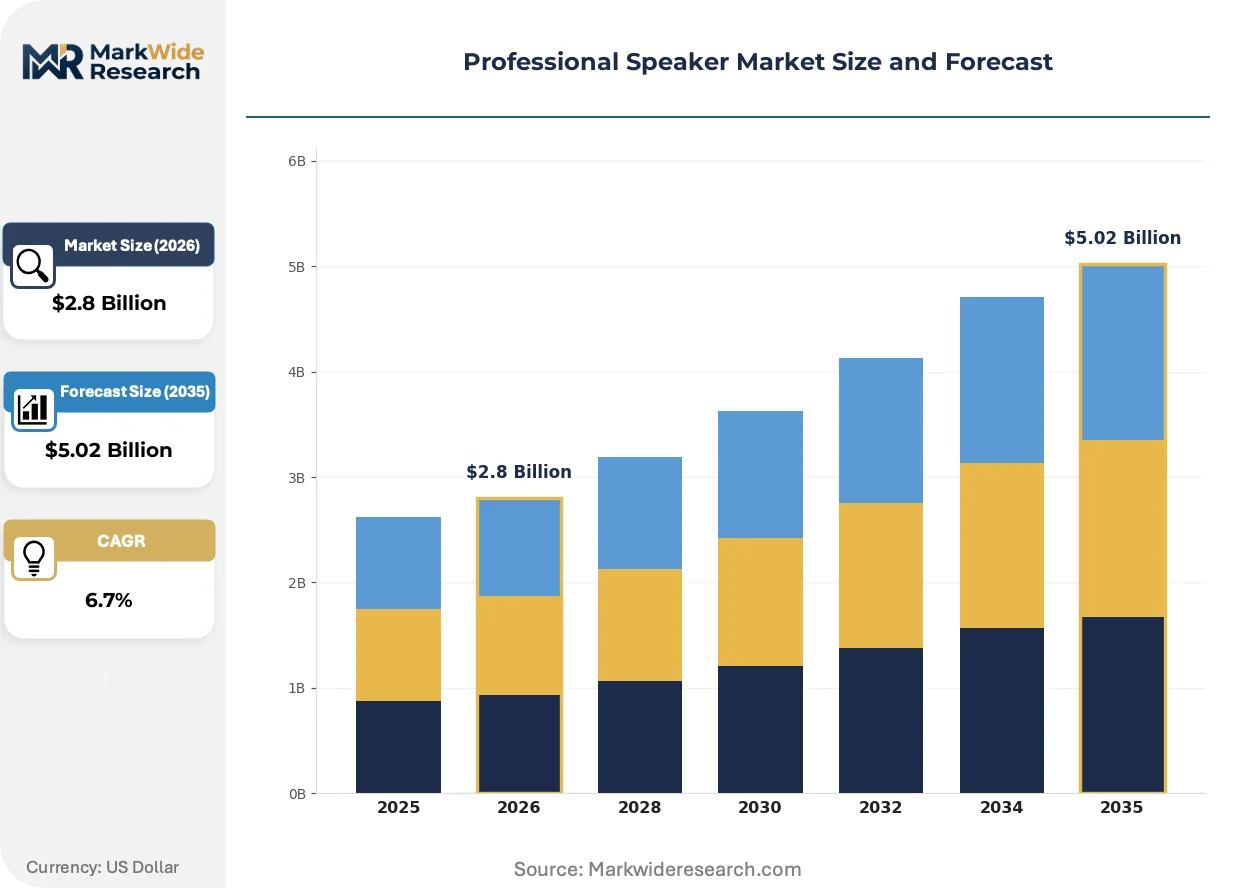
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Speaker Type: Motivational, Inspirational, Corporate, Keynote Industry Vertical: Education, Business, Health & Wellness, Technology Delivery Mode: In-Person, Virtual, Hybrid, Workshop Target Audience: Executives, Students, Entrepreneurs, Professionals |
| Companies Covered | JBL Professional, Electro-Voice, L-Acoustics, Adamson Systems Engineering, RCF, Meyer Sound, QSC, NEXO, d&b audiotechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Professional Speaker Market Strategic Shifts
Integrated amplification ecosystems are consolidating vendor relationships and compressing procurement decisions toward single-source contracts for festival and installation venues.
Neodymium magnet assemblies are consolidating driver manufacturing standards across touring and fixed-installation product lines. Rental houses and venue operators are specifying lightweight cone drivers to reduce rigging labor and truck pack volume. This consolidation is compressing ferrite magnet demand to legacy replacement markets and entry-level portable systems.
The EU AI Act synthetic disclosure framework is mandating transparency labels for AI-generated voice content in recorded media. Live keynote engagements are capturing budget share as enterprises seek unambiguous human authenticity for leadership messaging. European corporate procurement teams are rewriting speaker bureau contracts to exclude undisclosed synthetic voice derivatives.
Retainer-based talent access is replacing transactional per-event booking in technology and financial services verticals. Speaker bureaus are unbundling preparation, travel, and delivery into subscription tiers with priority scheduling guarantees. This model is most visible in United States SaaS corridors where annual meeting calendars require predictable executive presence.
Professional Speaker Market Segmentation
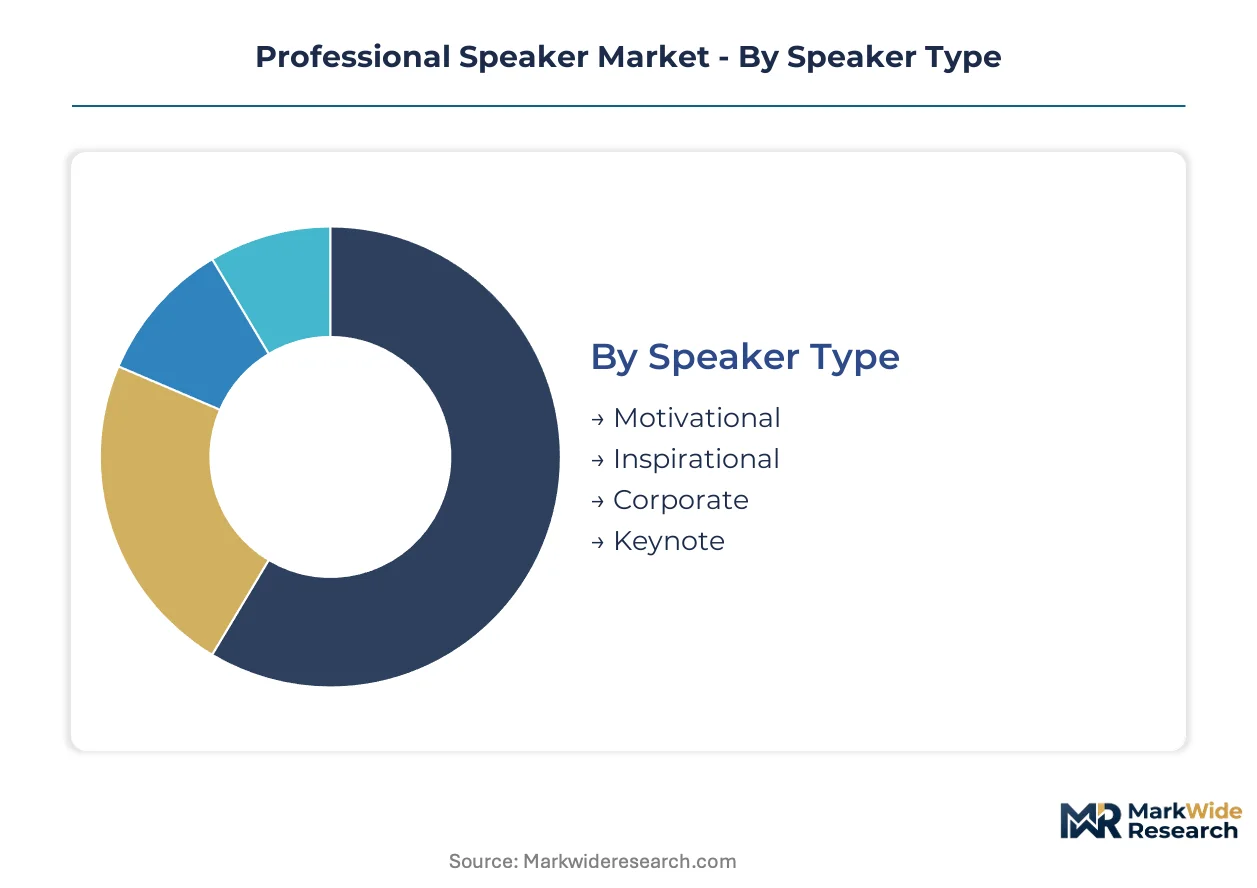
Professional speaker procurement patterns diverge sharply by engagement context. Buyers prioritize narrative authenticity for C-suite audiences, technical depth for practitioner workshops, and scalable reach for distributed employee bases.
Speaker Type:
Booking fees and preparation cycles vary dramatically based on the intellectual property intensity and performance format each speaker type demands.
- Keynote:Single-appearance engagements commanding premium fees through exclusive narrative frameworks and proprietary leadership methodologies. Fortune 500 annual meetings in the United States sustain the largest procurement pools for this tier, with contracts increasingly stipulating human-only delivery to satisfy EU AI Act disclosure mandates on synthetic content.
- Motivational:High-energy performance formats emphasizing emotional narrative arcs and audience interaction mechanics. Demand concentrates in corporate training budgets redirecting from recorded modules toward live engagement, particularly in sectors undergoing restructuring or cultural transformation.
- Corporate:Standardized content modules adapted to internal communication objectives and compliance training requirements. Procurement runs through retainer-based speaker bureaus serving SaaS companies and financial services firms with predictable annual meeting calendars.
- Inspirational:Personal narrative formats leveraging authentic experience storytelling for employee engagement and brand alignment initiatives. Brief treatment: Tiered pricing separates celebrity-backed appearances from emerging voices building portfolio credibility.
Volume sits with Corporate; growth tilts toward Keynote.
Industry Vertical:
Vertical specialization determines content customization depth and recurrence frequency in speaker bureau relationships.
- Business:Encompasses financial services, professional services, and general corporate development. Retainer-based talent access is replacing transactional per-event booking, with subscription tiers unbundling preparation, travel, and delivery into priority scheduling guarantees.
- Technology:SaaS corridors in the United States anchor recurring revenue through speaker bureaus delivering technical founders and product leaders for customer conferences and internal enablement. The segment demands simultaneous in-room and streaming accessibility without duplicate talent costs.
- Education:Institutional procurement through university speaker series, alumni events, and student orientation programming. Brief treatment: Budget constraints favor regional talent pools and shared-appearance models across consortium institutions.
- Health & Wellness:Clinical credential requirements and outcome measurement protocols differentiate procurement from general corporate segments. Brief treatment: Hospital systems and employer wellness programs prioritize evidence-based content over pure motivational formats.
Business captures current volume; Technology climbs the fastest on retainer-model adoption.
Delivery Mode:
Technical infrastructure requirements and talent cost structures create distinct procurement economics across delivery formats.
- Hybrid:Simultaneous in-room and streaming production integrating venue AV systems with broadcast-quality remote feeds. Enterprise accounts are displacing pure virtual formats as the default specification for leadership events requiring broad employee access.
- In-Person:Traditional venue-based engagement with travel and lodging cost burdens absorbed by procurement budgets. OSHA noise exposure regulations in the United States compel precise directivity control specifications for stage monitor positions at large corporate events.
- Virtual:Remote delivery through webinar platforms and proprietary broadcast infrastructure. Brief treatment: Compressed fees and reduced preparation cycles position this format for internal training and high-frequency programming.
- Workshop:Extended-format engagements with facilitated participant interaction and breakout mechanics. Brief treatment: Higher per-hour fees reflect smaller audience caps and customized curriculum development requirements.
In-Person retains volume dominance; Hybrid gains share fastest on enterprise infrastructure investment.
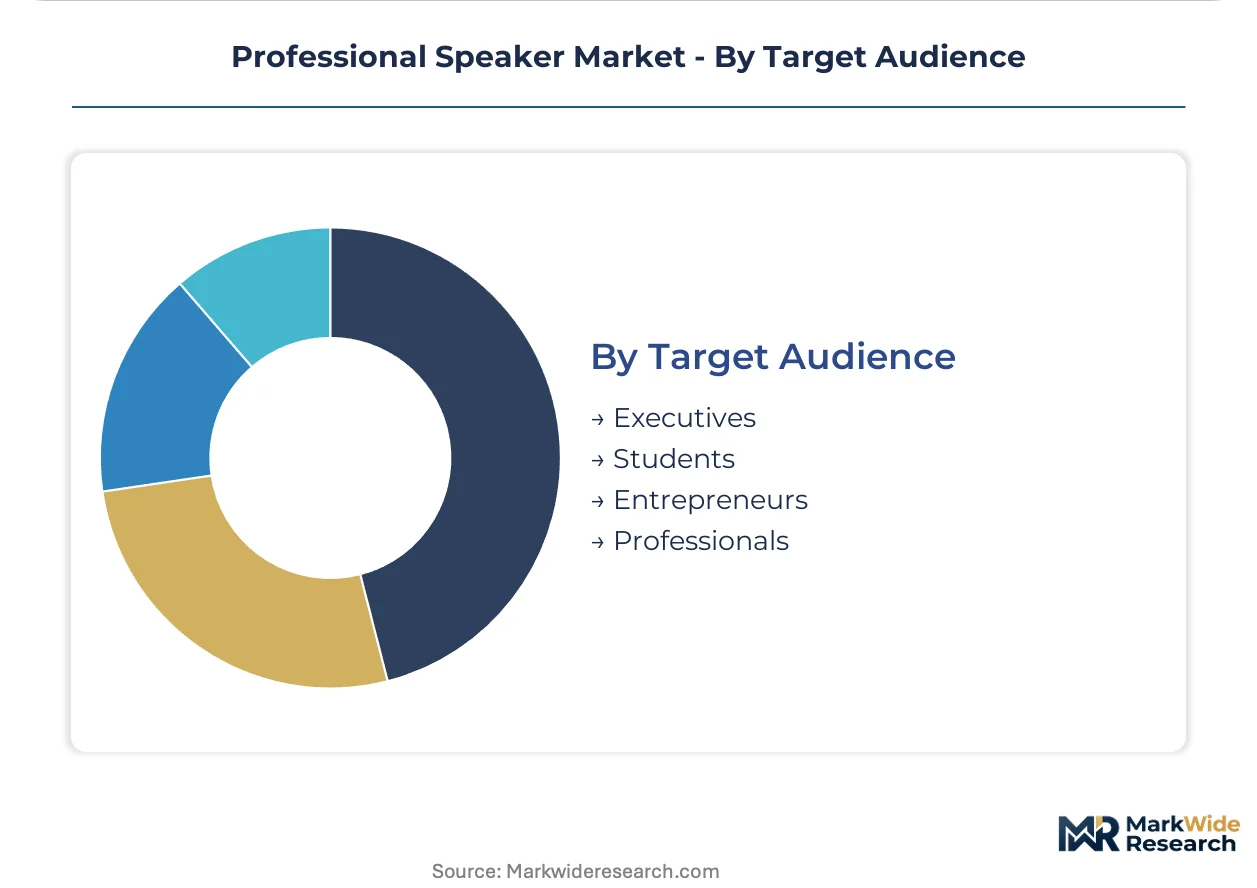
Target Audience:
Audience seniority shapes content sophistication, fee tolerance, and the procurement decision-making pathway.
- Executives:C-suite and board-level audiences demanding narrative-driven leadership content with strategic relevance to competitive positioning. Annual meeting and shareholder event procurement in the United States sustains premium fee structures.
- Professionals:Mid-level managers and functional specialists requiring skill-specific content and practitioner credibility. Brief treatment: Corporate training budgets redirecting toward live keynote engagements compress procurement cycles for this segment.
- Entrepreneurs:Founder and small-business audiences prioritizing actionable frameworks over theoretical models. Brief treatment: Accelerator and incubator networks aggregate demand through pooled speaker series and shared-cost arrangements.
- Students:Academic and early-career audiences reached through institutional speaker series and career services programming. Brief treatment: Fee compression and travel subsidy requirements differentiate procurement economics from corporate segments.
Professionals represent current volume concentration; Executives show the steepest expansion trajectory on leadership development program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate neodymium magnet processing for professional speaker driver assemblies. Fortune 500 corporate campuses in Chicago and Houston sustain the largest procurement pools for executive development programs. Festival circuits in Belgium and the Netherlands anchor venue-level contracts for integrated amplification ecosystems.
United States
Fortune 500 annual meetings in Chicago and Houston drive premium keynote procurement. OSHA noise exposure regulations compel venue operators to specify speakers with precise directivity control for stage monitor positions. The Pacific Northwest clusters touring equipment rental houses serving festival circuits across California and Nevada.
Germany
Industrial trade fairs in Frankfurt and Hannover generate recurring demand for corporate speaker engagements. CE marking and RoHS directives restrict hazardous substance content in crossover components sold across EU member states. Bavaria hosts precision manufacturing facilities supplying waveguide assemblies to touring sound providers.
China
Shenzhen and Dongguan special economic zones concentrate rare earth magnet refining for lightweight driver assemblies. GB standards and MIIT regulations govern wireless microphone spectrum allocations for venue installations. The Pearl River Delta exports finished enclosure systems to rental houses across Southeast Asia.
United Kingdom
London's financial services corridor sustains retainer-based speaker bureau relationships with SaaS companies. GDPR compliance requirements shape content recording and distribution protocols for hybrid delivery formats. The Midlands cluster manufactures hardened enclosure designs for repetitive load-in cycles.
France
EU AI Act disclosure mandates accelerate demand for verified human speakers at live corporate events in Paris and Lyon. Festival circuits in Provence-Alpes-Côte d'Azur lock in venue-level contracts for integrated amplification ecosystems. Île-de-France hosts broadcast infrastructure providers serving hybrid delivery specifications.
Professional Speaker Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with transducer-scale players controlling raw material costs and ecosystem-integrated firms locking in recurring venue contracts. The vendor base concentrates among three strategic archetypes: magnet-scale manufacturers, hardened-enclosure rental specialists, and amplification-ecosystem integrators. Dominant competitive moves include backward integration into neodymium supply chains and strategic partnerships with festival circuit operators.
Within the ecosystem-integrated tier, L-Acoustics and d&b audiotechnik exemplify the amplification-processing lock-in model that secures multi-year venue specifications. JBL Professional occupies a position representing magnet-scale manufacturing leverage across touring and installation product lines. Electro-Voice anchors the hardened-enclosure archetype purpose-built for rental house load-in cycles.
| Leading Market Players |
|---|
| JBL Professional |
| Electro-Voice |
| L-Acoustics |
| Adamson Systems Engineering |
| RCF |
| Meyer Sound |
| QSC |
| NEXO |
| d&b audiotechnik |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap speaker manufacturers in Germany and the United States anchor premium pricing discipline through captive magnet assembly operations, while private-equity-rolled-up rental houses compress procurement costs via centralized cone driver sourcing from Shenzhen. This ownership split concentrates pricing power upstream with magnet-scale producers and downstream with integrated ecosystem vendors, squeezing margin capture for standalone enclosure fabricators caught in the middle.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to rush touring rig configurations demanded by festival operators facing compressed load-in windows. Three-tier pricing structure across premium, standard, and economy levels separates neodymium-equipped line arrays from ferrite-based legacy systems and entry-level portable enclosures. Price differentiation hinges on certification grade for CE-marked EU compliance and volume scale for multi-venue rental house contracts. Pricing pressure stems from rare earth cost volatility in Chinese refining infrastructure, with margins tightening most acutely for mid-tier driver assemblers lacking backward integration. Fortune 500 corporate procurement teams show least price sensitivity for keynote-tier talent access, while regional rental houses absorb maximum cost compression.
Supply Chain Analysis
Freight cost inflation on containerized enclosure shipments from the Pearl River Delta to European festival circuits has prompted rental houses to regionalize inventory staging in Belgium and the Netherlands. Neodymium magnet processing concentrates in China, with secondary cone driver assembly in Malaysia and Mexico serving North American demand. Raw material dependencies span rare earth oxides from Chinese refining infrastructure, treated plywood from Baltic suppliers, and copper voice coil wire from Chilean smelters. Single-source vulnerability in neodymium supply creates exposure to export quota disruptions. Distribution runs through speaker bureau networks for corporate talent procurement and direct manufacturer relationships for venue installation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over neodymium magnet supply chains and amplification processing IP determines long-term margin capture. Players securing captive rare earth sourcing or locking venue-level ecosystem contracts will outcompete modular component suppliers.
For Market Incumbents: Anticipate FCC spectrum reallocation proceedings by pre-certifying wireless microphone configurations across alternative frequency blocks before venue operators face retrofit deadlines. Secure backward integration into neodymium magnet supply through offtake agreements with Shenzhen-based refiners to buffer against Chinese export quota volatility. Defensive consolidation of touring rental houses in California and Nevada will compress competitor access to festival circuit specifications. For New Entrants and Emerging Players: Regional university speaker series in the Midwest United States represent an underserved buyer archetype with pooled procurement budgets and lower credential barriers than Fortune 500 accounts. White-space targets include hybrid delivery infrastructure for mid-market SaaS companies in Austin and Denver, plus certified OSHA-compliant monitor enclosures for corporate training venues in Chicago. A direct-to-venue sales model bypassing established speaker bureaus offers fastest penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor hardened-enclosure specialists with repetitive load-in cycle expertise in the United Kingdom Midlands. Long-term viability over the next decade rests on acquisition of manufacturers possessing CE marking bandwidth and RoHS-compliant finish capabilities ahead of EU compliance deadlines. The signal to watch is FCC spectrum auction outcomes that would force premature wireless system refresh cycles across United States venue inventories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium sourcing from Shenzhen refiners insulates margin from Chinese export quota volatility. |
| Hybrid Delivery Infrastructure Buildout | Simultaneous in-room and streaming capability locks in SaaS corporate accounts in Austin and Denver. |
| CE Marking Bandwidth Expansion | Accelerated hazardous substance testing capacity secures EU venue contracts ahead of RoHS deadlines. |
| Festival Circuit Partnership | Multi-year venue specifications in Belgium and Netherlands anchor recurring amplification ecosystem revenue. |
| OSHA Compliance Certification | Precise directivity control documentation satisfies United States corporate training venue procurement requirements. |
Study Parameters
Document review covered SEC filings from publicly listed audio equipment manufacturers, FCC spectrum allocation dockets, EU AI Act implementation guidance, and OSHA noise exposure regulatory updates, complemented by interviews with touring rental house operations directors, speaker bureau talent managers, venue AV procurement leads, and neodymium magnet supply specialists. Secondary validation drew from customs trade data on loudspeaker enclosure imports, industry association membership directories, and patent filings for waveguide and amplification processing technologies. Bottom-up demand modeling from corporate training budget disclosures and top-down supply assessment from magnet processing capacity estimates were triangulated against midpoint projections.
Segment-level outputs across the projection horizon reflect modeled splits by speaker type, delivery mode, industry vertical, and target audience seniority, with cross-segment elasticity parameters calibrated to historical procurement pattern shifts. CAGRs were derived from regression analysis of Fortune 500 executive development spending, SaaS company event marketing allocations, and festival circuit infrastructure investment cycles. Industry-specific forecast inputs include FCC spectrum reallocation probability weights and EU AI Act enforcement timeline assumptions.
Revisions become necessary when rare earth export policy shifts, wireless spectrum reallocation decisions, or synthetic voice disclosure enforcement intensity diverge from baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
K-Pop Events Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Drone Art Performance Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Online Event Ticketing Market
Events and Festivals
Music Fountain Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Global Special Effects Fog and Smoke Machines Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
Indoor Entertainment Center Market