
 UK Arts Promoter Market | 2026-2036
UK Arts Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
UK Arts Promoter Market Insights
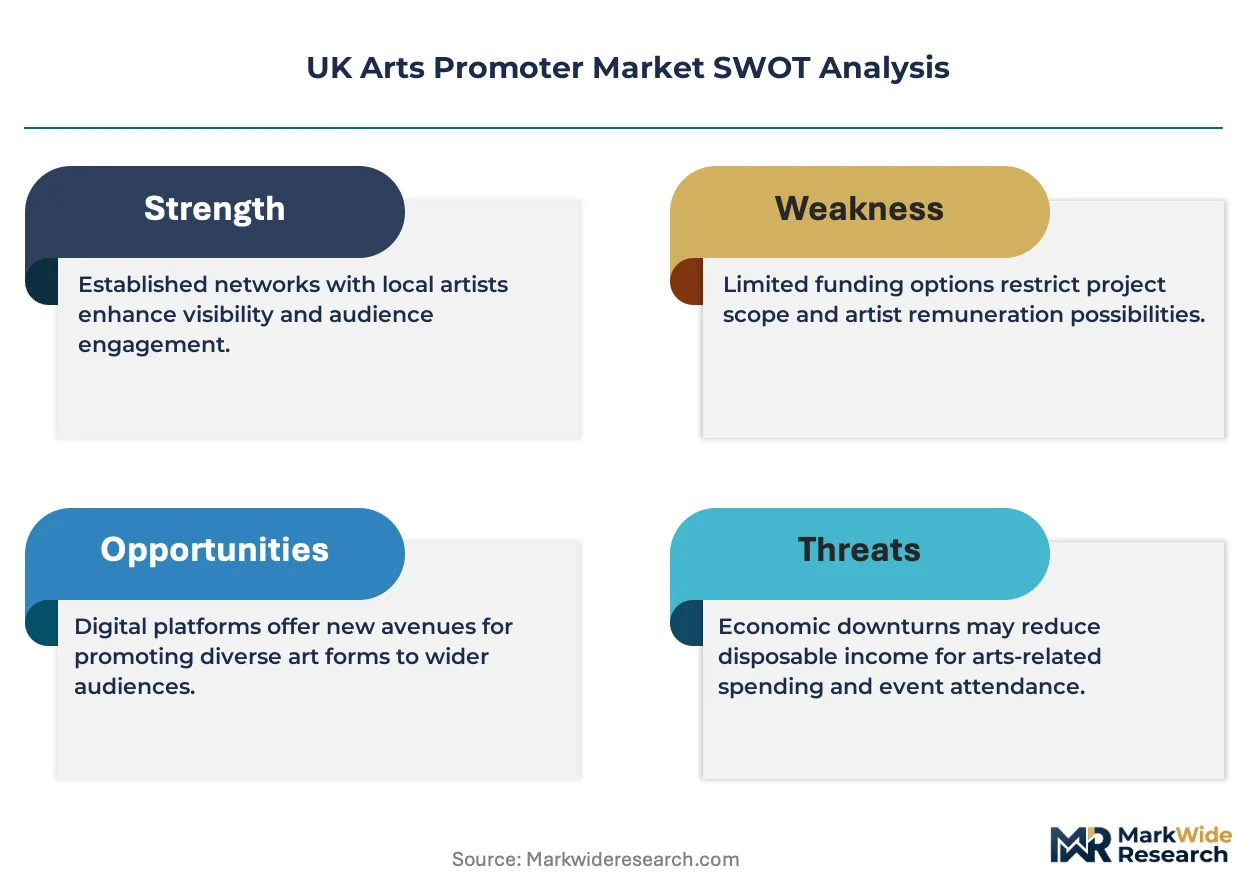
Multi-source talent procurement is decoupling from the traditional single-venue promoter model across the United Kingdom. Live Nation Entertainment leverages its international touring network to anchor arena-scale music events in British cities. AEG Presents competes through its control of The O2 and regional venue partnerships, while SJM Concerts specializes in mid-cap theatre and comedy tours that sustain consistent regional demand.
Arts promoters are entities that finance, market, and operationalize live cultural events across theatre, music, dance, and visual arts disciplines, typically earning revenue through ticket sales, sponsorships, and ancillary merchandising while managing venue logistics, artist contracting, and audience engagement platforms. Theatre and music promotion types occupy the largest margin pools due to higher per-ticket yields and repeatable touring formats. International event scale segments are recording the fastest expansion as British promoters export productions to European and Middle Eastern markets, while local event scale segments remain mature with stable but slower growth trajectories.
The UK's arts promoter sector operates under oversight from Arts Council England funding frameworks, the Health and Safety Executive's event licensing requirements, and local authority entertainment licensing under the Licensing Act 2003. These regulators shape demand by conditioning grant eligibility on accessibility standards and mandating crowd safety protocols that influence venue selection and production cost structures. Stakeholders must monitor how digital ticketing transparency rules and carbon reporting obligations for touring productions will reshape operational compliance and capital allocation decisions.
Market Dynamics
Immersive digital staging technologies are compressing production timelines and expanding venue flexibility across British arts promotion, forcing capital reallocation toward hybrid physical-digital infrastructure.
Growth Catalysts
- Arts Council England's Creative Industries Sector Vision:This funding framework channels public investment toward accessibility-compliant productions, expanding eligible promoter pipelines and subsidizing touring scale.
- Immersive digital staging:Projection mapping and real-time rendering tools reduce physical set construction costs while enabling rapid venue reconfiguration for multi-city theatre tours.
- Greater Manchester venue clustering:Concentrated cultural infrastructure in this northern city generates route efficiency for mid-cap promoters serving repeat regional audiences.
Market Restraints
- Energy input volatility:Touring productions face unpredictable diesel and electricity costs for transport and venue operations, compressing margin predictability on multi-date contracts.
- London venue supply concentration:Over-dependence on West End and arena infrastructure in the capital creates bottleneck risk and inflated rental premiums for national promoters.
- Licensing Act 2003 compliance friction:Local authority entertainment licensing variations across 326 English councils generate administrative overhead and timeline uncertainty for rolling tours.
Strategic Opportunities
- Edinburgh Festival Fringe export model:Scottish promoters can replicate this proven format in underpenetrated English regional cities lacking comparable annual cultural anchors.
- Carbon reporting mandates:Arts Council England's emerging environmental compliance requirements create first-mover advantage for promoters with verified low-carbon touring infrastructure.
- Streaming-physical convergence:Hybrid broadcast technologies enable simultaneous venue and digital ticket revenue streams, expanding addressable audience beyond physical capacity constraints.
Industry Challenges
- Technical production skills shortage:Qualified lighting designers and live sound engineers are scarce outside London, constraining tour quality consistency in regional markets.
- Legacy ticketing system integration:Promoters face friction merging modern dynamic pricing platforms with entrenched venue-controlled access systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Arts Promoter Market |
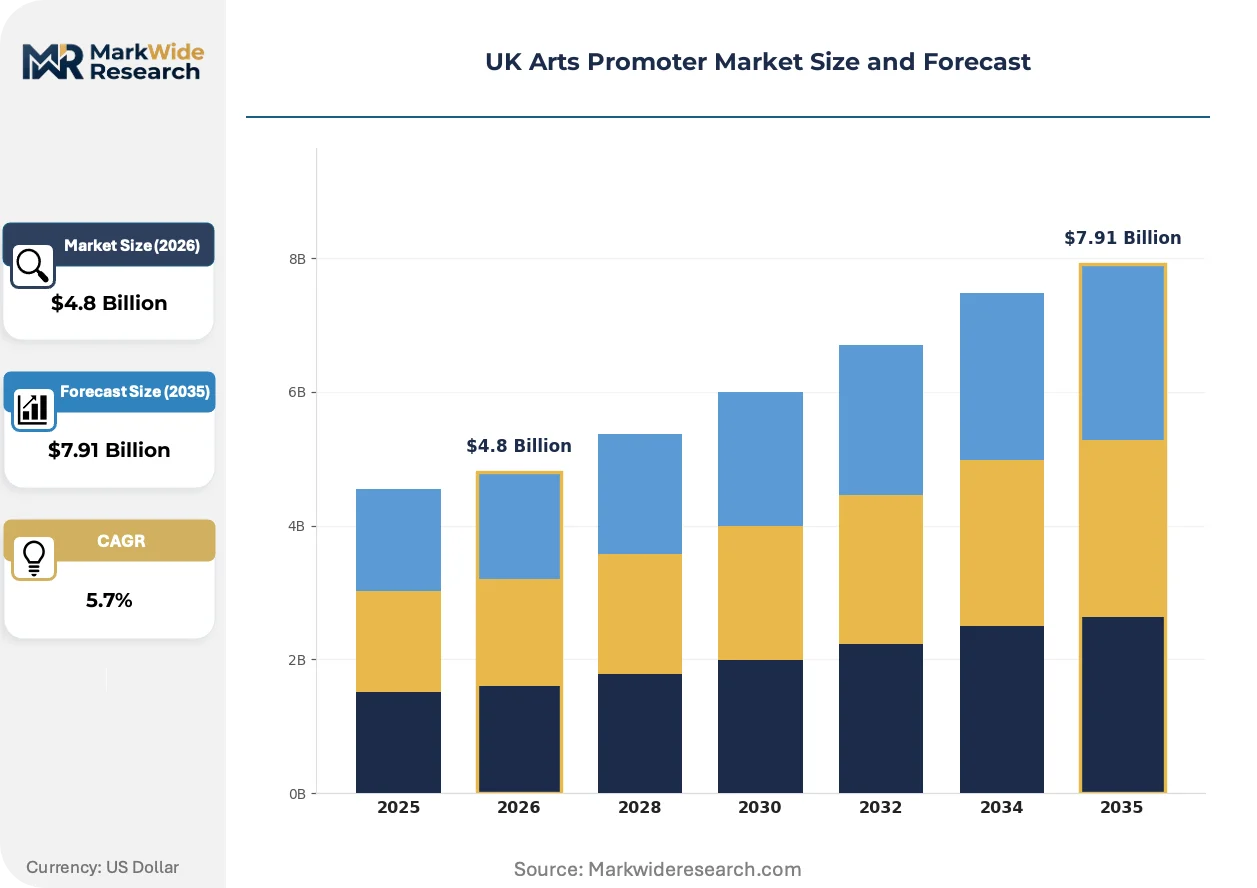
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Promotion Type: Theatre, Music, Dance, Visual Arts Event Scale: Local, Regional, National, International Audience Segment: Students, Professionals, Tourists, Families Funding Source: Private Sponsors, Government Grants, Ticket Sales, Donations |
| Companies Covered | Live Nation Entertainment, AEG Presents, Ambassador Theatre Group, SJM Concerts, Trafalgar Releasing, The O2, Metropolis Music, Eventim UK, Kilimanjaro Live, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Arts Promoter Market Trends and Innovations
Digital production tools and sustainability mandates are restructuring how British promoters conceive, finance, and deliver live cultural experiences to fragmented audience segments.
Extended reality (XR) staging systems combining augmented and virtual elements are absorbing traditional scenic design functions in touring theatre. Mid-cap promoters in Birmingham and Bristol are piloting these tools for rapid venue adaptation. The technology is absorbing set construction budgets into software licensing and hardware rental lines, flattening upfront capital requirements.
The Licensing Act 2003 is tightening scrutiny of temporary event notices for outdoor and non-traditional venues. Local authorities in England are extending consultation periods and adding crowd safety conditions that extend lead times. Promoters targeting pop-up and festival formats are responding by pre-negotiating multi-year venue partnerships to secure predictable approval pathways.
Audience subscription models are displacing single-ticket purchasing for recurring venue programmes. Theatres in Liverpool and Newcastle are bundling drama, comedy, and music events into seasonal memberships. This shift is most visible among under-35 demographics in northern English cities where discretionary entertainment spending faces competing digital subscription pressures.
UK Arts Promoter Market Segmentation
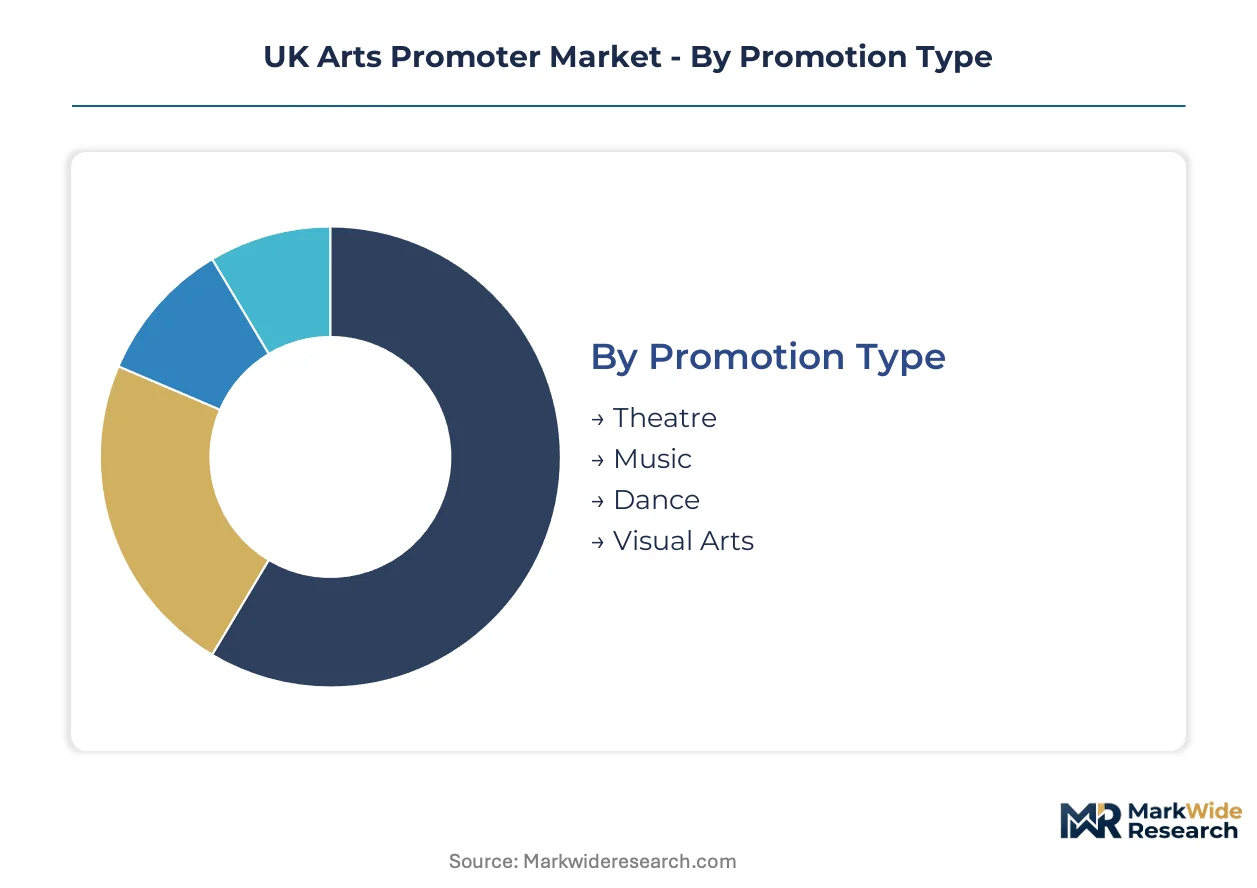
Segmentation in UK arts promotion reveals how revenue pools concentrate across discipline types and audience economics. Promoters calibrate production scale, funding mix, and geographic reach based on which segments command sustainable margin structures.
Promotion Type:
Standardization dominates touring music formats while theatre retains bespoke production complexity across this spectrum.
- Theatre:Touring drama and musical productions command premium ticket yields through repeatable formats with rotating casts. West End originators in London export proven shows to Manchester, Edinburgh, and Bristol, leveraging Arts Council England touring subsidies to offset venue rental premiums.
- Music:Arena and mid-cap concert promoters deploy standardized rider templates and rapid load-in protocols across British cities. Live Nation Entertainment and AEG Presents anchor this segment through control of The O2, AO Arena Manchester, and SEC Glasgow.
- Dance:Contemporary ballet and touring companies rely on mixed public-private funding with lower per-ticket revenue than music or theatre. Scottish promoters leverage Edinburgh's festival infrastructure for international co-productions.
- Visual Arts:Temporary exhibition promoters face higher venue adaptation costs due to climate control and security requirements. Commercial galleries in London and Manchester dominate private sponsorship capture for blockbuster shows.
Most installed capacity flows through Music. Expansion is steepest in Theatre.
Event Scale:
Cost tier separation shapes promoter capital requirements and risk exposure across venue sizes.
- International:British promoters export productions to European and Middle Eastern markets, generating foreign currency revenue streams. These operations demand extended advance planning due to cross-border licensing under the Licensing Act 2003 and local safety regulator compliance.
- National:Rolling tours across England, Scotland, and Wales require multi-city venue partnerships and standardized technical specifications. SJM Concerts specializes in this tier for mid-cap theatre and comedy tours.
- Regional:Concentrated northern England circuits around Manchester, Leeds, and Liverpool generate route efficiency for repeat audience cultivation. Greater Manchester's venue clustering reduces transport costs per show.
- Local:Single-city promoters serve stable but slower-growth markets with lower upfront capital requirements. These operators face compressed margins from limited ancillary revenue opportunities.
Highest revenue concentration sits in National. International climbs fastest.
Audience Segment:
Customer type determines pricing power and subscription potential across British cities.
- Professionals:Discretionary income concentration in London, Edinburgh, and Manchester sustains premium pricing for midweek performances. These audiences drive subscription membership adoption at theatres in Liverpool and Newcastle.
- Tourists:West End and Edinburgh Festival Fringe visitors pay elevated rates for short-run shows with limited advance purchase windows. This segment absorbs highest per-ticket yields during peak summer months.
- Families:School holiday programming and pantomime seasons generate predictable volume across regional markets. These events rely on merchandise and concession revenue to supplement ticket income.
- Students:Price-sensitive demand concentrates in university cities including Oxford, Cambridge, and Glasgow. Arts Council England accessibility mandates require subsidized ticket allocations for this segment.
Professionals account for largest revenue share. Tourists expand most quickly.
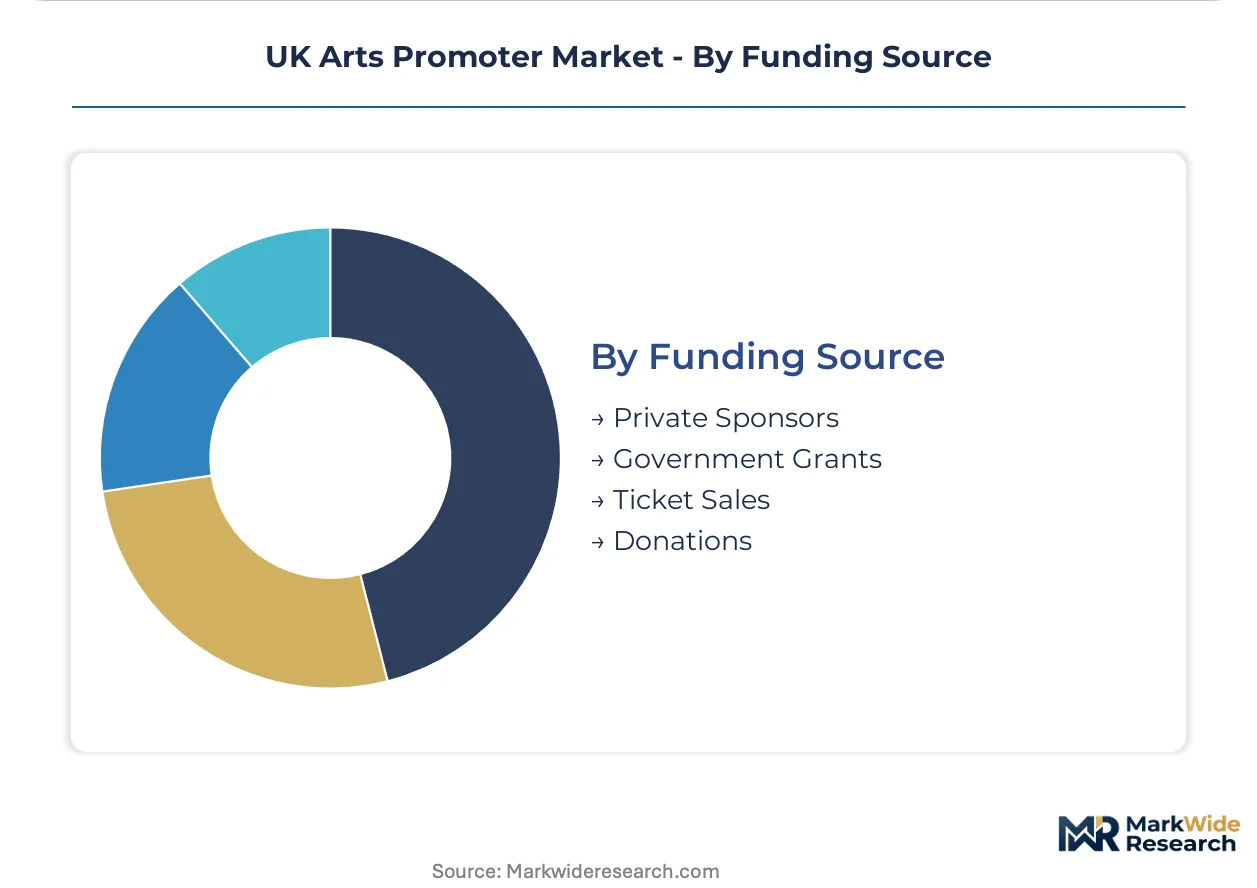
Funding Source:
Margin stability varies with funding predictability and sponsor concentration risk.
- Ticket Sales:Primary revenue driver for commercial music promoters with dynamic pricing capabilities. Digital platform fees and venue-controlled access systems create friction in margin capture.
- Government Grants:Arts Council England funding flows to accessibility-compliant and touring productions, subsidizing risk for experimental work. Grant eligibility requires carbon reporting and audience development metrics.
- Private Sponsors:Corporate partnerships concentrate around high-visibility London events and Edinburgh Festival Fringe. Banking and luxury goods brands dominate this pool.
- Donations:Philanthropic support sustains non-profit theatre and dance companies with limited commercial touring potential. Major donors cluster in Greater London and Edinburgh.
Ticket Sales dominates funding composition. Government Grants gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London's concentration of West End theatres and arena infrastructure generates disproportionate promoter revenue relative to population share. Scotland and northern England present contrasting growth profiles shaped by festival economics and venue clustering patterns.
Greater London and the Southeast
West End theatres and The O2 anchor national touring originations for theatre and music promoters. Arts Council England's National Portfolio funding directs subsidy toward accessibility-compliant productions staged in this corridor. The Southbank Centre and Barbican cluster generates year-round demand for contemporary dance and visual arts promoters.
Scotland
Edinburgh Festival Fringe and Edinburgh International Festival create concentrated seasonal demand for temporary event promoters. Licensing Act 2003 compliance through Edinburgh City Council shapes lead times for outdoor and non-traditional venue programming. Glasgow's SEC and King's Theatre cluster supports year-round music and theatre touring circuits.
North England
Manchester's AO Arena and Albert Hall concentration enables route efficiency for mid-cap music promoters serving repeat regional audiences. Greater Manchester Combined Authority cultural investment funds expand eligible venue pipelines for experimental work. Liverpool's Everyman and Playhouse theatres anchor touring drama circuits with strong subscription membership adoption.
Midlands
Birmingham Hippodrome and Symphony Hall generate consistent demand for touring musical theatre and classical music promoters. West Midlands Combined Authority creative sector funding supports venue infrastructure upgrades. Bristol's Colston Hall and Old Vic cluster attracts contemporary theatre promoters piloting immersive digital staging technologies.
Wales and Northern Ireland
Wales Millennium Centre and Belfast's Grand Opera House serve as primary touring destinations with limited indigenous promoter capacity. Arts Council of Wales and Arts Council of Northern Ireland funding frameworks subsidize accessibility and touring scale for productions originating in England. Cardiff and Belfast venue density constrains multi-date routing efficiency for national promoters.
UK Arts Promoter Market Competitive Landscape
Established promoters occupy the standard tier; emerging entrants pursue immersive digital formats and carbon-neutral touring infrastructure. The vendor base stratifies across three tiers: international arena-scale operators, national mid-cap specialists, and regional single-city promoters. Strategic archetypes include venue-integrated conglomerates, grant-dependent non-profits, and subscription-model theatre operators. Dominant competitive moves involve multi-year venue partnership pre-negotiation and hybrid physical-digital production capability acquisition.
Within the venue-integrated tier, Live Nation Entertainment and AEG Presents occupy positions anchored by arena control and international touring networks. SJM Concerts exemplifies the mid-cap specialist archetype through sustained regional theatre and comedy circuit presence. These three entities represent distinct scale vectors: global touring infrastructure, capital-intensive venue assets, and route-optimized national circuits.
| Leading Market Players |
|---|
| Live Nation Entertainment |
| AEG Presents |
| Ambassador Theatre Group |
| SJM Concerts |
| Trafalgar Releasing |
| The O2 |
| Metropolis Music |
| Eventim UK |
| Kilimanjaro Live |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up venue operators anchor supply-side concentration across British arts promotion, concentrating pricing power in arena-scale infrastructure while compressing margins for mid-cap touring specialists dependent on third-party rental agreements.
Pricing Analysis
Input-cost pass-through from diesel transport and venue electricity tariffs intensifies pricing pressure on multi-date touring contracts. Pricing stratifies across premium West End theatre, standard mid-cap regional venues, and economy outdoor festival tiers. Brand premium and Arts Council England accessibility compliance drive differentiation within each tier. Student segments in university cities exhibit highest price sensitivity, while tourist audiences at Edinburgh Festival Fringe absorb lowest elasticity.
Supply Chain Analysis
Technical production equipment supply rests on German lighting manufacturers, Dutch audio systems producers, and UK-based staging fabricators. Touring productions draw from projection mapping hardware, modular scenic construction materials, and temporary venue infrastructure. Single-source vulnerability concentrates in specialized LED wall and real-time rendering software licensing. Distribution runs through venue-integrated equipment pools and third-party rental houses serving rolling national circuits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK arts promoter market functions as a geographic-arbitrage play between Greater London's inflated venue premiums and Greater Manchester's clustered cultural infrastructure, where route efficiency generates 20-30% production cost savings on comparable touring circuits.
For Market Incumbents: Cement multi-year venue partnership pre-negotiations to lock rental rates ahead of Licensing Act 2003 compliance friction escalation. Acquire immersive digital staging capabilities through specialist technical production firms to defend against carbon-reporting-mandate displacement. Vertical integration into hybrid broadcast infrastructure captures streaming-physical convergence revenue.
For New Entrants and Emerging Players: Direct-to-audience subscription platforms offer lowest customer acquisition friction for under-35 demographics in northern English cities. Target Edinburgh Festival Fringe export replication in underpenetrated English regional markets lacking annual cultural anchors. Lead with carbon-neutral touring certification to differentiate for Arts Council England grant eligibility.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional single-city promoters with proven subscription membership adoption and underutilized venue assets. Long-term viability hinges on hybrid production capability and grant-secured funding diversification. Watch Arts Council England carbon reporting mandate enforcement timing as inflection indicator for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Venue Partnership Pre-Negotiation | Locks rental premiums ahead of Licensing Act 2003 timeline extensions across 326 English councils. |
| Hybrid Broadcast Infrastructure Investment | Enables simultaneous physical and digital ticket revenue beyond venue capacity constraints. |
| Carbon-Neutral Touring Certification | Secures first-mover Arts Council England grant eligibility as environmental compliance tightens. |
| Immersive Digital Staging Capability Acquisition | Compresses production timelines and reduces physical set construction capital requirements. |
| Subscription Membership Platform Launch | Captures recurring revenue from under-35 demographics facing competing digital subscription pressures. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with theatre programming directors, venue technical managers, Arts Council England funding officers, and touring production accountants with secondary validation against Arts Council England annual reports, Licensing Act 2003 local authority filings, and SEC disclosures from publicly listed entertainment conglomerates. Bottom-up venue capacity and ticket yield estimates triangulated against top-down sector revenue benchmarks.
Comparable-period anchoring linked projection assumptions to historical touring volume patterns and venue utilization rates across the analysis window. Segmentation dimensions modeled include promotion type, event scale, audience segment, and funding source. CAGRs derived from trend-line extrapolation of ticket volume growth and per-capita entertainment expenditure patterns, incorporating immersive digital technology adoption curves and carbon compliance cost trajectories as industry-specific inputs.
The model assumes a particular technology adoption path for immersive digital staging; alternative pathways for extended reality deployment would alter the outlook. Forecasts reflect assumptions about Arts Council England funding continuity and Licensing Act 2003 enforcement consistency. Energy input volatility and technical production skills shortage warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
Online Event Ticketing Market
Events and Festivals
Drone Art Performance Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
Professional Speaker Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Events Market
Events and Festivals
Virtual Events Market
Events and Festivals
North America K-Pop Events Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
India Event Services Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
Photo Booth Market
Events and Festivals
Music Fountain Market
Events and Festivals
Portable Photo Booth Market