
 Events and Exhibition Market | 2026-2036
Events and Exhibition Market Size, Share, and Industry Trends Forecast 2026-2036
Events and Exhibition Market Foresight
Hybrid-ready specification tiers is reorganizing procurement priorities across the events and exhibition value chain. Freeman leverages its integrated service portfolio to anchor large-scale corporate and association accounts in North America. IMEX Group specializes in international buyer-seller matching, while PRO EXPO competes through rapid-turnaround booth fabrication for mid-market exhibitors.
Events and exhibitions constitute temporary, purpose-built environments designed to facilitate commercial display, knowledge exchange, and relationship formation among concentrated professional audiences, typically incorporating modular aluminum framing systems, LED-integrated surfaces, and climate-controlled HVAC specifications to sustain multi-day occupancy. Trade shows and conferences represent the most structurally embedded formats, with trade shows commanding the largest share of square-meter bookings and sponsorship revenue, while booth design services capture disproportionate margin pools due to customization intensity and repeat-client retention dynamics.
Regulatory oversight from the US Occupational Safety and Health Administration, Germany's KBA-aligned venue inspection protocols, and the UAE's MOHAP event licensing framework collectively shape load-bearing standards, crowd-density limits, and electrical certification requirements that determine market access for contractors and venue operators. Stakeholders must monitor how evolving sustainability disclosure rules, including the EU's CSRD and emerging ISO 20121 alignment pressures, will redefine material sourcing and carbon accounting obligations across the exhibition supply base.
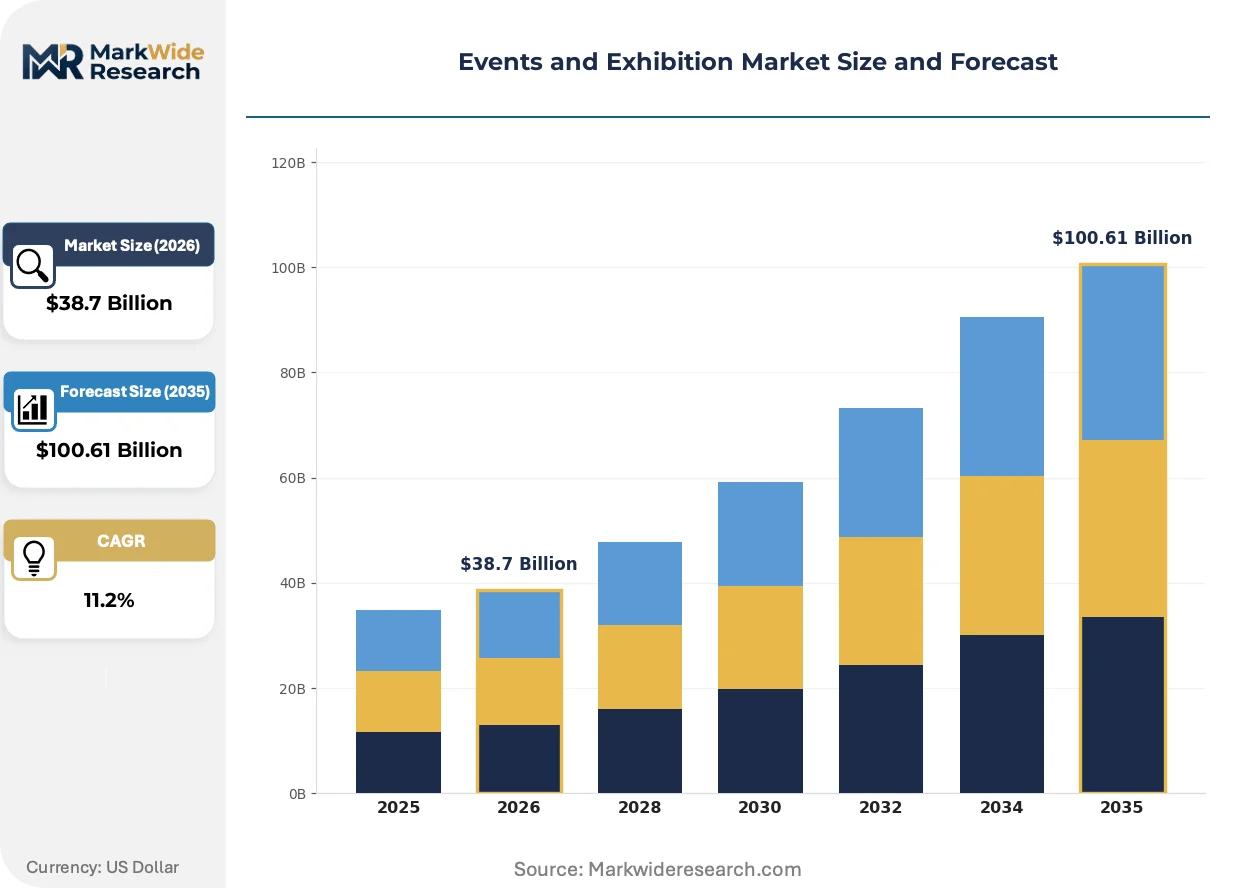
Market Dynamics
Hybrid-ready specification tiers are reorganizing procurement priorities across the events and exhibition value chain, forcing booth fabricators and venue operators to re-certify infrastructure for simultaneous physical and digital delivery.
Growth Catalysts
- Pharmaceutical exhibitor concentration:Biotechnology and life sciences companies now anchor the largest booth footprints at major medical convention circuits, driving premium square-meter bookings and multi-year sponsorship commitments.
- EU CSRD alignment pressure:Sustainability disclosure mandates are accelerating carbon accounting investments across European exhibition supply chains, creating certified-green venue differentiation.
- LED-integrated surface adoption:Modular display systems with embedded digital surfaces are compressing setup timelines while enabling real-time content reconfiguration between show days.
Market Restraints
- Aluminum alloy price volatility:Booth framing material costs fluctuate with energy-intensive smelting input prices, squeezing fabrication margins on fixed-price contracts.
- German venue certification backlog:KBA-aligned inspection protocols for hybrid-ready fire-safety systems are extending venue approval timelines by 4-8 months.
- Virtual event platform substitution:Persistent remote collaboration tools are capturing a portion of knowledge-exchange budgets previously allocated to physical exhibition attendance.
Strategic Opportunities
- Saudi Arabia giga-project circuit:NEOM and Red Sea development announcements are generating specialized infrastructure and capital equipment exhibition demand with limited incumbent competition.
- ISO 20121 certification pathway:Event sustainability management system accreditation is opening preferred-supplier status with ESG-mandated corporate accounts.
- HVAC-AV convergence:Climate control and broadcast infrastructure integration is creating bundled specification opportunities for systems integrators serving multi-day broadcast-anchored exhibitions.
Industry Challenges
- Hybrid technical director scarcity:Professionals capable of orchestrating simultaneous in-person and streaming production workflows command premium compensation and limited availability.
- Legacy venue electrical retrofit costs:Older convention centers face substantial capital requirements to meet LED-integrated booth power density and redundant connectivity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Events and Exhibition Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $100.61 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Trade Shows, Conferences, Seminars, Expos Service Type: Booth Design, Event Management, Sponsorship, Marketing Industry Vertical: Technology, Healthcare, Education, Retail Customer Type: Exhibitors, Attendees, Sponsors, Partners |
| Companies Covered | Expo Exhibition Stands, Ingenia Stand, Freeman, CrewExpo, Foster Display Group, Adam Expo Stand Solutions, PRO EXPO, IMEX Group, Expostandbuild, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Events and Exhibition Market Shifts & Advancements
Exhibition infrastructure is pivoting from static display environments to programmable, sensor-enabled spaces that capture attendee behavioral data and enable real-time sponsor content optimization.
Modular aluminum framing systems with embedded IoT sensors are displacing conventional passive booth structures across pharmaceutical and automotive exhibition segments. Major corporate exhibitors in Germany and the United States are specifying these intelligent frameworks for 40% of new booth builds. The technology is displacing post-show manual lead-capture processes with automated engagement scoring and immediate CRM integration.
Germany's KBA-aligned venue inspection protocols are mandating redundant fire-suppression and crowd-density monitoring systems for hybrid-certified exhibition halls. This regulatory tightening is accelerating demolition-and-rebuild cycles for aging European convention infrastructure. Frankfurt and Munich venue operators are absorbing compliance costs through multi-year technology partnerships with certified systems integrators.
Corporate procurement departments are consolidating exhibition spend under outcome-based vendor agreements that tie contractor payments to qualified lead generation and attendee engagement metrics. This shift is compressing traditional booth fabrication and logistics providers into integrated service models spanning creative, build, and digital analytics. The transformation is most visible among Fortune 500 technology and healthcare exhibitors operating across Las Vegas, Chicago, and Orlando circuits.
Events and Exhibition Market Segmentation
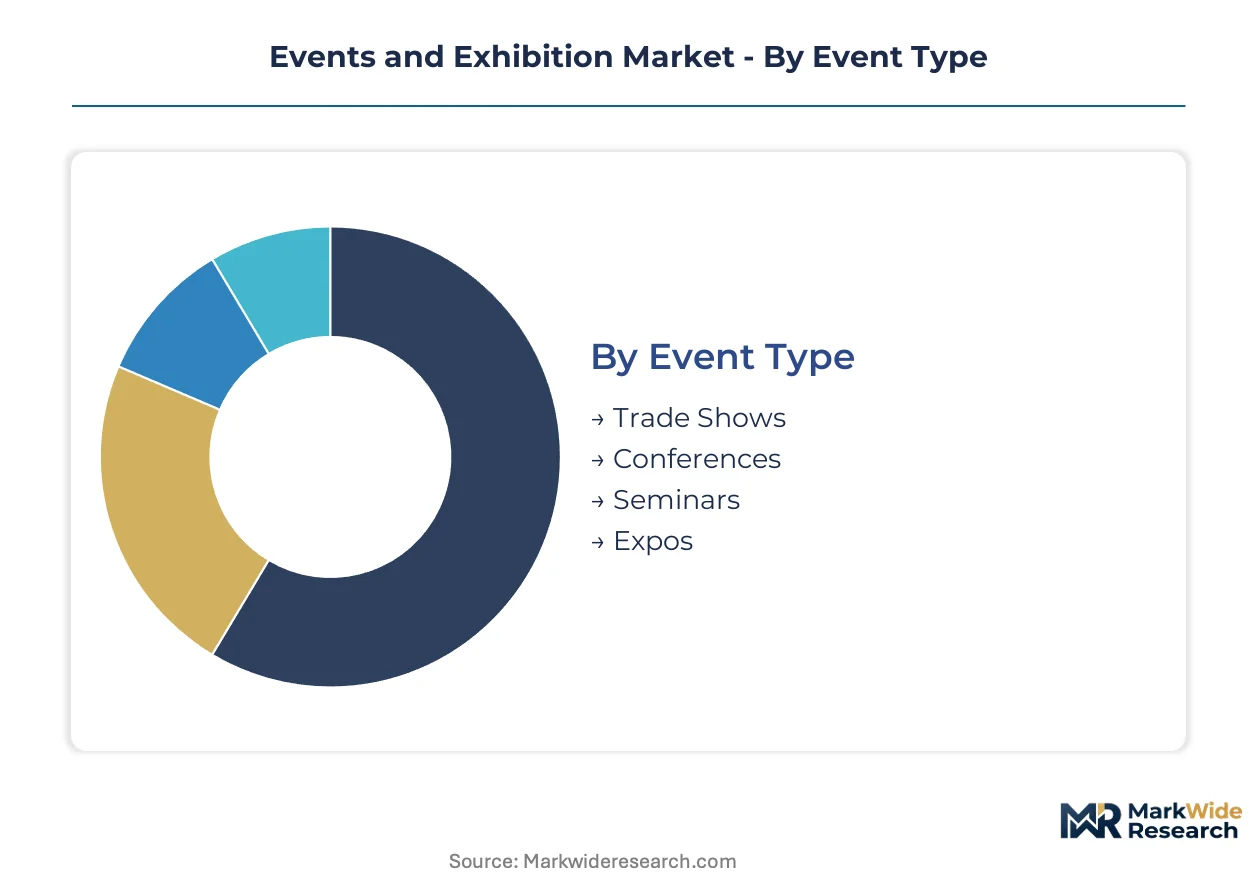
Events and exhibition market segmentation reveals how procurement budgets flow through distinct service channels and participant categories. Understanding these divisions exposes where margin pools concentrate and which verticals drive infrastructure investment cycles.
Event Type:
Channel mix varies sharply across event formats, with venue operators and service providers configuring entirely different staffing and technical specifications for each.
- Trade Shows:Multi-day commercial exhibitions occupying dedicated convention halls with modular booth systems and freight-handling infrastructure. Pharmaceutical and automotive manufacturers in Germany and the United States anchor square-meter bookings through multi-year anchor-tenant agreements.
- Conferences:Knowledge-exchange formats prioritizing auditorium seating, broadcast infrastructure, and simultaneous interpretation capabilities. Corporate technology accounts in Las Vegas and Orlando are consolidating spend here under outcome-based vendor contracts tied to attendee engagement metrics.
- Seminars:Intimate instructional gatherings requiring minimal booth fabrication but specialized AV and climate specifications.
- Expos:Consumer-facing demonstration events with high foot-traffic engineering and retail-anchored sponsorship structures.
Trade shows dominate installed base. Conferences are where expansion concentrates.
Service Type:
Cost tiering separates premium custom fabrication from standardized logistics packages, with procurement departments increasingly bundling across service layers.
- Booth Design:Custom architectural and structural planning for modular aluminum framing systems with LED-integrated surfaces and IoT sensor embedding. European pharmaceutical exhibitors are specifying intelligent frameworks for qualified lead capture and real-time CRM integration.
- Event Management:End-to-end coordination spanning venue contracting, freight logistics, and on-site technical direction. Hybrid-certified technical directors command premium compensation due to scarcity of professionals capable of orchestrating simultaneous physical and streaming workflows.
- Sponsorship:Revenue packaging combining physical space allocation with digital impression guarantees and attendee data access rights.
- Marketing:Pre-event promotion and post-show analytics services tied to engagement scoring and attribution modeling.
Booth design captures the steepest margin expansion. Event management is climbing the fastest as hybrid complexity escalates.
Industry Vertical:
Application intensity determines infrastructure specifications, with healthcare and technology verticals driving divergent certification and technical requirements.
- Technology:Software and hardware vendors requiring redundant connectivity, broadcast-grade AV, and real-time demo environments. Fortune 500 accounts operating across Las Vegas, Chicago, and Orlando circuits are consolidating exhibition spend under integrated service models.
- Healthcare:Medical device and pharmaceutical exhibitors subject to FDA promotional guidelines and EMA transparency requirements. Biotechnology companies now anchor the largest booth footprints at major medical convention circuits in the United States and Germany.
- Education:University and training providers with seasonal booking patterns and public-sector procurement constraints.
- Retail:Consumer goods and fashion exhibitors prioritizing high-traffic hall placement and experiential activation zones.
Healthcare dominates premium square-meter bookings. Technology is gaining share fastest through digital-native hybrid specifications.
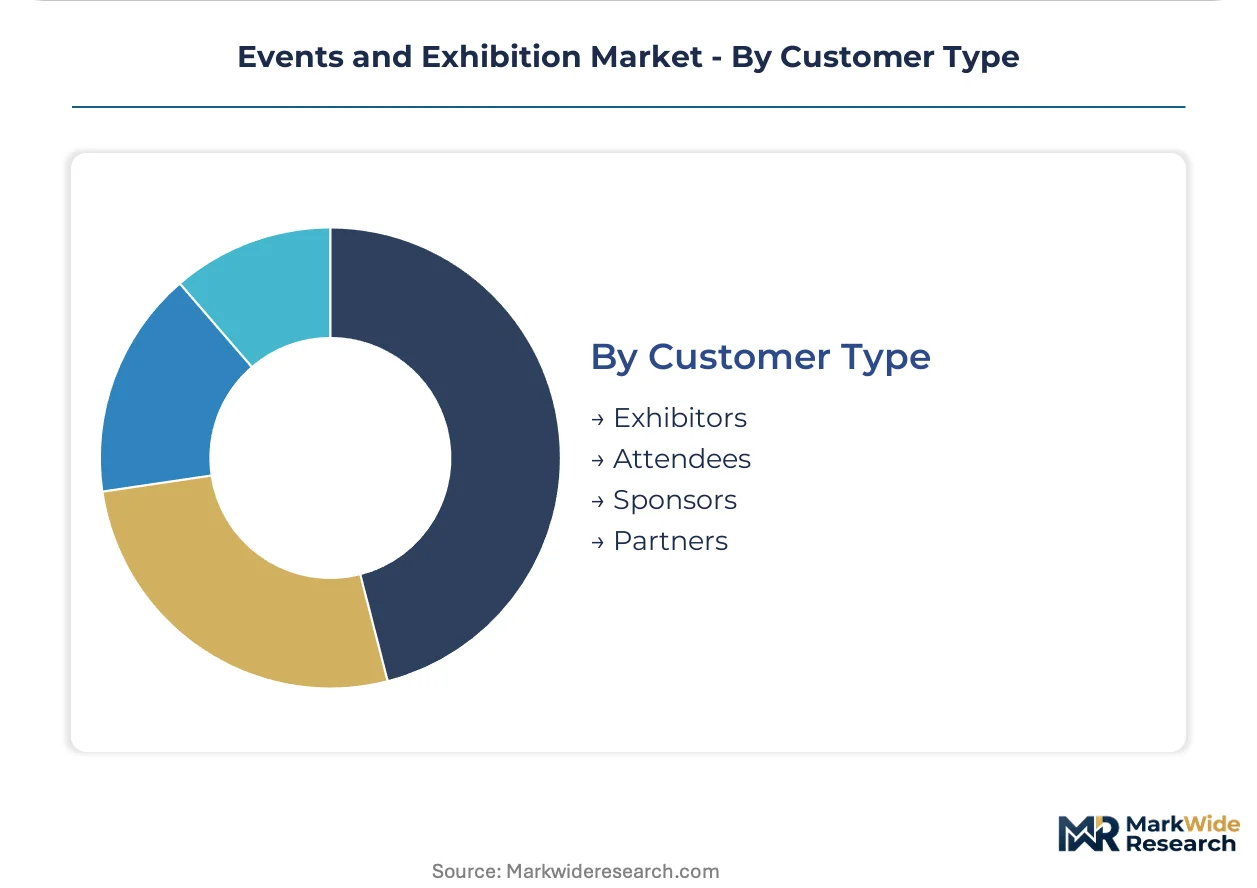
Customer Type:
Volume concentration and margin sensitivity diverge across participant categories, with procurement authority shifting toward centralized corporate functions.
- Exhibitors:Companies purchasing booth space, design, and logistics services to display products and capture leads. Corporate procurement departments are consolidating this spend under vendor agreements tying payments to qualified lead generation outcomes.
- Attendees:Individual professionals and corporate delegations purchasing admission and travel packages, with behavioral data becoming a monetizable asset for venue operators.
- Sponsors:Brands funding event programming in exchange for visibility and access rights, increasingly demanding engagement metrics and carbon disclosure alignment.
- Partners:Media, association, and technology collaborators contributing content or distribution in exchange for reciprocal value.
Exhibitors dominate revenue contribution. Sponsors are where pricing power is expanding most quickly through data and ESG requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exhibition venue infrastructure concentrates in metropolitan clusters where pharmaceutical, automotive, and technology exhibitors anchor multi-year booking commitments. Convention center operators in Germany, the United States, the United Arab Emirates, China, and Saudi Arabia are absorbing compliance costs for hybrid-ready certification and fire-safety retrofits.
United States
Las Vegas, Orlando, and Chicago anchor North America's largest exhibition complexes through multi-year anchor-tenant agreements with Fortune 500 technology and healthcare accounts. OSHA load-bearing standards and electrical certification requirements determine contractor market access across major convention circuits. Corporate procurement departments in these metropolitan markets are consolidating exhibition spend under outcome-based vendor agreements tied to qualified lead generation metrics.
Germany
Frankfurt and Munich venue operators are absorbing KBA-aligned inspection protocol costs through multi-year technology partnerships with certified systems integrators. The country's national fire-safety regulator mandates redundant fire-suppression and crowd-density monitoring systems for hybrid-certified exhibition halls. Pharmaceutical and automotive manufacturers anchor square-meter bookings through multi-year commitments at these metropolitan convention centers.
United Arab Emirates
Dubai and Abu Dhabi are generating specialized infrastructure exhibition demand through giga-project development announcements with limited incumbent competition. MOHAP event licensing frameworks shape crowd-density limits and electrical certification requirements for venue operators and contractors. Venue operators in these emirates are re-certifying infrastructure for simultaneous physical and digital delivery to capture pharmaceutical and biotechnology exhibitor investment.
China
Yangtze River Delta and Pearl River Delta metropolitan clusters are expanding LED-integrated surface adoption across modular display systems for real-time content reconfiguration. The country's national standards administration oversees technical specifications for booth framing materials and broadcast infrastructure integration. Major corporate exhibitors in Shanghai and Shenzhen are specifying intelligent frameworks with embedded IoT sensors for automated engagement scoring.
Saudi Arabia
NEOM and Red Sea development announcements are generating specialized capital equipment exhibition demand with limited incumbent competition. The Saudi Food and Drug Authority regulates promotional guidelines for healthcare exhibitors at major medical convention circuits. Riyadh-based venue operators are certifying infrastructure for hybrid-ready specification tiers to capture biotechnology and life sciences company booth investment.
Events and Exhibition Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the events and exhibition value chain. Integrated service providers with end-to-end coordination capabilities capture large-scale corporate and association accounts, while rapid-turnaround fabricators compete for mid-market exhibitor contracts. Two strategic archetypes dominate: full-service exhibition management firms spanning creative, build, and digital analytics; and specialized booth fabricators focused on modular aluminum framing with LED-integrated surfaces. Competitive moves concentrate on strategic partnerships with certified systems integrators and portfolio diversification into hybrid event infrastructure.
Among North America-based integrated service providers, Freeman occupies a position exemplifying full-service exhibition management, while IMEX Group represents international buyer-seller matching specialization. PRO EXPO sits within the rapid-turnaround fabrication tier, anchoring mid-market exhibitor contracts through accelerated booth build timelines. These three company names from the raw data illustrate how competitive positioning fragments across service intensity and geographic coverage vectors.
| Leading Market Players |
|---|
| Expo Exhibition Stands |
| Ingenia Stand |
| Freeman |
| CrewExpo |
| Foster Display Group |
| Adam Expo Stand Solutions |
| PRO EXPO |
| IMEX Group |
| Expostandbuild |
| Others |
Supply & Pricing Matrix
Convention center capacity utilization above 75% in Las Vegas, Orlando, and Chicago generates scale economies that compress per-square-meter logistics costs while simultaneously elevating price floors for premium hall placement. This concentration dynamic forces mid-market exhibitors toward secondary venue circuits or bundled service packages that subsidize booth fabrication through multi-year sponsorship commitments.
Pricing Analysis
OSHA electrical certification requirements dictate the pricing tier structure across booth fabrication and venue rental segments. Three-tier pricing structure across premium, standard, and economy levels separates hybrid-certified intelligent frameworks with embedded IoT sensors from conventional aluminum framing and basic shell schemes. Price differentiation hinges on ISO 20121 sustainability accreditation and real-time CRM integration capabilities. Cost compression in economy-tier fabrication is intensifying because aluminum alloy price volatility squeezes fixed-contract margins. Corporate procurement departments operating under ESG mandates exhibit the lowest price sensitivity, while independent exhibitors and association-managed pavilions face acute budget constraints.
Supply Chain Analysis
Strait of Hormuz transit underwrites a substantial share of aluminum alloy and LED module shipments into Dubai and Abu Dhabi venue construction projects. Geographic supply concentration centers on China for modular display system manufacturing, Germany for precision engineering components, and the United Arab Emirates for regional logistics hub consolidation. Raw material dependencies draw from bauxite refining for booth framing, rare earth elements for LED phosphors, and copper for redundant connectivity infrastructure. Single-source vulnerability in hybrid-certified technical director talent pools creates chokepoint risk. Distribution runs through certified systems integrators who bundle venue certification, fabrication, and on-site technical direction under unified contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment in venue certification standards creates substantial switching costs for anchor tenants and service providers alike.
For Market Incumbents: Secure multi-year technology partnerships with Frankfurt and Munich venue operators to lock in KBA-aligned fire-safety system deployment before inspection protocol backlogs clear. Deepen upstream control over aluminum framing fabrication capacity in Germany and the United States to offset alloy price volatility exposure. Virtual event platform substitution represents the primary substitution threat requiring counter-investment in hybrid-ready infrastructure bundles. For New Entrants and Emerging Players: Hybrid technical director scarcity opens service-layer gaps where incumbents under-serve mid-market pharmaceutical exhibitors seeking outcome-based vendor agreements. Target Saudi Arabia's NEOM and Red Sea giga-project circuits where specialized capital equipment exhibition demand outpaces incumbent systems integrator presence. Lead with ISO 20121 certification pathway offerings to capture ESG-mandated corporate accounts before established players re-certify. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated service providers with captive booth design and event management capabilities over pure-play fabricators. Long-term viability rests on consolidation of fragmented mid-market fabrication capacity under platforms with hybrid infrastructure investment capacity. Acquisition target archetype: regional booth fabricators with established pharmaceutical vertical relationships and underutilized LED-integrated surface production lines. Signal to watch: German venue certification backlog resolution timing as indicator of infrastructure replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Infrastructure Certification | KBA-aligned inspection protocols in Germany mandate redundant fire-suppression systems that accelerate venue replacement cycles. |
| ISO 20121 Accreditation Pathway | Event sustainability management certification opens preferred-supplier status with ESG-mandated Fortune 500 technology accounts. |
| Outcome-Based Vendor Consolidation | Corporate procurement departments tie contractor payments to qualified lead generation metrics across Las Vegas and Chicago circuits. |
| Intelligent Framework Specification | Embedded IoT sensors in modular aluminum systems displace manual lead-capture processes with automated CRM integration. |
| Saudi Giga-Project Circuit Entry | NEOM and Red Sea development announcements generate specialized infrastructure exhibition demand with limited incumbent competition. |
Research Methodology
Cross-validation between primary interviews with exhibition venue operators, booth fabrication executives, and corporate procurement directors anchors the qualitative findings against secondary validation from SEC filings of publicly traded service providers, OSHA regulatory guidance documents, and German KBA technical bulletins. Bottom-up triangulation incorporates contractor bid data and anchor-tenant contract structures, while top-down verification draws from national convention bureau statistics and pharmaceutical industry association expenditure surveys.
Sensitivity analysis across the projection horizon tests volume and value outputs against aluminum alloy price volatility scenarios and hybrid event platform substitution rates. Segmentation dimensions modeled include event type, service tier, industry vertical, and customer category, with geographic regulatory cluster as an additional industry-specific dimension. CAGRs were derived from trend extrapolation of square-meter bookings and sponsorship revenue trajectories, incorporating LED-integrated surface adoption curves and HVAC-AV convergence penetration assumptions.
Forecasts assume regulatory continuity in OSHA load-bearing standards, KBA-aligned venue inspection protocols, and UAE MOHAP event licensing frameworks; material policy shifts would require re-modeling of contractor market access assumptions and certification timeline projections. Practitioners should keep alternative scenarios live as sustainability disclosure mandates under EU CSRD and emerging ISO 20121 alignment pressures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
K-Pop Events Market
Events and Festivals
Asia-Pacific K-Pop Events Market
Events and Festivals
Events Market
Events and Festivals
Portable Photo Booth Market
Events and Festivals
Global Family Entertainment Center Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
Drone Art Performance Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
Professional Speaker Market
Events and Festivals
North America K-Pop Events Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
Corporate Luxury Events Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Event Photography Service Market