
 US Amusement and Theme Park Market | 2026-2036
US Amusement and Theme Park Market Size, Share, and Industry Trends Forecast 2026-2036
US Amusement and Theme Park Market Insights
Capital-intensity divergence between players is bifurcating the competitive landscape. Disney Parks, Experiences and Products leverages its integrated resort model to sustain pricing power across admissions and merchandising. Cedar Fair anchors regional dominance through concentrated park networks in the Midwest and Northeast. Six Flags Entertainment Corporation competes on season-pass penetration and regional accessibility.
US amusement and theme parks comprise gated entertainment destinations featuring mechanical rides, live entertainment venues, and themed environments built on plots typically exceeding 100 acres, with major installations employing steel-track roller coasters capable of exceeding 70 mph and immersive dark-ride systems using trackless vehicle navigation. These facilities generate revenue through per-capita spending across admissions, food and beverage, and licensed merchandise. The park type dimension shows theme parks commanding the deepest guest dwell times and highest ancillary spend rates, while water parks capture concentrated seasonal demand in Sun Belt states. Revenue source analysis reveals that food and beverage and merchandising together exceed admissions yield at mature gated properties.
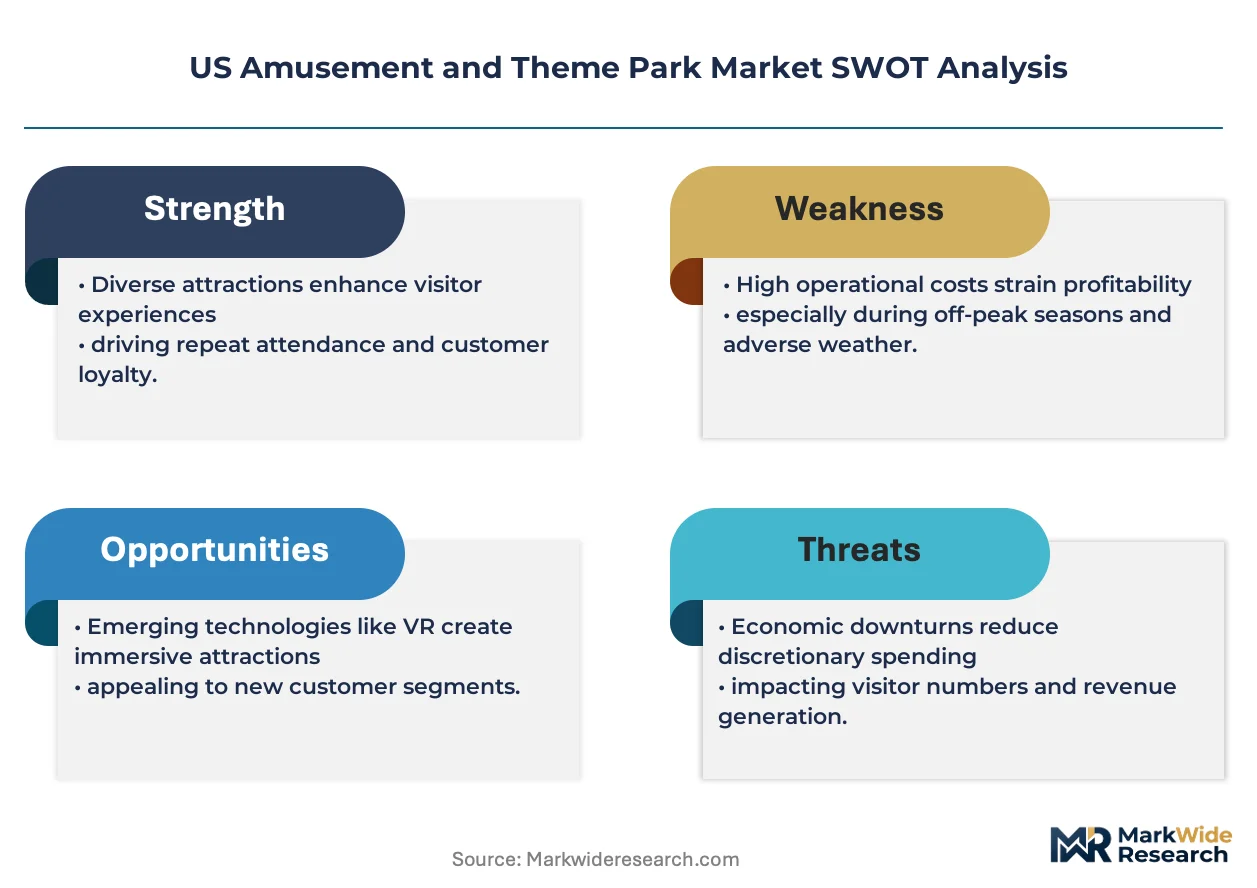
The Consumer Product Safety Commission coordinates with state inspectors on ride incident reporting, while OSHA governs worker safety protocols during attraction construction and maintenance cycles. Florida's Department of Agriculture and Consumer Services and California's Division of Occupational Safety and Health enforce distinct inspection calendars that shape seasonal opening schedules. Stakeholders must monitor evolving state-level liability frameworks and immersive technology refresh cycles to time capital redeployment.
Market Dynamics
Immersive technology refresh cycles are compressing capital deployment timelines across the US amusement and theme park sector, forcing operators to synchronize attraction investments with seasonal demand windows and inspection calendars.
Growth Catalysts
- OSHA Construction Standards:Federal workplace safety protocols during attraction builds have standardized project timelines, reducing variance in ride commissioning schedules and enabling more predictable revenue recognition.
- Family Visitor Segment Deepening:Multi-generational households are extending dwell times through experiential dining and character interactions, lifting per-capita food and beverage yields above admissions revenue at mature gated properties.
- Orlando Corridor Concentration:Florida's destination park cluster generates network effects that reduce customer acquisition costs for adjacent resort developments and support specialized supplier ecosystems.
Market Restraints
- Steel and Aluminum Input Volatility:Roller coaster track fabrication depends on specialty alloy supply chains concentrated in domestic foundries with limited spot market liquidity.
- Seasonal Labor Pool Constraints:Water park operations in Sun Belt states face recurring shortages of certified ride operators during peak summer demand windows.
- State Inspection Calendar Fragmentation:Florida's Department of Agriculture and California's Division of Occupational Safety and Health enforce non-synchronized inspection cycles that complicate national rollout schedules for new attractions.
Strategic Opportunities
- Texas and Arizona Water Park Expansion:Underpenetrated metro markets in desert Southwest states offer year-round operating potential through climate-controlled indoor-outdoor hybrid designs.
- Trackless Dark Ride Convergence:Integration of autonomous vehicle navigation with projection mapping systems enables retrofitting of legacy show buildings without structural track installation.
- Infrastructure Investment and Jobs Act:Federal transportation funding improves interstate access corridors to secondary regional park destinations in the Midwest and Mountain West.
Industry Challenges
- Certified Maintenance Technician Scarcity:Hydraulic and pneumatic systems specialists with amusement ride-specific credentials command premium wages that elevate fixed cost structures.
- Intellectual Property Licensing Complexity:Character and franchise agreements require renegotiation mid-cycle, creating uncertainty in merchandise planning and themed environment refresh budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Amusement and Theme Park Market |
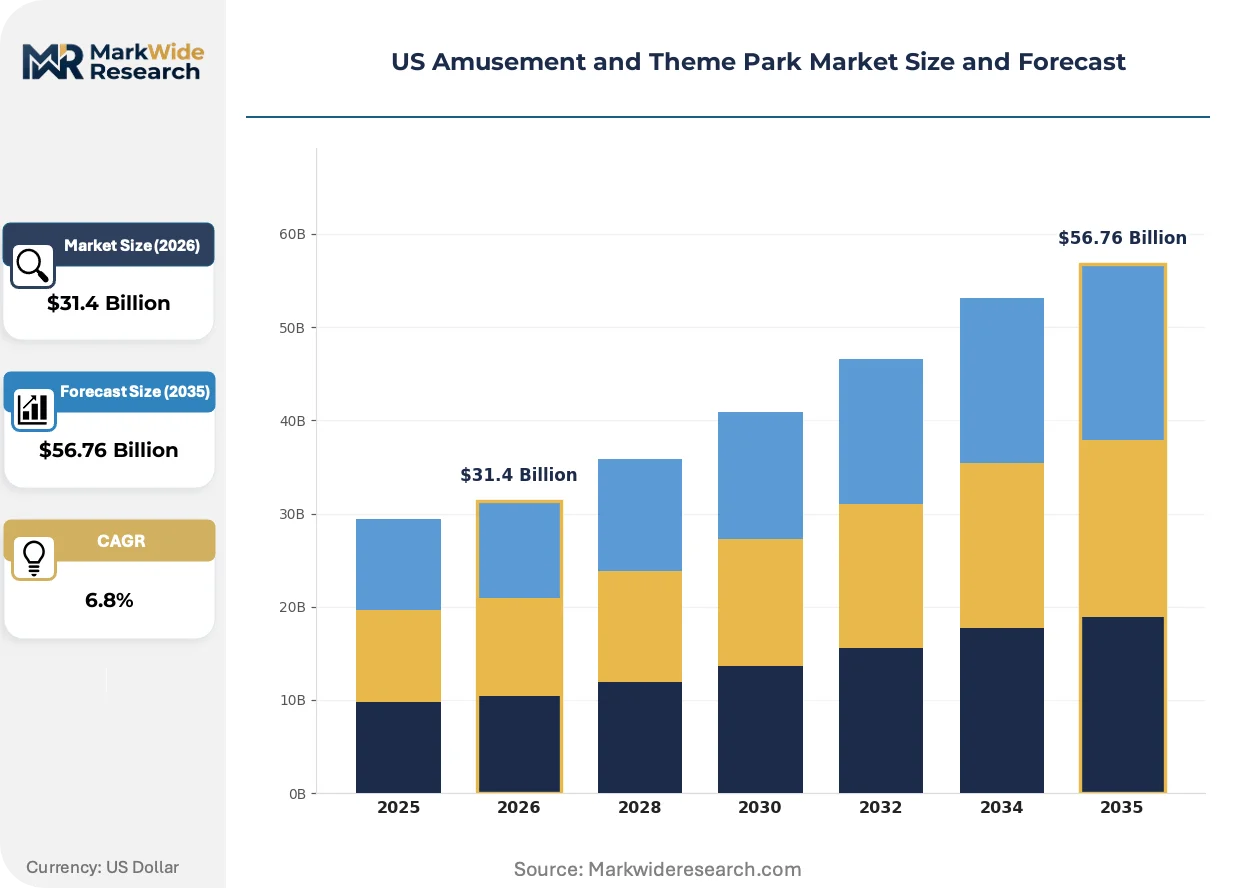
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $56.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Park Type: Amusement Park, Water Park, Theme Park, Adventure Park Visitor Type: Families, Couples, Solo Travelers, Groups Attraction Type: Roller Coasters, Live Shows, Themed Rides, Arcade Games Revenue Source: Admissions, Merchandising, Food & Beverage, Sponsorship |
| Companies Covered | Cedar Fair, Merlin Entertainments, Disney Parks, Experiences and Products, SeaWorld Parks & Entertainment, Palace Entertainment, Universal Destinations & Experiences, United Parks & Resorts, Dollywood, Six Flags Entertainment Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Amusement and Theme Park Market Trends and Innovations
Guest expectation thresholds are rising faster than ticket pricing power, compelling operators to embed narrative depth and personalization into mechanical attractions rather than relying on raw thrill metrics alone.
Projection mapping and real-time rendering engines are decomposing the traditional distinction between physical set pieces and digital environments. Major destination parks in Florida and California are retrofitting legacy dark rides with spatial computing overlays that respond to individual guest biometrics. This convergence is compressing the refresh cycle for themed attractions from decade-long horizons to three-to-five-year technology windows.
OSHA's updated Powered Industrial Trucks standard is extending compliance requirements to specialized maintenance vehicles used in attraction construction and seasonal setup. The rule is forcing operators to retrain existing workforces and procure certified equipment, with California's Division of Occupational Safety and Health already aligning state enforcement calendars to the federal timeline. Regional park networks in the Northeast and Midwest are consolidating vendor relationships to manage certification documentation across multi-state footprints.
Season-pass purchasing patterns are shifting from transaction-based renewal to subscription-model engagement, with members expecting continuous content drops and exclusive access windows. Regional operators are responding with tiered membership structures that bundle parking, dining credits, and merchandise discounts. This behavioral pivot is most pronounced in the Midwest, where Cedar Fair's concentrated park network enables cross-property redemption that deepens household lock-in.
US Amusement and Theme Park Market Segmentation
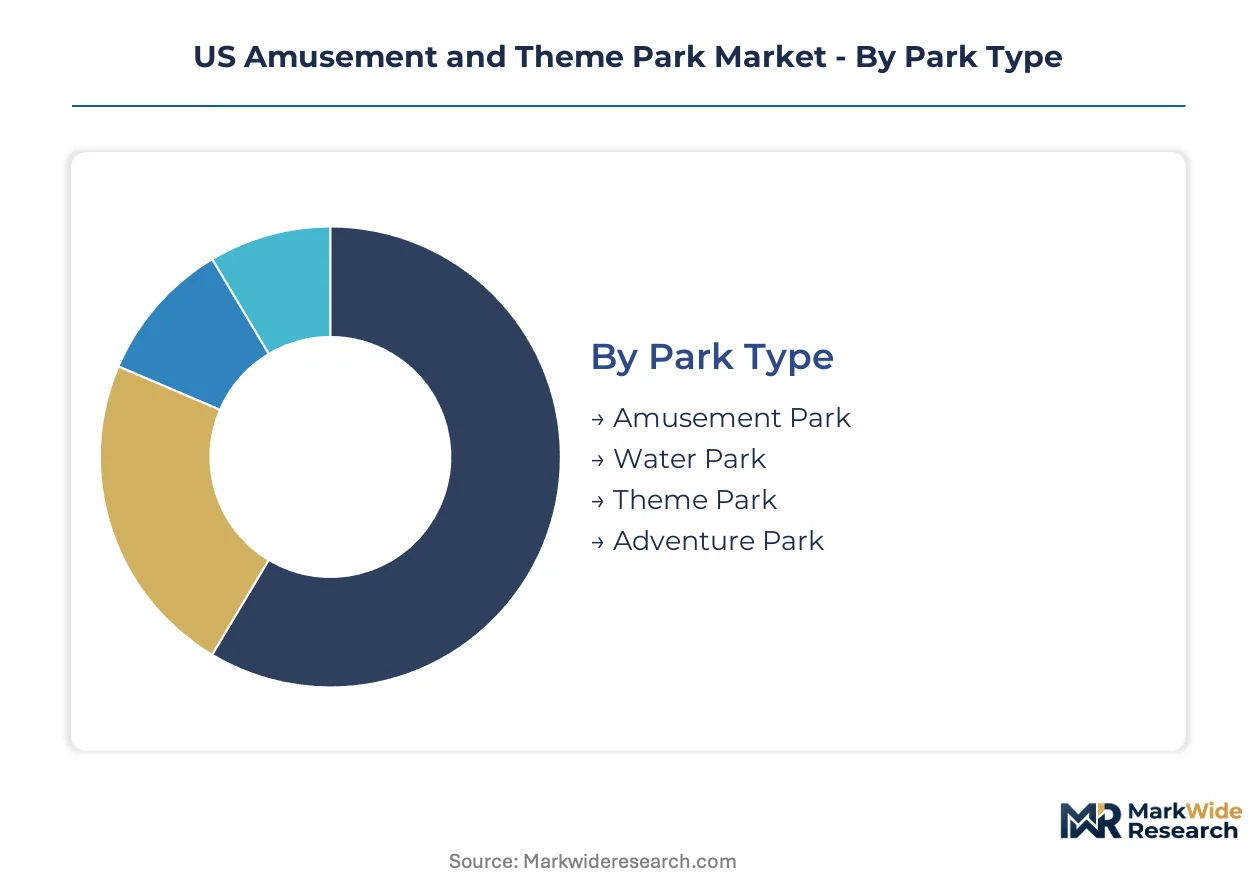
Segmentation in the US amusement and theme park market reveals divergent margin architectures across property types and spending categories. Operators calibrate capital deployment and pricing power differently depending on which visitor segments and revenue streams dominate their mix.
Park Type:
Highest ancillary spend per capita concentrates at immersive destination properties where dwell times extend across multiple days.
- Theme Park:Character-branded environments with narrative-driven attractions command premium admission pricing and merchandise attachment rates. Florida's Orlando corridor concentrates the deepest destination demand, where integrated resort models sustain per-capita spending above standalone properties.
- Amusement Park:Mechanical ride collections with limited theming operate on high-throughput, low-dwell models. Regional networks in the Midwest and Northeast capture repeat visitation through season-pass penetration rather than vacation-length stays.
- Water Park:Seasonal operations in Sun Belt states face compressed operating calendars and weather dependency. Indoor-outdoor hybrid designs in Texas and Arizona are extending viable seasons through climate-controlled infrastructure.
- Adventure Park:Zipline courses and climbing installations target group bookings and corporate events with lower capital intensity than steel-track attractions.
The dominant share belongs to Theme Park, while Water Park is closing the gap fastest through hybrid format expansion.
Visitor Type:
Multi-generational travel parties generate the highest food and beverage yields per visit through extended meal occasions.
- Families:Households with children drive character interaction demand and experiential dining attachment. Orlando's destination clusters concentrate this segment through multi-day vacation packaging.
- Groups:Corporate outings and school field trips provide off-peak revenue stabilization with contracted catering minimums. Midwest regional operators rely on this segment for shoulder-season occupancy.
- Couples:Adult pairs without children concentrate at evening events and premium dining experiences with higher per-capita spend but lower total party size.
- Solo Travelers:Individual visitors optimize for single-rider lines and flexible scheduling, representing a smaller but growing segment at destination properties with annual pass programs.
Families retain the largest visitor share, though Groups are expanding most quickly as corporate event programming deepens.
Attraction Type:
Capital allocation tilts toward immersive systems that differentiate properties within competitive drive-time radii.
- Themed Rides:Dark-ride vehicles with projection mapping and trackless navigation enable narrative depth without raw speed metrics. Florida and California parks are retrofitting legacy show buildings with spatial computing overlays.
- Roller Coasters:Steel-track installations exceeding 70 mph remain signature draws requiring specialty alloy supply chains and extended commissioning timelines. OSHA construction standards govern worker safety during assembly cycles.
- Live Shows:Theatrical productions with performer labor costs offer capacity flexibility but limited differentiation across properties.
- Arcade Games:Redemption and video game installations provide weather-resistant capacity with lower per-guest capital requirements.
Roller Coasters hold the installed base advantage, yet Themed Rides are climbing the fastest as refresh cycles compress.
Revenue Source:
Admissions pricing power varies inversely with the maturity of ancillary revenue development at individual properties.
- Food & Beverage:Experiential dining with character interactions and themed environments now exceeds admissions yield at mature gated properties. Florida destination parks lead in per-capita culinary spending.
- Merchandising:Licensed product sales depend on intellectual property renewal cycles and exclusive retail environments. Character agreements require mid-cycle renegotiation that creates planning uncertainty.
- Admissions:Gate revenue faces pricing resistance as guest expectation thresholds rise faster than ticket increases. Dynamic pricing algorithms are replacing static rate cards.
- Sponsorship:Corporate partnerships for attraction naming rights and event programming provide non-weather-dependent revenue streams with multi-year commitments.
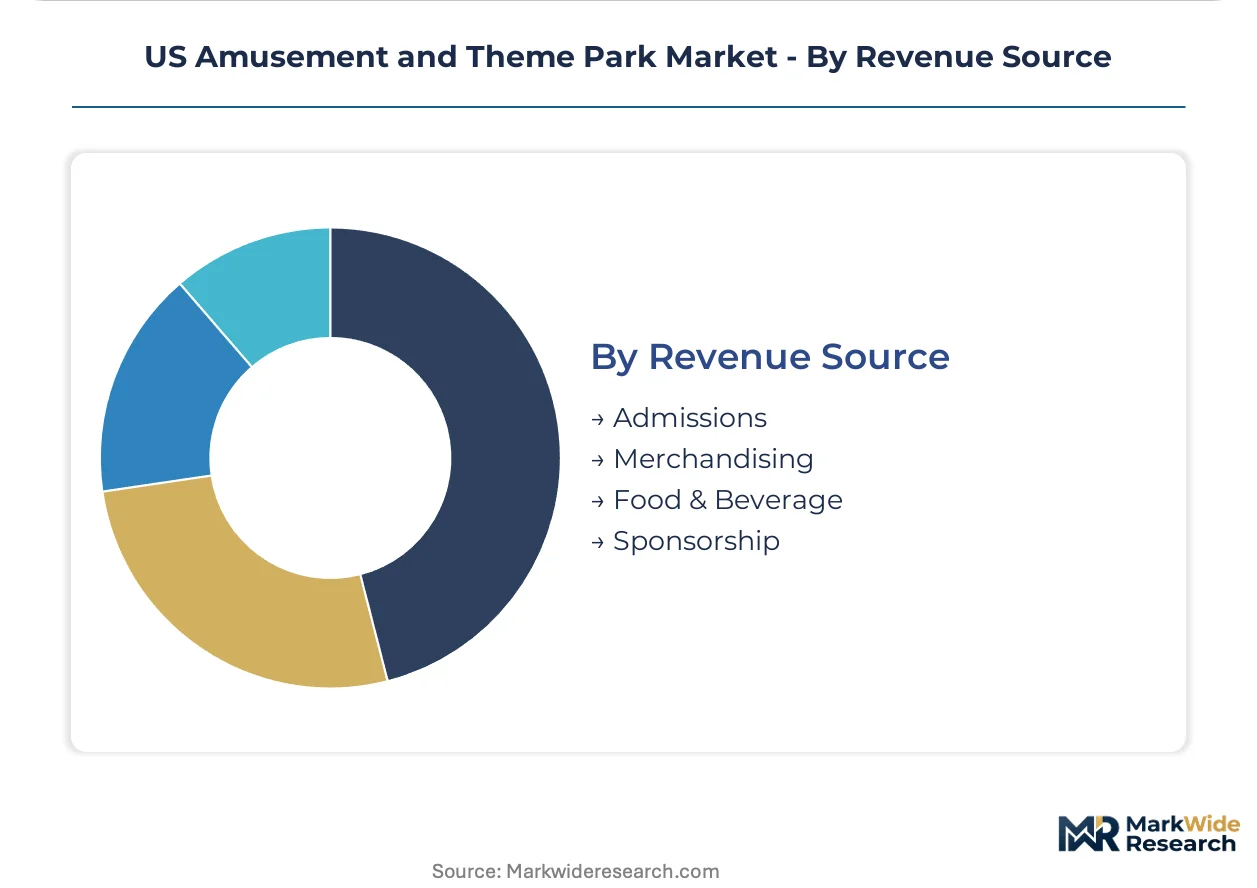
Food & Beverage captures the dominant revenue position, while Sponsorship is gaining share fastest as operators seek contracted income stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US sub-regions, with Florida destination visitors accepting premium admission tiers while Midwest regional park-goers prioritize season-pass value and repeat accessibility.
Florida
Orlando's destination corridor commands the highest per-capita spending through integrated resort models that extend dwell times across multiple days. Florida's Department of Agriculture and Consumer Services enforces ride inspection calendars that synchronize with seasonal demand peaks. The Orlando-Kissimmee cluster anchors supplier ecosystems for immersive dark-ride fabrication and character dining infrastructure.
California
Southern California's entertainment economy supports year-round operations with less weather dependency than eastern competitors. California's Division of Occupational Safety and Health aligns state enforcement with federal OSHA timelines for attraction construction. The Anaheim-Santa Ana corridor concentrates projection mapping vendors and spatial computing talent pools for ride system upgrades.
Texas
Metro Dallas-Fort Worth and Houston markets show underpenetrated demand for climate-controlled water park hybrids that extend operating seasons. Texas state regulators coordinate with county health departments on aquatic attraction safety protocols. The Texas Triangle is attracting indoor-outdoor park developments that blend regional accessibility with destination-grade theming.
Ohio-Pennsylvania Corridor
Cedar Fair's concentrated park network in this region captures repeat visitation through cross-property season-pass redemption. Ohio's Department of Agriculture and Pennsylvania's Department of Agriculture enforce distinct but overlapping inspection windows for multi-state operators. Sandusky and Allentown serve as regional maintenance hubs for steel-track coaster refurbishment cycles.
Southwest Desert States
Arizona and Nevada markets present expansion opportunities for water parks with climate-controlled infrastructure that defies traditional seasonal constraints. State environmental agencies in both jurisdictions regulate water usage and recirculation systems for aquatic attractions. Phoenix and Las Vegas are testing hybrid formats that combine water park elements with adjacent entertainment retail.
US Amusement and Theme Park Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where scale-driven destination operators command pricing power while regional networks compete on accessibility and membership penetration. The competitive landscape separates into three archetypes: integrated resort operators with intellectual property depth, regional park networks with season-pass density, and specialty destination properties with limited geographic footprints. Consolidation pressure favors operators with multi-property networks that spread fixed costs across inspection calendars and seasonal labor pools.
Within the integrated resort tier, Disney Parks, Experiences and Products and Universal Destinations & Experiences exemplify the destination archetype through Orlando and Southern California concentrations. Cedar Fair and Six Flags Entertainment Corporation occupy positions in the regional network segment, with Cedar Fair's Midwest-Northeast density and Six Flags' broader geographic scatter representing alternative scale strategies. SeaWorld Parks & Entertainment anchors the specialty destination category with marine-life differentiation that commands distinct visitor segments.
| Leading Market Players |
|---|
| Cedar Fair |
| Merlin Entertainments |
| Disney Parks, Experiences and Products |
| SeaWorld Parks & Entertainment |
| Palace Entertainment |
| Universal Destinations & Experiences |
| United Parks & Resorts |
| Dollywood |
| Six Flags Entertainment Corporation |
| Others |
Pricing and Supply Chain Analysis
Projection mapping hardware replacing traditional animatronic fabrication is redrawing supplier geography from domestic machine shops to Asian electronics clusters while compressing per-attraction refresh economics.
Pricing Analysis
Season-pass subscription tiers now drive lifetime value capture above single-admission transactions. Three-tier pricing structure across premium, standard, and economy levels segments visitors by visit frequency and ancillary bundle attachment. Price differentiation hinges on intellectual property exclusivity and experiential dining integration. Pricing pressure stems from guest expectation thresholds rising faster than ticket elasticity permits, with regional park-goers in the Midwest exhibiting highest sensitivity compared to Orlando destination visitors.
Supply Chain Analysis
China and South Korea anchor specialty steel track fabrication and projection mapping component manufacturing respectively. Domestic foundries in Ohio and Pennsylvania retain coaster structural steel capacity, though ride control systems draw from Taiwanese semiconductor supply chains. Single-source vulnerability concentrates in trackless vehicle navigation modules from European suppliers. Distribution runs through specialized ride system integrators who coordinate multi-country component consolidation for final site assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immersive technology refresh cycles are compressing from decade-long horizons to three-to-five-year windows, creating a high-growth disruption as OSHA construction standards simultaneously standardize project timelines.
For Market Incumbents: Secure multi-year intellectual property licensing extensions before mid-cycle renegotiation windows to eliminate merchandise planning uncertainty. Consolidate vendor relationships across multi-state footprints to manage OSHA certification documentation and reduce compliance cost duplication. Backward integration into projection mapping content production insulates against supplier pricing power in spatial computing overlays. For New Entrants and Emerging Players: Lead with climate-controlled indoor-outdoor hybrid water park formats in Texas and Arizona metro markets where year-round operating potential remains underpenetrated. Target corporate event programming for shoulder-season revenue stabilization through contracted catering minimums. Differentiate through autonomous vehicle navigation integration rather than raw thrill metrics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional park networks concentrated in the Midwest and Northeast. Five-to-ten year viability hinges on cross-property season-pass redemption density and maintenance technician workforce stability. Watch for inflection in state inspection calendar synchronization as signal of regulatory burden easing.| Strategic Initiative | Industry Significance |
|---|---|
| Intellectual Property Licensing Extension | Multi-year franchise agreements eliminate mid-cycle renegotiation uncertainty for themed environment budgets. |
| Climate-Controlled Hybrid Format Expansion | Indoor-outdoor water park designs in Texas and Arizona defy traditional seasonal operating constraints. |
| Trackless Dark Ride Retrofit | Autonomous vehicle navigation enables legacy show building upgrades without structural track installation. |
| Cross-Property Season-Pass Consolidation | Regional network density deepens household lock-in through multi-park redemption and tiered membership structures. |
| OSHA Compliance Vendor Consolidation | Unified certification documentation across multi-state footprints reduces administrative overhead and inspection friction. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with park operations executives, attraction design engineers, state inspection officials, season-pass program managers, and food and beverage directors. Secondary validation drew from OSHA enforcement calendars, Florida Department of Agriculture inspection records, California Division of Occupational Safety and Health filings, and Cedar Fair SEC disclosures. Bottom-up property-level revenue modeling triangulated against top-down sector expenditure analysis.
Across the analysis window, projections integrate park type segmentation by immersive depth, visitor type by household composition, attraction type by capital intensity tier, and revenue source by ancillary maturity. CAGRs derive from per-capita spending trajectory modeling and seasonal labor pool elasticity assumptions. Industry-specific inputs include steel alloy price indices, certified technician wage trends, and intellectual property renewal cycle frequencies.
The analysis sits within stated boundaries; outcomes outside sustained family visitor segment deepening or OSHA regulatory stability would require recalibration. Forecasts assume continued Orlando corridor demand concentration and projection mapping technology cost curves. Recalibration cycles align with material shifts in state inspection calendar harmonization or immersive refresh cycle compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Portable Photo Booth Market
Events and Festivals
K-Pop Events Market
Events and Festivals
Event Photography Service Market
Events and Festivals
India Event Services Market
Events and Festivals
Indoor Entertainment Center Market
Events and Festivals
Virtual Events Market
Events and Festivals
Drone Art Performance Market
Events and Festivals
Europe K-Pop Events Market
Events and Festivals
Global Escape Room Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
Global Live Event Ticketing Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Events Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
Global Family Entertainment Center Market