
 Indoor Entertainment Center Market | 2026-2036
Indoor Entertainment Center Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Entertainment Center Market Analysis
The indoor entertainment center sector is rebalancing between premium experience-driven venues and commodity amusement offerings as capital allocation diverges sharply. Dave & Buster's anchors its position through large-format sports-bar-arcade hybrids in metropolitan trade areas. Main Event Entertainment differentiates via full-service dining bundled with bowling and laser tag under one roof. Urban Air Adventure Park specializes in active recreation formats including climbing walls and ropes courses that command higher per-visit spend.
An indoor entertainment center constitutes a climate-controlled commercial facility housing multiple amusement attractions, typically spanning 15,000 to 60,000 square feet with engineered flooring systems, specialized lighting rigs, and automated scoring or tracking infrastructure designed to host recreational activities regardless of external weather conditions. Facility type segmentation shows trampoline parks and laser tag arenas capturing disproportionate expansion capital as these formats require less square footage per revenue dollar than traditional bowling alleys. Service offering segmentation reveals food and beverage operations generating the highest margin pools, with kitchen and bar infrastructure transforming visit economics from single-attraction transactions into extended-duration social occasions.
ASTM International standards govern trampoline park equipment and operational safety, while the Consumer Product Safety Commission monitors injury reporting and facility compliance across the United States. State-level amusement ride inspection programs in Texas, Florida, and California add layered compliance obligations that shape insurance costs and capital deployment timelines. Stakeholders must monitor evolving municipal zoning for large-format entertainment retail as cities reconsider parking minimums and traffic impact requirements for destination venues.
Market Dynamics
ASTM International safety certification tightening is compressing capital deployment timelines for trampoline parks and active recreation formats, forcing operators to front-load compliance costs before revenue generation begins.
Growth Catalysts
- Sun Belt Metro Expansion:Year-round indoor recreation demand concentrates in Houston, Phoenix, and Las Vegas where extreme summer heat eliminates outdoor alternatives for extended periods.
- F&B Integration Mandate:Kitchen and bar infrastructure transforms single-attraction transactions into extended-duration social occasions, lifting per-visit economics across suburban family entertainment complexes.
- Active Recreation Formats:Climbing walls and ropes courses command higher per-visit spend than traditional arcade gaming, redirecting capital toward physically engaging attractions.
Market Restraints
- Insurance Cost Escalation:State-level amusement ride inspection programs in Texas, Florida, and California layer compliance obligations that inflate liability premiums for trampoline park operators.
- Real Estate Concentration:Large-format venues require 15,000 to 60,000 square feet in metropolitan trade areas where commercial rents absorb disproportionate revenue share.
- Seasonal Staffing Volatility:Peak demand periods around school holidays create workforce management friction that compresses margin stability.
Strategic Opportunities
- Suburban Corridor Infill:Family entertainment complexes in secondary metropolitan rings face reduced competition from established urban anchors while capturing household formation growth.
- Technology Convergence:Automated scoring infrastructure and RFID tracking systems merge with mobile payment platforms to reduce labor dependency at entry and concession points.
- Municipal Zoning Liberalization:Cities reconsidering parking minimums and traffic impact requirements for destination venues unlock previously restricted development sites.
Industry Challenges
- Certification Timeline Compression:ASTM International equipment approval processes for trampoline parks and adventure attractions extend pre-opening periods, delaying cash flow generation.
- Attrition-Resistant Talent Scarcity:Specialized maintenance technicians for engineered flooring systems and automated scoring infrastructure command premium wages in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Entertainment Center Market |
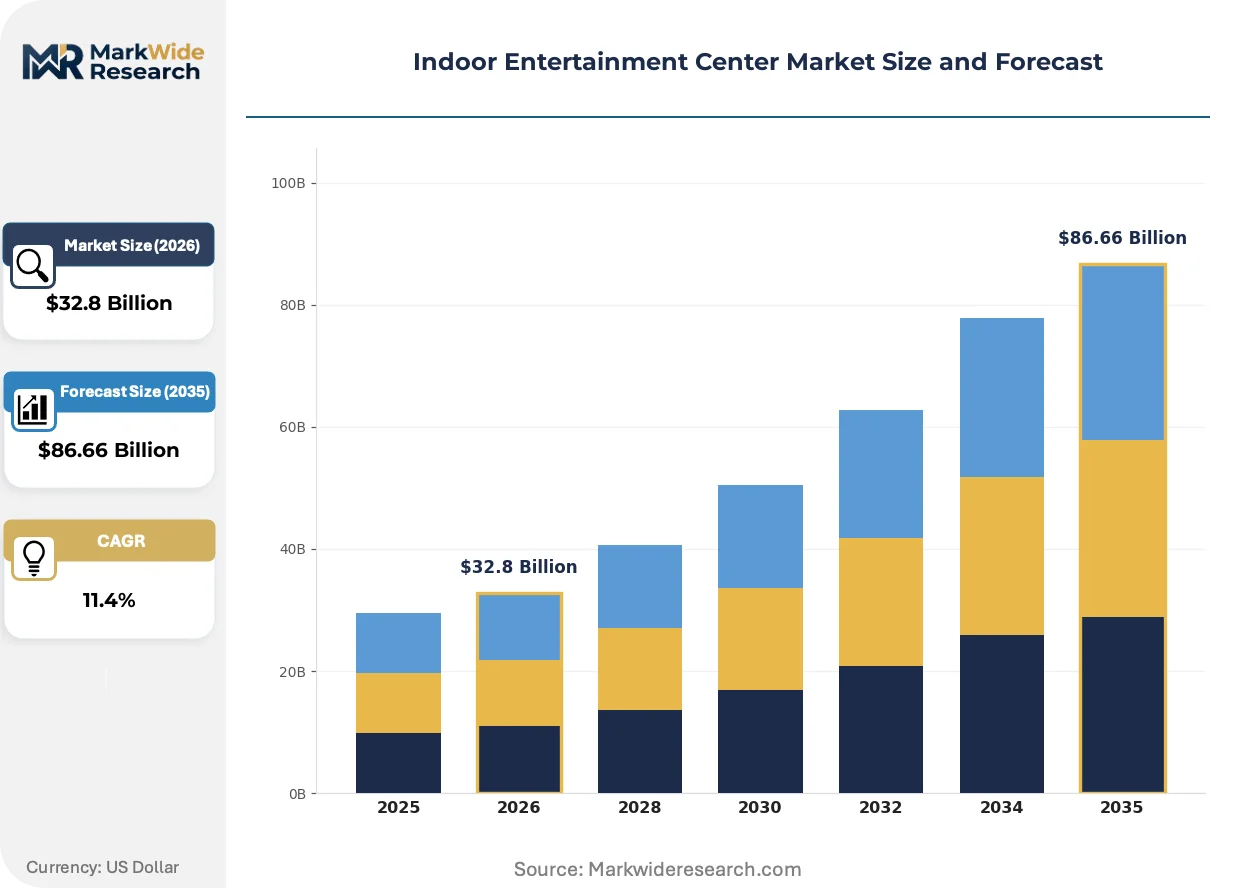
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $86.66 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Bowling Alleys, Arcade Centers, Trampoline Parks, Laser Tag Arenas Service Offering: Food & Beverage, Amusement Rides, Event Hosting, Retail Outlets Target Demographic: Families, Teens, Young Adults, Corporate Groups Engagement Model: Membership Plans, Pay-Per-Play, All-Access Passes, Group Packages |
| Companies Covered | CEC Entertainment, Dave & Buster's, Main Event Entertainment, Scene75 Entertainment Centers, Urban Air Adventure Park, Cinergy Entertainment Group, Chuck E. Cheese, KidZania, Bowlero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Entertainment Center Market Emerging Trajectories
Digital infrastructure integration is redefining visitor flow management and revenue capture across indoor entertainment formats. Physical attractions now compete on data-enabled personalization and frictionless transaction architecture.
RFID wristband systems are converging with cloud-based visitor analytics platforms to eliminate token-based currency and queue-based bottlenecks. Family entertainment centers in Dallas and Atlanta deploy these systems to track individual attraction usage and trigger dynamic pricing for peak-demand periods. The technology is converging with mobile app ecosystems that extend engagement beyond physical visits through achievement tracking and reservation management.
ASTM International standards for trampoline park equipment and operational safety are tightening inspection protocols and documentation requirements. The Consumer Product Safety Commission monitors injury reporting with escalating penalty structures for non-compliance. Texas, Florida, and California operators face the steepest compliance cost inflation as state amusement ride inspection programs add layered obligations beyond federal baseline.
Subscription membership models are displacing single-visit ticketing as the dominant revenue architecture. Urban parents in Sun Belt metropolitan areas purchase monthly passes for unlimited access, shifting operator economics toward predictable recurring revenue. Arizona and Nevada venues report the fastest adoption curves as extreme summer heat eliminates outdoor alternatives for three to four months annually.
Indoor Entertainment Center Market Segmentation
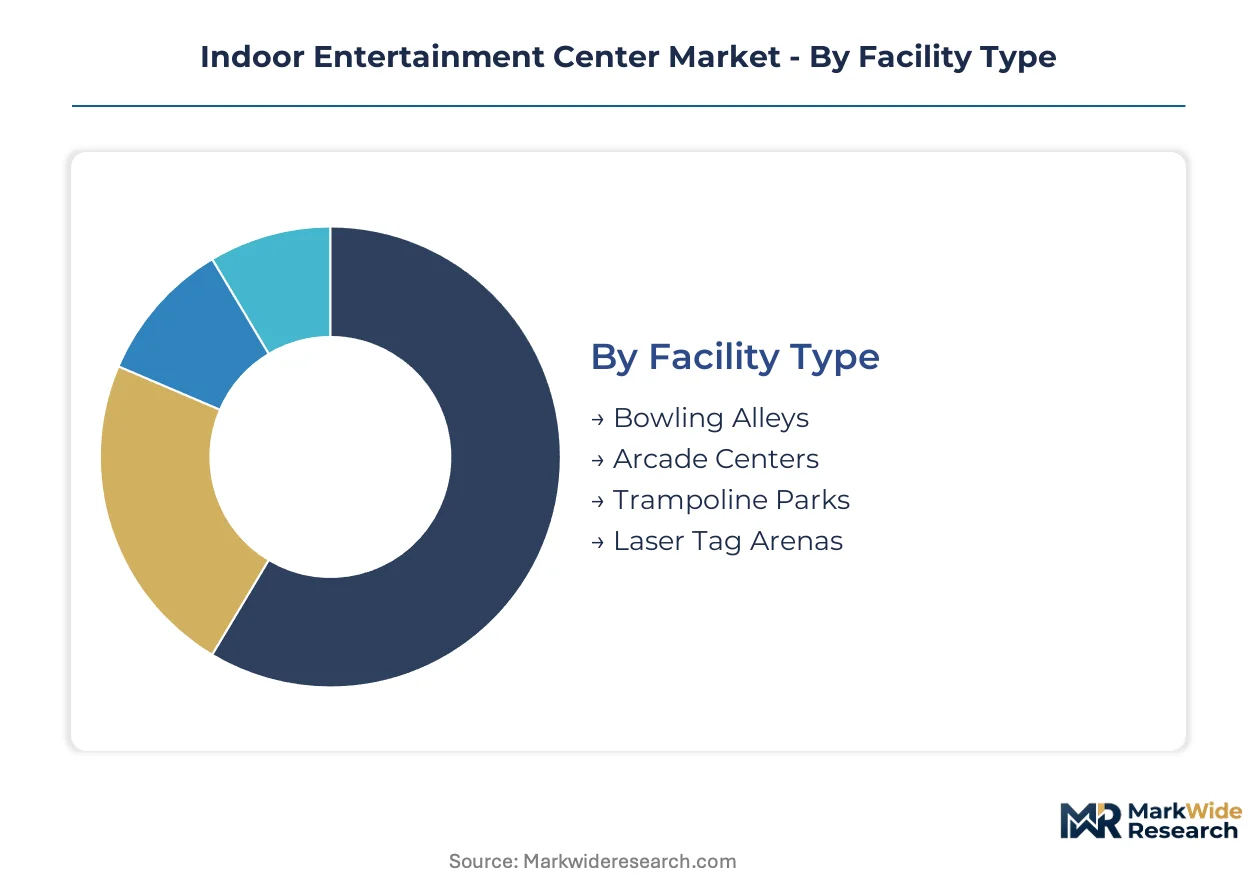
Segmentation in the indoor entertainment center market reveals how capital allocation and site selection criteria diverge across format types and revenue architectures. Operators configure facility specifications, service bundles, and access pricing to match distinct household spending patterns and occasion-based demand.
Facility Type:
Engineered flooring systems and specialized infrastructure requirements differentiate capital intensity and revenue velocity across venue formats.
- Trampoline Parks:Engineered spring-floor systems with perimeter padding and wall-mounted features occupy 20,000 to 35,000 square feet. Demand concentrates in suburban Sun Belt corridors where extreme summer heat sustains year-round visitation, though ASTM International certification timelines compress pre-opening cash flow generation.
- Laser Tag Arenas:Modular arena construction with programmable LED environments and RFID scoring infrastructure requires 8,000 to 15,000 square feet. Operators in Texas and Florida prioritize this format for lower per-revenue-dollar real estate requirements amid elevated commercial rents.
- Bowling Alleys:Traditional lane-based entertainment with automated pinsetters and synthetic lane surfaces demands 30,000 to 60,000 square feet with substantial HVAC loads.
- Arcade Centers:Token or card-based gaming floors with redemption prize infrastructure and high-turnover concession integration.
Mature deployment sits with bowling alleys. Newer deployment is concentrated in trampoline parks.
Service Offering:
Margin architecture varies sharply between experiential attractions and ancillary revenue streams that extend visit duration.
- Food & Beverage:Full-service kitchens and bar infrastructure transform single-attraction transactions into extended social occasions. Venues in Houston and Phoenix report the highest attach rates as extreme heat eliminates outdoor dining alternatives for extended periods annually.
- Amusement Rides:Mechanical attractions including climbing walls, ropes courses, and adventure elements command premium per-visit spend through physical engagement requirements.
- Event Hosting:Dedicated party rooms and corporate event programming with catering integration and dedicated staffing.
- Retail Outlets:Branded merchandise and redemption prize counters capturing impulse purchase behavior at exit points.
Margin concentration sits with food and beverage operations. Revenue expansion is climbing the fastest in amusement ride integration.
Target Demographic:
Household formation patterns and discretionary spending elasticity shape programming mix and pricing architecture.
- Families:Multi-generational visit patterns with children's activity zones and parent observation areas. Suburban corridors around Dallas and Atlanta anchor the highest concentration of dedicated family entertainment complexes.
- Teens:Social occasion-driven demand with peer-group dynamics and competitive gaming preferences.
- Young Adults:Evening and weekend social visitation with bar-integrated formats and tournament-style competition.
- Corporate Groups:Team-building programming and private event bookings with catering and facilitated activity packages.
Volume concentration sits with families. Per-visit spend expansion is gaining share fastest among young adults.
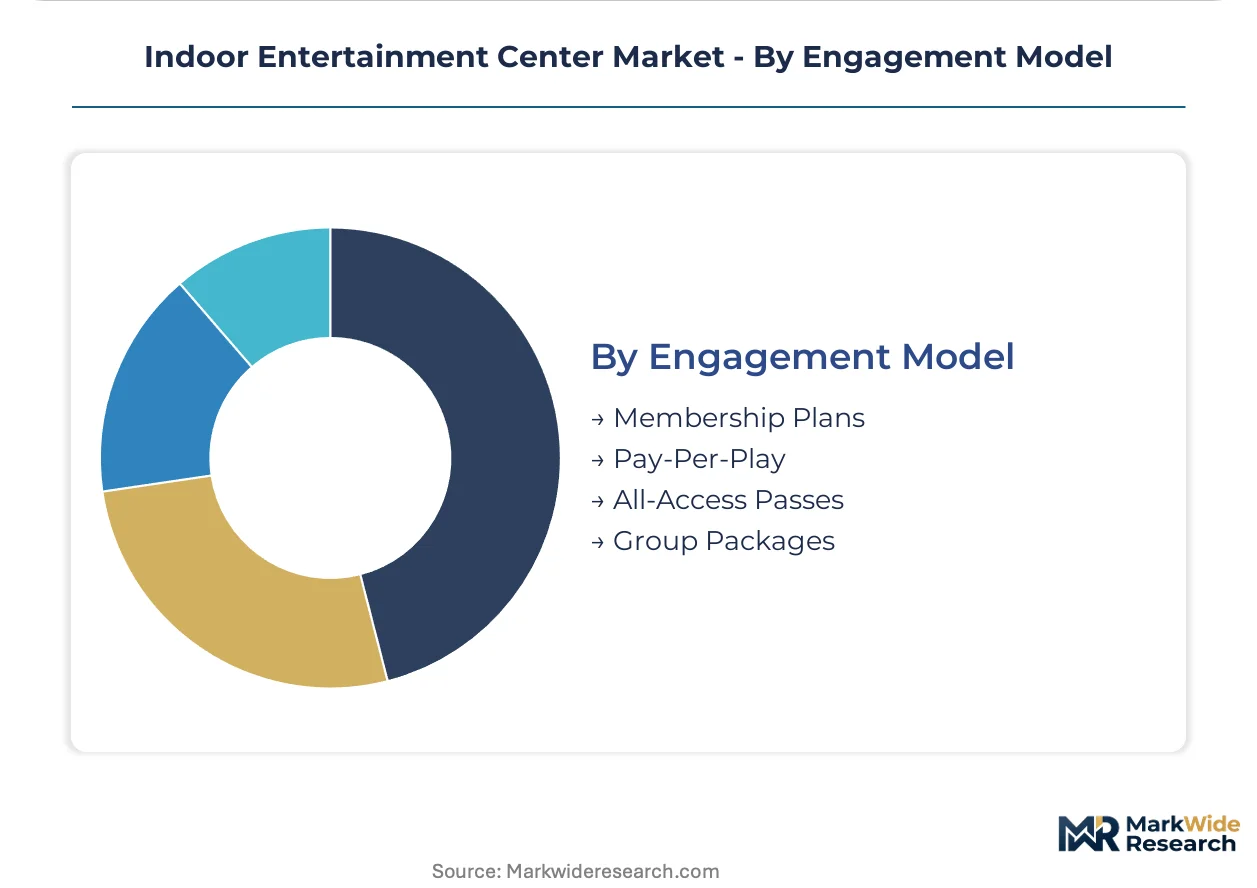
Engagement Model:
Revenue predictability and customer lifetime value hinge on subscription architecture versus transactional access.
- Membership Plans:Monthly unlimited-access subscriptions generating predictable recurring revenue. Arizona and Nevada venues report the steepest adoption curves as extreme summer heat eliminates outdoor alternatives for three to four months annually.
- Pay-Per-Play:Token or card-based attraction access with variable spend per visit.
- All-Access Passes:Single-visit unlimited attraction entry with time-bound validity.
- Group Packages:Pre-negotiated event pricing with dedicated staffing and catering integration for parties and corporate bookings.
Transactional dominance sits with pay-per-play. Predictable revenue conversion is expanding most quickly in membership plans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston, Phoenix, and Las Vegas anchor the highest concentration of indoor entertainment center development, where extreme summer heat sustains year-round demand for climate-controlled recreation facilities.
United States
Texas, Florida, and California dominate facility deployment through state-level amusement ride inspection programs that layer compliance obligations beyond federal ASTM International baseline. OSHA workplace safety standards govern technician training for engineered flooring systems. Dallas-Fort Worth corridor operators report the steepest adoption of RFID wristband payment systems.
United Arab Emirates
Dubai and Abu Dhabi drive premium-format venue investment through year-round air-conditioning dependency and tourism-driven foot traffic. MOHAP facility licensing requirements mandate specialized safety documentation for active recreation attractions. Dubai Investment Park clusters multiple family entertainment complexes competing on integrated F&B scale.
Saudi Arabia
Riyadh and Jeddah experience accelerated venue construction under Vision 2030 entertainment sector liberalization. The General Entertainment Authority issues operational permits with escalating safety audit frequencies. Riyadh Front entertainment district anchors the kingdom's largest concentration of bowling-laser tag hybrid formats.
Australia
Sydney and Melbourne sustain indoor entertainment demand through seasonal weather volatility and suburban household formation. State-level work health and safety regulators enforce trampoline park equipment certification with documented inspection protocols. Western Sydney corridor operators specialize in climbing wall and ropes course integration.
United Kingdom
Greater London and Manchester metropolitan areas concentrate premium-format venue investment despite compressed real estate availability. Health and Safety Executive guidelines govern adventure attraction operational protocols with penalty structures for documentation failures. Trafford Centre entertainment zone anchors northwest England's highest per-capita family entertainment complex density.
Indoor Entertainment Center Market Vendor Landscape
Premium-margin players sit above commodity-margin players across food-and-beverage integration depth and attraction technology sophistication. The vendor base stratifies into three tiers: large-format sports-bar-arcade hybrids, full-service dining bundled with bowling and laser tag, and active recreation specialists commanding higher per-visit spend through physical engagement requirements. Strategic archetypes include suburban corridor infill specialists, technology convergence leaders, and municipal zoning adaptation experts. Competitive moves concentrate on F&B kitchen infrastructure expansion and RFID payment system deployment.
Within the large-format hybrid tier, Dave & Buster's and Main Event Entertainment exemplify metropolitan trade area anchoring strategies. Among active recreation specialists, Urban Air Adventure Park occupies a position emphasizing climbing walls and ropes courses. CEC Entertainment, through its Chuck E. Cheese brand, represents the legacy family entertainment archetype adapting to subscription membership models.
| Leading Market Players |
|---|
| CEC Entertainment |
| Dave & Buster's |
| Main Event Entertainment |
| Scene75 Entertainment Centers |
| Urban Air Adventure Park |
| Cinergy Entertainment Group |
| Chuck E. Cheese |
| KidZania |
| Bowlero |
| Others |
Supply Flow & Price Mechanics
RFID wristband payment systems and cloud-based visitor analytics platforms are compressing transaction labor costs while concentrating procurement leverage among technology-integrated operators. This infrastructure convergence simultaneously lowers per-visit operational overhead and rewards scaled buyers who can amortize platform development across multiple facilities.
Pricing Analysis
Per-visit throughput economics anchor pricing architecture across facility formats, with trampoline parks and active recreation venues commanding premium rates over traditional arcade gaming. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM International certification tier, geographic Sun Belt corridor positioning, and F&B integration depth. Pricing pressure stems from insurance cost escalation in Texas, Florida, and California where state inspection programs inflate liability premiums. Young adult segments show lowest price sensitivity for bar-integrated evening formats, while family groups exhibit highest elasticity during off-peak weekday periods.
Supply Chain Analysis
Dual-sourcing requirements for engineered flooring systems and automated scoring infrastructure are fragmenting supplier relationships as operators mitigate single-source vulnerability. Equipment manufacturing concentrates in China, Germany, and the United States for trampoline spring systems, laser tag arena components, and bowling pinsetter mechanisms. Raw material dependencies span steel alloys for structural frames, synthetic polymers for padding surfaces, and semiconductor chips for RFID tracking hardware. Supply chain risk centers on tariff exposure for Chinese-manufactured adventure attraction components. Distribution runs through specialized recreation equipment distributors and direct OEM relationships for large-format venue developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as ASTM International certification timelines and insurance cost inflation force sub-scale operators toward exit or acquisition. Compliance burden asymmetry favors capitalized players who can front-load safety investment across multi-facility portfolios.
For Market Incumbents: Hedge against margin compression by deepening backward integration into F&B supply chains and securing exclusive municipal zoning positions in suburban Sun Belt corridors. Prioritize RFID payment platform standardization across portfolios to reduce labor dependency. Counter emerging active recreation specialists by accelerating climbing wall and ropes course retrofits in legacy bowling-laser tag hybrids.
For New Entrants and Emerging Players: The mid-market price-point gap between Dave & Buster's premium positioning and Chuck E. Cheese economy tier offers white-space entry in secondary Sun Belt metropolitan rings. Target suburban corridor infill around Houston, Phoenix, and Las Vegas where household formation outpaces established venue density. Differentiate through technology-enabled dynamic pricing and subscription membership models rather than attraction novelty alone.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by national platform operators seeking geographic density. Long-term viability favors operators with diversified attraction mixes and recurring revenue conversion above transactional dependence. Monitor municipal parking minimum liberalization and traffic impact requirement relaxation as inflection indicators for development site availability acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| F&B Kitchen Infrastructure Expansion | Houston and Phoenix venues report highest attach rates as extreme heat eliminates outdoor dining alternatives. |
| RFID Payment System Deployment | Dallas-Fort Worth operators lead adoption of wristband systems that eliminate token-based currency friction. |
| Active Recreation Format Integration | Climbing walls and ropes courses command higher per-visit spend than traditional arcade gaming floors. |
| Subscription Membership Conversion | Arizona and Nevada venues show steepest adoption curves as summer heat sustains year-round demand. |
| Suburban Corridor Infill Development | Secondary metropolitan rings face reduced competition while capturing household formation growth. |
Methodological Framework
Document review covered ASTM International safety standards, Consumer Product Safety Commission injury reporting databases, and state-level amusement ride inspection protocols, complemented by interviews with facility operations directors, equipment procurement managers, municipal zoning officials, and insurance underwriters specializing in recreation liability. Secondary validation drew from SEC filings of publicly traded operators, trade association membership data, and commercial real estate transaction records. Bottom-up facility count triangulation against top-down metropolitan market sizing anchored volume estimates.
Segmentation-level projections across facility type, service offering, target demographic, and engagement model dimensions were generated through the analytical framework. CAGRs were derived from trend extrapolation of capital deployment patterns and visitation elasticity to household formation metrics. Key inputs included ASTM certification timeline compression effects, Sun Belt demographic migration patterns, and F&B attach rate differentials by climate zone.
Underlying measurement precision varies by segment; trampoline park and laser tag arena data carry tighter precision than emerging hybrid formats where definitional boundaries remain fluid. Forecasts reflect assumptions around sustained Sun Belt population growth and stable insurance regulatory environments. A model refresh is warranted upon material change in ASTM International equipment approval timelines or municipal zoning liberalization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Festivals
Event Services Market
Events and Festivals
Professional Speaker Market
Events and Festivals
India Event and Exhibition Market
Events and Festivals
US Amusement and Theme Park Market
Events and Festivals
K-Pop Events Market
Events and Festivals
Stage and Scenery Equipment Market
Events and Festivals
UK Arts Promoter Market
Events and Festivals
Asia-Pacific Amusement Parks Market
Events and Festivals
Global Exhibition Market
Events and Festivals
Global Roller Coaster Market
Events and Festivals
Music Fountain Market
Events and Festivals
Events and Exhibition Market
Events and Festivals
Europe Event Pro-Av Services Market
Events and Festivals
Event Photography Service Market
Events and Festivals
Sports Events Tickets Market
Events and Festivals
North America K-Pop Events Market