
 Talent As a Service Market | 2026-2036
Talent As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Talent As a Service Market Analytics
Platform providers in North America is realigning how enterprises access specialized technical expertise. Upwork leverages its marketplace density to sustain freelancer liquidity across premium skill categories. Toptal competes through rigorous vetting protocols that anchor its positioning in elite software engineering placements.
Talent As a Service denotes the procurement of skilled human capital through digital platforms and managed service providers on flexible engagement terms, typically orchestrated via cloud-based workforce management systems with embedded compliance and payment automation. Its primary purpose is to reduce time-to-productivity for project-specific or scaling labor needs while transferring employment liability to specialized intermediaries. Staff augmentation currently dominates revenue flow due to enterprise preference for embedded team extensions over transactional hiring. AI-driven solutions within the technology dimension are expanding fastest as matching algorithms and skills assessment automation improve placement precision and reduce recruiter overhead.
The US Department of Labor enforces classification standards that shape how platforms structure contractor relationships and benefits obligations. The EU AI Act and GDPR impose algorithmic transparency and data governance requirements on European-deployed talent matching systems. Stakeholders must monitor evolving worker classification rulings across multiple jurisdictions to anticipate compliance cost shifts and platform model viability.
Market Dynamics
Platform providers are compressing time-to-placement through AI-driven matching engines while regulatory pressure from the EU AI Act and US worker classification rulings forces structural compliance investments.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy auditable talent-matching algorithms, driving procurement of certified platform infrastructure.
- Silicon Valley SaaS expansion:Technology firms in California and Washington State embed flexible talent pools to accelerate product release cycles.
- Skills assessment automation:Natural language processing and coding evaluation tools reduce recruiter screening hours by standardizing technical validation.
Market Restraints
- US Department of Labor classification uncertainty:Evolving contractor-employee boundary rulings create liability exposure for platform intermediaries.
- GDP concentration in freelance liquidity:Talent availability clusters in urban technology corridors, leaving rural and secondary markets underserved.
- Algorithmic bias litigation risk:Automated screening systems face discrimination claims that increase insurance and legal reserves.
Strategic Opportunities
- German industrial Mittelstand penetration:Mid-sized manufacturing enterprises remain underpenetrated by contingent technical talent platforms.
- Healthcare credentialing automation:Blockchain-verified professional licenses enable rapid deployment of specialized clinical and IT staff.
- Japan METI work-style reform incentives:Government subsidies for flexible employment models accelerate platform adoption among conservative enterprises.
Industry Challenges
- Legacy HR system integration:Enterprise resource planning platforms from SAP and Oracle require custom API development for workforce data synchronization.
- Cross-border payment complexity:Multi-currency settlements and tax withholding across jurisdictions demand specialized treasury infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Talent As a Service Market |
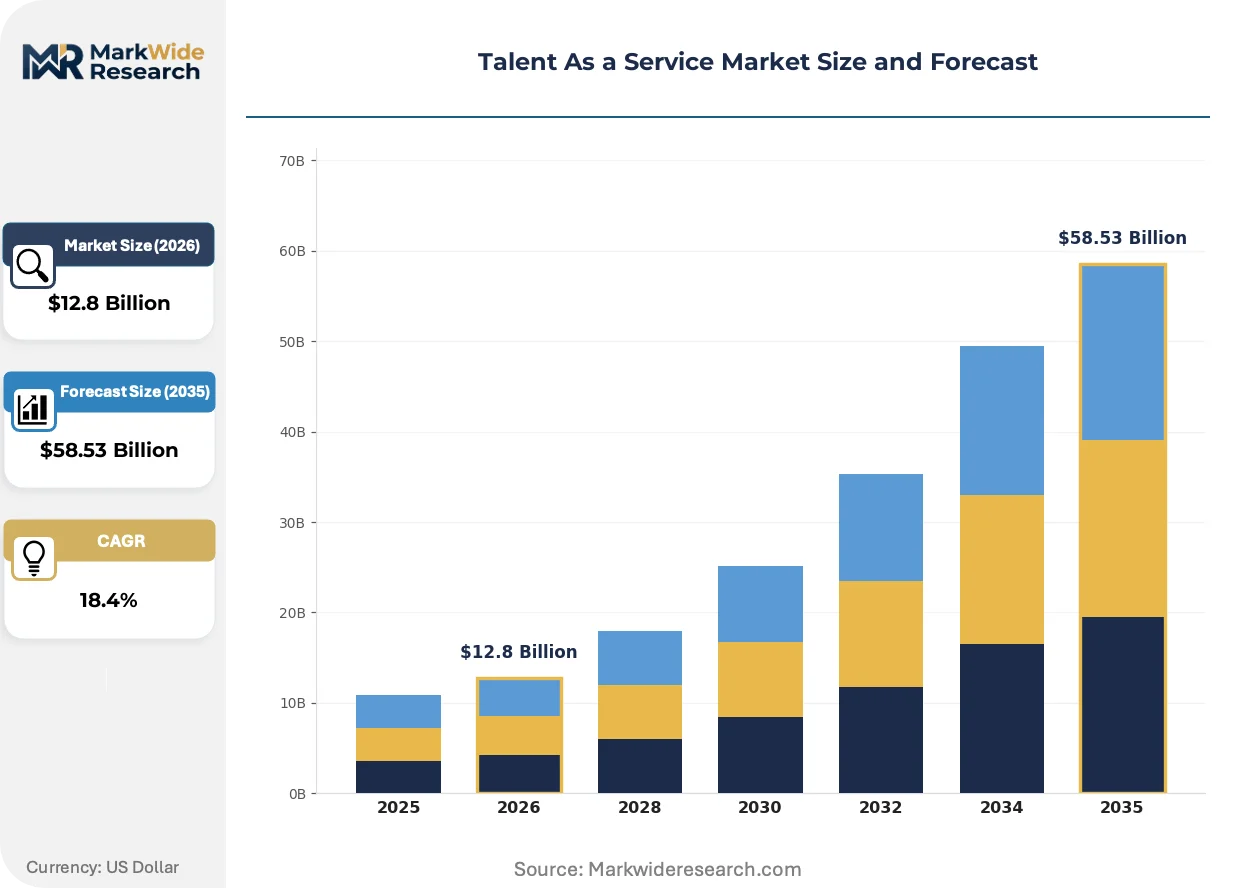
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recruitment, Staff Augmentation, Consultancy, Training Client Type: Startups, Enterprises, Non-Profits, Government Agencies Technology: AI-Driven Solutions, Cloud-Based Platforms, Data Analytics, Blockchain Engagement Model: Project-Based, Retainer, Hourly, On-Demand |
| Companies Covered | Upwork, Toptal, Randstad, ManpowerGroup, Adecco, Korn Ferry, IBM Corporation, Oracle Corporation, Andela, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Talent As a Service Market Evolving Landscape
Generative AI is rewiring how talent platforms source, vet, and match candidates, compressing traditional recruitment timelines while introducing new governance requirements.
Large language models paired with skills graph databases are rewriting the logic of candidate-job alignment. Technology enterprises in the United States deploy these systems to surface non-obvious capability adjacencies. The structural consequence is a shift from credential-based to demonstrated-competency hiring, flattening traditional degree requirements.
GDPR Article 22 automated decision-making restrictions are forcing European platforms to implement human-in-the-loop override protocols for AI-generated candidate rankings. This creates operational friction but also differentiation for vendors with transparent audit trails. Financial services and healthcare sectors in Germany and France are most affected, demanding explainable matching logic in procurement contracts.
Subscription-based talent access is displacing transactional per-hire fees among Fortune 500 technology divisions. Chief procurement officers negotiate annual platform licenses with embedded volume commitments, replacing contingent search firm relationships. This pattern is most visible in Seattle and Austin, where SaaS enterprises consolidate vendor relationships to reduce procurement overhead.
Talent As a Service Market Segmentation
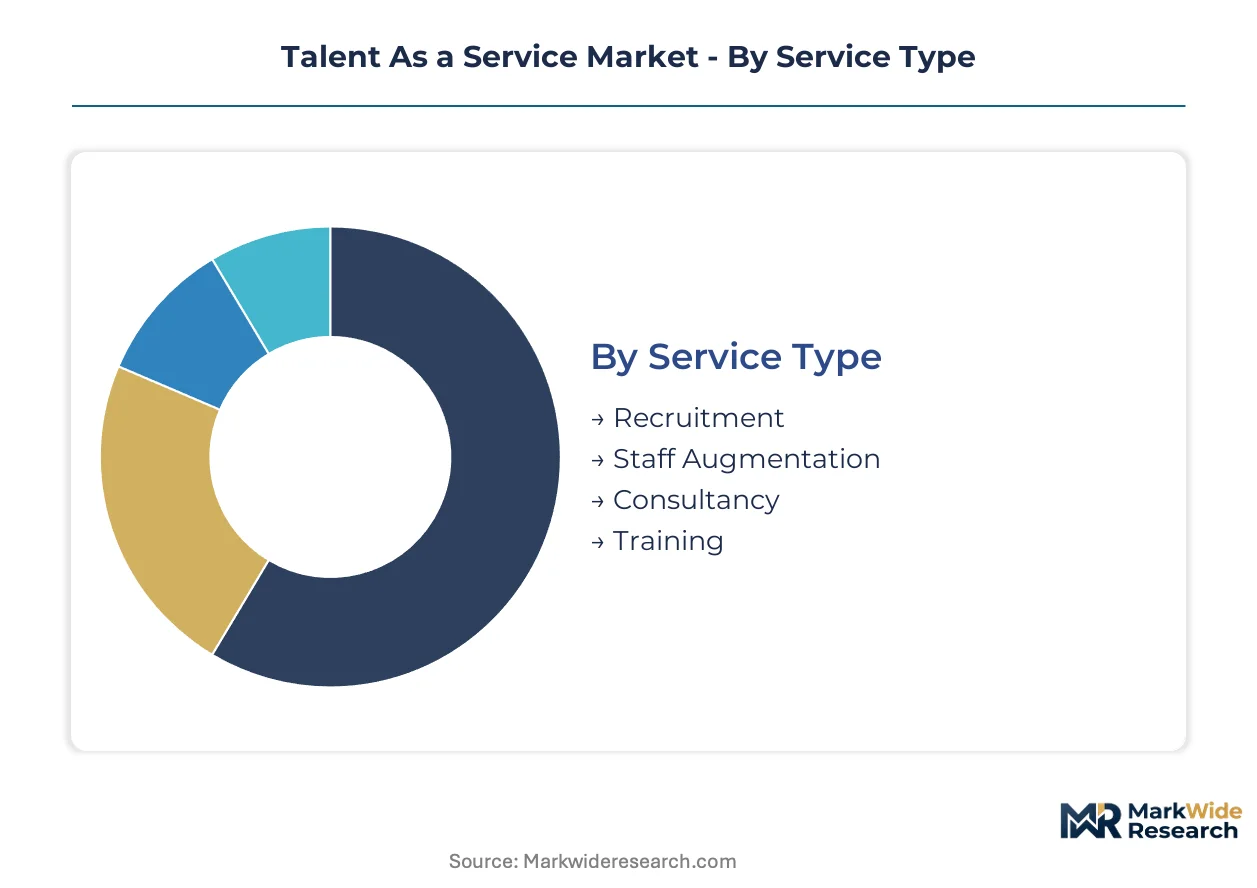
Segmentation in the Talent As a Service market reveals how procurement priorities diverge across buyer sophistication, technology readiness, and workforce flexibility requirements. Understanding these fault lines enables platform providers to calibrate pricing, compliance features, and matching algorithms to specific buyer archetypes.
Service Type:
Enterprise procurement teams prioritize speed-to-productivity and liability transfer when selecting engagement structures for contingent technical talent.
- Staff Augmentation:Embedded team extensions where external professionals operate under client direction within existing engineering workflows. Fortune 500 technology divisions in the United States favor this model for core platform development, transferring employment liability to specialized intermediaries while retaining technical oversight.
- Recruitment:Permanent placement services leveraging digital sourcing pipelines and automated screening tools. Silicon Valley SaaS firms concentrate demand here for specialized roles in machine learning infrastructure and cybersecurity, compressing time-to-hire through AI-driven candidate ranking.
- Consultancy:Strategic advisory engagements delivering project-specific expertise without long-term employment obligations. Mid-sized enterprises deploy this model for digital transformation roadmapping where internal capability gaps persist.
- Training:Skills development programs reskilling existing workforces or onboarding contingent talent to proprietary technology stacks. Demand clusters among German industrial Mittelstand firms modernizing legacy manufacturing systems.
Staff augmentation leads on scale; AI-enhanced recruitment leads on momentum.
Client Type:
Budget predictability and compliance sophistication separate how organizations structure flexible workforce relationships.
- Enterprises:Large organizations with dedicated procurement functions negotiating annual platform licenses and volume commitments. These buyers demand embedded compliance automation for GDPR and EU AI Act adherence across European operations.
- Startups:Venture-backed technology firms prioritizing speed and cost flexibility over process rigor. Hourly and project-based engagements dominate, with founders directly managing talent relationships through self-service platform interfaces.
- Government Agencies:Public sector entities subject to strict classification standards and benefits obligations. The US Department of Labor enforcement patterns shape how these buyers structure contractor relationships.
- Non-Profits:Mission-driven organizations with constrained procurement budgets and limited HR infrastructure. These buyers favor simplified engagement models with transparent pricing and minimal administrative overhead.
Enterprises dominate contract value; startups drive transaction velocity.
Technology:
Matching precision and audit transparency determine platform selection across regulatory environments.
- AI-Driven Solutions:Machine learning systems automating candidate-job alignment through skills graph analysis and natural language processing. European deployments require human-in-the-loop override protocols under GDPR Article 22 restrictions.
- Cloud-Based Platforms:Centralized workforce management systems enabling real-time collaboration, time tracking, and payment automation across distributed teams. These systems form the operational backbone for multi-jurisdictional talent deployment.
- Data Analytics:Performance measurement tools tracking productivity metrics and engagement quality. Procurement teams leverage these insights to optimize vendor relationships and forecast staffing needs.
- Blockchain:Distributed ledger applications verifying professional credentials and employment history. Healthcare and financial services buyers in Germany and France pilot these systems for rapid credential validation.
Cloud infrastructure anchors current deployments; blockchain credentialing climbs fastest.
Engagement Model:
Cash flow predictability and project scope certainty drive structural preferences for talent access.
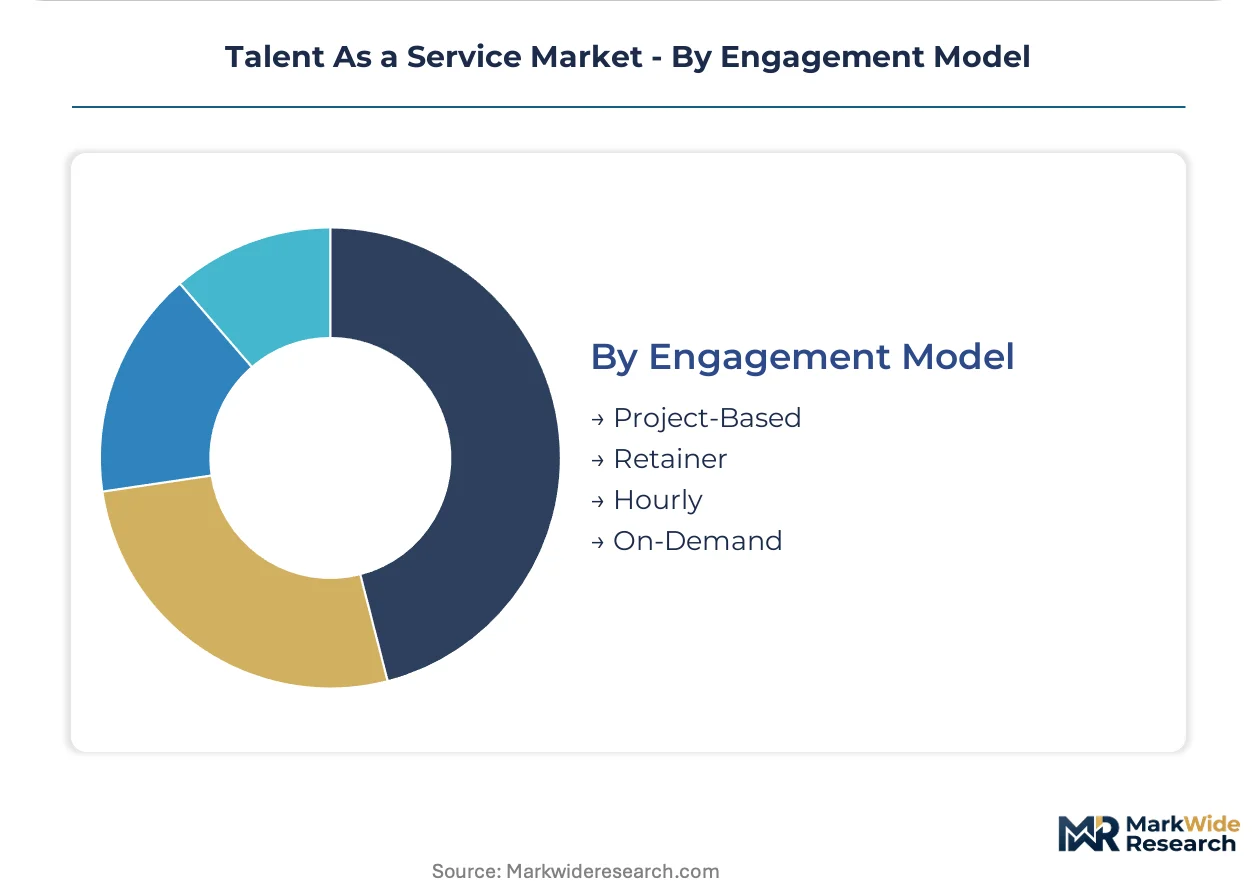
- Project-Based:Fixed-scope engagements with defined deliverables and milestone-based payments. Technology enterprises favor this model for product launches requiring surge capacity without ongoing obligations.
- Retainer:Prepaid access to reserved talent pools with guaranteed availability windows. Chief procurement officers negotiate these arrangements to secure specialized expertise during competitive hiring periods.
- Hourly:Time-and-materials billing for ad-hoc tasks and exploratory work. Startups and lean operations prefer this flexibility, though US worker classification uncertainty creates compliance exposure.
- On-Demand:Instant activation of pre-vetted talent through automated matching interfaces. This model compresses time-to-placement to hours rather than days, serving urgent technical needs.
Project-based engagements capture the largest revenue share; on-demand access gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is accelerating platform migration toward jurisdictions with clearer contractor classification frameworks. The United States maintains operational scale advantages despite classification uncertainty, while European markets absorb compliance premiums from the EU AI Act and GDPR mandates.
United States
Silicon Valley SaaS firms and Seattle-based cloud providers drive demand for embedded technical talent. The US Department of Labor enforces evolving contractor-employee boundary standards that reshape platform liability structures. Austin and Boston technology corridors concentrate startup adoption of flexible workforce models.
Germany
Industrial Mittelstand manufacturers modernizing legacy systems generate demand for contingent technical expertise. The EU AI Act mandates auditable algorithmic transparency for talent-matching systems deployed across German operations. Munich and Stuttgart engineering clusters anchor healthcare credentialing pilots using blockchain verification.
United Kingdom
London financial services and fintech ventures prioritize subscription-based talent access over transactional hiring. Post-Brexit regulatory divergence from EU frameworks creates compliance complexity for cross-border workforce deployment. The Southeast England technology corridor concentrates demand for AI-driven recruitment automation.
India
Domestic technology services firms and multinational captive centers expand flexible talent pools for software engineering capacity. The country's national labor codes introduce new social security obligations for platform-mediated work relationships. Bengaluru and Hyderabad technology hubs concentrate freelancer liquidity across premium skill categories.
Japan
Conservative enterprises accelerate platform adoption under METI work-style reform subsidy programs. The country's employment security traditions create cultural friction against contingent workforce normalization. Tokyo and Osaka metropolitan areas concentrate demand for specialized IT and clinical staff deployment.
Talent As a Service Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-native matching architectures and vertical specialization vectors. The market structures around three maturity tiers: global staffing conglomerates with legacy infrastructure, pure-play digital platforms with marketplace density, and enterprise software vendors embedding workforce modules. Competitive positioning hardens through M&A consolidation of regional specialists and strategic partnerships between platforms and cloud infrastructure providers.
Within the pure-play digital tier, Upwork and Toptal exemplify divergent vetting philosophies—marketplace breadth versus elite curation—while Randstad represents legacy staffing adaptation to platform economics. These anchors illustrate how geographic origin and organizational heritage shape competitive archetype selection: California-based marketplace models, New York-rooted professional services hybrids, and Dutch-originated global staffing networks each occupy distinct positions in buyer procurement hierarchies.
| Leading Market Players |
|---|
| Upwork |
| Toptal |
| Randstad |
| ManpowerGroup |
| Adecco |
| Korn Ferry |
| IBM Corporation |
| Oracle Corporation |
| Andela |
| Others |
Value Network & Pricing Analysis
Elite-vetting premium tiers command 3-4x rate multiples over marketplace-standard access, with Toptal's rigorous screening protocols and Upwork's density-driven liquidity representing divergent supply chain architectures. This bifurcation concentrates pricing power with curated talent networks while compressing margins in open-access marketplaces, forcing platform providers to calibrate compliance investments against contractor classification exposure.
Pricing Analysis
Platform take rates spanning 15-30 percent of contractor billings fund matching infrastructure and regulatory compliance reserves. Three-tier pricing structure across premium, standard, and economy levels segments by vetting depth, with Fortune 500 technology divisions absorbing premium rates for embedded team extensions. Cost compression in standard-tier access intensifies because AI-driven matching automation reduces recruiter overhead. Startups exhibit highest price sensitivity, negotiating hourly rates directly, while enterprise procurement officers prioritize liability transfer over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from risk-averse enterprises mandate qualification across multiple talent platforms, preventing single-provider dependency. Geographic supply concentration centers on the United States, India, and Germany, with Silicon Valley and Bengaluru anchoring premium software engineering liquidity. Raw material dependencies include cloud infrastructure from AWS and Azure, payment rails from Stripe and PayPal, and identity verification APIs. Single-source vulnerability persists in specialized credentialing databases. Distribution runs through direct enterprise sales teams and self-service marketplace interfaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Talent As a Service rests on AI-driven matching efficiency compressing recruiter cost-per-hire while enterprises migrate toward subscription-based talent access premiums.
For Market Incumbents: Cement platform stickiness through embedded compliance automation for EU AI Act and GDPR adherence, locking in European enterprise renewals. Acquire specialized credentialing technology to defend against blockchain-verified identity startups threatening verification moats. Vertical integration into payroll and benefits administration captures contractor relationship economics. For New Entrants and Emerging Players: EU AI Act compliance mandates in Germany and France open a window for auditable matching algorithm providers to displace incumbent platforms lacking transparency infrastructure. Target German industrial Mittelstand manufacturers modernizing legacy systems, where contingent technical talent penetration remains below 15 percent. Deploy healthcare credentialing automation as beachhead entry, leveraging blockchain-verified licenses for rapid clinical staff deployment. For Investors and Strategic Acquirers: Consolidation pressure builds where regional specialists lack capital to fund compliance infrastructure for multi-jurisdictional deployment. Platforms with demonstrated EU AI Act audit trails and established contractor liquidity in secondary US technology corridors represent priority acquisition profiles. Watch US Department of Labor classification rulings as inflection indicator for platform liability restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| AI Matching Engine Deployment | Natural language processing from Google Cloud and OpenAI compresses time-to-placement for Silicon Valley SaaS clients. |
| Compliance Infrastructure Investment | Human-in-the-loop override protocols satisfy GDPR Article 22 requirements for German financial services procurement. |
| Vertical Specialization | Healthcare credentialing automation targets Munich and Stuttgart engineering clusters with blockchain-verified licenses. |
| Geographic Expansion | Japan METI work-style reform subsidies accelerate platform adoption among conservative Tokyo enterprises. |
| Strategic Partnership | Salesforce and Workday integrations embed talent access within enterprise HR workflow systems. |
Research Methodology
Multiple input streams — primary interviews with platform executives and enterprise procurement officers, secondary validation through SEC filings and hyperscaler workforce disclosures, and customs data on cross-border service payments — were reconciled to construct market estimates. Chief technology officers at SaaS firms, talent acquisition leads at Fortune 500 technology divisions, and compliance officers at staffing intermediaries provided operational benchmarks. Bottom-up aggregation of platform transaction volumes and top-down cross-reference against enterprise technology spending produced convergent estimates.
Historical growth patterns from workforce management software adoption were cross-referenced against panel input from procurement executives to anchor projection assumptions. Segmentation dimensions modeled include service type, client size tier, technology deployment mode, and engagement structure across the analysis window. CAGRs were derived from S-curve penetration modeling calibrated to AI-driven recruitment automation adoption rates and EU regulatory compliance cost trajectories.
Revisions become necessary when US Department of Labor classification rulings materially shift contractor liability structures or when EU AI Act enforcement patterns alter platform operating costs. Forecasts reflect assumptions about enterprise subscription adoption and algorithmic matching precision improvement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Corporate Training and Talent Development
Europe Consulting Services Market
Corporate Training and Talent Development
Middle East and Africa Management Consulting Services Market
Corporate Training and Talent Development
Europe Corporate Training Market
Corporate Training and Talent Development
Asia-Pacific Management Consulting Services Market
Corporate Training and Talent Development
Educational Consulting and Training Market
Corporate Training and Talent Development
Asia Pacific Strategic Consulting Services Market
Corporate Training and Talent Development
Competency-Based Education Spending Market
Corporate Training and Talent Development
Corporate Workforce Development Training Market
Corporate Training and Talent Development
Global Outplacement Services Market
Corporate Training and Talent Development
Corporate Leadership Training Market
Corporate Training and Talent Development
France Outplacement Services Market
Corporate Training and Talent Development
United States HR Professional Service Market
Corporate Training and Talent Development
Asia-Pacific Corporate Training Market
Corporate Training and Talent Development
Europe Management Consulting Services Market
Corporate Training and Talent Development
Corporate Training Software Market
Corporate Training and Talent Development
Canada Outplacement Services Market