
 Global Mechanical Electrical and Plumbing (MEP) Services Market | 2026-2036
Global Mechanical Electrical and Plumbing (MEP) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mechanical Electrical and Plumbing (MEP) Services Market Foresight
Integrated design-build MEP bundling is consolidating buyer procurement patterns across large-scale construction projects. AECOM leverages its multidisciplinary engineering platform to capture bundled contracts spanning mechanical, electrical, and plumbing scopes. Jacobs anchors its position through deep R&D intensity in digital project delivery and energy modeling. Siemens competes by extending its building automation hardware into full-service MEP integration for smart infrastructure.
Mechanical Electrical and Plumbing services encompass the engineering, installation, commissioning, and maintenance of building systems including HVAC ductwork, electrical distribution networks, and water supply and drainage infrastructure, typically governed by ASHRAE standards, NEC codes, and local plumbing codes. The primary purpose is to ensure safe, efficient, and code-compliant environmental control and utility delivery within built structures. Installation services dominate value capture in new construction cycles, while Maintenance services generate recurring revenue streams with higher margin stability across building portfolios. Data Centers represent the fastest-growing application segment as hyperscale computing loads intensify cooling and power density requirements.
The U.S. Department of Energy enforces building energy codes that mandate minimum MEP system efficiency, while the EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in HVAC equipment, directly reshaping mechanical service specifications across member states. China's MIIT and GB standards impose dual carbon compliance thresholds on commercial building energy use, creating mandatory retrofit demand for existing MEP infrastructure. Stakeholders must monitor how tightening refrigerant regulations and escalating electrification codes reshape equipment selection and service contracting models.
Market Dynamics
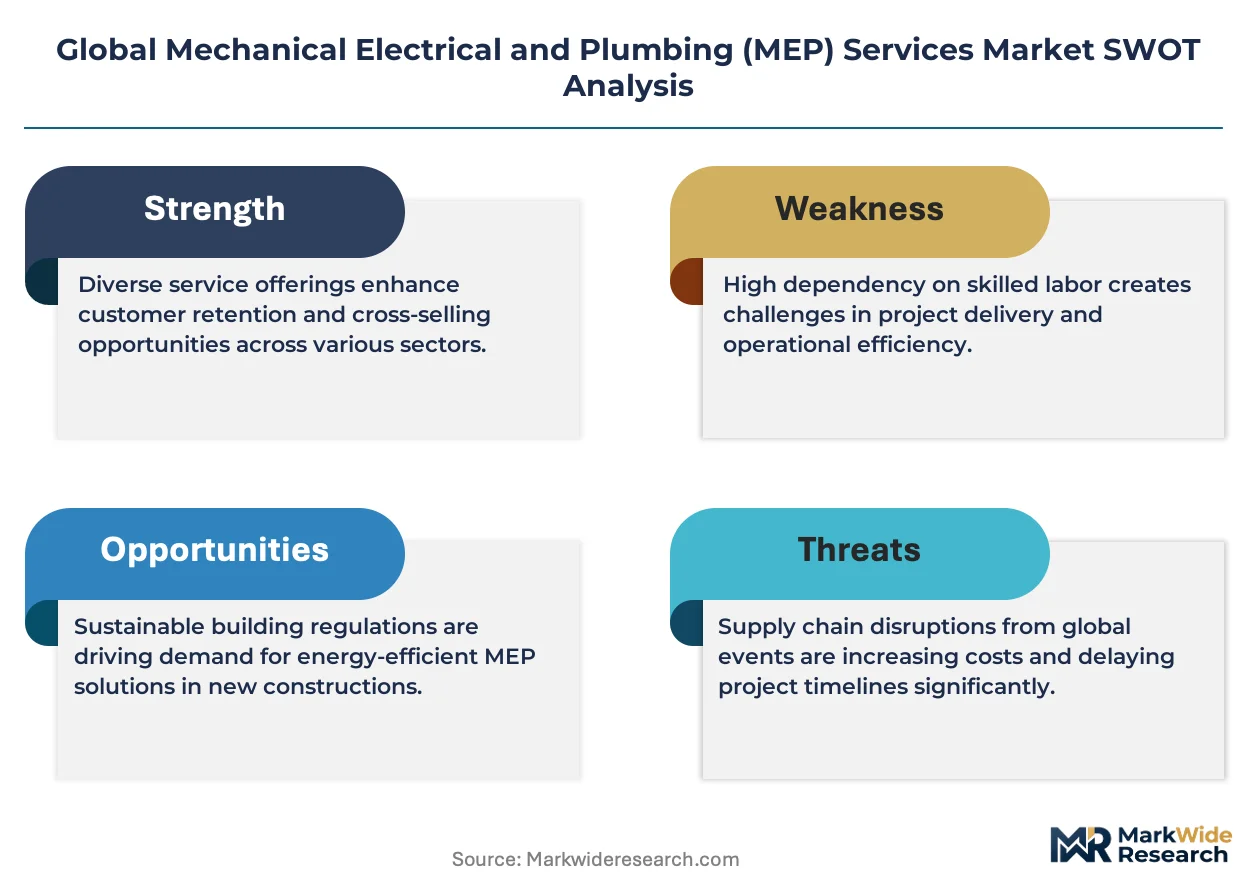
Building electrification mandates and refrigerant phase-down protocols are compressing equipment replacement cycles while expanding retrofit service scopes across commercial portfolios.
Growth Catalysts
- EU F-Gas Regulation:The hydrofluorocarbon phase-down is forcing HVAC equipment replacement across member states, expanding mechanical service contracts for refrigerant conversion and system upgrades.
- Data Center Power Density:Hyperscale computing loads are intensifying cooling and electrical infrastructure demands, pulling specialized MEP engineering into mission-critical facility construction.
- China's Dual Carbon Compliance:MIIT-mandated energy thresholds for commercial buildings are creating compulsory retrofit demand for existing mechanical and electrical systems.
Market Restraints
- Copper and Steel Input Volatility:Raw material price swings for electrical conduit and HVAC ductwork compress bid margins on fixed-price installation contracts.
- Specialized Labor Concentration:Licensed master electricians and certified refrigeration technicians cluster in metropolitan markets, constraining service expansion into secondary cities.
- Electrification Code Friction:Patchwork adoption of ASHRAE standards across municipalities creates compliance complexity for national service providers.
Strategic Opportunities
- India Commercial Retrofit Gap:BIS energy efficiency standards for existing buildings remain underenforced, creating first-mover advantage for code-compliant MEP upgrade services.
- Digital Twin Convergence:Building information modeling is converging with IoT sensor networks, enabling predictive maintenance contracts that displace reactive service models.
- US IRA Efficiency Incentives:Tax credits for building electrification and heat pump deployment are expanding homeowner and commercial buyer budgets for system replacements.
Industry Challenges
- Master Electrician Pipeline:Apprenticeship completion rates lag retirement outflows across Germany, the United States, and Australia, constraining installation capacity.
- Legacy BAS Integration:Proprietary building automation protocols from the 1990s resist interoperability with cloud-native energy management platforms, complicating smart retrofit scopes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mechanical Electrical and Plumbing (MEP) Services Market |
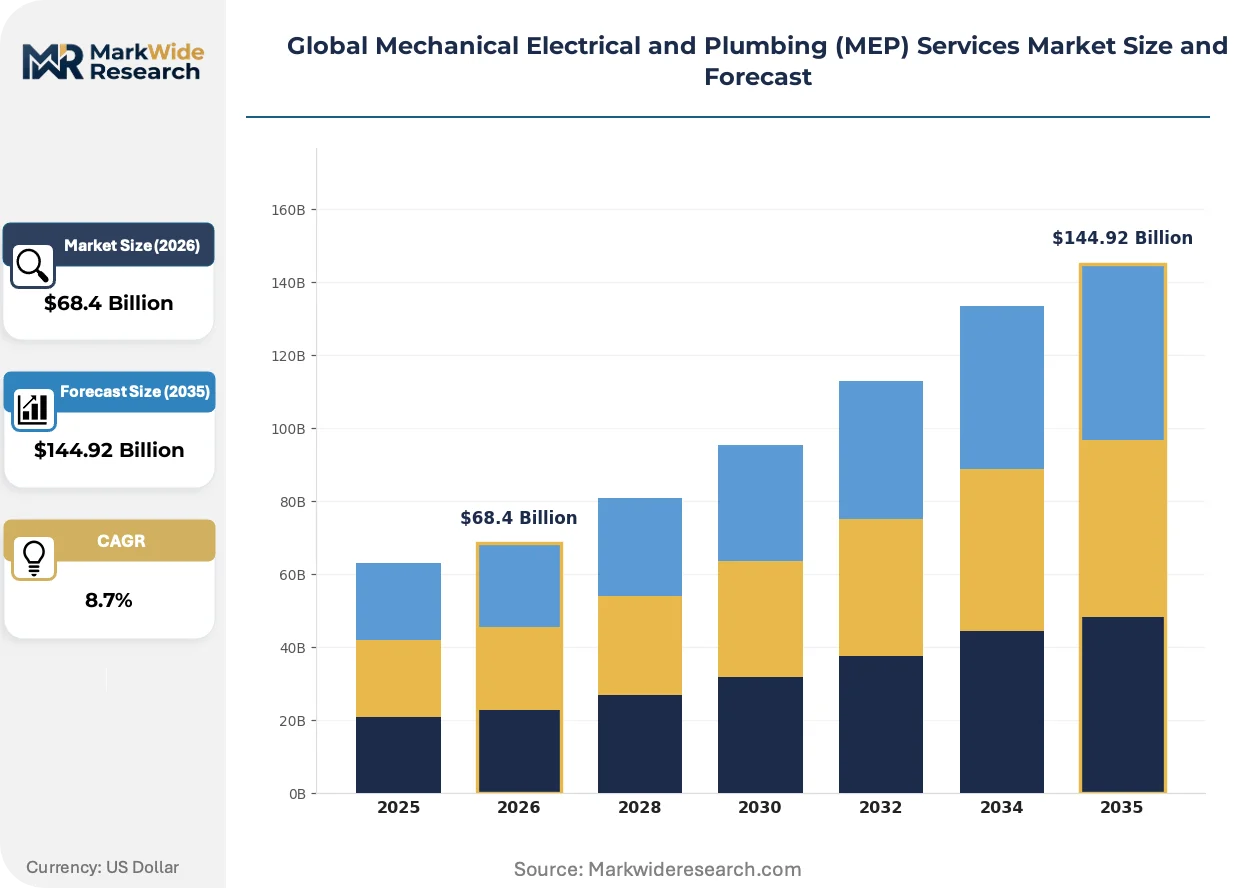
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
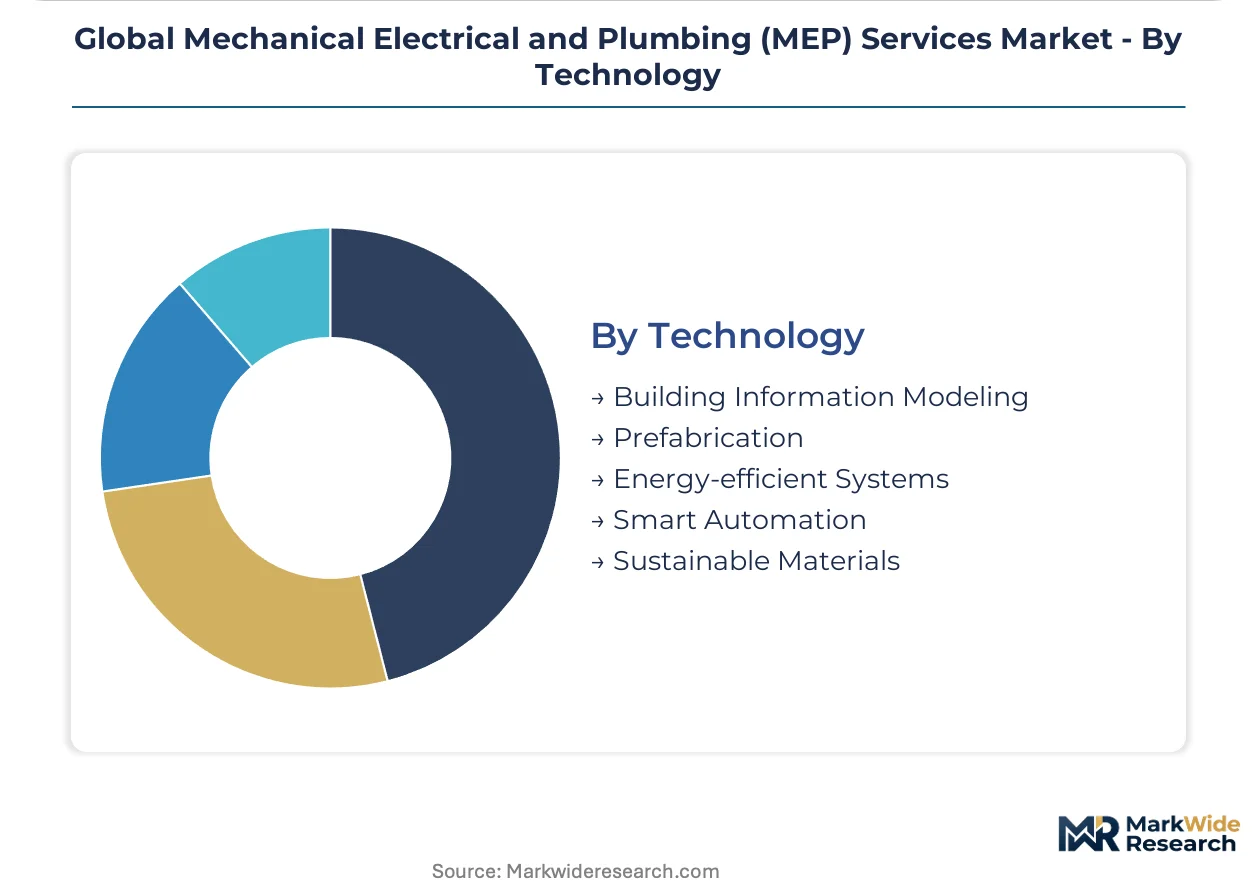
| Segmentation | Service Type: Installation, Maintenance, Renovation, Design, Inspection Application: Commercial Buildings, Industrial Facilities, Infrastructure Projects, Educational Institutions, Data Centers End User: Property Developers, Facility Managers, Construction Companies, Contractors, Government Agencies Technology: Building Information Modeling, Prefabrication, Energy-efficient Systems, Smart Automation, Sustainable Materials |
| Companies Covered | AECOM, Jacobs, WSP Global, Fluor Corporation, EMCOR Group, Arup, Schneider Electric, Siemens, Johnson Controls, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mechanical Electrical and Plumbing (MEP) Services Market Shifts & Advancements
Computational design tools and refrigerant chemistry advances are compressing system design cycles while expanding performance guarantees that service providers must underwrite.
Heat pump technology is converging with thermal energy storage systems to enable load-shifting capabilities in commercial buildings. Large-scale developers in Germany and the northeastern United States are specifying these hybrid configurations for new construction. The technology convergence is compressing traditional boundaries between mechanical design and electrical grid interaction services.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is mandating refrigerant chemistry transitions across HVAC equipment portfolios. Equipment manufacturers must retool production lines for lower-global-warming-potential alternatives. Commercial property managers in France and Italy are accelerating replacement timelines to avoid stranded-asset risk from service refrigerant unavailability.
Lifecycle service contracting is displacing discrete installation procurement in institutional building portfolios. University and healthcare facility managers in the United States and United Kingdom are bundling design, construction, and twenty-year maintenance into single-source agreements. This model concentrates vendor selection authority with procurement teams rather than project construction managers.
Global Mechanical Electrical and Plumbing (MEP) Services Market Segmentation
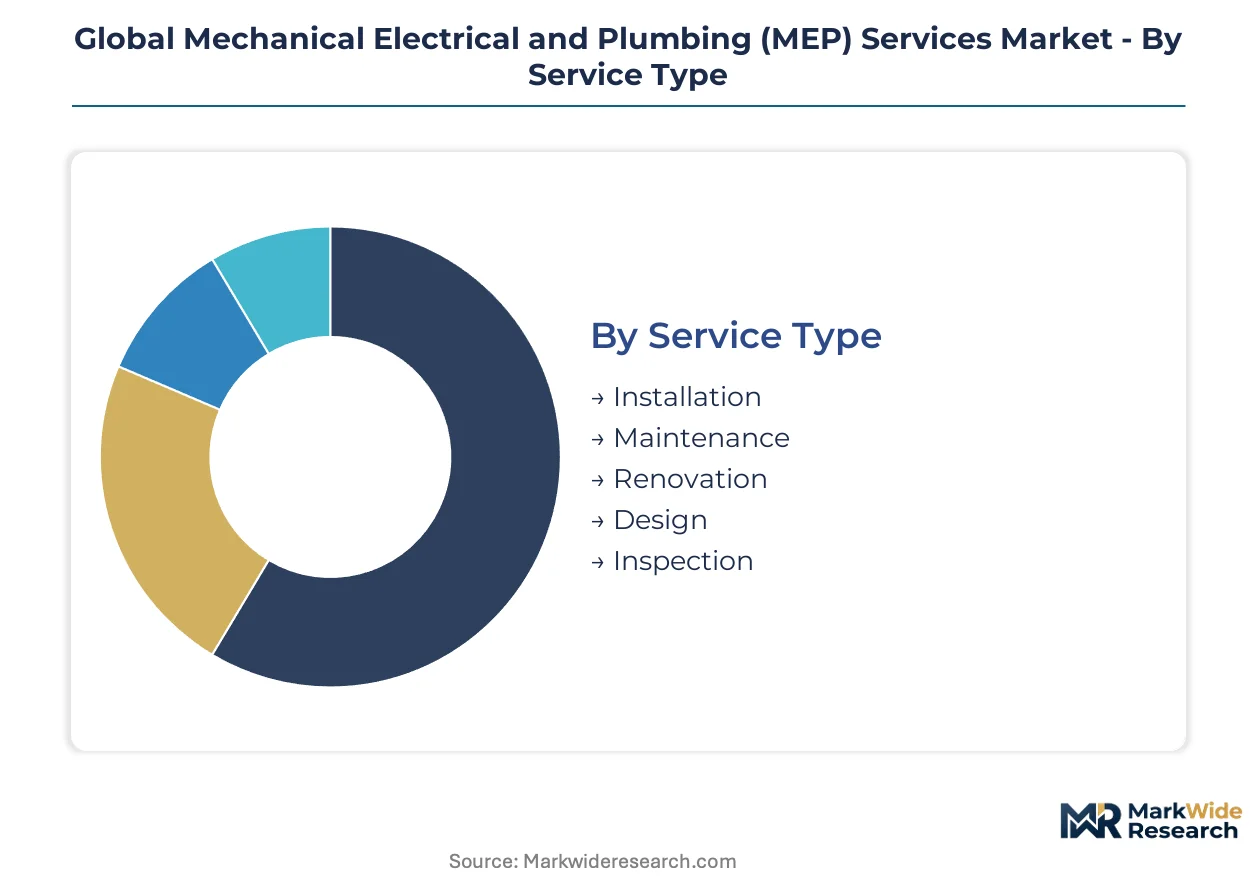
MEP service segmentation reveals how procurement patterns split between discrete project delivery and integrated lifecycle contracts. Technology and service type combinations determine margin structures and customer retention profiles across building portfolios.
Service Type:
Standalone installation contracts dominate new construction cycles, while embedded maintenance agreements lock in recurring revenue through multi-year facility management relationships.
- Installation:Encompasses HVAC ductwork, electrical distribution panels, and plumbing rough-in for new construction and major renovations. Demand concentrates in data center construction across the United States, Germany, and China, where power density requirements are forcing specialized high-voltage and precision cooling infrastructure deployment.
- Maintenance:Covers preventive servicing, emergency repair, and system optimization under recurring contracts. Facility managers in commercial office towers across London, New York, and Singapore are consolidating vendor relationships to reduce procurement overhead and ensure code compliance continuity.
- Renovation:Retrofit and system replacement services for aging building stock. EU F-Gas Regulation mandates are accelerating refrigerant conversion projects across France and Italy.
- Design:Engineering and consulting for system specification and energy modeling. Developers in Germany specify heat pump-thermal storage hybrid configurations requiring integrated mechanical-electrical design.
- Inspection:Code compliance verification and commissioning services. China's MIIT energy thresholds are expanding mandatory inspection scopes for existing commercial buildings.
Installation leads volumes today; Maintenance is gaining share fastest through lifecycle contracting adoption.
Application:
Cost tier segmentation separates mission-critical facilities with premium engineering budgets from commodity construction with standardized MEP specifications.
- Data Centers:Hyperscale computing loads demand redundant power distribution, liquid cooling, and precision environmental control. Developers in Northern Virginia, Frankfurt, and Singapore are specifying N+1 electrical resilience and direct-to-chip cooling architectures.
- Commercial Buildings:Office towers, retail centers, and mixed-use developments requiring standard HVAC, lighting, and plumbing systems. Retrofit demand is concentrating in New York and London as electrification codes tighten.
- Industrial Facilities:Manufacturing plants with heavy electrical loads and process cooling requirements. Automotive battery gigafactories across Germany and the United States are pulling specialized high-amperage infrastructure engineering.
- Infrastructure Projects:Transportation hubs, utilities, and public works with extended asset lifecycles. Airport expansions in Dubai and Delhi are bundling MEP into design-build-operate contracts.
- Educational Institutions:Schools and universities with extended maintenance horizons and sustainability mandates. University systems in California and the United Kingdom are piloting twenty-year single-source MEP agreements.
Commercial Buildings anchor revenue today; Data Centers show the steepest expansion trajectory.
End User:
Customer type determines contract structure, with institutional buyers favoring performance guarantees and private developers prioritizing capital cost optimization.
- Property Developers:Speculative and build-to-suit construction with fixed-budget procurement. Greenfield residential towers in Mumbai and São Paulo are standardizing MEP packages to accelerate pre-sales.
- Facility Managers:Operating-phase building stewardship with lifecycle cost accountability. Corporate real estate teams in Sydney and Toronto are consolidating vendor panels to reduce service fragmentation.
- Construction Companies:General contractors subcontracting specialized MEP scopes. Large infrastructure primes in the Middle East are demanding design-assist partnerships to mitigate schedule risk.
- Contractors:Trade specialists executing electrical, mechanical, or plumbing work packages. Master electrician shortages across Germany and Australia are constraining installation capacity.
- Government Agencies:Public procurement with prevailing wage and domestic content requirements. Federal building retrofits under the US Inflation Reduction Act are expanding heat pump deployment budgets.
Construction Companies dominate transaction volumes; Facility Managers are displacing project-led procurement fastest.
Technology:
Maturity segmentation separates proven methods with established pricing from emerging approaches requiring capability investment and risk underwriting.
- Building Information Modeling:Digital twin platforms integrating 3D design with construction sequencing and asset data. Jacobs anchors competitive positioning through R&D intensity in BIM-enabled project delivery.
- Prefabrication:Off-site module assembly for ductwork, electrical skids, and plumbing risers. Labor cost arbitrage is expanding modular adoption in high-wage markets like Switzerland and Scandinavia.
- Energy-efficient Systems:Heat pumps, LED lighting, and variable refrigerant flow equipment. US IRA tax credits are expanding commercial buyer budgets for system replacements.
- Smart Automation:IoT-enabled building controls and predictive maintenance platforms. Proprietary legacy BAS protocols from the 1990s resist cloud-native integration.
- Sustainable Materials:Low-global-warming-potential refrigerants and recycled copper conduit. EU F-Gas Regulation is mandating refrigerant chemistry transitions across HVAC portfolios.
Energy-efficient Systems command the largest installed base; Smart Automation is climbing the fastest as predictive maintenance contracts displace reactive service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The MEP services industry traces its modern scale to post-war American construction standardization, with ASHRAE codes and NEC electrical standards later diffusing to Europe and Asia-Pacific markets through multinational engineering firm expansion.
United States
Data center construction in Northern Virginia and hyperscale cloud expansion across Phoenix and Dallas are pulling specialized high-voltage and precision cooling engineering. The Inflation Reduction Act's tax credits for building electrification and heat pump deployment are expanding retrofit budgets for commercial portfolios. Master electrician shortages across Texas and California are constraining installation capacity and inflating labor bid premiums.
Germany
Automotive battery gigafactories in Lower Saxony and Baden-Württemberg are demanding heavy electrical infrastructure and process cooling specialization. The EU F-Gas Regulation's hydrofluorocarbon phase-down is mandating refrigerant chemistry transitions across HVAC equipment portfolios. Frankfurt's data center cluster is specifying N+1 electrical resilience and direct-to-chip liquid cooling architectures.
China
MIIT-mandated dual carbon compliance thresholds for commercial buildings are creating compulsory retrofit demand across Shanghai and Beijing office towers. GB standards enforcement is tightening energy performance specifications for new construction. The Yangtze River Delta's manufacturing base is pulling industrial MEP services for semiconductor fabrication facilities.
India
BIS energy efficiency standards for existing buildings remain underenforced, creating first-mover positioning for code-compliant MEP upgrade services in Mumbai and Delhi-NCR. Commercial retrofit gaps in Bangalore and Hyderabad are attracting specialized contractors. Greenfield residential towers across Pune and Chennai are standardizing MEP packages to accelerate pre-sales velocity.
Singapore
Tropical data center construction with liquid cooling requirements is intensifying demand for precision environmental control engineering. The city-state's building codes mandate stringent energy performance standards for commercial developments. Facility managers in the central business district are consolidating vendor panels to reduce service fragmentation and ensure compliance continuity.
Global Mechanical Electrical and Plumbing (MEP) Services Market Competitive Landscape
The competitive structure tilts toward diversified engineering conglomerates with multidisciplinary platform capabilities. Large-scale developers favor bundled procurement spanning mechanical, electrical, and plumbing scopes under single-source accountability. Three archetypes dominate: integrated design-build operators, hardware-extended service integrators, and specialized mission-critical engineering boutiques. Consolidation pressure is intensifying through design-assist partnerships and lifecycle service contract bundling.
Among diversified engineering conglomerates, AECOM and Jacobs exemplify the integrated platform archetype, while Siemens anchors the hardware-to-services extension model. AECOM leverages its multidisciplinary engineering footprint to capture bundled contracts across building systems. Jacobs occupies a position defined by digital project delivery intensity and energy modeling specialization. Siemens represents the building automation hardware manufacturer's path into full-service MEP integration for smart infrastructure deployments.
| Leading Market Players |
|---|
| AECOM |
| Jacobs |
| WSP Global |
| Fluor Corporation |
| EMCOR Group |
| Arup |
| Schneider Electric |
| Siemens |
| Johnson Controls |
| Others |
Supply & Pricing Matrix
Horizontal integration across mechanical, electrical, and plumbing trades anchors both supply positioning and pricing power for diversified engineering conglomerates. Bundled design-build contracts compress procurement overhead for developers while inflating vendor switching costs, concentrating margin capture with platform-scale operators in the United States, Germany, and China.
Pricing Analysis
Project-based fixed-price contracting dominates installation scopes, with premium-mid-economy pricing differentiation separating mission-critical data center engineering from commodity commercial building work. Price differentiation rests on certification density and after-sales bundling, as LEED-accredited and ASHRAE-certified engineers command bid premiums. Cost compression in standard commercial installation is intensifying because copper and steel input volatility erodes fixed-margin contracts. Property developers exhibit highest price sensitivity, while facility managers prioritize lifecycle cost guarantees over upfront capital outlays.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act and China's GB standards enforcement are reshaping sourcing patterns for electrical equipment and HVAC components. Manufacturing concentration centers on China for copper conduit and switchgear, Germany for precision control systems, and the United States for high-voltage distribution equipment. Raw material dependencies draw from Chilean copper, Australian steel, and South Korean semiconductors for building automation controllers. Single-source vulnerability in refrigerant chemistry supplies feeds from EU F-Gas Regulation phase-down timelines. Distribution runs through authorized dealer networks for equipment and direct project contracting for installation labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MEP services market functions as a regulatory compounder, where the EU F-Gas Regulation's hydrofluorocarbon phase-down mandates recurring equipment replacement cycles across member states. This structural demand driver insulates service providers from pure construction cyclicality.
For Market Incumbents: Hedge refrigerant chemistry transition risk by building captive service capacity for lower-global-warming-potential alternatives across France and Italy. Deepen backward integration into thermal energy storage manufacturing to capture heat pump-thermal hybrid specification demand in Germany and the northeastern United States. Anchor position through twenty-year lifecycle contracts that displace reactive maintenance models in university and healthcare portfolios. For New Entrants and Emerging Players: Enter via India's underenforced BIS energy efficiency standards, where first-mover positioning for code-compliant retrofit services in Mumbai and Delhi-NCR offers protected margin pools. Target predictive maintenance platform development as the most penetrable technology segment, where legacy BAS protocol fragmentation creates incumbent vulnerability. Pursue design-assist partnerships with Middle Eastern infrastructure primes to mitigate schedule risk and build referenceability. For Investors and Strategic Acquirers: Roll-up economics work for specialized mission-critical engineering boutiques because master electrician and certified refrigeration technician shortages constrain organic expansion across Germany, the United States, and Australia. Five-to-ten year viability favors acquisition targets with embedded digital twin capabilities and IoT-enabled predictive maintenance contracts. Monitor apprenticeship completion rate inflections as the signal indicating installation capacity loosening or tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Lifecycle Service Contracting | Bundled design-build-maintain agreements concentrate procurement authority with facility managers in US and UK university systems. |
| Refrigerant Chemistry Transition | Lower-global-warming-potential retooling captures EU F-Gas Regulation-mandated replacement demand across France and Italy. |
| Digital Twin Platform Development | BIM-IoT convergence enables predictive maintenance contracts displacing reactive service models in Singapore commercial towers. |
| Master Electrician Apprenticeship Programs | Pipeline investment addresses retirement outflow constraints in Texas and California installation markets. |
| Heat Pump-Thermal Storage Hybrid Specification | Integrated mechanical-electrical design capability captures German automotive battery gigafactory and data center demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEP engineering directors, facility management procurement leads, construction company project executives, and building automation system integrators with secondary validation. Regulatory filings from the US Department of Energy, EU F-Gas Regulation implementation documents, and China's MIIT compliance circulars anchored policy impact assessment. SEC 10-K disclosures from diversified engineering conglomerates, construction industry association reports, and energy code adoption databases supplied financial and operational benchmarks. Bottom-up project pipeline tracking and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across installation, maintenance, renovation, design, and inspection service types, with application splits across data centers, commercial buildings, industrial facilities, infrastructure projects, and educational institutions. Technology segmentation captured Building Information Modeling, prefabrication, energy-efficient systems, smart automation, and sustainable materials adoption curves. CAGRs were derived from regression analysis against construction spending, regulatory compliance deadlines, and equipment replacement cycle data. Hyperscale data center power density requirements and dual carbon compliance thresholds provided industry-specific forecast anchors.
Inputs from primary stakeholder interviews and regulatory documentation were available through the study window; gaps in real-time project cancellation data and labor migration patterns introduce uncertainty bands around installation capacity assumptions. Forecasts reflect documented policy implementation timelines and equipment replacement schedules, with revision risk tied to ASHRAE code adoption patchwork, copper price volatility, and apprenticeship program funding shifts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
Pressure Pumping Services Market