
 US Electrical Services Market | 2026-2036
US Electrical Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Electrical Services Market Analysis
Texas utility-scale solar construction is broadening the addressable market for high-voltage contractors across the ERCOT interconnection. Quanta Services dominates transmission infrastructure deployment across the Southwest, leveraging its unionized craft labor pool to secure utility-scale contracts. MYR Group anchors specialized substation and switchyard work for renewable developers, while Rosendin Electric competes aggressively in data center electrical packages across Phoenix and Dallas-Fort Worth.
Electrical services encompass the design, installation, commissioning, and lifecycle maintenance of power distribution systems operating from 120V premises wiring through 345kV transmission interconnections, including switchgear, transformers, protective relaying, and grounding systems. The primary commercial purpose is to deliver code-compliant, continuously available electrical energy to end-use equipment while maintaining arc-flash safety and power quality standards. Installation services currently capture the largest revenue pool across the value chain, while maintenance contracts tied to smart grid and energy storage assets represent the fastest-expanding margin segment. LED lighting retrofits in commercial buildings have matured into a price-commoditized category, whereas solar panel and energy storage integration commands premium technician rates due to DC-to-AC conversion complexity and inverter synchronization requirements.
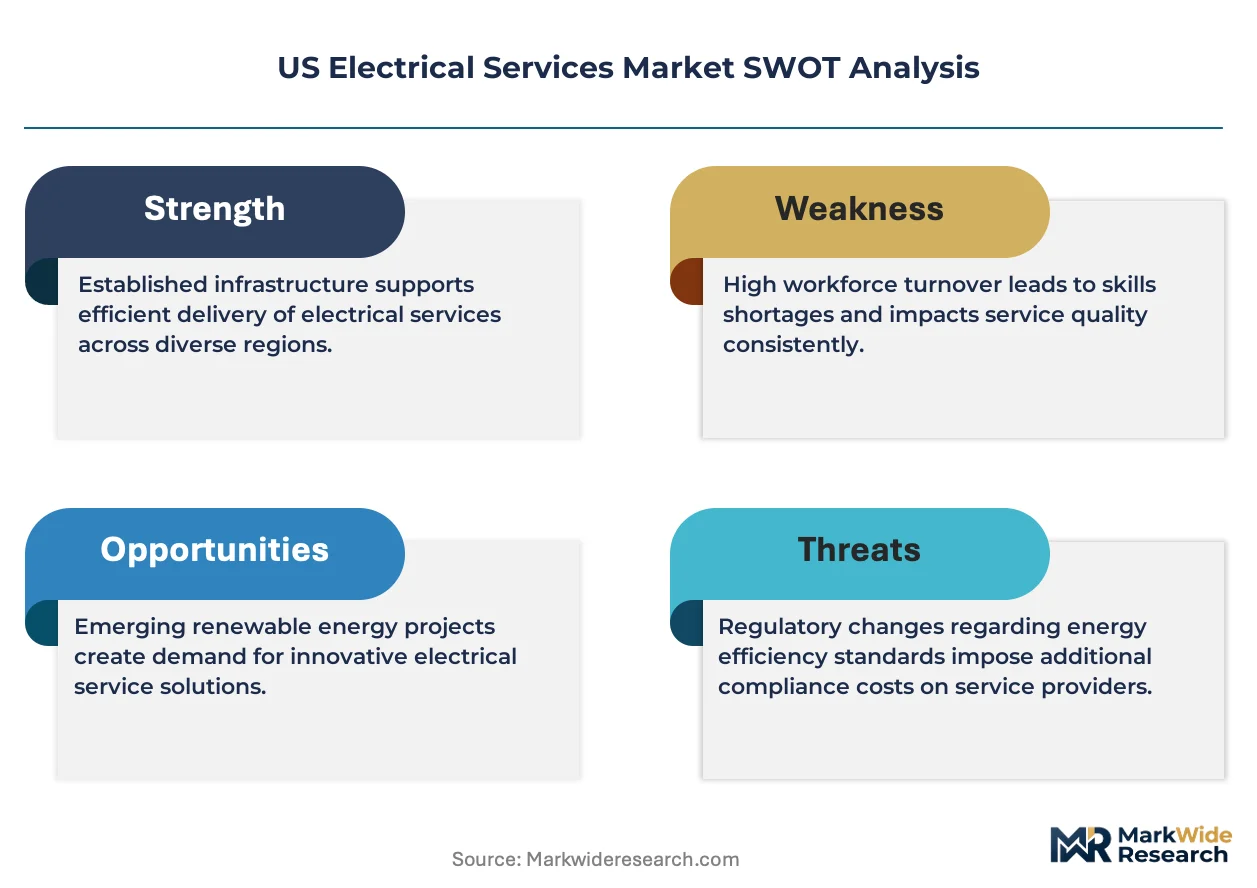
NECA, IBEW, and OSHA standards govern workforce qualification, job site safety protocols, and energized work permitting across the United States, with state-level amendments in California and New York imposing additional solar-specific licensing requirements that filter market access. The Inflation Reduction Act's domestic content bonuses for renewable projects are reshaping contractor sourcing decisions toward union-trained electricians and American-manufactured switchgear. Stakeholders must monitor interconnection queue backlogs at regional transmission organizations, as delayed utility approvals are compressing project cash conversion cycles and forcing working capital restructuring across the contractor base.
Market Dynamics
The Inflation Reduction Act's domestic content bonuses are rewiring contractor procurement toward union-trained labor pools and American-manufactured switchgear, compressing margins for non-compliant bidders while elevating qualified electrical services providers across transmission and renewable interconnection segments.
Growth Catalysts
- Data Center Power Density:Hyperscale facilities in Northern Virginia and Phoenix are demanding 345kV substation construction and specialized medium-voltage distribution, pulling high-voltage contractors into mission-critical uptime contracts.
- ERCOT Solar Buildout:Texas utility-scale solar and battery storage interconnection queues are expanding contractor addressable market for collector system installation and inverter synchronization services.
- OSHA Energized Work Rulemaking:Updated arc-flash protection standards are mandating certified technicians for live-line maintenance, tightening labor supply and elevating rates for qualified electrical services firms.
Market Restraints
- Copper and Aluminum Price Volatility:Raw material input swings for conductor cable and busbar are compressing fixed-price contract margins and forcing escalation clauses into project bids.
- Transformer Manufacturing Concentration:Domestic production capacity for medium-voltage transformers is concentrated among a handful of original equipment manufacturers, extending lead times and constraining project scheduling flexibility.
- Interconnection Queue Backlogs:Regional transmission organization approval delays at PJM and ERCOT are stretching cash conversion cycles and forcing working capital restructuring across the contractor base.
Strategic Opportunities
- Energy Storage Integration:DC-coupled battery systems paired with solar arrays require specialized inverter commissioning and protective relaying configuration, opening premium service tiers for technicians with power electronics certification.
- California Electrification Mandates:Title 24 building efficiency standards and SB 100 renewable portfolio requirements are channeling retrofit demand toward certified contractors capable of EV infrastructure and heat pump electrical upgrades.
- Smart Grid Maintenance Contracts:Distribution automation and advanced metering infrastructure lifecycles are generating recurring revenue streams for firms with substation communication and SCADA integration capabilities.
Industry Challenges
- Journeyman Electrician Shortage:IBEW apprenticeship completion rates are lagging project demand across Texas and Arizona, forcing wage inflation and schedule compression.
- NECA Certification Timelines:Specialized credentials for high-voltage switching and renewable interconnection are extending technician onboarding cycles, constraining workforce scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electrical Services Market |
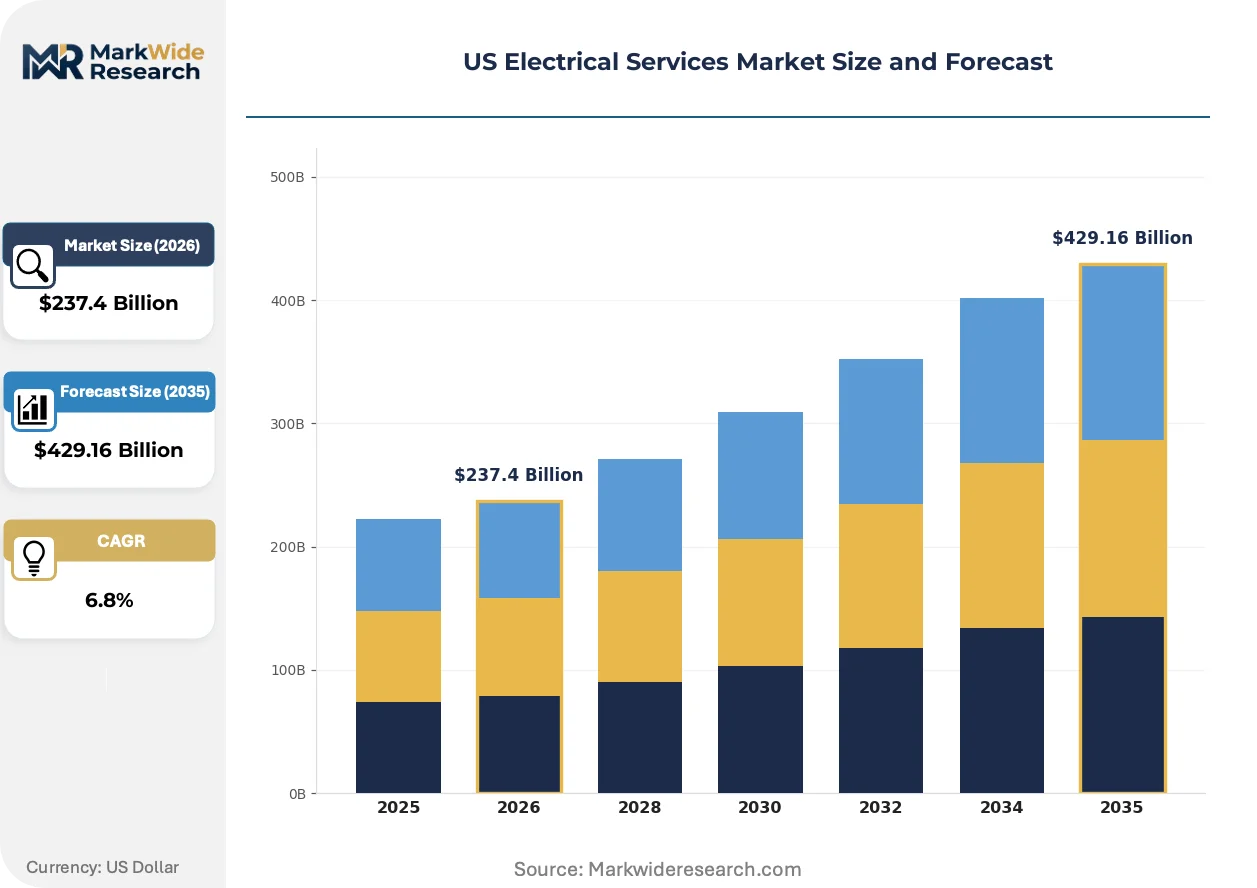
| Market Size in 2026 | $237.4 Billion |
| Market Size in 2035 | $429.16 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Repair, Inspection End User: Residential, Commercial, Industrial, Government Power Source: Renewable, Non-Renewable, Hybrid, Backup Technology: Smart Grids, LED Lighting, Solar Panels, Energy Storage |
| Companies Covered | EMCOR, MasTec, Quanta Services, Cleveland Electric, MDU Resources Group, MYR Group, IES Holdings, Five Star Electric, Rosendin Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electrical Services Market Emerging Trajectories
Digital design tools and prefabricated electrical assemblies are compressing field installation hours while elevating quality consistency, reshaping how contractors bid labor versus material content in competitive tenders.
Power electronics hardware is converging with cloud-based asset monitoring platforms, enabling predictive maintenance contracts for inverter and transformer fleets. Renewable developers are adopting these bundled service agreements to minimize unplanned outage exposure. This convergence is compressing traditional time-and-materials maintenance models into performance-guaranteed subscription structures.
OSHA's updated energized work permitting framework is tightening documentation requirements for arc-flash boundary calculations and personal protective equipment verification. Electrical contractors are responding by embedding certified safety officers into project teams and digitizing job hazard analysis workflows. The regulatory shift most acutely affects transmission and substation contractors operating above 15kV, where live-line work permits carry elevated liability exposure.
Buyer consolidation among hyperscale data center operators is compressing vendor qualification cycles and unbundling design-build contracts into separate engineering, procurement, and construction phases. Tier-one contractors are responding by deepening relationships with direct equipment manufacturers to secure switchgear allocation priority. This behavioral shift is most visible across Northern Virginia's Loudoun County corridor, where Microsoft, Amazon Web Services, and Google account for concentrated procurement volume.
US Electrical Services Market Segmentation
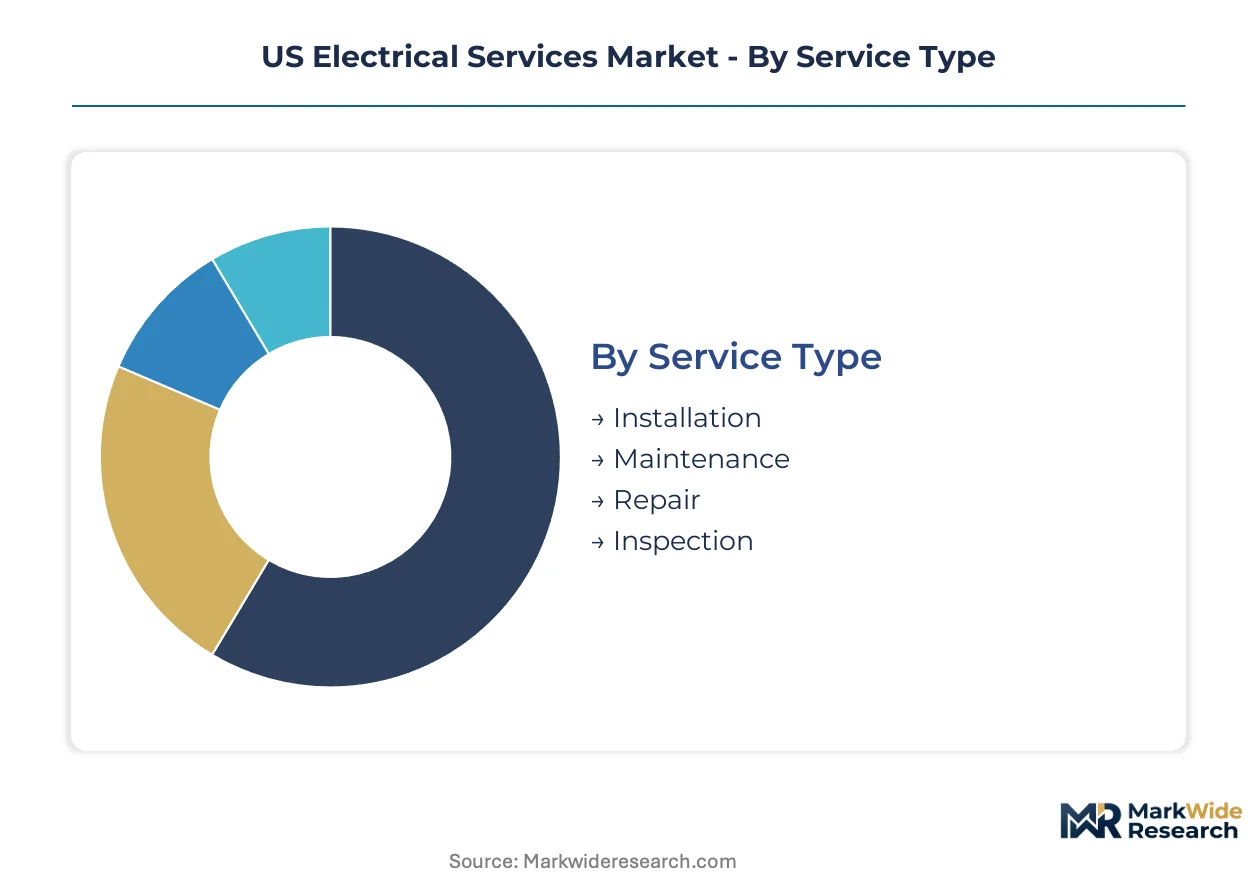
Electrical services contractors configure workforce capabilities and equipment portfolios around distinct demand profiles. Service mix, customer vertical, power source, and technology application each dictate divergent margin structures and capital intensity requirements.
Service Type:
Buyers differentiate primarily by project lifecycle phase and contractual risk allocation.
- Installation:Greenfield construction of switchgear, transformers, and distribution infrastructure from 120V premises wiring through 345kV transmission interconnections. Demand concentrates across Northern Virginia data center corridors and Texas ERCOT solar zones, where hyperscale facilities and utility-scale renewable developers are pulling high-voltage contractors into fixed-price EPC arrangements.
- Maintenance:Lifecycle service contracts covering protective relaying calibration, arc-flash boundary verification, and thermal imaging diagnostics. Smart grid and energy storage asset owners in California and Arizona are expanding recurring revenue pools for firms with substation SCADA integration capabilities.
- Repair:Emergency restoration and fault isolation services following storm damage or equipment failure. Hurricane exposure across Gulf Coast states and winter storm vulnerability in Texas are elevating demand for 24/7 mobilization capabilities.
- Inspection:Code compliance verification and energized work permitting documentation. OSHA's updated arc-flash protection standards are tightening documentation requirements and extending inspection cycle durations across transmission and substation assets above 15kV.
Installation leads volumes today; maintenance is gaining share fastest.
End User:
Customer scale and regulatory exposure shape procurement sophistication and contract terms.
- Industrial:Heavy manufacturing, petrochemical, and semiconductor fabrication facilities requiring 480V through 34.5kV distribution with power quality guarantees. Texas Gulf Coast chemical complexes and Arizona chip fabrication plants are expanding demand for mission-critical uptime contracts with penalty clauses.
- Commercial:Office, retail, and hospitality properties focusing on LED retrofit and EV infrastructure upgrades. California Title 24 electrification mandates are channeling retrofit volume toward certified contractors capable of heat pump electrical integration.
- Residential:Single-family and multifamily premises wiring, panel upgrades, and rooftop solar interconnection. Distributed solar net-metering reforms in Nevada and Hawaii are compressing installation margins while elevating technical complexity for inverter synchronization.
- Government:Federal, state, and municipal infrastructure including military bases, correctional facilities, and transportation electrification. The Inflation Reduction Act's domestic content bonuses are restricting eligibility to union-trained labor pools and American-manufactured switchgear.
Industrial captures the highest contract values; commercial retrofits are expanding most quickly.
Power Source:
Generation technology determines voltage conversion requirements and interconnection complexity.
- Renewable:Utility-scale solar, wind, and battery storage requiring DC-to-AC conversion, collector system installation, and inverter synchronization. Texas ERCOT interconnection queues and California ISO backlogs are stretching project timelines and forcing working capital restructuring.
- Non-Renewable:Natural gas peaker plants and legacy coal infrastructure maintenance. PJM capacity market retirements are shifting maintenance demand toward decommissioning and environmental remediation electrical work.
- Hybrid:Co-located solar-plus-storage and wind-plus-battery configurations demanding integrated control systems and bidirectional power flow management. Developer preference for DC-coupled architectures is opening premium service tiers for power electronics-certified technicians.
- Backup:Diesel, natural gas, and battery uninterruptible power supply systems for data center and healthcare critical loads. Northern Virginia Loudoun County hyperscale clusters are specifying 10-minute ride-through capabilities and automated transfer switching.
Renewable dominates new construction flows; hybrid configurations are climbing the fastest.
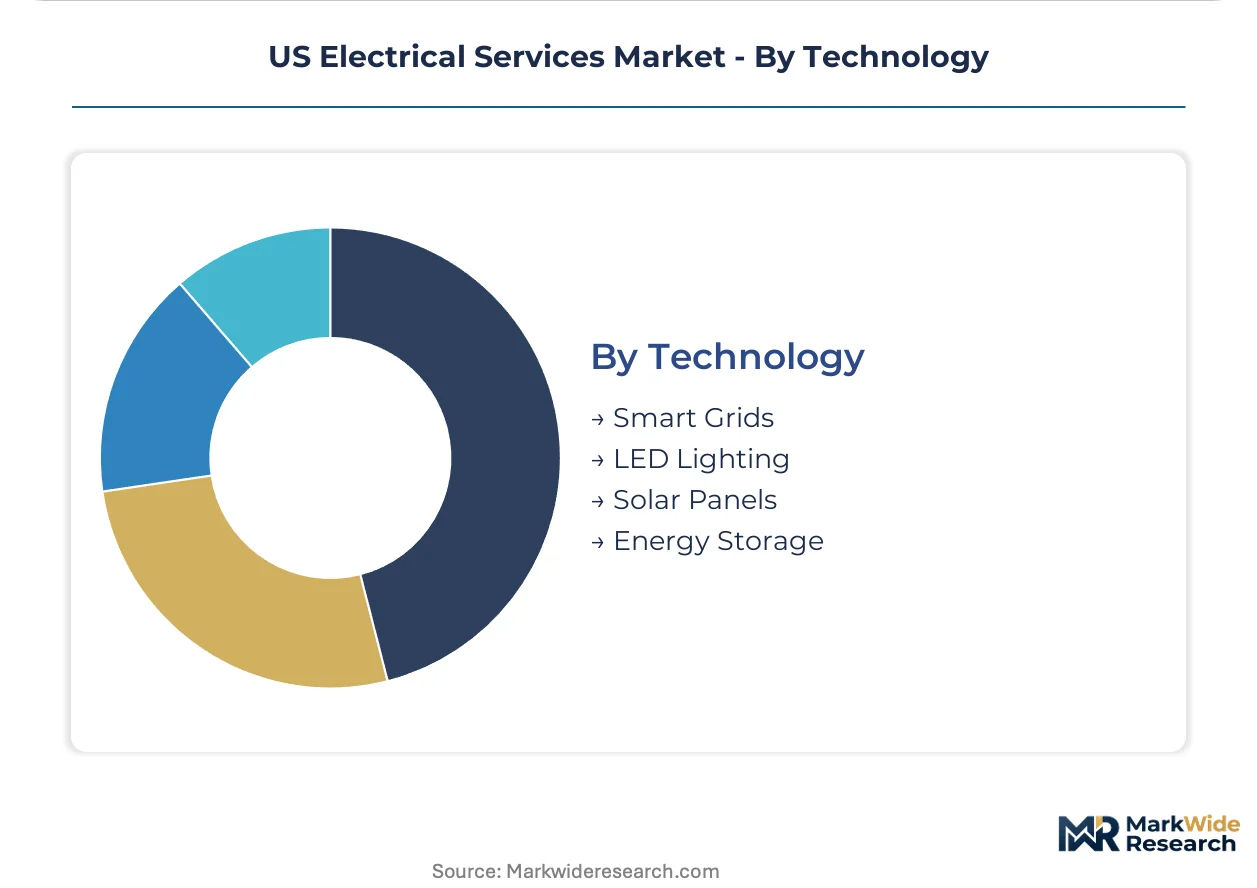
Technology:
Technology application determines technician certification requirements and equipment specialization.
- Smart Grids:Distribution automation, advanced metering infrastructure, and substation communication networks requiring SCADA integration and cybersecurity-hardened protocols. Investor-owned utilities in Illinois and Ohio are expanding AMI lifecycle replacement programs.
- Energy Storage:Battery energy storage system installation, DC-coupled inverter commissioning, and protective relaying configuration for grid-forming inverters. FERC Order 2222 aggregation rules are expanding behind-the-meter storage interconnection volume.
- Solar Panels:Photovoltaic module installation, string inverter configuration, and rapid shutdown compliance. Domestic content bonus requirements are filtering contractor eligibility toward union IBEW apprenticeship programs.
- LED Lighting:Retrofit lamp and fixture replacement with controls integration. Commercial building efficiency standards have matured this category into price-commoditized procurement with compressed margins.
Smart grids anchor utility spending today; energy storage is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is minimal in electrical services given localized licensing requirements, yet cost-of-compliance gaps between union and open-shop jurisdictions are redistributing project volume across state lines. The Inflation Reduction Act's domestic content bonuses are accelerating geographic concentration where IBEW apprenticeship density meets renewable interconnection queues.
Texas
ERCOT interconnection backlogs and utility-scale solar buildouts are stretching contractor capacity across West Texas and the Rio Grande Valley. OSHA's energized work standards filter market access for transmission voltage projects above 15kV. The Permian Basin and Dallas-Fort Worth corridor anchor the nation's fastest-expanding high-voltage contractor order books.
California
Title 24 electrification mandates and SB 100 renewable portfolio requirements are channeling retrofit demand toward certified contractors. The California Energy Commission's solar-specific licensing requirements compress non-compliant vendor participation. The Central Valley and Imperial Valley concentrate utility-scale solar construction, while Silicon Valley data centers pull specialized medium-voltage contractors into mission-critical uptime contracts.
Virginia
Hyperscale data center power density requirements in Loudoun County are demanding 345kV substation construction and specialized distribution infrastructure. FERC interconnection standards govern transmission-level project approvals. Northern Virginia's Data Center Alley represents the densest concentration of mission-critical electrical services procurement in the United States.
Arizona
Phoenix metro data center clusters and utility-scale solar zones are expanding addressable market for high-voltage contractors. State-level amendments to NECA standards impose additional workforce qualification requirements. The Salt River Valley and Greater Phoenix area concentrate both renewable interconnection and critical load infrastructure deployment.
Illinois
Smart grid modernization and advanced metering infrastructure replacement programs are generating recurring maintenance contract volume. PJM interconnection queue delays are compressing project cash conversion cycles for transmission contractors. The Chicago metropolitan area and central Illinois utility corridors anchor distribution automation and substation communication network deployment.
US Electrical Services Market Vendor Landscape
Texas-based contractors anchor one tier; Southwest specialists hold differentiated positions in high-voltage transmission. The market structures around three tiers: national-scale integrated providers, regional specialists with union labor access, and metropolitan-focused commercial contractors. Strategic archetypes include transmission infrastructure deployers, renewable interconnection specialists, and data center mission-critical contractors. M&A activity concentrates on union-trained workforce acquisition, while capacity expansion targets ERCOT and CAISO interconnection zones.
Within the integrated infrastructure tier, Quanta Services and MasTec exemplify scale-driven positioning across transmission and renewable segments. MYR Group occupies a specialized position in substation and switchyard work, reflecting the premium-tier archetype for complex interconnection projects. EMCOR represents diversified facility services integration, spanning commercial electrical through industrial maintenance contracts.
| Leading Market Players |
|---|
| EMCOR |
| MasTec |
| Quanta Services |
| Cleveland Electric |
| MDU Resources Group |
| MYR Group |
| IES Holdings |
| Five Star Electric |
| Rosendin Electric |
| Others |
Supply Flow & Price Mechanics
IBEW apprenticeship density across Texas and Arizona establishes the first pricing-tier spread, with union-trained journeyman rates commanding 15-25% premiums over open-shop equivalents while delivering IRA domestic content compliance that unlocks federal bonus eligibility.
Pricing Analysis
Distributor markups on medium-voltage switchgear and transformer assemblies compress as direct OEM relationships deepen among tier-one contractors. Project-based fixed-price contracts dominate transmission and data center segments, with price differentiation driven by arc-flash certification tier and union labor compliance status. Cost compression in LED retrofit services is intensifying because price-commoditized procurement has eliminated technical differentiation. Commercial building owners exhibit highest price sensitivity, while hyperscale data center operators prioritize uptime guarantees over unit cost.
Supply Chain Analysis
OSHA energized work certification and state-level solar-specific licensing filter vendor participation, constraining qualified labor supply. Domestic transformer manufacturing concentrates in Wisconsin, Pennsylvania, and Texas, while copper conductor and aluminum busbar feedstock draws from Chilean mining operations and domestic smelters. Single-source vulnerability runs through medium-voltage transformer OEMs with 18-month lead times. Distribution runs through direct equipment manufacturer allocation agreements and electrical distributor networks serving metropolitan contractor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Electrical Services Market reads as a late-cycle quality story, with IRA domestic content bonuses and OSHA arc-flash standards filtering demand toward premium-certified contractors capable of 345kV transmission and mission-critical data center uptime specifications.
For Market Incumbents: Anchor transmission infrastructure positions through captive IBEW apprenticeship pipeline investments in ERCOT and PJM interconnection zones. Deepen vertical integration into American-manufactured switchgear allocation agreements to defend against lead-time compression. Prioritize SCADA integration capabilities to capture smart grid maintenance contract renewals.
For New Entrants and Emerging Players: Power electronics certification programs for DC-coupled battery commissioning offer a technology-first wedge into the fastest-expanding margin segment. Target California Title 24 electrification retrofits and Arizona utility-scale solar zones where certification barriers filter incumbent density. Pursue direct relationships with renewable developers seeking inverter synchronization specialists outside union-dominant corridors.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with union labor access and substation switching credentials. Long-term viability hinges on exposure to interconnection queue velocity and data center power density trends. The signal to watch is FERC rulemaking on transmission permitting reform as inflection indicator for contractor working capital cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| IBEW Apprenticeship Pipeline Investment | Secures IRA-compliant labor pools for renewable interconnection projects across ERCOT and CAISO zones. |
| Direct OEM Switchgear Allocation Agreement | Bypasses distributor markups and secures transformer priority amid 18-month domestic lead times. |
| Power Electronics Certification Program | Opens DC-coupled battery commissioning revenue as solar-plus-storage deployments accelerate. |
| SCADA Integration Capability Buildout | Captures recurring smart grid maintenance contracts from investor-owned utilities in Illinois and Ohio. |
| Geographic Expansion into Phoenix Data Center Corridor | Positions for hyperscale 345kV substation demand from Microsoft, Amazon Web Services, and Google clusters. |
Methodological Framework
Coverage spans Texas, California, Virginia, Arizona, and Illinois, with primary inputs from each state's contractor licensing boards and IBEW training coordinators. The approach combines primary interviews with utility procurement officers, EPC project managers, renewable developer interconnection leads, and electrical distributor sales directors with secondary validation against FERC interconnection queue databases, EIA generation capacity reports, OSHA enforcement records, and NECA apprenticeship completion statistics. Bottom-up project pipeline aggregation and top-down utility capital expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates installation from maintenance revenue trajectories across the projection horizon. Segmentation dimensions modeled include service type, end-user vertical, power source technology, and voltage tier classification. CAGRs derive from utility-scale solar and battery storage interconnection forecasts, data center power density specifications, and electrification retrofit mandate compliance timelines. Transformer lead-time elasticities and copper price volatility scenarios inform margin compression assumptions.
The model holds under sustained IRA domestic content bonus enforcement and OSHA arc-flash rulemaking implementation; deviation in FERC transmission permitting reform or NECA certification timeline acceleration would shift contractor capacity utilization assumptions. A model refresh is warranted upon material change in regional transmission organization interconnection queue clearance rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
Pressure Pumping Services Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Rotary Machinery Market