
 MEP Services in US Market | 2026-2036
MEP Services in US Market Size, Share, and Industry Trends Forecast 2026-2036
MEP Services in US Market Insights
Data center operators are unwinding traditional procurement patterns as hyperscale buyers gain share over conventional commercial developers. AECOM Technology Corporation leverages its integrated design-build platform to capture complex mission-critical infrastructure. Jacobs Engineering Group Inc. anchors its position through deep vertical expertise in advanced manufacturing and life sciences facilities. Burns & McDonnell competes by sustaining self-perform capabilities across electrical transmission and power distribution.
MEP Services in US encompasses the engineering, installation, and maintenance of building systems including HVAC with minimum efficiency ratings, electrical distribution up to medium-voltage infrastructure, plumbing with low-flow fixture mandates, and fire protection with NFPA 13 compliance. The service type dimension shows HVAC and electrical commanding the largest share of contract value due to equipment intensity and code complexity. Application patterns reveal renovation and maintenance outpacing new construction in mature urban corridors where building stock ages and energy codes tighten. Technology adoption clusters around BIM and building automation, where margin pools deepen for firms that integrate digital twins with real-time commissioning.
OSHA standards govern worker safety across installation sites, while the EPA regulates refrigerant transitions under AIM Act phasedowns that reshape HVAC specifications. The Department of Energy enforces appliance efficiency standards that filter directly into equipment selection and system design. Stakeholders must monitor how state-level stretch codes in California and New York diverge from federal baselines, forcing service providers to maintain multi-jurisdictional compliance capabilities or surrender geographic coverage.
Market Dynamics
The Inflation Reduction Act is compressing project timelines as developers race to capture tax credits before qualification windows narrow, forcing MEP contractors to accelerate design-build cycles while maintaining code compliance across diverging state stretch codes.
Growth Catalysts
- Data center power density:Hyperscale operators are procuring integrated medium-voltage electrical and liquid cooling systems as rack densities exceed 50kW, pulling specialized MEP contractors into mission-critical infrastructure pipelines.
- IRA efficiency retrofits:Commercial building owners are triggering renovation waves to capture Section 179D deductions, expanding contract volumes for HVAC replacement and building automation upgrades in aging urban stock.
- Texas development corridor:Austin and Dallas-Fort Worth are anchoring a concentrated pipeline of institutional and commercial ground-up construction, concentrating demand for full-service MEP design-build capacity.
Market Restraints
- Copper and aluminum volatility:Electrical contractors face margin compression from commodity price swings in conductor materials, complicating fixed-bid pricing on large-scale distribution projects.
- Refrigerant supply concentration:The AIM Act phasedown is constraining availability of legacy HFCs while low-GWP alternatives remain supply-constrained from limited domestic manufacturing capacity.
- Specialized labor scarcity:Journeyman electricians and certified pipefitters are exiting the workforce faster than apprenticeship programs replenish them, extending project timelines in tight labor markets.
Strategic Opportunities
- Building automation convergence:Integration of digital twin platforms with real-time commissioning systems is creating new service revenue streams for firms that master IoT sensor deployment and predictive maintenance algorithms.
- Federal electrification mandates:The Department of Energy's appliance efficiency standards are accelerating heat pump adoption in commercial retrofits, opening specialized contracting niches for thermal system redesign.
- Life sciences facility expansion:Advanced manufacturing and pharmaceutical cleanroom construction is demanding precision environmental controls, rewarding MEP providers with vertical expertise in cGMP compliance and contamination control.
Industry Challenges
- BIM-to-field coordination gaps:Design intent frequently diverges from as-built conditions during complex system integration, requiring costly rework when clash detection fails to capture real-world constructability constraints.
- Multi-jurisdictional code navigation:Contractors operating across state lines must maintain compliance capabilities for California Title 24, New York Local Law 97, and federal baseline ASHRAE standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEP Services in US Market |
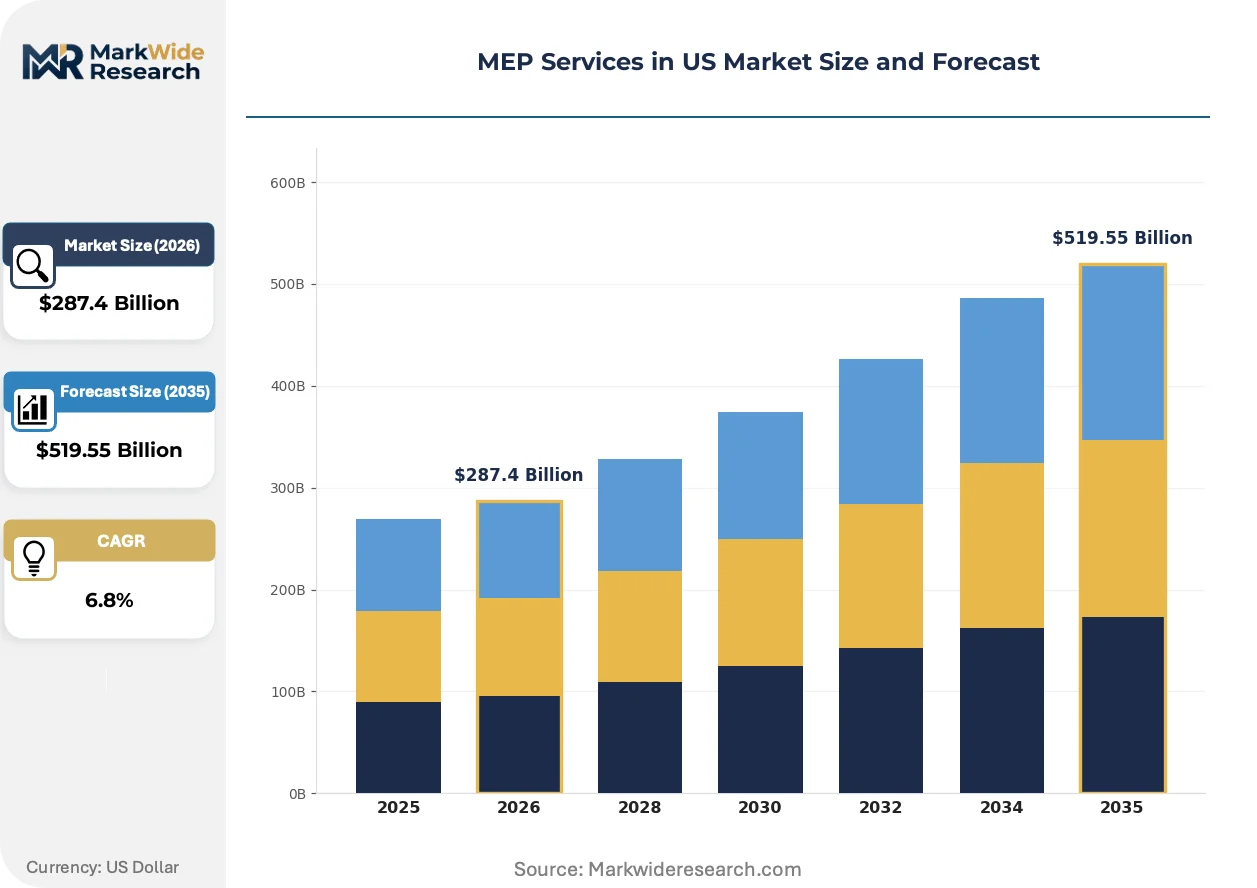
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $519.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: HVAC, Plumbing, Electrical, Fire Protection End User: Commercial Buildings, Industrial Facilities, Residential Homes, Institutional Structures Application: New Construction, Renovation, Maintenance, Design-Build Technology: BIM, Energy Management Systems, Building Automation, Prefabrication |
| Companies Covered | AECOM Technology Corporation, Tetra Tech, Jacobs Engineering Group Inc., Affiliated Engineers, Inc., Burns & McDonnell, WSP USA, Arup Group, EXP, HDR Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEP Services in US Market Trends and Innovations
Digital fabrication and modular system delivery are compressing on-site labor requirements while raising precision expectations. Three developments are restructuring how mechanical, electrical, and plumbing systems are engineered, procured, and commissioned.
Prefabricated electrical skids and modular plant rooms are displacing traditional stick-built installation methods in data center and healthcare construction. Turner Construction and DPR Engineering are specifying factory-assembled medium-voltage switchgear and packaged chiller plants to reduce on-site trade stacking and accelerate commissioning schedules. This shift is compressing field labor hours while demanding upfront coordination between design teams and fabrication facilities.
The EPA's AIM Act refrigerant phasedown is mandating transition to A2L and natural refrigerant alternatives across commercial HVAC specifications. Equipment manufacturers are reengineering compressor architectures and safety systems to accommodate mildly flammable chemistries, while service contractors must recertify technician credentials for handling and charging protocols. The impact concentrates in supermarket refrigeration and large-tonnage chiller replacements where system charge volumes trigger heightened regulatory scrutiny.
Performance-based service agreements are supplanting time-and-materials maintenance contracts in institutional client portfolios. Healthcare systems and university campuses are contracting for guaranteed energy savings and uptime availability, transferring operational risk to MEP providers who must instrument buildings for continuous monitoring. This restructuring is most visible in the Northeast and California where energy cost volatility and carbon reporting mandates sharpen financial accountability for building system performance.
MEP Services in US Market Segmentation
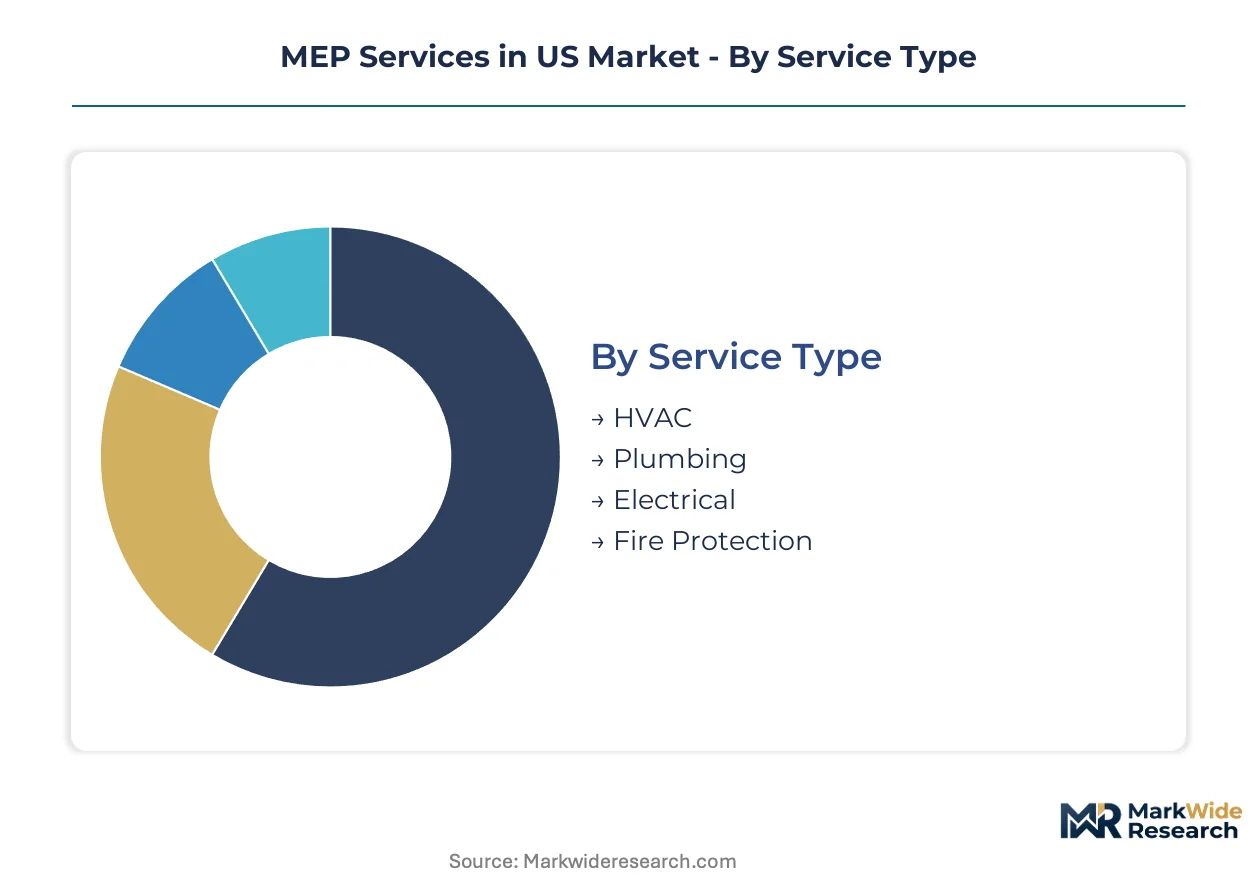
Service specialization determines margin capture in MEP contracting, where equipment intensity and code complexity create divergent profitability profiles across mechanical, electrical, and plumbing disciplines. Understanding segment boundaries reveals where capital deployment concentrates and which technology integrations reshape competitive positioning.
Service Type:
Margin pools deepen fastest where equipment specifications intersect with federal efficiency mandates and refrigerant transition timelines.
- HVAC:Systems span rooftop units to district-scale chillers with efficiency ratings governed by Department of Energy appliance standards. Demand concentrates in Texas commercial corridors and Northeast retrofit markets where IRA Section 179D deductions accelerate replacement cycles amid AIM Act refrigerant phasedowns.
- Electrical:Distribution infrastructure ranges from low-voltage branch circuits to medium-voltage switchgear serving data center loads above 50kW per rack. Procurement is concentrating among hyperscale operators in Northern Virginia and Dallas-Fort Worth who specify integrated medium-voltage and liquid cooling packages.
- Plumbing:Potable water, sanitary drainage, and stormwater systems incorporate low-flow fixture mandates under EPA WaterSense specifications.
- Fire Protection:NFPA 13-compliant sprinkler and suppression systems serve high-occupancy institutional and high-value industrial assets.
HVAC holds installed capacity. Electrical is rotating up the share rankings.
End User:
Customer archetypes segment by capital cycle timing, with institutional and industrial clients favoring performance contracts over transactional procurement.
- Commercial Buildings:Office, retail, and hospitality assets drive renovation demand in aging urban cores where Local Law 97 in New York and California Title 24 stretch codes trigger compliance-driven system replacements.
- Industrial Facilities:Advanced manufacturing and pharmaceutical cleanrooms demand precision environmental controls with cGMP documentation. Texas and Southeast corridors anchor ground-up construction pipelines for semiconductor and battery manufacturing campuses.
- Residential Homes:Single-family and multifamily construction follows interest rate sensitivity and regional migration patterns into Sun Belt markets.
- Institutional Structures:Healthcare systems and university campuses contract for guaranteed energy savings and uptime availability under performance-based service agreements.
Commercial Buildings dominate contract volume. Industrial Facilities is climbing the fastest.
Application:
Project delivery methods restructure risk allocation between owners and contractors, with integrated design-build capturing complex mission-critical infrastructure.
- New Construction:Ground-up development concentrates in Texas urban corridors and Southeast manufacturing hubs where institutional and commercial pipelines remain active.
- Renovation:System replacements in mature building stock accelerate under IRA tax credit windows, with HVAC and building automation upgrades outpacing new construction in Northeast and California markets.
- Maintenance:Time-and-materials contracts are supplanting with performance-based agreements that transfer operational risk to service providers.
- Design-Build:Single-source accountability compresses timelines for data center and life sciences facilities where commissioning precision governs operational readiness.
Renovation holds installed capacity. Design-Build is rotating up the share rankings.
Technology:
Digital adoption clusters around platforms that compress field labor requirements while raising precision expectations for system integration and commissioning.
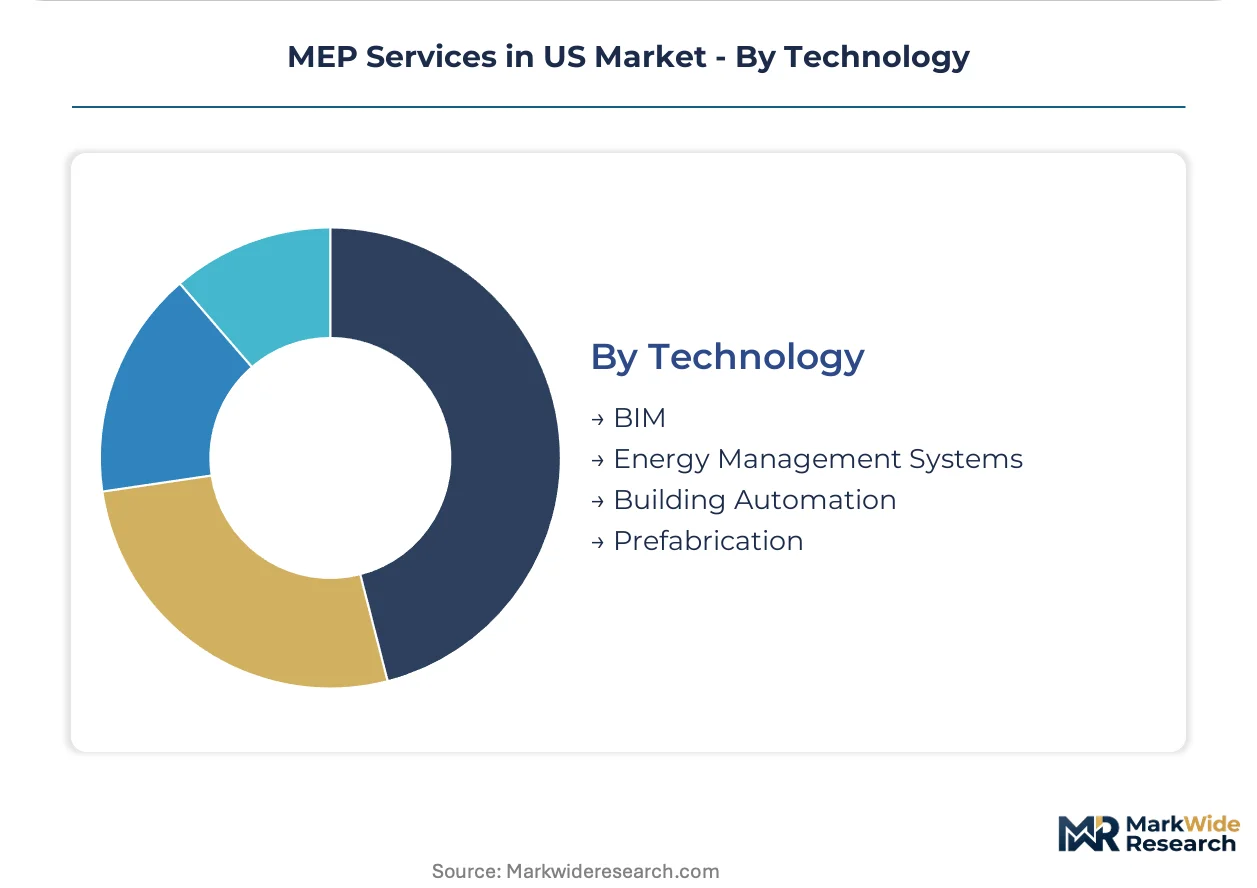
- BIM:Building Information Modeling enables clash detection and fabrication-ready detailing, though BIM-to-field coordination gaps still generate costly rework when constructability constraints escape digital detection.
- Energy Management Systems:Continuous monitoring platforms instrument buildings for predictive maintenance and guaranteed savings contracts in institutional portfolios.
- Building Automation:Integration of digital twins with real-time commissioning creates new service revenue streams for firms mastering IoT sensor deployment.
- Prefabrication:Factory-assembled electrical skids and modular plant rooms displace stick-built methods in data center and healthcare construction, reducing on-site trade stacking.
Building Automation holds installed capacity. Prefabrication is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US MEP services concentrate in trade-flow corridors linking domestic engineering capacity to hyperscale data center demand in Northern Virginia and Dallas-Fort Worth, with equipment and specialized labor moving from established industrial bases to high-growth construction zones.
Texas
Hyperscale data center construction and advanced manufacturing campuses are driving procurement of integrated medium-voltage electrical and liquid cooling systems. Texas state energy codes and utility incentive programs accelerate efficiency-driven retrofits in commercial building stock. Austin and Dallas-Fort Worth anchor concentrated pipelines of institutional and ground-up commercial projects, pulling MEP design-build capacity from national contractors.
California
Title 24 stretch codes and Local Law 97-style carbon mandates are triggering HVAC replacement waves in aging urban cores. The California Energy Commission enforces appliance efficiency standards that filter directly into equipment selection and thermal system redesign. Los Angeles and San Francisco Bay Area markets concentrate renovation demand for building automation upgrades and heat pump conversions under IRA Section 179D windows.
New York
Local Law 97 compliance deadlines are compressing project timelines for commercial building owners racing to avoid carbon penalties. The New York State Energy Research and Development Authority channels funding toward electrification retrofits and district-scale thermal networks. New York City anchors the largest concentration of renovation contract volume for HVAC replacement and controls integration in the Northeast corridor.
Northern Virginia
Hyperscale data center operators are procuring integrated electrical and mechanical packages as rack densities exceed 50kW, pulling specialized contractors into mission-critical infrastructure pipelines. Virginia state permitting frameworks accommodate accelerated commissioning schedules for digital infrastructure. Loudoun County and Prince William County concentrate the highest density of data center power distribution projects in the US market.
Florida
Institutional healthcare expansion and hurricane-resilient infrastructure standards are driving demand for precision environmental controls and emergency power systems. Florida building codes mandate enhanced wind-load and flood-resistance specifications for MEP systems in critical facilities. Miami and Orlando anchor commercial and healthcare construction pipelines where performance-based service agreements are supplanting traditional maintenance contracts.
MEP Services in US Market Competitive Landscape
Player mix skews toward diversified engineering conglomerates with self-perform electrical capabilities, creating a tiered structure where national-scale design-build platforms compete against specialized regional contractors. The market fragments across service archetypes: integrated full-service providers, electrical transmission specialists, and vertical-specific life sciences experts. Consolidation pressure intensifies as hyperscale clients demand single-source accountability for mission-critical infrastructure. Competitive moves center on design-build platform expansion and prefabrication capability investments that compress field labor requirements.
Within the integrated full-service tier, AECOM Technology Corporation and Jacobs Engineering Group Inc. represent archetypes of scale-driven engineering platforms with national coverage. Burns & McDonnell occupies a position among self-perform specialists with captive electrical transmission and power distribution capabilities. Tetra Tech exemplifies the diversified infrastructure consulting model with exposure to federal and institutional client portfolios. These anchors reflect the market's segmentation between conglomerates pursuing vertical integration through design-build consolidation and specialists defending position through trade-specific depth.
| Leading Market Players |
|---|
| AECOM Technology Corporation |
| Tetra Tech |
| Jacobs Engineering Group Inc. |
| Affiliated Engineers, Inc. |
| Burns & McDonnell |
| WSP USA |
| Arup Group |
| EXP |
| HDR Inc. |
| Others |
Pricing and Supply Chain Analysis
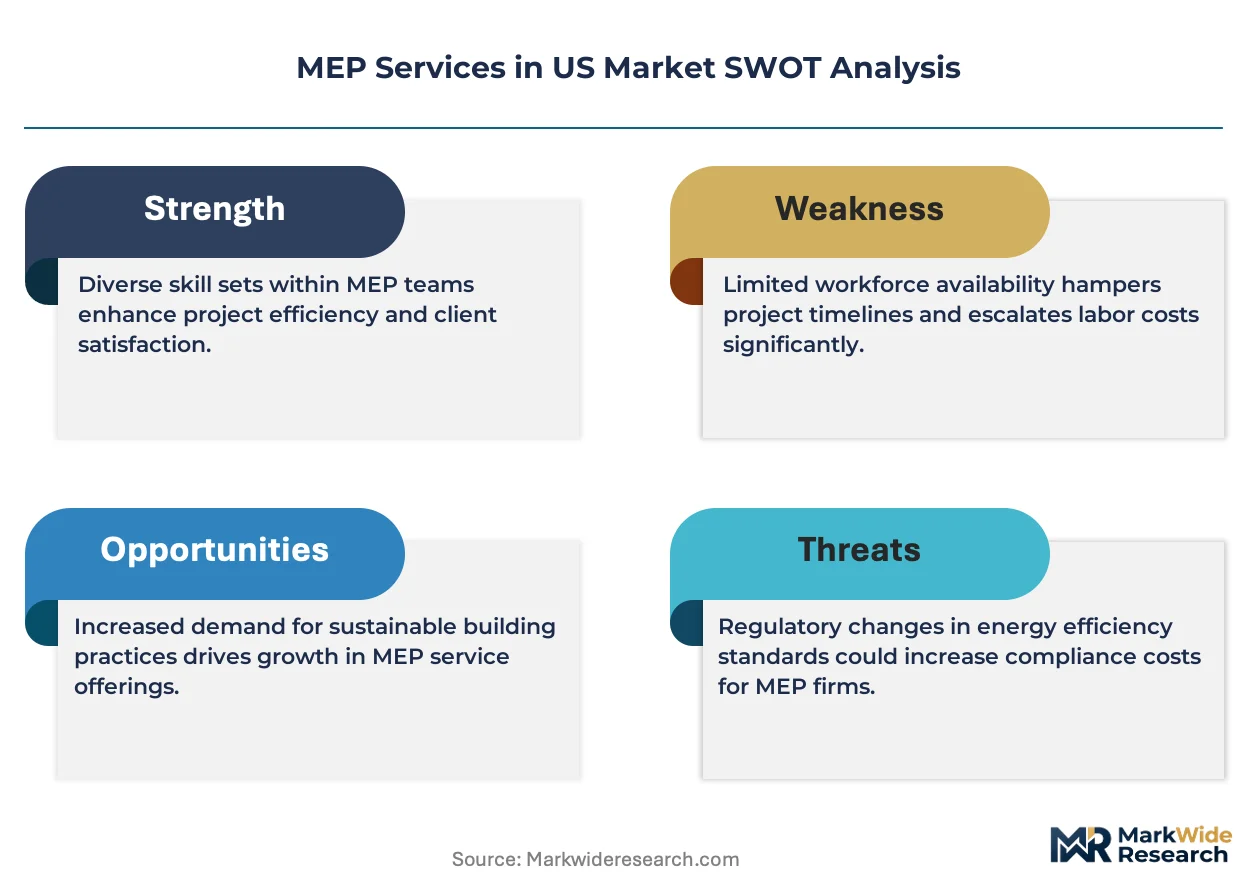
Project-based fixed-bid contracting locks MEP contractors into price visibility across multi-year timelines while copper and aluminum futures volatility erodes margin predictability on electrical distribution awards. This structure concentrates pricing power with hyperscale data center developers who bundle medium-voltage and liquid cooling procurement, forcing trade contractors to absorb commodity risk or surrender market access.
Pricing Analysis
Next-generation A2L refrigerant systems command 15-25% premiums over legacy HFC equipment while prior-generation R-410A installations face accelerated depreciation from EPA AIM Act phasedown timelines. Project-based fixed-bid structures dominate commercial and institutional awards, with price differentiation driven by cGMP certification tier for life sciences work and self-perform electrical capability for data center missions. Cost compression in standard commercial HVAC retrofits is intensifying because IRA Section 179D qualification windows compress bidding cycles. Small regional contractors exhibit highest price sensitivity due to limited balance sheet capacity for commodity hedging, while integrated design-build platforms absorb volatility through diversified portfolio exposure.
Supply Chain Analysis
Strategic stockpiling of copper conductor and medium-voltage switchgear components is displacing just-in-time preferences as lead time volatility from domestic electrical equipment manufacturers extends project schedules. Manufacturing concentration rests on Mexico and Canada for HVAC equipment assemblies, China for A2L compressor architectures and IoT sensor components, and domestic fabrication facilities for NFPA-compliant fire suppression systems. Single-source vulnerability concentrates in low-GWP refrigerant supply from limited domestic chemical production capacity. Distribution runs through manufacturer-direct channels for hyperscale data center projects and regional distributor networks for commercial renovation work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Journeyman electrician and certified pipefitter shortages are constraining project execution capacity faster than apprenticeship pipelines replenish, creating acute bottlenecks for contractors pursuing data center and advanced manufacturing awards.
For Market Incumbents: Secure captive electrical transmission capabilities through acquisition of regional self-perform specialists, insulating margin exposure from subcontractor pricing volatility. Defend design-build platform positioning by embedding BIM-to-fabrication workflows that compress field labor requirements and reduce rework exposure from clash detection failures. Reinforce Texas and Northern Virginia market presence through localized prefabrication facility investment, countering emerging regional competitors. For New Entrants and Emerging Players: Building automation integration services represent the most penetrable white-space where incumbent MEP contractors under-serve institutional client demand for guaranteed energy savings contracts. Target healthcare systems and university campuses in the Northeast corridor where performance-based agreements supplant time-and-materials maintenance. Pursue OEM partnership routes with A2L refrigerant equipment manufacturers to capture recertification training revenue streams. For Investors and Strategic Acquirers: Regional design-build platforms with vertical expertise in cGMP life sciences compliance represent the most attractive acquisition archetype for long-term viability across the 5-10 year pharmaceutical manufacturing expansion cycle. Monitor EPA refrigerant phasedown enforcement intensity as the critical inflection signal for HVAC contractor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Capability Investment | Factory-assembled electrical skids reduce on-site trade stacking for Turner Construction and DPR Engineering data center projects. |
| A2L Refrigerant Certification Program | Technician recredentialing opens service revenue streams amid EPA AIM Act compliance mandates. |
| Performance-Based Service Agreement | Guaranteed energy savings contracts transfer operational risk from healthcare systems to MEP providers. |
| Vertical Integration into Medium-Voltage | Self-perform electrical transmission capabilities defend margin position against copper price volatility. |
| Geographic Expansion into Texas Corridor | Austin and Dallas-Fort Worth institutional pipelines concentrate demand for full-service design-build capacity. |
Research Methodology
Initial hypotheses were tested against primary input from MEP contractor project directors, data center developer procurement leads, state energy code enforcement officials, and HVAC equipment manufacturer sales engineers and refined through secondary validation. Trade association filings from the National Electrical Contractors Association and Mechanical Contractors Association of America, EPA refrigerant transition enforcement records, Department of Energy appliance efficiency rulemaking dockets, and state-level stretch code adoption timelines anchored quantitative baselines. Bottom-up project pipeline aggregation across Texas, California, New York, and Northern Virginia construction permits was triangulated against top-down market sizing from federal infrastructure spending disclosures.
Variance-decomposition across service type, end user, application method, and technology adoption dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling that weighted IRA tax credit qualification windows, data center power density trajectories, and refrigerant supply transition timelines. Equipment intensity coefficients for HVAC and electrical systems, labor productivity assumptions from Bureau of Labor Statistics construction employment data, and regional code divergence indices informed scenario boundaries.
Underlying assumptions cover IRA Section 179D deduction continuity, A2L refrigerant supply scaling, and journeyman trade labor replenishment rates, with deviation risk concentrated in commodity price volatility and multi-jurisdictional code enforcement intensity. Revision becomes warranted when federal efficiency standard acceleration or state stretch code divergence crosses implementation thresholds that reshape contractor compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Pressure Pumping Services Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market