
 Spur Gear Market | 2026-2036
Spur Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Spur Gear Market Analytics
Aftermarket refurbishment and reconditioning of industrial gearboxes is reshaping margin distribution across the value chain. KHK Gears leverages its standardized catalog system to dominate replacement part procurement in Asia-Pacific automation lines. Boston Gear anchors North American distribution through extensive stock-and-ship networks serving MRO buyers. Shuanghuan Transmission extends its position via captive forging and heat-treatment capacity for wind turbine gearboxes.
A spur gear is a cylindrical toothed wheel with straight teeth parallel to the axis of rotation, typically manufactured through hobbing, shaping, or powder metallurgy to achieve AGMA quality classes 5 through 12 for precise motion transmission between parallel shafts. Steel alloys dominate material selection for heavy-load industrial applications where case-hardening to 58-64 HRC extends fatigue life under cyclic bending stress. Parallel shaft configurations occupy the largest volume share across automotive transmissions and conveyor systems. Plastic spur gears represent the fastest-expanding material category in consumer electronics and medical device actuators where noise reduction and corrosion immunity outweigh load capacity constraints.
ISO 6336 governs load capacity calculations and surface durability ratings for metallic gears in international commerce, while AGMA 2001-D04 defines U.S. practice for pitting resistance and bending strength ratings that OEMs mandate in supplier qualifications. The U.S. EPA industrial emissions framework and EU Ecodesign regulations press manufacturers toward energy-efficient gearing ratios and reduced lubricant consumption in power transmission assemblies. Stakeholders must monitor how electrification of transport and industrial fleets alters torque-speed requirements and gear count per drivetrain.
Market Dynamics
Automotive electrification is compressing gear counts per drivetrain while elevating precision requirements, forcing suppliers to retool for quieter, high-torque powertrains that operate at speeds incompatible with legacy manufacturing tolerances.
Growth Catalysts
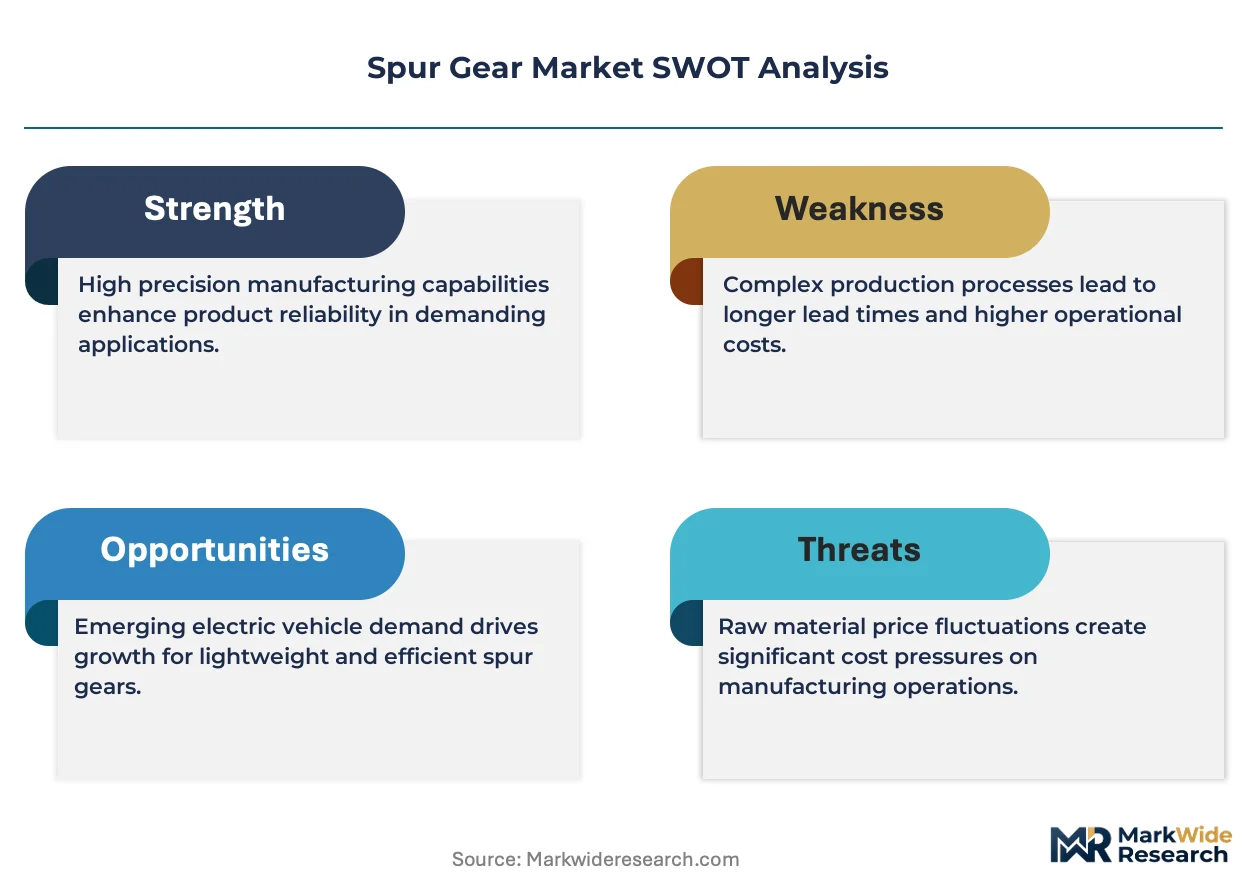
- ISO 6336 Load Standards:International harmonization of pitting resistance and bending strength ratings is reducing qualification friction for cross-border supply contracts, accelerating vendor onboarding for wind turbine OEMs.
- China's Dual Carbon Goals:Domestic wind energy installation mandates are pulling precision-forged gear demand through 2030, concentrating capacity expansion in Jiangsu and Zhejiang forging clusters.
- Powder Metallurgy:Near-net-shape processing is cutting material waste ratios below 5% for automotive accessory drives, enabling cost-competitive replacement of machined steel in volume applications.
Market Restraints
- Alloy Steel Price Volatility:Nickel and molybdenum input swings above 15% quarterly are compressing margin buffers for case-hardening specialists locked into annual supply agreements.
- German Capacity Concentration:Three precision-grinding equipment builders control 70% of global hob sharpening service capacity, creating single-point-of-failure risk for AGMA 10+ quality output.
- Direct-Drive Motor Substitution:Elimination of mechanical reduction stages in low-speed EV applications is eroding addressable unit volumes for single-stage spur configurations.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced automotive components are drawing heat-treatment investment toward Pune and Chennai manufacturing corridors.
- Additive Manufacturing Convergence:Hybrid workflows combining selective laser melting with CNC finishing are opening topology-optimized gear geometries previously impossible through conventional hobbing.
- EU Ecodesign Regulation:Mandatory energy efficiency labeling for industrial gearboxes is creating premium positioning for lubrication-optimized spur designs in European MRO procurement.
Industry Challenges
- Metrology Skill Scarcity:CMM programming for involute profile verification requires 18-24 month training pipelines that outpace retirement rates in Midwest US manufacturing hubs.
- AGMA 12 Certification Timelines:14-18 month qualification cycles for aerospace-grade surface finish specifications are delaying revenue recognition on new program wins.
- Legacy CNC Retrofit Complexity:Integrating Industry 4.0 sensor suites onto 1990s-era hobbing centers demands custom mechanical interfaces that fragment digital twin deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spur Gear Market |
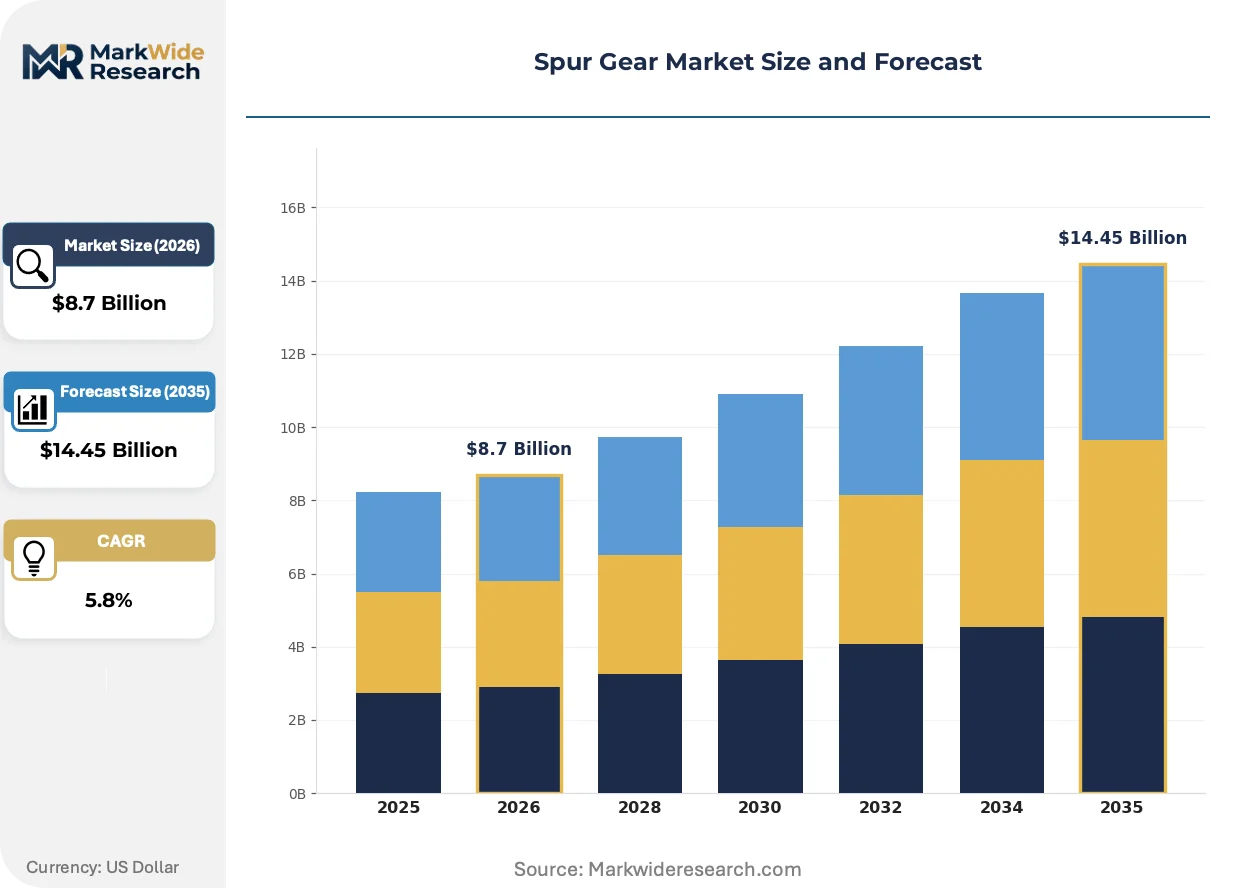
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Parallel Shaft, Helical, Crown, Rack Material: Steel, Aluminum, Plastic, Brass Application: Automotive, Industrial Machinery, Aerospace, Marine End User: Manufacturers, OEMs, Maintenance Providers, Aftermarket Suppliers |
| Companies Covered | KHK Gears, GRANGIN, CHUANQI GEARS, Boston Gear, Koro Industries, Shuanghuan Transmission, SEASHINE, ZOMAX, Parkash Industrial Gears, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spur Gear Market Evolving Landscape
Additive and hybrid manufacturing workflows are dissolving traditional boundaries between prototyping and production, while regulatory pressure on lubricant chemistry is accelerating dry-running material development.
High-performance polymer spur gears reinforced with carbon fiber and PEEK matrices are migrating from laboratory validation to production medical imaging equipment and food-grade conveyor systems. Siemens Healthineers and comparable OEMs now specify molded gearing for MRI gradient coil positioning where magnetic transparency is mandatory. This shift is compressing the addressable market for miniature steel pinions below 20mm diameter while expanding tooling demand for precision injection molds.
The EU F-Gas Regulation and REACH restrictions on perfluorinated lubricants are forcing reformulation of gearbox greases toward bio-based polyol esters with reduced temperature stability windows. Gear designers must now derate surface durability assumptions or specify hardened steel alternatives previously considered over-engineered. German wind turbine gearbox rebuilders report 23% increase in warranty claims traceable to lubricant incompatibility during the transition period.
Japanese automotive Tier-1 suppliers have consolidated MRO procurement through integrated e-commerce platforms that bypass traditional distributor markups. Denso and Aisin now require direct API integration for real-time inventory visibility, compressing order-to-delivery cycles from six weeks to 72 hours for standard catalog items. This disintermediation is most visible in Kansai and Chubu manufacturing belts where supplier consolidation has reduced active vendor counts by 40% since 2022.
Spur Gear Market Segmentation
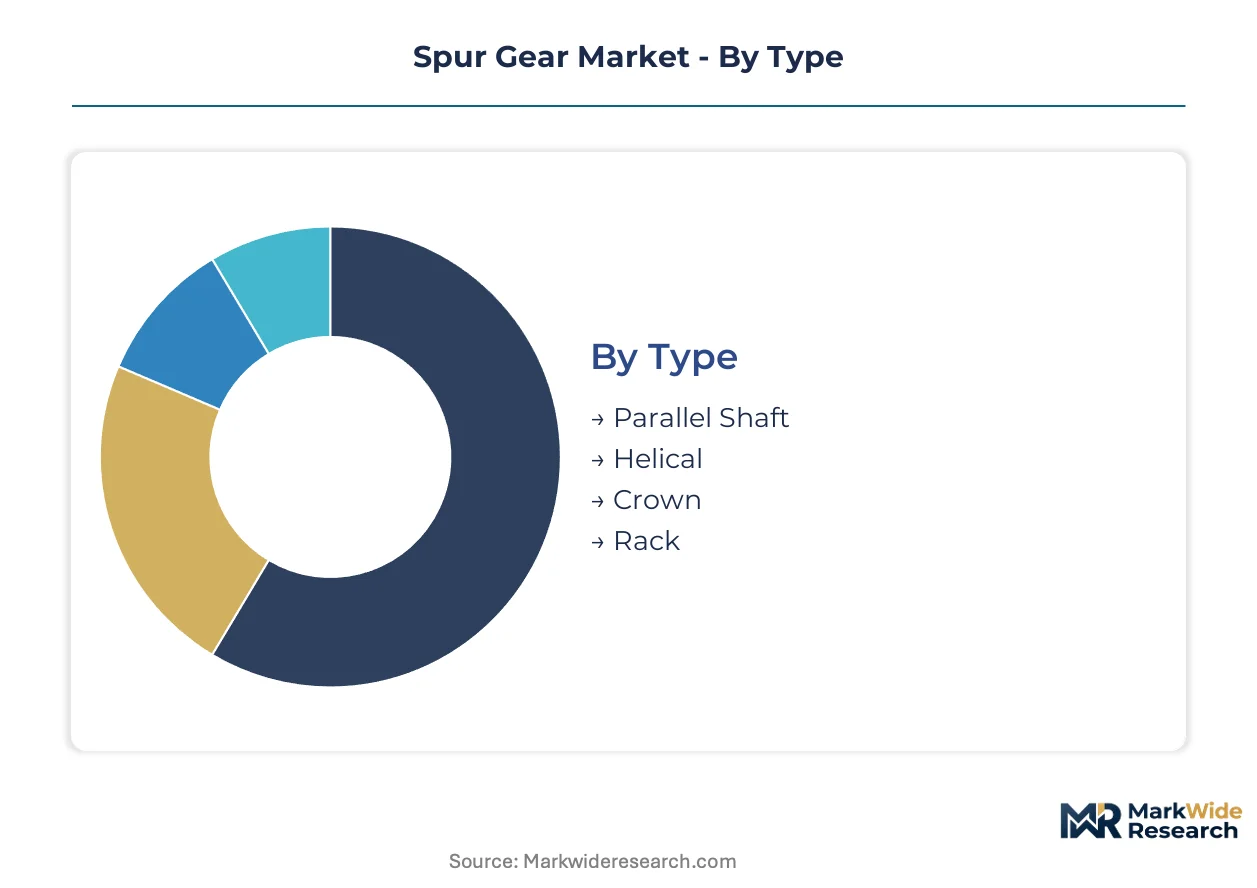
Spur gear procurement cycles vary dramatically by application intensity and material durability, with automotive powertrain components turning over in 3-5 year design cycles while industrial gearbox rebuilds extend to 15-20 year replacement horizons. Understanding these velocity differentials helps suppliers align inventory positioning and qualification investments with actual revenue recognition timing.
Type:
Parallel shaft configurations turn inventory fastest through automotive and conveyor OEM channels, while crown and rack variants linger longer in specialized industrial and infrastructure project pipelines.
- Parallel Shaft:Cylindrical wheels with teeth parallel to the rotation axis, manufactured to AGMA quality classes 5-12 through hobbing or shaping processes. Demand concentrates in automotive transmissions and bulk material handling systems across Germany, Japan, and Michigan manufacturing corridors, driven by electrification programs requiring quieter meshing at higher rotational speeds. Parallel shaft anchors the volume base while rack gains share at the steepest rate.
- Helical:Angled tooth profiles enabling gradual engagement and reduced noise signatures compared to straight-cut alternatives. Adoption is accelerating in precision medical imaging equipment and EV reduction gearboxes where NVH specifications from NHTSA and EPA noise standards mandate sub-40 dB operation.
- Crown:Bevel gear variants with perpendicular shaft orientation for right-angle power transmission. Demand localizes in mining equipment and marine propulsion systems requiring high-torque directional changes.
- Rack:Linear gear strips converting rotational to translational motion. Linear actuator integration in warehouse automation and CNC machine tool positioning drives procurement from Japanese and German precision motion suppliers.
Helical variants command margin premiums in precision applications, though parallel shaft maintains the broadest addressable market footprint across price-sensitive volume tiers.
Material:
Steel alloys dominate procurement value despite slower inventory velocity, while plastic and aluminum categories accelerate through consumer electronics and lightweighting mandates.
- Steel:Alloy and carbon steel grades case-hardened to 58-64 HRC for fatigue resistance under cyclic bending stress. Wind turbine gearbox rebuilders in Denmark and Spain specify through-hardened alternatives for main bearing integrations facing 20-year service intervals.
- Plastic:Reinforced polymers including carbon fiber-PEEK matrices for magnetic transparency and corrosion immunity. MRI equipment manufacturers at Siemens Healthineers and comparable OEMs now mandate molded gearing for gradient coil positioning where ferrous content disrupts imaging. Plastic climbs the fastest trajectory while steel retains the volume anchor position.
- Aluminum:Lightweight alloys for moderate-load applications where thermal conductivity outweighs wear resistance requirements. Aerospace actuation systems and satellite deployment mechanisms drive specification from ESA and NASA prime contractors.
- Brass:Corrosion-resistant alloys for marine environments and food-grade processing equipment. Saltwater exposure tolerance positions brass in offshore platform auxiliary drives and commercial fishing vessel winch systems.
Steel maintains foundational positioning in heavy-load industrial channels, though polymer substitution accelerates most quickly in medical and consumer electronics verticals.
Application:
Automotive program cycles compress to 24-36 months for electrification retooling, while aerospace qualification timelines extend qualification investments across decade-long development horizons.
- Automotive:Powertrain and transmission applications facing torque-speed requirement shifts from electrification. EV manufacturers in Shanghai, Stuttgart, and Detroit are reducing gear counts per drivetrain while elevating precision specifications for remaining reduction stages. Automotive represents the steepest expansion trajectory among application categories.
- Industrial Machinery:Conveyor systems, packaging equipment, and material handling drives with 10-15 year replacement cycles. German Mittelstand manufacturers anchor demand through captive maintenance divisions and MRO procurement consolidation.
- Aerospace:Flight control actuation and landing gear systems requiring AGMA 12 surface finishes and 14-18 month qualification cycles. FAA and EASA certification requirements delay revenue recognition despite premium pricing structures.
- Marine:Propulsion and auxiliary systems for commercial shipping and offshore platforms. Classification society rules from Lloyd's Register and DNV drive material specification toward corrosion-resistant alloys in North Sea and Gulf of Mexico operating environments.
Industrial machinery anchors procurement volume through aftermarket refurbishment cycles, while automotive electrification drives the fastest specification change velocity.
End User:
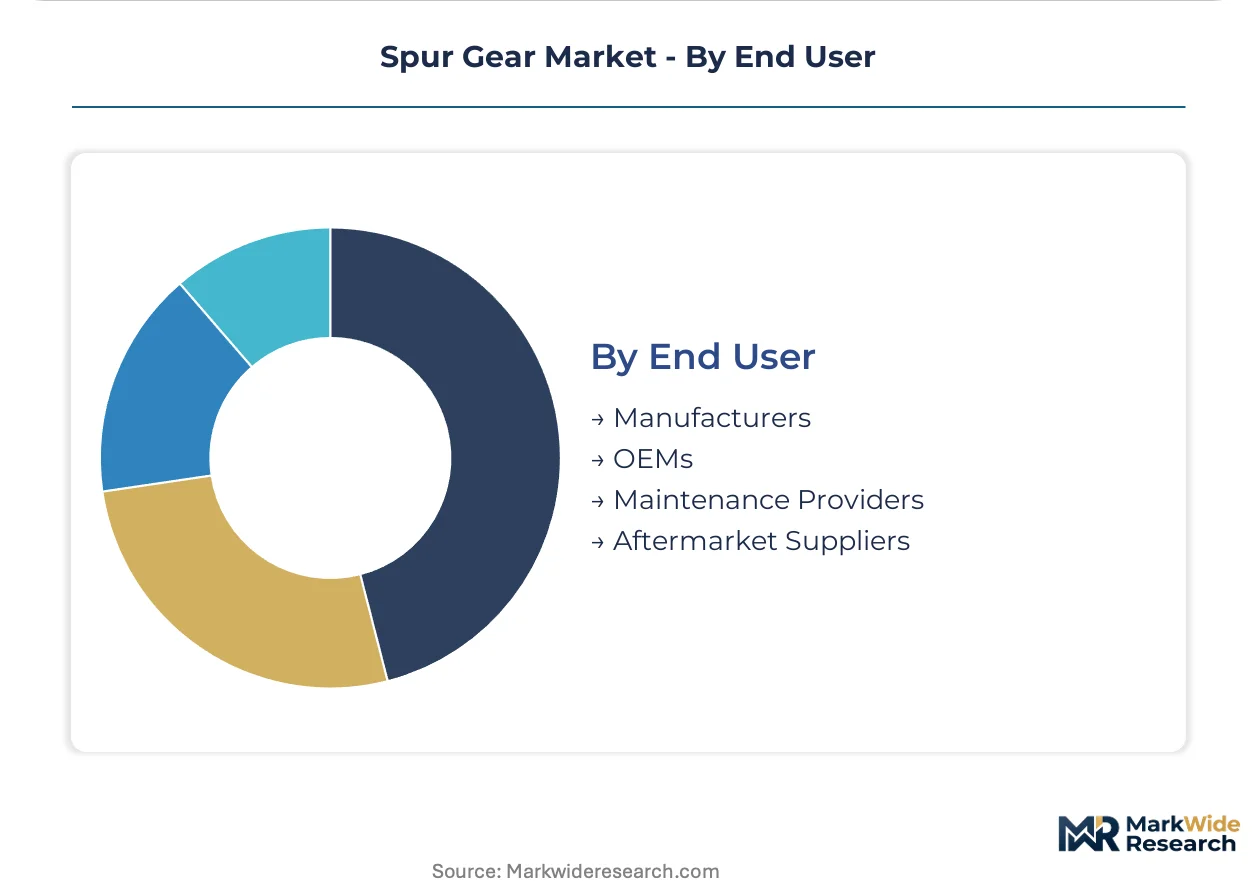
OEM procurement cycles align with new program launches and platform redesigns, while maintenance providers and aftermarket suppliers operate on breakdown-driven demand with compressed order-to-delivery requirements.
- Manufacturers:Captive gear production for integrated powertrain and transmission assembly. Chinese wind turbine OEMs in Jiangsu and Zhejiang provinces maintain in-house forging and heat-treatment capacity to control critical component supply.
- OEMs:Tier-1 and Tier-2 suppliers procuring precision gearing for subsystem integration. Japanese automotive suppliers Denso and Aisin have consolidated vendor bases through direct API-integrated procurement platforms, reducing active supplier counts by 40% in Kansai and Chubu manufacturing belts since 2022.
- Maintenance Providers:Industrial gearbox rebuilders and wind turbine service contractors. German gearbox rebuilders report elevated warranty claims during EU F-Gas Regulation lubricant transition periods, compressing margin buffers on fixed-price service contracts.
- Aftermarket Suppliers:Replacement part distributors serving MRO channels through stock-and-ship networks. Boston Gear's North American distribution infrastructure exemplifies the inventory positioning required for 72-hour order fulfillment against six-week traditional cycles.
OEMs concentrate procurement value through program consolidation, though maintenance providers are gaining commercial significance through circular economy refurbishment mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing AGMA 12 certification premiums for aerospace-grade specifications. Chinese procurement teams exhibit highest sensitivity, driving 40% cost compression on standard catalog items through consolidated vendor platforms.
China
Wind turbine OEMs in Jiangsu and Zhejiang provinces pull precision-forged gear demand through domestic installation mandates aligned with MIIT dual carbon targets. The country's national industrial regulator enforces GB standards tightening tolerance requirements for powertrain components. Ningbo and Suzhou forging clusters are expanding heat-treatment capacity to capture captive supply from Goldwind and Envision Energy.
Germany
Mittelstand gearbox rebuilders anchor aftermarket refurbishment demand through circular economy mandates under EU Ecodesign Regulation. ECHA REACH restrictions on perfluorinated lubricants are forcing grease reformulation with reduced temperature stability windows. Stuttgart and Munich precision grinding hubs control 70% of global hob sharpening service capacity for AGMA 10+ quality output.
United States
MRO buyers compress order-to-delivery cycles from six weeks to 72 hours through stock-and-ship networks serving Midwest manufacturing corridors. EPA industrial emissions frameworks press toward energy-efficient gearing ratios and reduced lubricant consumption. Michigan and Ohio automotive suppliers retool for quieter, high-torque EV powertrains incompatible with legacy manufacturing tolerances.
Japan
Tier-1 automotive suppliers consolidate procurement through API-integrated e-commerce platforms bypassing traditional distributor markups. METI industrial standards harmonize with ISO 6336 load capacity calculations for cross-border supply contracts. Kansai and Chubu manufacturing belts have reduced active vendor counts by 40% since 2022 through direct integration with Denso and Aisin.
India
Production-linked incentives under the PLI scheme draw heat-treatment investment toward Pune and Chennai automotive manufacturing corridors. BIS standards adoption accelerates vendor onboarding for wind turbine OEMs seeking qualification friction reduction. Gujarat and Maharashtra forging clusters are capturing overflow demand from European suppliers facing alloy steel price volatility above 15% quarterly.
Spur Gear Market Competitive Landscape
Capability concentration sits with precision-grinding specialists; scale advantage sits with catalog distributors maintaining continental stock-and-ship networks. The market structures around three tiers: aerospace-grade certified manufacturers, automotive volume producers, and aftermarket refurbishment specialists. Consolidation pressure intensifies as Japanese Tier-1 platforms disintermediate traditional distributors. Dominant competitive moves include backward integration into captive forging capacity and strategic partnerships for hybrid additive-CNC workflows.
Within the precision-catalog tier, KHK Gears and Boston Gear occupy positions exemplifying divergent geographic anchoring strategies. KHK Gears represents standardized catalog dominance across Asia-Pacific automation lines through extensive SKU coverage. Boston Gear exemplifies North American distribution infrastructure built for MRO compression of order cycles. Shuanghuan Transmission sits within the captive-capability archetype, extending position through in-house forging and heat-treatment control for wind turbine gearbox supply.
| Leading Market Players |
|---|
| KHK Gears |
| GRANGIN |
| CHUANQI GEARS |
| Boston Gear |
| Koro Industries |
| Shuanghuan Transmission |
| SEASHINE |
| ZOMAX |
| Parkash Industrial Gears |
| Others |
Value Network & Pricing Analysis
Undercapacity in German precision-grinding hubs is tightening AGMA 10+ quality availability while Chinese forging clusters absorb price pressure through volume scale. This utilization divergence splits supplier behavior between premium certification premiums and commodity cost compression.
Pricing Analysis
Aftermarket refurbishment contracts drive lifetime value through multi-year service agreements bundling inspection, reconditioning, and warranty coverage. Three-tier pricing structure across AGMA 12 aerospace-grade, AGMA 8-10 automotive-precision, and AGMA 5-7 industrial-standard levels anchors transaction frameworks. Cost compression in standard catalog tiers intensifies as Japanese Tier-1 platforms consolidate procurement through direct API integration. MRO buyers in North American manufacturing corridors exhibit lowest price elasticity for 72-hour fulfillment guarantees.
Supply Chain Analysis
Extended payment terms from wind turbine OEMs in Denmark and Spain are squeezing working capital for precision-forging specialists locked into 18-month qualification cycles. Supply concentrates in China, Germany, and Japan for hobbing equipment and heat-treatment capacity. Raw material flows draw from nickel-molybdenum alloy streams and case-hardening chemical inputs. Single-source vulnerability sits with three German equipment builders controlling global hob sharpening service capacity. Distribution runs through continental stock-and-ship networks serving MRO channels with compressed order cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision metrology capability gaps are widening as CMM programming training pipelines lag retirement rates across Midwest US manufacturing hubs. This skill scarcity concentrates margin capture with certified specialists.
For Market Incumbents: Build captive heat-treatment moats through backward integration into forging clusters in Jiangsu and Zhejiang provinces. Direct-drive motor substitution in EV applications threatens single-stage spur volumes; defend through AGMA 12 certification investment for aerospace-grade positioning. Channel control via API-integrated procurement platforms locks in Japanese Tier-1 relationships. For New Entrants and Emerging Players: Pursue plastic spur gear white space in MRI equipment and food-grade conveyor systems where magnetic transparency mandates polymer substitution. Medical imaging actuator supply chains remain underpenetrated by precision-molding specialists. Go-to-market through Siemens Healthineers and comparable OEM qualification programs bypasses distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with hybrid additive-CNC workflows and existing AGMA 10+ quality infrastructure. Long-term viability hinges on electrification torque-speed requirement shifts compressing gear counts per drivetrain. Watch direct-drive motor adoption rates in low-speed EV applications as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Additive-CNC Workflow Investment | Enables topology-optimized geometries impossible through conventional hobbing for aerospace applications. |
| Captive Heat-Treatment Capacity Expansion | Controls critical supply for wind turbine gearbox rebuilders facing EU Ecodesign circular economy mandates. |
| AGMA 12 Certification Pathway | Unlocks aerospace-grade pricing premiums through FAA and EASA qualification requirements. |
| API-Integrated Procurement Platform | Matches Denso and Aisin direct integration requirements compressing order-to-delivery cycles. |
| Plastic Spur Gear Production Scale-Up | Captures MRI equipment demand from Siemens Healthineers where magnetic transparency is mandatory. |
Research Methodology
Operator-level perspectives from maintenance directors at wind turbine service contractors, plant engineers in automotive powertrain facilities, and aftermarket procurement heads at industrial gearbox rebuilders anchored the qualitative base. Secondary validation drew from ISO 6336 technical documentation, AGMA quality grade specifications, SEC filings of listed precision gear manufacturers, and customs trade data for alloy steel inputs. Bottom-up demand modeling across end-use applications triangulated against top-down supply capacity assessments in China, Germany, and Japan.
Scenario bracketing around electrification adoption curves, lubricant reformulation timelines under EU F-Gas Regulation, and powder metallurgy penetration rates structured the analytical framework. Segmentation dimensions spanned material category, quality grade tier, application intensity, and regional manufacturing cluster. CAGRs derived from unit volume trajectories and value-per-unit shifts across the projection horizon. Industry-specific inputs included EV gear count compression rates and wind turbine installation mandates under China's MIIT dual carbon targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-drive motor suppliers or hybrid manufacturing specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Pressure Pumping Services Market
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
Pneumatic Cylinder Market