
 Diaphragm Coupling in Turbo Machinery Market | 2026-2036
Diaphragm Coupling in Turbo Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Diaphragm Coupling in Turbo Machinery Market Analysis
Asset-light leasing models for turbo machinery packages is narrowing the competitive field to suppliers who can bundle coupling replacement into long-term service contracts. Rexnord Corporation leverages its aftermarket logistics network to lock in multi-year agreements with independent power producers. Voith GmbH anchors its position through captive foundry capacity for Inconel diaphragm discs used in geothermal turbine applications. SKF Group competes by integrating condition monitoring sensors directly into coupling hubs, shifting revenue from hardware to predictive service subscriptions.
Diaphragm coupling in turbo machinery refers to a flexible torque-transmitting device that uses a thin metallic disc pack, typically 0.2–0.5 mm thick, to accommodate angular, parallel, and axial misalignment between rotating shafts while maintaining torsional stiffness critical for high-speed turbocompressors and gas turbines. The flexural steel segment dominates unit volumes due to fatigue resistance in combined-cycle power plants, while composite variants represent the fastest-growing material class as aerospace OEMs seek weight reduction for auxiliary power units. Marine applications concentrate margin pools around corrosion-resistant coatings for offshore platform duty, where salt spray and cyclic loading accelerate replacement cycles.
API 671 governs flexible coupling design for petroleum and chemical services in the United States, mandating material traceability and nondestructive testing that elevates qualification costs for new entrants. The EU Machinery Directive and ATEX standards regulate turbo machinery deployed in European refineries and offshore installations, coupling safety requirements with CE marking obligations. Stakeholders must monitor how carbon border adjustments and evolving hydrogen turbine specifications reshape material selection and certification timelines for next-generation diaphragm packs.
Market Dynamics
Power generation utilities are consolidating procurement around long-term service contracts that bundle coupling replacement with predictive maintenance, squeezing standalone hardware vendors and elevating integrated solution providers.
Growth Catalysts
- API 671 Material Traceability Mandates:United States refineries now require full metallurgical documentation for flexible couplings, disqualifying uncertified suppliers and concentrating orders among pre-qualified vendors.
- Combined-Cycle Plant Expansion:Flexural steel diaphragm packs capture rising orders from natural gas turbine installations seeking fatigue resistance under thermal cycling.
- Germany's LNG Infrastructure Buildout:Compressor train deployments at Wilhelmshaven and Brunsbüttel terminals are generating concentrated demand for high-speed disc-pack couplings.
Market Restraints
- Inconel Price Volatility:Nickel-based superalloy costs fluctuate with mining output from Indonesian and Russian sources, compressing margins on geothermal-grade diaphragm discs.
- Captive Foundry Concentration:European coupling manufacturers rely on a limited supplier base for thin-section disc forgings, creating single-source vulnerability.
- Gear Coupling Substitution:Lower-speed auxiliary drives in some process industries tolerate gear-type alternatives that undercut diaphragm solutions on initial cost.
Strategic Opportunities
- Saudi Hydrogen Turbine Pilots:NEOM and similar giga-projects specify corrosion-resistant diaphragm packs for hydrogen-blended gas turbines, opening premium specification tiers.
- Embedded Sensor Convergence:Integration of vibration and torque monitoring into coupling hubs enables predictive service subscriptions that displace break-fix maintenance models.
- India's PLI-Backed Manufacturing:Production-linked incentives for precision engineering components attract diaphragm disc fabrication capacity to serve domestic power and petrochemical sectors.
Industry Challenges
- Multi-Axis Misalignment Simulation Expertise:Finite element modeling of combined angular, parallel, and axial displacement requires specialized talent scarce outside established turbomachinery hubs.
- ISO 10494 Certification Timelines:Evolving European turbine testing standards extend qualification periods for new diaphragm pack designs, delaying revenue recognition.
- Legacy System Integration Complexity:Retrofit installations on aging compressor trains demand custom spacer configurations that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaphragm Coupling in Turbo Machinery Market |
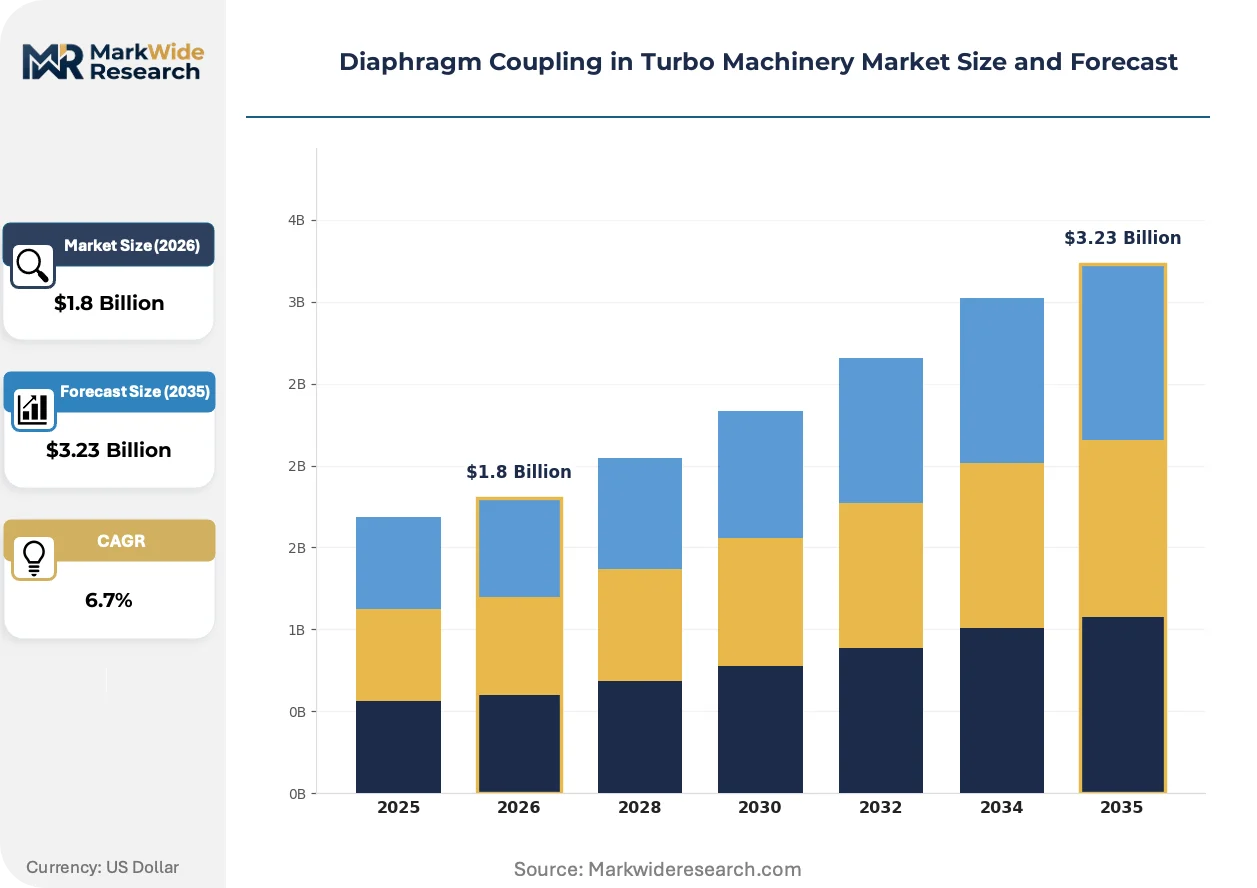
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Flexural, Steel, Aluminum, Composite Application: Power Generation, Oil Extraction, Aerospace, Marine End User: Manufacturers, OEMs, Service Providers, Maintenance Firms Installation Type: Onshore, Offshore, Industrial, Commercial |
| Companies Covered | Rexnord Corporation, KTR Systems, Voith GmbH, SKF Group, Siemens Energy, Regal-Beloit Corporation, John Crane Inc., Eagle Industry Co. Ltd., R+W Couplings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaphragm Coupling in Turbo Machinery Market Emerging Trajectories
Composite material adoption and embedded intelligence are restructuring how diaphragm couplings deliver value, compressing hardware margins while expanding recurring revenue streams.
Additive manufacturing is collapsing lead times for prototype disc-pack geometries that previously required months of forging and machining. Siemens Energy and specialized job shops are qualifying laser-powder-bed fusion for Inconel 718 diaphragm elements, cutting iteration cycles from quarters to weeks. This acceleration is collapsing the traditional barrier between custom engineering and series production.
REACH substance restrictions are forcing reformulation of corrosion-resistant coatings applied to marine-duty couplings. The European Chemicals Agency's authorization requirements for hexavalent chromium processes are pushing suppliers toward plasma-sprayed ceramic alternatives. Offshore platform operators in the North Sea are absorbing higher coating costs to maintain CE marking compliance.
Power producers are unbundling after-sales service from original equipment procurement, creating standalone contracting opportunities for coupling specialists. Independent power producers in Texas and the PJM interconnection now issue separate RFPs for hardware supply and predictive maintenance, favoring vendors with localized field service networks over distant manufacturers.
Diaphragm Coupling in Turbo Machinery Market Segmentation
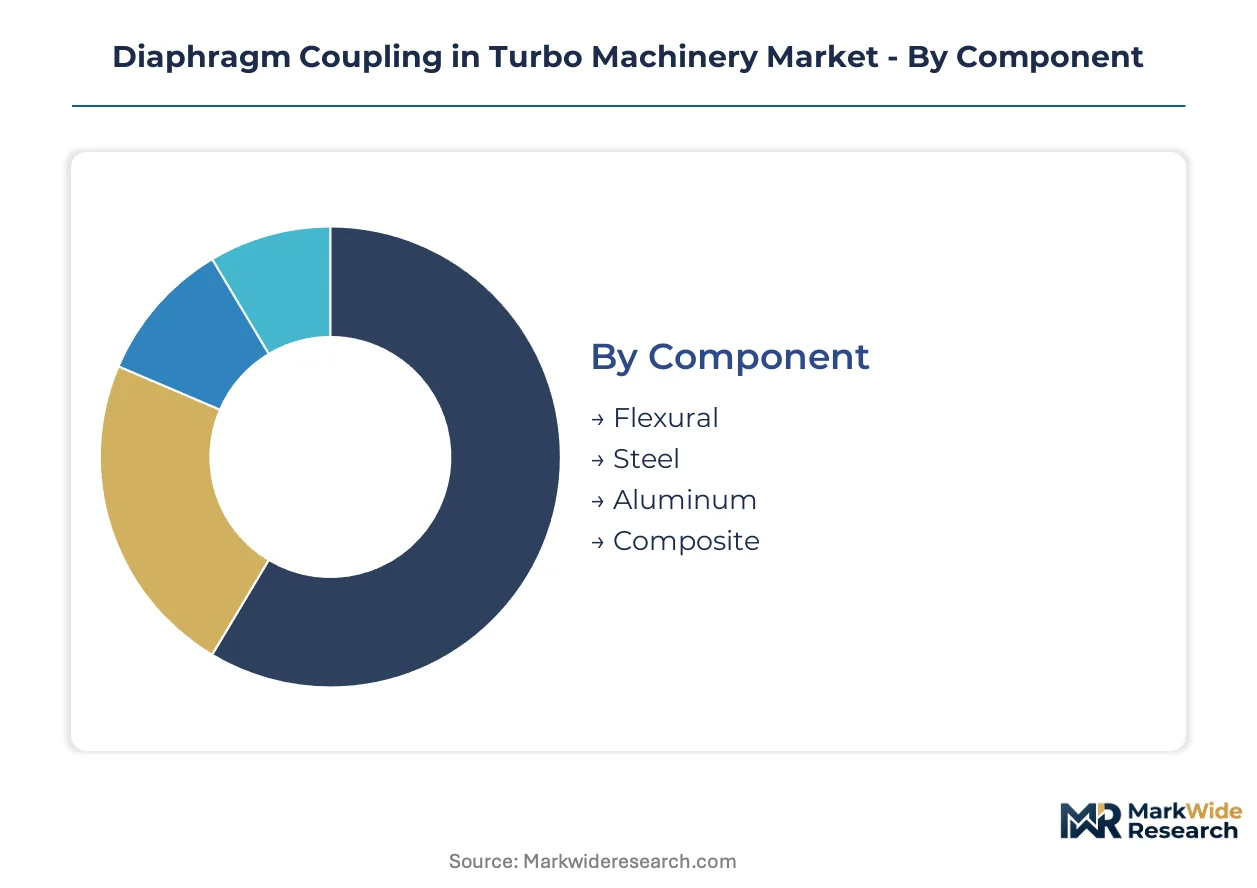
Segmentation in the diaphragm coupling market reveals how procurement cycles, certification burdens, and service intensity vary sharply across component materials and installation environments. Understanding these divergences allows suppliers to align inventory and engineering resources with predictable replacement rhythms.
Component:
Replacement cycles stretch from months for corrosion-vulnerable alloys to decades for aerospace-grade composites, compressing margin capture into distinct temporal windows.
- Flexural:Thin-section steel disc packs, typically 0.2–0.5 mm thick, deliver fatigue resistance under thermal cycling in combined-cycle gas turbines. German LNG compressor trains at Wilhelmshaven and Brunsbüttel anchor concentrated procurement of flexural configurations rated for high-speed operation.
- Steel:Standard carbon and alloy steel diaphragms dominate unit economics across petrochemical auxiliary drives. North American refineries under API 671 mandates favor steel variants with full metallurgical traceability, disqualifying uncertified suppliers from maintenance contracts.
- Aluminum:Lightweight aluminum disc packs serve lower-torque applications in auxiliary power units where mass reduction offsets stiffness penalties.
- Composite:Carbon-fiber-reinforced polymer laminates cut rotational inertia for aerospace turbine applications, though qualification timelines under evolving turbine testing standards delay revenue recognition for new designs.
Steel dominates installed base. Composite is where expansion concentrates.
Application:
Cost tiers separate mission-critical prime movers from auxiliary systems, with pricing stratifying across certification grade and performance requirements.
- Power Generation:Grid-connected gas turbines and steam turbines demand API 671-compliant flexural steel packs with embedded condition monitoring. Independent power producers in Texas and the PJM interconnection unbundle hardware procurement from predictive maintenance contracts, favoring vendors with localized field service networks.
- Oil Extraction:Offshore platform duty imposes corrosion-resistant coating requirements under REACH substance restrictions, pushing suppliers toward plasma-sprayed ceramic alternatives that absorb higher costs to maintain CE marking compliance.
- Aerospace:Auxiliary power units in commercial aviation drive composite adoption for weight reduction, though OEM qualification cycles extend engineering bandwidth.
- Marine:Salt spray and cyclic loading on offshore vessels accelerate replacement cycles, concentrating margin pools around specialized coating formulations.
Power generation commands premium pricing. Oil extraction offers the steepest expansion trajectory as LNG infrastructure buildouts multiply compressor train deployments.
End User:
Customer type determines whether revenue flows through single-transaction hardware sales or multi-year service subscriptions.
- Manufacturers:Original equipment fabricators specify coupling performance during turbine assembly, locking in design decisions early in project development.
- OEMs:Turbine original equipment manufacturers bundle couplings into packaged systems, capturing aftermarket value through captive service networks.
- Service Providers:Independent maintenance contractors issue separate RFPs for hardware supply and predictive maintenance, creating standalone contracting opportunities for specialists with localized logistics.
- Maintenance Firms:Break-fix operators concentrate demand for rapid-turnaround replacement disc packs, favoring suppliers with additive manufacturing capabilities that collapse prototype lead times.
OEMs control design-in value. Service providers represent the fastest-climbing revenue channel as asset-light leasing models proliferate.
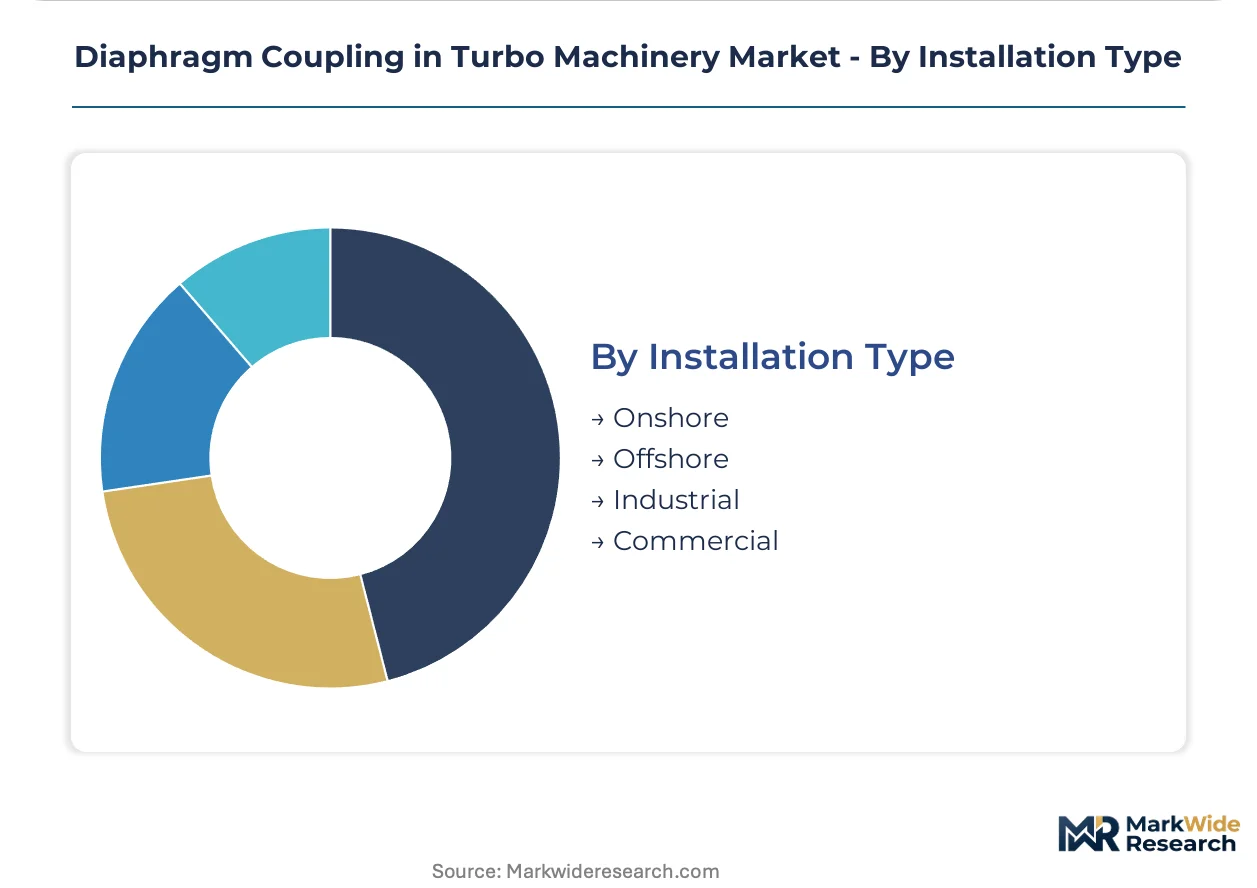
Installation Type:
Geographic and environmental exposure dictates material selection and coating specifications, with offshore duty imposing the most severe qualification burdens.
- Onshore:Land-based power plants and refineries under EPA and state environmental regulations favor standardized steel configurations with established maintenance protocols.
- Offshore:North Sea platforms and similar marine environments require hexavalent-chromium-free coatings under ECHA authorization requirements, accelerating supplier reformulation efforts.
- Industrial:Process industry installations tolerate wider misalignment tolerances, accepting gear coupling substitutes in lower-speed auxiliary drives that undercut diaphragm solutions on initial cost.
- Commercial:Distributed generation and smaller-scale turbomachinery prioritize compact spacer configurations for retrofit installations on aging compressor trains.
Onshore anchors volume scale. Offshore commands the highest margin premiums per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration among independent power producers and LNG terminal operators is reshaping geographic demand patterns for high-speed disc-pack couplings. API 671 compliance in the United States and evolving ISO 10494 standards in Europe are tightening material certification protocols. Industrial clusters in Germany, the United States, Saudi Arabia, India, and Japan anchor distinct supply-demand configurations.
United States
Independent power producers in Texas and the PJM interconnection unbundle hardware procurement from predictive maintenance contracts. EPA emissions regulations and FERC grid reliability mandates elevate API 671 compliance requirements for refinery-grade couplings. Houston anchors a dense maintenance contractor ecosystem serving Gulf Coast petrochemical installations.
Germany
LNG compressor train deployments at Wilhelmshaven and Brunsbüttel terminals generate concentrated demand for flexural steel configurations. ECHA REACH substance restrictions force coating reformulation for offshore-duty components. Siemens Energy and Voith GmbH anchor a supplier ecosystem serving combined-cycle gas turbine installations across Lower Saxony.
Saudi Arabia
NEOM and similar giga-projects specify corrosion-resistant diaphragm packs for hydrogen-blended gas turbines. The country's national industrial regulator tightens material traceability for geothermal-grade applications. Eastern Province industrial cities concentrate procurement for petrochemical expansion projects.
India
Production-linked incentives for precision engineering components attract diaphragm disc fabrication capacity. CEA grid codes and BIS standards tighten certification timelines for imported turbo machinery packages. Gujarat and Maharashtra industrial corridors concentrate domestic power and petrochemical sector demand.
Japan
Aerospace auxiliary power unit OEMs drive composite material adoption for weight-sensitive applications. METI industrial standards and JIS certification requirements extend qualification periods for new disc-pack designs. Nagoya-area manufacturing clusters concentrate precision forging capacity for thin-section turbine components.
Diaphragm Coupling in Turbo Machinery Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where aftermarket service integration determines margin capture. Consolidation around long-term leasing models favors vendors with captive foundry capacity and localized field networks. Three archetypes dominate: integrated turbine OEMs with bundled coupling offerings, standalone coupling specialists with additive manufacturing capabilities, and maintenance contractors with predictive service platforms. Competitive moves center on backward integration into thin-section disc forging and geographic expansion through field service acquisitions.
Among Germany-based fabricators, Voith GmbH exemplifies the captive-foundry archetype through in-house production of nickel-based superalloy components. Rexnord Corporation represents the channel-control model with aftermarket logistics networks locking multi-year service agreements. SKF Group occupies a position integrating condition monitoring hardware into coupling hubs, shifting revenue toward predictive subscriptions.
| Leading Market Players |
|---|
| Rexnord Corporation |
| KTR Systems |
| Voith GmbH |
| SKF Group |
| Siemens Energy |
| Regal-Beloit Corporation |
| John Crane Inc. |
| Eagle Industry Co. Ltd. |
| R+W Couplings |
| Others |
Supply Flow & Price Mechanics
Inconel price volatility originating from Indonesian and Russian mining output compresses margin spreads across geothermal-grade diaphragm discs while simultaneously forcing buyers toward long-term offtake contracts with captive foundry operators. This commodity exposure dictates a bifurcated pricing architecture where API 671-certified flexural steel packs command substantial premiums over uncertified alternatives, and supply chain resilience investments become inseparable from procurement strategy.
Pricing Analysis
Cost-plus contracts indexed to LME nickel futures dominate procurement for superalloy diaphragm components, with price differentiation separating API 671-certified flexural steel packs from standard carbon steel variants and uncertified imports. Pricing stratifies across premium, standard, and economy tiers based on certification grade and embedded sensor integration, with margins tightening in the standard tier due to gear coupling substitution in lower-speed auxiliary drives. Independent power producers in Texas exhibit highest price sensitivity through unbundled hardware RFPs, while Saudi hydrogen turbine pilots show lowest sensitivity given specification premiums for corrosion-resistant packs.
Supply Chain Analysis
Thin-section Inconel disc forgings draw from captive foundry capacity concentrated in Germany, the United States, and Japan, with secondary machining and coating operations distributed across lower-cost precision engineering clusters in India and Eastern Europe. Raw material dependencies center on nickel superalloy feedstock, plasma-sprayed ceramic coating precursors, and high-purity steel billets for flexural packs. Single-source vulnerability in European thin-section forging capacity creates structural risk, particularly under REACH-driven coating reformulation timelines. Distribution runs through OEM captive networks for original equipment, with independent maintenance contractors capturing aftermarket volume through localized field service platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions attached to sensor-embedded coupling hubs are expanding faster than standalone hardware sales, transforming procurement economics toward recurring-revenue capture. This service-attach dynamic rewards vendors with condition monitoring integration and penalizes pure-play fabricators lacking field service infrastructure.
For Market Incumbents: Insulate margin pools by securing captive foundry capacity for nickel-based superalloy components and embedding vibration monitoring hardware directly into coupling hubs before gear coupling substitutes capture auxiliary drive share. API 671 certification investments create switching costs that lock refineries into multi-year service contracts, while additive manufacturing capabilities for rapid prototype iteration defend against agile entrants collapsing lead times. For New Entrants and Emerging Players: India's PLI-backed precision engineering corridors offer the most penetrable manufacturing footprint for diaphragm disc fabrication serving domestic power and petrochemical procurement. Saudi hydrogen turbine pilots present specification-white-space opportunity for corrosion-resistant pack designs, with NEOM giga-projects accepting premium pricing for qualified suppliers. A go-to-market angle through independent maintenance contractors in Texas and the PJM interconnection bypasses OEM channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service platforms over standalone hardware fabricators, with predictive maintenance revenue multiples commanding premium valuations. Acquisition targets should exhibit captive superalloy forging capacity, embedded sensor engineering teams, or established field service networks in LNG infrastructure clusters. The signal to watch is unbundling velocity—acceleration of separate hardware and service RFPs by independent power producers indicates tipping point for platform-based business models.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Foundry Acquisition | Backward integration into Inconel disc forging secures supply continuity under nickel price volatility. |
| Embedded Sensor Platform Launch | Condition monitoring integration shifts revenue from hardware sales to predictive service subscriptions. |
| API 671 Certification Investment | Full metallurgical traceability qualifies vendors for refinery maintenance contracts under tightening mandates. |
| India Manufacturing Footprint | PLI scheme incentives attract precision engineering capacity for domestic turbo machinery demand. |
| Hydrogen Turbine Qualification | Corrosion-resistant pack certification opens premium specification tiers in Saudi giga-projects. |
Methodological Framework
Cross-validation between primary interviews with turbomachinery maintenance directors, OEM procurement teams, aftermarket service heads, and plant engineers anchors the qualitative findings, supplemented by secondary validation through API 671 compliance databases, ISO 10494 certification records, FERC grid reliability filings, and customs trade data for Inconel and steel billet flows. Bottom-up unit economics from individual compressor train deployments triangulate against top-down market sizing from power generation capacity expansion announcements.
Calibration against historical replacement cycle data and observed procurement patterns from LNG terminal buildouts in Germany and hydrogen turbine pilots in Saudi Arabia shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include component material class, application severity tier, end-user procurement archetype, and installation environment exposure, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements from major turbomachinery OEMs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by additive manufacturing specialists or sensor-integrated platform entrants would shift outcomes beyond modeled ranges. Cross-checking against EIA power plant commissioning schedules and IEA hydrogen turbine deployment roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
Rotary Machinery Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
Pressure Pumping Services Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
US Electrical Services Market