
 Exhibition, Convention & Meeting Market | 2026-2036
Exhibition, Convention & Meeting Market Size, Share, and Industry Trends Forecast 2026-2036
Exhibition, Convention & Meeting Market Insights
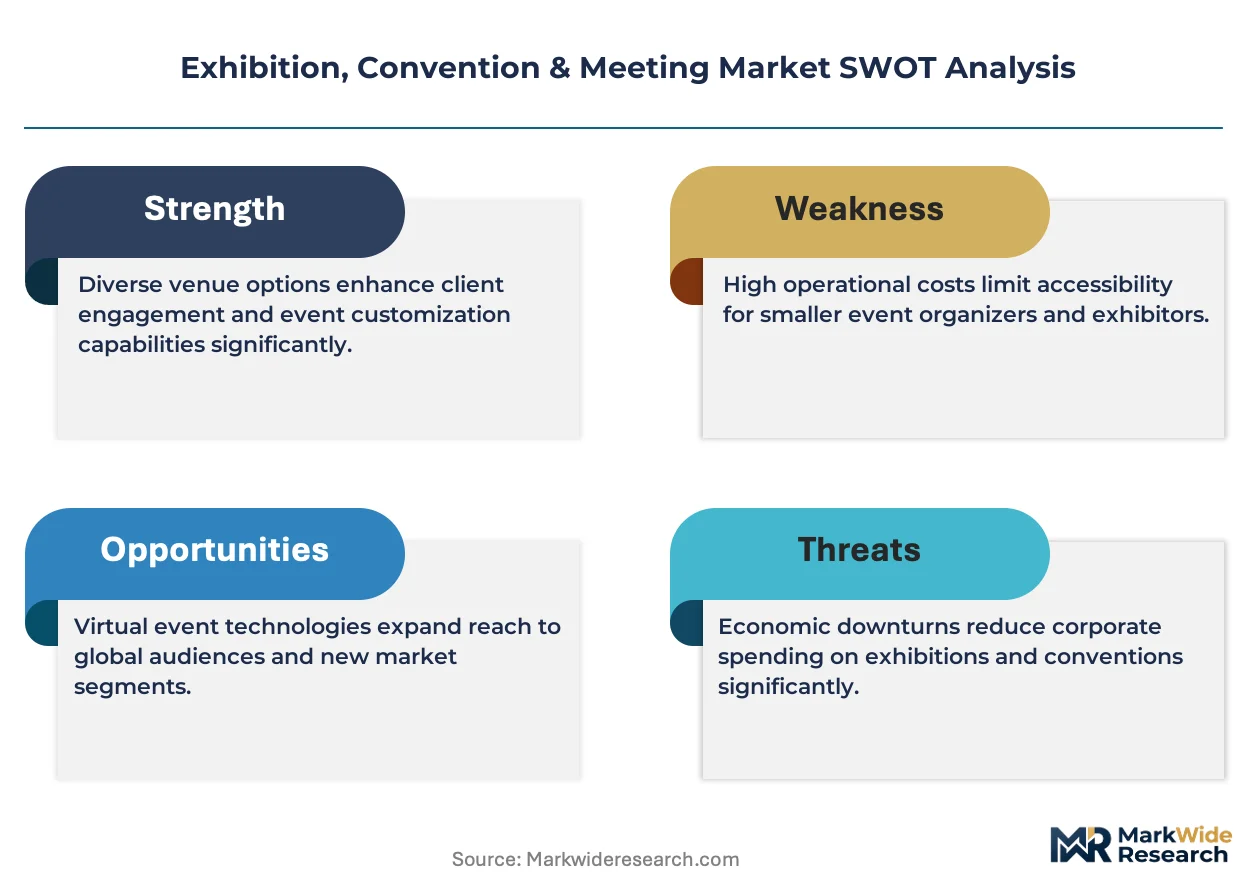
Asset-light leasing models for convention infrastructure is narrowing the capital barrier for mid-tier venue operators seeking national footprint expansion. Mandalay Bay Convention Center leverages its integrated resort ecosystem to sustain year-round booking density regardless of seasonal trade show cycles. McCormick Place anchors the Midwest corridor through its modular hall configuration, while Georgia World Congress Center competes on total contiguous exhibition space.
Exhibition, convention and meeting facilities comprise purpose-built halls, temporary structures, and hybrid digital-physical environments designed to host trade shows, corporate events, conferences and seminars, with specifications typically requiring minimum ceiling heights of 30 feet, load-bearing floors rated at 350 pounds per square foot, and integrated HVAC systems capable of full air exchange within 15 minutes. The primary commercial purpose centers on enabling business-to-business commerce, knowledge transfer, and professional networking across concentrated temporal windows. Trade shows and corporate events currently generate the deepest margin pools within event type segmentation, whereas SMEs represent the fastest-expanding organizational size category as cloud-based event management platforms reduce planning overhead. Venue management and audiovisual services capture disproportionate value within service type segmentation due to recurring technical upgrade cycles and captive demand during event execution.
FDA guidelines on pharmaceutical promotion directly shape booth design and disclosure requirements at healthcare conventions in the United States, while the EU AI Act imposes algorithmic transparency obligations on European events deploying facial recognition or behavioral analytics. OSHA workplace safety standards and local fire marshal codes govern maximum occupancy thresholds and egress protocols across US convention centers. Stakeholders must monitor how emerging carbon accounting rules from the EU Green Deal reshape attendee travel patterns and venue energy procurement decisions.
Market Dynamics
The EU AI Act is forcing exhibition organizers to dismantle opaque attendee tracking systems and rebuild data architectures around algorithmic transparency, compressing planning timelines for major trade shows while elevating compliance costs.
Growth Catalysts
- Pharmaceutical convention expansion:FDA disclosure requirements for healthcare booths are standardizing design specifications across US medical trade shows, creating predictable procurement cycles for venue operators.
- Cloud-based event management:SME adoption of integrated planning platforms is collapsing barriers to entry for mid-sized corporate events, expanding addressable demand.
- Germany's trade fair concentration:Frankfurt and Munich anchor automotive and medical exhibition clusters, concentrating infrastructure investment and international exhibitor flows.
Market Restraints
- Energy procurement volatility:EU Green Deal carbon accounting rules are exposing venue operators to scope 3 emissions liabilities from attendee air travel.
- Technical ceiling constraints:Legacy halls below 30-foot clear heights cannot accommodate modern pharmaceutical booth architectures requiring vertical rigging.
- Regulatory fragmentation:Divergent OSHA egress protocols across US state fire marshals complicate national touring exhibition logistics.
Strategic Opportunities
- Asset-light leasing models:Modular convention infrastructure rentals are enabling mid-tier operators to expand national footprints without balance-sheet expansion.
- Hybrid digital-physical convergence:Integration of virtual attendee platforms with physical hall environments is opening year-round revenue streams beyond temporal trade show windows.
- India's exhibition infrastructure gap:Underdeveloped purpose-built hall stock in Mumbai and Delhi presents first-mover positioning for international venue management contracts.
Industry Challenges
- Audiovisual technician scarcity:Rapid technical upgrade cycles in LED wall and spatial audio systems are outpacing certified technician supply in secondary markets.
- HVAC compliance timelines:15-minute full air exchange specifications require capital-intensive plant retrofits that conflict with seasonal booking cash flow patterns.
- Legacy integration friction:New facial recognition analytics systems face interoperability failures with existing badge-printing and CRM databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exhibition, Convention & Meeting Market |
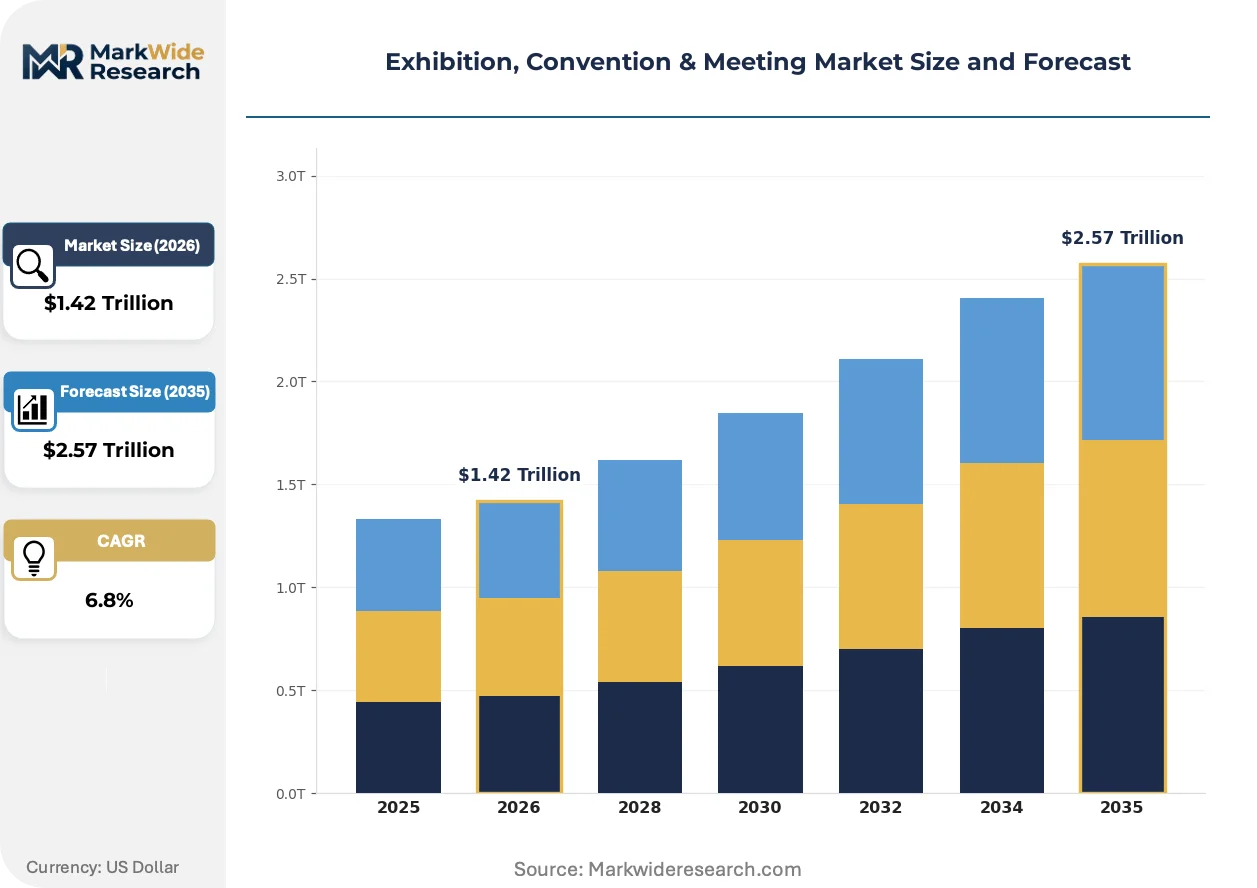
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.57 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Event Type: Trade Shows, Corporate Events, Conferences, Seminars Organizational Size: SMEs, Large Enterprises, Nonprofits, Government Agencies Service Type: Event Planning, Venue Management, Catering, Audiovisual Services Market Focus: Technology, Healthcare, Education, Government, Others |
| Companies Covered | Mandalay Bay Convention Center, Georgia World Congress Center, Las Vegas Convention Center, Anaheim Convention Center, Venetian Convention and Expo Center, McCormick Place, Kentucky Exposition Center, Indiana Convention Center, Orange County Convention Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exhibition, Convention & Meeting Market Trends and Innovations
Digital twin environments are compressing the boundary between physical exhibition halls and persistent virtual venues, enabling organizers to monetize attendee relationships beyond temporal event windows.
Immersive LED volume stages are migrating from high-end automotive launches to mid-tier pharmaceutical booths as production costs fall and FDA disclosure requirements demand dynamic content flexibility. Bayer and Roche deployment at ASCO and ESMO congresses is accelerating this transition. The technology is migrating from spectacle-driven brand activations toward compliance-driven information delivery, reshaping booth architecture around content adaptability rather than static structural investment.
The EU AI Act's algorithmic transparency mandates are compelling European venues to publish data retention policies and consent audit trails for behavioral analytics. This regulatory pressure is fragmenting vendor landscapes as non-compliant tracking providers exit the market. Healthcare conventions in Germany and France are responding by appointing dedicated data protection officers and restructuring sponsor agreements to exclude biometric capture clauses.
Corporate procurement departments are consolidating event spend under centralized procurement platforms that unbundle venue rental from audiovisual and catering services. This disintermediation is compressing margins for full-service convention centers while elevating specialized technical providers. The shift is most visible in US technology sector events, where procurement teams now mandate itemized service line bidding and prohibit bundled opaque pricing.
Exhibition, Convention & Meeting Market Segmentation
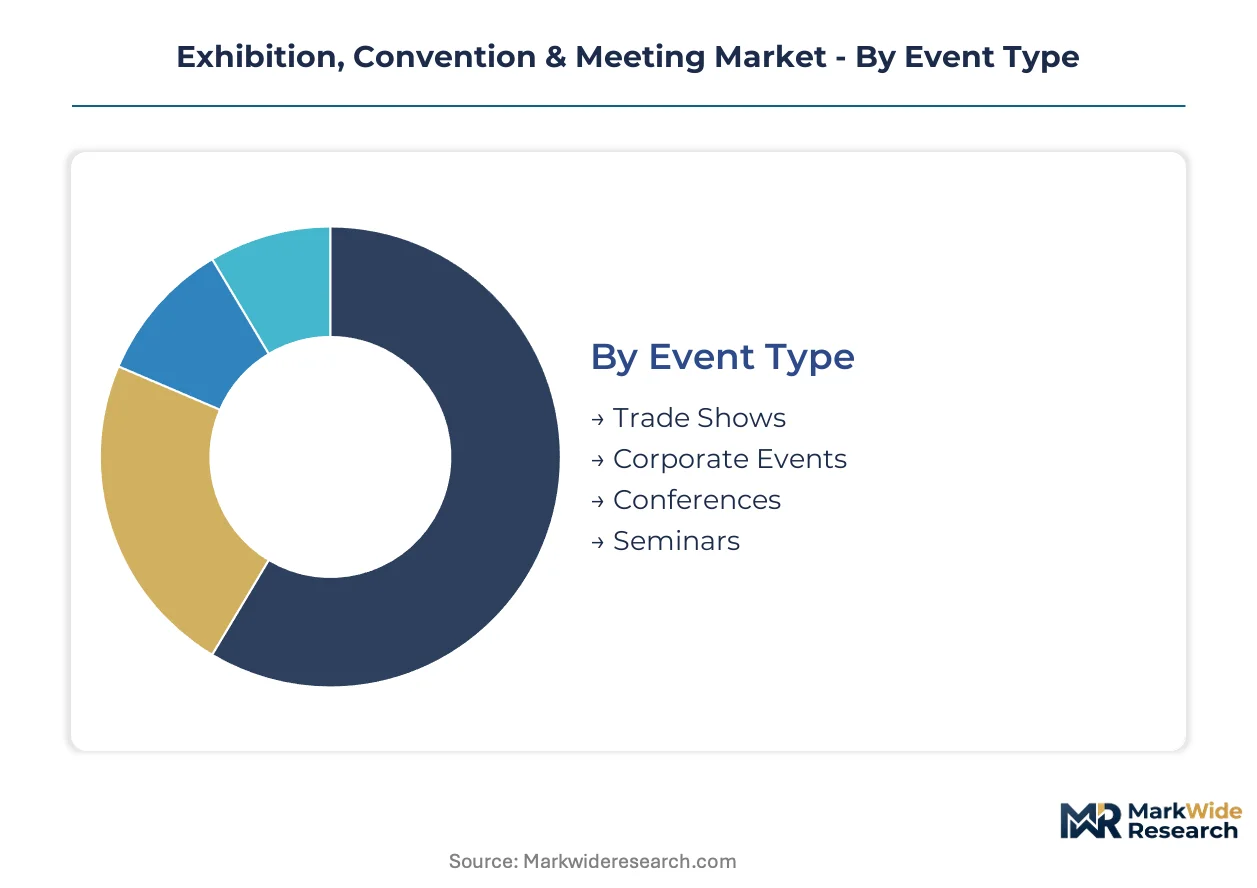
Event organizers deploy distinct commercial strategies across each segmentation axis. Venue operators configure physical specifications, staffing ratios, and technology stacks differently depending on whether they serve pharmaceutical trade shows or corporate training seminars.
Event Type:
Application determines venue specifications, with ceiling height requirements and load-bearing floors varying dramatically across formats.
- Trade Shows:Purpose-built halls with 30-foot minimum clear heights and 350 psf load-bearing floors accommodate multi-story pharmaceutical booths. FDA disclosure requirements at US healthcare conventions standardize booth architectures around dynamic content delivery rather than static structural investment.
- Corporate Events:Modular hall configurations and integrated resort ecosystems sustain year-round booking density regardless of seasonal cycles. Mandalay Bay leverages its hospitality infrastructure to capture recurring corporate retreat contracts.
- Conferences:Hybrid digital-physical environments with integrated streaming platforms serve dispersed attendee bases. Knowledge transfer formats prioritize auditorium acoustics and broadcast-grade video distribution over exhibition floor specifications.
- Seminars:Smaller footprint requirements enable hotel ballroom conversions and tertiary market penetration. Cloud-based event management platforms reduce planning overhead for mid-sized professional development programs.
Trade shows hold installed capacity. Corporate events are rotating up the share rankings.
Organizational Size:
Customer type shapes procurement complexity and service bundling preferences across the demand base.
- SMEs:Cloud-based planning platforms collapse barriers to entry for mid-sized events, expanding addressable demand beyond traditional enterprise accounts. Integrated software reduces headcount requirements for registration, scheduling, and post-event analytics.
- Large Enterprises:Centralized procurement platforms unbundle venue rental from audiovisual and catering services, compressing margins for full-service operators. US technology sector procurement teams now mandate itemized service line bidding.
- Nonprofits:Budget constraints drive preference for off-peak booking windows and shared service arrangements. Association-managed events concentrate in secondary markets with lower labor and facility costs.
- Government Agencies:Compliance protocols around accessibility, security clearance, and domestic content requirements restrict vendor pools. Federal procurement regulations in the US impose documentation burdens that favor established contractors.
Large enterprises hold installed capacity. SMEs are climbing the fastest expansion trajectory.
Service Type:
Margin concentration varies by service category, with technical upgrade cycles and captive demand during event execution determining value capture.
- Event Planning:Integrated software platforms consolidate registration, scheduling, and analytics into unified workflows. SME adoption is displacing fragmented point solutions and reducing planning overhead.
- Venue Management:Asset-light leasing models for modular infrastructure enable mid-tier operators to expand national footprints without balance-sheet expansion. Recurring facility maintenance contracts provide revenue visibility across seasonal booking cycles.
- Catering:Food service operations face margin compression from labor cost volatility and dietary accommodation requirements. Corporate procurement consolidation favors itemized bidding over bundled concessions.
- Audiovisual Services:Rapid technical upgrade cycles in LED wall and spatial audio systems outpace certified technician supply in secondary markets. Captive demand during event execution supports premium pricing for rush technical support.
Audiovisual services hold installed capacity. Venue management is gaining share fastest.
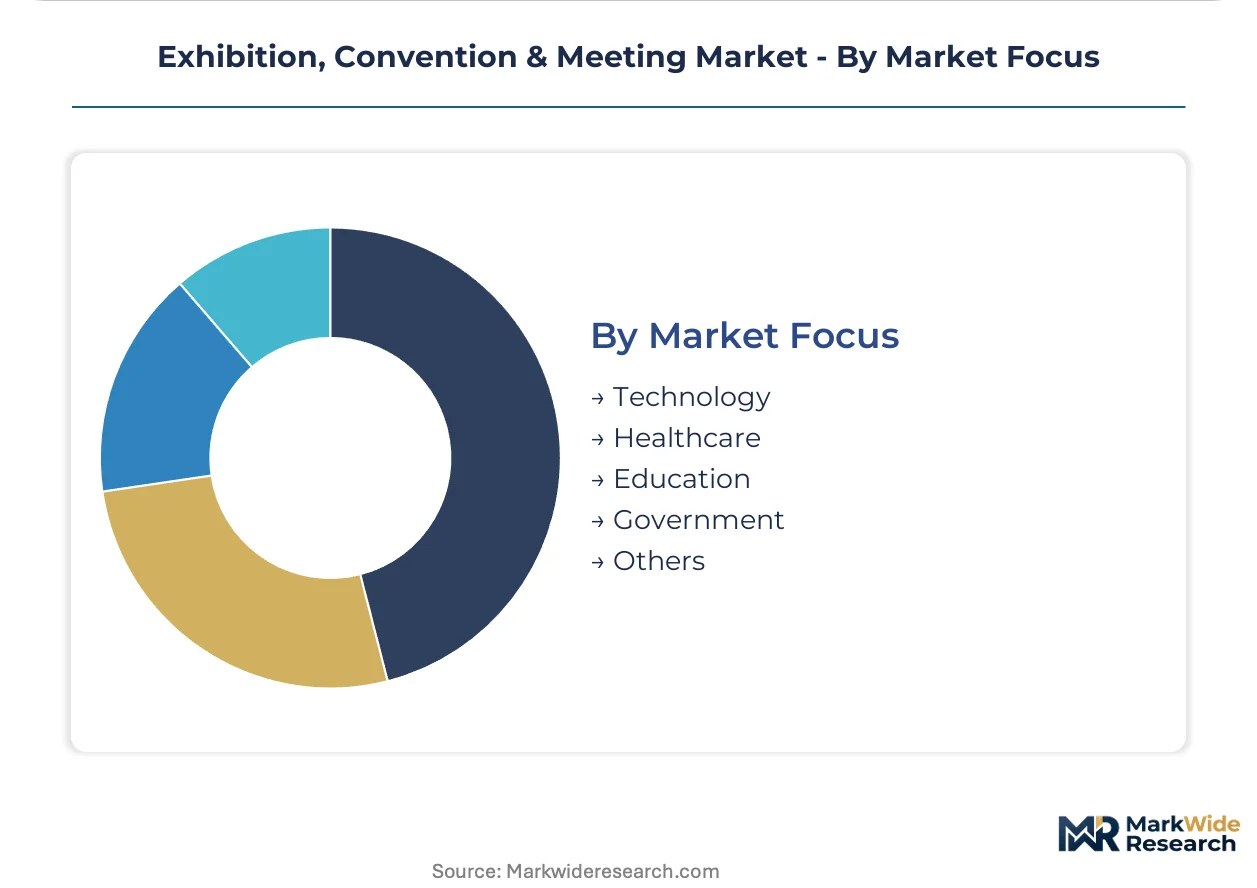
Market Focus:
End-use verticals impose distinct regulatory and technical requirements on venue operators and service providers.
- Technology:Digital twin environments and immersive LED volume stages migrate from high-end automotive launches to mid-tier booth deployments. Bayer and Roche deployment at ASCO and ESMO congresses accelerates this transition.
- Healthcare:FDA guidelines on pharmaceutical promotion directly shape booth design and disclosure requirements at US conventions. EU AI Act algorithmic transparency mandates compel European venues to restructure data collection protocols.
- Education:Professional development and certification programs concentrate in university-affiliated conference centers and hotel properties near research clusters. Hybrid delivery models expand reach beyond physical capacity constraints.
- Government:Security clearance requirements and domestic preference regulations restrict vendor eligibility for federal events. Procurement timelines extend well beyond commercial sector norms.
- Others:Consumer exhibitions and entertainment formats prioritize spectacle and social media integration over B2B knowledge transfer specifications.
Healthcare holds installed capacity. Technology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical procurement teams and automotive engineering departments concentrate exhibition spend in Germany and the United States, while corporate event planners fragment demand across integrated resort destinations. Regulatory divergence between FDA disclosure protocols and EU AI Act transparency mandates is forcing multinational organizers to maintain parallel compliance architectures.
Germany
Frankfurt and Munich anchor medical and automotive trade fair clusters that draw international exhibitor flows. The EU AI Act compels venues to publish algorithmic audit trails for attendee tracking systems, elevating compliance staffing requirements. Messe Frankfurt maintains Europe's deepest installed base of 30-foot clear-height halls purpose-built for pharmaceutical booth architectures.
United States
FDA guidelines on pharmaceutical promotion standardize healthcare booth specifications across Chicago, Las Vegas, and Orlando convention corridors. OSHA workplace safety standards and state-level fire marshal egress protocols create regulatory fragmentation for national touring exhibitions. McCormick Place anchors Midwest demand through modular hall configurations that accommodate both trade shows and corporate events.
China
Shanghai and Beijing exhibition complexes capture domestic pharmaceutical and technology sector event spend. National standards under MIIT and SAMR govern temporary structure safety and digital platform interoperability for hybrid events. The Yangtze River Delta concentration of automotive OEMs sustains demand for high-load-bearing exhibition floors.
United Arab Emirates
Dubai's integrated resort ecosystem attracts corporate retreat and incentive travel budgets from European and South Asian enterprises. MOHAP pharmaceutical regulations and UAE data protection frameworks shape healthcare event protocols. The Dubai World Trade Centre competes on year-round climate-controlled environments that bypass seasonal booking constraints.
India
Mumbai and Delhi exhibition infrastructure gaps force pharmaceutical and technology events into hotel ballroom conversions and temporary structures. CDSCO pharmaceutical regulations and BIS safety standards create compliance complexity for international organizers. Underdeveloped purpose-built hall stock presents first-mover positioning for global venue management contracts.
Exhibition, Convention & Meeting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across venue management, audiovisual services, and integrated resort ecosystems. The market structures around three tiers: destination-anchored mega-complexes with year-round booking density, regionally dominant modular facilities, and specialized technical service providers. Consolidation pressures concentrate among resort-integrated operators seeking geographic diversification, while fragmentation persists in audiovisual technician supply. Competitive moves center on asset-light leasing partnerships and hybrid digital-physical platform integration.
Among United States-based venue operators, Mandalay Bay Convention Center, Georgia World Congress Center, and McCormick Place exemplify the destination-anchored archetype. Mandalay Bay represents integrated resort ecosystem positioning that captures corporate retreat demand through hospitality infrastructure bundling. Georgia World Congress Center occupies a position competing on total contiguous exhibition space for pharmaceutical and automotive trade shows. McCormick Place anchors Midwest corridor demand through modular hall configurations that accommodate diverse event formats.
| Leading Market Players |
|---|
| Mandalay Bay Convention Center |
| Georgia World Congress Center |
| Las Vegas Convention Center |
| Anaheim Convention Center |
| Venetian Convention and Expo Center |
| McCormick Place |
| Kentucky Exposition Center |
| Indiana Convention Center |
| Orange County Convention Center |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in India's purpose-built exhibition hall stock concentrates pricing power with global venue management operators seeking first-mover contracts in Mumbai and Delhi. This utilization asymmetry drives supplier selection toward asset-light leasing partnerships while elevating cost-plus contracting with energy indexation for HVAC retrofits.
Pricing Analysis
Cost-plus contracts with energy cost indexation dominate venue management agreements, particularly for HVAC plant retrofits meeting EU Green Deal carbon accounting rules. Price differentiation separates pharmaceutical trade shows requiring 30-foot clear heights and 350 psf load-bearing floors from corporate seminars using converted hotel ballrooms. Pricing pressure stems from corporate procurement teams mandating itemized service line bidding and prohibiting bundled opaque pricing. SMEs exhibit highest price sensitivity due to cloud-based platform alternatives reducing planning overhead, while pharmaceutical exhibitors show lowest sensitivity given FDA-mandated booth specification compliance.
Supply Chain Analysis
Freeman Company and Encore Global hold dominant contract-manufacturing positions for temporary exhibition infrastructure and audiovisual equipment deployment across North America and Europe. Supply concentration centers on Germany, the United States, and China for purpose-built hall construction materials, LED wall systems, and modular staging components. Raw material dependencies include aluminum truss systems, high-load flooring substrates, and broadcast-grade fiber optic cable runs. Single-source vulnerability persists for certified audiovisual technicians capable of spatial audio and immersive LED volume configuration. Distribution runs through venue-operator procurement departments and corporate event planner networks rather than direct exhibitor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity for LED wall and spatial audio systems constrains capacity expansion in secondary markets, creating acquisition premiums for technical training pipelines and apprenticeship programs.
For Market Incumbents: Pre-empt audiovisual technician scarcity by acquiring specialized training academies or forming captive apprenticeship partnerships with technical institutes in secondary US markets. Consolidate venue management contracts in India before international operators establish footprint. Vertical integration into LED volume stage production insulates against equipment rental margin compression from corporate procurement unbundling. For New Entrants and Emerging Players: Mid-tier pharmaceutical booth design services represent the most penetrable entry point, as FDA disclosure requirements standardize procurement cycles and reduce incumbent relationship advantages. India's underdeveloped purpose-built hall stock in Mumbai and Delhi offers white-space positioning for asset-light modular infrastructure leasing. Go-to-market through cloud-based event management platform partnerships reduces direct sales force requirements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular convention infrastructure as leasing models displace balance-sheet ownership. Long-term viability favors operators with recurring facility maintenance contracts spanning seasonal booking cycles. Target acquisition archetype: regional venue operators with established fire marshal and OSHA compliance documentation. Signal to watch is EU AI Act enforcement patterns affecting behavioral analytics vendor exit rates.| Strategic Initiative | Industry Significance |
|---|---|
| Asset-Light Leasing Partnership | Modular infrastructure rentals enable national footprint expansion without balance-sheet expansion for mid-tier operators. |
| Hybrid Digital-Physical Platform Integration | Virtual attendee platforms with physical hall environments open year-round revenue streams beyond trade show windows. |
| Certified Technician Training Pipeline | Captive apprenticeship programs address LED wall and spatial audio scarcity constraining secondary market expansion. |
| EU AI Act Compliance Architecture | Algorithmic transparency mandates force restructuring of attendee tracking systems and sponsor agreement terms. |
| India First-Mover Venue Contracts | Underdeveloped purpose-built hall stock in Mumbai and Delhi presents positioning for international management contracts. |
Research Methodology
Desk research of SEC venue operator filings, EU regulatory registers, and pharmaceutical industry procurement databases preceded structured interviews with convention center operations directors, corporate event procurement managers, audiovisual technical directors, and pharmaceutical marketing compliance officers. Primary fieldwork validated secondary data on HVAC specification trends and LED volume stage adoption patterns. Bottom-up venue capacity assessments and top-down pharmaceutical marketing spend analysis were triangulated against trade association membership records.
Assumptions around EU AI Act implementation timelines, FDA disclosure requirement evolution, and cloud-based platform adoption curves were held fixed while energy cost trajectories and corporate travel recovery patterns were stress-tested across scenarios. The analytical framework modeled event type, organizational size, service type, and market focus dimensions across the projection horizon. CAGRs were derived from segment-level demand elasticity and supply constraint analysis. Forecast inputs included pharmaceutical R&D pipeline announcements and automotive OEM product launch calendars.
Stress conditions across energy procurement volatility, certified technician supply, and EU carbon accounting enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory implementation consistency and corporate travel budget normalization. Quarterly review of pharmaceutical convention expansion announcements and EU AI Act enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Asia-Pacific MICE Industry Market
Events and Conferences
Spain Event Services Market
Events and Conferences
India B2B Events Market
Events and Conferences
France Event Services Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
South Africa Wedding Services Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Vietnam MICE Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Global Event Management Service Market
Events and Conferences
Trade Show Services Market
Events and Conferences
UAE Event Management Market
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
Wedding Services Market
Events and Conferences
China Wedding Services Market