
 South Africa Wedding Services Market | 2026-2036
South Africa Wedding Services Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Wedding Services Market Insights
Vendor-booking channels in South Africa's wedding sector is fragmenting as couples bypass traditional agencies and engage planners, caterers, and photographers through direct digital platforms. The Aleit Group leverages its full-service production capabilities across the Western Cape to sustain premium positioning. Wedding Concepts anchors its reputation on bespoke design execution for high-net-worth clients in Johannesburg and Cape Town. Mosaic Weddings differentiates through curated cultural and multi-day celebration expertise serving diverse communities.
Wedding services encompass the coordinated provision of event planning, food and beverage preparation, visual documentation, floral styling, and venue access for marriage ceremonies and receptions, typically executed through fixed-term contracts with defined guest counts, service timelines, and aesthetic specifications. The primary commercial purpose centers on transforming client preferences into managed, insured, and logistically executable celebrations within budgeted parameters. Catering and venue rental dominate value capture given their fixed capacity constraints and per-guest pricing models, while photography commands disproportionate margin strength through album upsells and digital licensing. All-inclusive packages attract time-constrained couples and international destination clients, whereas custom packages serve domestic markets where family involvement drives granular decision-making across every service element.
The National Department of Tourism enforces hospitality grading standards that affect venue classification and pricing transparency, while the South African Revenue Service's VAT registration requirements shape formalization incentives for smaller vendors. Municipal bylaws in Cape Town, Johannesburg, and Durban regulate noise ordinances, alcohol licensing, and outdoor event permits, creating localized compliance complexity that advantages established operators with dedicated legal resources. Stakeholders must monitor evolving municipal tariff structures and tourism incentive programs to anticipate where venue investment and service expansion will yield sustainable returns.
Market Dynamics
Direct digital booking platforms are collapsing traditional agency intermediation in South Africa's wedding sector, as couples in Cape Town and Johannesburg increasingly source planners, caterers, and photographers through Instagram, TikTok, and specialized vendor marketplaces rather than established full-service agencies.
Growth Catalysts
- Destination wedding demand:International couples from Europe and North America are selecting Western Cape vineyard estates and coastal venues for multi-day celebrations, expanding the high-value buyer pool beyond domestic markets.
- National Department of Tourism hospitality standards:Mandatory grading classifications for venues create pricing transparency that reduces buyer search friction and accelerates booking velocity for formalized operators.
- Vineyard estate infrastructure:Stellenbosch and Franschhoek wine farms have invested in dedicated event facilities with on-site accommodation, capturing extended-stay wedding revenue that single-day urban venues cannot match.
Market Restraints
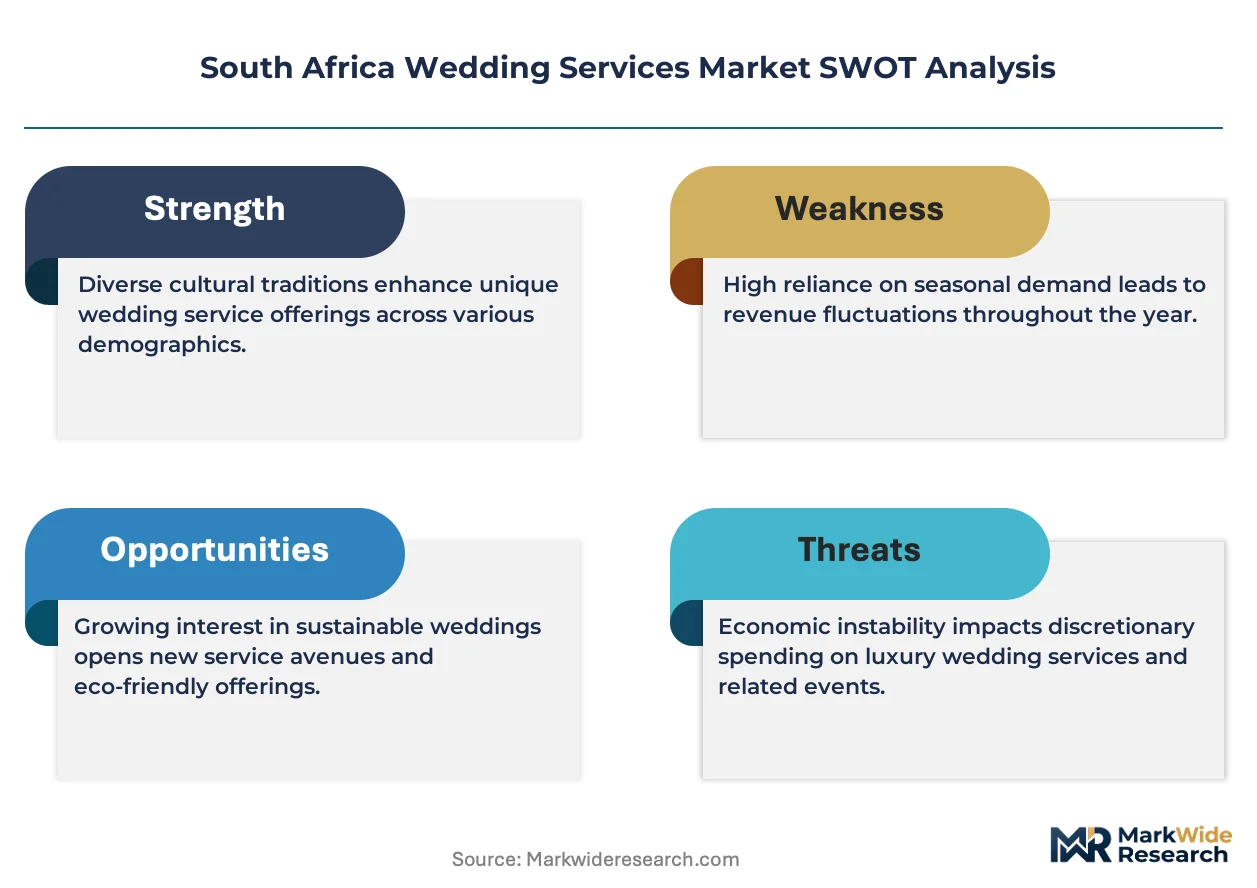
- Seasonal demand compression:Cape Town's Mediterranean climate concentrates 70% of outdoor wedding bookings into October through April, forcing fixed-cost venue operators to absorb underutilization during winter months.
- Municipal permitting fragmentation:Cape Town, Johannesburg, and Durban each maintain distinct noise ordinance schedules, alcohol licensing timelines, and outdoor event permit requirements that create compliance cost duplication for multi-city operators.
- Photography labor supply constraints:Premium wedding photographers command rates exceeding R25,000 per event, yet skilled second shooters and editing assistants remain scarce, capping studio scaling potential.
Strategic Opportunities
- KwaZulu-Natal coastal underpenetration:Ballito and Umhlanga offer comparable beachfront aesthetics to Western Cape venues at 30-40% lower rental rates, attracting price-sensitive domestic couples and regional African destination markets.
- Cultural celebration specialization:Multi-day Indian, Zulu, and Xhosa wedding formats remain underserved by full-service planners trained primarily in Western single-day templates, creating margin expansion through bespoke programming.
- Tourism Business Council event safety protocols:Certification as a compliant vendor for international corporate incentive weddings opens procurement channels through travel management companies and destination management organizations.
Industry Challenges
- Floral logistics coordination:Perishable décor elements require just-in-time delivery across dispersed rural venues with unreliable refrigeration infrastructure, elevating spoilage risk and insurance costs.
- Digital reputation management:Single negative TikTok or Google Reviews exposure can devastate small vendor bookings, forcing disproportionate marketing spend on influencer partnerships and review generation rather than service investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Wedding Services Market |
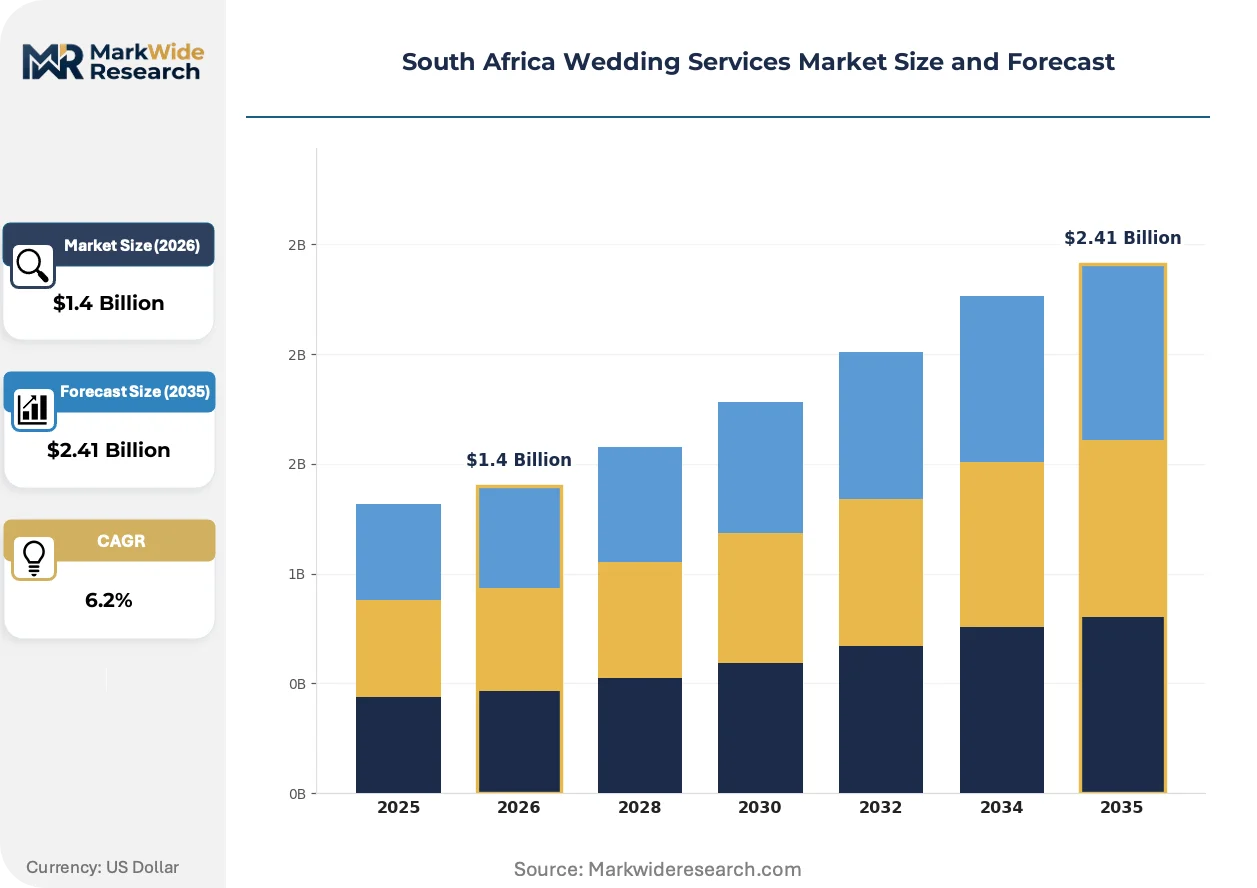
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Catering, Photography, Floral Design, Venue Rental Package Type: All-Inclusive Packages, Custom Packages, Elopement Packages, Destination Packages Client Type: Couples, Wedding Planners, Families, Event Coordinators Budget Range: Low Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Trunk Events, Anna Marcelle Weddings, Wedding Concepts, Infinite Concepts, Bisous Events, The Aleit Group, Mosaic Weddings, Megara Weddings, Otto de Jager Events, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Wedding Services Market Trends and Innovations
Technology and regulatory pressure are compressing traditional service boundaries in South African wedding planning, as digital tools reshape vendor discovery while municipal and national frameworks impose new operational compliance burdens on informal operators.
Drone-based aerial cinematography is collapsing the distinction between ground and aerial wedding documentation, enabling videographers to capture vineyard estate processions and coastal cliff ceremonies from previously inaccessible angles. Boutique studios in the Western Cape are bundling drone footage as standard in premium packages, compressing the market for standalone aerial specialists who cannot match integrated pricing.
The National Department of Tourism's hospitality grading standards are mandating fire safety certification, disability access compliance, and transparent published pricing for all classified venues. Properties in Johannesburg's northern suburbs and Cape Town's Atlantic seaboard are investing R500,000-R2 million in retrofitting infrastructure to maintain four-star and five-star classifications, while ungraded rural estates face exclusion from corporate and international buyer shortlists.
Couples are fragmenting vendor selection across direct digital channels rather than purchasing consolidated packages, spending 15-20 hours researching individual photographers, florists, and caterers through Instagram portfolios and WhatsApp consultation. This pattern concentrates in Gauteng and Western Cape urban markets where vendor density supports comparison shopping, while compressing commission revenue for traditional full-service agencies that previously captured 15-25% markup on subcontractor coordination.
South Africa Wedding Services Market Segmentation
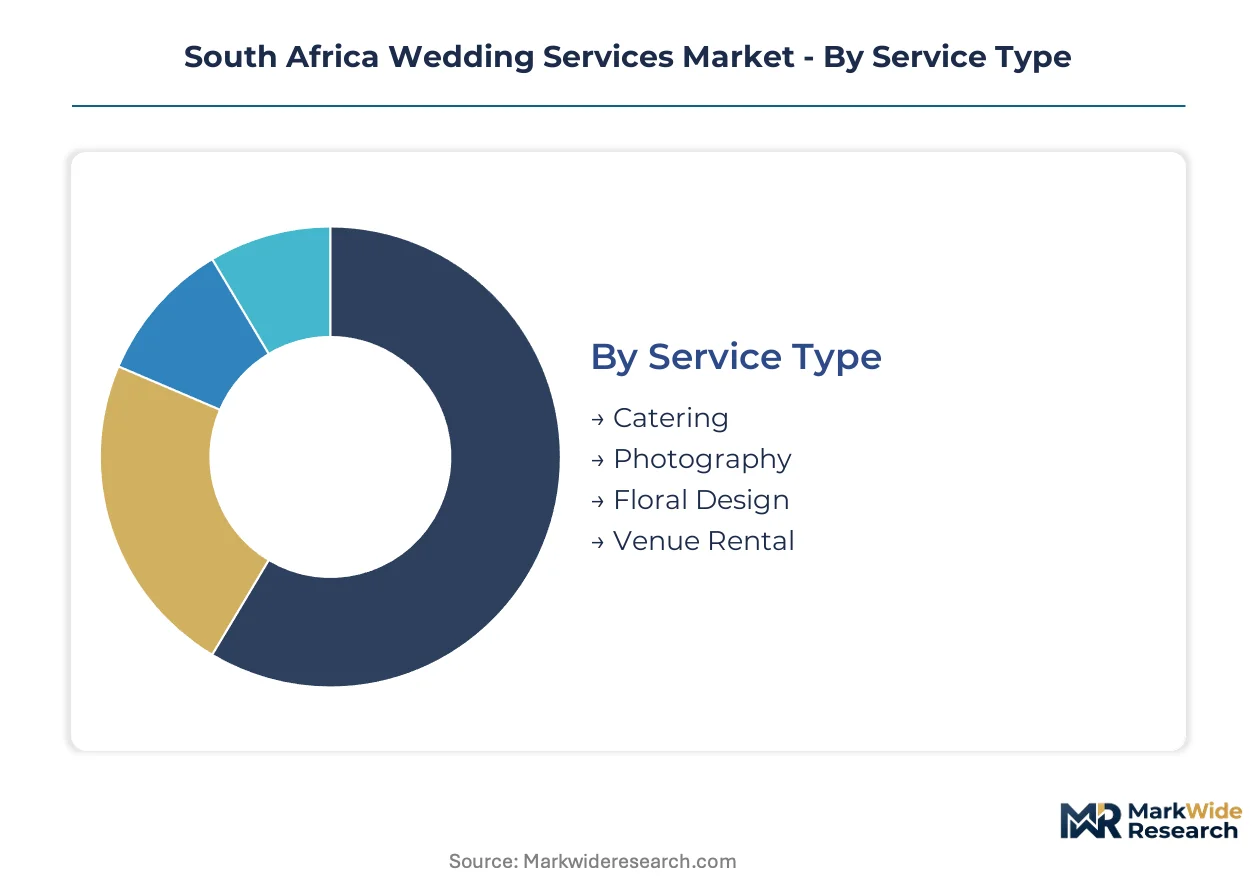
Segmentation in South Africa's wedding services market reveals how vendor specialization and client purchasing patterns create distinct competitive arenas. Service providers calibrate their offerings across multiple dimensions to capture value from Cape Town vineyard estates to KwaZulu-Natal beachfront venues.
Service Type:
Use cases span from single-service procurement by budget-conscious couples to fully outsourced production for destination celebrations.
- Catering:Per-guest pricing models dominate, with plated service and buffet formats commanding premium rates at Western Cape wine estates. Demand concentrates in Stellenbosch and Franschhoek where vineyard venues require bonded alcohol service and farm-to-table menu integration.
- Photography:Drone-enabled aerial cinematography and same-day editing now differentiate premium studios. Johannesburg and Cape Town urban markets drive demand for documentary-style coverage, while editing labor scarcity caps studio scaling.
- Floral Design:Perishable logistics challenge rural venue execution.
- Venue Rental:Fixed capacity constraints create pricing power during October-April peak season.
The dominant share belongs to Catering, while Photography is closing the gap fastest.
Package Type:
Cost tiers separate time-constrained buyers seeking convenience from families demanding granular control over every service element.
- All-Inclusive Packages:Bundled planning, catering, décor, and coordination services target international destination couples and corporate incentive events. Western Cape vineyard estates leverage these packages to capture extended-stay revenue beyond single-day celebrations.
- Custom Packages:Modular service selection serves domestic markets where family involvement drives vendor-by-vendor procurement. Gauteng and Western Cape urban couples spend substantial research hours comparing individual photographers, florists, and caterers through Instagram and WhatsApp.
- Elopement Packages:Intimate ceremonies for under 20 guests gain traction among cost-conscious couples.
- Destination Packages:Multi-day programming with guest accommodation and activity coordination.
All-Inclusive Packages capture the highest value per transaction, yet Custom Packages are expanding most quickly as digital vendor discovery reduces search friction.
Client Type:
Procurement authority varies from direct couple engagement to intermediary-mediated transactions with divergent margin structures.
- Couples:Direct digital sourcing through TikTok and Instagram collapses traditional agency intermediation. Cape Town and Johannesburg couples increasingly bypass full-service agencies to negotiate directly with photographers and caterers.
- Wedding Planners:Full-service coordinators capture markup on subcontractor management. The Aleit Group and Wedding Concepts anchor premium positioning through production capabilities and bespoke design execution.
- Families:Multi-generational decision-making dominates traditional and cultural celebrations.
- Event Coordinators:Corporate and incentive wedding procurement through travel management companies.
Couples retain the dominant procurement volume, though Wedding Planners are gaining share fastest among high-net-worth and destination segments.
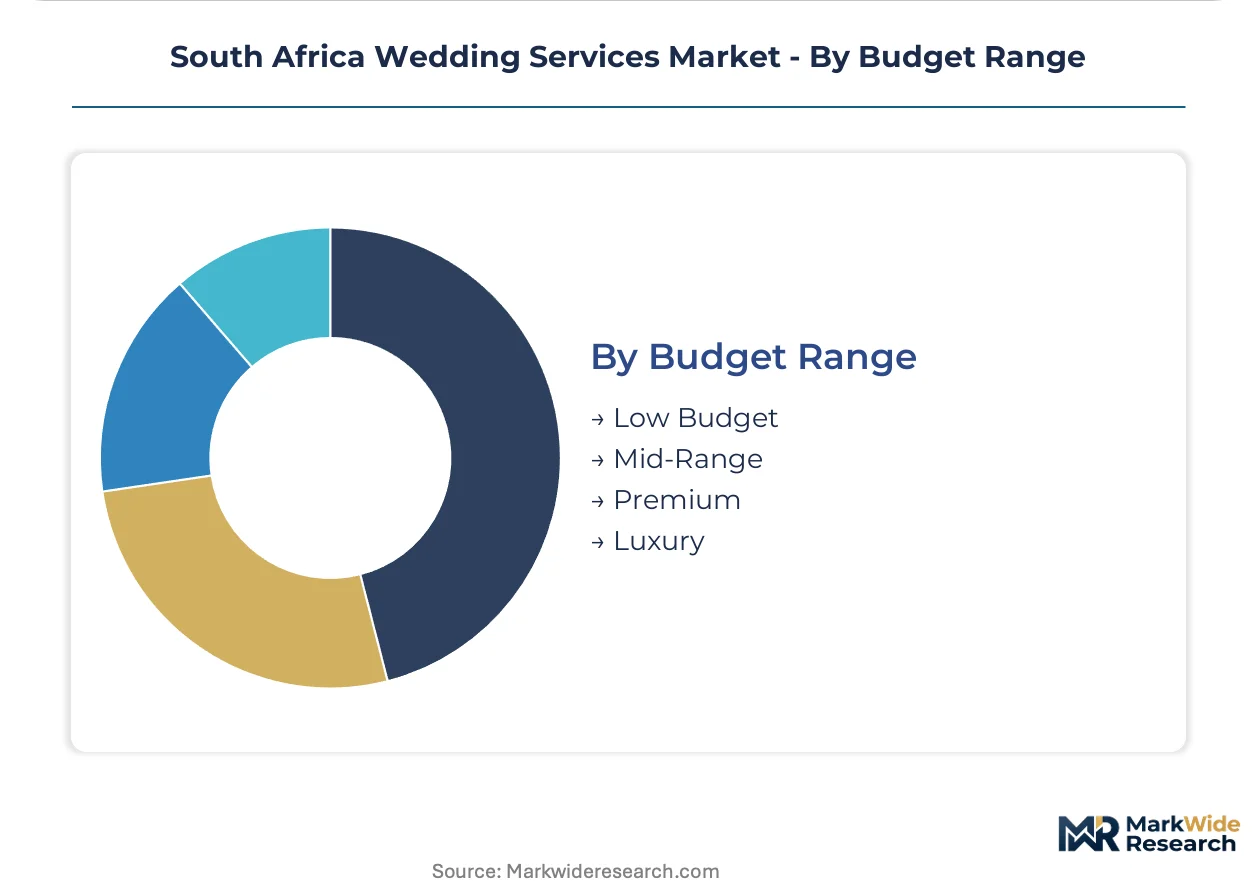
Budget Range:
Price stratification aligns with venue grading standards and service formalization levels enforced by national hospitality regulations.
- Luxury:Multi-day celebrations at five-star graded venues with dedicated event facilities and on-site accommodation. Stellenbosch wine farms and Cape Town Atlantic seaboard properties command rates requiring R500,000-R2 million infrastructure investment to maintain classification.
- Premium:Four-star venues and established full-service agencies with portfolio differentiation. Johannesburg northern suburbs and Cape Town coastal venues concentrate demand here.
- Mid-Range:Three-star graded properties and independent vendor coordination.
- Low Budget:Ungraded community halls and self-coordinated service procurement.
Luxury commands the highest absolute revenue, while Premium is climbing the fastest as formalization incentives push ungraded operators toward compliance investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cape Town International Airport's direct connectivity to European hubs underwrites the Western Cape's dominance in destination wedding logistics, channeling international guest traffic toward vineyard estates and coastal venues.
Western Cape
Vineyard estates in Stellenbosch and Franschhoek drive destination wedding demand through dedicated event facilities with on-site accommodation. The National Department of Tourism's hospitality grading standards mandate fire safety certification and disability access compliance for venue classification. Cape Town's Atlantic seaboard properties command premium rates after investing R500,000-R2 million in infrastructure upgrades to maintain four-star and five-star ratings.
Gauteng
Johannesburg's northern suburbs concentrate high-net-worth domestic celebrations with multi-generational family involvement in vendor selection. Municipal noise ordinances and alcohol licensing timelines in Johannesburg and Pretoria create localized compliance requirements. Sandton and Rosebank host established full-service agencies capturing markup on subcontractor coordination for bespoke design execution.
KwaZulu-Natal
Ballito and Umhlanga beachfront venues offer comparable aesthetics to Western Cape properties at 30-40% lower rental rates. Municipal bylaws in Durban regulate outdoor event permits and coastal access for ceremonies. The region attracts price-sensitive domestic couples and regional African destination markets underserved by vineyard estate infrastructure.
Eastern Cape
Port Elizabeth and East London coastal venues serve budget-conscious couples seeking alternatives to saturated Western Cape and Gauteng markets. Provincial tourism development incentives support informal operator formalization. The Wild Coast's ungraded rural estates face exclusion from corporate and international buyer shortlists lacking National Department of Tourism classification.
South Africa Wedding Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in photography, floral design, and catering execution. The vendor base organizes around three strategic archetypes: full-service production houses bundling planning, décor, and coordination; boutique studios specializing in single-service excellence; and vineyard estate operators capturing extended-stay revenue through captive venue-all-inclusive packages. Competitive moves concentrate on portfolio diversification into adjacent celebration formats and geographic expansion across provincial municipal jurisdictions to amortize compliance cost duplication.
Within the full-service production tier, The Aleit Group and Wedding Concepts exemplify premium positioning through Western Cape and Johannesburg market presence. Mosaic Weddings occupies a position serving diverse communities with curated cultural and multi-day celebration expertise. These three operators anchor the competitive structure alongside boutique specialists in photography and floral design.
| Leading Market Players |
|---|
| Trunk Events |
| Anna Marcelle Weddings |
| Wedding Concepts |
| Infinite Concepts |
| Bisous Events |
| The Aleit Group |
| Mosaic Weddings |
| Megara Weddings |
| Otto de Jager Events |
| Others |
Pricing and Supply Chain Analysis
Western Cape vineyard estates anchor pricing power through fixed capacity constraints and seasonal compression, with Stellenbosch and Franschhoek wine farms commanding premium rates during October-April peak demand while absorbing underutilization costs across winter months. This geographic supply concentration transfers directly to per-guest pricing models that escalate with National Department of Tourism grading classifications and on-site accommodation bundling.
Pricing Analysis
Volume-discount tiering structures separate luxury multi-day celebrations at five-star graded venues from mid-range ungraded community hall procurement, with premium-mid-economy pricing differentiation driven by certification level and geographic delivery cost. Price differentiation intensifies as direct digital booking platforms collapse traditional agency markups, forcing established operators to absorb 15-25% commission compression while Cape Town and Johannesburg couples negotiate vendor-by-vendor. Pricing pressure stems from KwaZulu-Natal beachfront venues offering comparable aesthetics at 30-40% lower rental rates, with domestic families exhibiting highest price sensitivity and international destination couples showing lowest.
Supply Chain Analysis
Export-control regime angles are absent in this services market, though municipal permitting fragmentation across Cape Town, Johannesburg, and Durban creates regulatory chokepoints limiting multi-city operator scaling. Geographic supply concentration centers on South Africa with Western Cape vineyard infrastructure, Gauteng urban vendor density, and KwaZulu-Natal coastal development as primary nodes. Raw material dependencies span perishable floral imports, bonded alcohol inventories, and specialized photography equipment. Supply chain risk rests on single-source vulnerability for premium photographers commanding rates exceeding R25,000 per event with scarce skilled second shooters. Distribution feeds from direct digital channels through Instagram, TikTok, and WhatsApp consultation collapsing traditional agency intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DIY digital coordination threatens incumbent full-service agencies as Cape Town and Johannesburg couples increasingly bypass established operators to negotiate directly with individual vendors, forcing substitution defense through captive venue bundling and certification differentiation.
For Market Incumbents: Insulate margin position by deepening backward integration into vineyard estate ownership and securing exclusive catering contracts at National Department of Tourism five-star graded properties. The Aleit Group and Wedding Concepts should accelerate certification investment to maintain exclusion from corporate and international buyer shortlists, while deploying dedicated legal resources to amortize municipal permitting cost duplication across Western Cape and Gauteng operations. For New Entrants and Emerging Players: Build out cultural celebration specialization serving multi-day Indian, Zulu, and Xhosa wedding formats underserved by Western single-day templates in Johannesburg and Durban. KwaZulu-Natal coastal venues at Ballito and Umhlanga offer the most penetrable geography with 30-40% lower rental rates attracting price-sensitive domestic couples, with go-to-market execution through WhatsApp-native vendor discovery and regional African destination marketing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors boutique studios with drone-enabled aerial cinematography and same-day editing capabilities differentiating premium photography packages. Long-term viability across the projection horizon rests on acquisition targets with established National Department of Tourism grading compliance and vineyard estate captive venue relationships, with signal to watch being accelerated municipal tariff restructuring forcing ungraded operator formalization.| Strategic Initiative | Industry Significance |
|---|---|
| Venue Infrastructure Investment | Properties investing R500,000-R2 million in fire safety and disability access retrofitting maintain four-star and five-star National Department of Tourism classifications. |
| Cultural Programming Specialization | Multi-day Indian, Zulu, and Xhosa wedding expertise captures margin expansion in Johannesburg and Durban markets underserved by Western templates. |
| Direct Digital Channel Development | Instagram and TikTok-native vendor discovery collapses traditional agency intermediation for Cape Town and Johannesburg couple procurement. |
| Geographic Expansion | Multi-city operators amortize municipal permitting cost duplication across Cape Town, Johannesburg, and Durban regulatory jurisdictions. |
| Drone Cinematography Integration | Boutique studios bundling aerial footage as standard compress standalone aerial specialist markets through integrated premium package pricing. |
Research Methodology
Operator-level perspectives from wedding planners, vineyard estate managers, catering procurement leads, and photography studio owners anchored the qualitative base for this analysis. Primary interviews across Western Cape, Gauteng, and KwaZulu-Natal were triangulated against National Department of Tourism hospitality grading databases, municipal bylaws from Cape Town and Johannesburg, and Tourism Business Council event safety protocol documentation. Secondary validation drew from vendor marketplace transaction patterns, Instagram and TikTok platform engagement metrics, and bonded alcohol service licensing records. Bottom-up service provider capacity assessments and top-down regional tourism expenditure estimates were reconciled to establish market sizing.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation dimensions spanning service type, package configuration, client procurement authority, and budget range tiered by grading classification. CAGRs were derived from elasticity modeling against international arrival forecasts and domestic household formation patterns, with specific inputs including vineyard estate capacity utilization curves and municipal permitting timeline variations across provincial jurisdictions.
Practitioners should monitor National Department of Tourism grading standard revisions, municipal tariff restructuring, and TikTok-driven vendor discovery acceleration for early signals of structural shift. Forecasts reflect assumptions around seasonal demand compression persistence and direct digital channel penetration rates. Material shifts in international destination wedding travel patterns or municipal alcohol licensing timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
Vietnam MICE Market
Events and Conferences
Wedding Services Market
Events and Conferences
MICE Market
Events and Conferences
Global Event Management Service Market
Events and Conferences
Exhibition, Convention & Meeting Market
Events and Conferences
China Wedding Services Market
Events and Conferences
Trade Show Services Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Spain Event Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
Corporate Event Planner Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
Japan Wedding Services Market
Events and Conferences
Asia-Pacific MICE Industry Market
Events and Conferences
North America Wedding Services Market