
 GCC Event Management Market | 2026-2036
GCC Event Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Event Management Market Insights
Saudi production infrastructure for live entertainment is shifting toward permanent venue ecosystems. Flash Entertainment leverages its Abu Dhabi base to sustain festival-scale operations across multiple emirates. MDLBEAST anchors the kingdom's music and youth culture segment with dedicated Riyadh-based production capabilities. Live Nation Middle East competes through touring logistics and international artist access.
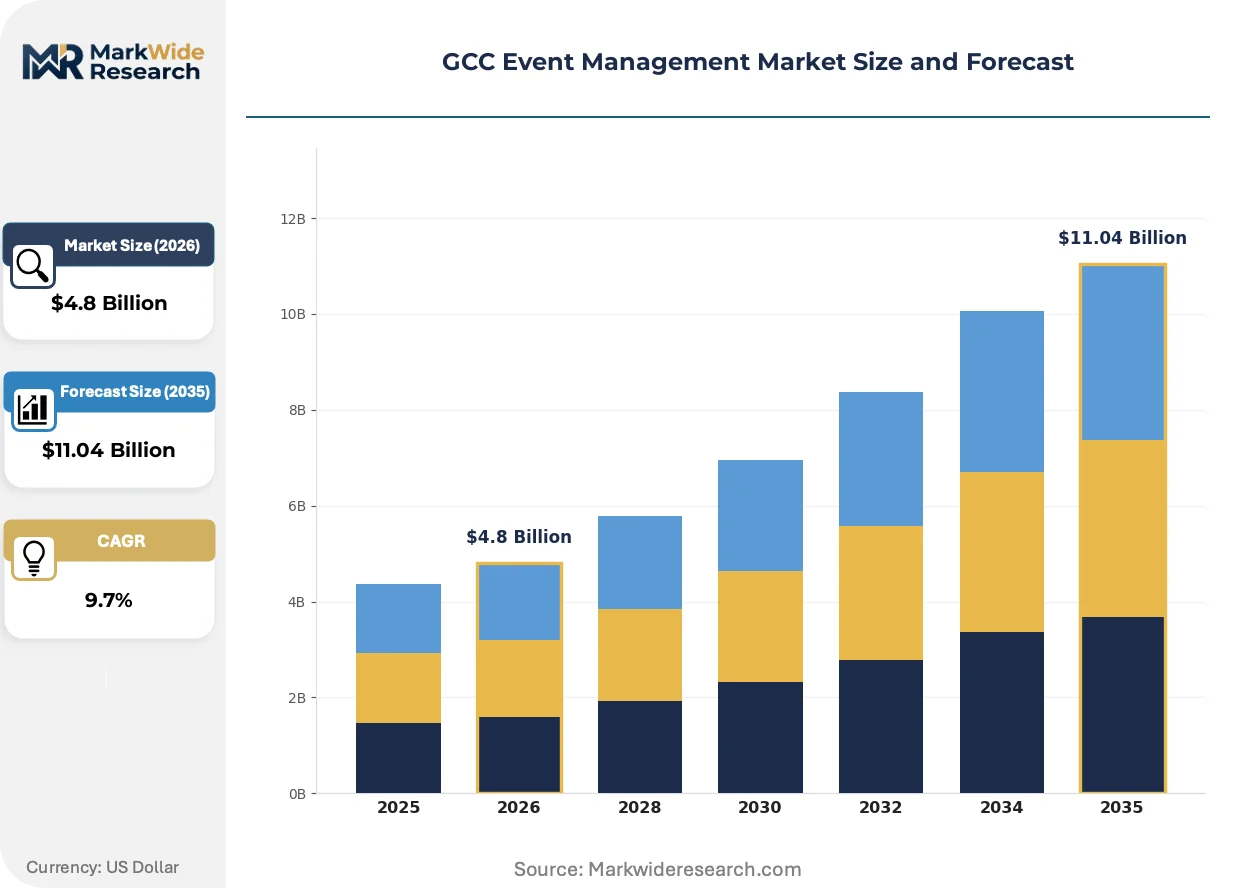
GCC event management encompasses the strategic planning, logistical coordination, technical production, and audience engagement execution required for corporate, social, and commercial gatherings across the Gulf Cooperation Council states. The discipline integrates venue procurement, vendor orchestration, regulatory compliance, and real-time operational control to deliver measurable outcomes for clients. Corporate events and conferences dominate current service type revenue due to sustained public sector and sovereign wealth fund activity. Hybrid events represent the fastest-expanding delivery model as clients demand simultaneous physical and digital audience reach. Event management software within the technology dimension captures concentrated margin pools through recurring licensing and data analytics subscriptions.
MOHAP in the UAE and the Saudi General Entertainment Authority shape venue licensing, safety protocols, and content approval timelines across their respective jurisdictions. MOHAP's health and safety mandates for large gatherings directly influence staffing ratios and emergency planning requirements in Dubai and Abu Dhabi. Stakeholders must monitor evolving entertainment authority guidelines as each Gulf state develops distinct permitting frameworks for international content and artist entry.
Market Dynamics
Hybrid event infrastructure deployment across Saudi Arabia and the UAE is compressing traditional venue economics while expanding addressable audience reach beyond physical capacity constraints. This technology-driven shift forces simultaneous investment in broadcast-grade production suites and conventional hospitality operations.
Growth Catalysts
- Vision 2030 entertainment mandates:Saudi Arabia's sovereign commitment to cultural sector expansion under its national transformation program generates sustained public funding for large-scale venue construction and festival programming.
- Expo legacy infrastructure:Dubai's retained world exhibition sites provide turnkey mega-event capabilities that reduce setup costs for international organizers seeking Middle East entry points.
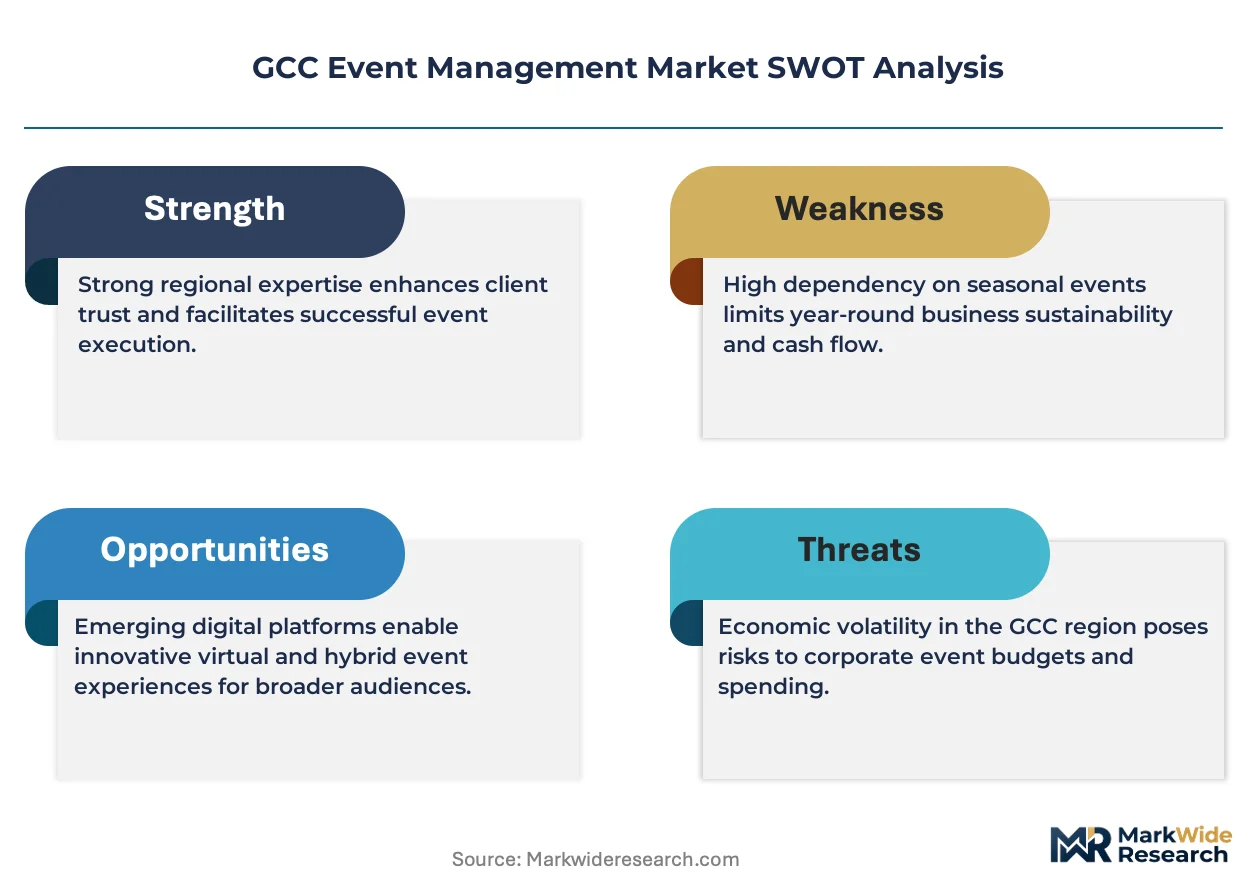
- Cloud-based event management platforms:SaaS tools for registration, analytics, and real-time audience engagement are compressing operational overhead for mid-tier event producers across the Gulf states.
Market Restraints
- Specialized technical labor scarcity:Broadcast engineers, rigging specialists, and simultaneous interpretation technicians command premium wages due to limited regional training pipeline output.
- Import-dependent staging equipment:LED walls, line-array systems, and specialized lighting rigs concentrate sourcing through European and East Asian manufacturers, exposing budgets to freight volatility.
- Content approval timelines:Saudi General Entertainment Authority review processes for international artist performances and thematic content create scheduling uncertainty that compresses marketing lead times.
Strategic Opportunities
- Kuwait and Bahrain corporate segments:These underdeveloped markets lack dedicated convention infrastructure, creating first-mover advantages for regional operators establishing permanent venue management contracts.
- Carbon-neutral event certification:Early adoption of ISO 20121 sustainable event management standards allows premium positioning as ESG disclosure requirements tighten across Gulf sovereign wealth fund portfolios.
- AI-powered audience analytics:Convergence of computer vision and natural language processing enables real-time sentiment tracking and personalized content delivery for hybrid attendees.
Industry Challenges
- Cross-border crew mobility:Visa processing inconsistencies between UAE, Saudi Arabia, Qatar, and Bahrain disrupt talent deployment for multi-venue touring productions.
- Legacy venue retrofit costs:Older hotels and exhibition halls in secondary GCC cities require substantial capital injection to meet MOHAP's updated emergency evacuation and crowd density protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Event Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Corporate Events, Social Gatherings, Conferences, Trade Shows Client Type: Non-Profit Organizations, Government Agencies, Private Corporates, Educational Institutions Delivery Model: On-Site Events, Virtual Events, Hybrid Events, Pop-Up Experiences Technology: Event Management Software, Ticketing Platforms, Mobile Apps, Virtual Reality Solutions |
| Companies Covered | Flash Entertainment, Global Event Management, SELA, Mosaic Live, Plan3 Media, MDLBEAST, Platinumlist, Max Events Dubai, Live Nation Middle East, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Event Management Market Trends and Innovations
Broadcast infrastructure is merging with physical venue operations across Gulf cities, creating permanent hybrid-ready assets rather than temporary overlay installations. This structural investment pattern favors operators with technical production capabilities over pure hospitality managers.
Spatial computing and extended reality platforms are integrating with conventional stage design to enable immersive presenter environments and virtual attendee participation. Corporate clients in Riyadh and Dubai are adopting these tools at accelerating pace for product launches and shareholder meetings. The technology is integrating physical and digital production workflows into unified creative departments, compressing the traditional separation between live and virtual event specialists.
MOHAP's updated health and safety mandates for large gatherings now require real-time crowd monitoring systems and automated emergency communication protocols in Dubai and Abu Dhabi venues. These rules force technology upgrades at legacy properties while creating compliance service opportunities for specialized safety consultants. Hotel and convention center operators are responding by embedding certified safety officers into permanent staffing structures rather than relying on event-specific contractors.
Enterprise procurement teams are consolidating preferred vendor relationships across multiple event categories, replacing fragmented spot-buying with annual framework agreements. This concentration pressures independent event agencies to demonstrate consistent cross-project performance or exit the corporate segment entirely. Saudi Aramco and ADNOC subsidiary procurement departments exemplify this pattern, maintaining rotating shortlists of pre-qualified production partners for recurring executive and technical conferences.
GCC Event Management Market Segmentation
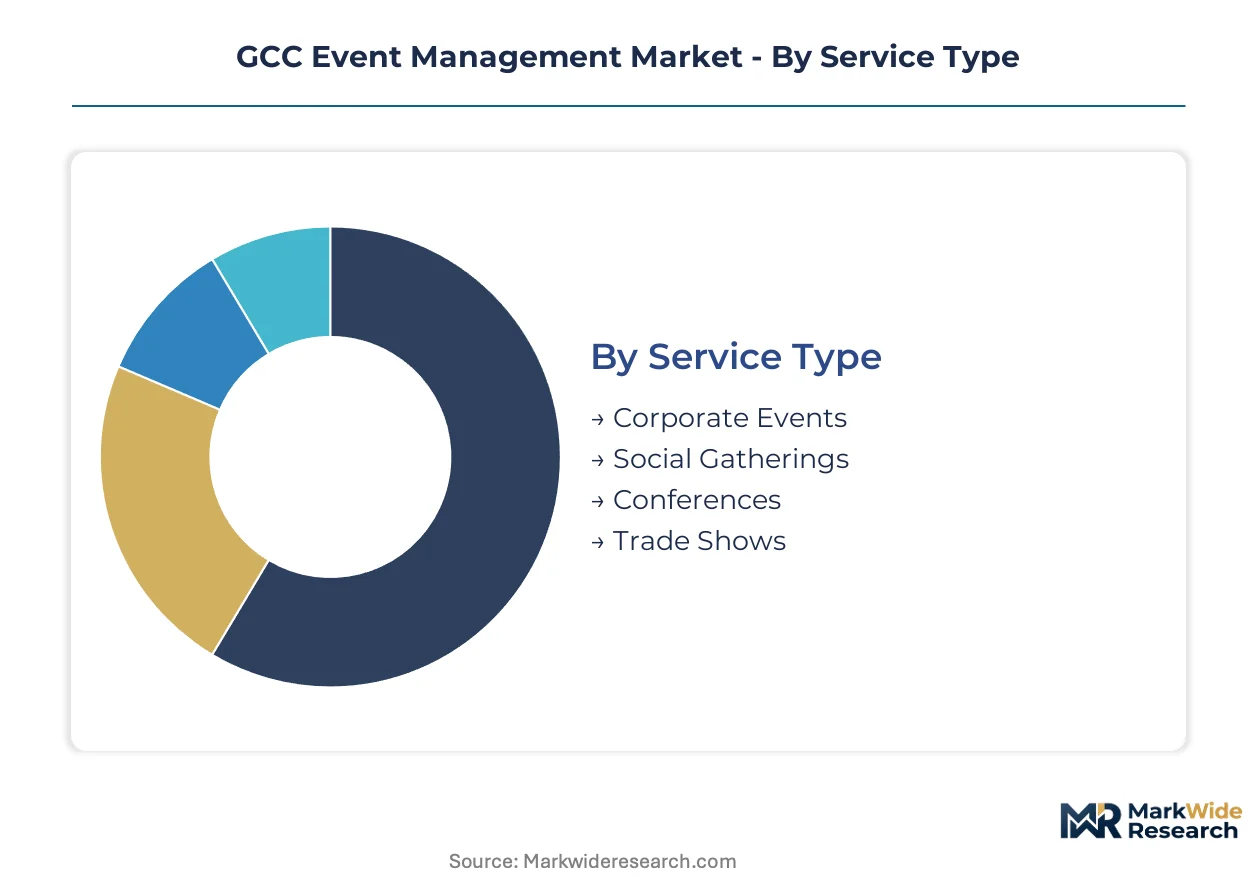
GCC event management segmentation reveals how procurement priorities diverge across client budgets, technical sophistication, and regulatory exposure. Understanding these dimensions enables vendors to align capability investments with the highest-margin service combinations.
Service Type:
Budget scale and procurement complexity drive buyer selection, with sovereign wealth fund-backed mandates commanding premium production values.
- Corporate Events:Encompass executive retreats, product launches, and internal communications requiring branded environments and confidentiality protocols. Saudi Aramco and ADNOC subsidiaries sustain recurring demand through rotating shortlists of pre-qualified production partners for technical conferences.
- Conferences:Multi-day gatherings with parallel tracks, exhibition halls, and simultaneous interpretation infrastructure. Dubai's Expo legacy sites reduce setup costs for international organizers seeking turnkey mega-event capabilities.
- Social Gatherings:Weddings, celebrations, and private functions emphasizing hospitality choreography and cultural customization.
- Trade Shows:Industry-specific exhibitions requiring booth fabrication, lead retrieval systems, and international exhibitor logistics coordination.
Volume sits with corporate events; growth tilts toward conferences as government agencies prioritize economic diversification programming.
Client Type:
Funding stability and approval timelines segment the buyer base, with public sector contracts offering scale but extended procurement cycles.
- Government Agencies:Sovereign entities under Vision 2030 and similar national transformation programs. Saudi General Entertainment Authority content approval timelines create scheduling uncertainty that compresses marketing lead times for these clients.
- Private Corporates:Enterprise procurement teams consolidating preferred vendor relationships across multiple event categories through annual framework agreements.
- Educational Institutions:Universities and research centers requiring academic conference infrastructure and student-facing programming.
- Non-Profit Organizations:Mission-driven gatherings with constrained budgets and volunteer-dependent execution models.
Revenue concentrates with government agencies; margin expansion favors private corporates consolidating vendor relationships.
Delivery Model:
Technical capability requirements determine competitive positioning, with hybrid infrastructure demanding simultaneous mastery of physical and broadcast production.
- Hybrid Events:Simultaneous physical and digital audience reach through integrated broadcast-grade production suites and conventional hospitality operations. This segment is expanding most quickly as venues in Dubai and Riyadh invest in permanent hybrid-ready assets.
- On-Site Events:Traditional physical gatherings requiring venue procurement, vendor orchestration, and real-time operational control.
- Virtual Events:Fully digital experiences leveraging cloud-based platforms for registration, analytics, and audience engagement.
- Pop-Up Experiences:Temporary activations in non-traditional spaces requiring rapid deployment and regulatory navigation.
On-site events retain volume dominance; hybrid models capture the steepest expansion trajectory as clients demand expanded addressable audience reach.
Technology:
Recurring revenue potential and data asset accumulation differentiate technology segments from project-based service revenue.
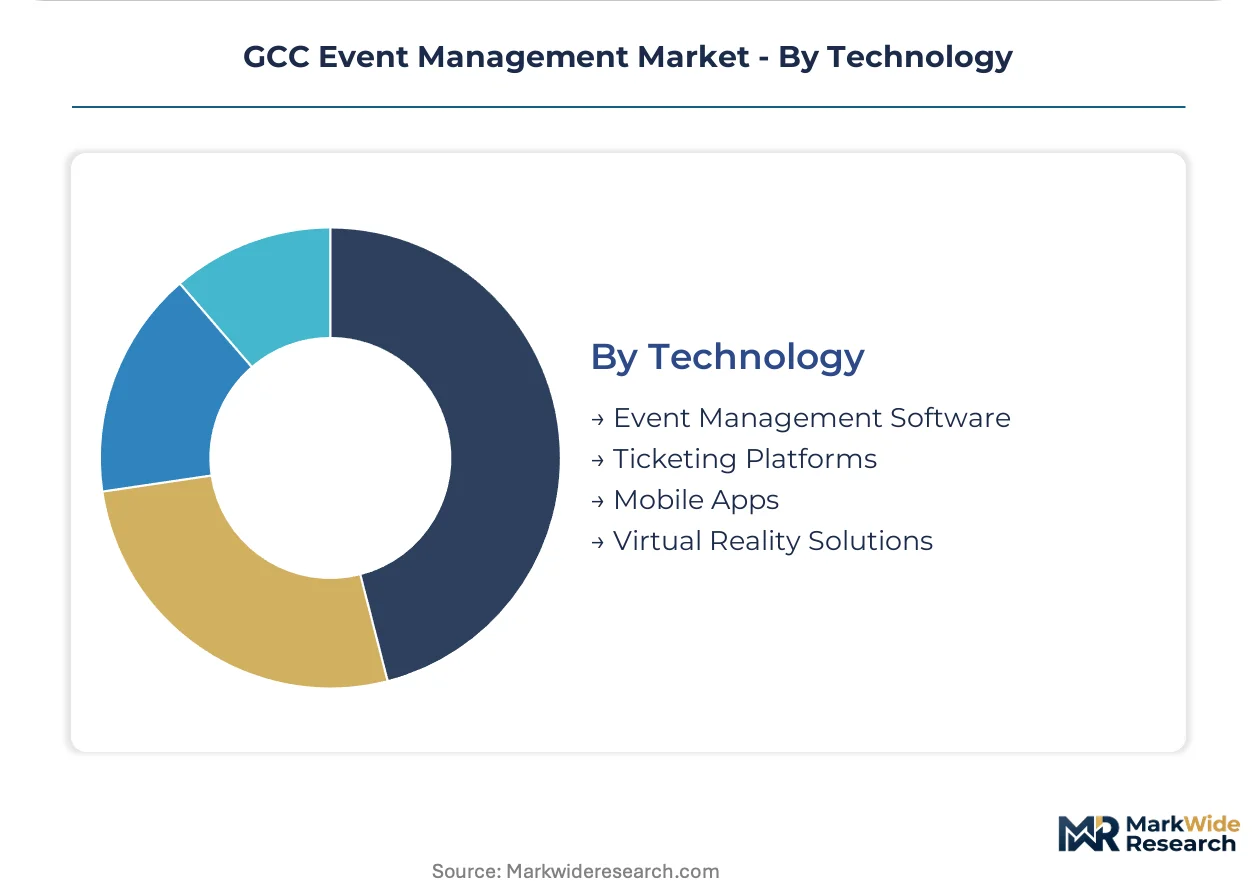
- Event Management Software:SaaS tools for registration, analytics, and real-time audience engagement compressing operational overhead for mid-tier event producers. Concentrated margin pools emerge through recurring licensing and data analytics subscriptions.
- Virtual Reality Solutions:Spatial computing and extended reality platforms integrating with conventional stage design for immersive presenter environments.
- Ticketing Platforms:Transactional infrastructure with fraud prevention, dynamic pricing, and secondary market control capabilities.
- Mobile Apps:Attendee-facing interfaces for agenda management, networking, and real-time communication.
Deployment scale favors event management software; innovation investment clusters around virtual reality solutions as corporate clients in Riyadh and Dubai adopt immersive tools for shareholder meetings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived sovereign wealth anchors event infrastructure investment across the Gulf Cooperation Council. Hydrocarbon revenues fund permanent venue construction and festival programming at scale unavailable elsewhere in the Middle East. Government transformation programs redirect these resources toward cultural sector expansion and economic diversification.
Saudi Arabia
Riyadh's entertainment district construction and MDLBEAST's festival operations drive demand for technical production capabilities. The Saudi General Entertainment Authority mandates content approval timelines that compress marketing schedules for international performances. Jeddah and the Eastern Province host corporate gatherings serving Aramco subsidiaries and petrochemical joint ventures.
United Arab Emirates
Dubai's Expo legacy sites provide turnkey mega-event infrastructure reducing setup costs for international organizers. MOHAP health and safety mandates require real-time crowd monitoring systems and automated emergency protocols at licensed venues. Abu Dhabi anchors Flash Entertainment's festival-scale operations across multiple emirates through integrated production capabilities.
Qatar
Post-World Cup stadium assets convert to concert and exhibition venues serving regional touring productions. The country's national tourism authority oversees venue licensing and international content approval processes. Doha's hospitality cluster concentrates corporate event demand from LNG sector headquarters and sovereign wealth fund portfolio companies.
Kuwait
Corporate event demand exceeds dedicated convention infrastructure supply, creating first-mover opportunities for regional operators. The country's investment authority sponsors economic diversification forums requiring international-standard production values. Kuwait City hotels and exhibition halls require substantial retrofit investment to meet updated crowd density and emergency evacuation standards.
Bahrain
Financial services sector conferences sustain premium corporate event demand with limited local production capacity. The country's central bank and sovereign wealth fund host recurring investor gatherings requiring simultaneous interpretation and broadcast infrastructure. Manama's hospitality operators compete for regional business through competitive venue pricing against Dubai and Riyadh alternatives.
GCC Event Management Market Competitive Landscape
Global touring operators compete with regional production champions across artist access and venue control dimensions. Market structure concentrates around sovereign-funded mandates and corporate framework agreements rather than fragmented spot-buying. Three archetypes dominate: integrated festival producers with permanent venue assets, touring logistics specialists leveraging international artist relationships, and SaaS-enabled platform operators capturing recurring technology revenue. Competitive moves center on venue management contract acquisition and hybrid broadcast capability deployment.
Within the integrated production tier, Flash Entertainment anchors Abu Dhabi-based operations across multiple emirates, while MDLBEAST exemplifies Saudi-first festival infrastructure built around Riyadh headquarters. Live Nation Middle East occupies the touring logistics position, connecting international artist availability with Gulf venue networks. These three represent distinct capability configurations responding to Vision 2030 entertainment mandates and hybrid delivery model requirements.
| Leading Market Players |
|---|
| Flash Entertainment |
| Global Event Management |
| SELA |
| Mosaic Live |
| Plan3 Media |
| MDLBEAST |
| Platinumlist |
| Max Events Dubai |
| Live Nation Middle East |
| Others |
Pricing and Supply Chain Analysis
Sovereign wealth fund procurement offices and enterprise framework agreements concentrate buying power across Saudi Arabia and the UAE, compressing spot-market premiums while elevating subscription-based SaaS pricing for event management platforms. Project-based production services face margin erosion as annual vendor consolidation replaces fragmented purchasing.
Pricing Analysis
Service bundling separates turnkey production packages from unbundled venue-only rentals across Dubai and Riyadh markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier under ISO 20121 sustainable event standards and after-sales technical support inclusion. Pricing pressure stems from enterprise procurement teams consolidating preferred vendor relationships through rotating shortlists. Government agencies under Vision 2030 mandates demonstrate lowest price sensitivity; mid-tier corporate event producers face highest cost compression.
Supply Chain Analysis
Saudi General Entertainment Authority local-content guidelines and UAE MOHAP procurement preferences reshape sourcing toward regional staging equipment distributors and certified safety consultants. LED wall systems and line-array audio hardware draw from Germany, China, and South Korea manufacturing bases. Rigging specialists and broadcast engineers represent single-source vulnerability due to limited GCC training pipeline output. Distribution runs through Flash Entertainment and MDLBEAST integrated production networks rather than independent equipment brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around operators with permanent hybrid-ready venue assets as enterprise procurement consolidation eliminates fragmented independent agencies.
For Market Incumbents: Cement control over Riyadh and Dubai venue management contracts through embedded broadcast infrastructure investments. Threat from cloud-based SaaS entrants compressing operational overhead demands backward integration into proprietary event management software development. Priority lever: certified safety officer staffing to meet MOHAP's updated emergency protocol mandates. For New Entrants and Emerging Players: The premium-to-economy price gap in Kuwait and Bahrain corporate segments offers white-space entry before regional champions establish permanent presence. Most penetrable geography: Kuwait City convention infrastructure requiring substantial retrofit investment. Go-to-market angle: ISO 20121 carbon-neutral certification bundled with technical production services. For Investors and Strategic Acquirers: The window for entry favors integrated festival producers with Riyadh or Abu Dhabi venue control before Vision 2030 entertainment mandates fully deploy. Long-term viability hinges on hybrid broadcast capability deployment and recurring SaaS revenue streams. Acquisition target archetype: mid-tier event management software platforms with data analytics subscriptions. Signal to watch: Saudi General Entertainment Authority content approval timeline compression indicating regulatory maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Infrastructure Deployment | Permanent broadcast-grade production suites at Dubai Expo legacy sites reduce international organizer setup costs. |
| Backward Integration into Software | Captive event management SaaS development locks in recurring licensing revenue from corporate framework agreements. |
| Venue Management Contract Acquisition | Control of Riyadh entertainment district assets anchors MDLBEAST's festival-scale production capabilities. |
| ISO 20121 Certification Investment | Sustainable event standards enable premium positioning as ESG disclosure requirements tighten across Gulf sovereign wealth portfolios. |
| Specialized Technical Labor Pipeline | Regional training partnerships for broadcast engineers address scarcity premiums disrupting multi-venue touring logistics. |
Research Methodology
Independent corroboration across event production executives, venue procurement officers, and regulatory compliance consultants underwrites the qualitative findings. Primary interviews with Flash Entertainment operations directors, MDLBEAST technical production leads, and Live Nation Middle East touring logistics managers combined with secondary validation from Saudi General Entertainment Authority permitting disclosures, UAE MOHAP safety mandate updates, and Expo legacy site utilization reports. Bottom-up project pipeline tracking and top-down sovereign wealth fund expenditure analysis triangulate market sizing.
Comparable historical reference periods anchored the forecast window to pre-pandemic physical event baselines and post-2020 hybrid adoption inflection. Segmentation modeling across service type, client type, delivery model, and technology deployment complexity generated discrete growth trajectories. CAGRs were derived from vendor revenue run-rates and venue capacity utilization curves. Industry-specific inputs include MDLBEAST festival attendance capacities and Dubai Expo site booking backlogs.
Inputs from Saudi General Entertainment Authority and UAE MOHAP regulatory filings were available through the study window; gaps in Qatar and Bahrain entertainment authority disclosure introduce uncertainty bands around smaller-market projections. Forecasts reflect assumptions regarding Vision 2030 funding continuity and hybrid infrastructure depreciation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Events and Conferences
UAE Event Management Market
Events and Conferences
Saudi Arabia Event Services Market
Events and Conferences
Canada Wedding Services Market
Events and Conferences
Corporate Event Market
Events and Conferences
Canada Event Services Market
Events and Conferences
Event Tourism Market
Events and Conferences
Europe Discount Events and Experiences Market
Events and Conferences
Saudi Arabia MICE Market
Events and Conferences
Asia-Pacific Wedding Services Market
Events and Conferences
Global Exhibition Organizing Market
Events and Conferences
Mexico Event Services Market
Events and Conferences
Saudi Arabia Event Management Market
Events and Conferences
MICE Market
Events and Conferences
Trade Show Services Market
Events and Conferences
Europe Event Logistics Market
Events and Conferences
Corporate Event Planner Market