
 Europe Glamping Market | 2026-2036
Europe Glamping Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Glamping Market Insights
Online travel aggregators and direct-to-consumer booking platforms is reconfiguring how European glamping operators reach guests. Huttopia leverages its vertically integrated site ownership model across France and Benelux. Eco Retreats anchors its positioning through off-grid energy systems and conservation-area partnerships. Canopy & Stars differentiates via curated rural property networks and editorial content strategy.
Europe glamping encompasses upscale outdoor accommodation combining permanent tent structures, cabins, or modified vehicles with hotel-grade amenities including en-suite plumbing, climate control, and furnished interiors, primarily serving tourists seeking nature immersion without comfort sacrifice. Safari tents and treehouses command premium nightly rates due to higher construction costs and limited site availability. The wellness purpose segment expands fastest as yoga retreats and thermal spa adjacencies proliferate across Portugal and Slovenia. Families represent the largest demographic pool, though couples generate superior per-stay margins through extended bookings and ancillary dining purchases.
EU Green Deal building standards and national planning regulations in France, Spain, and Italy constrain new site approvals while mandating renewable energy integration and wastewater treatment. EMAS eco-management certification and national tourism quality labels in Germany and Austria create tiered market access barriers that favor established operators with compliance infrastructure. Stakeholders must monitor evolving country-level rural zoning amendments and carbon accounting rules for temporary structures.
Market Dynamics
EU Green Deal sustainability mandates are compressing site development timelines while elevating capital requirements for new entrants, creating asymmetric compliance burdens across France, Spain, and Italy.
Growth Catalysts
- Wellness tourism operators:Yoga retreat and thermal spa adjacencies in Portugal and Slovenia are pulling dedicated infrastructure investment into rural zones previously bypassed by hospitality development.
- EMAS eco-management certification:German and Austrian national tourism quality labels create tiered market access that rewards operators with established compliance infrastructure and documented carbon accounting.
- Off-grid energy systems:Solar-battery hybrid installations and rainwater harvesting technologies are reducing operational dependency on rural grid extensions in conservation-area partnerships.
Market Restraints
- Timber and engineered wood input costs:Safari tent platforms and treehouse structural elements face volatile pricing from Nordic and Baltic supply concentration.
- Rural zoning amendment delays:France's departmental planning authorities and Spain's autonomous community regulators impose 18-36 month approval cycles for temporary structure permits.
- Substitute accommodation pressure:Boutique agritourism properties and design-forward hostels in Tuscany and Andalusia capture overlapping demand segments at lower nightly rates.
Strategic Opportunities
- Slovenia's Soča Valley:Underdeveloped glamping infrastructure relative to outdoor recreation demand creates first-mover positioning for wellness-anchored concepts.
- EU Green Deal building standards:Renewable energy integration mandates favor operators with captive technical capabilities for photovoltaic and geothermal system deployment.
- Direct-to-consumer booking platforms:Proprietary reservation systems are bypassing online travel aggregator commissions and capturing guest data for ancillary service targeting.
Industry Challenges
- Conservation-area partnership negotiations:Site access agreements with France's Parcs Naturels Régionaux and Italy's Riserve Naturali require 24-48 month relationship cultivation.
- Climate control system integration:HVAC specification for canvas and timber structures demands specialized mechanical engineering absent from standard hospitality construction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Glamping Market |
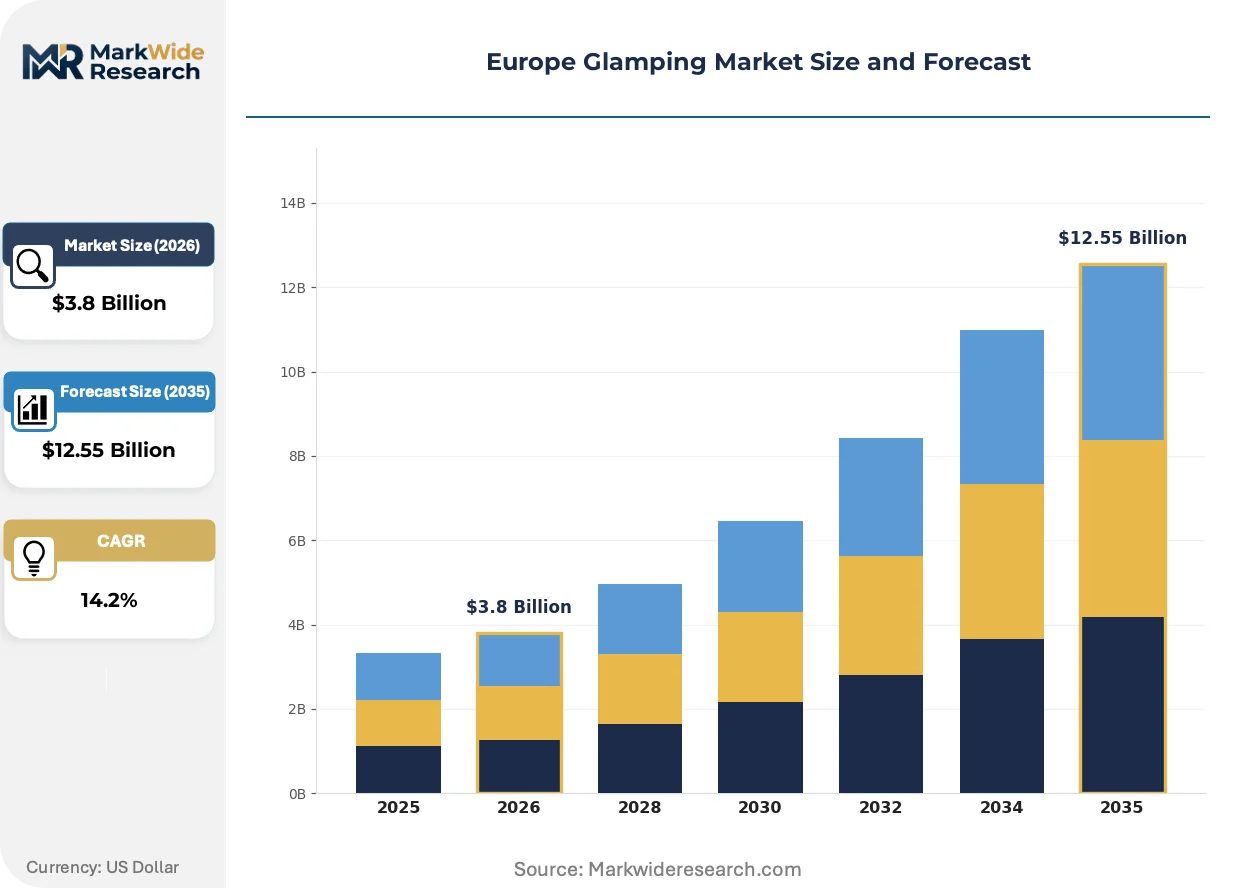
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Yurts, Safari Tents, Treehouses, Airstreams Purpose: Leisure, Eco-Tourism, Corporate Retreats, Wellness Facilities Offered: Private Bathrooms, Kitchenettes, Heating, Air Conditioning Target Demographic: Families, Couples, Adventure Seekers, Groups |
| Companies Covered | CampSolutions, Eco Retreats, Bushtec Safari, Canopy & Stars, Wigwam Holidays, Sawday's Canopy & Stars Ltd., Glamphouse, Glamping Life, Huttopia, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Glamping Market Trends and Innovations
Technology convergence and regulatory stringency are compressing the gap between temporary outdoor structures and permanent hospitality assets, reshaping capital deployment and operational capability requirements.
Photovoltaic-thermal hybrid systems are hybridizing energy provision for off-grid sites, combining electricity generation with hot water production in single rooftop or ground-mounted arrays. Portuguese and Slovenian wellness retreat operators are adopting these systems fastest, driven by thermal spa adjacency requirements. The technology is hybridizing site selection criteria, enabling viable development in locations previously excluded by grid connection costs.
France's national planning regulations and Italy's Codice dei Beni Culturali are mandating archaeological impact assessments and landscape integration studies for rural tourism developments. These requirements extend project timelines by 12-18 months but elevate barrier-to-entry for speculative operators. Spanish glamping concepts in Extremadura and Aragón are responding through heritage architecture partnerships that satisfy aesthetic compliance while differentiating guest experience.
Booking behavior is fragmenting across platform types, with family segments clustering on online travel aggregators for price transparency while couples migrate to curated direct channels for experience customization. France's Dordogne operators report 40% of extended-stay reservations originating from Instagram-driven discovery rather than traditional search. This channel rotation is most pronounced among 35-50 year-old urban professionals seeking multi-night rural immersion without packaged tour constraints.
Europe Glamping Market Segmentation
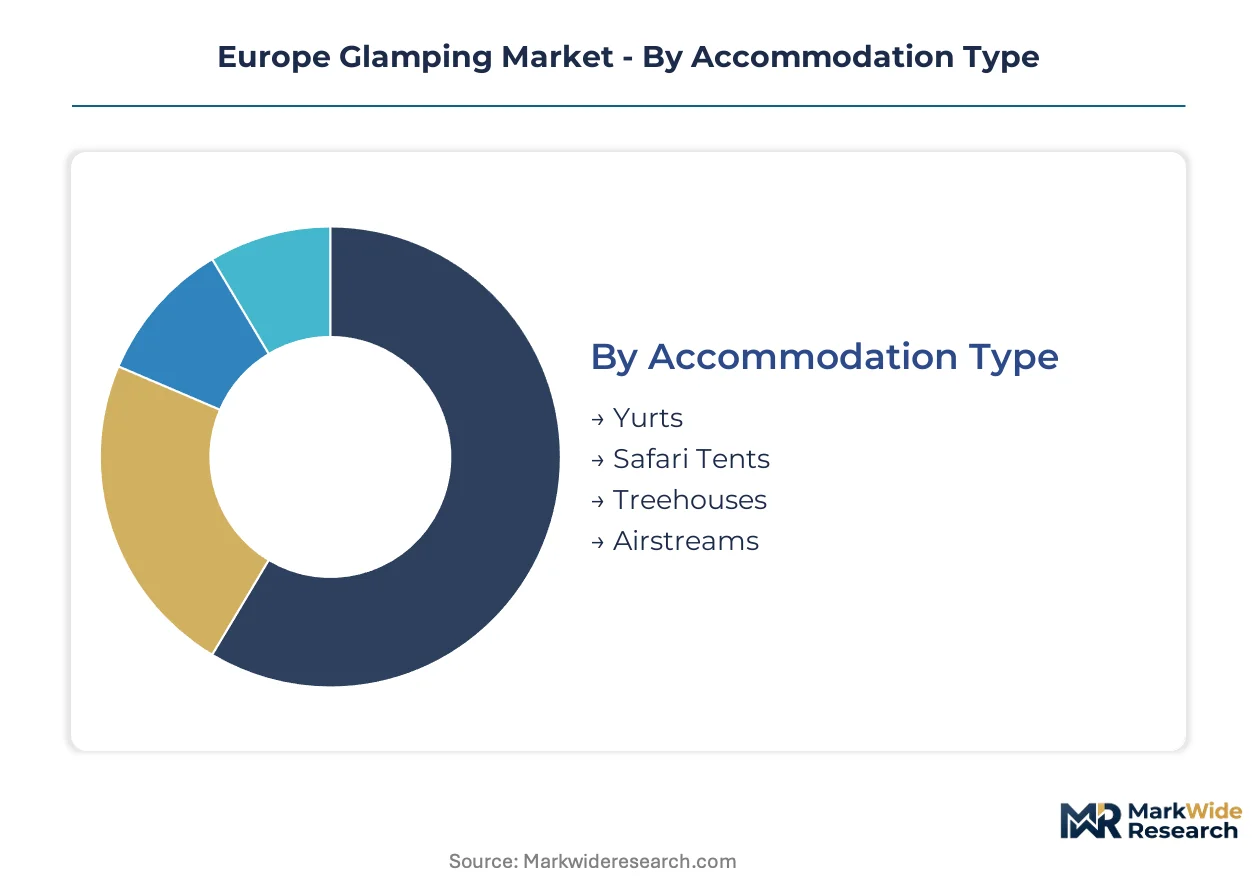
Glamping operators configure their inventory and service layers around distinct guest profiles and site constraints. Segmentation reveals where capital concentrates and which accommodation formats command rate premiums across European conservation zones.
Accommodation Type:
Safari tents and treehouses anchor the premium tier through construction complexity and limited site availability, while yurts and Airstreams scale across mid-market positioning.
- Safari Tents:Canvas structures mounted on engineered timber platforms with en-suite plumbing and climate control. Demand concentrates in France's Dordogne valley where Parcs Naturels Régionaux partnerships restrict permanent construction. EU Green Deal building standards elevate capital requirements for thermal insulation and renewable energy integration.
- Treehouses:Elevated timber pods requiring specialized structural engineering and arborist consultation for conservation-area compliance. Portugal's Alentejo region and Slovenia's Soča Valley attract wellness retreat operators seeking differentiated positioning through forest canopy immersion.
- Yurts:Circular tent structures with radial frame construction, prevalent across Spanish Extremadura and Italian agritourism clusters.
- Airstreams:Retrofitted aluminum travel trailers repurposed as stationary accommodation, concentrated in coastal Portugal and French Atlantic sites.
Established volume favors safari tents; emerging adoption favors treehouses.
Purpose:
Guest motivation determines ancillary revenue potential and booking duration, with wellness and corporate segments extending average length of stay beyond leisure baselines.
- Wellness:Yoga retreat and thermal spa adjacencies in Portugal and Slovenia. Off-grid energy systems and conservation-area partnerships enable positioning in zones previously excluded from hospitality development.
- Leisure:Short-break rural immersion for urban professionals, concentrated in France's Provence clusters and Italian Tuscany.
- Eco-Tourism:EMAS eco-management certification and national tourism quality labels in Germany and Austria create tiered market access.
- Corporate Retreats:Team-building and off-site meeting configurations, expanding in Benelux and northern France.
Leisure dominates reservation volume; wellness climbs the fastest.
Facilities Offered:
Amenity layering separates premium positioning from budget-adjacent alternatives, with climate control and private bathrooms now baseline expectations rather than differentiators.
- Private Bathrooms:En-suite composting or conventional plumbing systems, mandatory for German and Austrian quality label compliance.
- Kitchenettes:Self-catering configurations extending length of stay in French and Spanish family segments.
- Heating:Wood-burning stoves and underfloor systems for shoulder-season occupancy in northern Europe.
- Air Conditioning:HVAC specification for canvas structures, demanding specialized mechanical engineering absent from standard hospitality construction.
Private bathrooms command rate premiums; air conditioning adoption accelerates in Mediterranean markets.
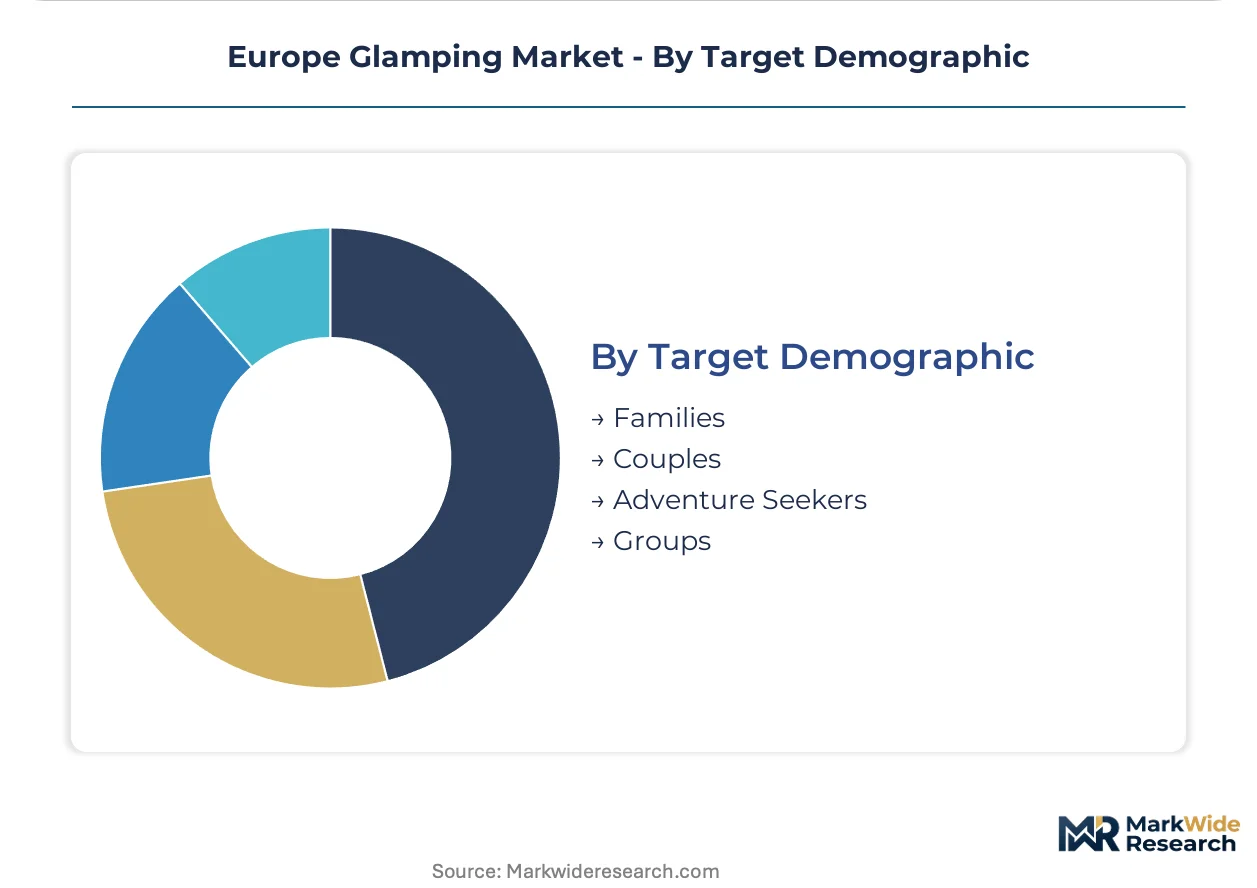
Target Demographic:
Family units drive occupancy volume while couples generate superior per-stay margins through extended bookings and ancillary dining purchases.
- Families:Multi-bed configurations and activity programming, concentrated in French departmental clusters during school holiday periods.
- Couples:Romantic positioning with privacy emphasis, generating 40% of extended-stay reservations in Dordogne through Instagram-driven discovery.
- Adventure Seekers:Proximity to cycling, climbing, and water sports infrastructure in Slovenia's Soča Valley and Portuguese Algarve.
- Groups:Multi-unit bookings for celebrations and reunions, expanding in Spanish Extremadura heritage architecture partnerships.
Family segments cluster on online travel aggregators; couples migrate to curated direct channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Channel Tunnel and high-speed rail corridors connecting London, Paris, and Brussels underwrite Western Europe's concentration of glamping demand, compressing travel times for urban professionals seeking rural immersion.
France
Dordogne valley and Provence clusters attract wellness retreat operators seeking Parcs Naturels Régionaux partnerships that restrict permanent construction. EU Green Deal building standards mandate renewable energy integration and wastewater treatment for new site approvals. French departmental planning authorities impose 18-36 month approval cycles for temporary structure permits.
Spain
Extremadura and Aragón regions leverage heritage architecture partnerships to satisfy aesthetic compliance under landscape integration studies. The autonomous community regulators extend project timelines through archaeological impact assessments. Andalusian boutique agritourism properties capture overlapping demand segments at lower nightly rates.
Italy
Tuscany's leisure segment concentrates short-break rural immersion for urban professionals. The Codice dei Beni Culturali mandates landscape integration studies that extend project timelines by 12-18 months. Italian Riserve Naturali require 24-48 month relationship cultivation for conservation-area partnership negotiations.
Portugal
Alentejo region and coastal Atlantic sites attract thermal spa adjacencies and yoga retreat infrastructure investment. Off-grid energy systems enable positioning in zones previously excluded by grid connection costs. Portuguese wellness retreat operators adopt photovoltaic-thermal hybrid systems fastest.
Slovenia
Soča Valley presents underdeveloped glamping infrastructure relative to outdoor recreation demand, creating first-mover positioning for wellness-anchored concepts. The country's conservation-area partnerships enable forest canopy immersion through specialized structural engineering. Cycling, climbing, and water sports infrastructure supports adventure seeker demographics.
Europe Glamping Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated site owners and curated property networks that bypass online travel aggregator commissions. Strategic archetypes include vertically integrated operators with captive site ownership, curated network platforms with editorial content strategies, and off-grid specialists with conservation-area partnerships. Dominant competitive moves encompass proprietary reservation system deployment and heritage architecture partnerships for regulatory compliance differentiation.
Within the vertically integrated tier, Huttopia anchors French and Benelux positioning through site ownership concentration. Eco Retreats exemplifies the off-grid specialist archetype through conservation-area energy system deployment. Canopy & Stars occupies the curated network position, leveraging editorial content strategy and direct-channel guest data capture. These three entities represent the structural fault lines between asset-heavy and platform-light operating models.
| Leading Market Players |
|---|
| CampSolutions |
| Eco Retreats |
| Bushtec Safari |
| Canopy & Stars |
| Wigwam Holidays |
| Sawday's Canopy & Stars Ltd. |
| Glamphouse |
| Glamping Life |
| Huttopia |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Nordic engineered timber mills is compressing supplier bargaining power and elevating safari tent platform costs for French and Benelux operators, while simultaneously pushing mid-market glamping concepts toward standardized yurt configurations that sacrifice differentiation for procurement stability.
Pricing Analysis
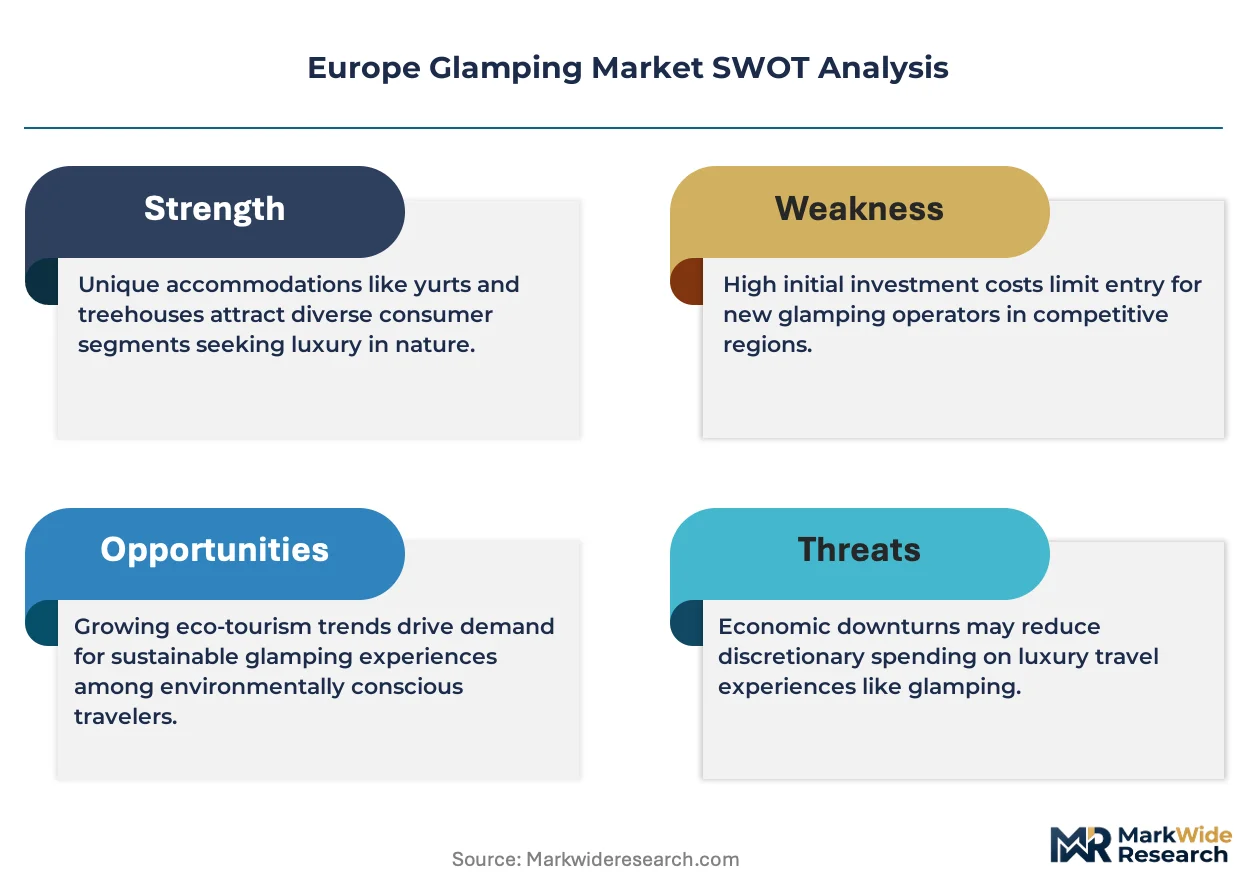
Volume-discount tiering structures separate safari tent and treehouse premiums from yurt and Airstream mid-market positioning, with EMAS certification in Germany and Austria creating a quality-grade price premium that uncertified operators cannot match. Price differentiation rests on renewable energy integration compliance and conservation-area partnership access, with boutique agritourism substitutes in Tuscany and Andalusia intensifying cost compression in the leisure segment. Corporate retreat buyers exhibit lowest price sensitivity due to per-diem budgeting, while family segments cluster on online travel aggregators and drive rate transparency pressure.
Supply Chain Analysis
Tariff exposure between Baltic states and Western European assembly sites dominates supply chain risk planning, as engineered timber and canvas membrane inputs concentrate in Estonia, Latvia, and Lithuania before final fit-out in France and Portugal. Raw material dependencies center on FSC-certified structural timber, weather-resistant canvas polymers, and photovoltaic-thermal hybrid components. Single-source vulnerability runs through Nordic arborist consultation networks for treehouse structural engineering. Distribution runs through direct-to-consumer booking platforms for couples and curated network aggregators for family volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as booking behavior splits between price-transparent aggregators and experience-curated direct channels, creating dual-path positioning for operators with differentiated site control or editorial content capabilities.
For Market Incumbents: Pre-empt substitute accommodation pressure from Tuscan boutique agritourism by securing exclusive Parcs Naturels Régionaux partnerships in France's Dordogne valley, locking in site scarcity that design-forward hostels cannot replicate. Deepen backward integration into photovoltaic-thermal hybrid system deployment to capture EU Green Deal compliance margins that new entrants lack capital to match.
For New Entrants and Emerging Players: Slovenia's Soča Valley presents underdeveloped glamping infrastructure relative to outdoor recreation demand, enabling first-mover wellness-anchored positioning before established operators consolidate conservation-area partnerships. Target thermal spa adjacencies with off-grid energy system capabilities as the most penetrable segment, leveraging Portuguese regulatory familiarity with renewable mandates as a go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across treehouse and safari tent premium tiers due to specialized structural engineering and arborist consultation requirements. Long-term viability favors vertically integrated site owners with captive technical capabilities over platform-light curated networks. Watch for rural zoning amendment acceleration in France's departmental planning authorities as the signal for approval timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Conservation-Area Partnership Securement | Parcs Naturels Régionaux agreements in France create 24-48 month barriers against replication. |
| Photovoltaic-Thermal Hybrid Deployment | Portuguese wellness operators adopt fastest, enabling grid-independent site selection. |
| Direct-to-Consumer Platform Development | Proprietary reservation systems bypass online travel aggregator commissions and capture guest data. |
| Heritage Architecture Partnership | Spanish Extremadura operators satisfy Codice dei Beni Culturali compliance while differentiating experience. |
| EMAS Eco-Management Certification | German and Austrian quality labels reward established operators with tiered market access. |
Research Methodology
The analysis maps accommodation type, purpose, facilities offered, and target demographic segments, each validated through site development directors, conservation-area partnership negotiators, renewable energy system integrators, and online travel aggregator category managers. Primary interviews combined with secondary validation from EU Green Deal regulatory filings, national tourism quality label databases, and Parcs Naturels Régionaux partnership records. Bottom-up site inventory modeling and top-down tourism expenditure triangulation anchored volume estimates.
Assumption-sets held EU Green Deal building standard trajectory and rural zoning amendment timelines fixed across the projection horizon, while varying wellness tourism operator investment intensity and substitute accommodation pricing. Segmentation dimensions modeled include accommodation format, guest purpose, amenity tier, and demographic cluster alongside conservation-area partnership status. CAGRs derived from compounding annual site capacity additions and rate trajectory assumptions, with thermal spa adjacency penetration and off-grid energy adoption as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated French operators or Portuguese wellness specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
RV Rental Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
North America Glamping Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market