
 Asia-Pacific Glamping Market | 2026-2036
Asia-Pacific Glamping Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Glamping Market Insights
Australia's luxury tent manufacturing base is narrowing as domestic operators scale fabrication capabilities for export across Southeast Asia. Paperbark Camp leverages its coastal New South Wales location to anchor premium eco-lodge design standards regionally. Hoshinoya Fuji competes through minimalist architectural integration with volcanic landscapes. Natra Bintan differentiates via private-island configurations that control exclusive access channels.
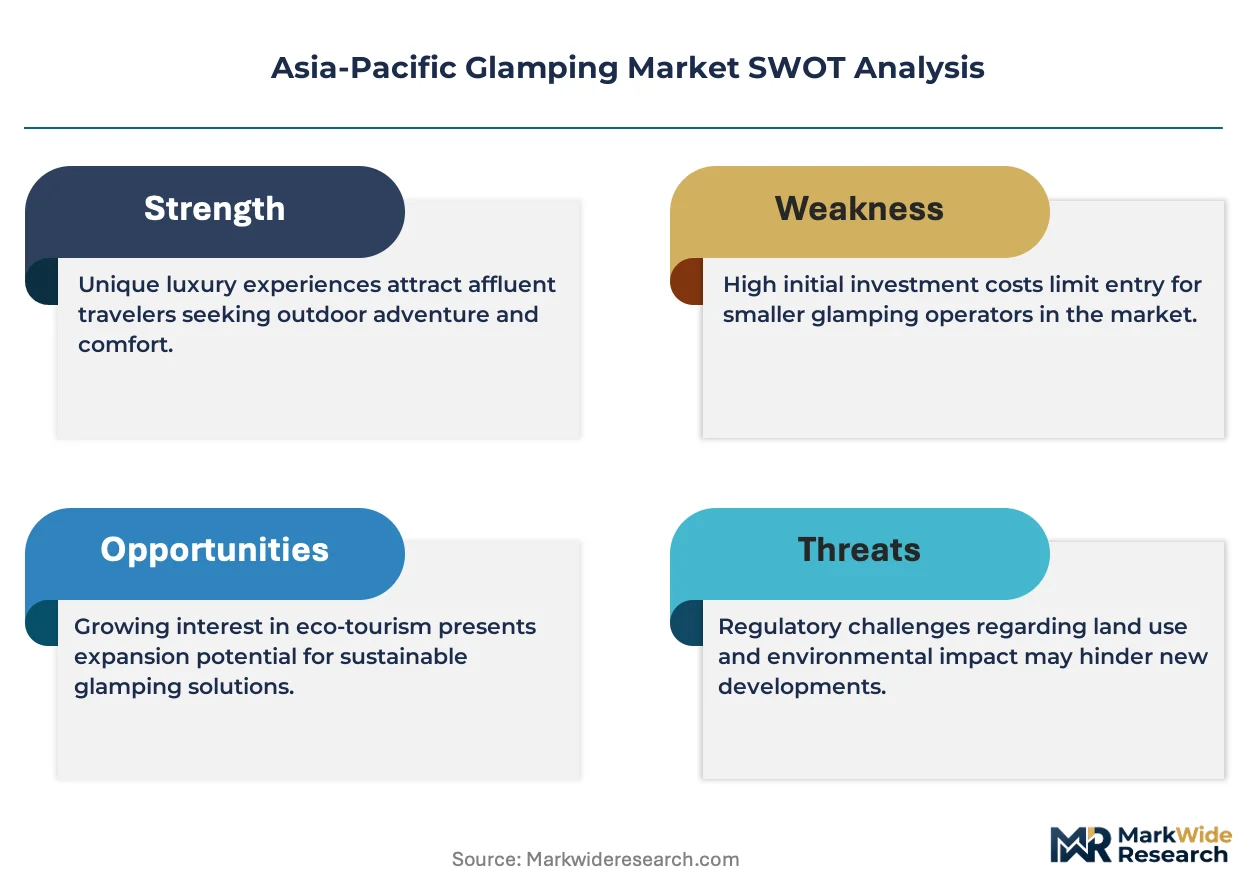
Glamping denotes semi-permanent upscale outdoor accommodation combining weather-resistant fabric or timber structures with hotel-grade amenities including climate control, en-suite facilities, and curated experiential programming; primary commercial purpose centers on capturing traveler willingness to pay premium rates for nature immersion without utility sacrifice. Tents and treehouses command the widest margin pools where material innovation in tensile membranes reduces seasonal maintenance costs. Online travel agencies and direct booking channels are diverging in commission structures, with property operators increasingly investing in proprietary reservation platforms to retain guest data and reduce intermediary dependency.
Thailand's Ministry of Tourism and Sports, Indonesia's Ministry of Environment and Forestry, and Japan's METI collectively shape site licensing, environmental impact thresholds, and hospitality classification standards that determine operational legality and tax treatment. Australia's EcoCertification program from Ecotourism Australia creates a voluntary but commercially consequential quality signal that influences OTA algorithmic ranking and corporate travel procurement. Stakeholders must monitor evolving coastal setback regulations and carbon-offset mandates that will determine which existing properties qualify for license renewal versus forced retrofit or closure.
Market Dynamics
Domestic leisure travelers across Southeast Asia are accelerating bookings for luxury tent accommodations, while Australia's national tourism infrastructure policies incentivize eco-certified lodging developments. This dual pressure from demand-side preference shifts and supply-side certification mandates is compressing development timelines and reshaping competitive positioning across the region.
Growth Catalysts
- Australia's EcoCertification program:Ecotourism Australia's voluntary quality signal influences OTA algorithmic ranking and corporate travel procurement, creating commercial incentives for operators to upgrade facilities.
- Japan's METI hospitality standards:METI's classification frameworks for experiential lodging legitimize premium pricing structures and clarify operational legality for alpine prefecture developments.
- Tensile membrane material innovation:Advanced weather-resistant fabrics reduce seasonal maintenance costs for tent and treehouse configurations, widening margin pools for operators.
Market Restraints
- Coastal setback regulatory tightening:Indonesia's Ministry of Environment and Forestry mandates increasing buffer zones that disqualify existing waterfront sites from license renewal without costly relocation.
- Fabric supply concentration:Technical textile production for luxury tent membranes clusters in a narrow supplier base, exposing operators to input cost volatility and extended lead times.
- Utility infrastructure gaps:Remote island and alpine locations lack grid connectivity, forcing capital-intensive off-grid power and water systems that extend payback periods.
Strategic Opportunities
- Thailand's secondary island destinations:Domestic operators are expanding beyond Phuket and Koh Samui into underpenetrated archipelagos where land costs remain subdued and exclusivity premiums hold.
- Carbon-offset mandate alignment:Australia's emerging carbon-offset requirements for tourism licensing create first-mover advantages for properties with pre-certified renewable energy and waste systems.
- Direct booking platform investment:Proprietary reservation systems are displacing OTA dependency, enabling guest data retention and commission structure renegotiation across Southeast Asian markets.
Industry Challenges
- Experiential programming talent scarcity:Curated nature-immersion activities require guides with dual competencies in hospitality and ecology, a skill combination with limited training pipeline capacity.
- Multi-agency licensing complexity:Indonesia's Ministry of Tourism and Sports and Ministry of Environment and Forestry maintain overlapping jurisdiction, creating compliance timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Glamping Market |
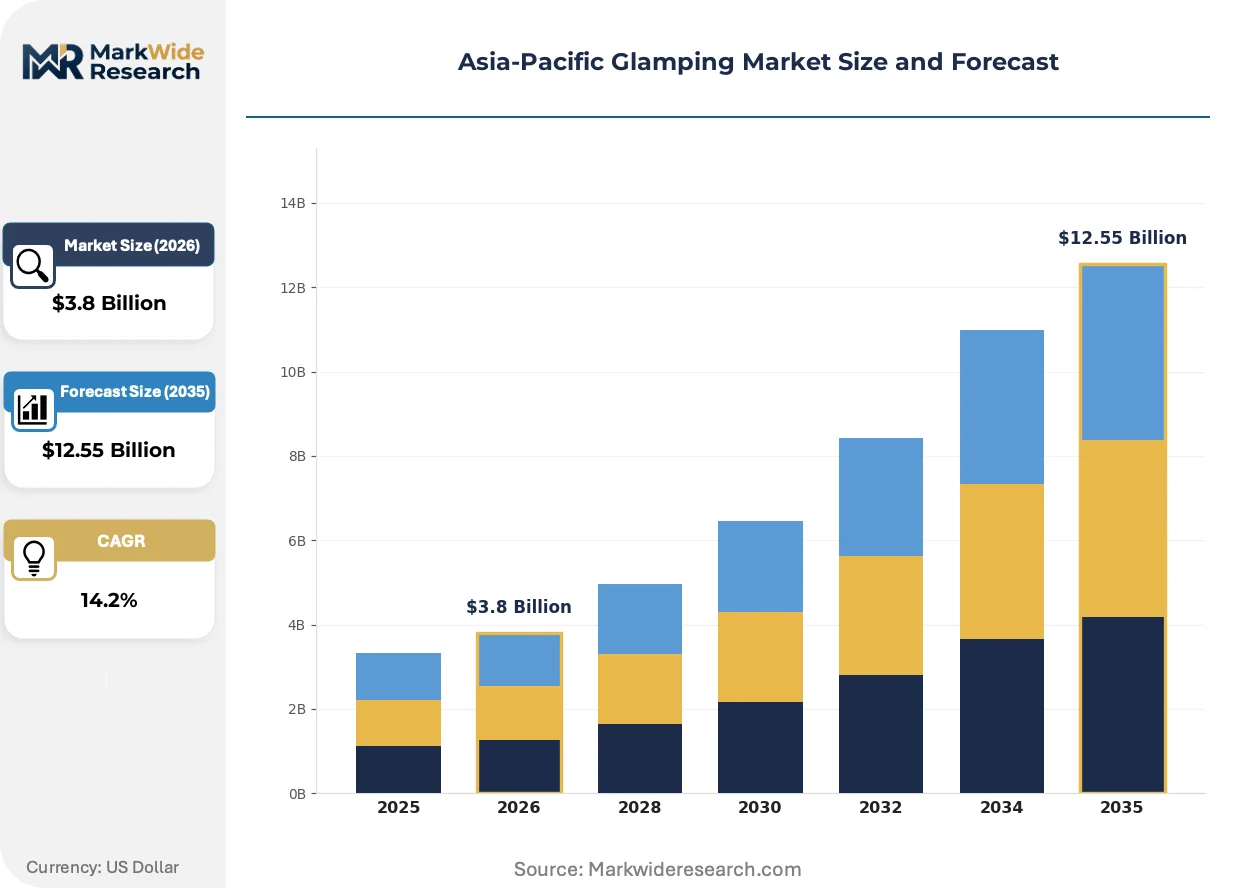
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Tents, Yurts, Cabins, Treehouses Experience Level: Luxury, Mid-range, Budget, Family-Oriented Booking Channel: Online Travel Agencies, Direct, Travel Agents, Mobile Apps Target Audience: Couples, Families, Solo Travelers, Adventure Seekers |
| Companies Covered | The Glamping Company Australia, Paperbark Camp, Tanja Lagoon Camp, Hoshinoya Fuji, Natra Bintan, Treehouse Villas Thailand, Jaisalmer Desert Glamping, Wayand Wild, Glamping Society, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Glamping Market Trends and Innovations
Material science breakthroughs and regulatory certification pressures are converging to reshape how semi-permanent upscale outdoor accommodations are designed, booked, and experienced across the Asia-Pacific region.
Smart climate control systems integrated with tensile membrane structures are digitizing guest experience management. Resort operators in Indonesia's resort islands are deploying IoT-enabled HVAC and lighting at scale. This convergence is digitizing operational oversight and compressing staff-to-guest ratios without service degradation.
Thailand's Ministry of Tourism and Sports is tightening site licensing thresholds for coastal developments. The industrial consequence is a permit bottleneck forcing operators toward inland or elevated terrain configurations. Boutique properties in Krabi and Phang Nga provinces are responding with cliffside and mangrove-adjacent designs that satisfy setback requirements while preserving experiential differentiation.
Corporate travel procurement teams are embedding EcoCertification status as a mandatory filter in vendor selection. Direct booking channels are displacing traditional OTA relationships for certified properties. This behavioral shift is most visible in Australia's corporate retreat and incentive travel segments, where sustainability credentials determine shortlist inclusion before price negotiation begins.
Asia-Pacific Glamping Market Segmentation
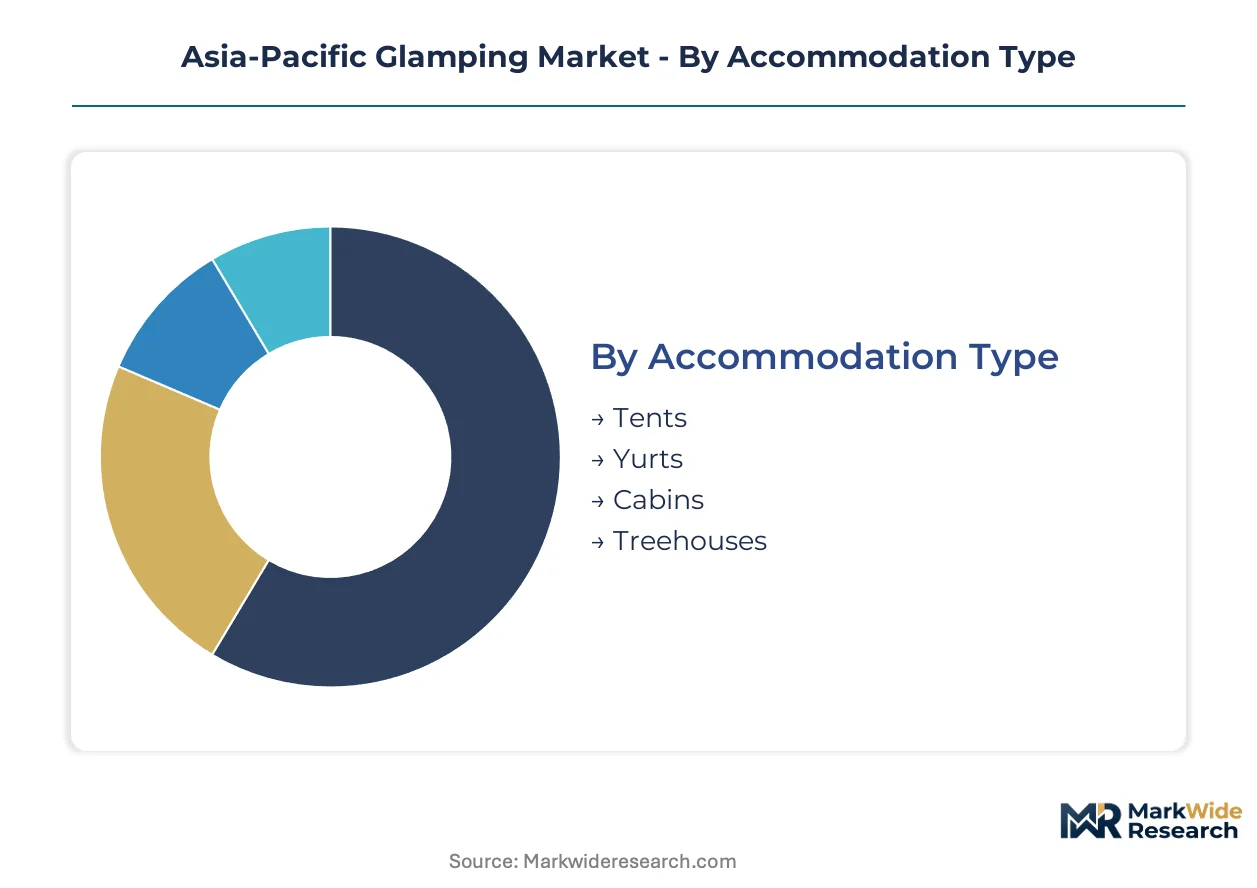
Segmentation in the Asia-Pacific glamping market reveals divergent operational economics across accommodation formats and booking channels. Operators configure service intensity, maintenance schedules, and amenity provisioning differently for each segment, directly affecting margin profiles and capital deployment priorities.
Accommodation Type:
After-sales service intensity varies sharply across structure types, with fabric-based accommodations demanding seasonal membrane replacement and timber configurations requiring structural integrity monitoring.
- Tents:Tensile membrane structures with weather-resistant fabric enclosures dominate Indonesia's resort islands and Thailand's coastal provinces. Material innovation in polymer coatings reduces maintenance cycles while sustaining premium rate capture in high-humidity environments.
- Treehouses:Elevated timber configurations command the widest margin pools in Japan's alpine prefectures where vertical construction navigates strict setback requirements. Engineering certification for load-bearing suspension systems adds compliance cost layers that filter out undercapitalized entrants.
- Yurts:Circular framed structures with tension-band roofing concentrate in Australia's ecotourism corridors where portability supports seasonal relocation strategies.
- Cabins:Solid-wall configurations attract extended-stay demand in Australia's hinterland developments where climate control reliability outweighs experiential novelty preferences.
By volume, tents lead across Southeast Asian markets. By growth pace, treehouses are climbing the fastest as alpine jurisdictions tighten ground-level development permits.
Experience Level:
Cost tier stratification determines amenity density and staff-to-guest ratios, with luxury properties deploying dedicated experience curators while budget configurations automate service touchpoints.
- Luxury:Climate-controlled interiors with en-suite facilities and curated programming command rate premiums exceeding 300% above budget alternatives in Japan's Fuji Five Lakes corridor. Corporate procurement teams embed this tier as mandatory for executive retreat vendor shortlists.
- Mid-range:Standardized amenity packages with shared facility access capture domestic leisure travelers across Thailand's secondary islands where land costs constrain full-service development.
- Budget:Minimal infrastructure configurations with communal sanitation facilities concentrate in Australia's working-holiday traveler corridors.
- Family-Oriented:Multi-bed layouts with safety-certified structures and activity programming target Indonesia's domestic market where intergenerational travel patterns dominate booking patterns.
By revenue concentration, luxury properties dominate. By booking velocity, family-oriented configurations are expanding most quickly as Southeast Asian domestic markets mature.
Booking Channel:
Channel mix directly determines customer acquisition economics and data ownership, with direct bookings eliminating commission burdens while OTAs provide demand visibility.
- Direct:Proprietary reservation platforms enable guest data retention and loyalty program deployment, with Australian EcoCertified properties leading regional investment in this channel to reduce intermediary dependency.
- Online Travel Agencies:Algorithmic ranking systems prioritize EcoCertification status, creating commercial pressure for operators to maintain certification compliance despite voluntary program status.
- Travel Agents:Corporate and incentive travel segments in Australia and Japan maintain this channel for complex multi-property itinerary construction.
- Mobile Apps:Last-minute booking interfaces capture spontaneous demand in Thailand's domestic leisure market where smartphone penetration drives channel preference.
By transaction volume, online travel agencies still lead. By margin contribution, direct bookings are gaining share fastest as property operators complete platform buildouts.
Target Audience:
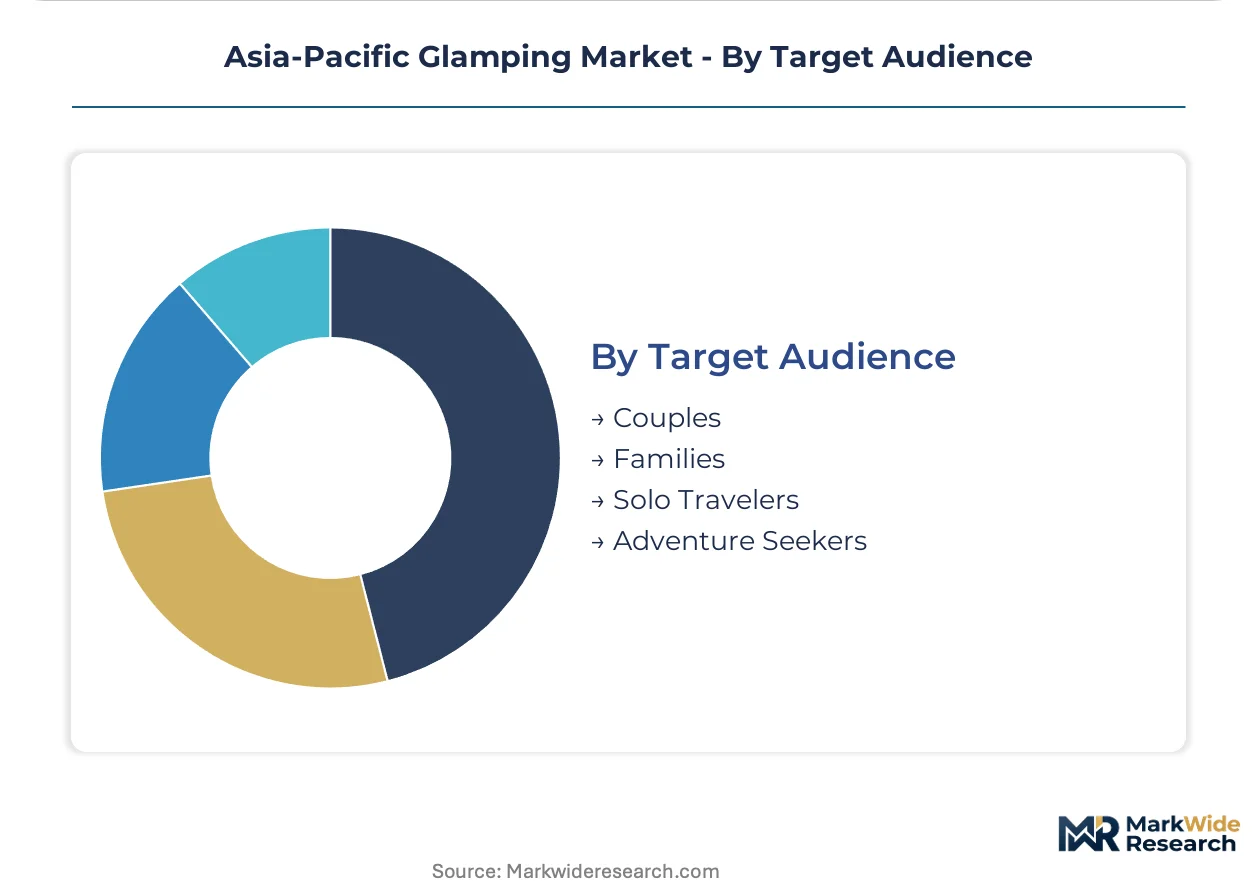
Audience segmentation shapes experiential programming design and marketing channel allocation, with couples-oriented properties emphasizing privacy architecture and adventure seekers requiring guide certification infrastructure.
- Couples:Intimate configurations with privacy screening and couples-focused amenities concentrate in Indonesia's private-island developments where exclusive access channels support rate premiums.
- Families:Multi-unit clusters with supervised activity programming dominate Australia's school-holiday booking calendars.
- Solo Travelers:Social infrastructure and guided group experiences attract this segment to Japan's alpine properties where safety concerns constrain independent exploration.
- Adventure Seekers:Activity-integrated accommodations with equipment provisioning and guide services concentrate in New South Wales coastal corridors where Paperbark Camp anchors regional standards.
By property count, family-oriented accommodations lead. By rate realization, couples-focused configurations command the steepest expansion trajectory as privacy premiums intensify across Southeast Asian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecotourism Australia anchors certification standards that shape operational legitimacy across the region. Domestic leisure travelers and corporate procurement teams filter vendor selections through this quality signal. National tourism infrastructure policies in multiple jurisdictions now embed sustainability mandates into licensing frameworks.
Australia
Corporate retreat demand and incentive travel procurement accelerate bookings for EcoCertified properties. Ecotourism Australia's voluntary program influences OTA algorithmic rankings and shortlist inclusion. New South Wales coastal corridors host Paperbark Camp and Tanja Lagoon Camp, which anchor regional design standards for premium eco-lodge configurations.
Japan
Alpine prefecture developments attract experiential travelers seeking minimalist architectural integration with volcanic terrain. METI's hospitality classification frameworks legitimize premium pricing structures and clarify operational legality. The Fuji Five Lakes corridor concentrates luxury-tier properties where Hoshinoya Fuji competes through landscape-responsive design.
Indonesia
Domestic intergenerational travel patterns and international exclusivity seekers drive private-island configurations. The Ministry of Environment and Forestry mandates tightening coastal setback buffers that disqualify waterfront sites from license renewal. Bintan Island developments feature Natra Bintan, which controls exclusive access channels through marine estate configurations.
Thailand
Smartphone penetration and spontaneous booking behavior favor mobile app channels for domestic leisure travelers. The Ministry of Tourism and Sports is tightening site licensing thresholds that force operators toward inland or elevated terrain. Krabi and Phang Nga provinces respond with cliffside and mangrove-adjacent designs that satisfy regulatory requirements.
India
Adventure tourism infrastructure and desert landscape immersion attract both domestic and international experiential travelers. State-level tourism boards coordinate with environmental regulators on carrying capacity limits for sensitive ecosystems. Rajasthan's Thar Desert hosts Jaisalmer Desert Glamping, while Kerala's Western Ghats concentrate Wayand Wild in biodiversity corridor zones.
Asia-Pacific Glamping Market Competitive Landscape
Specialist eco-lodge operators and diversified hospitality groups split the market into distinct capability tiers. The vendor base organizes around experiential programming depth versus capital-scale efficiency. Three archetypes dominate: design-forward boutique properties, multi-site portfolio operators, and integrated resort-hotel hybrids. Competitive moves concentrate on direct booking platform buildouts and carbon-offset pre-certification to secure license renewal advantages.
Within the design-forward boutique tier, Paperbark Camp and Hoshinoya Fuji exemplify minimalist architectural integration with sensitive landscapes. Tanja Lagoon Camp and Natra Bintan occupy positions emphasizing exclusive access control through marine or coastal estate configurations. Treehouse Villas Thailand represents the elevated-timber specialization segment responding to Thailand's tightening coastal setback regulations.
| Leading Market Players |
|---|
| The Glamping Company Australia |
| Paperbark Camp |
| Tanja Lagoon Camp |
| Hoshinoya Fuji |
| Natra Bintan |
| Treehouse Villas Thailand |
| Jaisalmer Desert Glamping |
| Wayand Wild |
| Glamping Society |
| Others |
Pricing and Supply Chain Analysis
Singapore-Jakarta freight corridors transmit cost volatility from technical textile suppliers to downstream operators, concentrating margin pressure on tent fabricators while amplifying price differentiation between EcoCertified and uncertified properties across Southeast Asian markets.
Pricing Analysis
Geographic price spreads widen from Australia's corporate retreat corridors to Thailand's secondary islands, with luxury-tier properties commanding triple-digit premiums over budget configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and experiential programming depth. Pricing pressure stems from tensile membrane input cost volatility as technical textile production clusters in narrow supplier bases. Corporate procurement teams exhibit lowest price sensitivity, prioritizing EcoCertification status before rate negotiation.
Supply Chain Analysis
Extended payment terms from Australian fabricators to Southeast Asian operators are compressing working capital cycles as project financing complexity rises. Technical textile production concentrates in China, South Korea, and Taiwan, with polymer coating innovation reducing maintenance cycles for tropical deployments. Raw material dependencies center on fluoropolymer membranes, engineered timber laminates, and IoT-enabled climate control modules. Single-source vulnerability in membrane coating technology exposes operators to supply disruption. Distribution runs through direct booking platforms displacing traditional OTA intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operational viability in this market hinges on securing dual-competency talent pools combining hospitality service standards with ecological guide certification, an intersection where training pipeline capacity lags demand acceleration across Indonesia's resort islands and Japan's alpine prefectures.
For Market Incumbents: Insulate margin structures by deepening captive supply relationships with tensile membrane fabricators in Australia and New South Wales, reducing exposure to extended lead times from concentrated technical textile suppliers. Accelerate proprietary booking platform deployment to retain guest data and renegotiate OTA commission structures before corporate procurement teams finalize vendor shortlists. For New Entrants and Emerging Players: Establish a beachhead in Thailand's underpenetrated secondary archipelagos where land costs remain subdued and coastal setback regulations have not yet triggered permit bottlenecks. Target family-oriented configurations with multi-bed layouts and safety-certified structures, leveraging domestic intergenerational travel patterns that dominate Indonesia's booking velocity. Deploy mobile-first reservation interfaces to capture smartphone-driven spontaneous demand. For Investors and Strategic Acquirers: Design-forward boutique properties with pre-certified renewable energy systems offer asymmetric license renewal advantages as Australia's carbon-offset mandates crystallize. Long-term viability centers on experiential programming depth rather than room count scale, with properties controlling exclusive access channels through marine or coastal estate configurations commanding persistent rate premiums. Watch for regulatory clarity on coastal setback buffer enforcement as the inflection indicator for portfolio revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Booking Platform Buildout | Proprietary reservation systems reduce OTA dependency and enable guest data retention for Australian EcoCertified operators. |
| Carbon-Offset Pre-Certification | Pre-certified renewable energy systems secure first-mover advantages under Australia's emerging tourism licensing requirements. |
| Experiential Programming Talent Acquisition | Dual-competency guides combining hospitality and ecology expertise differentiate properties in Japan's alpine prefectures. |
| Technical Textile Supplier Integration | Captive supply relationships with membrane fabricators mitigate lead time volatility and input cost pressure. |
| Cliffside and Elevated Terrain Development | Inland configurations satisfy Thailand's tightening coastal setback regulations while preserving experiential differentiation. |
Research Methodology
Desk research of hospitality licensing databases, tourism ministry policy filings, and technical textile trade flows preceded structured interviews with glamping property operators, Ecotourism Australia certification officers, and corporate travel procurement managers. Secondary validation drew from customs records for tensile membrane imports, OTA algorithmic ranking documentation, and METI hospitality classification frameworks. Bottom-up property-level capacity assessments triangulated against top-down tourism arrival projections across the analysis window.
Assumptions held fixed include regulatory enforcement timelines for coastal setback buffers and carbon-offset mandates, while variables tested included domestic leisure traveler preference shifts and corporate procurement sustainability filter adoption. The analytical framework modeled accommodation type, experience level, booking channel, and target audience dimensions alongside regional regulatory cluster differentiation. CAGRs derived from volume-weighted average growth across property development pipelines and tourism infrastructure investment disclosures, with tensile membrane cost trajectories and OTA commission rate evolution as key inputs.
Sensitivities concentrate around regulatory enforcement acceleration for coastal setbacks and carbon-offset compliance thresholds. Forecasts reflect documented assumptions on certification program adoption curves and domestic traveler booking channel migration. Macroeconomic contraction, regulatory timeline compression, or breakthrough material science deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market
Short-term Rentals and Vacation Homes
Europe Glamping Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
RV Rental Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
North America Glamping Market