
 Vacation Ownership Timeshare Market | 2026-2036
Vacation Ownership Timeshare Market Size, Share, and Industry Trends Forecast 2026-2036
Vacation Ownership Timeshare Market Intelligence
Digital booking platforms is expanding their share of primary sales, reducing reliance on high-pressure gallery tours. Marriott International dominates the branded timeshare segment through its extensive resort network and loyalty integration. Wyndham Hotels & Resorts anchors its position with a vast portfolio of mid-market properties across North American leisure destinations. Hilton Grand Vacations differentiates through premium urban and resort locations tied to its hotel brand ecosystem.
Vacation ownership timeshare denotes a shared property-rights arrangement granting purchasers recurring usage intervals, typically structured as deeded real estate or right-to-use contracts with annual maintenance obligations. The product functions as a prepaid lodging mechanism, locking in future accommodation costs while transferring inflation risk to the developer. Points-based systems now lead transaction volume due to their exchange flexibility across resort networks and seasons. Fixed-week inventory remains mature, concentrated in legacy beach and mountain markets where resale liquidity lags. Fractional ownership occupies the luxury tier, commanding higher entry thresholds and delivering concierge-level services distinct from traditional timeshare operations.
The US Federal Trade Commission enforces mandatory rescission periods, compelling developers to maintain compliance infrastructure that elevates customer acquisition costs. State-level real estate commissions in Florida, California, and Hawaii impose additional licensing and disclosure standards that shape market entry barriers. The Consumer Financial Protection Bureau scrutinizes timeshare financing products, pressuring operators to restructure loan terms. Stakeholders must monitor evolving cooling-off regulations and consumer-protection litigation trends to anticipate margin compression in direct sales channels.
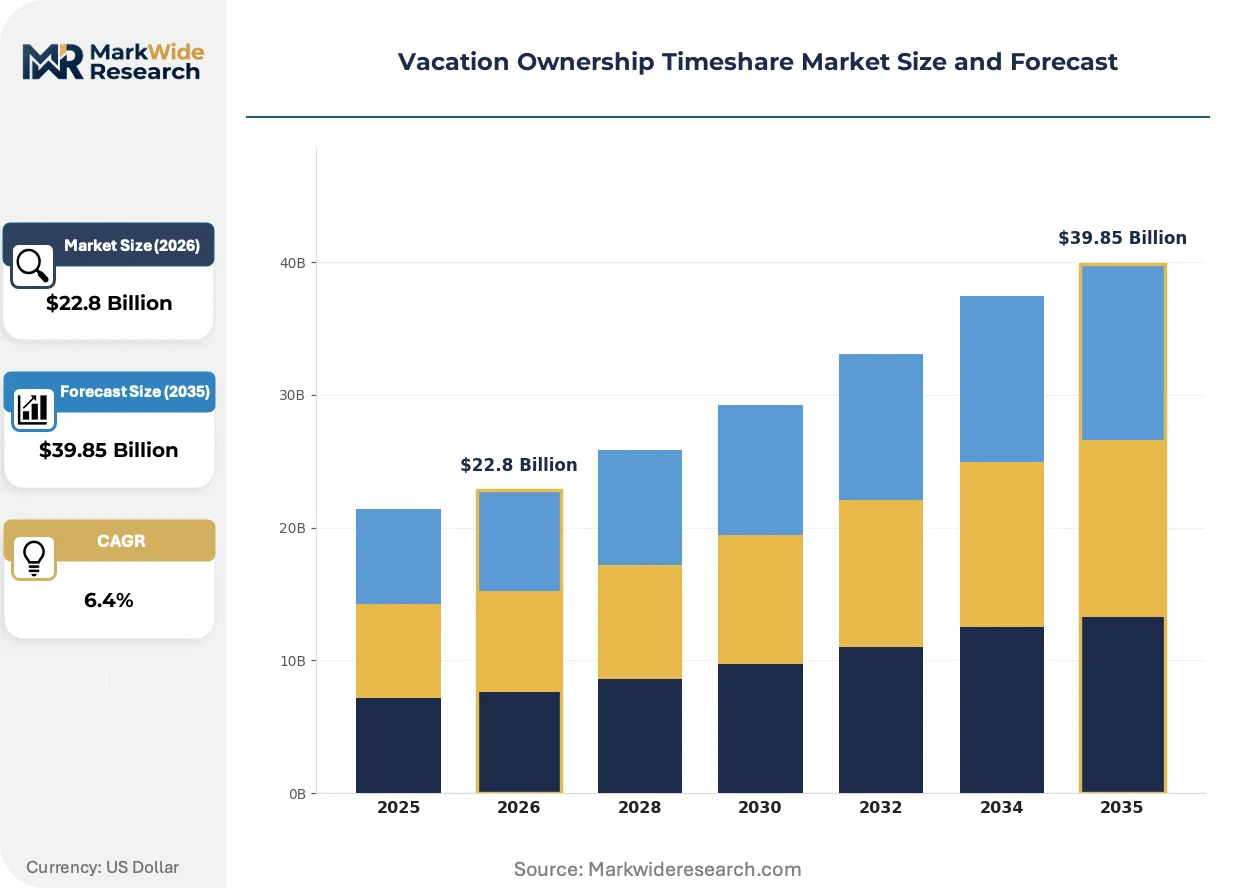
Market Dynamics
The FTC's cooling-off period mandates are compressing developer margins while points-based systems restructure inventory liquidity across resort networks.
Growth Catalysts
- Points-based exchange platforms:Flexible redemption systems attract multi-generational family vacationers seeking destination variety without fixed-week constraints. Exchange networks expand inventory utility beyond home resort boundaries.
- Florida's coastal development pipeline:Orlando and Miami-Dade construction activity concentrates new supply where legacy inventory already saturates secondary resale channels.
- Loyalty program integration:Hotel-branded timeshare operators leverage existing guest databases to reduce customer acquisition costs and accelerate owner conversion from transient stays.
Market Restraints
- Resale market illiquidity:Fixed-week beach and mountain inventory trades at steep discounts to developer pricing, trapping owners in maintenance fee obligations with limited exit pathways.
- Financing product scrutiny:The Consumer Financial Protection Bureau examines loan term structures and disclosure practices, elevating compliance costs for developers offering purchase financing.
- High-pressure sales model dependency:Gallery tour economics require substantial upfront investment per prospect, constraining unit economics as digital channels capture younger buyer segments.
Strategic Opportunities
- Fractional luxury tier expansion:Concierge-level service products command entry thresholds distinct from traditional timeshare operations, attracting high-net-worth buyers seeking asset-light vacation ownership.
- Digital-native booking pathways:Primary sales through online platforms reduce tour dependency and enable targeted demographic segmentation beyond legacy prospecting methods.
- Urban resort development:Premium city-center locations tied to hotel brand ecosystems capture business-leisure travel convergence and extended-stay demand patterns.
Industry Challenges
- Sales force regulatory certification:State-level real estate licensing requirements in Florida, California, and Hawaii create training bottlenecks and turnover costs that scale with expansion velocity.
- Legacy system integration friction:Points-based inventory management requires re-platforming from fixed-week reservation architectures, complicating data migration and owner communication during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacation Ownership Timeshare Market |
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $39.85 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Week, Floating Week, Points-Based, Fractional Ownership End User: Families, Couples, Retirees, Business Travelers Sales Channel: Direct Sales, Online Platforms, Travel Agents, Timeshare Exchanges Size: Small Units, Medium Units, Large Units, Luxury Units |
| Companies Covered | Travel + Leisure Co., Grupo Vidanta, Marriott International Inc., RCI (Resort Condominiums International), Westgate Resorts, Wyndham Hotels & Resorts Inc., InterContinental Hotels Group (IHG), Bluegreen Vacations LLC, Hilton Grand Vacations Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacation Ownership Timeshare Market Strategic Shifts & Innovations
Digital distribution channels are fragmenting the traditional gallery-tour sales model while regulatory pressure and shifting buyer demographics compress legacy operational assumptions.
Blockchain-based title registry systems are consolidating fractional ownership records across resort networks. Family vacationers and resale market participants adopt these verification tools to reduce title search friction and accelerate transfer timelines. Distributed ledger infrastructure is consolidating trust mechanisms that previously required centralized developer mediation.
The FTC's cooling-off period enforcement tightens rescission compliance infrastructure requirements. Developers must maintain extended customer service capabilities and documentation systems that elevate per-sale administrative burdens. Smaller operators lacking captive legal resources face disproportionate cost pressure from these consumer protection mandates.
Subscription-style vacation access models disrupt traditional deeded ownership structures. Younger buyer cohorts favor annual fee arrangements with cancellation flexibility over perpetual maintenance obligations. Coastal Florida and Arizona retirement communities witness the strongest adoption of these non-deeded product formats.
Vacation Ownership Timeshare Market Segmentation
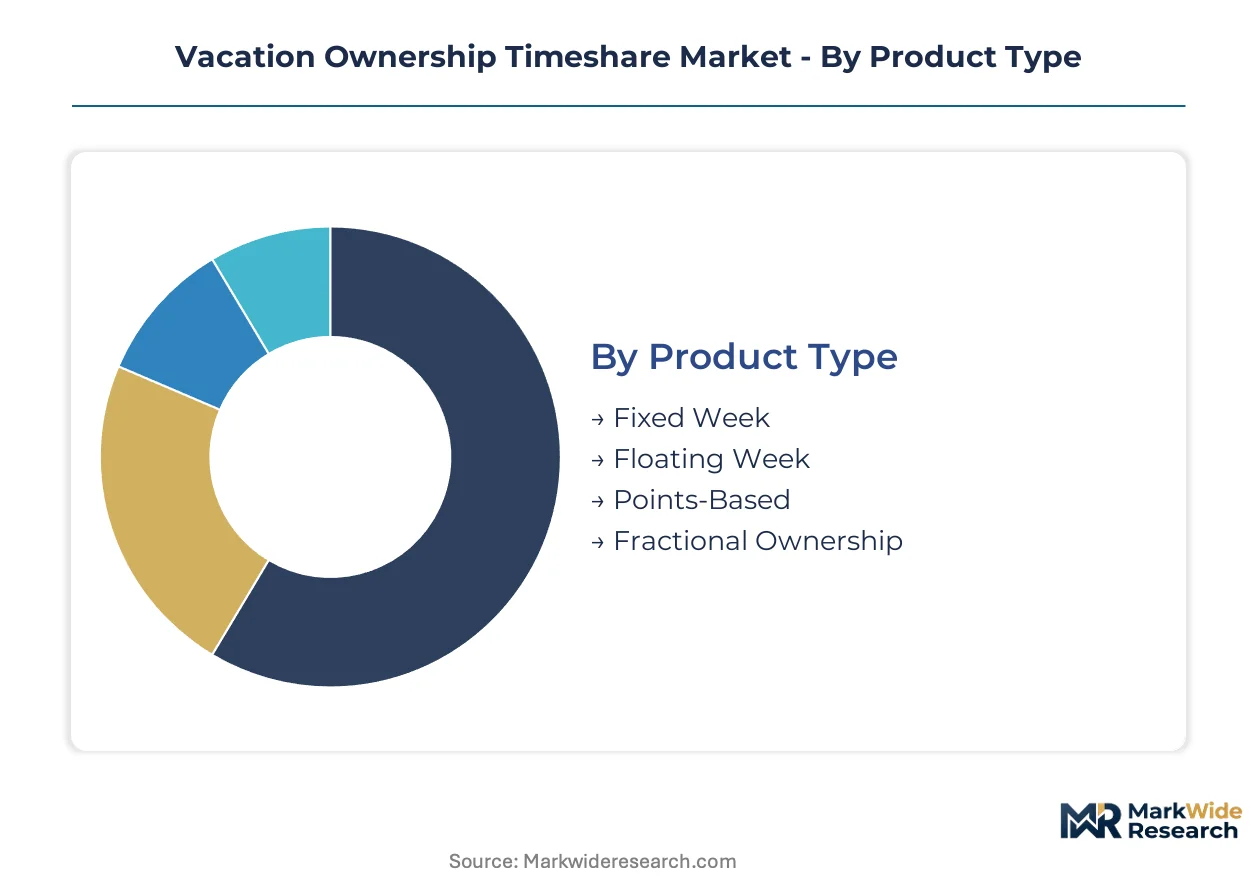
Product architecture determines capital deployment patterns across resort networks. Developer inventory strategies align with distinct buyer risk profiles and liquidity preferences.
Product Type:
Supply concentration tilts toward exchangeable inventory formats as legacy fixed obligations lose favor with younger acquisition cohorts.
- Fixed Week:Deeded real estate instruments assign specific calendar intervals to owners. Coastal Florida and legacy mountain markets hold concentrated inventory where resale liquidity constraints trap owners in perpetual maintenance obligations.
- Points-Based:Flexible redemption systems decouple usage rights from specific resorts or dates. Demand concentrates among multi-generational family vacationers seeking destination variety without fixed-week constraints; exchange networks expand inventory utility beyond home resort boundaries.
- Floating Week:Seasonal flexibility within designated time bands without fixed calendar assignment. Seasonal allocation conflicts create reservation friction during peak demand windows.
- Fractional Ownership:High-entry-threshold arrangements delivering concierge-level services distinct from traditional operations. Ultra-high-net-worth buyers seeking asset-light vacation ownership dominate this tier.
Points-Based absorbs the bulk of installed capacity; Fractional Ownership is expanding most quickly.
End User:
Cost tier stratification separates mass-market acquisition economics from premium service delivery models.
- Families:Multi-generational travel parties prioritize exchange flexibility and kitchen-equipped accommodations. Orlando and coastal Florida development pipelines target this segment with points-based product configurations.
- Couples:Smaller unit requirements and flexible travel windows reduce peak-season competition. Urban resort locations and boutique mountain properties capture this demand.
- Retirees:Extended-stay patterns and predictable seasonal preferences align with fixed-week or low-exchange-fee points products. Arizona and Florida retirement communities concentrate ownership density.
- Business Travelers:Hybrid leisure-work itineraries favor urban locations with meeting infrastructure and loyalty program integration. Premium city-center properties tied to hotel brand ecosystems serve this niche.
Families command the largest ownership base; Business Travelers are climbing the fastest as hybrid travel patterns normalize.
Sales Channel:
Volume distribution shifts away from high-fixed-cost gallery tours toward variable-cost digital acquisition pathways.
- Direct Sales:High-pressure gallery tour economics dominate developer primary revenue. FTC cooling-off period mandates elevate compliance infrastructure and per-sale administrative burdens.
- Online Platforms:Digital-native booking pathways reduce tour dependency and enable targeted demographic segmentation. Younger buyer segments show strongest adoption.
- Travel Agents:Third-party distribution retains relevance for complex multi-destination exchange arrangements. Commission structures compress developer margins relative to direct channels.
- Timeshare Exchanges:Secondary market liquidity mechanisms facilitate inventory redeployment across resort networks. Resale market illiquidity in fixed-week inventory limits exchange utility for legacy owners.
Direct Sales maintains dominant transaction volume; Online Platforms are gaining share fastest among acquisition channels.
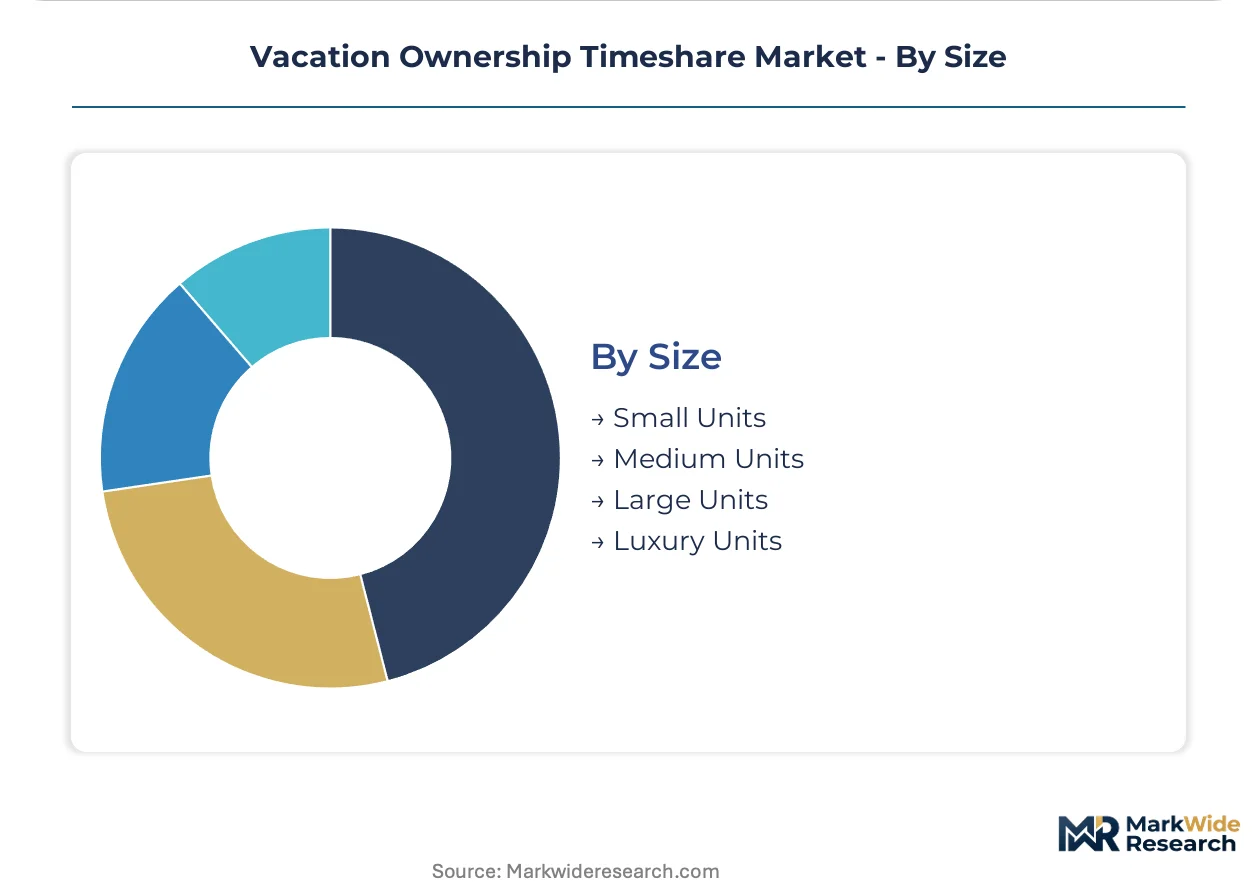
Size:
Margin structure varies sharply across accommodation scale, with luxury units commanding disproportionate service revenue attachment.
- Small Units:Studio and one-bedroom configurations serve couples and solo travelers with lower maintenance fee burdens. Urban resort developments favor this format for space-constrained locations.
- Medium Units:Two-bedroom layouts balance family accommodation needs with exchange liquidity. This format dominates points-based network inventory.
- Large Units:Three-bedroom and multi-room configurations target extended-family gatherings. Higher maintenance fees constrain resale market liquidity.
- Luxury Units:Premium finishes, dedicated concierge services, and exclusive amenity access define this tier. Fractional ownership structures and branded residence affiliations concentrate in this segment.
Medium Units carry the majority of network inventory; Luxury Units show the steepest expansion trajectory among new construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer demand concentrates in coastal leisure corridors where legacy inventory overlaps with new construction pipelines. The United States absorbs the dominant share of transaction volume, though development patterns vary sharply across sub-regions. Regulatory frameworks in each jurisdiction reshape developer compliance costs and sales channel economics.
United States
Florida's Orlando and Miami-Dade corridors anchor domestic demand, with multi-generational family vacationers driving points-based product adoption. The Federal Trade Commission enforces mandatory rescission periods that elevate customer acquisition infrastructure costs. Developer construction pipelines concentrate along the Gulf and Atlantic coasts where maintenance fee burdens already strain resale liquidity.
Mexico
Cancún and Los Cabos resort zones attract North American buyers seeking deeded alternatives to domestic pricing tiers. Mexico's consumer protection agency Profeco mandates disclosure standards for international purchasers that parallel US cooling-off requirements. Grupo Vidanta anchors development activity across the Riviera Maya corridor with integrated hospitality ecosystems.
Spain
Costa del Sol and Balearic Islands inventory serves British and German vacation ownership demand through floating-week and points-based structures. Spain's Ley de Ordenación del Turismo imposes licensing requirements on timeshare promoters that filter smaller operators from primary markets. Marbella and Mallorca development clusters concentrate luxury fractional products targeting ultra-high-net-worth European buyers.
Thailand
Phuket and Pattaya resort corridors attract Asian and Australian buyers seeking right-to-use contracts with lower entry thresholds. Thailand's Consumer Protection Act mandates cooling-off periods for condominium and timeshare sales that reshape gallery tour economics. Bangkok-based developers increasingly integrate urban resort locations to capture business-leisure hybrid travel patterns.
United Arab Emirates
Dubai's branded residence pipeline extends into fractional ownership structures targeting Gulf and South Asian buyers. The UAE's Real Estate Regulatory Agency enforces escrow and disclosure standards that elevate developer capital requirements. Palm Jumeirah and Downtown Dubai clusters concentrate inventory where hotel-brand loyalty integration drives conversion from transient stays.
Vacation Ownership Timeshare Market Key Industry Players
Portfolio diversification dominates the current landscape as operators restructure around points-based exchange networks and loyalty program integration. The vendor base clusters into three distinct tiers: hotel-branded giants with captive distribution, independent developers with regional resort concentrations, and exchange platform specialists facilitating secondary liquidity. Strategic archetypes separate into loyalty-integrated hospitality conglomerates, fixed-asset regional operators, and technology-enabled exchange networks. M&A activity and digital channel expansion represent the two dominant competitive vectors reshaping market share distribution.
Within the loyalty-integrated tier, Marriott International Inc., Hilton Grand Vacations Inc., and Wyndham Hotels & Resorts Inc. exemplify the hotel-brand ecosystem model that reduces customer acquisition costs through existing guest database conversion. These operators occupy positions where transient hotel stays feed owner prospect pipelines, with points-based products enabling cross-property redemption flexibility. Independent developers such as Bluegreen Vacations LLC and Westgate Resorts represent regional-scale archetypes concentrated in specific leisure corridors rather than distributed networks. Exchange platform specialists including RCI anchor secondary market liquidity mechanisms that sustain inventory utility across otherwise disconnected resort systems.
| Leading Market Players |
|---|
| Travel + Leisure Co. |
| Grupo Vidanta |
| Marriott International Inc. |
| RCI (Resort Condominiums International) |
| Westgate Resorts |
| Wyndham Hotels & Resorts Inc. |
| InterContinental Hotels Group (IHG) |
| Bluegreen Vacations LLC |
| Hilton Grand Vacations Inc. |
| Others |
Cost & Logistics Intelligence
Sales force concentration in Florida's Orlando corridor amplifies labor-cost differentials between high-pressure gallery operations and digital-native booking platforms, widening pricing-tier spreads across direct and online acquisition channels. Developer margin compression from FTC cooling-off compliance further stratifies entry thresholds between legacy fixed-week inventory and flexible points-based products.
Pricing Analysis
Volume concentrates in mid-market points-based products while margins accrue to fractional luxury tiers with concierge service attachments. Price differentiation separates branded residence affiliations from independent resort inventory, with hotel-brand ecosystems commanding premium positioning through loyalty integration. Pricing pressure stems from resale market illiquidity trapping owners in maintenance fee obligations with limited exit pathways. First-time buyer segments show highest price sensitivity, while ultra-high-net-worth purchasers in fractional tiers demonstrate minimal elasticity to entry thresholds.
Supply Chain Analysis
Development financing rests on captive lender relationships in the United States, construction materials sourcing from Mexico and China, and hospitality technology platforms concentrated in North American and European software hubs. Raw material dependencies include steel and concrete for coastal Florida construction, furnishings from Southeast Asian manufacturing clusters, and reservation system infrastructure from cloud providers. Supply chain risk centers on single-source vulnerability in legacy fixed-week reservation architectures requiring re-platforming for points-based inventory management. Distribution runs through developer direct sales galleries, online booking platforms, and third-party exchange networks facilitating secondary liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacation ownership timeshare market sits in a technology-transition phase as blockchain-based title registry systems displace centralized developer mediation for fractional ownership verification and resale market transparency.
For Market Incumbents: Lock in loyalty program data assets to reduce customer acquisition costs against digital-native entrants capturing younger buyer segments through targeted online segmentation. Consolidate points-based exchange network dominance through backward integration into reservation technology platforms, insulating against third-party platform disintermediation threatening gallery tour economics. For New Entrants and Emerging Players: Enter via urban resort development in premium city-center locations tied to business-leisure hybrid travel patterns, the most penetrable white-space as hotel-brand ecosystems underindex on metropolitan inventory. Target subscription-style vacation access models in Arizona and Florida retirement communities where younger cohorts favor annual fee arrangements with cancellation flexibility over perpetual maintenance obligations, deploying direct-to-consumer digital acquisition to bypass high-fixed-cost tour infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with exchange platform specialists facilitating secondary market liquidity given blockchain title registry adoption accelerating transfer timelines and reducing friction costs. Long-term viability favors operators with captive loyalty databases and points-based infrastructure over fixed-asset regional developers concentrated in saturated coastal corridors. Monitor cooling-off period enforcement intensity and Consumer Financial Protection Bureau financing scrutiny as inflection indicators for margin compression severity in direct sales channels.| Strategic Initiative | Industry Significance |
|---|---|
| Points-Based Platform Migration | Re-platforming from fixed-week architectures expands inventory utility across resort networks and seasons. |
| Blockchain Title Registry Integration | Distributed ledger infrastructure reduces title search friction and accelerates fractional ownership transfer timelines. |
| Loyalty Program Data Monetization | Hotel-brand ecosystems convert transient guest databases into owner prospect pipelines at lower acquisition cost. |
| Urban Resort Development Pipeline | Premium city-center locations capture business-leisure convergence and extended-stay demand patterns outside traditional leisure corridors. |
| Digital-Native Booking Pathway Buildout | Online primary sales reduce tour dependency and enable demographic segmentation beyond legacy prospecting methods. |
Research Approach
Document review covered SEC filings from hospitality conglomerates, state real estate commission licensing databases, and Consumer Financial Protection Bureau enforcement actions, complemented by interviews with resort development executives, timeshare sales directors, exchange platform operators, and hospitality technology specialists. Secondary validation drew from FTC regulatory guidance, Florida Department of Business and Professional Regulation records, and industry association membership data. Bottom-up unit economics modeling triangulated against top-down market sizing from construction pipeline tracking and transaction volume estimates.
Cross-referencing historical fixed-week to points-based transition patterns against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user archetype, sales channel, and accommodation scale tier. CAGRs were derived from installed capacity growth, demographic cohort penetration rates, and regulatory cost pass-through assumptions. Forecast inputs incorporated maintenance fee escalation trajectories, resale market discount depth, and digital channel adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under intensified cooling-off period enforcement or accelerated subscription-model disruption. Projections reflect assumptions regarding points-based product mix evolution, state-level licensing requirement stability, and exchange network liquidity depth. A small set of named triggers warrants ongoing watch: Consumer Financial Protection Bureau financing product restructuring mandates, blockchain title registry adoption velocity, and coastal Florida construction cost inflation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Australia Glamping Market
Short-term Rentals and Vacation Homes
Europe Glamping Market
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
North America Glamping Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market
Short-term Rentals and Vacation Homes
RV Rental Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market