
 Australia Glamping Market | 2026-2036
Australia Glamping Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Glamping Market Intelligence
Affluent urban professionals and experience-seeking couples is bifurcating the traditional camping customer base toward premium outdoor hospitality. Paperbark Camp leverages its South Coast NSW location to anchor a high-yield ecotourism niche with minimal environmental footprint. BIG4 Holiday Parks competes through scaled site networks that sustain family-oriented revenue across multiple states. Sal Salis Ningaloo Reef differentiates via marine wilderness access, occupying a rare position where reef proximity commands rate premiums.
Glamping in Australia denotes semi-permanent luxury outdoor accommodation combining weather-resistant fabric or timber structures with hotel-grade amenities such as ensuites, climate control, and curated F&B service, designed to minimize ecological disturbance while maximizing guest comfort in natural settings. Safari lodge and treehouse accommodation types lead capital deployment where operators target extended-stay high-spend guests, while yurt configurations attract fastest-growing interest from mid-range experience seekers seeking shorter booking windows. Wildlife watching and stargazing activities concentrate margin pools where guides, equipment hire, and photography packages extend per-guest spend beyond base rates.
TGA guidelines on sanitation and food safety apply where glamping sites provide on-site catering, while state-level planning regulators in Queensland and Western Australia shape development approvals for remote-area construction. The Australian Competition and Consumer Commission monitors cancellation and refund practices as booking platforms expand. Stakeholders must weigh capital allocation between fixed-structure durability and modular repositioning flexibility as climate exposure intensifies across key operating regions.
Market Dynamics
Domestic millennial and Gen Z travelers are accelerating booking velocity across New South Wales and Queensland, forcing operators to rebalance inventory between coastal eco-sites and outback wilderness locations. The Australian Tourism Accreditation Program and state-level environmental compliance frameworks are reshaping capital deployment timelines and site development requirements.
Growth Catalysts
- Queensland Planning Framework:Streamlined remote-area development approvals under the state's regional planning instruments are reducing site establishment timelines for operators targeting reef-adjacent and hinterland locations.
- Solar-integrated modular construction:Fabrication advances in off-grid power systems and prefabricated low-impact structures are lowering environmental compliance costs while enabling rapid site activation.
- Experience-seeking couples:This demographic segment is driving premium rate acceptance for ensuited safari tents and curated F&B packages in coastal corridors.
Market Restraints
- Timber and engineered fabric input volatility:Weather-resistant membrane materials and certified sustainable hardwoods face supply concentration risk from limited Australian manufacturers.
- TGA sanitation compliance:On-site catering operations trigger food safety guideline adherence that adds operational complexity and inspection frequency for remote sites.
- Traditional camping substitution:Low-cost caravan and self-contained RV travel retains price-sensitive family segments during economic pressure periods.
Strategic Opportunities
- Tasmania wilderness corridors:Underdeveloped Cradle Mountain and Bay of Fires regions offer first-mover positioning for operators with cold-climate structural expertise.
- Stargazing activity packages:Dark sky reserve proximity in Warrumbungle National Park and outback South Australia enables guided astronomy experiences with equipment hire margin expansion.
- Western Australia marine access:Ningaloo Reef-adjacent sites command rate premiums through whale shark and manta ray encounter packaging that extends average length of stay.
Industry Challenges
- Specialized guide recruitment:Wildlife interpretation and photography instruction expertise remains scarce in remote operating regions, constraining activity revenue expansion.
- Climate exposure reconfiguration:Intensifying bushfire and cyclone risk across key operating regions is forcing capital allocation trade-offs between fixed-structure durability and modular repositioning flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Glamping Market |
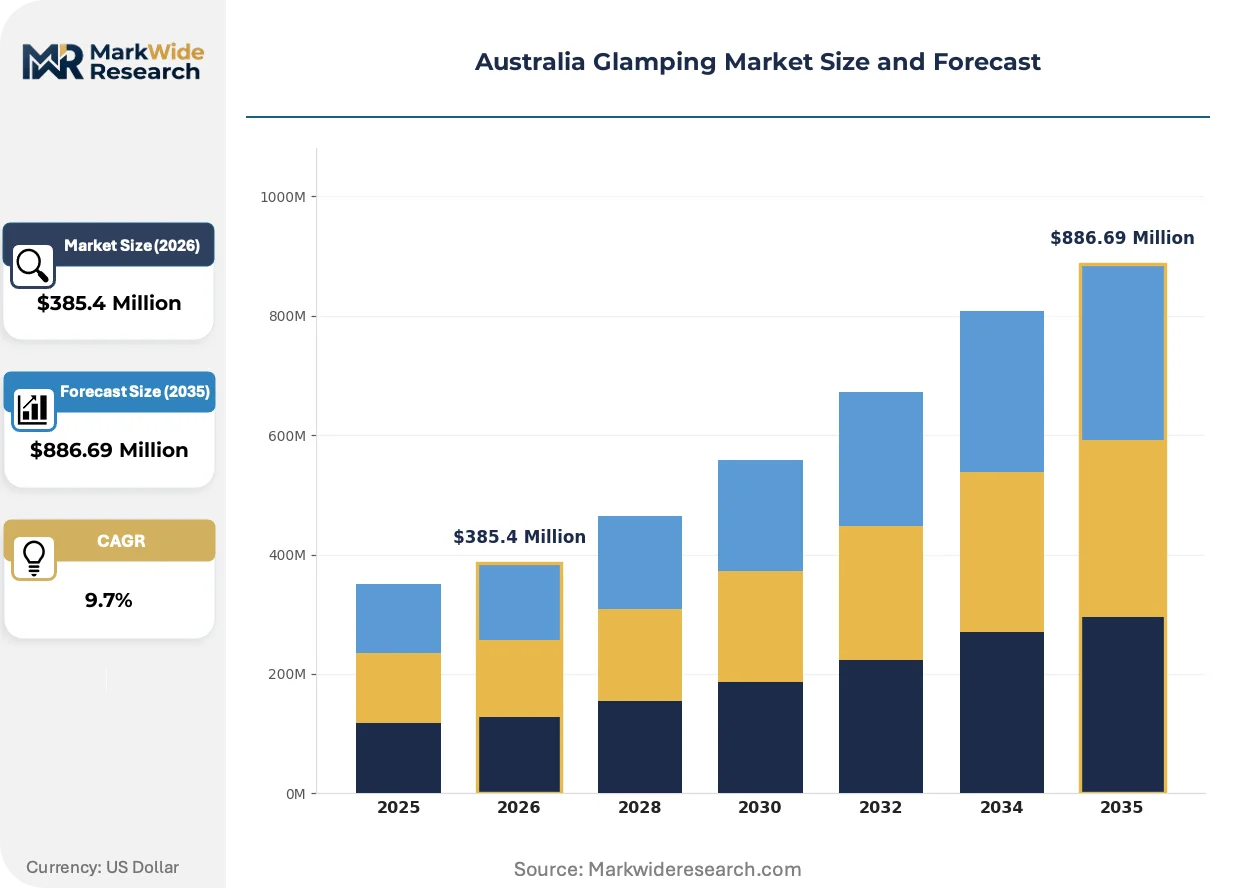
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accommodation Type: Tent, Yurt, Treehouse, Safari Lodge Experience Level: Luxury, Mid-range, Budget, Family-oriented Primary Activity: Hiking, Wildlife Watching, Water Sports, Stargazing Target Audience: Couples, Families, Solo Travelers, Adventure Seekers |
| Companies Covered | Paperbark Camp, BIG4 Holiday Parks, Sal Salis Ningaloo Reef, Eco Beach Resort, Cooinda Lodge, Spicers Retreats, Ingenia Holidays, Eco Structures, Longitude 131°, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Glamping Market Strategic Shifts & Innovations
Technology convergence and regulatory tightening are compressing traditional development timelines while elevating guest experience expectations. Operators now compete on integrated sustainability credentials and seamless digital service delivery.
Modular timber-fabric hybrid structures are decomposing conventional permanent construction economics in remote site development. Mid-range operators across Victoria and South Australia are adopting these systems at accelerating pace. The technology is decomposing capital intensity barriers that previously restricted premium accommodation to established resort zones.
The Australian Tourism Accreditation Program's environmental criteria are mandating renewable energy integration and waste management protocols. Site developers must now demonstrate carbon footprint reduction plans prior to planning approval. Queensland and Western Australia operators face the steepest compliance ramps where marine and outback sensitivities trigger additional state-level environmental assessments.
Direct booking platform migration is fragmenting traditional OTA dependency among established operators. Guests increasingly research through Instagram and TikTok discovery before transacting on proprietary sites, compressing commission structures. This pattern concentrates in New South Wales coastal corridors where millennial and Gen Z travelers dominate search behavior and purchase decisions.
Australia Glamping Market Segmentation
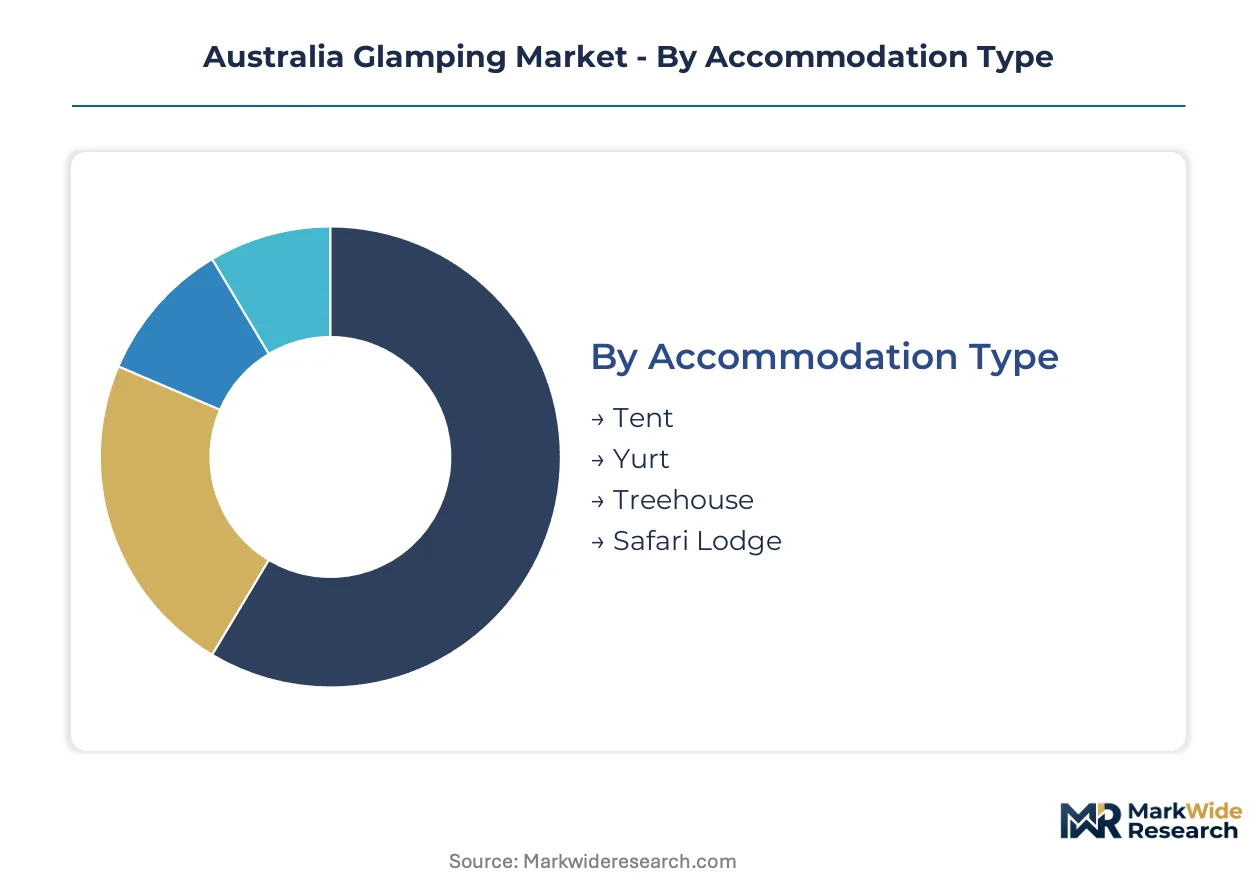
Segmentation in Australian glamping reveals how operators allocate capital across structural formats and guest psychographics. Margin capture varies dramatically between fixed-structure safari lodges and repositionable tent configurations, while activity packaging determines per-guest spend beyond base accommodation rates.
Accommodation Type:
Margin pools concentrate in permanent structures where extended-stay guests accept premium nightly rates, while modular formats enable rapid geographic repositioning as demand shifts between coastal and outback corridors.
- Safari Lodge:Permanent timber-fabric hybrid structures with ensuites and climate control command the highest nightly rates. Demand concentrates in Queensland reef-adjacent sites and Western Australia marine wilderness zones where whale shark encounter packaging extends average length of stay.
- Treehouse:Elevated timber construction with limited footprint disturbance attracts experience-seeking couples in New South Wales coastal hinterland. Daintree and Byron Bay proximity drives booking velocity during domestic travel peaks.
- Tent:Weather-resistant membrane structures with modular power integration dominate mid-range inventory across Victoria and South Australia. Solar off-grid configurations reduce environmental compliance costs for remote site activation.
- Yurt:Circular fabric-timber hybrid designs with collapsible frames attract fastest-growing interest from shorter-booking-window travelers. Operators deploy these across Tasmanian wilderness corridors where cold-climate structural adaptations prove critical.
Safari Lodge holds installed capacity. Yurt is rotating up the share rankings.
Experience Level:
Cost tier stratification determines operational complexity, with luxury segments requiring dedicated F&B staffing while budget configurations compete against traditional caravan substitution.
- Luxury:Curated dining, private guides, and bespoke activity scheduling define this tier. Queensland operators near the Great Barrier Reef extract rate premiums through marine biologist-led interpretive programs.
- Mid-range:Ensuited structures with standardized activity menus capture millennial and Gen Z domestic travelers. New South Wales South Coast deployments concentrate here, balancing amenity investment against accessible price points.
- Budget:Shared facilities and self-catering configurations compete directly with caravan parks and RV travel. Price-sensitive family segments dominate this tier during economic pressure periods.
- Family-oriented:Multi-bed configurations with supervised activity programs target school-holiday demand windows. BIG4 Holiday Parks network scales this format across multiple states through standardized amenity packages.
Luxury commands rate premiums. Mid-range is climbing the fastest.
Primary Activity:
Activity packaging extends margin pools beyond accommodation rates, with specialized equipment hire and guide services creating incremental revenue streams per guest.
- Wildlife Watching:Guided interpretation and photography instruction packages command premium add-on pricing. Demand concentrates in Tasmania and Queensland where endemic species access differentiates site positioning.
- Stargazing:Dark sky reserve proximity in Warrumbungle National Park and outback South Australia enables telescope hire and astronomy guide margins. Operators partner with equipment suppliers to avoid capital-intensive inventory ownership.
- Hiking:Self-guided trail access with mapped route support represents baseline amenity across most sites. Grampians and Blue Mountains proximity shapes operator site selection in this category.
- Water Sports:Kayak, paddleboard, and snorkel equipment hire generates activity revenue in coastal Queensland and Western Australia locations. Ningaloo Reef adjacency commands steepest premium positioning.
Wildlife Watching holds installed capacity. Stargazing is gaining share fastest.
Target Audience:
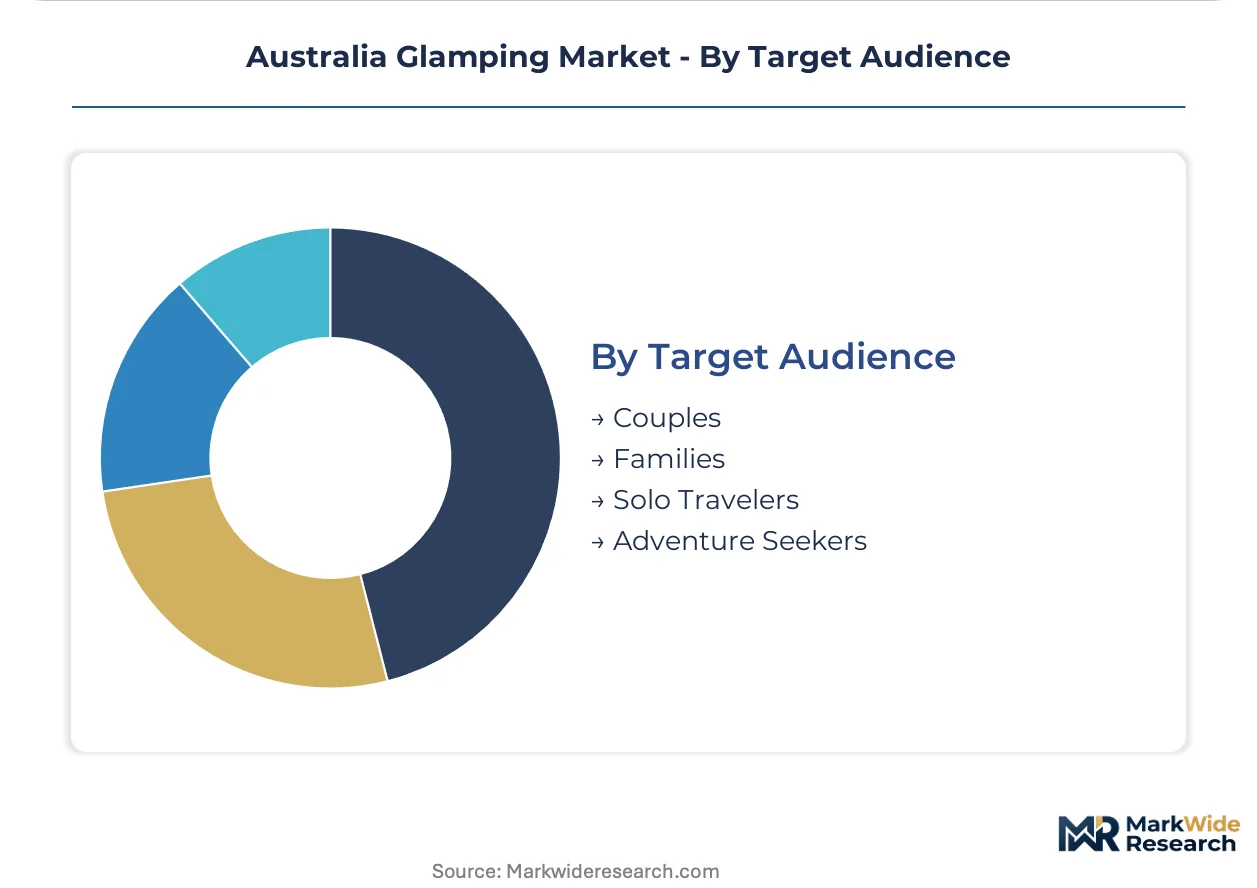
Customer type determines marketing channel allocation and booking platform strategy, with couples migrating toward direct proprietary sites while families remain concentrated on traditional OTA discovery.
- Couples:Experience-seeking pairs drive premium rate acceptance for ensuited privacy and curated F&B. Instagram and TikTok discovery patterns dominate their research behavior before transacting on operator direct sites.
- Families:Multi-generational groups prioritize amenity density and supervised programming during school holiday windows. Traditional booking platforms retain stronger hold here due to package comparison needs.
- Solo Travelers:Individual guests seeking structured social environments gravitate toward group activity scheduling and communal dining formats. This segment shows fastest growth in Tasmanian wilderness corridor deployments.
- Adventure Seekers:High-activity-intensity guests prioritize equipment access and guide availability over accommodation luxury. Western Australia marine access and Queensland hinterland locations concentrate this demand.
Couples holds installed capacity. Solo Travelers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic tourism corridors from Sydney and Melbourne export demand into Queensland reef zones and South Australian outback circuits, creating concentrated booking velocity across coastal and wilderness corridors.
New South Wales
Millennial and Gen Z travelers from Sydney and Melbourne drive peak-season occupancy in South Coast and Byron Bay hinterland locations. The Australian Tourism Accreditation Program mandates renewable energy integration for new site approvals. Jervis Bay and Byron Bay clusters concentrate safari lodge and treehouse deployments where Paperbark Camp anchors the premium ecotourism niche.
Queensland
Great Barrier Reef proximity commands rate premiums for marine wilderness access and extended-stay bookings. Queensland Planning Framework instruments streamline remote-area development approvals for reef-adjacent and hinterland sites. Daintree and Whitsunday Islands concentrate capital deployment where operators package whale shark encounters and guided reef interpretation.
Western Australia
Ningaloo Reef adjacency enables rate premiums through manta ray and whale shark encounter packaging that extends average length of stay. State-level environmental compliance frameworks add assessment layers for marine-sensitive construction zones. Exmouth and Coral Bay sub-regions concentrate luxury safari lodge inventory where Sal Salis anchors the marine-access positioning.
Victoria
Phillip Island wildlife access and Grampians hiking corridors attract mid-range experience seekers with shorter booking windows. State planning regulators shape development approvals for remote-area modular construction. Mornington Peninsula and Yarra Valley clusters adopt solar-integrated tent configurations at accelerating pace to reduce environmental compliance costs.
Tasmania
Cradle Mountain and Bay of Fires wilderness corridors offer first-mover positioning for operators with cold-climate structural expertise. Dark sky reserve proximity in central highlands enables stargazing activity packages with equipment hire margins. Hobart-based travelers drive discovery-phase demand where yurt configurations with collapsible frames adapt to variable weather exposure.
Australia Glamping Market Key Industry Players
Player mix skews toward experience-specialist operators with site-specific environmental positioning rather than scaled network players. The competitive set fragments across permanent-structure safari lodges, repositionable modular tent systems, and hybrid timber-fabric treehouse configurations. Two strategic archetypes dominate: reef-adjacent marine wilderness specialists and hinterland ecotourism minimal-footprint operators. Geographic expansion through site acquisition and portfolio diversification into curated F&B and guided activity packaging represent the dominant competitive vectors.
Among New South Wales-based ecotourism operators, Paperbark Camp exemplifies the minimal-footprint safari lodge archetype through its South Coast positioning. BIG4 Holiday Parks represents the scaled network model with standardized amenity packages across multiple states. Sal Salis Ningaloo Reef anchors the marine-access premium tier where reef proximity commands rate premiums through wildlife encounter packaging.
| Leading Market Players |
|---|
| Paperbark Camp |
| BIG4 Holiday Parks |
| Sal Salis Ningaloo Reef |
| Eco Beach Resort |
| Cooinda Lodge |
| Spicers Retreats |
| Ingenia Holidays |
| Eco Structures |
| Longitude 131° |
| Others |
Cost & Logistics Intelligence
Modular timber-fabric hybrid structures replacing conventional permanent construction are redrawing supply geography toward prefabrication hubs while compressing capital intensity and enabling tiered rate positioning across coastal and outback corridors.
Pricing Analysis
Current-generation solar-integrated modular systems command rate premiums over prior-generation fixed-structure safari lodges, while next-generation collapsible-frame yurt configurations target mid-range price compression. Three-tier pricing structure across premium, standard, and economy levels separates ensuited reef-adjacent safari lodges from shared-facility tent configurations and self-catering budget tiers. Price differentiation hinges on certification grade under the Australian Tourism Accreditation Program and geographic delivery cost to remote Western Australia marine zones. Pricing pressure stems from timber and engineered fabric input volatility, with margins tightening most acutely in mid-range segments where millennial travelers exhibit highest price sensitivity.
Supply Chain Analysis
Strategic stockpiling of weather-resistant membrane materials and certified sustainable hardwoods dominates over just-in-time approaches given Australian manufacturer concentration risk. Supply draws from domestic timber processors, Chinese engineered fabric specialists, and South Korean solar component suppliers. Raw material dependencies center on marine-grade canvas membranes, structural hardwood certification chains, and lithium-ion battery storage systems. Single-source vulnerability concentrates in membrane material supply where limited Australian manufacturers create chokepoint exposure. Distribution runs through direct operator procurement for permanent structures and third-party logistics networks for modular component field assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: the Australian Tourism Accreditation Program and state-level environmental compliance frameworks create approval timelines and capital barriers that protect established site operators from rapid competitive replication.
For Market Incumbents: Shield rate premiums by deepening vertical integration into curated F&B and guided activity packaging where specialized wildlife interpretation expertise remains scarce. Invest in certification maintenance under evolving Queensland and Western Australia environmental assessment protocols. Consolidate position through site acquisition in Tasmania wilderness corridors before cold-climate structural expertise becomes commoditized.
For New Entrants and Emerging Players: Solo traveler service-layer gaps in Tasmanian wilderness and stargazing activity packaging present penetrable white-space where incumbents under-serve structured social environments. Target dark sky reserve adjacency in Warrumbungle National Park with equipment hire partnerships rather than capital-intensive inventory ownership. Deploy collapsible-frame yurt configurations for rapid geographic repositioning as demand shifts between coastal and outback corridors.
For Investors and Strategic Acquirers: The market sits at an infrastructure-buildout phase that favors operators with demonstrated environmental compliance track records and existing accreditation status. Long-term viability hinges on portfolio diversification into experience packaging rather than pure accommodation plays. Acquisition targets should show modular repositioning capability alongside fixed-structure rate premium capture. Watch for Queensland Planning Framework streamlining velocity as inflection indicator for site establishment timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Certification Investment | Australian Tourism Accreditation Program compliance secures planning approval priority in Queensland reef-adjacent zones. |
| Modular Construction Capability Buildout | Prefabricated timber-fabric hybrid systems reduce capital intensity barriers for remote site activation. |
| Activity Packaging Diversification | Wildlife interpretation and stargazing guide services extend per-guest spend beyond base accommodation rates. |
| Direct Booking Platform Migration | Proprietary site transactions compress OTA commission structures among millennial and Gen Z travelers. |
| Cold-Climate Structural Expertise Development | Tasmania wilderness corridor positioning requires collapsible-frame adaptations to variable weather exposure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with glamping site developers, environmental compliance consultants, and state planning regulators across New South Wales, Queensland, and Western Australia. Secondary validation drew from Australian Bureau of Tourism Research data, TGA sanitation guideline documentation, state-level planning instrument filings, and Australian Competition and Consumer Commission regulatory notices. Bottom-up site capacity modeling and top-down tourism expenditure flows were triangulated to cross-verify demand estimates.
Across the analysis window, forecasts incorporate accommodation type segmentation by structural format, experience level tiering, primary activity packaging, and target audience psychographics. CAGRs were derived from installed base growth trajectories, replacement cycle timing, and per-guest spend expansion patterns. Key inputs include domestic travel recovery velocity, environmental compliance cost evolution, and modular construction technology adoption curves.
Forecasts assume regulatory continuity in Australian Tourism Accreditation Program criteria and Queensland Planning Framework instruments; material policy shifts would require re-modeling of site establishment timelines and capital deployment assumptions. Revision becomes warranted when bushfire or cyclone risk intensity crosses thresholds that force structural durability trade-offs or when timber and engineered fabric supply concentration triggers sustained input cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Short-term Rentals and Vacation Homes
North America Glamping Market
Short-term Rentals and Vacation Homes
Asia-Pacific Glamping Market
Short-term Rentals and Vacation Homes
RV Rental Market
Short-term Rentals and Vacation Homes
Treehouse Glamping Market
Short-term Rentals and Vacation Homes
Vacation Ownership Market
Short-term Rentals and Vacation Homes
Luxury Vacation Rental Market
Short-term Rentals and Vacation Homes
Short-Term Vacation Rental Market
Short-term Rentals and Vacation Homes
Vacation Ownership Timeshare Market
Short-term Rentals and Vacation Homes
Vacation Rental Website Market
Short-term Rentals and Vacation Homes
Online Home Rental Services Market
Short-term Rentals and Vacation Homes
Europe Glamping Market
Short-term Rentals and Vacation Homes
Short-Term Rental Platform Market
Short-term Rentals and Vacation Homes
Vacation Rentals Market