
 Art and Craft Tools Market | 2026-2036
Art and Craft Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Art and Craft Tools Market Analysis
Online craft marketplaces and specialty retailer networks is fragmenting as direct-to-consumer platforms and maker-space cooperatives capture share from traditional art supply distributors. Fiskars Group leverages its Nordic manufacturing heritage to sustain premium positioning in scissors and cutting tools across European hobby channels. Crayola LLC anchors the school procurement segment with institutional contracts that dominate North American education budgets. Faber-Castell AG differentiates through in-house graphite production and forest stewardship certification that commands professional artist loyalty.
Art and craft tools encompass hand-operated instruments and consumables used for visual expression, decoration, and material manipulation, typically specifying pigment load percentages, tensile strength in adhesives, or blade hardness ratings on cutting implements. These products serve educational curricula, therapeutic recreation, professional studio practice, and commercial design workflows where precision and material safety determine utility. Paints and brushes constitute the largest value pool within product type segmentation, though adhesives is expanding fastest as mixed-media and upcycling techniques gain practitioner adoption. By material, plastic dominates volume production for beginner and school-grade tools, while wood and metal command premium margins in professional and advanced skill-level categories where durability and ergonomic balance justify higher price positioning.
EPA guidelines on volatile organic compound emissions shape paint formulation requirements in the United States, while REACH chemical registration in Europe restricts certain solvent bases and heavy metal pigments across imported and domestic art supplies. BIS certification mandates in India govern product safety standards for school-distributed craft materials, creating compliance thresholds that filter smaller unorganized suppliers from institutional tenders. Stakeholders must monitor evolving chemical disclosure rules across multiple jurisdictions and calibrate R&D investment toward water-based, low-VOC formulations that satisfy the strictest regional standards without sacrificing performance characteristics that professionals demand.
Market Dynamics
REACH and RoHS compliance in Europe is forcing wholesale reformulation of adhesives and paints, while India's PLI incentives for stationery manufacturing are accelerating domestic capacity expansion that redirects import dependency patterns.
Growth Catalysts
- India's PLI scheme for stationery manufacturing:Government-funded art education programs and production-linked incentives are accelerating local manufacturing capacity for school-grade supplies.
- Water-based paint formulations:EPA guidelines on volatile organic compound emissions are pulling investment toward low-VOC chemistry that satisfies institutional procurement standards.
- Mixed-media techniques:Practitioner adoption of upcycling and material-layering methods is expanding consumption of specialized adhesives across hobby and professional segments.
Market Restraints
- Petrochemical input volatility:Plastic resin prices for beginner-grade tool production create margin compression that suppliers cannot fully pass through to school budgets.
- European chemical registration friction:REACH documentation requirements for imported pigments impose compliance costs that filter smaller suppliers from institutional tenders.
- Durability substitution pressure:Professional users with long replacement cycles favor metal and wood implements that reduce repeat purchase frequency.
Strategic Opportunities
- Maker-space cooperatives:Direct-to-consumer platforms and community workshop networks are capturing share from traditional art supply distributors.
- Forest stewardship certification:In-house graphite production and sustainable wood sourcing commands professional artist loyalty and premium positioning.
- Therapeutic recreation expansion:Clinical art therapy programs in institutional settings create demand for certified, safety-compliant material kits.
Industry Challenges
- Multi-jurisdiction chemical disclosure:Stakeholders must monitor evolving rules across EPA, REACH, and BIS frameworks without sacrificing performance characteristics professionals demand.
- Legacy distributor relationship reconfiguration:Direct channel expansion requires investment in digital infrastructure and logistics capabilities that mid-tier suppliers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Art and Craft Tools Market |
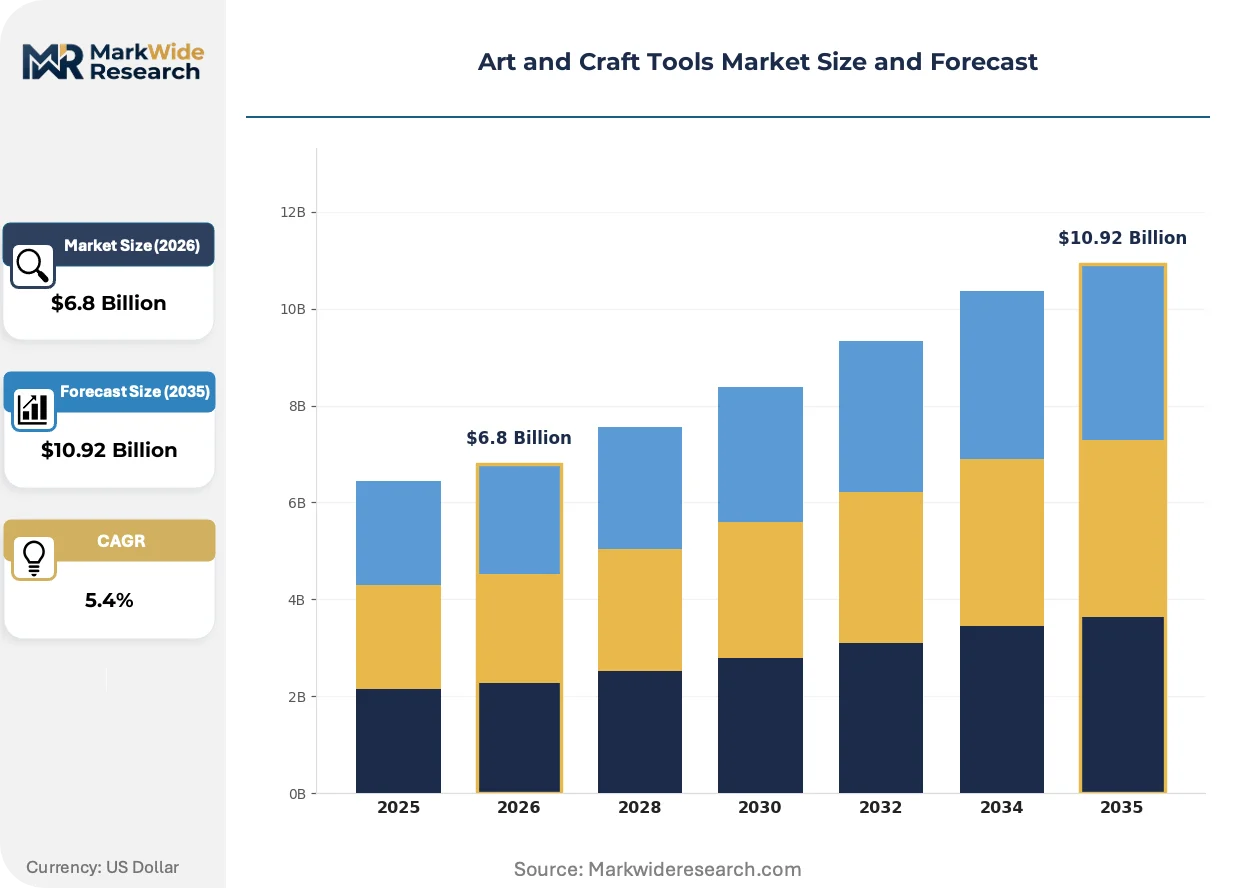
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Brushes, Scissors, Adhesives Material: Wood, Plastic, Metal, Fabric Skill Level: Beginner, Intermediate, Advanced, Professional End User: Schools, Hobbyists, Artists, Retailers |
| Companies Covered | Fiskars Group, Pilot-Pen, Crayola LLC, Shanghai M&G Stationery, Kokuyo Camlin Ltd., Newell Brands, STAEDTLER Mars GmbH & Co. KG, Société Bic S.A., Faber-Castell AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Art and Craft Tools Market Emerging Trajectories
Material science advances and regulatory tightening are converging to reshape product specifications across pigment chemistry, substrate compatibility, and ergonomic design standards.
Solvent-based paint formulations are migrating from professional studio environments to specialized industrial applications. Art schools and therapeutic programs are adopting water-based alternatives at accelerated pace to satisfy institutional safety protocols. This chemistry transition is compressing demand for traditional oil-based mediums while expanding R&D investment in acrylic and hybrid binders.
REACH chemical registration in Europe restricts certain solvent bases and heavy metal pigments across imported and domestic art supplies. Manufacturers must reformulate legacy product lines or exit the European institutional procurement channel entirely. Professional-grade pigment suppliers are responding by accelerating certification of synthetic organic alternatives to cadmium and cobalt compounds.
Institutional buyers are consolidating vendor relationships around certified suppliers capable of documenting full material provenance. School procurement departments are replacing fragmented local purchasing with framework contracts that mandate BIS or equivalent safety certification. This concentration pattern is most visible in India, where government-funded art education programs filter unorganized suppliers from tender participation.
Art and Craft Tools Market Segmentation
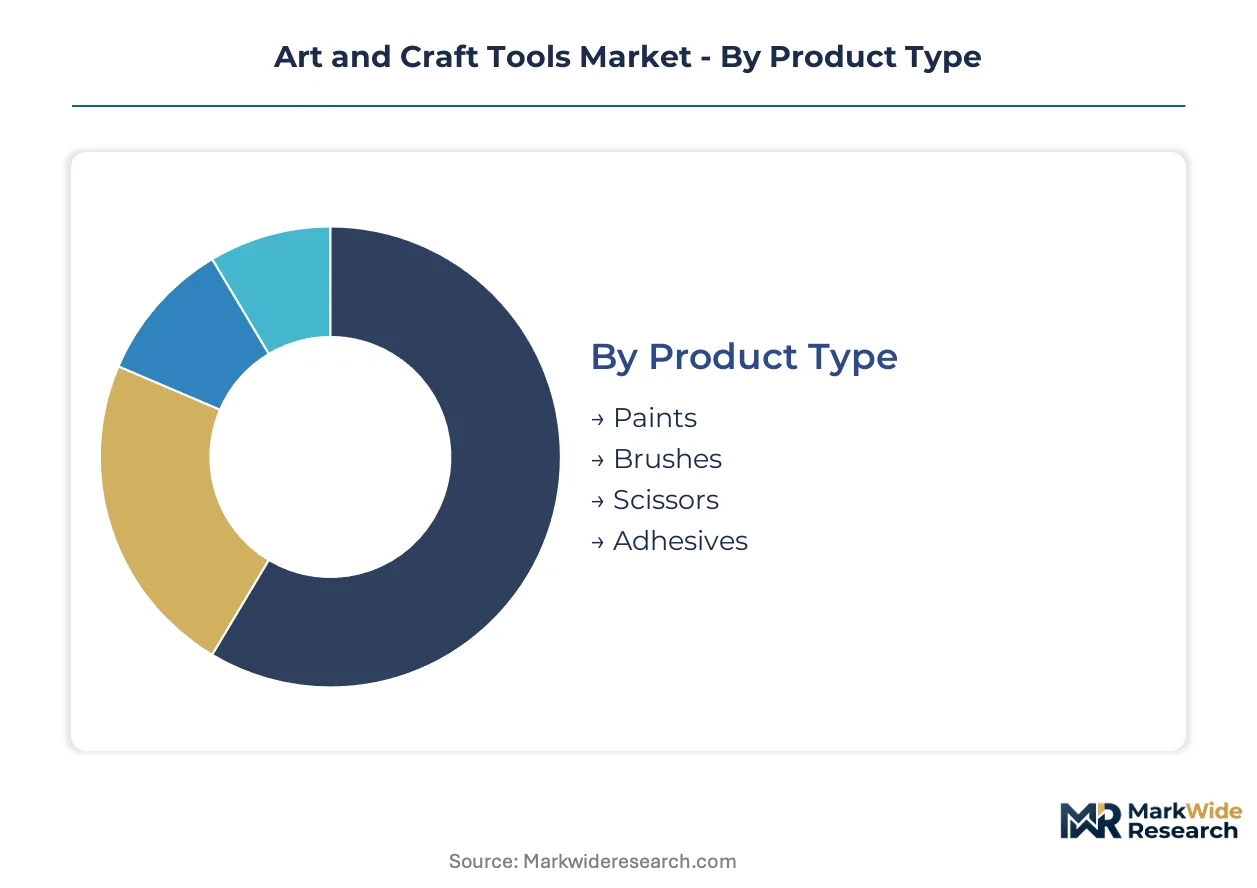
Segmentation in art and craft tools reveals how procurement authority, material specifications, and skill-based utility create distinct commercial battlegrounds. Manufacturers calibrate formulation chemistry, durability grades, and certification depth to match the divergent requirements of institutional buyers versus individual practitioners.
Product Type:
Mature pigment and brush categories coexist with emerging adhesive formats as mixed-media techniques reshape consumption patterns.
- Paints:Water-based acrylics and low-VOC emulsions now dominate institutional procurement, with EPA-compliant formulations capturing school and therapeutic program contracts. Oil-based mediums retreat to specialized professional studios willing to absorb ventilation and disposal costs.
- Adhesives:Specialized bonding agents for material-layering and upcycling applications are expanding most quickly across hobby and professional segments. REACH-compliant solvent-free formulations command premium positioning in European markets.
- Brushes:Synthetic filament brushes displace natural hair in school-grade and mid-tier professional categories.
- Scissors:Cutting implements segment by blade hardness ratings and ergonomic handle designs for repetitive-use environments.
Paints retain volume leadership; adhesives hold the steepest expansion curve.
Material:
Cost tier differentiation separates commodity volume production from premium margin capture.
- Plastic:Injection-molded resins enable mass production of beginner-grade tools at price points accessible to school budgets. Petrochemical input volatility compresses supplier margins without corresponding pricing flexibility in institutional contracts.
- Wood:Forest stewardship certification and ergonomic balance justify premium positioning in advanced skill-level categories. Sustainable sourcing documentation increasingly filters supplier eligibility for professional artist loyalty.
- Metal:Blade hardness ratings and tensile strength specifications serve professional durability requirements with extended replacement cycles.
- Fabric:Textile substrates support specialized craft applications including quilting and fiber arts.
Plastic dominates unit volume; wood commands the highest margin per unit.
Skill Level:
Customer type determines certification depth, durability specification, and price elasticity across the proficiency spectrum.
- Beginner:School-grade tools prioritize safety certification and cost containment over performance longevity. BIS mandates in India and equivalent standards elsewhere filter unorganized suppliers from government-funded program tenders.
- Professional:Studio practitioners demand pigment load percentages, blade hardness ratings, and full material provenance documentation. Metal and wood implements with extended replacement cycles reduce repeat purchase frequency.
- Intermediate:Hobbyists upgrading from school-grade supplies seek performance improvement without professional-tier investment.
- Advanced:Serious amateurs bridge hobby and professional categories with selective premium purchases.
Beginner retains volume leadership; professional holds the steepest expansion curve.
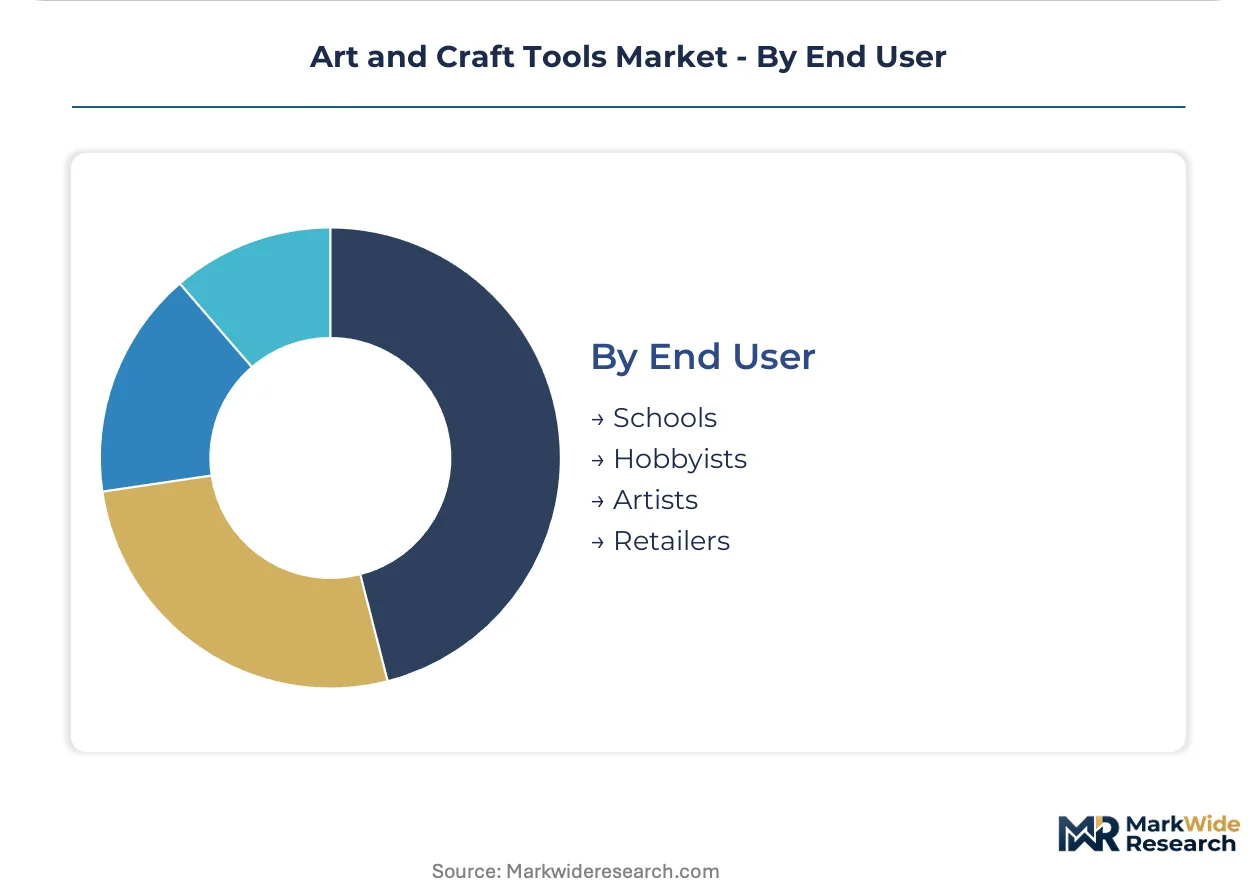
End User:
Procurement authority concentration is reshaping channel structure and vendor consolidation patterns.
- Schools:Institutional procurement departments consolidate fragmented local purchasing into framework contracts mandating certified safety documentation. Government-funded art education programs in India exemplify this concentration pattern.
- Hobbyists:Individual practitioners drive direct-to-consumer platform growth and maker-space cooperative participation, fragmenting traditional distributor relationships.
- Artists:Professional studio practice demands performance characteristics that justify premium positioning through in-house material production and sustainability certification.
- Retailers:Specialty and mass-market channels maintain inventory breadth for impulse and project-based purchasing.
Schools retain volume leadership; hobbyists hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium tool manufacturers in Germany command price premiums that school-grade suppliers in India cannot replicate, creating a bifurcated sourcing map where procurement authority concentrates in high-standard markets while production capacity scales in cost-optimized locations.
United States
Institutional procurement through school districts and therapeutic programs drives certified supply demand, with EPA volatile organic compound guidelines mandating low-VOC paint formulations for education contracts. Specialty retailer networks in metropolitan clusters face erosion from direct-to-consumer platforms and maker-space cooperatives capturing hobbyist spend.
Germany
Professional artist studios and design workflows sustain premium positioning for precision implements, with ECHA REACH chemical registration restricting solvent bases and heavy metal pigments across domestic and imported supplies. The Baden-Württemberg manufacturing corridor anchors European production of certified graphite and forest-stewardship-certified wood tools.
India
Government-funded art education programs and BIS certification mandates for school-distributed materials are filtering unorganized suppliers from institutional tenders. The PLI scheme for stationery manufacturing accelerates domestic capacity expansion in Maharashtra and Gujarat, redirecting import dependency patterns for beginner-grade tools.
China
Mass production of plastic resin-based beginner supplies serves export markets and domestic education procurement, with MIIT industrial standards governing product safety for school-grade distribution. The Yangtze River Delta manufacturing belt concentrates injection-molded tool fabrication for volume-tier global supply.
Japan
Professional-grade brush and cutting tool traditions sustain artisan manufacturing clusters, with METI quality standards and JIS specifications governing material provenance documentation. The Osaka-Kobe industrial zone maintains specialized production of synthetic filament and natural hair implements for precision applications.
Art and Craft Tools Market Vendor Landscape
Heritage manufacturers and scale-driven commodity producers split the market into distinct competitive spheres where certification depth and cost containment operate as mutually exclusive positioning vectors. Consolidation pressure concentrates around institutional procurement channels demanding documented compliance, while fragmentation persists in hobbyist-direct segments where brand loyalty yields to price accessibility. Three archetypes dominate: European heritage houses with in-house material production, Asian scale manufacturers serving school-grade volume, and specialty distributors bridging professional studio supply. Competitive moves center on backward integration into certified raw material sourcing and digital channel infrastructure investment to bypass legacy distributor relationships.
Among heritage European manufacturers, Faber-Castell AG and STAEDTLER Mars GmbH & Co. KG exemplify the premium-tier archetype through sustained positioning in professional artist segments. Shanghai M&G Stationery occupies a position within the scale-driven Asian supply tier serving education procurement volumes. Fiskars Group represents Nordic manufacturing heritage in precision cutting implements across hobby and professional channels.
| Leading Market Players |
|---|
| Fiskars Group |
| Pilot-Pen |
| Crayola LLC |
| Shanghai M&G Stationery |
| Kokuyo Camlin Ltd. |
| Newell Brands |
| STAEDTLER Mars GmbH & Co. KG |
| Société Bic S.A. |
| Faber-Castell AG |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing belt anchors global supply for plastic resin-based beginner tools, with capacity expansion in Maharashtra and Gujarat redirecting procurement patterns toward domestic Indian production. This geographic concentration grants scale manufacturers pricing leverage over school-grade contract negotiations, while REACH compliance costs in Europe compress margins for imported pigment formulations.
Pricing Analysis
Configured-to-order professional-grade implements command spreads of 40-60% above standard school-grade equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth and material provenance documentation. Pricing pressure stems from petrochemical input volatility that suppliers cannot fully pass through to institutional budgets. School procurement departments exhibit highest price sensitivity; professional artists demonstrate lowest sensitivity when performance specifications are met.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard for institutional procurement contracts in North America and Europe. Manufacturing concentrates in China, India, and Germany. Raw material dependencies include petroleum-derived resins, sustainably certified wood stocks, and synthetic organic pigments. Single-source vulnerability exists for REACH-compliant solvent-free adhesive formulations. Distribution runs through consolidated framework contracts for schools and direct-to-consumer platforms for hobbyists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where BIS certification in India and REACH registration in Europe create switching costs that entrench certified suppliers. Network effects concentrate around institutional procurement channels demanding documented compliance.
For Market Incumbents: Entrench position through backward integration into certified raw material sourcing and captive production of synthetic organic pigments. Accelerate capacity addition in Maharashtra and Gujarat to capture PLI scheme benefits. Counter direct-to-consumer platform threats by investing in digital infrastructure that bypasses legacy distributor relationships.
For New Entrants and Emerging Players: Pursue white-space opportunities in maker-space cooperative supply and therapeutic recreation program certification. The most penetrable segment sits in intermediate hobbyist tools bridging school-grade and professional tiers. Go-to-market execution should leverage community workshop networks rather than traditional retail channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors heritage manufacturers with in-house material production and forest stewardship certification. Long-term viability over a five-to-ten year window rests on regulatory entrenchment rather than price competition. Acquisition targets should display documented REACH and BIS compliance capabilities. The signal to watch is consolidation pressure around institutional procurement channels as framework contracts displace fragmented local purchasing.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Migration | Reformulation of legacy solvent-based paints preserves European institutional procurement access against ECHA restrictions. |
| Maker-Space Cooperative Partnership | Direct channel expansion captures hobbyist spend migrating from specialty retailer networks in metropolitan clusters. |
| PLI-Aligned Capacity Expansion | Domestic manufacturing scale-up in Maharashtra and Gujarat redirects import dependency for school-grade supplies. |
| Forest Stewardship Certification Investment | Sustainable wood sourcing documentation filters supplier eligibility for professional artist loyalty and premium positioning. |
| Water-Based Paint R&D Acceleration | Low-VOC chemistry development satisfies EPA guidelines and institutional safety protocols for education contracts. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with art supply procurement managers, school district purchasing officers, professional studio practitioners, and therapeutic program coordinators; and secondary validation through customs records, BIS certification databases, ECHA REACH registration filings, and SEC disclosures from listed manufacturers. Bottom-up triangulation across product type, material grade, skill level, and end-user segmentation reconciled with top-down market sizing.
Forecast inputs span water-based paint adoption curves, mixed-media technique penetration, and institutional procurement consolidation patterns across the analysis window. Segmentation dimensions modeled include product type, material composition, skill proficiency tier, and procurement authority concentration. CAGRs derive from regression analysis against historical volume trajectories and projected regulatory enforcement intensity. Industry-specific inputs incorporate PLI scheme uptake rates and REACH compliance cost pass-through assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by unorganized suppliers achieving rapid certification would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Needlecraft Patterns Market