
 Dibber Market | 2026-2036
Dibber Market Size, Share, and Industry Trends Forecast 2026-2036
Dibber Market Outlook
Market Overview
Subscription-based maintenance and seasonal calibration services for precision planting tools is pivoting how dibber vendors capture recurring revenue beyond one-time hardware sales. Fiskars Group leverages its Nordic design heritage and broad retail distribution to sustain premium positioning across European garden centers. Sneeboer anchors artisanal demand through forged-handled dibbers crafted in the Netherlands, commanding collector-tier pricing. Burgon and Ball Company competes on British manufacturing pedigree and royal warrant status, occupying heritage-conscious segments in Commonwealth markets.
Product Segmentation
A dibber is a pointed hand tool, typically 150–300 mm in length with a tapered or bulbous handle, designed to create uniform holes in soil for seed, bulb, or seedling insertion at controlled depth and spacing. Metal variants—hardened steel or stainless alloys—dominate commercial farming use cases where repeated field insertion demands durability, while wooden and composite materials serve home gardening and landscaping segments prioritizing ergonomics and aesthetic integration. Handheld dibbers retain the largest volume share across amateur gardener and institutional end users, though electric dibbers represent the fastest-expanding category as battery-powered horticulture tools penetrate professional landscaping fleets. Plastic dibbers concentrate in entry-level retail channels, whereas composite materials capture margin pools among sustainability-oriented agricultural producers seeking reduced soil contamination risk.
Regulatory Environment
REACH governs chemical composition and surface treatment standards for metal dibbers sold in the European Union, while the EPA regulates pesticide-adjacent tool classifications in the United States where dibbers contact treated soils. BIS certification requirements in India and GB standards in China shape export eligibility for manufacturers sourcing components across Asia. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and emerging state-level green procurement mandates in California and New York that will determine which material certifications unlock institutional and municipal contracts.
Market Dynamics
Precision agriculture protocols are compressing dibber replacement cycles as professional landscapers and municipal groundskeepers demand calibrated depth consistency for seedling survival rates.
Growth Catalysts
- REACH surface-treatment mandates:EU chemical compliance is accelerating stainless-steel dibber adoption over zinc-coated alternatives, redirecting procurement toward certified European suppliers.
- Municipal greening programs:German cities including Hamburg and Stuttgart are embedding hand-tool specifications into public landscaping tenders, sustaining premium dibber demand.
- Battery-powered horticulture fleets:Electric dibbers are penetrating professional landscaping as lithium-ion tool platforms standardize across North American maintenance contractors.
Market Restraints
- Heritage hand-forging capacity:Dutch and British artisanal producers face generational skill attrition, constraining output of collector-grade forged-handled dibbers.
- Composite material certification costs:EU ECHA testing protocols for sustainable dibber substrates inflate R&D timelines for mid-tier manufacturers.
- Substitution by multi-function trowels:Combination planting tools threaten standalone dibber volume in entry-level retail channels.
Strategic Opportunities
- Subscription calibration services:Precision agriculture vendors can bundle seasonal depth-verification contracts with hardware sales, capturing recurring institutional revenue.
- California green procurement mandates:State-level sustainable purchasing rules are opening certified composite dibber access to municipal contracts.
- Sensor-integrated electric dibbers:Convergence of soil-moisture sensing and battery platforms enables premium positioning among data-driven agricultural producers.
Industry Challenges
- Artisanal forging skill transmission:Traditional blacksmithing expertise for heritage dibber production lacks structured apprenticeship pipelines in the Netherlands and Britain.
- Extended producer responsibility compliance:EU waste-framework obligations require manufacturers to establish reverse-logistics networks for end-of-life tool collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dibber Market |
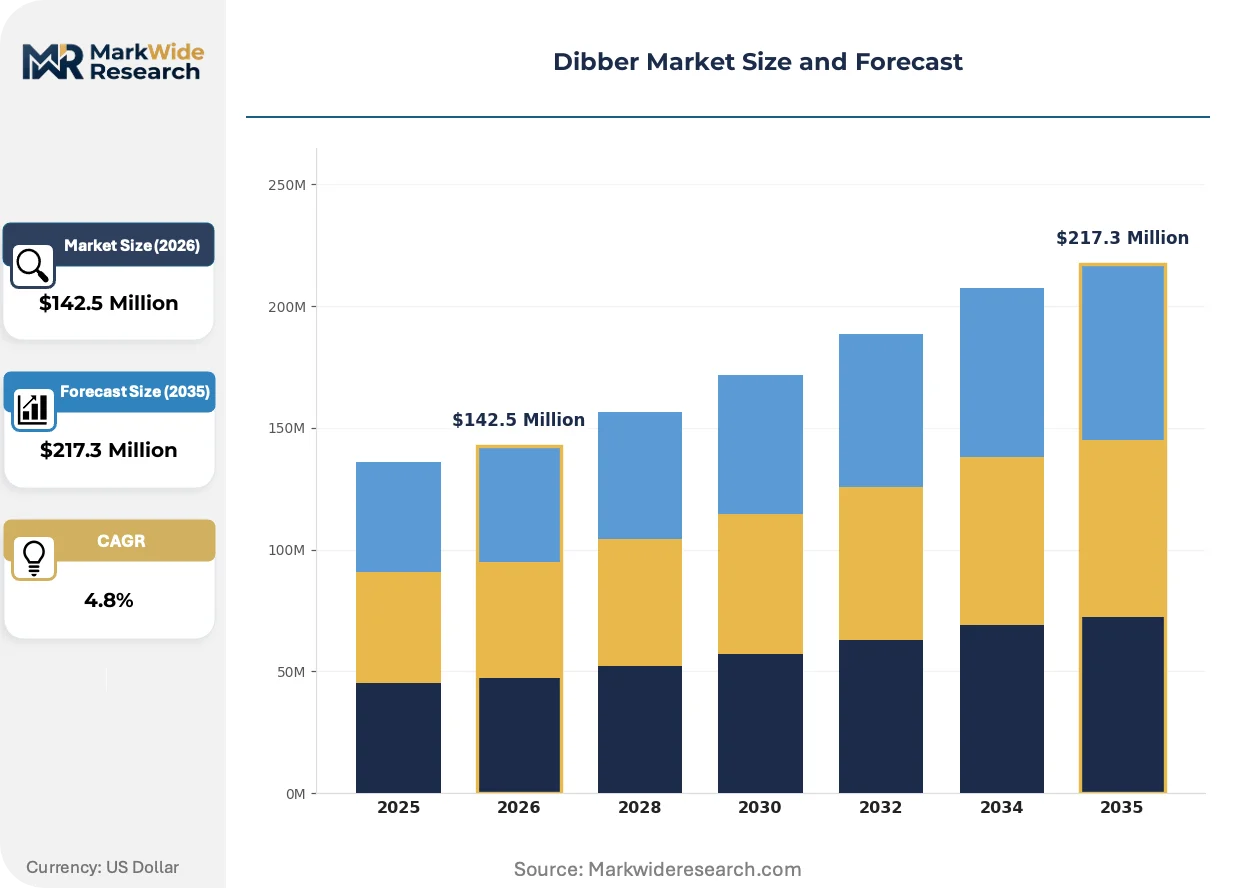
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Electric, Garden, Specialty Use Case: Home Gardening, Commercial Farming, Landscaping, Vegetable Cultivation Material: Plastic, Metal, Wood, Composite End User: Amateur Gardeners, Professional Landscapers, Agricultural Producers, Institutions |
| Companies Covered | Sneeboer, Burgon and Ball Company, Fiskars Group, Spear and Jackson Company, Zenport Industries, The Garden Tool Company, Bosmere Inc., Darlac Tool Company, RHS Enterprise Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dibber Market Strategic Shifts
Material science advances and digitized maintenance protocols are fragmenting dibber value chains into specialized hardware and service layers.
Carbon-fiber reinforced polymer dibbers are rewriting durability benchmarks for commercial agriculture. Large-scale vegetable producers in the Netherlands are piloting these lightweight alternatives to reduce operator fatigue during extended planting shifts. The technology is compressing replacement cycles for traditional metal variants while opening margin pools in ergonomic certification.
REACH Annex XVII restrictions on chromium(VI) surface treatments are forcing coating-method transitions across EU-sourced metal dibbers. Manufacturers are migrating toward trivalent chromium and ceramic-based alternatives, adding process complexity for forged-handled premium lines. German and French suppliers face the steepest compliance timelines given their concentration of heritage hand-tool production.
Direct-to-landscaper digital channels are displacing traditional garden-center distribution for professional-grade dibber procurement. North American landscaping fleets are consolidating purchases through specialized horticulture supply platforms, bypassing retail markup. This pattern is most pronounced in California and Texas, where large maintenance contractors negotiate volume pricing on calibrated electric dibber systems.
Dibber Market Segmentation
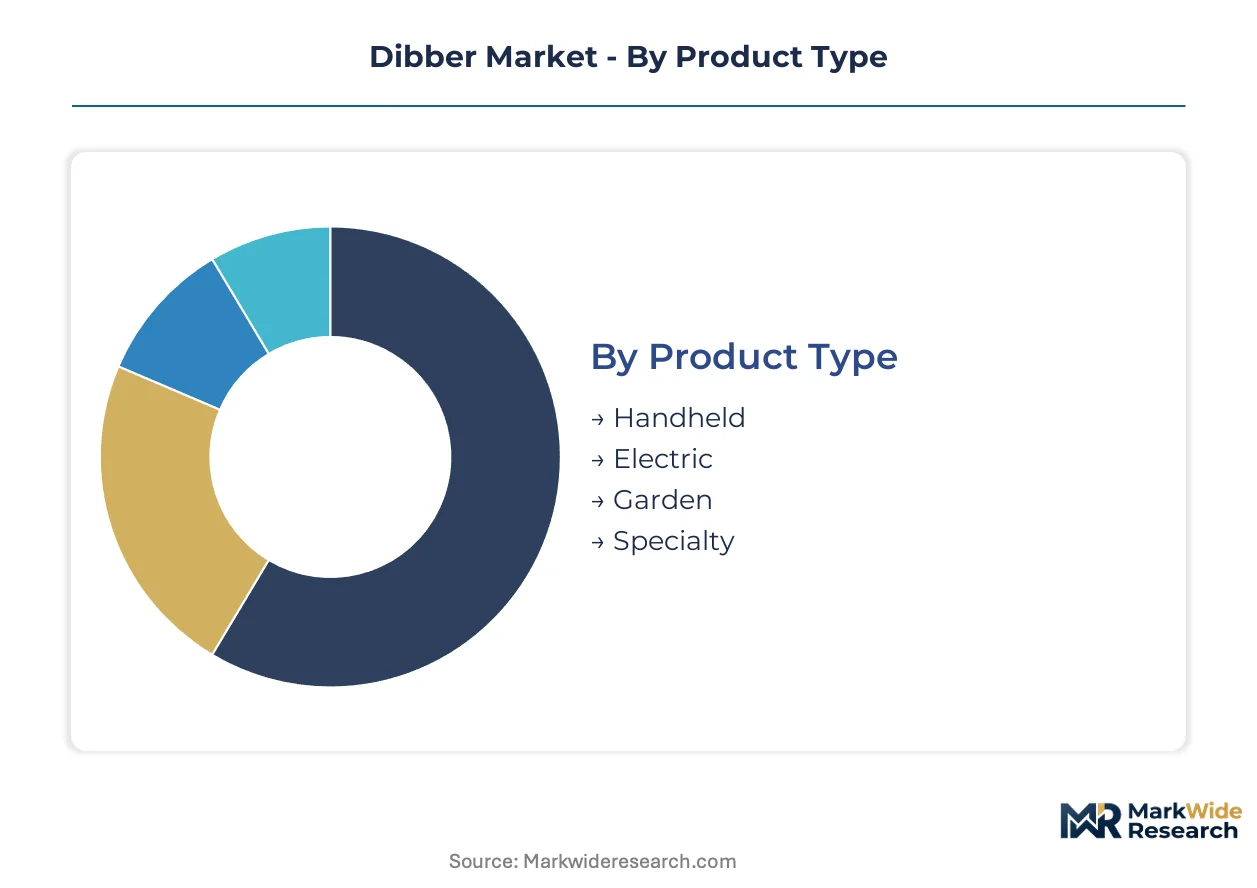
Dibber segmentation reveals divergent value chains across amateur and professional use cases. Material specifications and power source configurations create distinct margin pools that manufacturers must navigate through differentiated distribution strategies.
Product Type:
Standardization dominates entry-level channels while precision agriculture demands calibrated, customizable solutions.
- Handheld:Manual dibbers span 150–300 mm lengths with tapered or bulbous handles for controlled depth insertion. Demand concentrates among amateur gardeners in Germany and heritage-conscious Commonwealth markets where municipal greening programs specify traditional tool procurement.
- Electric:Battery-powered variants integrate with lithium-ion horticulture platforms standardizing across North American maintenance contractors. Sensor-integrated models with soil-moisture detection are gaining share fastest among data-driven agricultural producers.
- Garden:General-purpose dibbers optimized for residential planting tasks prioritize ergonomic handle design and aesthetic integration with garden storage systems.
- Specialty:Precision-calibrated instruments for bulb forcing, seedling transplantation, and controlled-environment agriculture serve institutional research stations and commercial nurseries.
Leading the category by volume: Handheld. Expanding most quickly: Electric.
Use Case:
Application intensity separates occasional residential use from fleet-deployed professional operations.
- Home Gardening:Weekend cultivation drives demand for wooden and composite-handled dibbers prioritizing tactile comfort and visual appeal over durability metrics.
- Commercial Farming:Large-scale vegetable producers in the Netherlands pilot carbon-fiber reinforced polymer variants to reduce operator fatigue during extended planting shifts. Carbon-fiber alternatives are compressing replacement cycles for traditional metal tools.
- Landscaping:Municipal groundskeepers and maintenance contractors across California and Texas consolidate procurement through specialized horticulture supply platforms, bypassing retail markup on calibrated electric systems.
- Vegetable Cultivation:Row-crop precision protocols demand consistent hole depth for seedling survival rates, accelerating adoption of depth-verified dibber systems.
Dominant by application scale: Commercial Farming. Steepest expansion trajectory: Landscaping.
Material:
Regulatory compliance costs and sustainability positioning fragment sourcing strategies across geographies.
- Plastic:Entry-level retail channels concentrate polypropylene dibbers where cost minimization outweighs longevity concerns. California green procurement mandates are restricting municipal access for uncertified variants.
- Metal:Hardened steel and stainless alloys serve repeated field insertion demands across commercial agriculture. REACH Annex XVII restrictions on chromium(VI) surface treatments are forcing German and French manufacturers toward trivalent chromium and ceramic-based coating alternatives.
- Wood:Forged-handled artisanal dibbers from Dutch and British producers command collector-tier pricing, though generational skill attrition constrains output expansion.
- Composite:Sustainable substrates reduce soil contamination risk for EU ECHA-certified agricultural producers. Testing protocol compliance inflates R&D timelines for mid-tier manufacturers.
Highest volume share: Metal. Gaining share fastest: Composite.
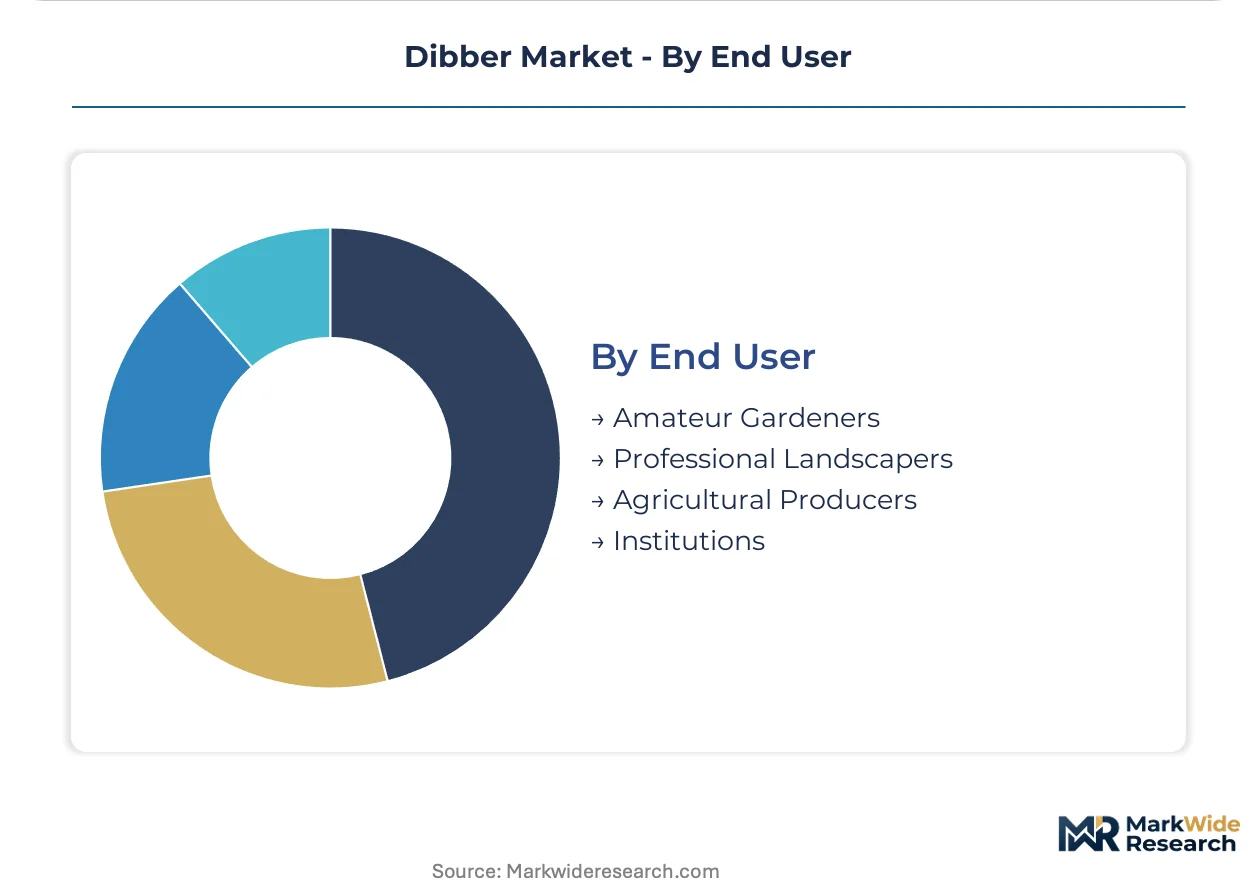
End User:
Procurement sophistication separates individual purchasers from institutional tender processes.
- Amateur Gardeners:Individual consumers purchase through garden centers and direct-to-consumer channels, prioritizing ergonomic certification and Nordic design heritage.
- Professional Landscapers:Fleet operators negotiate volume pricing on battery-powered tool platforms, consolidating purchases through specialized horticulture supply platforms in North America.
- Agricultural Producers:Precision agriculture protocols compress replacement cycles as large-scale operators demand calibrated depth consistency for seedling survival rates.
- Institutions:Municipal greening programs in Hamburg and Stuttgart embed hand-tool specifications into public landscaping tenders, sustaining premium dibber demand through formal procurement channels.
Largest customer base: Amateur Gardeners. Fastest-growing procurement segment: Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European forging centers while consumption spreads across precision agriculture adopters in North America and municipal greening programs in Germany. The Netherlands and Britain supply artisanal hand-forged dibbers. Battery-powered variants gain traction among North American landscaping contractors.
Germany
Municipal greening programs in Hamburg and Stuttgart sustain premium hand-tool procurement through formal tender specifications. REACH Annex XVII restrictions on chromium(VI) surface treatments force domestic manufacturers toward trivalent chromium and ceramic-based coating alternatives. The Ruhr Valley and Baden-Württemberg host heritage hand-tool production clusters adapting to compliance timelines.
United States
Professional landscaping fleets in California and Texas consolidate dibber procurement through specialized horticulture supply platforms. EPA regulations on pesticide-adjacent tool classifications shape requirements where dibbers contact treated soils. The Central Valley agricultural corridor pilots sensor-integrated electric dibbers among large-scale vegetable producers.
Netherlands
Carbon-fiber reinforced polymer dibbers reduce operator fatigue for commercial vegetable producers during extended planting shifts. EU ECHA testing protocols for sustainable substrates inflate R&D timelines for mid-tier manufacturers seeking certification. The Randstad region anchors artisanal forging capacity for collector-grade hand tools.
United Kingdom
Heritage-conscious Commonwealth markets drive demand for forged-handled dibbers commanding collector-tier pricing. Generational skill attrition constrains output expansion among traditional blacksmithing operations. The West Midlands and Sheffield retain concentration of hand-forge capacity despite apprenticeship pipeline gaps.
India
BIS certification requirements shape export eligibility for manufacturers sourcing components across Asian supply chains. Entry-level plastic dibbers concentrate in domestic retail channels serving home gardening segments. Maharashtra and Gujarat host emerging fabrication capacity targeting cost-sensitive agricultural implements.
Dibber Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent value chain positions in the dibber market. Forged-handled artisanal workshops maintain premium positioning through heritage craftsmanship while mass-market fabricators optimize injection-molding and stamping operations. Three archetypes dominate: heritage European forgers, Nordic design-led tool conglomerates, and Asian volume manufacturers. Competitive moves center on material certification investments for EU market access and direct-to-landscaper digital channel development.
Among heritage European forgers, Sneeboer and Burgon and Ball Company exemplify artisanal positioning through forged-handled construction and geographic design pedigrees. Fiskars Group represents the design-led conglomerate archetype, leveraging Nordic heritage and broad retail distribution across European garden centers. These three occupy distinct tier positions—Sneeboer and Burgon and Ball Company anchor collector-premium segments, while Fiskars Group bridges premium and mass-market channels through portfolio breadth.
| Leading Market Players |
|---|
| Sneeboer |
| Burgon and Ball Company |
| Fiskars Group |
| Spear and Jackson Company |
| Zenport Industries |
| The Garden Tool Company |
| Bosmere Inc. |
| Darlac Tool Company |
| RHS Enterprise Ltd |
| Others |
Value Chain & Pricing Dynamics
Carbon-fiber reinforced polymer adoption in commercial vegetable production is simultaneously compressing unit economics for traditional metal variants and concentrating procurement leverage among Netherlands-based material innovators. Battery-powered horticulture platforms standardizing across North American maintenance contractors are forcing coating-method transitions that reshape supplier tiering.
Pricing Analysis
Margin tightening in entry-level plastic dibbers traces to California green procurement mandates restricting municipal access for uncertified variants. Three-tier pricing structure across premium, standard, and economy levels separates forged-handled collector-grade instruments from injection-molded retail products from polypropylene disposables. Price differentiation hinges on REACH certification grade and volume scale in fleet procurement. Amateur gardeners exhibit highest price sensitivity, while institutional tenders in Hamburg and Stuttgart sustain premium positioning.
Supply Chain Analysis
EU ECHA testing protocols for sustainable substrates are gating supplier qualification, elongating R&D timelines for mid-tier manufacturers. Production concentrates in the Netherlands, Britain, and Germany, with carbon-fiber feedstock drawing from specialized polymer suppliers. Raw material dependencies include hardened steel alloys, FSC-certified hardwoods, and lithium-ion battery cells. Single-source vulnerability sits with heritage hand-forging capacity facing generational skill attrition. Distribution runs through specialized horticulture supply platforms displacing traditional garden-center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dibber market is executing a technology-transition phase as sensor-integrated electric variants displace calibrated handheld instruments in precision agriculture protocols.
For Market Incumbents: Deepen backward integration into carbon-fiber reinforced polymer supply to secure margin pools in ergonomic certification. Fortify REACH Annex XVII compliance capabilities in German and French production clusters before trivalent chromium transition deadlines. Multi-function trowel substitution in entry-level retail channels demands portfolio diversification into battery-powered platforms. For New Entrants and Emerging Players: Specialized horticulture supply platforms offer the most penetrable channel wedge for calibrated electric dibber systems. Municipal greening programs in German cities present white-space tender opportunities requiring formal procurement navigation. Direct-to-landscaper digital channels enable bypass of retail markup consolidation in California and Texas. For Investors and Strategic Acquirers: Re-rating potential sits with sensor-integrated electric dibber specialists given convergence of soil-moisture sensing and battery platform standardization. Long-term viability favors manufacturers with established EU ECHA certification and lithium-ion tool platform integration. Watch for inflection in California state-level green procurement mandate enforcement as signal for composite material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Product Launch | Soil-moisture detection capabilities enable premium positioning among data-driven agricultural producers. |
| REACH Compliance Investment | Trivalent chromium coating transitions unlock continued EU market access for heritage forged-handled lines. |
| Direct-to-Landscaper Channel Expansion | Specialized horticulture supply platforms displace garden-center distribution in North American fleet procurement. |
| Carbon-Fiber Supply Agreement | Reinforced polymer feedstock secures lightweight variant production for Netherlands vegetable producers. |
| Subscription Calibration Service | Seasonal depth-verification contracts capture recurring institutional revenue beyond hardware sales. |
Study Parameters
Multi-period observation of municipal tender specifications, battery platform adoption rates, and REACH compliance timelines anchored the trend analysis, supplemented by interviews with landscaping fleet managers, heritage tool forgers, agricultural procurement officers, and composite material R&D directors. Secondary validation drew from EU ECHA regulatory filings, German municipal procurement databases, lithium-ion horticulture tool platform disclosures, and customs records for carbon-fiber reinforced polymer trade flows. Bottom-up segment sizing triangulated against top-down market aggregation.
Segment-weighting across material type, power source configuration, end-user procurement sophistication, and geographic regulatory cluster shaped the analytical framework. CAGRs were derived from trajectory fitting across the projection horizon. Industry-specific forecast inputs included municipal greening program budget allocations and battery platform standardization curves among North American maintenance contractors.
Caveats apply where REACH Annex XVII enforcement intensity or lithium-ion cell supply constraints could materially shift the outlook. Forecasts reflect documented assumptions on substitution elasticity between handheld and electric variants. A model refresh is warranted upon material change in California green procurement mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Needlecraft Patterns Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
Craft Supplies Market