
 Global K-12 Arts and Crafts Material Market | 2026-2036
Global K-12 Arts and Crafts Material Market Size, Share, and Industry Trends Forecast 2026-2036
Global K-12 Arts and Crafts Material Market Foresight
Non-toxic ASTM D-4236 certification is reorganizing procurement standards across the Global K-12 Arts and Crafts Material Market. Crayola LLC leverages its vertically integrated Pennsylvania manufacturing to control raw material quality from pigment sourcing to finished crayon. Faber-Castell AG anchors premium positioning through its proprietary SV-bonded colored pencil technology and cedar wood supply chain. STAEDTLER Mars GmbH & Co. KG competes on precision instrument heritage, extending its technical drawing expertise into ergonomic student tools.
Global K-12 Arts and Crafts Material encompasses consumable and reusable supplies engineered for child-safe creative expression in structured educational environments, typically formulated with water-based pigments, certified non-toxic binders, and age-appropriate tool geometries. Acrylic paints and colored pencils dominate volume due to their durability and color saturation, while modeling clay captures margin expansion through premium polymer formulations. Specialty stores and school suppliers still handle the bulk of institutional procurement, though online retailers are capturing home-school and parent segments with subscription-based replenishment models.
FDA oversight through 21 CFR 175.105 indirect food additive rules and Consumer Product Safety Commission CPSIA lead-content limits govern U.S. classroom material compliance, while REACH chemical registration in the European Union restricts phthalate plasticizers in modeling compounds. These frameworks force reformulation cycles that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor pending state-level green chemistry legislation in California and New York, as these jurisdictions typically set precedents for broader North American adoption timelines.
Market Dynamics
ASTM D-4236 non-toxic certification mandates are compressing supplier margins while consolidating procurement authority among institutional buyers with dedicated compliance teams. School districts now require batch-level traceability from pigment sourcing through finished goods, favoring manufacturers with captive laboratory testing facilities.
Growth Catalysts
- STEAM curriculum mandates:State education departments in the United States and Germany now mandate weekly art instruction with measurable creative assessment rubrics. Districts allocate dedicated budgets for consumable material replenishment.
- REACH chemical registration:ECHA's expanded substance restrictions on phthalate plasticizers in modeling compounds force reformulation toward bio-based polymer alternatives. Premium positioning opens for compliant European manufacturers.
- Home-school segment expansion:Parent-led education collectives in Australia and Canada drive subscription-based replenishment models for age-graded craft kits. Online retailers capture recurring revenue streams outside institutional procurement cycles.
Market Restraints
- Pigment cost volatility:Titanium dioxide and organic azo pigment prices fluctuate with energy-intensive German and Chinese production schedules. Water-based acrylic formulations absorb margin compression disproportionately.
- Supply concentration in cedar sourcing:Premium colored pencil manufacturers depend on PEFC-certified cedar forests concentrated in California and Japanese Hokkaido regions. Climate-related harvest disruptions propagate through finished goods pricing.
- Substitution by digital drawing tablets:Secondary schools in South Korea and Finland replace consumable sketching supplies with stylus-based devices for technical drawing modules. Art supply vendors lose volume in grades seven through twelve.
Strategic Opportunities
- Underpenetrated Brazilian public system:Municipal education networks outside São Paulo and Rio de Janeiro lack structured art curricula. Local distribution partnerships with established stationery wholesalers unlock district-level contracts.
- Green chemistry legislation tailwinds:California's pending Safer Consumer Products regulations and New York's Toxics in Packaging laws create first-mover advantage for bio-based binder formulations. Early certification builds procurement preference.
- 3D printing filament convergence:Polymer modeling clay manufacturers extend formulation expertise into PLA and ABS filaments for classroom additive manufacturing stations. Art suppliers capture STEAM lab budgets previously siloed in technology categories.
Industry Challenges
- Regulatory affairs talent scarcity:CPSIA lead-content testing and REACH SVHC documentation require specialized chemists and compliance officers. Mid-tier manufacturers struggle to staff dedicated certification teams.
- Legacy ERP integration friction:Batch-level traceability requirements demand real-time inventory systems incompatible with decades-old procurement software common in United States school districts. Implementation timelines delay contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global K-12 Arts and Crafts Material Market |
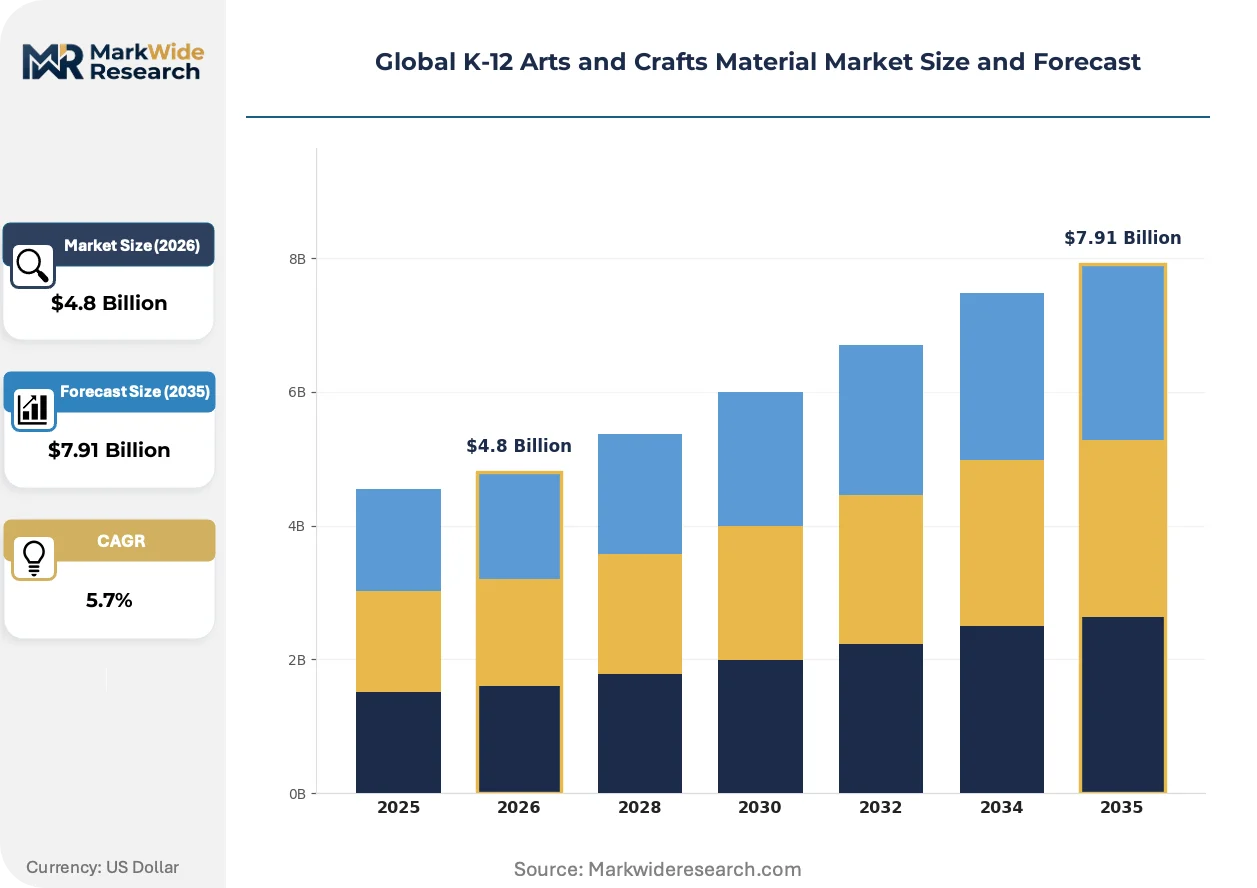
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawing Paper, Acrylic Paints, Modeling Clay, Glue Sticks, Watercolors, Colored Pencils Application: Art Projects, DIY Crafts, Educational Workshops, Creative Therapy, Skill Development, School Events End User: Primary Schools, Secondary Schools, Home-School Programs, After-School Clubs, Art Institutions, Community Centers Sales Channel: Specialty Stores, Online Retailers, School Suppliers, Supermarkets, Warehouse Clubs, Catalog Distributors |
| Companies Covered | Crayola LLC, School Specialty, Michaels Stores, STAEDTLER Mars GmbH & Co. KG, Kaplan Early Learning Company, Pacon Corporation, Faber-Castell AG, Ningbo Rainma Stationery, TTS Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global K-12 Arts and Crafts Material Market Shifts & Advancements
Water-based pigment chemistry and digital design tools are converging to reshape how creative materials reach classrooms. Manufacturers now compete on formulation transparency and pedagogical integration rather than color range alone.
Alcohol-free marker ink systems are decomposing the solvent-based dominance that defined professional illustration for decades. Primary art teachers in Ontario and Bavaria specify odorless, xylene-free formulations for enclosed classroom environments. The shift compresses demand for traditional solvent carriers while expanding addressable market share in early childhood segments previously excluded due to ventilation constraints.
EU Green Deal chemical sustainability criteria are forcing disclosure of carbon intensity across the full pigment supply chain. ECHA's SCIP database requirements now obligate notification of substances of very high concern in concentrations above 0.1 percent. German and French school procurement consortia have begun screening suppliers against these thresholds, disqualifying manufacturers without lifecycle assessment documentation.
Parent purchasing patterns now favor curated monthly subscription boxes over retail aisle selection for home art consumption. Home-school networks in Texas and Alberta coordinate bulk orders through dedicated educational supply platforms, bypassing traditional brick-and-mortar channels. This disintermediation concentrates buyer power among platform operators who negotiate exclusive formulation contracts with mid-sized manufacturers.
Global K-12 Arts and Crafts Material Market Segmentation
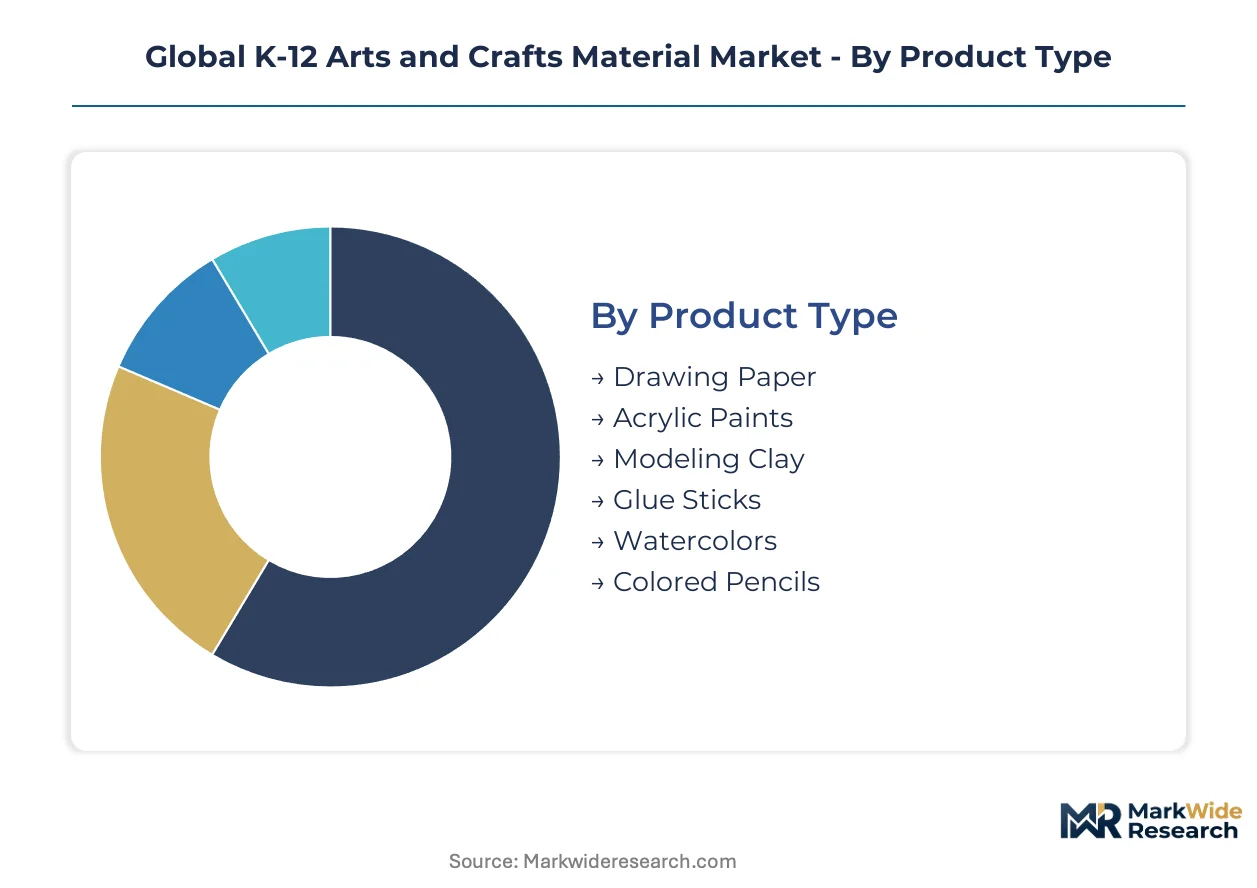
Segmentation in the Global K-12 Arts and Crafts Material Market reveals where digital substitution pressure concentrates versus where tactile material demand proves durable. Understanding these fault lines guides resource allocation across formulation R&D and channel investments.
Product Type:
Digital stylus tablets and screen-based creative tools threaten certain analog segments more severely than others, reshaping procurement priorities across institutional buyers.
- Colored Pencils:SV-bonded cedar wood construction delivers break-resistant cores essential for precision shading exercises. German and Japanese primary schools specify these for weekly art curriculum mandates despite per-unit premiums.
- Acrylic Paints:Water-based pigment suspensions with ASTM D-4236 certification dominate volume through durability and washability. United States school districts in Texas and California allocate replenishment budgets here as STEAM lab investments expand.
- Drawing Paper:Acid-free cellulose formulations support archival student portfolios required for assessment rubrics in Ontario and Bavaria.
- Modeling Clay:Polymer and air-dry variants face REACH phthalate restrictions driving bio-based reformulation costs.
- Glue Sticks:PVA solid adhesives with child-safe applicator geometries serve early childhood segments where ventilation constraints exclude solvent alternatives.
- Watercolors:Pan and liquid formats retain steady demand in Japanese elementary schools with traditional painting curriculum requirements.
Acrylic paints anchor the volume base while colored pencils gain share at the steepest rate.
Application:
Cost tier stratification separates consumable replenishment cycles from capital-intensive program investments across institutional budgets.
- Art Projects:Curriculum-integrated assignments requiring ASTM-certified consumables on predictable replenishment schedules. United States Title I schools in Illinois and Georgia drive volume through federal arts education grants.
- DIY Crafts:Parent-purchased home activity kits with age-graded difficulty levels. Subscription platforms in Alberta and Texas coordinate bulk procurement outside institutional channels.
- Educational Workshops:Time-bound intensive programs demanding higher material throughput per student-hour.
- Creative Therapy:Specialized non-toxic formulations for occupational therapy settings in Canadian school districts.
- Skill Development:Progressive technique modules from basic motor control to advanced color theory.
- School Events:Seasonal demand spikes for fairs and exhibitions with compressed procurement timelines.
Art projects command the largest absolute spend while DIY crafts expand most quickly through home-school network coordination.
End User:
Customer type determines compliance burden intensity and purchasing authority concentration across fragmented decision-making structures.
- Primary Schools:District-level procurement with dedicated compliance teams managing CPSIA batch traceability. Municipal networks in Germany's Bavaria and North Rhine-Westphalia regions mandate weekly art instruction with measurable outcomes.
- Home-School Programs:Parent collectives in Australia and Canada bypass traditional distribution through educational supply platforms negotiating exclusive formulations.
- Secondary Schools:Digital substitution pressure concentrates here as South Korean and Finnish technical drawing modules adopt stylus-based devices.
- After-School Clubs:Non-profit operators with limited storage capacity favor just-in-time replenishment models.
- Art Institutions:Museum-affiliated youth programs with premium positioning requirements.
- Community Centers:Municipal recreation departments with seasonal budget cycles.
Primary schools generate the steadiest demand flow while home-school programs climb the fastest through platform-enabled consolidation.
Sales Channel:
Supply concentration in legacy procurement systems creates friction against real-time traceability requirements now mandatory for district contracts.
- School Suppliers:Institutional procurement specialists with dedicated compliance documentation and volume pricing structures. United States regional distributors in the Northeast and Midwest maintain decades-long district relationships.
- Online Retailers:Subscription-based replenishment platforms capturing home-school segments with curated monthly kits. Australian and Canadian parent networks coordinate bulk orders through these channels.
- Specialty Stores:Independent retailers with localized inventory and art educator staff expertise.
- Supermarkets:Seasonal back-to-school aisles with limited certification transparency.
- Warehouse Clubs:Bulk packaging for parent stockpiling with minimal pedagogical curation.
- Catalog Distributors:Legacy print-based procurement common in rural United States districts with outdated ERP systems.
School suppliers retain the largest contract value while online retailers gain share fastest through home-school segment capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Home-school buyers in Canada and Australia absorb premium pricing for certified kits, while Brazilian municipal districts prioritize volume discounts over compliance documentation.
United States
Texas and California school districts drive institutional volume through STEAM lab expansion mandates. The Consumer Product Safety Commission enforces CPSIA lead-content limits with batch-level traceability requirements. Pennsylvania hosts vertically integrated pigment-to-finished-goods manufacturing clusters serving Northeast corridor procurement contracts.
Germany
Bavaria and North Rhine-Westphalia mandate weekly art instruction with measurable outcome rubrics. ECHA REACH regulations restrict phthalate plasticizers in modeling compounds, favoring domestic reformulation capabilities. Nuremberg-area manufacturers leverage SV-bonded pencil technology for premium positioning in European institutional tenders.
China
Zhejiang and Guangdong provinces concentrate export-oriented manufacturing for water-based pigment formulations. The country's national standards body aligns GB safety specifications with ASTM D-4236 for North American market access. Ningbo stationery clusters supply cost-optimized glue sticks and acrylic paints to Australian and Canadian home-school platforms.
Brazil
Municipal networks outside São Paulo and Rio de Janeiro lack structured art curricula, creating greenfield procurement opportunities. ANVISA oversees cosmetic-grade safety standards that partially overlap with classroom material compliance. São Paulo-based stationery wholesalers negotiate district-level contracts for basic consumable replenishment cycles.
Australia
Parent collectives in New South Wales and Victoria coordinate subscription-based bulk orders through educational supply platforms. The TGA oversees therapeutic goods while state education departments specify non-toxic certification for classroom materials. Melbourne distributors curate age-graded craft kits bypassing traditional retail channels.
Global K-12 Arts and Crafts Material Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Global K-12 Arts and Crafts Material Market. Established European and North American manufacturers control premium formulation certification and captive laboratory testing, while Asian fabricators dominate volume production of standardized consumables. Three archetypes define competitive positioning: heritage brands with regulatory affairs depth, vertically integrated pigment specialists, and platform-captive contract manufacturers serving subscription channels. Consolidation pressures favor M&A activity among mid-tier compliance-strapped players, while geographic expansion into underpenetrated Latin American districts accelerates.
Within the heritage-brand tier, Crayola LLC and Faber-Castell AG exemplify regulatory-first positioning through decades of CPSIA and REACH compliance infrastructure. STAEDTLER Mars GmbH & Co. KG occupies a precision-instrument niche extending technical drawing heritage into ergonomic student tools. Among platform-aligned fabricators, Ningbo Rainma Stationery represents cost-optimized supply for Australian and Canadian home-school subscription operators. School Specialty and Kaplan Early Learning Company sit within institutional procurement specialists, anchoring district-level contract relationships with dedicated compliance documentation teams.
| Leading Market Players |
|---|
| Crayola LLC |
| School Specialty |
| Michaels Stores |
| STAEDTLER Mars GmbH & Co. KG |
| Kaplan Early Learning Company |
| Pacon Corporation |
| Faber-Castell AG |
| Ningbo Rainma Stationery |
| TTS Group |
| Others |
Supply & Pricing Matrix
Ninety-day pigment-to-shelf lead times for ASTM-certified acrylics concentrate pricing power with German and Chinese manufacturers possessing captive laboratory testing, while inventory carrying costs at United States school distributors compress margins on non-certified economy tiers. Procurement officers in Texas and California districts leverage batch-traceability mandates to extract volume discounts from suppliers lacking vertical pigment sourcing.
Pricing Analysis
Replenishment subscription revenue from home-school platforms in Alberta and Texas drives lifetime value above per-unit transactional margins. Three-tier pricing structure across premium SV-bonded pencils, standard water-based paints, and economy glue sticks separates certification-grade products from basic consumables. Cost compression in economy acrylics intensifies because titanium dioxide feedstock volatility absorbs margin at Ningbo manufacturing clusters. Home-school parent collectives show lowest price sensitivity for curated monthly kits, while Brazilian municipal districts prioritize volume discounts over compliance documentation.
Supply Chain Analysis
China and Germany anchor water-based pigment formulation and SV-bonded pencil manufacturing respectively, with Pennsylvania hosting the only vertically integrated crayon production cluster in North America. Cedar wood for premium colored pencils draws from PEFC-certified forests in California and Japanese Hokkaido regions. Single-source vulnerability concentrates in German titanium dioxide processing for high-opacity acrylics. Distribution runs through regional school suppliers with decades-long district relationships in the United States Northeast and Midwest, though online platforms disintermediate home-school segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital stylus tablets threaten analog sketching supplies in secondary grades, forcing incumbents to defend tactile material relevance through STEAM curriculum integration and non-toxic certification moats.
For Market Incumbents: Compound regulatory affairs capabilities into subscription-based replenishment platforms serving Australian and Canadian home-school networks. Deepen backward integration into pigment sourcing to buffer titanium dioxide volatility. Defend against digital substitution by embedding art supplies into mandated STEAM lab budgets. For New Entrants and Emerging Players: Subscription curation services for age-graded craft kits represent the widest service-layer gap where incumbents under-serve parent collectives. Target Brazilian municipal districts outside São Paulo through partnerships with established stationery wholesalers. Penetrate via exclusive formulation contracts with educational supply platforms coordinating bulk home-school orders. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier manufacturers lacking dedicated CPSIA and REACH compliance teams. Long-term viability hinges on regulatory capacity depth rather than volume scale alone. Watch for California Safer Consumer Products implementation as inflection signal favoring bio-based binder investments.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | CPSIA and REACH compliance teams unlock district-level contracts in Texas and Bavaria. |
| Subscription Platform Partnership | Exclusive supply agreements with Australian educational platforms capture recurring home-school revenue. |
| Bio-based Binder Reformulation | California green chemistry laws create first-mover procurement preference for compliant manufacturers. |
| Backward Pigment Integration | Captive titanium dioxide sourcing insulates margin from German and Chinese energy price volatility. |
| Brazilian Distribution Alliance | Local wholesaler partnerships unlock municipal contracts in underpenetrated districts beyond São Paulo. |
Research Methodology
Cross-validation between procurement officer interviews and customs trade data anchors the qualitative findings on supply concentration. Primary discussions with district-level buyers, art curriculum coordinators, regulatory affairs directors at pigment suppliers, and home-school platform operators combined with secondary validation from ECHA substance registrations, CPSC recall databases, and Brazilian ANVISA safety guidelines. Bottom-up demand modeling from school district budget allocations triangulates against top-down trade flow analysis.
Sensitivity analysis across pigment cost scenarios and digital substitution rates frames the projection horizon. Segmentation dimensions include product type, end-user grade level, procurement channel, and regional regulatory cluster. CAGRs derive from enrollment trend extrapolation, STEAM mandate adoption curves, and subscription platform penetration rates. Industry-specific inputs encompass ASTM D-4236 certification adoption timelines and REACH SVHC disclosure thresholds.
Material uncertainties — regulatory timeline shifts, cedar harvest disruptions, and digital stylus adoption acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about curriculum mandate durability and parent collective coordination feasibility. Recalibration cycles align with material shifts in state-level green chemistry legislation and district ERP modernization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
Needlecraft Patterns Market