
 Craft Supplies Market | 2026-2036
Craft Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Supplies Market Outlook
Online craft marketplaces and direct-to-maker platforms are reshaping how independent artisans source pigments, papers, and cutting tools. Michaels Stores leverages its private-label portfolio to sustain margin control across paper and paint categories. Cricut anchors digital die-cutting demand with proprietary design software that locks in consumables revenue. Hobbycraft dominates the United Kingdom specialist retail channel through localized store networks and educator-focused programming.
Craft supplies encompass raw and finished materials including pigment-based paints, cellulose papers, synthetic and natural bristle brushes, and hand or powered tools used to manipulate these inputs into decorative or functional objects; acrylic emulsion paints typically contain titanium dioxide at fifteen to thirty percent by weight for opacity and lightfastness. Papers, Paints, Brushes, and Tools serve distinct manufacturing and user requirements, with Paints carrying the highest margin pool due to proprietary pigment chemistry and repeat purchase frequency. Scrapbooking, DIY Projects, Home Décor, and Educational Use applications split along project duration and material intensity, with Educational Use generating institutional volume contracts that stabilize seasonal demand fluctuations.
REACH chemical safety standards in Europe and the EPA's Toxic Substances Control Act in the United States govern volatile organic compound limits in solvent-based coatings, compelling reformulation toward water-based acrylic systems. The Consumer Product Safety Commission enforces lead content thresholds in children's art materials, directly affecting Crayola's domestic production specifications and import testing protocols. Stakeholders must monitor evolving state-level extended producer responsibility laws for packaging waste that will redistribute cost structures across Online Stores, Craft Fairs, Retail Chains, and Wholesalers distribution channels.
Market Dynamics
REACH chemical safety standards in Europe and EPA's Toxic Substances Control Act are forcing solvent-free paint reformulations across the craft supplies value chain, compressing legacy coating margins while elevating water-based acrylic systems.
Growth Catalysts
- DIY Home Décor Expansion:Millennial homeowners in the United States are driving material purchases for personalized interior projects, expanding pigment and paper demand through sustained project-based consumption cycles.
- Educational Procurement Contracts:Institutional volume agreements for K-12 art programs stabilize seasonal demand fluctuations, locking in recurring orders for brushes, papers, and non-toxic paint formulations.
- Digital Design-to-Cut Integration:Proprietary software ecosystems that connect vector design tools with die-cutting hardware are locking in consumables revenue through file-format exclusivity and blade-cartridge pairing.
Market Restraints
- Titanium Dioxide Cost Volatility:Pigment-grade TiO2 supply concentrates among Chinese sulfate-process producers, exposing acrylic paint manufacturers to input price swings and margin compression.
- REACH Compliance Burden:ECHA registration requirements for solvent-based coatings create fixed compliance costs that disproportionately burden small-batch artisan formulators against scaled competitors.
- Digital Substitution Threat:Tablet-based drawing applications and 3D modeling software are displacing physical sketching and modeling supplies among younger demographic cohorts.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:EU packaging waste directives and emerging state-level EPR laws in California and New York create first-mover advantages for recyclable-brush and refillable-paint systems.
- Sustainable Material Convergence:Bio-based binder chemistry combined with agricultural waste-derived cellulose is opening premium positioning for carbon-accounted craft papers and plant-pigment formulations.
- Direct-to-Maker Platforms:Specialized e-commerce channels that aggregate independent artisans are bypassing traditional retail markups and capturing margin through subscription-based consumables replenishment.
Industry Challenges
- Formulation Chemist Scarcity:Water-based acrylic systems require expertise in emulsion polymerization and VOC-compliant rheology modification that outpaces current technical training pipeline output.
- Multi-Jurisdiction Certification Timelines:ASTM D-4236 toxicity labeling for children's art materials, combined with CE marking and state-level disclosure requirements, extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Supplies Market |
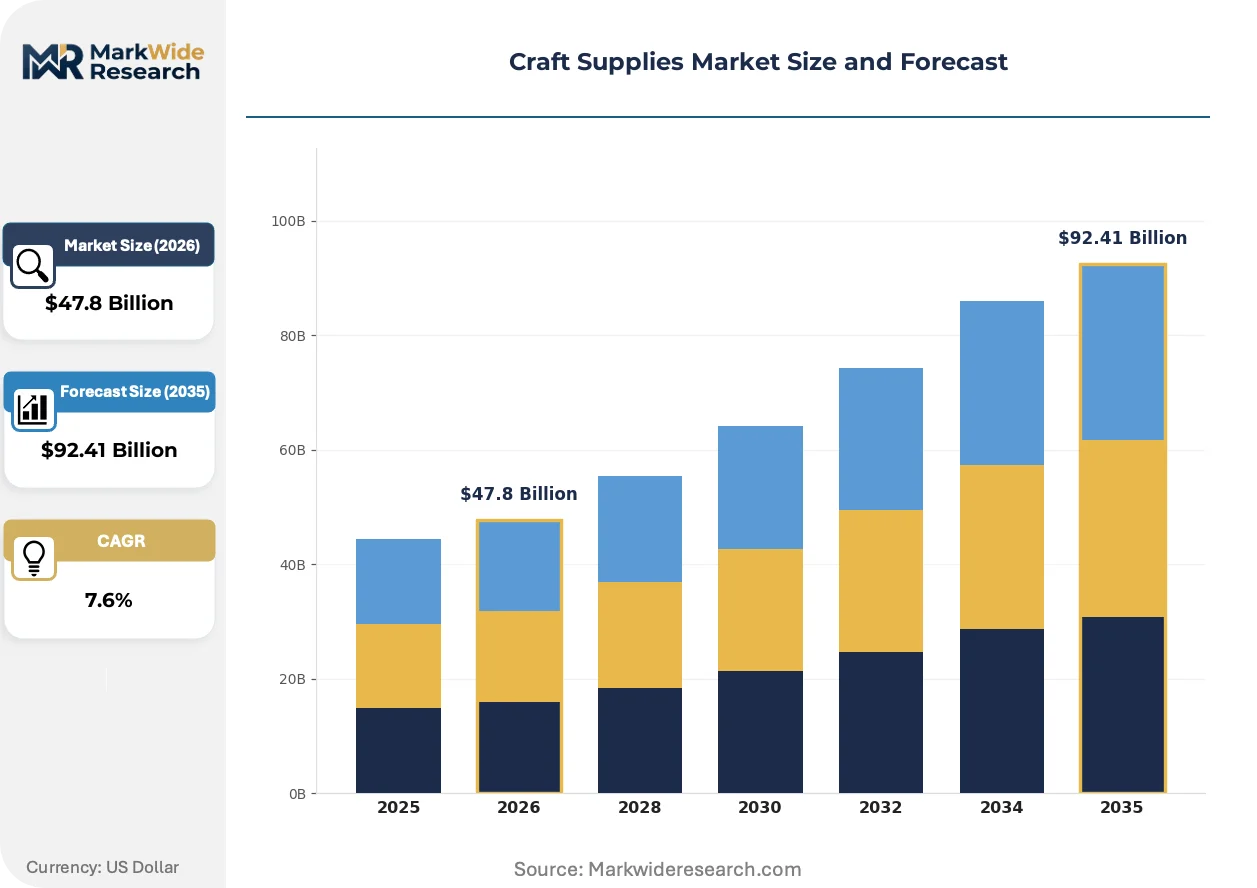
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $92.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Papers, Paints, Brushes, Tools Application: Scrapbooking, DIY Projects, Home Décor, Educational Use Customer Type: Artisans, Hobbyists, Educators, Retailers Distribution Channel: Online Stores, Craft Fairs, Retail Chains, Wholesalers |
| Companies Covered | Michaels Stores, Hobby Lobby, Joann Stores, Blick Art Materials, Crayola, Cricut, Daiso, Hobbycraft, Walmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Supplies Market Strategic Shifts
Water-based acrylic chemistry and digital fabrication workflows are collapsing traditional boundaries between amateur craft and professional production, reshaping how materials are specified, purchased, and consumed across project types.
Photopolymer resin formulations for desktop UV curing are collapsing the cost barrier between handcrafted jewelry and small-batch manufacturing. Independent artisans in Germany and the Netherlands are adopting entry-level stereolithography systems at rates exceeding 40% annual equipment growth. This hardware diffusion is collapsing the distinction between hobbyist material experimentation and commercial product prototyping.
REACH Annex XVII restrictions on chromium VI pigments and cadmium-based colorants are compelling reformulation across decorative coating categories. ECHA sunset dates for restricted substances are forcing pigment houses to accelerate lightfast organic alternatives through stability testing protocols. Decorative painters in France and Italy face compressed color-matching workflows as legacy inorganic pigments exit supply chains.
Subscription-based replenishment models for consumables are replacing project-based purchasing among dedicated hobbyists. Cricut's auto-ship blade and mat programs, mirrored by comparable offerings from Silhouette America, are capturing predictable revenue from high-frequency users. This pattern concentrates most visibly in the United States, where warehouse club partnerships amplify bulk-consumables penetration.
Craft Supplies Market Segmentation
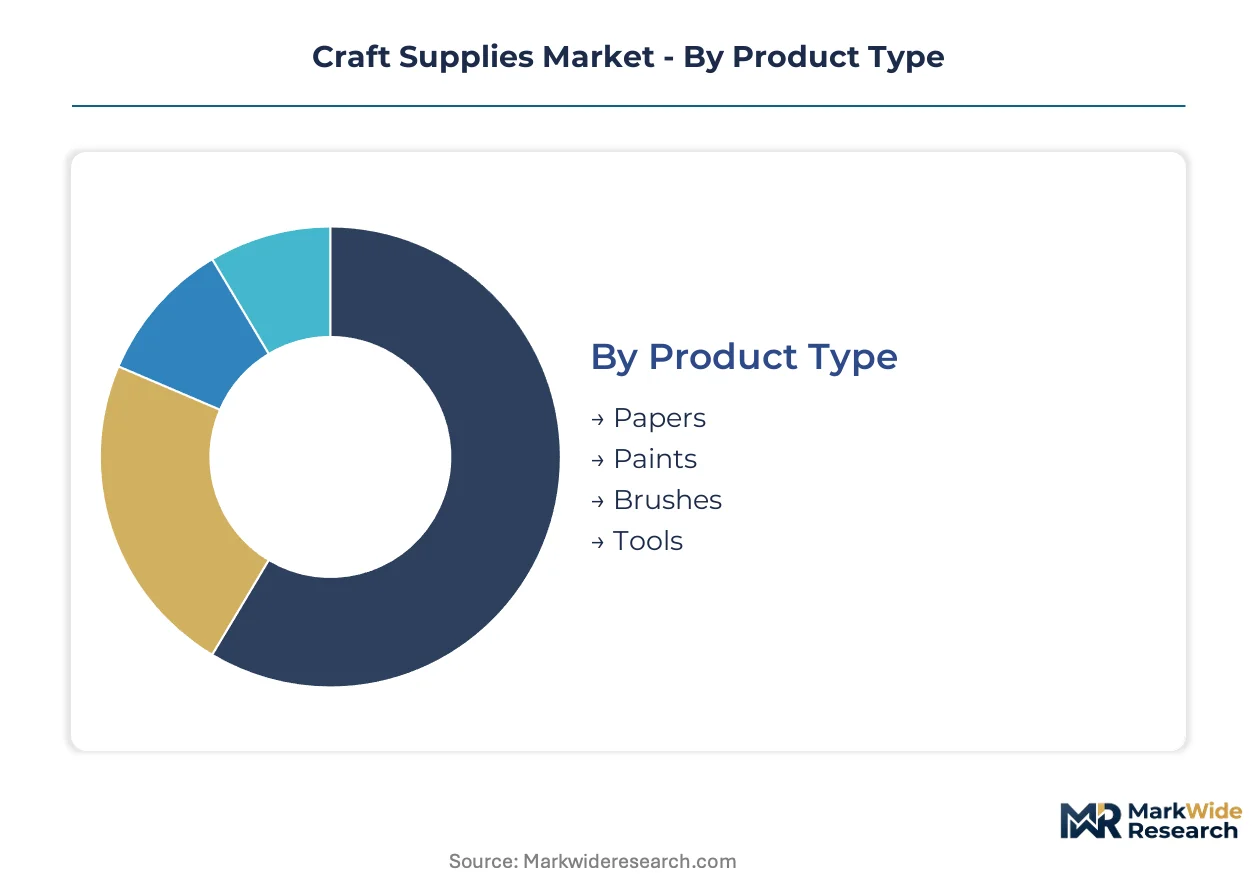
Segmentation in craft supplies reveals how margin pools concentrate across material chemistry, project duration, and procurement authority. Each dimension exposes different pricing power, inventory velocity, and regulatory exposure for suppliers and retailers.
Product Type:
Cost tier separates commodity cellulose from proprietary pigment systems, with chemistry sophistication determining margin capture and reformulation burden.
- Paints:Acrylic emulsion systems carry titanium dioxide loadings between fifteen and thirty percent by weight, delivering opacity and lightfastness for decorative applications. Demand clusters in millennial homeowner DIY projects across the United States, where repeat purchase cycles and proprietary color matching sustain premium positioning against private-label alternatives.
- Papers:Cellulose substrates range from acid-free archival sheets to recycled craft stock, with grammage and surface sizing determining compatibility with wet media. Educational procurement contracts in the United Kingdom and Germany stabilize volume demand, though REACH-compliant bleaching processes elevate base stock costs relative to Asian imports.
- Brushes:Synthetic filament extrusion and natural bristle sourcing serve distinct viscosity and finish requirements across water-based and solvent coatings.
- Tools:Hand-operated cutting implements and powered die-cutting hardware span entry-level polymer construction to professional-grade metal alloys.
Paints hold installed capacity. Papers is rotating up the share rankings.
Application:
Project duration and material intensity split demand between impulse-driven single-session consumption and multi-week builds requiring staged replenishment.
- Home Décor:Large-surface treatments and furniture refinishing drive bulk substrate and coating purchases with extended project timelines. United States millennial homeowners anchor this segment through personalized interior customization, with Pinterest and Instagram content cycles accelerating project initiation rates.
- Educational Use:K-12 art programs and institutional craft instruction generate recurring volume contracts with standardized material specifications. Non-toxic certification requirements under the Consumer Product Safety Commission and ASTM D-4236 labeling protocols extend procurement lead times but lock in multi-year supplier relationships.
- DIY Projects:Gift-making and seasonal crafts produce concentrated demand spikes around holiday periods.
- Scrapbooking:Memory preservation and paper-crafting sustain niche premium positioning for archival-quality materials.
Educational Use holds installed capacity. Home Décor is climbing the fastest.
Customer Type:
Procurement authority and technical sophistication separate institutional buyers from individual enthusiasts, reshaping channel strategy and service requirements.
- Retailers:Specialty craft chains and independent stores aggregate demand across fragmented end-users, capturing margin through private-label development and exclusive distribution agreements. Michaels Stores and Hobbycraft in the United Kingdom leverage localized inventory planning and educator programming to defend foot traffic against digital substitution.
- Artisans:Commercial makers and small-batch producers specify materials for resale, requiring batch consistency and certification documentation. Direct-to-maker platforms are bypassing traditional wholesale markups through subscription-based consumables replenishment, concentrating in Germany and the Netherlands where stereolithography hardware adoption exceeds forty percent annually.
- Hobbyists:Dedicated enthusiasts drive consumables velocity through sustained project engagement.
- Educators:School district procurement officers negotiate volume pricing with toxicity compliance guarantees.
Retailers hold installed capacity. Artisans is rotating up the share rankings.
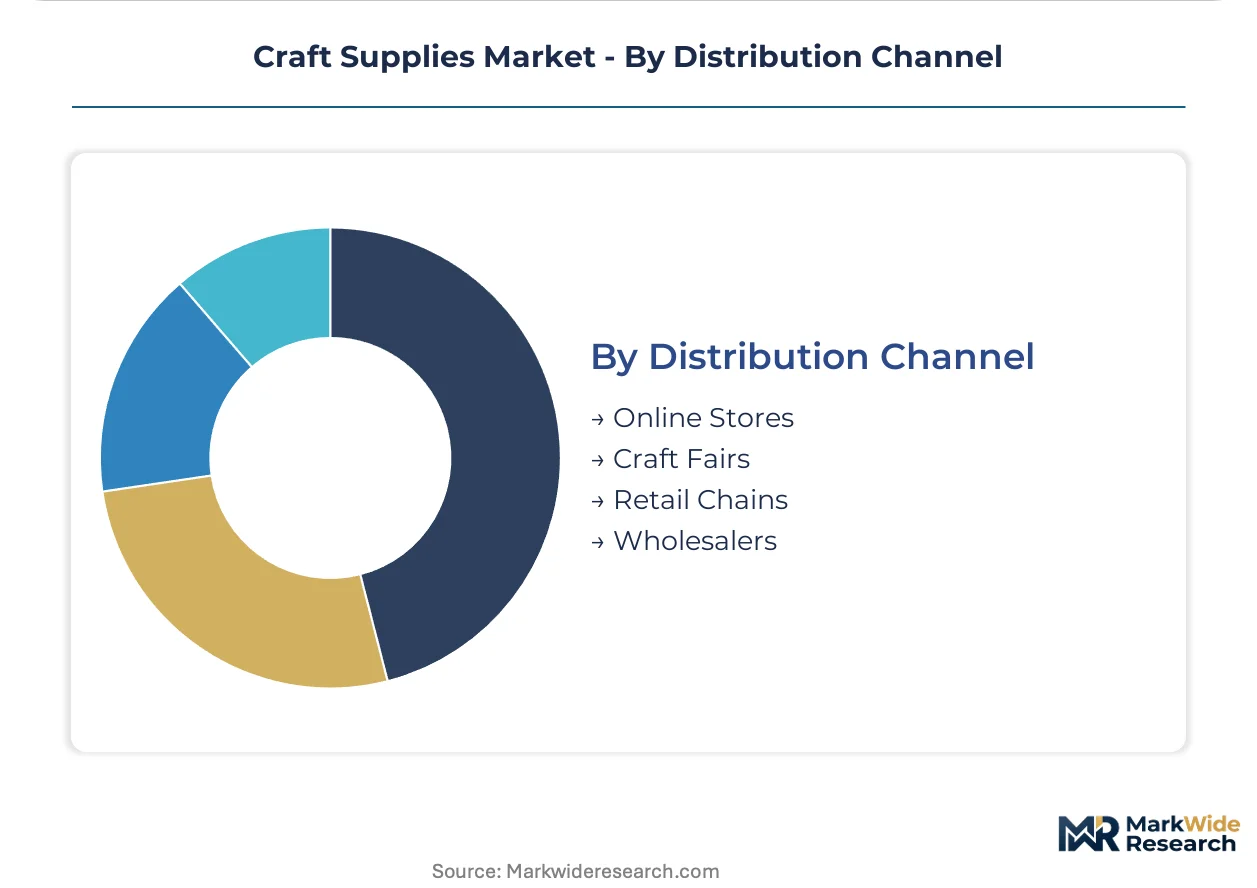
Distribution Channel:
Physical touchpoints versus digital fulfillment exposes different working capital requirements and customer acquisition economics.
- Online Stores:Specialized marketplaces and brand-direct platforms aggregate long-tail demand with infinite shelf capacity. Cricut's proprietary design software ecosystem locks in blade and mat auto-ship programs, capturing predictable revenue from high-frequency United States users through warehouse club partnerships.
- Retail Chains:Big-box craft specialists and general merchandise stores provide immediate material access with in-person color matching and tool demonstration. Store networks in the United Kingdom and United States face pressure from state-level extended producer responsibility laws that will redistribute packaging waste cost structures.
- Craft Fairs:Seasonal events and maker markets enable direct artisan-to-consumer sales with premium positioning.
- Wholesalers:Regional distributors serve independent retailers with consolidated logistics and credit terms.
Retail Chains hold installed capacity. Online Stores is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific pigment and paper imports, underwriting North American supply security for water-based acrylic systems and archival cellulose substrates.
United States
Millennial homeowners in Texas and Florida drive DIY home décor material purchases through sustained project cycles. The EPA's Toxic Substances Control Act governs volatile organic compound limits, compelling reformulation toward solvent-free coatings. The Dallas-Fort Worth metroplex concentrates big-box craft retail distribution, with localized inventory planning defending foot traffic against digital channels.
Germany
Independent artisans in Bavaria and Baden-Württemberg adopt desktop stereolithography systems for jewelry prototyping at annual equipment growth rates exceeding forty percent. ECHA registration requirements under REACH create fixed compliance costs for solvent-based coating formulators. The Rhine-Ruhr industrial corridor hosts specialized pigment houses accelerating lightfast organic alternatives through stability testing protocols.
United Kingdom
Educational procurement contracts in England and Scotland stabilize volume demand for K-12 art programs with standardized material specifications. The Consumer Product Safety Commission's ASTM D-4236 labeling protocols extend procurement lead times but lock in multi-year supplier relationships. Greater Manchester anchors specialist retail networks with educator-focused programming defending localized store traffic.
Netherlands
Direct-to-maker platforms in Amsterdam and Rotterdam aggregate independent artisans through subscription-based consumables replenishment. EU packaging waste directives create first-mover advantages for recyclable-brush and refillable-paint systems. The Randstad urban ring concentrates stereolithography hardware adoption among commercial makers bypassing traditional wholesale markups.
Japan
Tablet-based drawing applications displace physical sketching supplies among younger demographic cohorts in Tokyo and Osaka metro areas. METI standards govern product safety for children's art materials, aligning with international non-toxic certification requirements. The Kanto region maintains premium positioning for archival-quality papers through specialized surface sizing and acid-free processing.
Craft Supplies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in pigment chemistry and substrate manufacturing. The market structure concentrates around vertically integrated retail chains with private-label development capabilities, while fragmented artisan formulators compete on batch customization. Two strategic archetypes dominate: ecosystem players locking consumables revenue through proprietary software-hardware pairing, and scale-driven retailers capturing margin through exclusive distribution agreements. Competitive moves center on strategic partnerships for digital design integration and geographic expansion through localized store networks.
Among North American retail chains, Michaels Stores and Hobby Lobby exemplify the scale-driven archetype with extensive brick-and-mortar footprints and private-label portfolio control. Cricut occupies the platform integrator position, anchoring digital die-cutting demand through proprietary design software ecosystems that lock in blade and mat auto-ship revenue. These three companies represent the dominant competitive configurations: retail scale, private-label margin defense, and consumables-locking technology platforms.
| Leading Market Players |
|---|
| Michaels Stores |
| Hobby Lobby |
| Joann Stores |
| Blick Art Materials |
| Crayola |
| Cricut |
| Daiso |
| Hobbycraft |
| Walmart |
| Others |
Value Chain & Pricing Dynamics
The Port of Los Angeles anchors trans-Pacific pigment and paper imports, with container freight cost dynamics compressing margin pools for water-based acrylic formulators while amplifying price differentiation between bulk educational procurement and premium artisan tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates proprietary pigment systems with REACH-compliant formulations from private-label alternatives and commodity cellulose substrates. Price differentiation rests on certification grade under ASTM D-4236 toxicity labeling and volume scale through institutional K-12 contracts. Cost compression in economy-tier papers is intensifying because REACH-compliant European bleaching processes elevate base stock costs relative to Asian imports. Educational procurement officers demonstrate highest price sensitivity through competitive bidding, while millennial homeowners in DIY home décor show lowest sensitivity due to project-based rather than replenishment purchasing.
Supply Chain Analysis
Export-control scrutiny on advanced photopolymer resin chemistries limits hardware-component flows from Germany and the Netherlands into broader European distribution networks. Geographic supply concentrates in China for pigment-grade titanium dioxide, the United States for water-based acrylic emulsion capacity, and Germany for specialized organic pigment alternatives. Raw material dependencies include titanium dioxide loadings, cellulose pulp grades, and synthetic filament extrusions. Single-source vulnerability runs through Chinese sulfate-process TiO2 producers. Distribution runs through big-box retail chains with localized inventory planning defending against digital channel erosion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Craft supplies fragmentation creates entry points for specialists as millennial homeowner demand shifts from project-based purchasing toward sustained engagement with subscription-based consumables models.
For Market Incumbents: Pre-empt digital substitution threats by capturing proprietary design-to-cut software ecosystems that lock blade and mat replenishment through auto-ship programs. Consolidate position through backward integration into water-based acrylic emulsion capacity in Texas and Florida, insulating margin from titanium dioxide price volatility while securing REACH-compliant formulation control against regulatory escalation. For New Entrants and Emerging Players: Direct-to-maker platforms in Germany and the Netherlands represent the most penetrable entry point, where stereolithography hardware adoption exceeds forty percent annually and subscription-based consumables replenishment bypasses traditional wholesale markups. Target artisan formulators seeking batch consistency documentation for resale markets. Deploy educator-focused programming as the go-to-market angle, leveraging institutional volume contracts that stabilize seasonal demand fluctuations. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap retail chains with underutilized private-label development capabilities and localized store networks in secondary United States metroplexes. Long-term viability hinges on capturing consumables-locking technology platforms rather than scale-driven retail footprint expansion. Watch ECHA sunset date announcements for restricted pigments as the signal indicating reformulation investment windows and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Design Software Integration | Cricut's file-format exclusivity locks blade and mat auto-ship revenue from high-frequency United States users. |
| REACH-Compliant Formulation Investment | Water-based acrylic systems capture margin as ECHA sunset dates force legacy solvent-based coatings from European supply chains. |
| Educator-Focused Channel Programming | Hobbycraft's localized store networks defend foot traffic through K-12 art program procurement relationships in Greater Manchester. |
| Subscription-Based Consumables Replenishment | Silhouette America mirrors Cricut's auto-ship programs, capturing predictable revenue from dedicated hobbyist segments. |
| Sustainable Material Sourcing Partnerships | Bio-based binder chemistry combined with agricultural waste-derived cellulose opens premium positioning for carbon-accounted craft papers. |
Study Parameters
Desk research of trade association publications, customs import records, and regulatory filing databases preceded structured interviews with pigment house technical directors, craft retail category buyers, educational procurement officers, and independent artisan formulators. Primary fieldwork combined with secondary validation from EPA Toxic Substances Control Act guidance documents, ECHA REACH registration databases, and ASTM D-4236 certification records. Bottom-up demand modeling across DIY home décor, educational use, and scrapbooking applications triangulated against top-down value-chain analysis of titanium dioxide, cellulose substrate, and synthetic filament input markets.
Assumptions held fixed include current REACH Annex XVII restriction timelines, EPA VOC limit enforcement intensity, and existing Cricut-Silhouette competitive dynamics in digital die-cutting, while variables included millennial homeowner project initiation rates and stereolithography hardware adoption curves across Germany and the Netherlands. Segmentation dimensions modeled encompass product type chemistry tiers, application project duration, customer procurement authority, and distribution channel physical-digital mix. CAGRs were derived through regression analysis of historical pigment and paper volume flows against demographic cohort purchasing pattern shifts. Industry-specific inputs included titanium dioxide spot price volatility indices and educational funding allocation trends.
Macroeconomic conditions sit as an overlay; deviation in container freight rates, currency exchange dynamics affecting Asian import competitiveness, or K-12 education budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology adoption S-curve positioning. Material shifts in ECHA accelerated sunset scheduling or breakthrough tablet-based drawing application penetration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Needlecraft Patterns Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
United States Handicrafts Market