
 North America Handicrafts Market | 2026-2036
North America Handicrafts Market Size, Share, and Industry Trends Forecast 2026-2036
North America Handicrafts Market Intelligence
The price gap between gallery-grade artisan work and mass-produced craft imports is hardening across North American distribution channels. Ten Thousand Villages leverages its fair-trade sourcing network to anchor premium positioning in ethically sourced textiles. Pendleton Woolen Mills sustains vertical control over wool procurement and weaving operations in the Pacific Northwest. Peking Handicraft competes on volume in decorative home accessories while occupying a lower-margin tier distinct from heritage craft producers.
North American handicrafts encompass manually fabricated goods employing traditional techniques, raw natural materials such as cotton, clay, and bamboo, and small-batch production methods yielding non-standardized outputs for decorative, functional, or cultural purposes. Wood crafts and textiles retain the largest revenue footprint, while pottery commands higher per-unit margins due to material fragility and kiln-fired specialization requirements. Online stores represent the fastest-expanding sales channel, though artisan markets and craft fairs still concentrate margin pools through direct producer-consumer relationships that eliminate platform fees.
The US Consumer Product Safety Commission and Health Canada enforce material safety standards for dyed textiles and glazed ceramics sold across domestic retail channels. The US Indian Arts and Crafts Act imposes authenticity requirements on Native American craft labeling, shaping market access for tribal and non-tribal producers alike. Stakeholders must monitor evolving e-commerce tax obligations at the state and provincial level, as these will determine whether small-scale artisans retain cost advantages against centralized specialty retailers.
Market Dynamics
Digital marketplace infrastructure is compressing traditional wholesale layers between artisan producers and retail buyers across North American distribution channels. The US Indian Arts and Crafts Act enforcement and state-level craft fair permitting reforms are simultaneously expanding legitimate market access while intensifying compliance requirements for cross-border sellers.
Growth Catalysts
- E-commerce platform proliferation:Digital sales channels eliminate geographic constraints for rural artisans in New Mexico and Arizona, connecting Native American weavers directly to buyers in urban coastal markets without intermediary markups.
- Fair-trade certification frameworks:Third-party ethical sourcing standards are opening premium shelf space at major US retailers for cooperatively produced textiles and ceramics, commanding price premiums over uncertified imports.
- Heritage tourism infrastructure:Federal and state investment in cultural corridor development across the southwestern United States is concentrating visitor traffic at artisan markets and studio tours, driving direct-to-consumer revenue concentration.
Market Restraints
- Wool and cotton input cost volatility:Climate-driven supply fluctuations in Texas and California sheep ranching regions create margin compression for textile producers dependent on domestic fiber sourcing.
- Kiln energy intensity:Natural gas price spikes in the Pacific Northwest and Ontario are forcing pottery studios to absorb production cost increases or reduce firing schedules, constraining output capacity.
- Substitute product encroachment:Machine-woven textiles from Central American free-trade zones are undercutting hand-loom pricing in mid-market home décor segments, forcing North American artisans toward premium positioning exclusively.
Strategic Opportunities
- Underpenetrated Canadian prairie markets:Saskatchewan and Manitoba lack established craft fair infrastructure relative to US counterparts, creating first-mover advantage for mobile artisan market operators and seasonal festival organizers.
- Corporate gifting program expansion:Custom-branded artisan goods for employee recognition and client retention are displacing mass-produced promotional items at technology and professional services firms.
- Blockchain provenance verification:Distributed ledger technology convergence with mobile photography is enabling tamper-resistant authenticity documentation for Native American craft claims, reducing legal exposure under the US Indian Arts and Crafts Act.
Industry Challenges
- Master craftsperson succession gaps:Traditional weaving, pottery, and metalsmithing knowledge transfer is stalling as aging practitioners in tribal communities lack formally structured apprenticeship pipelines, threatening design continuity.
- Multi-jurisdiction tax compliance burden:Post-Wayfair economic nexus rules require small-scale artisans selling across state lines to track and remit sales tax in dozens of jurisdictions, consuming administrative bandwidth that scales disproportionately with revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Handicrafts Market |
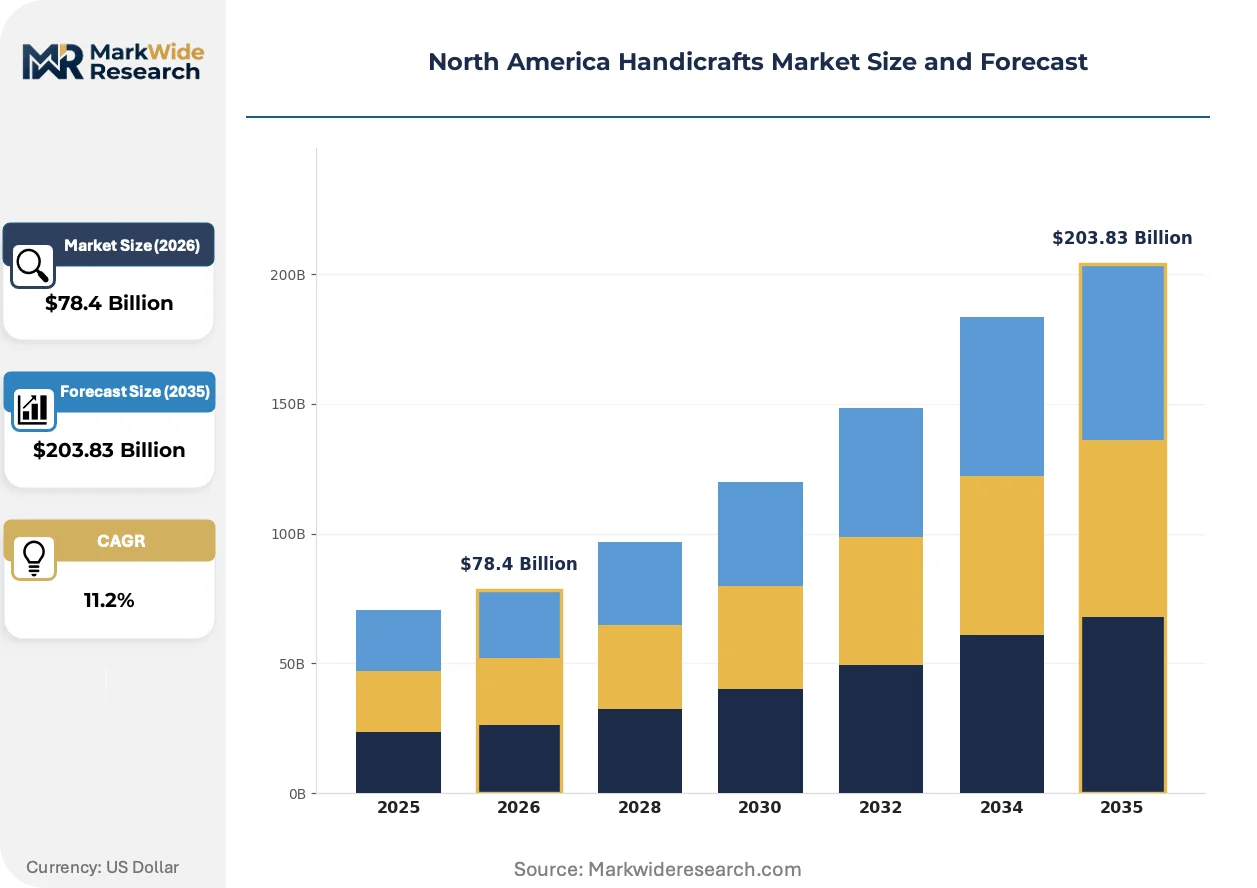
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $203.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textiles, Pottery, Wood Crafts, Metal Crafts End User: Retail Consumers, Art Collectors, Businesses, Nonprofits Sales Channel: Online Stores, Craft Fairs, Artisan Markets, Specialty Shops Material: Cotton, Clay, Bamboo, Recycled Materials |
| Companies Covered | Ten Thousand Villages, Pendleton Woolen Mills, Native Crafts and Arts, Simon Pearce, Sheldon Ceramics, Peking Handicraft, Monague Native Crafts, Colonial Tin Works, Handicrafts Home, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Handicrafts Market Strategic Shifts & Innovations
Production technology and distribution infrastructure are converging to reshape how handmade goods reach buyers. Three distinct movements are altering competitive positioning across material categories and sales channels.
Laser cutting and CNC routing systems adapted for small-batch woodcraft operations are consolidating previously fragmented furniture and home accessory production. Southwestern US studio furniture makers are adopting these tools to reduce hand-carving labor while preserving design customization. The technology is compressing delivery timelines from commission to completion, enabling these producers to compete with mass-market lead times without sacrificing material authenticity.
Health Canada and the US Consumer Product Safety Commission are tightening coordinated enforcement of lead content limits in glazed ceramics and dyed textiles sold through cross-border e-commerce. The regulatory convergence is forcing importers and domestic producers alike to consolidate testing documentation and supplier qualification protocols. Small-scale potters in Ontario and Quebec are responding by shifting toward locally sourced clay bodies with known mineral compositions to reduce third-party testing costs.
Buyer preference is rotating toward transparent supply chain documentation and direct producer relationships, displacing traditional gallery consignment models. Younger collectors in Texas and California urban centers are purchasing through Instagram and TikTok shop functions rather than established craft fair circuits. This channel migration is most visible in textile and jewelry categories, where visual storytelling around technique and maker identity drives purchase decisions more than physical product handling.
North America Handicrafts Market Segmentation
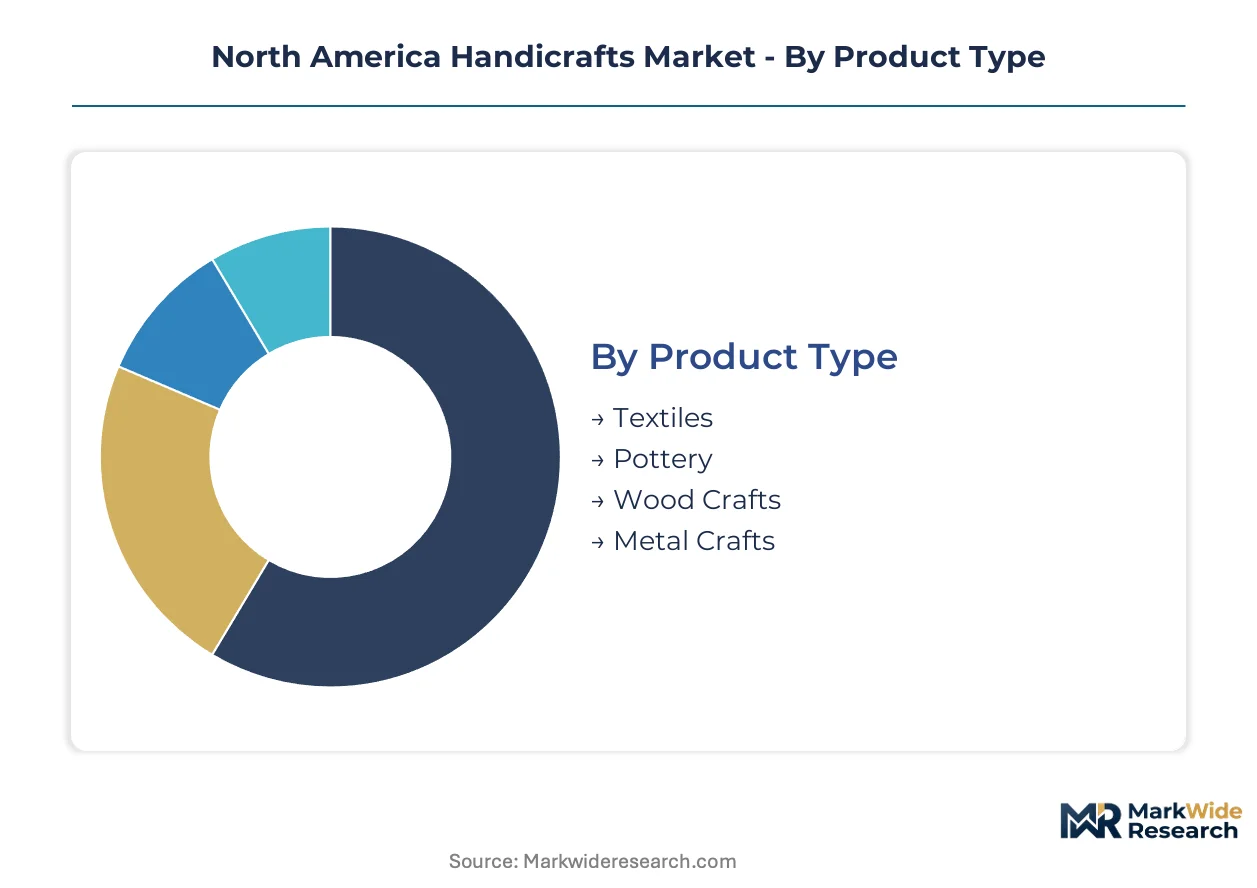
Segmentation in North American handicrafts reveals how artisan production clusters around material availability, buyer sophistication, and channel economics. Distinct margin structures and compliance burdens separate gallery-grade collectibles from volume home décor. Understanding these fault lines guides producer positioning and retailer assortment strategy.
Product Type:
Supply concentration in textile weaving and woodcraft operations across the southwestern United States and Pacific Northwest creates tiered production capacity that shapes competitive dynamics.
- Textiles:Hand-loomed wool, cotton, and natural fiber fabrics employing Navajo, Hopi, and contemporary studio techniques. Demand concentrates in Arizona and New Mexico urban corridor buyers seeking authenticated Native American weavings, constrained by master weaver succession gaps in tribal communities.
- Wood Crafts:Carved, turned, and joined furniture and decorative objects utilizing regional hardwoods and softwoods. Southwestern studio furniture makers in Santa Fe and Taos are adopting CNC routing to compress lead times while preserving material authenticity and design customization.
- Pottery:Kiln-fired functional and decorative ceramics from locally sourced clay bodies.
- Metal Crafts:Forged, cast, and fabricated jewelry and home accessories.
Today's leader: Textiles. Tomorrow's challenger: Wood Crafts.
End User:
Buyer sophistication and purchase frequency create divergent margin profiles across customer categories, with corporate and collector segments commanding premium positioning.
- Retail Consumers:Individual purchasers of home décor, gifts, and personal accessories through direct and intermediated channels. Texas and California urban centers drive volume through Instagram and TikTok shop functions, displacing traditional craft fair circuits.
- Art Collectors:Serious buyers acquiring investment-grade pieces with documented provenance and maker reputation. Gallery consignment models face displacement as younger collectors demand transparent supply chain documentation and direct producer relationships.
- Businesses:Corporate procurement of custom-branded artisan goods for employee recognition and client retention programs.
- Nonprofits:Mission-driven organizations sourcing fair-trade and culturally significant items for fundraising and program support.
Retail Consumers anchor present volume. Art Collectors are climbing the fastest as authentication technology reduces legal exposure.
Sales Channel:
Channel economics separate fee-bearing digital infrastructure from margin-preserving direct relationships, with regulatory compliance costs altering small-scale producer calculus.
- Online Stores:Digital marketplace platforms and proprietary e-commerce sites connecting artisans to geographically dispersed buyers. Native American weavers in rural New Mexico and Arizona leverage these channels to reach urban coastal markets without intermediary markups.
- Craft Fairs:Seasonal and recurring exhibition events with state-level permitting reforms broadening producer access. Federal and state investment in southwestern cultural corridor development is concentrating visitor traffic and driving direct-to-consumer revenue concentration.
- Artisan Markets:Permanent or semi-permanent vendor spaces with established foot traffic.
- Specialty Shops:Curated brick-and-mortar retailers with trained staff and physical product handling.
Online Stores gain share fastest. Craft Fairs defend margin pools through producer-consumer proximity.
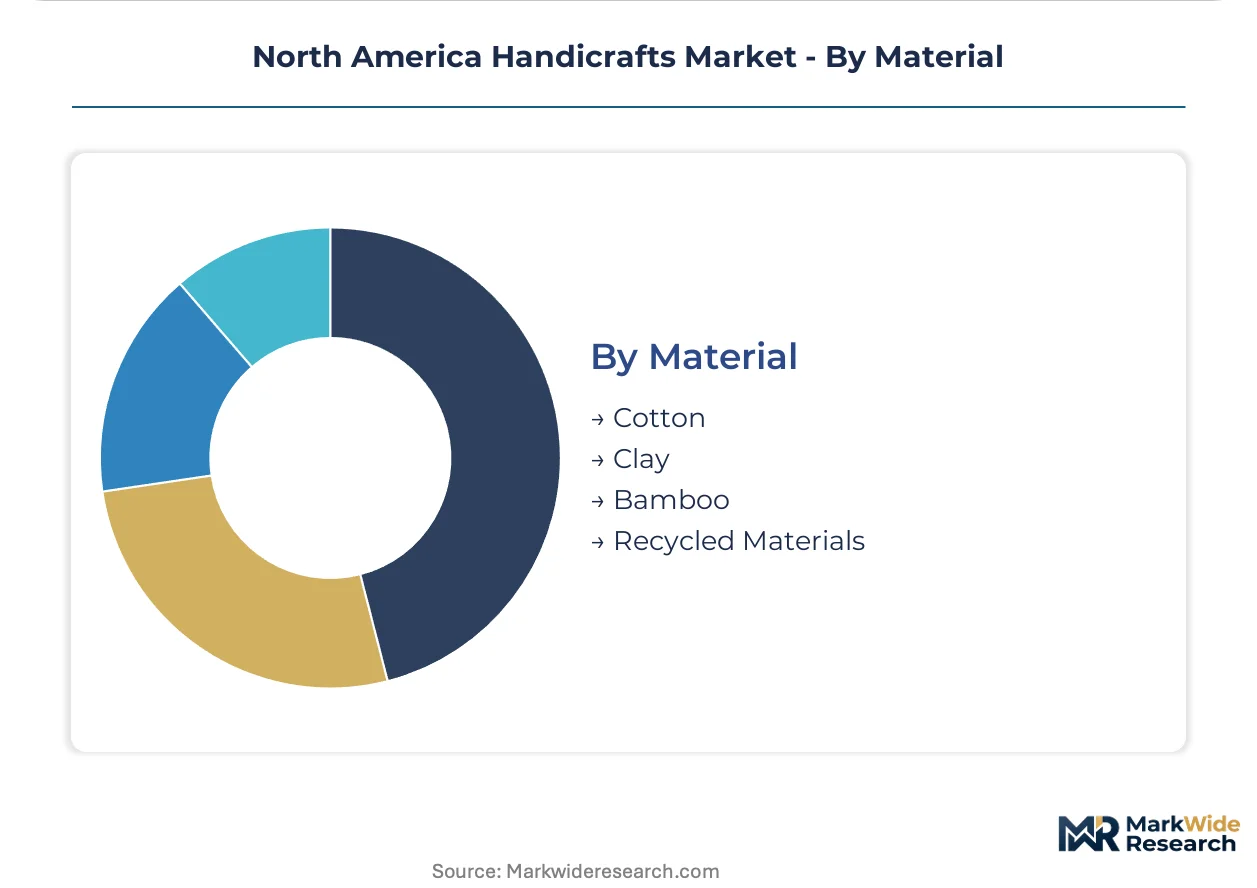
Material:
Input cost volatility and regulatory testing requirements are forcing material substitution and supplier consolidation across production categories.
- Cotton:Natural cellulosic fiber for weaving and textile crafts, subject to climate-driven supply fluctuations in California growing regions that create margin compression for domestic fiber-dependent producers.
- Clay:Kiln-formable earthenware, stoneware, and porcelain bodies. Ontario and Quebec potters are shifting toward locally sourced clay with known mineral compositions to reduce third-party testing costs under tightening Health Canada and US Consumer Product Safety Commission enforcement.
- Bamboo:Rapidly renewable grass species for lightweight structural and decorative applications.
- Recycled Materials:Reclaimed and repurposed inputs for sustainability-positioned product lines.
Cotton dominates current throughput. Clay faces steepest cost pressure from energy and compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master weavers in tribal communities anchor southwestern production clusters, while Pacific Northwest woolen mills and Ontario pottery studios concentrate specialized fabrication capacity across the continent.
United States
Navajo and Hopi weaving traditions drive authenticated textile demand across Arizona and New Mexico urban corridors. The US Indian Arts and Crafts Act imposes strict authenticity labeling requirements that shape market access for both tribal and non-tribal producers. Santa Fe and Taos studio furniture makers are adopting CNC routing to compress lead times while preserving material authenticity.
Canada
First Nations craft cooperatives sustain concentrated buyer activity in British Columbia and Ontario cultural tourism corridors. Health Canada enforces coordinated lead content limits in glazed ceramics and dyed textiles through cross-border e-commerce channels. Quebec potters are shifting toward locally sourced clay bodies with known mineral compositions to reduce third-party testing costs.
Mexico
Oaxacan and Michoacán artisan collectives supply carved wood and tinwork through established border trade networks. Mexico's Secretariat of Economy supports craft sector formalization through microenterprise financing programs and export certification assistance. Guadalajara and San Miguel de Allende function as consolidation hubs connecting regional producers to US retail buyers.
North America Handicrafts Market Key Industry Players
Top-tier vendors anchor heritage craft positioning, while volume-driven importers and cooperative networks occupy distinct margin tiers. The market structure fragments across three strategic archetypes: vertically integrated woolen mills controlling upstream fiber sourcing, fair-trade certified cooperatives leveraging ethical sourcing premiums, and import distributors competing on decorative accessory volume. Consolidation pressure is accelerating through direct-to-consumer channel expansion and authenticity verification technology deployment.
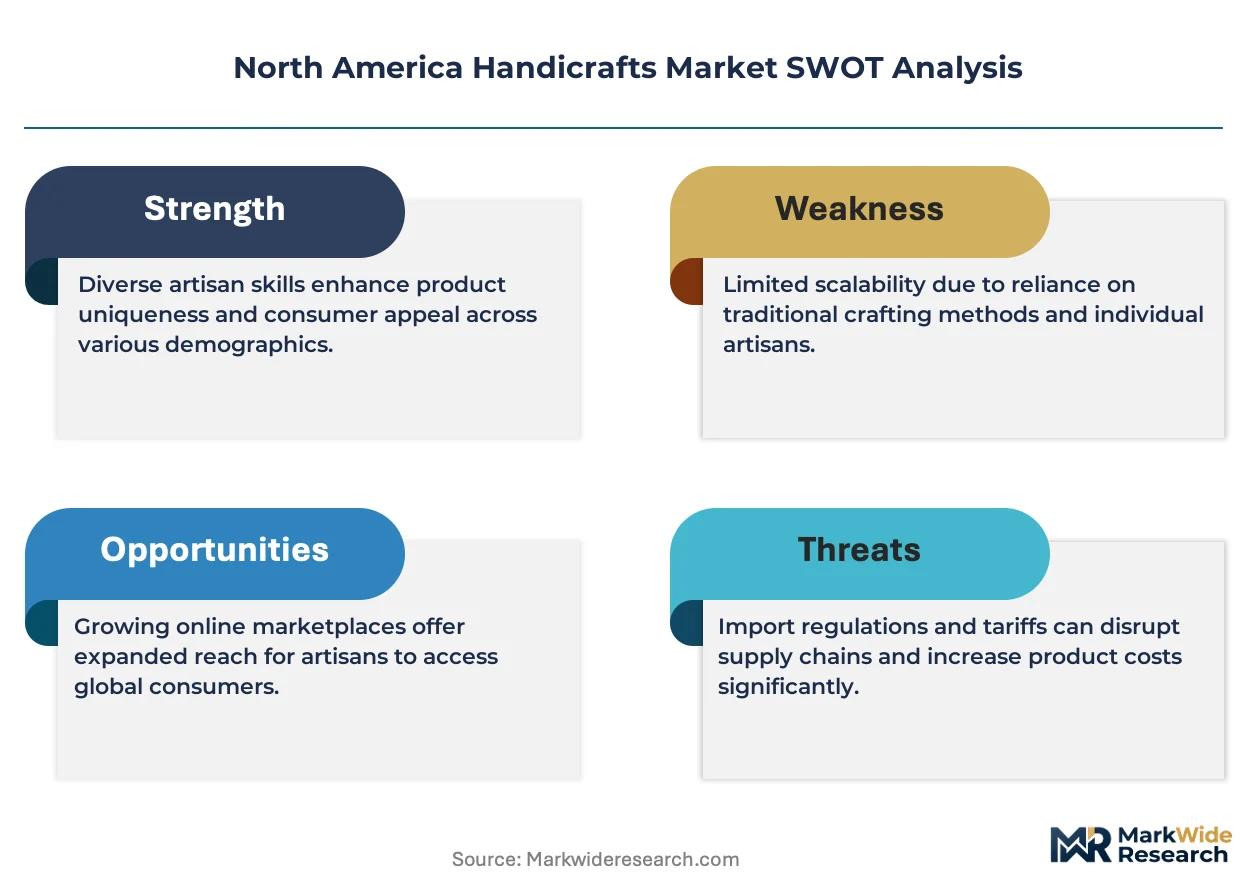
Within the heritage-tier vector, Ten Thousand Villages and Pendleton Woolen Mills exemplify divergent sourcing models—one leveraging cooperative networks for ethically positioned textiles, the other maintaining captive wool procurement and weaving operations. Peking Handicraft occupies a position at the volume-driven end, representing import-dependent distribution focused on decorative home accessories without premium craft provenance claims. These three anchors illustrate how pricing stratifies across authentication grade, supply chain transparency, and production scale rather than material category alone.
| Leading Market Players |
|---|
| Ten Thousand Villages |
| Pendleton Woolen Mills |
| Native Crafts and Arts |
| Simon Pearce |
| Sheldon Ceramics |
| Peking Handicraft |
| Monague Native Crafts |
| Colonial Tin Works |
| Handicrafts Home |
| Others |
Cost & Logistics Intelligence
Natural gas kiln firing costs in Ontario and the Pacific Northwest cascade through pottery pricing tiers, separating studio-scale producers absorbing margin compression from gallery-grade operations passing energy premiums to authenticated collectors.
Pricing Analysis
The bundled-vs-unbundled service split separates gallery consignment models with authentication documentation from direct-to-consumer digital sales without intermediary fees. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under the US Indian Arts and Crafts Act and supply chain transparency depth. Cost compression in mid-market textiles intensifies because machine-woven Central American imports undercut hand-loom equivalents. Corporate gifting buyers show least price sensitivity, while retail consumers through mass-market channels exhibit highest elasticity.
Supply Chain Analysis
Warehouse-distribution layer concentration in Guadalajara and San Miguel de Allende funnels Oaxacan woodcraft and Michoacán tinwork through border trade networks into US retail channels. Raw material sourcing draws from Texas and California cotton growing regions, Pacific Northwest wool ranches, and locally sourced clay bodies in Quebec. Single-source vulnerability runs through master weaver succession gaps in Navajo and Hopi communities. Distribution runs through direct-to-consumer digital platforms and seasonal craft fair circuits with state-level permitting variance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Handicrafts Market functions as a geographic-arbitrage play where Saskatchewan and Manitoba's underdeveloped craft fair infrastructure offers first-mover returns unavailable in saturated southwestern US corridors.
For Market Incumbents: To counter substitute product encroachment from Central American free-trade zone textiles, Pendleton Woolen Mills and heritage-tier producers should deepen upstream control over wool procurement while investing in blockchain provenance verification to harden authentication premiums against machine-woven competitors.
For New Entrants and Emerging Players: A mid-market price-point gap between Ten Thousand Villages fair-trade premiums and Peking Handicraft import volumes creates entry space for mobile artisan market operators targeting Saskatchewan prairie cities and corporate gifting programs at technology firms seeking custom-branded recognition goods.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction tax compliance burdens from post-Wayfair economic nexus rules consume disproportionate administrative bandwidth at small-scale artisans. Viability over the coming decade hinges on acquiring cooperative networks with established fair-trade certification and direct-to-consumer channel infrastructure. Watch blockchain authenticity verification adoption rates as the inflection signal for premium tier margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Verification | Tamper-resistant documentation reduces legal exposure under the US Indian Arts and Crafts Act enforcement. |
| Corporate Gifting Program Expansion | Custom-branded artisan goods displace mass-produced promotional items at technology and professional services firms. |
| Mobile Artisan Market Development | First-mover operators capture underpenetrated Canadian prairie markets lacking established craft fair infrastructure. |
| Direct-to-Consumer Channel Migration | Instagram and TikTok shop functions displace traditional gallery consignment models among younger collectors. |
| Locally Sourced Material Substitution | Ontario and Quebec potters shift toward known-composition clay bodies to reduce Health Canada testing costs. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining interviews with master weavers in Navajo and Hopi communities, craft fair organizers, gallery consignment directors, corporate procurement officers, and cooperative network managers. Secondary validation draws from US Consumer Product Safety Commission enforcement records, Health Canada regulatory filings, US Indian Arts and Crafts Act documentation, state-level craft fair permitting databases, and e-commerce platform transaction disclosures. Bottom-up artisan production estimates and top-down retail channel value flows undergo triangulation.
Granularity-level modeling operates at product type, end user category, sales channel, and material input dimensions across the analysis window. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers including heritage tourism investment flows and digital marketplace penetration curves. Forecast inputs incorporate kiln energy cost trajectories in the Pacific Northwest and Ontario, climate-driven fiber supply volatility in Texas and California, and cross-border e-commerce tax obligation evolution at state and provincial levels.
The model assumes a particular technology adoption path; alternative pathways for blockchain provenance verification and CNC routing adoption in studio furniture would alter the outlook for authentication premium sustainability and production lead time compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
Needlecraft Patterns Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Daughter Craft Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
Dibber Market
Crafts & Hobbies
Handicrafts Market