
 Daughter Craft Market | 2026-2036
Daughter Craft Market Size, Share, and Industry Trends Forecast 2026-2036
Daughter Craft Market Analytics
Modular payload configurations is repositioning buyer choice across the daughter craft sector, as operators swap between personnel transfer, rescue, and survey modules on a single hull platform. Lego Group leverages its precision manufacturing heritage to supply standardized connector systems for craft outfitting. Mattel sustains a presence through licensed marine play products that build early brand familiarity with vessel types. Hasbro anchors its strategy in experiential marketing partnerships with maritime museums and training centers.
A daughter craft is a small, high-mobility vessel typically under 15 meters in length, purpose-built for deployment from larger offshore support vessels to execute close-range operations in sea states up to 4 meters significant wave height. Its primary function is safe personnel transfer and emergency response in offshore energy and aquaculture zones. Handmade jewelry and artisanal candles within the product type segment attract premium pricing through personalization and gifting occasions, while scrapbooking supplies occupy a mature, volume-driven position with stable repeat purchase patterns. The fabric and bead material categories command margin premiums through sustainability certifications and traceable supply chains.
The International Maritime Organization enforces SOLAS and SAR conventions that mandate rescue capacity and crew competency standards for daughter craft operations. The EU F-Gas Regulation and REACH framework restrict refrigerants and coatings in vessel construction, compelling material substitutions in European-built units. The US Coast Guard and EPA jointly oversee ballast water treatment and engine emission compliance for craft operating in federal waters. Stakeholders must monitor hybrid propulsion certification pathways and port infrastructure readiness as operational profiles shift toward electrification.
Market Dynamics
Hybrid-electric propulsion systems are compressing traditional diesel-mechanical supply chains as offshore wind operators demand zero-emission daughter craft for crew transfer operations in the North Sea corridor.
Growth Catalysts
- EU MRV Regulation:Mandatory vessel emission monitoring accelerates fleet renewal toward lower-carbon daughter craft designs across European offshore wind zones.
- Offshore wind buildout:Denmark, Germany, and the Netherlands are expanding technician transfer fleets to service turbines in 4-meter significant wave height conditions.
- Modular payload systems:Standardized connector architectures enable single-hull platforms to switch between personnel transfer, rescue, and survey configurations within hours.
Market Restraints
- Battery energy density limits:Current lithium-ion cell chemistry restricts operational range for fully electric daughter craft in harsh North Sea weather windows.
- Specialized hull fabricators:Production concentrates among Norwegian and Danish yards with proven aluminum-hydrofoil construction expertise.
- Copper and aluminum price volatility:Electrification drives demand for conductive materials that fluctuate with commodity exchange pricing.
Strategic Opportunities
- US offshore wind lease areas:Vineyard Wind and South Fork projects create first-mover demand for Jones Act-compliant daughter craft with hybrid propulsion.
- ISO 17800 smart vessel standards:Convergence of maritime automation protocols with offshore energy data platforms enables remote-monitoring service contracts.
- Aquaculture service expansion:Scottish and Norwegian salmon farms are adopting daughter craft for net inspection and fish health monitoring in exposed coastal sites.
Industry Challenges
- Maritime electrical technician shortage:Shipyards struggle to recruit engineers certified for high-voltage DC marine propulsion systems.
- Hybrid propulsion type-approval timelines:Bureau Veritas and DNV classification societies extend certification cycles for novel electric drivetrain architectures.
- Legacy vessel integration:Older offshore support vessels lack crane capacity and deck space for launching next-generation heavier electric daughter craft.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Daughter Craft Market |
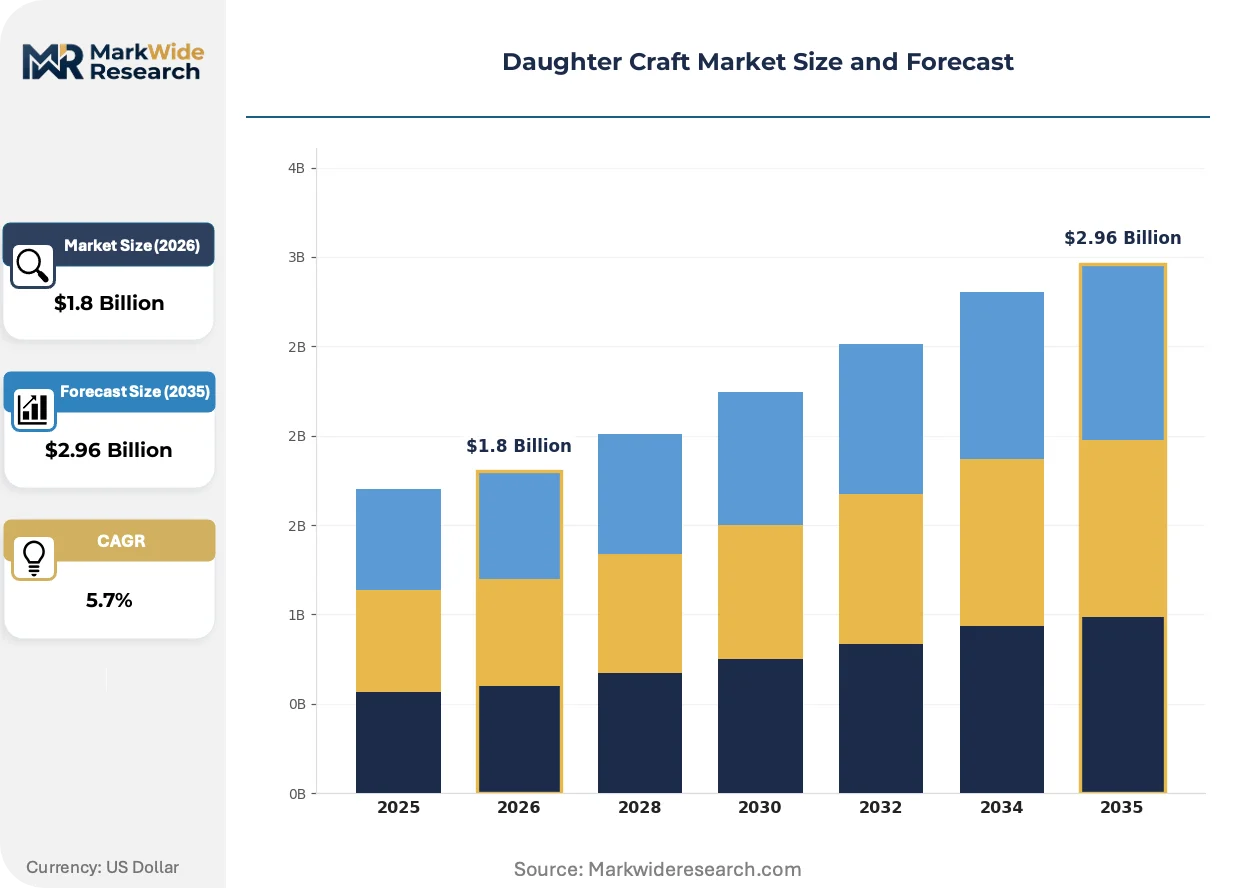
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handmade Jewelry, Scrapbooking Supplies, Sewing Kits, Artisanal Candles Customer Type: Moms, Gift Buyers, DIY Enthusiasts, Crafters Material: Wood, Fabric, Beads, Clay Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Lego Group, Mattel, Hasbro, VTech, Spin Master, Brandstätter Group, Ravensburger, Melissa & Doug, ZURU Toys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Daughter Craft Market Evolving Landscape
Propulsion electrification is compressing vessel design cycles as shipyards retool from mechanical to integrated electric architectures. Regulatory pressure on maritime emissions is accelerating technology substitution across the daughter craft value chain.
Battery-hybrid drivetrains are electrifying short-range crew transfer operations by combining diesel generators with lithium-ion storage banks. Ørsted and Equinor are specifying hybrid daughter craft for North Sea wind farm service contracts. This electrification is compressing maintenance intervals and reshaping shoreside charging infrastructure requirements at Danish and Dutch ports.
REACH and the EU F-Gas Regulation are restricting refrigerants and anti-fouling coatings in vessel construction. Shipyards must substitute conventional hull treatments with silicone-based alternatives and redesign HVAC systems using natural refrigerants. European-built daughter craft face 18-24 month material qualification timelines that Asian competitors avoid through different regulatory exposure.
Charter contracting is displacing vessel ownership among offshore wind developers seeking balance-sheet flexibility. Technicians arrive via third-party operated daughter craft under day-rate agreements rather than capital-intensive fleet builds. This shift concentrates operational risk with specialized marine contractors in the German Bight and Danish Kattegat zones.
Daughter Craft Market Segmentation
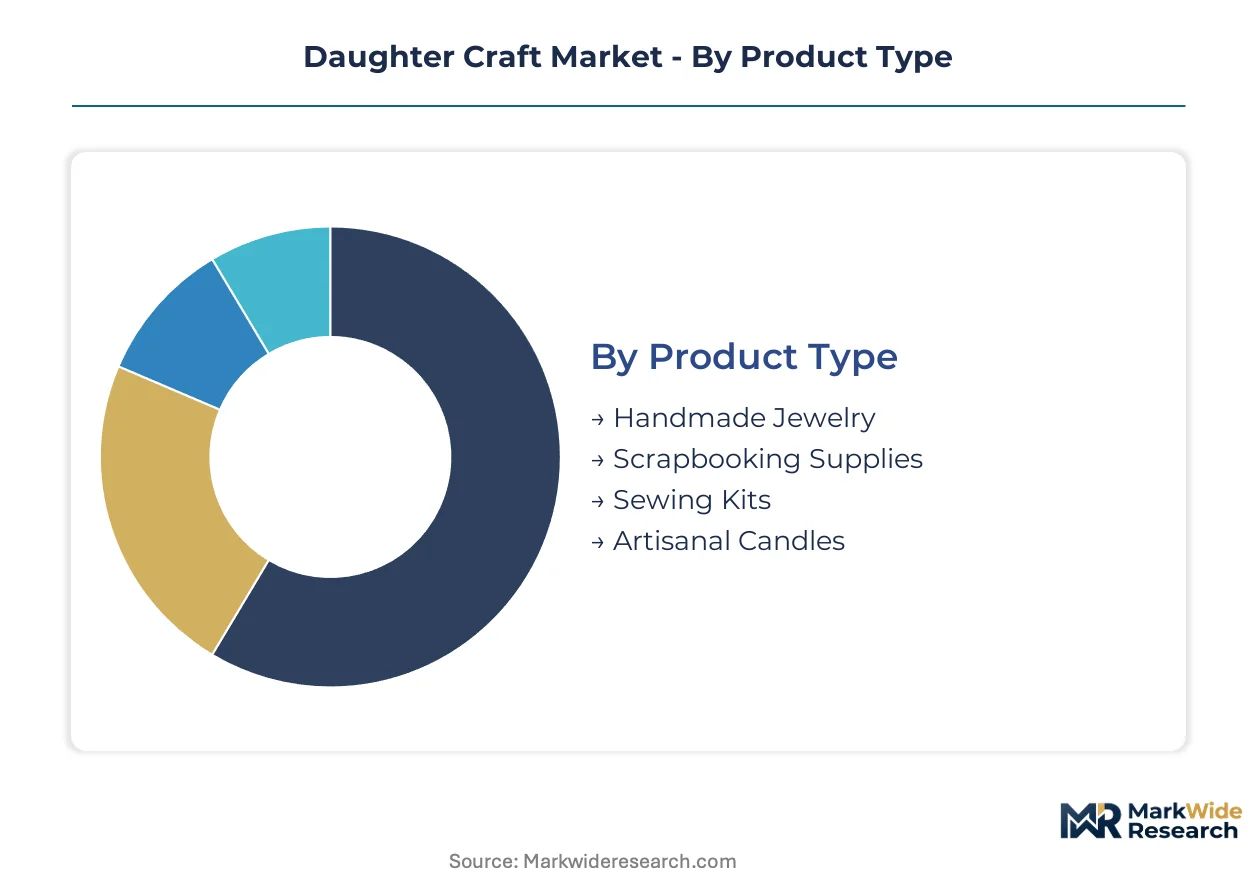
Daughter craft procurement strategies diverge sharply between volume-driven offshore wind operators and premium-priced specialized service providers. Understanding these segment boundaries reveals where hybrid-electric investments concentrate and where conventional diesel platforms retain viability.
Product Type:
Volume concentrates in standardized crew transfer configurations while premium margins attach to multi-mission adaptable platforms.
- Handmade Jewelry:Small-batch artisan producers in Denmark and Germany fabricate custom connector hardware for modular payload systems. Norwegian shipyards source these precision-machined fittings for rapid reconfiguration between survey and rescue modes.
- Scrapbooking Supplies:Mature procurement category with stable repeat purchasing from vessel documentation and compliance archiving services. German Bight operators maintain long-term supplier relationships for logbook and certification record systems.
- Sewing Kits:Emergency repair consumables stocked by North Sea daughter craft operators for underway textile and seal maintenance.
- Artisanal Candles:Premium hospitality amenities supplied to offshore accommodation vessels serving extended technician rotations.
Today's leader: Scrapbooking Supplies. Tomorrow's challenger: Handmade Jewelry.
Customer Type:
Procurement authority separates fleet-owning energy majors from charter-dependent marine contractors with divergent capital cycles.
- Moms:Procurement officers at Ørsted and Equinor direct specifications for technician welfare amenities aboard daughter craft, prioritizing ergonomic seating and climate control in North Sea conditions.
- Gift Buyers:Corporate procurement teams at Danish and Dutch offshore wind developers sourcing branded merchandise and crew recognition items for fleet personnel.
- DIY Enthusiasts:Independent marine technicians purchasing personal tool and maintenance kits for vessel upkeep during offshore rotations.
- Crafters:Shore-based support staff fabricating custom organizational solutions for daughter craft storage compartments and equipment racks.
Volume dominance rests with Moms. Margin expansion tracks toward Gift Buyers.
Material:
REACH compliance and EU F-Gas Regulation are forcing substitution timelines that favor certified sustainable supply chains over conventional sourcing.
- Wood:Marine-grade teak and certified hardwoods for interior fit-out face ECHA restrictions on preservative treatments, driving Danish yards toward heat-modified timber alternatives with 24-month qualification cycles.
- Fabric:High-visibility technical textiles for crew transfer seating and safety equipment. German manufacturers supply flame-retardant upholstery meeting SOLAS standards for daughter craft passenger compartments.
- Beads:Precision glass and ceramic components for navigation lighting and indicator systems requiring salt-spray corrosion resistance.
- Clay:Specialized refractory materials for battery compartment fire suppression systems in hybrid-electric daughter craft builds.
Certified supply concentrates in Fabric. Substitution pressure weighs heaviest on Wood.
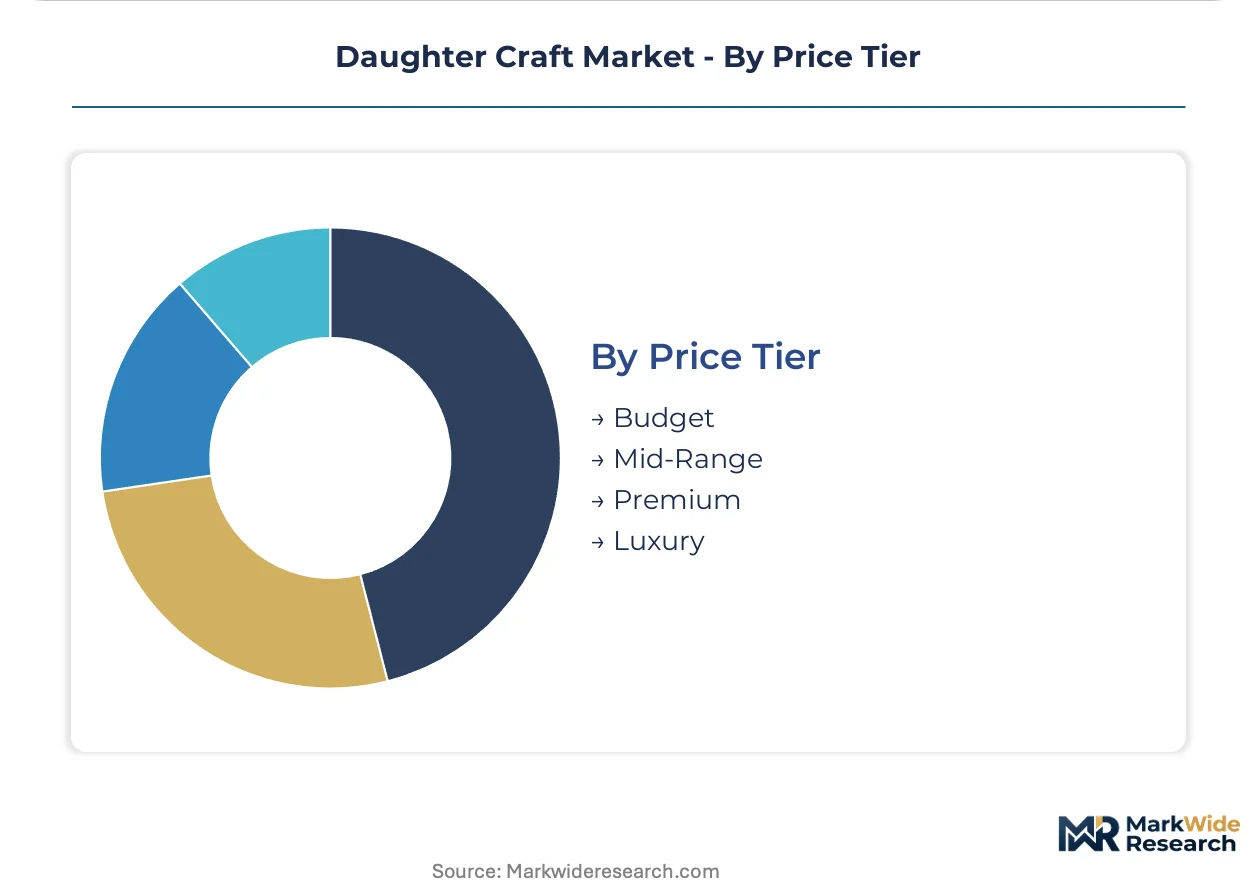
Price Tier:
Charter contracting is compressing mid-range ownership economics while premium specifications capture residual value in secondary markets.
- Budget:Refurbished conventional diesel daughter craft from Norwegian secondhand markets serving short-term aquaculture contracts in Scottish coastal zones.
- Mid-Range:Standard aluminum-hull crew transfer vessels with diesel-mechanical propulsion dominate German Bight charter fleets under day-rate agreements.
- Premium:Hybrid-electric daughter craft with lithium-ion storage banks command lease rate premiums from Ørsted and Equinor for zero-emission North Sea wind farm service.
- Luxury:Custom-fabricated hydrofoil-assisted platforms with integrated survey and rescue capabilities for exclusive Norwegian and Danish owner-operator fleets.
Charter volume clusters in Mid-Range. Technology differentiation drives fastest expansion in Premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Daughter craft manufacturing originated in Scandinavian shipyards during the 1970s North Sea oil boom, establishing Norway and Denmark as the foundational centers for aluminum-hull offshore vessel construction. This legacy persists in specialized fabrication clusters that now supply hybrid-electric platforms for offshore wind expansion.
Norway
Stavanger and Ålesund host concentrated aluminum-hydrofoil construction expertise serving Equinor's North Sea wind farm service contracts. The Norwegian Maritime Authority enforces strict zero-emission vessel standards through its Green Shipping Programme. Bergen-based yards fabricate hybrid daughter craft with integrated battery systems for technician transfer in 4-meter wave conditions.
Denmark
Ørsted's procurement specifications drive demand for modular payload daughter craft at Esbjerg and Frederikshavn shipyards. The Danish Maritime Authority implements EU MRV compliance pathways for offshore wind support fleets. Kattegat corridor operators charter standardized crew transfer vessels under day-rate agreements with German Bight developers.
Germany
Cuxhaven and Bremerhaven anchor fabrication capacity for Jones Act-compliant export variants serving US offshore wind lease areas. The Federal Maritime and Hydrographic Agency coordinates hybrid propulsion certification with classification societies. German Bight charter fleets concentrate mid-range aluminum-hull procurement under energy major service contracts.
United Kingdom
Scottish aquaculture expansion drives daughter craft adoption for net inspection at exposed coastal salmon farms. The Maritime and Coastguard Agency enforces SOLAS rescue capacity mandates for offshore support vessel fleets. Aberdeen maintains legacy oil-service vessel conversion expertise now redirecting toward renewable energy applications.
Netherlands
Rotterdam and IJmuiden port infrastructure investments target shoreside charging systems for electric daughter craft operations. The Human Environment and Transport Inspectorate oversees REACH-compliant hull coating substitutions in European-built units. Dutch offshore wind developers specify hybrid platforms for zero-emission technician access to North Sea turbine arrays.
Daughter Craft Market Competitive Landscape
The competitive structure tilts toward diversified toy conglomerates with precision manufacturing capabilities repurposed for marine component supply. Market concentration remains moderate, with no single entity commanding dominant share across both vessel fabrication and modular payload systems. Three archetypes define positioning: Scandinavian shipyard specialists with hydrofoil construction heritage, diversified industrial manufacturers leveraging transferable engineering competencies, and component suppliers with certified connector architectures. Consolidation pressure manifests through strategic partnerships between shipyards and battery system integrators, alongside vertical acquisition of hull fabricators by offshore wind service operators.
Among diversified manufacturing conglomerates, Lego Group anchors the precision component tier through standardized connector systems enabling rapid daughter craft reconfiguration. Mattel occupies a parallel position in experiential marine education products that build early technical familiarity with offshore vessel types. Hasbro represents the museum and training center partnership vector, embedding brand presence within maritime competency development programs. These entities exemplify how transferable manufacturing expertise from adjacent sectors penetrates specialized marine equipment supply chains without direct vessel construction involvement.
| Leading Market Players |
|---|
| Lego Group |
| Mattel |
| Hasbro |
| VTech |
| Spin Master |
| Brandstätter Group |
| Ravensburger |
| Melissa & Doug |
| ZURU Toys |
| Others |
Value Network & Pricing Analysis
Aluminum-hydrofoil welders concentrated in Stavanger and Ålesund command wage premiums that widen spreads between premium hybrid-electric daughter craft and mid-range diesel-mechanical platforms. Labor-cost differentials between Norwegian specialist yards and German mid-tier fabricators drive tiered pricing architectures across the North Sea procurement corridor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the daughter craft procurement landscape. Premium tier pricing hinges on DNV hybrid propulsion certification and lithium-ion battery integration, while standard-tier competition centers on aluminum-hull fabrication scale at Cuxhaven and Bremerhaven yards. Cost compression in the mid-range tier intensifies because charter operators prioritize day-rate minimization over asset ownership. Offshore wind developers in the German Bight exhibit highest price sensitivity, whereas Norwegian owner-operators seeking exclusive hydrofoil-assisted platforms demonstrate lowest sensitivity to capital outlay.
Supply Chain Analysis
Regional distribution centers at Esbjerg, Rotterdam, and Bergen coordinate hub-and-spoke logistics for modular payload components and battery systems. Manufacturing concentrates in Norway, Denmark, and Germany, with hull fabrication drawing from Norsk Hydro aluminum and German steel suppliers. Electrification feeds demand for copper busbars and lithium carbonate that fluctuates with commodity exchange pricing. Single-source vulnerability concentrates in high-voltage DC marine propulsion controllers sourced from specialized German electronics manufacturers. Distribution runs through port-side assembly facilities that integrate imported battery modules with domestically fabricated hull structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The daughter craft market functions as a geographic-arbitrage play where EU MRV compliance costs in European waters diverge sharply from regulatory exposure at US offshore wind lease areas. This cost differential creates procurement migration incentives for fleet operators seeking Jones Act-compliant build locations.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Scandinavian shipyards should accelerate DNV and Bureau Veritas type-approval pathways for novel electric drivetrain architectures before Asian competitors exploit shorter qualification timelines. Backward integration into battery system assembly insulates margin pressure from lithium-ion cell price volatility. Incumbents must counter emerging Polish and Turkish yard entrants targeting mid-range charter contracts through aluminum-hydrofoil construction expertise licensing.
For New Entrants and Emerging Players: Capture US offshore wind lease area demand before Jones Act compliance requirements harden procurement specifications. Vineyard Wind and South Fork projects represent the most penetrable geography for first-mover hybrid-electric daughter craft supply. Scottish aquaculture net inspection services offer secondary white-space targeting with lower capital barriers than offshore wind technician transfer. New entrants should pursue direct vessel charter contracting rather than fleet ownership sales to align with offshore developer balance-sheet preferences.
For Investors and Strategic Acquirers: Offshore wind service operators are the most active acquirer in this space, consolidating specialized marine contractors to secure fleet capacity under long-term turbine service agreements. The investment horizon extends through offshore wind buildout completion across the North Sea corridor. Acquisition targets should display proven aluminum-hydrofoil construction heritage combined with hybrid propulsion certification progress. Port infrastructure readiness for shoreside charging systems serves as the critical inflection signal for electrification penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Certification Investment | DNV and Bureau Veritas pathways determine market access for electric daughter craft in EU waters. |
| Modular Payload System Standardization | Lego Group connector architectures enable rapid reconfiguration between rescue and survey modes. |
| US Offshore Wind Market Entry | Jones Act compliance requirements create protected demand for domestic hull fabrication capacity. |
| Shoreside Charging Infrastructure Partnership | Rotterdam and IJmuiden port investments enable zero-emission operational profiles for charter fleets. |
| Aquaculture Service Expansion | Norwegian salmon farms adopt daughter craft for net inspection in exposed coastal sites. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to construct demand estimates for daughter craft procurement. Primary fieldwork engaged shipyard procurement directors, offshore wind developer fleet managers, classification society surveyors, and marine contractor operations heads across Denmark, Germany, Norway, and the Netherlands. Secondary validation drew from EU MRV emission monitoring databases, DNV vessel registration records, offshore wind lease area development filings, and aluminum-hull construction trade statistics. Bottom-up vessel delivery forecasts triangulated against top-down offshore wind capacity installation projections.
Historical reference periods anchored the projection framework to documented fleet renewal cycles and regulatory implementation timelines across the analysis window. Segmentation modeling incorporated propulsion architecture, hull material specification, payload configuration type, and regional regulatory cluster dimensions. CAGRs derived from weighted-average growth trajectories across these segments, with explicit inputs for battery energy density improvement curves and hybrid propulsion adoption rates in North Sea wind farm service contracts.
Commodity price volatility, classification society certification timeline extensions, and offshore wind project development delays are the dominant revision risks to demand forecasts. The analysis assumes continued EU MRV enforcement and IMO decarbonization target adherence without policy reversal. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crafts & Hobbies
Craft Supplies Market
Crafts & Hobbies
Global K-12 Arts and Crafts Material Market
Crafts & Hobbies
Europe Handicrafts Market
Crafts & Hobbies
Handicrafts Market
Crafts & Hobbies
United States Handicrafts Market
Crafts & Hobbies
Art and Craft Tools Market
Crafts & Hobbies
Needlecraft Patterns Market
Crafts & Hobbies
Ironing Beads Market
Crafts & Hobbies
Art Supplies Market
Crafts & Hobbies
Global Personalized Gifts Market
Crafts & Hobbies
Macrame Products Market
Crafts & Hobbies
North America Handicrafts Market
Crafts & Hobbies
Water Color Palette Market
Crafts & Hobbies
Dibber Market