
 Wine Cabinets Market | 2026-2036
Wine Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Cabinets Market Outlook
Modular wine cabinet configurations with interchangeable shelving, racking, and cooling units is hardening as the dominant product architecture. Haier leverages its appliance manufacturing scale to offer integrated compressor systems across price tiers. EuroCave anchors its position through specialized cellar-grade climate management technology. Liebherr differentiates via precision German engineering and dual-zone temperature architectures.
Wine cabinets are electromechanical storage appliances engineered to maintain stable temperature, humidity, and UV protection for wine preservation, typically operating between 45°F and 65°F with vibration-dampened compressor or thermoelectric cooling systems. Their primary commercial purpose is to extend wine aging potential and protect investment-grade collections from environmental degradation. Freestanding units dominate residential channel volume due to installation flexibility, while built-in configurations command premium positioning in luxury kitchen renovations. Dual-zone temperature control represents the fastest-expanding specification category as collectors diversify across red and white varietals requiring distinct serving temperatures.
The Department of Energy enforces minimum appliance efficiency standards that constrain compressor selection and insulation thickness in US-manufactured units. California Title 20 regulations impose additional standby power limits that influence control board design and thermoelectric system viability. EPA SNAP program guidelines on refrigerant phase-down are forcing transitions to lower-GWP cooling agents across the supply base. Stakeholders must monitor evolving federal efficiency rulemakings and refrigerant compliance deadlines to align R&D pipelines with forthcoming product certification requirements.
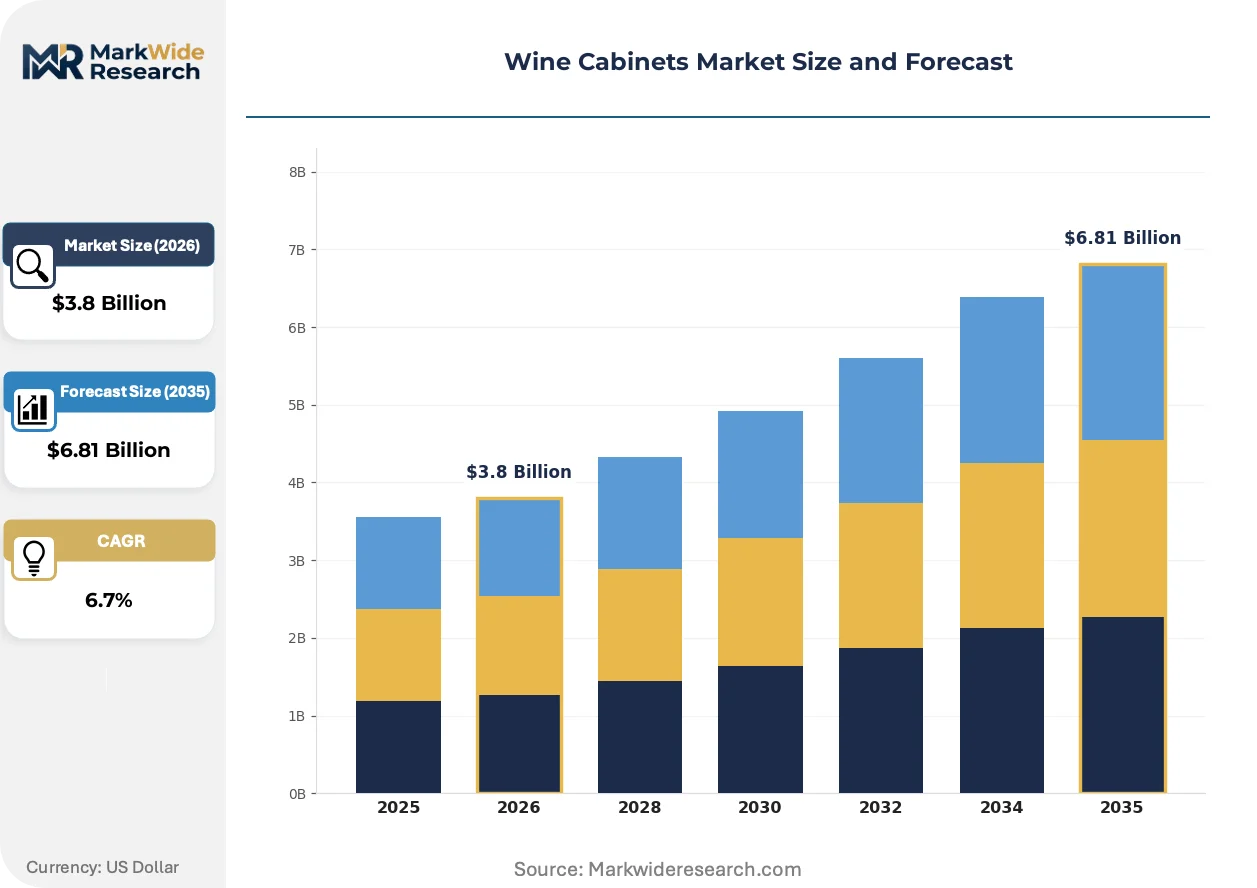
Market Dynamics
Modular wine cabinet architectures are reconfiguring competitive positioning as residential collectors demand interchangeable cooling, racking, and humidity control subsystems. The Department of Energy's escalating efficiency mandates are compressing compressor selection flexibility and forcing insulation redesign cycles.
Growth Catalysts
- California Title 20 standby power limits:Manufacturers are redesigning control boards and thermoelectric systems to meet state-level appliance efficiency thresholds, accelerating innovation in low-draw cooling architectures.
- Dual-zone temperature specification:Collector diversification across red and white varietals is pulling demand for independent climate chambers within single units.
- Home renovation clusters in Texas and Florida:Elevated residential construction activity in these states is expanding installation opportunities for freestanding and built-in configurations.
Market Restraints
- Copper and aluminum input volatility:Compressor manufacturing and heat exchanger fabrication face margin pressure from base metal price swings.
- Refrigerant supply concentration:EPA SNAP program phase-down timelines for high-GWP cooling agents are constraining qualified supplier pools.
- Thermoelectric cooling efficiency ceiling:Peltier systems hit performance walls above 65°F ambient conditions, limiting deployment in warm-climate garages.
Strategic Opportunities
- Underpenetrated secondary US metros:Nashville, Austin, and Raleigh-Durham exhibit rising wine consumption without proportional climate-controlled storage penetration.
- Smart home integration convergence:Wi-Fi-enabled temperature logging and mobile alert systems are opening premium positioning adjacent to connected kitchen ecosystems.
- Hospitality renovation tax incentives:Federal energy-efficient commercial equipment deductions are accelerating replacement cycles in restaurant and hotel wine programs.
Industry Challenges
- Refrigerant certification timeline compression:EPA SNAP compliance deadlines are forcing R&D pipelines to accelerate alternative cooling agent validation.
- Installation skill fragmentation:Built-in configurations require carpentry, electrical, and HVAC coordination that residential contractors rarely consolidate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Cabinets Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Wine Cooler, Under-counter Size: Small Capacity, Medium Capacity, Large Capacity, X-Large Capacity Material: Wood, Metal, Glass, Plastic Temperature Control: Dual Zone, Single Zone, Thermoelectric, Compressor |
| Companies Covered | Haier, Danby, Middleby Corporation, Liebherr, Electrolux, Sub-Zero Group, Avanti Products, EuroCave, Perlick Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Cabinets Market Strategic Shifts
Vibration-dampened compressor mounting and solid-state humidity sensing are rewriting how collectors evaluate preservation performance. Three technology and behavioral vectors are restructuring product development priorities.
Inverter-driven compressor technology is rewriting the trade-off between temperature stability and energy consumption. Residential collectors in premium kitchen renovations are specifying variable-speed cooling systems that eliminate the temperature spikes of traditional on-off cycles. This capability is compressing the performance gap between thermoelectric and compressor architectures at mid-price tiers.
The EPA SNAP program's refrigerant phase-down mandates are forcing transitions to lower-GWP cooling agents across the supply base. Compressor manufacturers must validate alternative refrigerants without sacrificing the 45°F-65°F precision that defines cellar-grade performance. California and Florida manufacturers face the steepest compliance curves due to state-level amplification of federal deadlines.
Collector purchasing patterns are fragmenting across direct-to-manufacturer, specialty appliance retail, and integrated kitchen design channels. Hospitality buyers are consolidating procurement through national foodservice equipment distributors, while residential collectors increasingly specify wine cabinets during architectural planning phases. This bifurcation is most pronounced in California, where kitchen renovation timelines stretch 18-24 months and early specification locks in vendor selection.
Wine Cabinets Market Segmentation
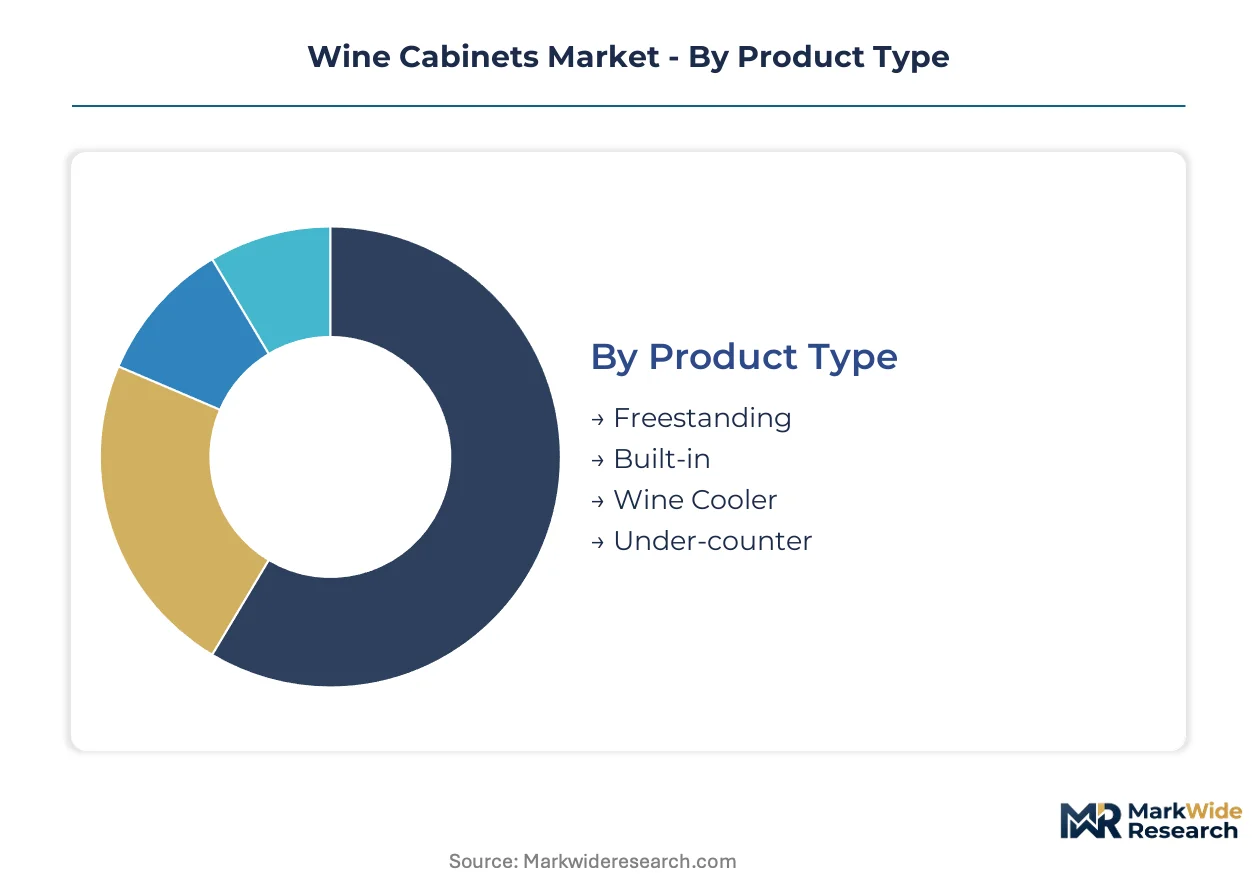
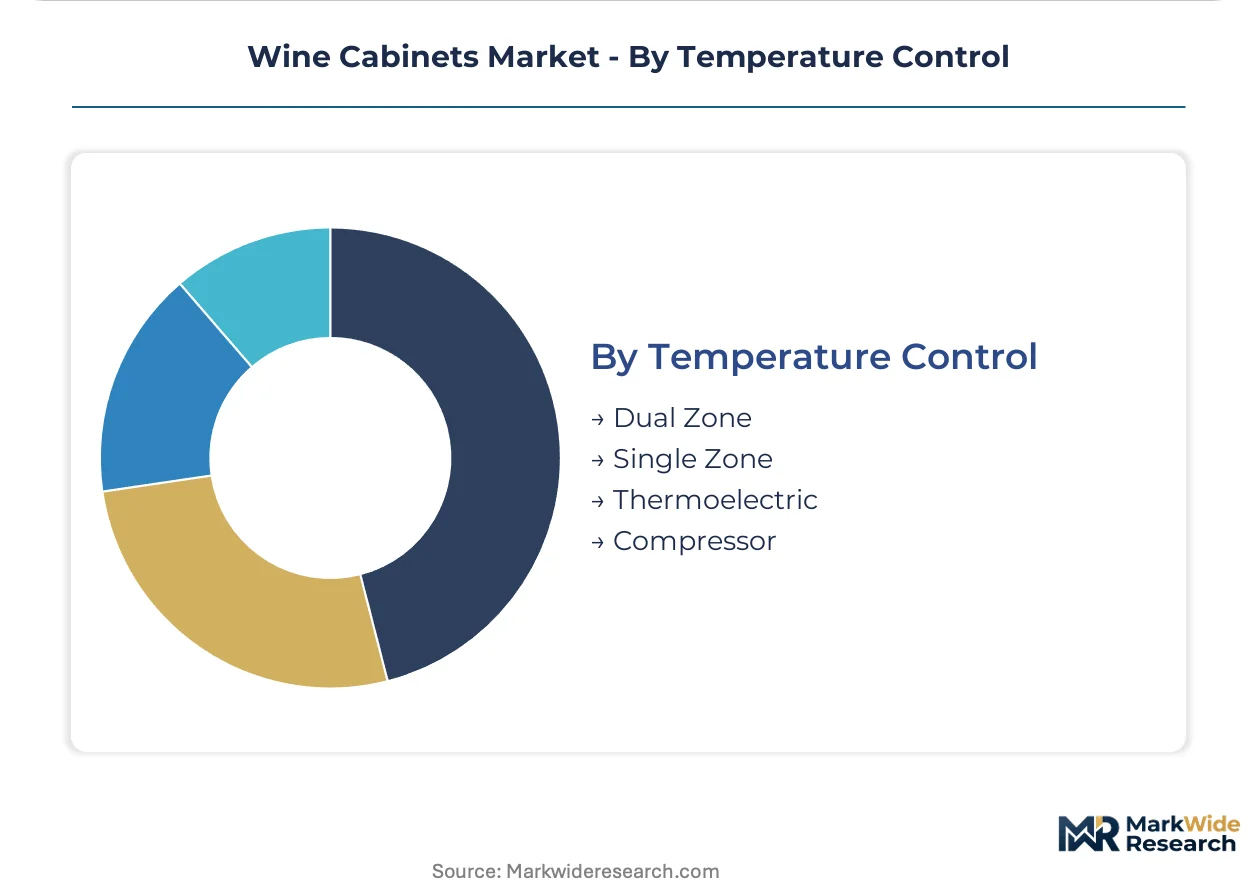
Wine cabinet segmentation tracks how collectors balance installation flexibility against preservation performance. Each dimension—product architecture, storage scale, material finish, and cooling method—carries distinct trade-offs between upfront cost, energy consumption, and aging precision.
Product Type:
Standalone units dominate residential channels where renovation timing or rental constraints prevent permanent installation; embedded configurations anchor luxury kitchen specifications requiring HVAC and cabinetry coordination.
- Freestanding:Self-contained units with integrated cooling and ventilation systems require no permanent utility connections. Demand clusters in Texas and Florida home renovations where installation flexibility outweighs built-in aesthetics, with compressor reliability serving as the primary purchase filter.
- Built-in:Front-venting designs integrate with kitchen cabinetry and require dedicated electrical and sometimes plumbing rough-ins. California luxury renovation pipelines specify these units during 18-24 month architectural planning phases, locking vendor relationships early.
- Wine Cooler:Compact countertop or floor-standing units prioritize portability over precision climate control. Apartment dwellers in secondary metros like Nashville favor these for entry-level collection management.
- Under-counter:Space-efficient designs fit standard kitchen cabinet dimensions with modified ventilation. Florida condo renovations leverage these where square footage constraints eliminate full-height alternatives.
Volume placements concentrate in Freestanding; the faster expansion belongs to Built-in.
Size:
Capacity selection tracks collection maturity curves, with collectors upgrading through tiers as acquisition velocity outpaces consumption.
- Small Capacity:Units storing 12-50 bottles serve novice collectors testing climate-controlled preservation. Austin's emerging wine clubs drive disproportionate demand in this tier.
- Medium Capacity:50-150 bottle configurations balance footprint against aging runway. Raleigh-Durham residential renovations specify these as bridge solutions before dedicated cellar construction.
- Large Capacity:150-300 bottle systems anchor serious residential collections. California collectors migrating from passive storage to active climate management favor this tier for investment-grade holdings.
- X-Large Capacity:300+ bottle commercial-grade units serve hospitality venues and private collectors with institutional-scale holdings. Texas restaurant renovation tax incentives accelerate replacement cycles in this segment.
Medium Capacity generates the highest absolute shipments; X-Large Capacity posts the steepest expansion trajectory among hospitality buyers.
Material:
Finish selection signals aesthetic positioning within kitchen design schemes, with thermal properties secondary to visual integration.
- Wood:Traditional racking and cabinet faces using oak, mahogany, or reclaimed variants. Premium California kitchen designers specify these for wine cellar visual continuity.
- Metal:Stainless steel and aluminum framing dominates contemporary kitchen specifications. Florida coastal installations favor these for humidity resistance.
- Glass:UV-treated door panels balance display visibility against light degradation protection. Texas show kitchens leverage these for entertaining focal points.
- Plastic:Injection-molded shelving and interior components reduce unit cost and weight. Entry-level freestanding units in secondary metros rely heavily on these materials.
Metal and Glass command the highest specification rates in renovation-driven markets; Wood maintains loyalty among traditional cellar aesthetic buyers.
Temperature Control:
Cooling architecture determines precision, noise profile, and ambient temperature tolerance—critical for garage or non-conditioned space deployments.
- Dual Zone:Independent climate chambers maintain distinct temperatures for red and white varietals simultaneously. Collector diversification across varietal categories pulls demand fastest in California and Texas where serving temperature precision matters.
- Single Zone:Uniform temperature throughout the cabinet suits collectors focusing on one wine category or prioritizing aging over serving readiness. Baseline specification for entry-tier units.
- Thermoelectric:Peltier-effect cooling operates without compressor vibration or noise. Efficiency ceilings above 65°F ambient limit deployment in warm-climate garages despite silent operation appeal.
- Compressor:Vapor-compression systems deliver the temperature stability and range required for cellar-grade performance. EPA SNAP refrigerant phase-down mandates are forcing supplier transitions to lower-GWP agents without sacrificing 45°F-65°F precision.
Compressor systems dominate absolute volume; Dual Zone configurations are gaining share fastest as collector sophistication deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal energy-efficient commercial equipment deductions in the United States are accelerating replacement cycles in restaurant and hotel wine programs, concentrating demand in states with elevated renovation activity and wine consumption clusters.
United States
Residential collectors and hospitality venues in California, Texas, and Florida are expanding adoption of climate-controlled storage systems. The Department of Energy enforces minimum appliance efficiency standards that constrain compressor selection and insulation thickness in US-manufactured units. Demand concentrates in California's luxury kitchen renovation pipelines, where 18-24 month architectural planning phases lock vendor relationships early.
Germany
Precision engineering requirements from commercial hospitality buyers are pulling demand for dual-zone temperature architectures. The EU F-Gas Regulation mandates refrigerant phase-down timelines that force transitions to lower-GWP cooling agents across German manufacturing bases. Industrial activity clusters in Baden-Württemberg, where compressor manufacturers validate alternative refrigerants without sacrificing cellar-grade performance precision.
France
Traditional cellar aesthetic preferences sustain demand for wood-finish racking and cabinet faces using oak and mahogany variants. The EU Green Deal amplifies efficiency mandates beyond baseline F-Gas requirements, accelerating insulation redesign cycles. Specialist manufacturers in Burgundy and Bordeaux wine regions anchor positions through localized climate management expertise.
Italy
Contemporary kitchen specifications favor stainless steel and aluminum framing for humidity resistance in coastal installations. CE marking requirements standardize safety and performance thresholds across export-oriented production. Manufacturing concentrates in Lombardy and Veneto, where appliance fabricators serve both domestic renovation demand and Mediterranean hospitality export markets.
China
Dual carbon goals from the Ministry of Ecology and Environment are reshaping compressor and insulation specifications for domestic and export production. MIIT appliance efficiency standards constrain thermoelectric system viability in warm-climate deployments. Production gravity centers on the Yangtze River Delta, where integrated appliance manufacturing scales support cost-competitive freestanding unit exports.
Wine Cabinets Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered price and performance bands. The vendor base organizes around three strategic archetypes: appliance-scale manufacturers leveraging integrated compressor systems, precision-engineering specialists anchoring premium climate management, and hospitality-focused fabricators serving commercial installation channels. Competitive moves concentrate on modular architecture standardization and refrigerant compliance acceleration ahead of regulatory deadlines.
Within the appliance-scale tier, Haier leverages its manufacturing breadth across price tiers, while Electrolux anchors European positioning through diversified kitchen appliance portfolios. EuroCave exemplifies the precision-specialist archetype, occupying a position defined by cellar-grade climate management technology rather than volume scale. Liebherr represents German engineering-focused positioning through dual-zone temperature architectures. These three companies illustrate how competitive differentiation fragments across manufacturing scale, regional engineering heritage, and application-specific climate precision.
| Leading Market Players |
|---|
| Haier |
| Danby |
| Middleby Corporation |
| Liebherr |
| Electrolux |
| Sub-Zero Group |
| Avanti Products |
| EuroCave |
| Perlick Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive compressor manufacturing by Haier and Liebherr anchors supply positions while insulating premium tiers from commodity metal volatility. This vertical integration choice concentrates pricing power with integrated manufacturers, forcing modular assemblers to compete on lead-time flexibility rather than cost structure.
Pricing Analysis
Short lead-time premiums of 15-20% apply to built-in configurations specified during California's extended kitchen renovation cycles, while spot inventory of freestanding units trades at discounted rates. Three-tier pricing structure across premium, standard, and economy levels stratifies by cooling architecture precision and humidity control sophistication. Pricing pressure stems from copper and aluminum input volatility compressing margins on compressor-dependent tiers. Hospitality buyers in Texas and Florida exhibit lowest price sensitivity due to federal energy-efficient equipment tax deductions, whereas apartment dwellers in secondary metros like Nashville drive economy-tier volume through acute cost consciousness.
Supply Chain Analysis
Returns and refurbishment flows remain underdeveloped in wine cabinets, with end-of-life units typically landfilled rather than remanufactured due to refrigerant recovery costs. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta facilities feeding cost-competitive freestanding exports and Baden-Württemberg plants serving precision-engineered dual-zone demand. Supply chains draw from copper wire, aluminum heat exchangers, and lower-GWP refrigerant alternatives. Single-source vulnerability concentrates in compressor motors sourced from integrated appliance conglomerates. Distribution runs through national foodservice equipment distributors for hospitality and specialty appliance retail for residential collectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wine cabinets occupy a technology-transition phase as inverter-driven compressor architectures displace traditional on-off cycling systems. This displacement rewrites the efficiency-stability trade-off that previously favored thermoelectric alternatives in mid-market tiers.
For Market Incumbents: To counter EPA SNAP refrigerant phase-down timeline compression, accelerate alternative cooling agent validation through partnerships with Baden-Württemberg compressor specialists. Secure backward integration into humidity sensor fabrication to defend margin position against solid-state sensing commoditization. Lock early-stage specification relationships with California kitchen designers before architectural planning phases crystallize vendor selection. For New Entrants and Emerging Players: Begin with underpenetrated secondary metros—Nashville, Austin, and Raleigh-Durham—where rising wine consumption lacks proportional climate-controlled storage infrastructure. Target medium-capacity freestanding configurations as the most penetrable tier, bridging novice collectors toward upgrade cycles. Pursue direct-to-consumer channels with Wi-Fi-enabled temperature logging as the primary go-to-market angle against established distributor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified appliance conglomerates seeking climate-management capabilities. Long-term viability favors precision-engineering specialists with cellar-grade certification rather than volume-scale assemblers. Monitor EPA SNAP compliance deadline acceleration as the critical inflection signal for supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Acceleration | EPA SNAP phase-down timelines force lower-GWP validation without sacrificing 45°F-65°F precision standards. |
| Modular Architecture Standardization | Interchangeable cooling and racking subsystems reduce inventory carrying costs across distributor networks. |
| Smart Home Integration Partnership | Wi-Fi-enabled temperature logging opens premium positioning adjacent to connected kitchen ecosystems. |
| Secondary Metro Channel Expansion | Nashville and Austin residential construction pipelines lack proportional climate-controlled storage penetration. |
| Hospitality Tax Incentive Leverage | Federal energy-efficient commercial equipment deductions accelerate replacement cycles in restaurant wine programs. |
Study Parameters
Document review covered SEC 10-K filings from appliance manufacturers, EPA SNAP program rulemakings, and Department of Energy efficiency standards, complemented by interviews with HVAC contractors, kitchen designers, and hospitality procurement managers. Primary fieldwork engaged residential collectors, restaurant wine program directors, and national foodservice equipment distributors. Secondary validation drew from customs trade data, California Title 20 regulatory filings, and industry association shipment reports. Bottom-up demand modeling triangulated against top-down macroeconomic consumption patterns.
Historical shipment trajectories cross-referenced against expert panel inputs on refrigerant transition timelines and renovation cycle durations. Segmentation dimensions modeled include product architecture, capacity tier, cooling method, material finish, and regional regulatory cluster. CAGRs derived from slope-intercept analysis of historical volume trends adjusted for efficiency mandate acceleration. Industry-specific forecast inputs incorporated kitchen renovation pipeline durations and hospitality capital expenditure cycles.
Underlying measurement precision varies by segment; built-in configurations carry tighter precision than freestanding due to specification visibility during architectural planning phases. Forecasts reflect assumptions on refrigerant supplier pool stability and copper price trajectory continuity. Practitioners should monitor EPA SNAP deadline acceleration and California Title 20 standby power limit expansion for early signals of competitive restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Windows Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Mosquito Screen Doors Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
North America Aromatherapy Diffuser Market