
 Mosquito Screen Doors Market | 2026-2036
Mosquito Screen Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Mosquito Screen Doors Market Analytics
Modular screen-and-frame kits is decoupling hardware from installation services, expanding buyer choice across retail and e-commerce channels. Larson Manufacturing Company leverages captive aluminum extrusion capacity to control input costs across hinged and sliding product lines. Phantom Screens specializes in retractable mechanisms, sustaining premium positioning through dealer-exclusive distribution. Andersen Corporation anchors its portfolio with integrated patio door systems that bundle screening with primary glazing.
Mosquito screen doors are barrier assemblies combining woven mesh panels with aluminum, fiberglass, or stainless steel framing, engineered to permit airflow while excluding insects and particulates; mesh density typically ranges from 18×16 to 20×20 strands per inch, with fiberglass dominating residential applications due to corrosion resistance and color stability. Retractable screens command the fastest expansion as homeowners prioritize unobstructed views and seasonal deployment flexibility. Aluminum frames retain structural share in commercial and industrial end uses where durability thresholds exceed residential requirements. DIY installation channels erode professional fitting margins in mature North American and European markets while creating volume opportunities in price-sensitive geographies.
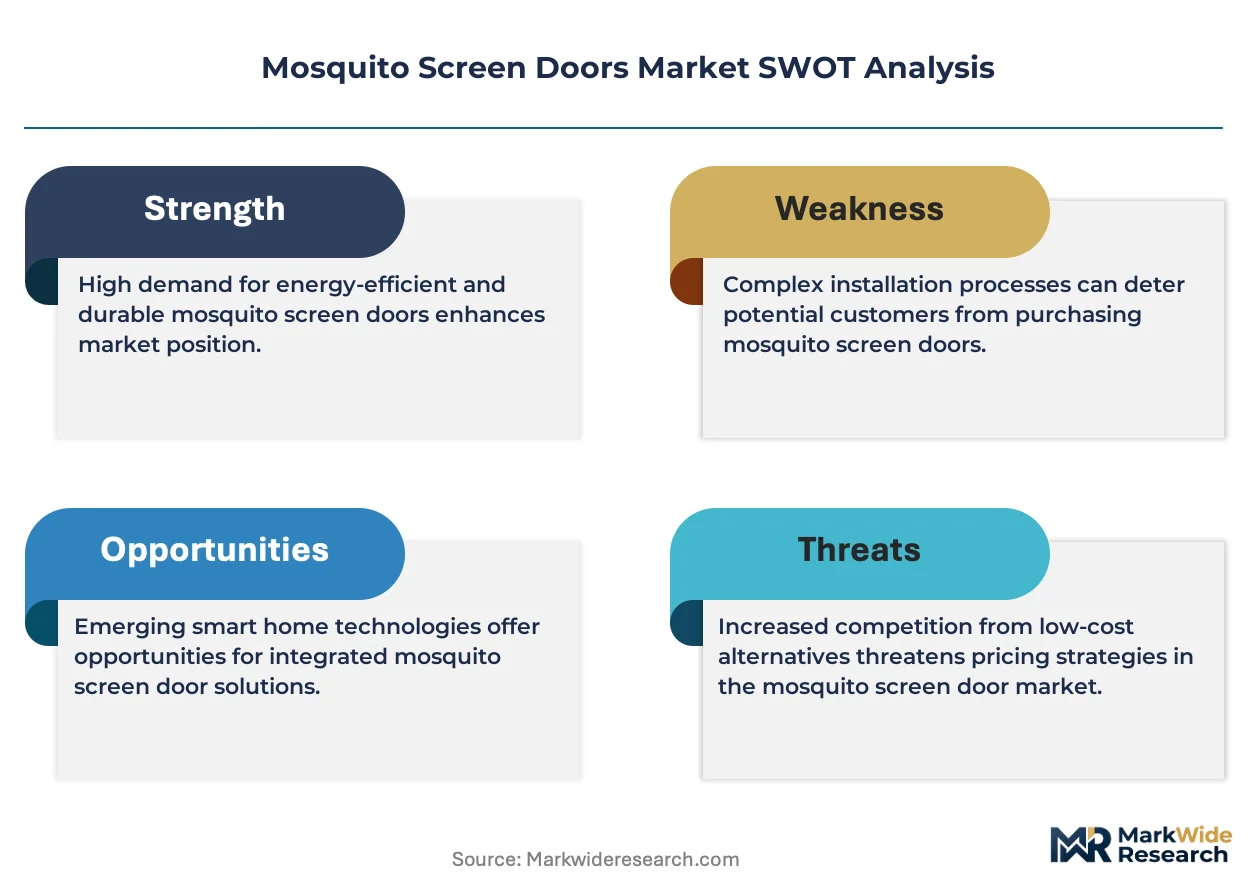
The US EPA regulates treated mesh coatings under FIFRA pesticide device provisions, while REACH compliance in Europe restricts heavy metal content in aluminum alloy finishes and phthalate plasticizers in vinyl frame components. India's BIS mandates dimensional and performance standards for insect screens under IS 17009, shaping product specifications for domestic manufacturers and import qualification. Stakeholders must monitor evolving vector-control public health mandates and building envelope energy codes that increasingly classify insect screening as thermal performance accessories rather than standalone hardware.
Market Dynamics
Climate-adaptive building codes across tropical and subtropical zones are mandating insect screening as standard envelope components, converting discretionary purchases into compliance-driven specifications and compressing traditional hardware distribution channels.
Growth Catalysts
- Vector-borne disease programs:India's National Vector Borne Disease Control Programme and Brazil's Ministry of Health are subsidizing household screening installations in endemic regions, creating institutional procurement pipelines.
- Fiberglass mesh fatigue reduction:Advanced polymer coatings are extending service life from 5-7 years to 12-15 years, lowering total cost of ownership for multi-unit residential developers.
- REACH compliance migration:European aluminum finish restrictions are accelerating water-based coating adoption, opening premium positioning for certified suppliers.
Market Restraints
- Raw aluminum price volatility:LME aluminum fluctuations above 15% annually destabilize frame manufacturing margins, particularly for extrusion-dependent producers.
- Supply concentration in Chinese mesh weaving:70% of global fiberglass screen fabric originates from Zhejiang and Jiangsu provinces, creating geopolitical and logistics risk exposure.
- Vinyl frame brittleness in UV extremes:Phthalate-restricted formulations under REACH show accelerated degradation in Gulf Coast and Australian interior conditions versus legacy compounds.
Strategic Opportunities
- Retractable mechanism retrofits:North American and Australian homeowners are replacing fixed screens with motorized retraction systems, commanding 3-4x unit economics.
- E-commerce kit penetration:Modular screen-and-frame assemblies are bypassing traditional dealer networks in Southeast Asian urban corridors, capturing price-sensitive first-time buyers.
- Integrated thermal performance classification:California Title 24 and similar state energy codes are reclassifying insect screening as envelope insulation accessories, qualifying products for efficiency rebates.
Industry Challenges
- Dealer network certification bottlenecks:Phantom Screens and similar premium brands require 18-24 month dealer qualification cycles, constraining geographic expansion velocity.
- Cross-border BIS compliance complexity:India's IS 17009 dimensional standards create testing and documentation burdens for Southeast Asian exporters targeting the subcontinent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mosquito Screen Doors Market |
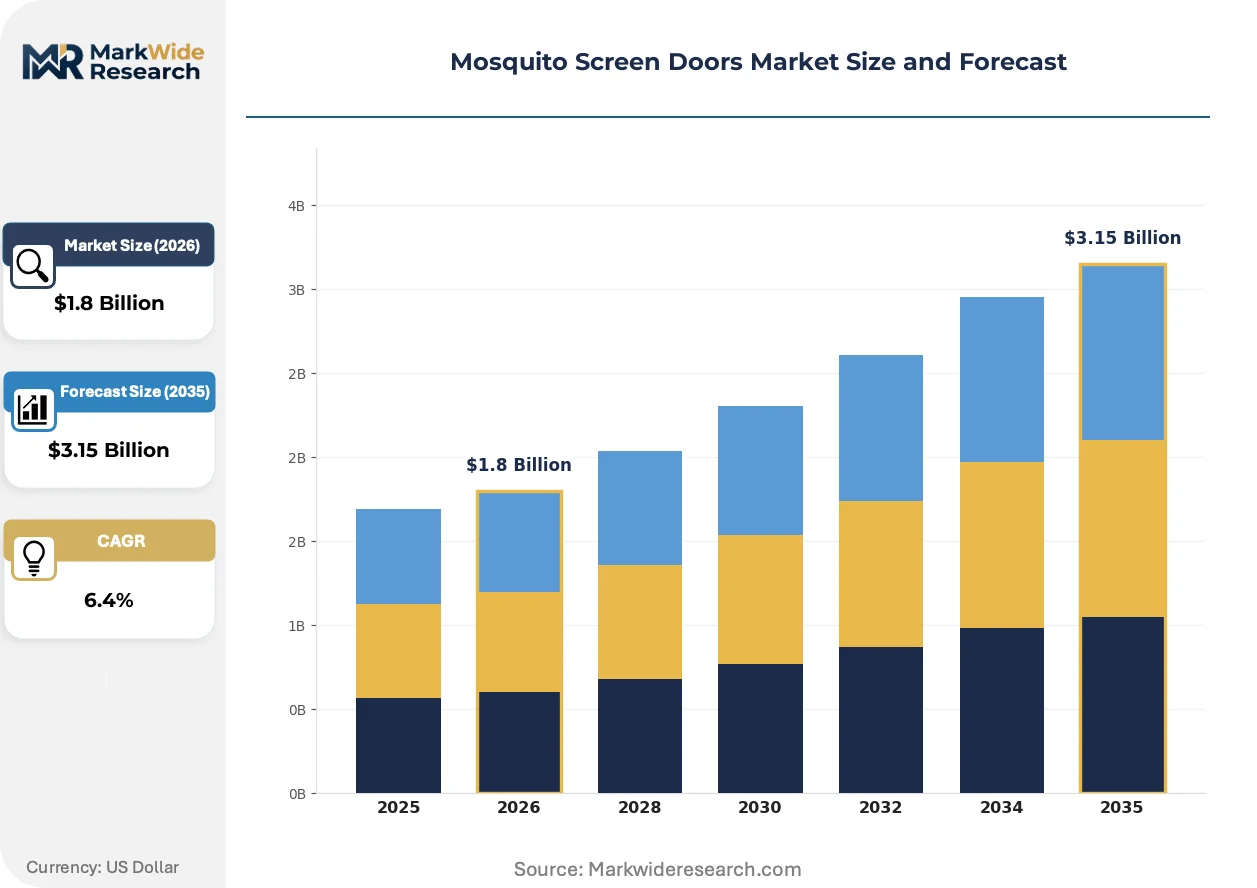
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable Screens, Magnetic Screens, Hinged Screens, Sliding Screens Material: Fiberglass, Aluminum, Polyester, Stainless Steel End User: Residential, Commercial, Industrial, Retail Installation Type: DIY Installation, Professional Installation, Fixed Installation, Temporary Installation |
| Companies Covered | Larson Manufacturing Company, Velux Group, Andersen Corporation, Saint-Gobain, Masonite International Corporation, Pella Corporation, Marvin, Phantom Screens, JELD-WEN Holding, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mosquito Screen Doors Market Evolving Landscape
Mesh engineering and frame material science are converging with smart home infrastructure, while regulatory reclassification of screening as building envelope components is rewiring procurement authority from maintenance departments to construction specification teams.
Photocatalytic titanium dioxide coatings are integrating self-cleaning functionality into fiberglass mesh surfaces, decomposing organic debris through UV activation. High-end residential developers in Florida and Queensland are specifying these treatments as standard, compressing after-sales service revenue pools while enabling 20-year warranty terms that differentiate premium positioning.
REACH restrictions on hexavalent chromium in aluminum anodizing are forcing European manufacturers toward trivalent chromium and ceramic-based alternatives. Frame finish durability testing cycles have extended from 1,000 to 3,000 hours salt spray exposure, raising capital requirements for compliant coating lines and filtering smaller extrusion shops from certified supplier lists.
Seasonal deployment patterns are fragmenting the replacement cycle from fixed 7-10 year intervals to staggered component refresh, with retractable mechanism hardware replaced at 8-12 years while mesh panels refresh at 4-6 years. This unbundling is most visible in Australian and Californian markets where homeowners treat screening as climate-responsive equipment rather than permanent fixtures, creating recurring revenue opportunities for service-oriented distributors.
Mosquito Screen Doors Market Segmentation
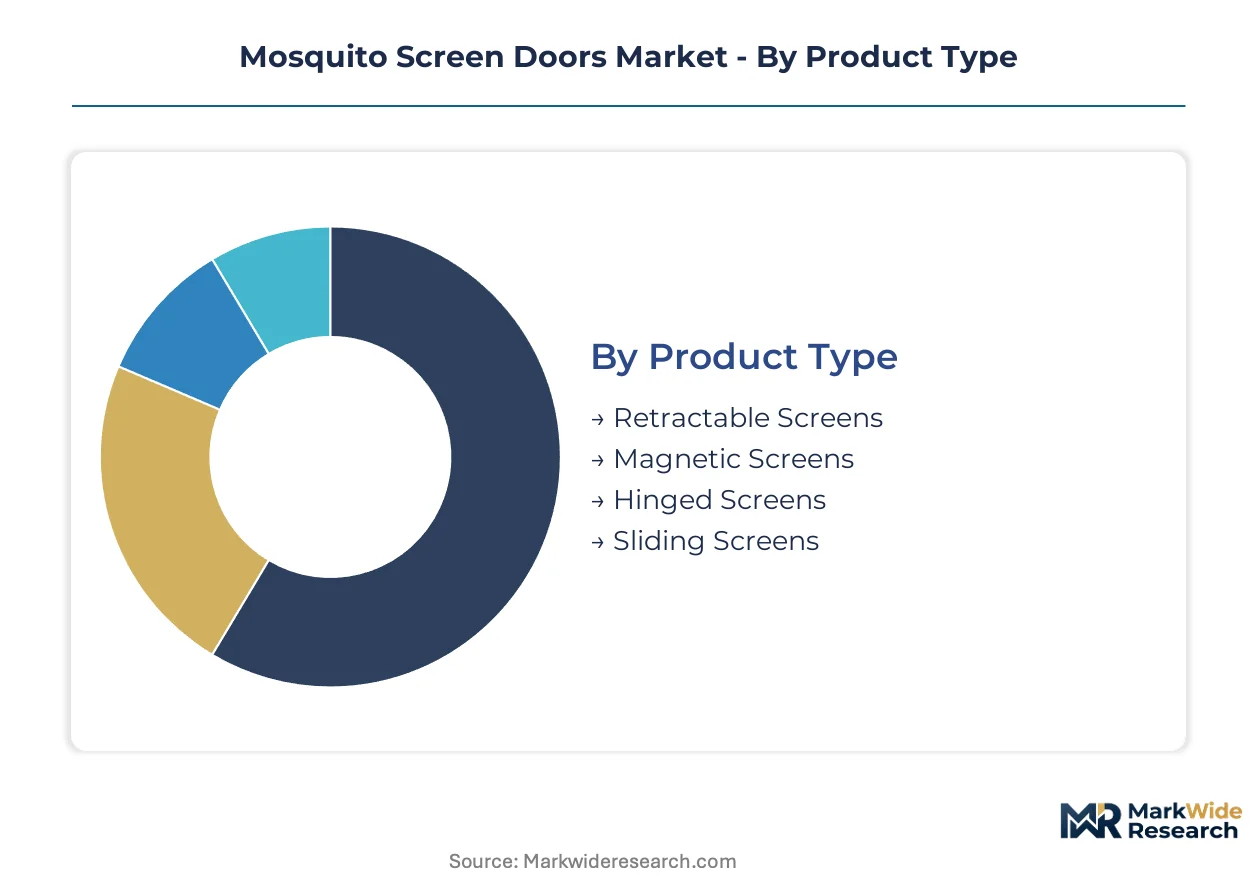
Segmentation in mosquito screen doors reveals how supply chain configuration, material science maturity, and installation labor economics partition value capture across distinct buyer ecosystems. Understanding these divides enables suppliers to align production capacity with channels where margin structures remain defensible.
Product Type:
Supply concentration in retractable mechanism manufacturing centers on North American and Australian specialist producers with captive extrusion and motorization capabilities.
- Retractable Screens:Motorized or manual roll-away systems using spring-tensioned or electric drive mechanisms, typically housing mesh in aluminum cassettes. Demand concentrates in Florida, California, and Queensland where seasonal deployment flexibility commands premium positioning against fixed alternatives.
- Magnetic Screens:Mesh panels with magnetic center closures enabling hands-free passage, constructed with fiberglass or polyester weave. These dominate Southeast Asian e-commerce channels where price-sensitive first-time buyers prioritize low entry cost over durability ratings.
- Hinged Screens:Traditional swing-door assemblies with aluminum or fiberglass frames mounted on butt or piano hinges. These retain share in Indian and Brazilian residential construction where vector-borne disease programs subsidize standardized screening.
- Sliding Screens:Track-mounted panels operating parallel to primary door systems, common in patio and balcony applications. European markets favor these for integration with aluminum-framed glazing systems under REACH-compliant finish specifications.
Hinged screens absorb the bulk of installed capacity; retractable screens are expanding most quickly.
Material:
Cost tier differentiation separates premium corrosion-resistant alloys from commodity polymer weaves, with volume economics favoring integrated manufacturers controlling upstream fiber or extrusion inputs.
- Fiberglass:Vinyl-coated glass fiber strands woven into 18×16 to 20×20 mesh density, offering color stability and salt corrosion resistance. This material dominates residential applications across India, Brazil, and Southeast Asia where humidity and coastal exposure accelerate metal fatigue.
- Aluminum:Extruded alloy frames in 6063-T5 or 6061-T6 grades, with anodized or powder-coated finishes. Commercial and industrial end uses in the US, Germany, and Japan specify these for structural load-bearing thresholds exceeding residential requirements.
- Polyester:Synthetic polymer mesh with PVC or PET coatings, lighter than fiberglass but prone to UV embrittlement. Temporary installation channels favor these for seasonal deployment in price-sensitive geographies.
- Stainless Steel:304 or 316 grade woven wire mesh providing maximum durability and security integration. Premium residential and high-security commercial applications in Australia and the UAE specify these despite 3-4x material cost premiums.
Fiberglass commands the greatest production volume; stainless steel is gaining share fastest in security-integrated segments.
End User:
Application-specific performance requirements create divergent procurement authority patterns, with construction specification teams controlling commercial and industrial decisions while residential buyers fragment across retail and contractor channels.
- Residential:Single-family and multi-unit housing applications driving replacement cycles and new construction fit-outs. India's National Vector Borne Disease Control Programme and Brazil's Ministry of Health subsidization programs concentrate institutional procurement in this segment.
- Commercial:Office, hospitality, and healthcare facilities requiring code-compliant screening with fire-rated or accessibility certifications. California Title 24 and similar state energy codes in the US reclassify these as thermal performance accessories qualifying for efficiency rebates.
- Industrial:Manufacturing and warehousing facilities prioritizing particulate exclusion alongside insect barrier functionality. These applications favor aluminum frame durability under OSHA and EPA facility standards.
- Retail:Showroom, restaurant, and storefront installations where aesthetic integration with primary glazing systems determines specification. Dealer-exclusive distribution networks control access to premium retractable products in this segment.
Residential absorbs the bulk of unit volume; commercial is climbing the fastest as energy code reclassification unlocks rebate-funded upgrades.
Installation Type:
Customer type fragmentation separates skilled labor-dependent professional fitting from self-assembly kit economics, with channel strategy determining margin capture across mature versus emerging markets.
- DIY Installation:Modular screen-and-frame kits with pre-cut components and snap-fit or screw-mount hardware. E-commerce penetration in Southeast Asian urban corridors and North American big-box retail channels expands access for price-sensitive buyers.
- Professional Installation:Dealer or contractor-fitted systems with measurement, customization, and warranty service bundled. Premium retractable brands require 18-24 month dealer qualification cycles, constraining geographic expansion velocity.
- Fixed Installation:Permanent mounting integrated during construction or major renovation, common in new residential and commercial builds. Climate-adaptive building codes across tropical zones mandate these as standard envelope components.
- Temporary Installation:Seasonal or rental-friendly solutions using tension rods, adhesive mounts, or magnetic attachments. Australian and Gulf Coast markets treat these as climate-responsive equipment with 4-6 year replacement cycles.
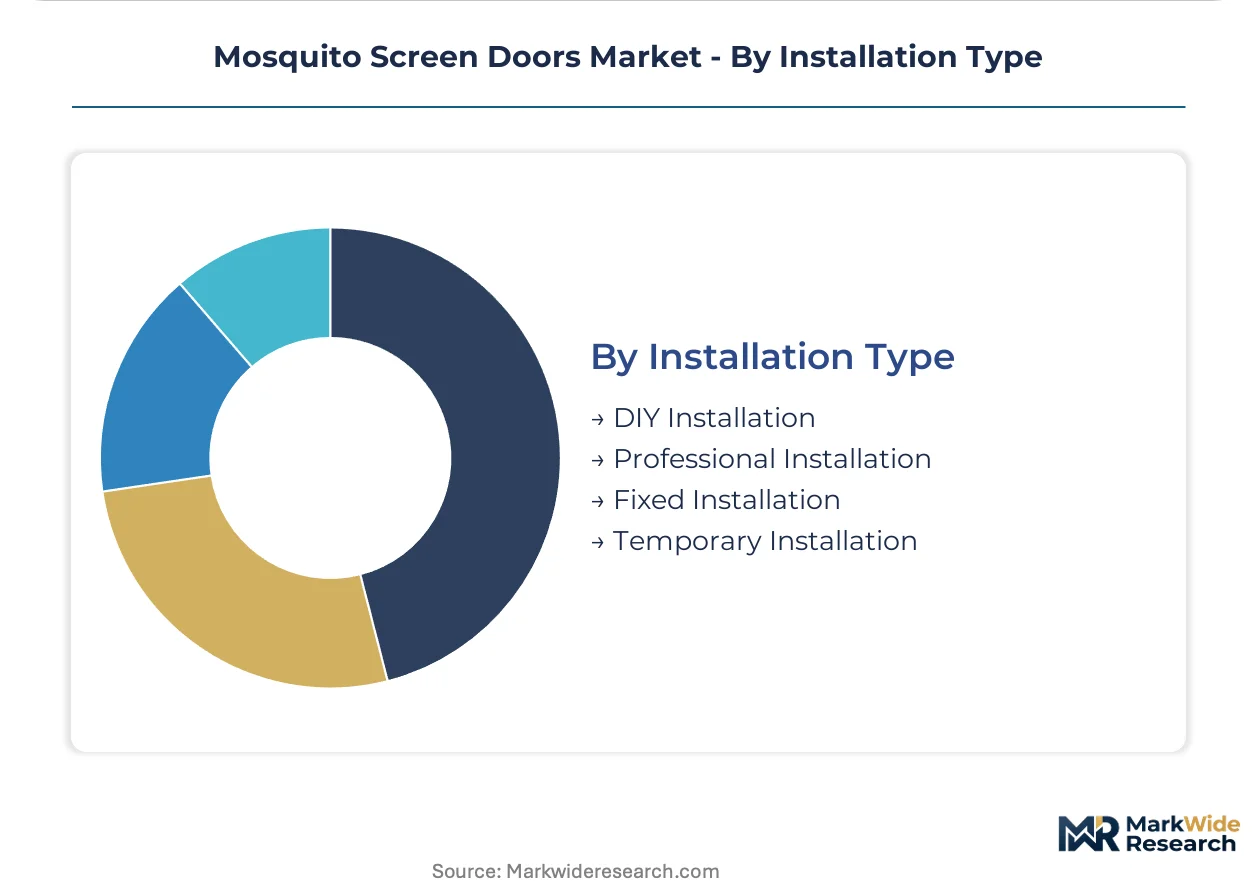
Fixed installation retains the largest installed base; DIY channels are expanding most quickly as e-commerce logistics mature in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China dominates mesh weaving capacity while India and Brazil absorb the bulk of finished product demand through vector-control subsidy programs. Southeast Asian construction markets are converting discretionary screening purchases into mandatory building code compliance.
United States
California Title 24 reclassifies insect screening as thermal performance accessories, unlocking efficiency rebates for retrofits. The EPA regulates treated mesh coatings under FIFRA pesticide device provisions. Florida's Gulf Coast corridor concentrates demand for retractable systems with seasonal deployment flexibility.
India
The National Vector Borne Disease Control Programme subsidizes household screening installations across endemic regions. BIS mandates dimensional and performance standards under IS 17009, shaping import qualification requirements. Maharashtra and Gujarat host domestic manufacturing clusters serving institutional procurement pipelines.
Brazil
The Ministry of Health funds screening installations in dengue and malaria-endemic zones through municipal health budgets. ANVISA oversight applies to insecticide-impregnated mesh products. São Paulo state's construction sector drives specification of hinged screen systems in multi-unit residential developments.
Germany
REACH restrictions on hexavalent chromium in aluminum anodizing force trivalent chromium and ceramic coating adoption. Frame finish durability testing extends to 3,000 hours salt spray exposure. North Rhine-Westphalia's extrusion industry filters smaller shops from certified supplier lists.
Australia
Queensland homeowners treat screening as climate-responsive equipment with staggered component refresh cycles. The TGA framework influences treated mesh registration for therapeutic insecticide claims. Southeast Queensland and New South Wales coastal markets prioritize retractable mechanisms for unobstructed views.
Mosquito Screen Doors Market Competitive Landscape
The competitive structure tilts toward integrated building products conglomerates with captive aluminum extrusion capacity. Market concentration remains moderate, with premium retractable specialists commanding margin premiums through dealer-exclusive distribution. Three archetypes dominate: vertically integrated door/window manufacturers, specialist screening mechanism producers, and commodity mesh fabricators. Competitive moves center on geographic expansion into Southeast Asian e-commerce channels and portfolio diversification toward motorized smart-home integration.
Among North American integrated manufacturers, Larson Manufacturing Company, Andersen Corporation, and Phantom Screens occupy distinct positioning tiers. Larson Manufacturing Company exemplifies the extrusion-integrated archetype controlling input costs across hinged and sliding product lines. Andersen Corporation anchors the premium patio door system segment where screening bundles with primary glazing. Phantom Screens represents the specialist retractable mechanism tier sustaining premium positioning through extended dealer qualification cycles.
| Leading Market Players |
|---|
| Larson Manufacturing Company |
| Velux Group |
| Andersen Corporation |
| Saint-Gobain |
| Masonite International Corporation |
| Pella Corporation |
| Marvin |
| Phantom Screens |
| JELD-WEN Holding, Inc. |
| Others |
Value Network & Pricing Analysis
Raw aluminum extrusion costs cascade through three pricing tiers as LME volatility destabilizes frame manufacturing margins, with captive smelter access separating premium retractable specialists from commodity hinged-screen assemblers in India and Brazil.
Pricing Analysis
Price erosion across economy-tier magnetic screens traces to fiberglass mesh oversupply from Zhejiang weaving clusters, while premium retractable systems sustain margin buffers through dealer-exclusive bundling of measurement and installation services. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with BIS IS 17009 compliance commanding tier-one positioning in Indian institutional procurement. DIY installation kits face acute buyer price sensitivity in Southeast Asian e-commerce channels, eroding hardware-only margins.
Supply Chain Analysis
Workforce availability constraints in Guangdong extrusion shops and Maharashtra assembly plants are tightening lead times for aluminum frame components. Raw material dependencies draw from Chinese fiberglass weaving, Indonesian bauxite refining, and German coating chemistry. Single-source vulnerability concentrates in Zhejiang and Jiangsu provinces where seventy percent of global mesh fabric originates. Distribution runs through dealer networks for premium retractable brands and direct-to-retailer logistics for modular kit producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive aluminum extrusion capacity has become the decisive upstream lever as frame finish durability testing extends to three thousand hours salt spray exposure, filtering smaller suppliers from certified procurement lists.
For Market Incumbents: Deepen backward integration into fiberglass mesh coating operations to offset REACH compliance costs and raw material volatility. Secure long-term offtake agreements with Zhejiang weaving clusters to mitigate single-source concentration risk. Expand captive extrusion capacity in Maharashtra and Gujarat to serve India's vector-control subsidy pipelines. For New Entrants and Emerging Players: Photocatalytic titanium dioxide coating technology offers a technology-first wedge into Florida and Queensland premium residential specifications where twenty-year warranty terms differentiate positioning. Target Southeast Asian e-commerce channels for modular magnetic screen kits where price-sensitive first-time buyers bypass traditional dealer networks. Pursue white-label partnerships with regional aluminum extruders to circumvent eighteen-month dealer qualification cycles. For Investors and Strategic Acquirers: California Title 24 reclassification of insect screening as thermal performance accessories is the leading indicator that rebate-funded commercial retrofit demand will sustain above-trend replacement cycles. Acquisition targets should screen for captive coating line certification and BIS IS 17009 testing documentation. Monitor LME aluminum price volatility as a margin compression signal requiring portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Extrusion Capacity Expansion | Larson Manufacturing's in-house 6063-T5 production insulates frame margins from LME volatility. |
| REACH-Compliant Coating Line Investment | Trivalent chromium and ceramic alternatives filter smaller European suppliers from certified lists. |
| Dealer Network Certification Acceleration | Phantom Screens' eighteen-month qualification cycles constrain geographic expansion velocity for rivals. |
| E-Commerce Kit Penetration | Modular assemblies bypass traditional distribution in Southeast Asian urban corridors. |
| Smart Home Integration Partnership | Motorized retraction systems command three-to-four-fold unit economics in North American retrofits. |
Research Methodology
Multi-period observation of fiberglass mesh fatigue rates, aluminum price volatility, and vector-control subsidy disbursements anchored the trend analysis, supplemented by interviews with aluminum extrusion plant managers, insect screen distributors, building code specification officers, and public health procurement leads. Secondary validation drew from BIS certification databases, EPA FIFRA registration filings, REACH compliance disclosures, and customs trade records. Bottom-up channel volume estimates triangulated against top-down construction permit data.
Segment-weighting across product type, material grade, end-user application, and installation channel structured the analytical framework. CAGRs derived from installed base replacement cycles, new construction fit-out ratios, and regulatory mandate adoption curves. Industry-specific inputs included climate-adaptive building code expansion timelines and vector-borne disease program budget allocations.
Several conditions sit outside the modeled scope, including geopolitical disruption to Chinese mesh weaving capacity, abrupt REACH formulation bans, and aluminum price spikes exceeding historical volatility bands. Forecasts reflect assumptions about subsidy program continuity and code adoption trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
Windows Market