
 Global Stair Lifts Market | 2026-2036
Global Stair Lifts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stair Lifts Market Outlook
The divergence between premium custom-curved rail systems and commodity straight-rail units is realigning how manufacturers allocate engineering resources. Savaria Corporation leverages its vertical integration into rail fabrication to sustain margin control across North American distribution. Stannah Lifts Holdings Ltd. anchors its competitive position through century-old brand equity in British domestic installations. Handicare Group AB differentiates via specialized pediatric and bariatric seating configurations that command higher service attach rates.
A stair lift is a motorized chair or platform transport system mounted on a rail affixed to stair treads or walls, typically powered by a 24-volt DC motor with battery backup, designed to convey mobility-limited individuals between floor levels in residential and commercial structures. Electric stair lifts dominate installed base volumes while rack and pinion drive systems capture preference in steep-gradient or outdoor applications where belt slippage risks escalate. Healthcare facilities represent the fastest-growing application segment as hospitals retrofit aging infrastructure to meet accessibility mandates without elevator shaft construction.
The FDA classifies powered stair lifts as Class II medical devices under 510(k) premarket notification pathways, while the EU Medical Device Regulation and CE marking framework impose clinical evaluation and post-market surveillance obligations that extend product development cycles. Japan's Ministry of Economy, Trade and Industry (METI) enforces JIS standards for electromagnetic compatibility and structural load testing that shape export eligibility for foreign manufacturers. Stakeholders must monitor how reimbursement code harmonization between Medicare Advantage plans and national health systems in key markets determines end-user affordability thresholds and replacement cycle timing.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines while simultaneously elevating barriers to entry for powered mobility equipment, forcing manufacturers to absorb extended clinical evaluation costs or exit European markets entirely.
Growth Catalysts
- Aging-in-place policy mandates:OECD governments are expanding home modification subsidies that directly cover stair lift installations, accelerating residential procurement cycles in Germany, Japan, and the United States.
- Healthcare facility retrofit mandates:Accessibility compliance deadlines for aging hospital infrastructure are triggering non-residential demand without requiring capital-intensive elevator shaft construction.
- Rack and pinion drive technology:Steep-gradient and outdoor applications are shifting toward this mechanism where belt slippage risks previously limited product viability.
Market Restraints
- Aluminum and steel input volatility:Rail fabrication costs fluctuate with commodity metal prices, squeezing margin control for manufacturers lacking captive supply of extruded rail stock.
- Certification timeline extension:The EU MDR's post-market surveillance obligations are stretching product development cycles by twelve to eighteen months for new entrants.
- Platform lift substitution:Vertical platform lifts are capturing bariatric and wheelchair-user demand in commercial settings where stair geometry permits alternative configurations.
Strategic Opportunities
- Pediatric and bariatric seating specialization:Specialized configurations command premium service attach rates in underserved mobility segments with distinct anthropometric requirements.
- Medicare Advantage harmonization:Reimbursement code alignment between private plans and national health systems is expanding end-user affordability thresholds in the United States.
- Outdoor weatherized systems:Corrosion-resistant drive mechanisms and sealed electronics are opening residential exterior stair applications previously abandoned to platform alternatives.
Industry Challenges
- Electromechanical technician scarcity:Installation and maintenance networks require specialized skills combining 24-volt DC motor diagnostics with structural load assessment, limiting service expansion velocity.
- Legacy building integration complexity:Pre-1940s residential stair geometries often lack uniform tread dimensions, forcing custom rail fabrication that fragments production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stair Lifts Market |
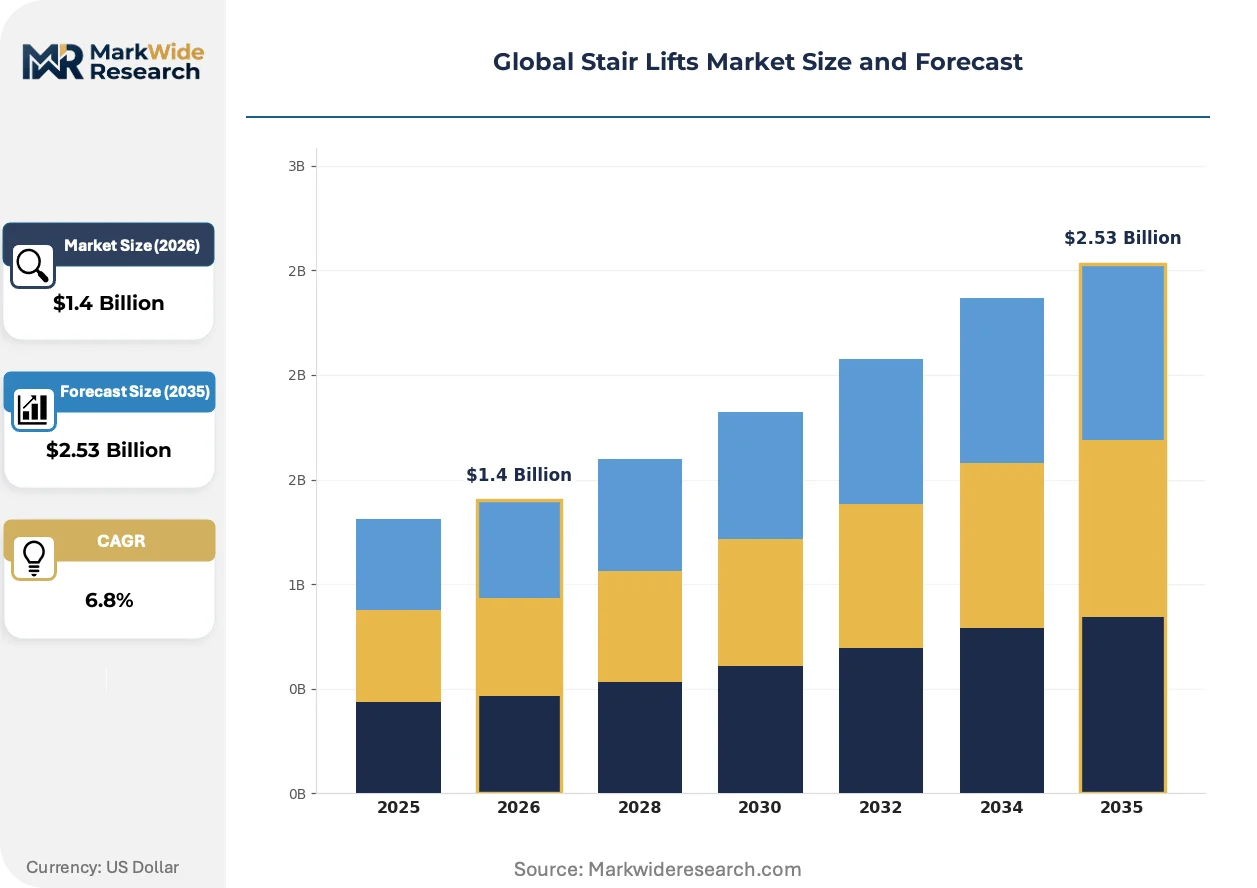
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
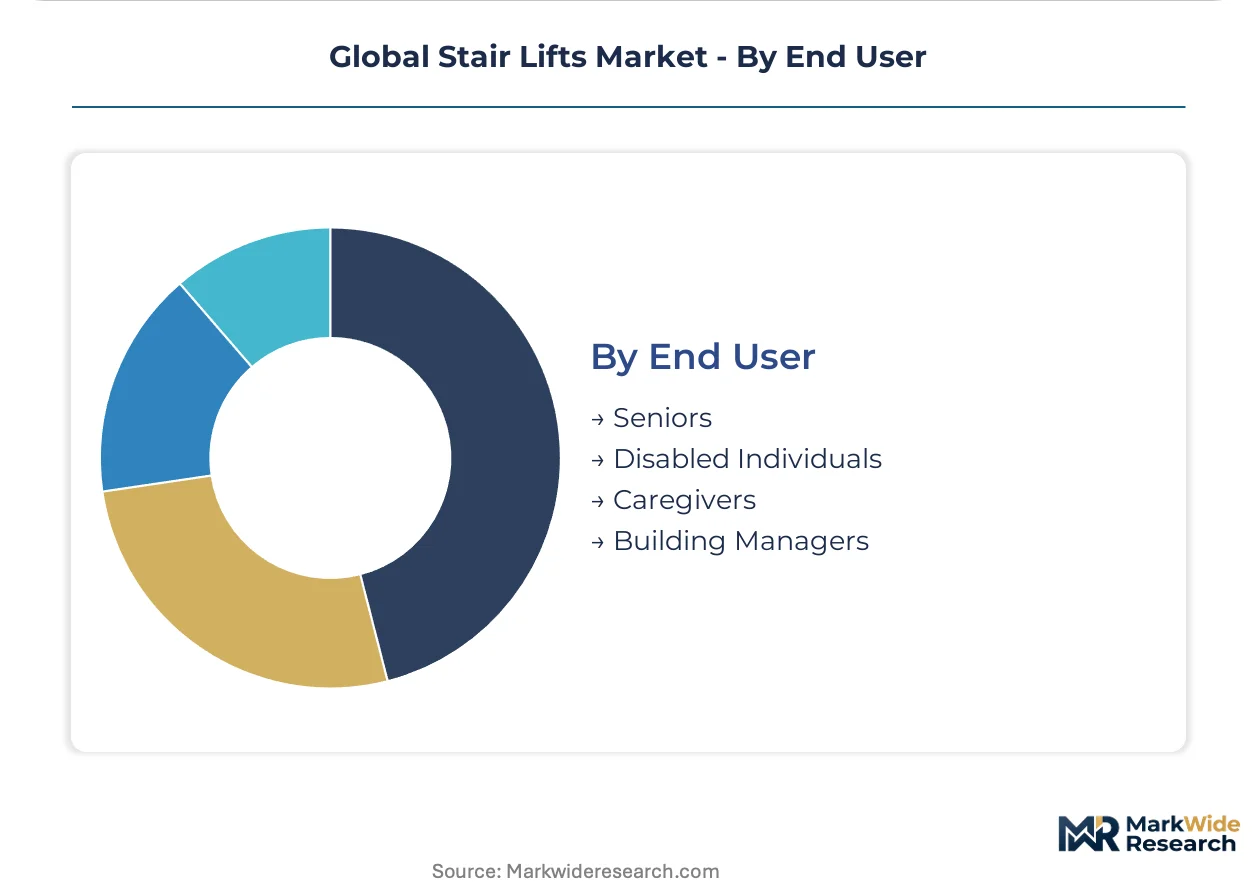
| Segmentation | Product Type: Acoustic Stair Lifts, Electric Stair Lifts, Manual Stair Lifts, Vertical Lifts Application: Residential Buildings, Commercial Spaces, Healthcare Facilities, Public Access Buildings Technology: Hydraulic Systems, Mechanical Systems, Belt Systems, Rack and Pinion Systems End User: Seniors, Disabled Individuals, Caregivers, Building Managers |
| Companies Covered | Savaria Corporation, Stannah Lifts Holdings Ltd., Acorn Stairlifts Inc., Bruno Independent Living Aids Inc., Handicare Group AB, Otolift Stairlifts Ltd., Harmar Mobility LLC, ThyssenKrupp AG, TK Elevator GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stair Lifts Market Strategic Shifts
Software-defined safety systems and modular rail architectures are displacing fixed mechanical designs, enabling faster field customization while reducing inventory carrying costs for distribution networks.
Smart diagnostic sensors embedded in drive motors and rail tracks are rewriting maintenance economics for residential stair lifts. Home care agencies and third-party service providers are adopting predictive failure monitoring to compress emergency call response times. The technology is enabling outcome-based service contracts that shift revenue from equipment margin to recurring monitoring fees.
The EU Medical Device Regulation's clinical evaluation requirements are reshaping competitive positioning for powered mobility equipment. Manufacturers must now maintain post-market surveillance systems that document real-world performance across installed bases. German and British domestic installers are consolidating supplier relationships to reduce compliance auditing burdens.
Direct-to-consumer digital channels are fragmenting traditional dealer networks for straight-rail commodity units. Manufacturers are bypassing regional distributors to capture margin through online configuration tools and virtual site assessment. Japan's METI standards for electromagnetic compatibility are shaping which foreign suppliers can participate in this channel shift.
Global Stair Lifts Market Segmentation
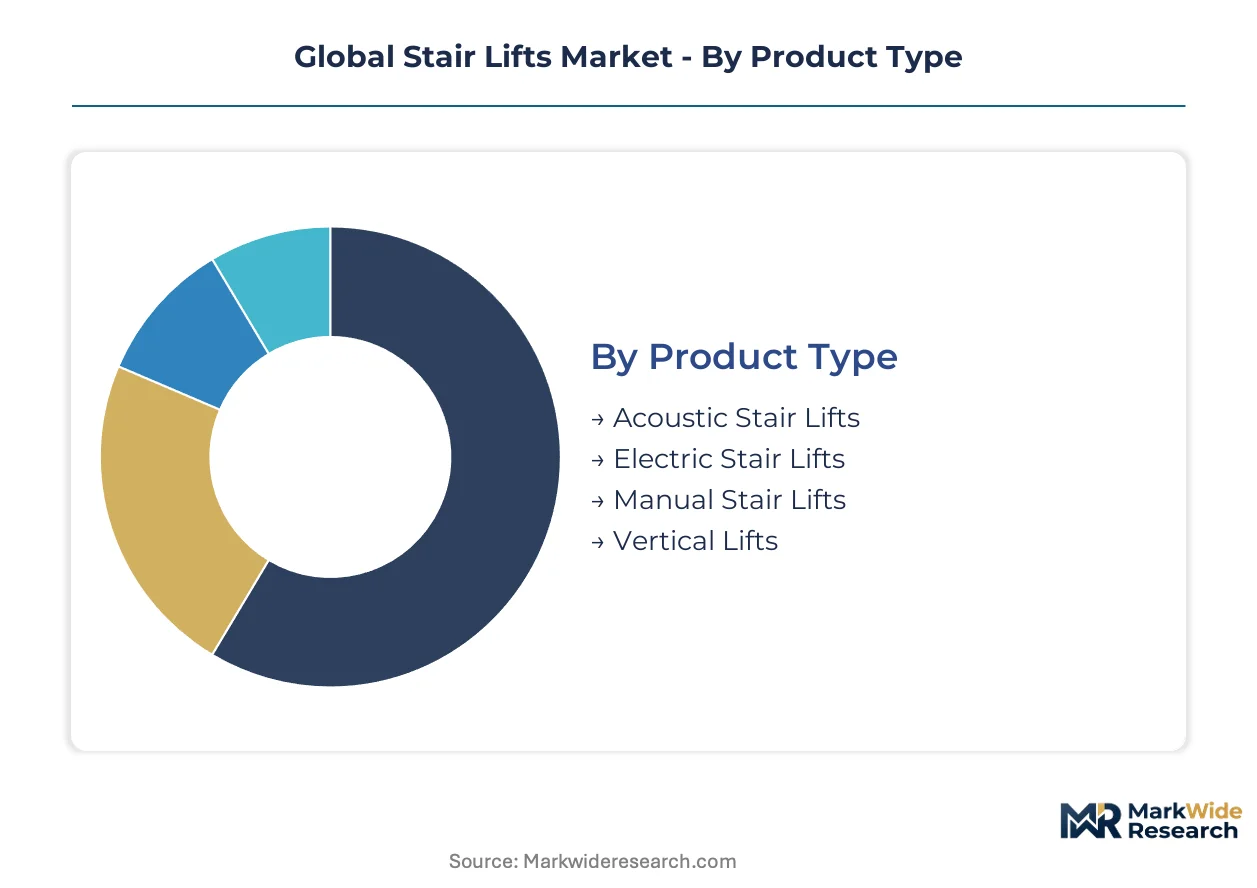
Stair lift procurement patterns diverge sharply between standardized straight-rail configurations for volume residential deployment and engineered curved-rail systems demanding custom rail fabrication. Manufacturers allocate production capacity across these segments based on margin profiles, installation complexity, and service attach rate potential.
Product Type:
Standardization dominates the lower-cost tiers while acoustic and specialized drive systems occupy premium positioning with extended engineering cycles.
- Acoustic Stair Lifts:Sound-dampened drive mechanisms reduce operational noise below 45 decibels for nighttime residential use. Demand concentrates in German and Japanese urban apartments where thin walls amplify motor vibration complaints.
- Electric Stair Lifts:24-volt DC motor systems with battery backup constitute the dominant installed base across OECD residential markets. Medicare Advantage reimbursement pathways in the United States and Japan's LTCI program accelerate replacement cycles for aging DC drive units.
- Manual Stair Lifts:Human-powered chair systems serve emergency backup roles and off-grid installations. Niche demand persists in rural Japan and Alpine regions of Austria and Switzerland.
- Vertical Lifts:Platform configurations bypass stair geometry entirely for wheelchair users. Commercial building managers in the United States specify these for ADA compliance where stair width prohibits seated transport.
Most installed capacity flows through Electric Stair Lifts. Expansion is steepest in Acoustic Stair Lifts.
Application:
End-use economics shift dramatically between private residential decision-makers and institutional procurement committees with mandated accessibility deadlines.
- Residential Buildings:Single-family and multi-unit dwellings drive volume procurement through aging-in-place subsidies. Germany's KfW development bank and Japan's municipal home modification grants cover 70-90% of installation costs for qualifying seniors.
- Commercial Spaces:Retail and office installations face faster payback scrutiny from facility managers. Belt drive systems dominate here for moderate-traffic environments where aesthetic rail integration matters.
- Healthcare Facilities:Hospitals and nursing homes retrofit aging infrastructure without elevator shaft construction. The EU's accessibility mandates for public healthcare buildings trigger non-residential demand climbing fastest among application segments.
- Public Access Buildings:Government and transit facilities specify heavy-duty rack and pinion systems for code compliance. METI certification requirements shape supplier eligibility for Japanese municipal contracts.
Residential Buildings absorb the majority of annual unit shipments. Healthcare Facilities are expanding most quickly as regulatory deadlines approach.
Technology:
Drive mechanism selection hinges on gradient steepness, duty cycle intensity, and outdoor exposure risk.
- Hydraulic Systems:Fluid-powered drives deliver smooth acceleration for bariatric load ratings exceeding 160 kilograms. German manufacturers favor these for commercial installations requiring continuous-duty cycles.
- Mechanical Systems:Gear-based drives offer simplicity and field-serviceability for rural distribution networks. Cost-sensitive markets in the United States specify these for straight-rail residential applications.
- Belt Systems:Toothed belt drives operate quietly for indoor residential environments. Belt slippage risks limit deployment to gradients below 45 degrees and climate-controlled interiors.
- Rack and Pinion Systems:Positive engagement mechanisms eliminate slippage for steep outdoor stairs. Corrosion-resistant variants open residential exterior applications previously abandoned to platform alternatives.
Belt Systems carry the largest installed base. Rack and Pinion Systems are gaining share fastest in outdoor and steep-gradient specifications.
End User:
Purchasing authority varies from direct consumer decisions to institutional procurement committees with technical evaluation teams.
- Seniors:Adults aged 65+ represent the core demographic for residential installations. Reimbursement eligibility through Medicare Advantage and Japan's LTCI program determines affordability thresholds.
- Disabled Individuals:Users with mobility impairments from birth or acquired conditions drive demand for specialized seating configurations. Pediatric and bariatric anthropometric requirements command premium pricing tiers.
- Caregivers:Home health agencies and family members influence specification decisions for third-party installations. Predictive diagnostic sensors enable outcome-based service contracts shifting revenue to monitoring fees.
- Building Managers:Commercial and public facility operators prioritize code compliance and liability reduction over user comfort features. EU MDR post-market surveillance obligations extend their vendor auditing burdens.
Seniors account for the dominant share of end-user decisions. Disabled Individuals are expanding most quickly as pediatric and bariatric specialization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KfW development bank disburses home modification subsidies faster than Japan's municipal grant programs, yet both markets compress procurement cycles through reimbursement pathways that cover 70-90% of installation costs for qualifying seniors.
United States
Medicare Advantage plans harmonize reimbursement codes with national health systems, expanding end-user affordability thresholds for residential installations. The FDA classifies powered stair lifts as Class II medical devices under 510(k) premarket notification pathways. Installation networks concentrate in Florida, Arizona, and California where senior household density drives replacement cycle timing.
Germany
The KfW development bank channels aging-in-place subsidies toward rail fabrication and DC motor system replacements. EU Medical Device Regulation post-market surveillance obligations extend product development cycles for new entrants. Industrial clusters in North Rhine-Westphalia and Bavaria host captive supply chains for extruded aluminum rail stock.
Japan
METI enforces JIS standards for electromagnetic compatibility and structural load testing that determine export eligibility for foreign manufacturers. Japan's Long-Term Care Insurance program accelerates replacement cycles for aging DC drive units. Tokyo and Osaka metropolitan areas concentrate demand for acoustic stair lifts in thin-walled urban apartments.
United Kingdom
Stannah Lifts Holdings Ltd. anchors century-old brand equity in domestic installations across British residential markets. The EU MDR's clinical evaluation requirements reshape competitive positioning for powered mobility equipment. Installation networks cluster in Southeast England and the Midlands where pre-1940s residential stair geometries force custom rail fabrication.
Canada
Health Canada regulates powered stair lifts through medical device licensing pathways that align with FDA Class II frameworks. Provincial home modification programs in Ontario and British Columbia expand procurement for aging-in-place residential installations. Quebec's manufacturing base supplies rack and pinion drive systems for steep-gradient outdoor applications.
Global Stair Lifts Market Competitive Environment
Top-tier vendors anchor premium custom-curved rail fabrication, while commodity straight-rail specialists compete on distribution velocity and virtual site assessment tools. The vendor base stratifies across three archetypes: vertically integrated rail fabricators, brand-anchored domestic installers, and specialized seating configuration providers. Competitive moves concentrate on backward integration into extruded aluminum supply and predictive diagnostic sensor deployment for outcome-based service contracts.
Within the vertically integrated tier, Savaria Corporation and ThyssenKrupp AG represent archetypes of captive supply chain control. Stannah Lifts Holdings Ltd. exemplifies brand-anchored positioning in domestic installation markets. Handicare Group AB occupies a specialist position in pediatric and bariatric seating configurations that command premium service attach rates.
| Leading Market Players |
|---|
| Savaria Corporation |
| Stannah Lifts Holdings Ltd. |
| Acorn Stairlifts Inc. |
| Bruno Independent Living Aids Inc. |
| Handicare Group AB |
| Otolift Stairlifts Ltd. |
| Harmar Mobility LLC |
| ThyssenKrupp AG |
| TK Elevator GmbH |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up installation specialists anchor mid-market pricing discipline through captive service networks, while family-owned rail fabricators in Germany and Quebec defend margin control via backward integration into extruded aluminum supply. This ownership fragmentation creates divergent pricing power across straight-rail commodity tiers versus custom-curved premium configurations.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment margin from recurring maintenance revenue across residential procurement. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and customization intensity. Pricing pressure stems from direct-to-consumer digital channels fragmenting traditional dealer networks for straight-rail units. Home care agencies exhibit highest price sensitivity; healthcare facilities demonstrate lowest sensitivity due to mandated accessibility compliance deadlines.
Supply Chain Analysis
Extruded aluminum rail stock rests on captive supply chains in Germany, Quebec, and China's Yangtze River Delta industrial clusters. DC motor systems draw from Japanese and South Korean electromagnetic component suppliers; battery backup modules feed from Taiwan and mainland China cell manufacturers. Single-source vulnerability concentrates in specialized rack and pinion gear fabrication. Distribution runs through regional dealer networks for custom installations and direct-to-consumer platforms for standardized straight-rail units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: manufacturers can exploit cost differentials between North American installation labor rates and East Asian component sourcing while navigating divergent FDA and EU MDR certification timelines.
For Market Incumbents: Extend predictive diagnostic sensor deployment to capture recurring monitoring fee revenue and compress emergency response times. Deepen backward integration into extruded aluminum rail fabrication to offset commodity metal price volatility. Fortify supplier consolidation in Germany and Britain to reduce EU MDR compliance auditing burdens from post-market surveillance obligations.
For New Entrants and Emerging Players: Launch via direct-to-consumer digital channels with virtual site assessment tools for straight-rail commodity segments where brand equity barriers remain lowest. Target pediatric and bariatric seating configurations as the most penetrable white-space segment with distinct anthropometric requirements and premium service attach rates. Exploit Medicare Advantage reimbursement code harmonization as the primary go-to-market angle in United States residential markets.
For Investors and Strategic Acquirers: Home health agency consolidators represent the most active acquirer in this space as they seek captive installation networks for aging-in-place service bundles. The five-to-ten year viability window favors targets with established EU MDR certification pathways and predictive maintenance technology stacks. Watch rack and pinion outdoor system penetration rates as the signal indicating whether corrosion-resistant drive mechanisms can expand addressable market beyond traditional stair geometry constraints.
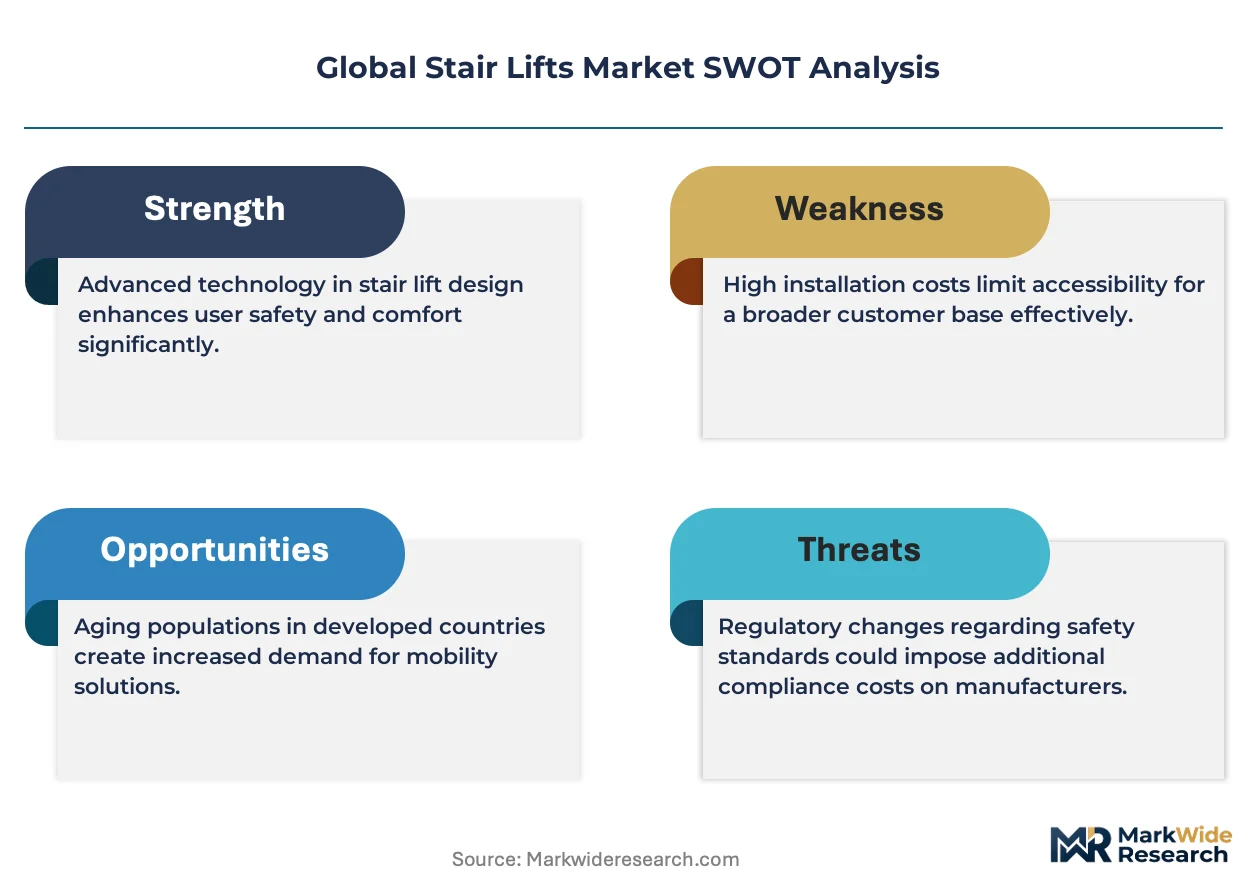
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Sensor Deployment | Enables outcome-based service contracts shifting revenue from equipment margin to recurring monitoring fees for home care agencies. |
| EU MDR Certification Investment | Extends product development cycles but creates defensive moats against unqualified competitors in German and British markets. |
| Direct-to-Consumer Channel Launch | Bypasses regional distributor margin capture through online configuration tools and virtual site assessment capabilities. |
| Pediatric-Bariatric Seating Specialization | Commands premium pricing tiers in underserved mobility segments with distinct anthropometric and service requirements. |
| Backward Integration into Rail Fabrication | Defends margin control against aluminum price volatility through captive supply of extruded rail stock in North America. |
Study Parameters
Coverage spans Germany, Japan, the United States, the United Kingdom, and Canada, with primary inputs from each market's regulatory and distribution landscape. The research combines structured interviews with stair lift installation network managers, biomedical engineers at healthcare facilities, GPO contracts managers, and home care agency procurement leads with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation documentation, METI JIS standards publications, and CMS Medicare Advantage reimbursement code databases. Bottom-up unit shipment modeling and top-down market value triangulation cross-validate projections across the analysis window.
Granularity-level modeling disaggregates volume and value outputs across product type, application, technology, and end user dimensions, with additional segmentation by reimbursement pathway eligibility and certification tier. CAGRs derive from fitted growth curves applied to replacement cycle timing and new installation penetration rates. Industry-specific forecast inputs include aging-in-place policy subsidy disbursement trajectories from Germany's KfW development bank and Japan's municipal grant programs, plus healthcare facility retrofit mandate deadlines under EU accessibility regulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum and steel commodity price volatility, EU MDR certification timeline extensions, and electromechanical technician scarcity constraints. Projections reflect documented assumptions regarding reimbursement code harmonization and aging demographics. Regulatory shifts in FDA classification pathways, METI electromagnetic compatibility standards revisions, and Medicare Advantage plan coverage expansions warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Windows Market
Home Products & Utilities
Mosquito Screen Doors Market