
 North America Aromatherapy Diffuser Market | 2026-2036
North America Aromatherapy Diffuser Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aromatherapy Diffuser Market Analytics
Bundle configurations pairing ultrasonic diffusers with proprietary essential oil starter sets is realigning how consumers enter the category. Young Living Essential Oils leverages its captive oil supply to anchor premium bundle economics. doTERRA competes through wellness advocate networks that sustain high-margin direct sales. InnoGear specializes in value-tier ultrasonic hardware, dominating Amazon's online retail channel.
An aromatherapy diffuser disperses essential oils into ambient air through ultrasonic vibration, heat evaporation, nebulization, or passive reed absorption, typically operating at frequencies between 1-2 MHz for ultrasonic variants to preserve volatile compound integrity. The device serves commercial wellness environments, residential spaces, and clinical settings seeking non-pharmaceutical stress reduction or odor management. Ultrasonic diffusers lead product type volumes due to low energy draw and water-based dilution safety, while nebulizing units command margin pools among clinical and luxury spa end users. Battery-powered technology shows structural momentum as portable formats penetrate travel and workplace segments.
The U.S. Consumer Product Safety Commission and Health Canada jointly shape electrical safety and essential oil labeling requirements, with California's Proposition 65 adding chemical disclosure obligations that increase compliance costs for oil-diffuser bundles. The U.S. FDA monitors therapeutic claims closely, constraining how brands market health outcomes. Stakeholders must track evolving state-level fragrance ingredient transparency laws and decide whether to front-run disclosure standards or absorb reactive reformulation costs.
Market Dynamics
The North America aromatherapy diffuser market is restructuring around battery-powered portable formats as hospitality chains and workplace wellness programs demand mobility without cord dependency, forcing hardware manufacturers to redesign power architectures and thermal management systems.
Growth Catalysts
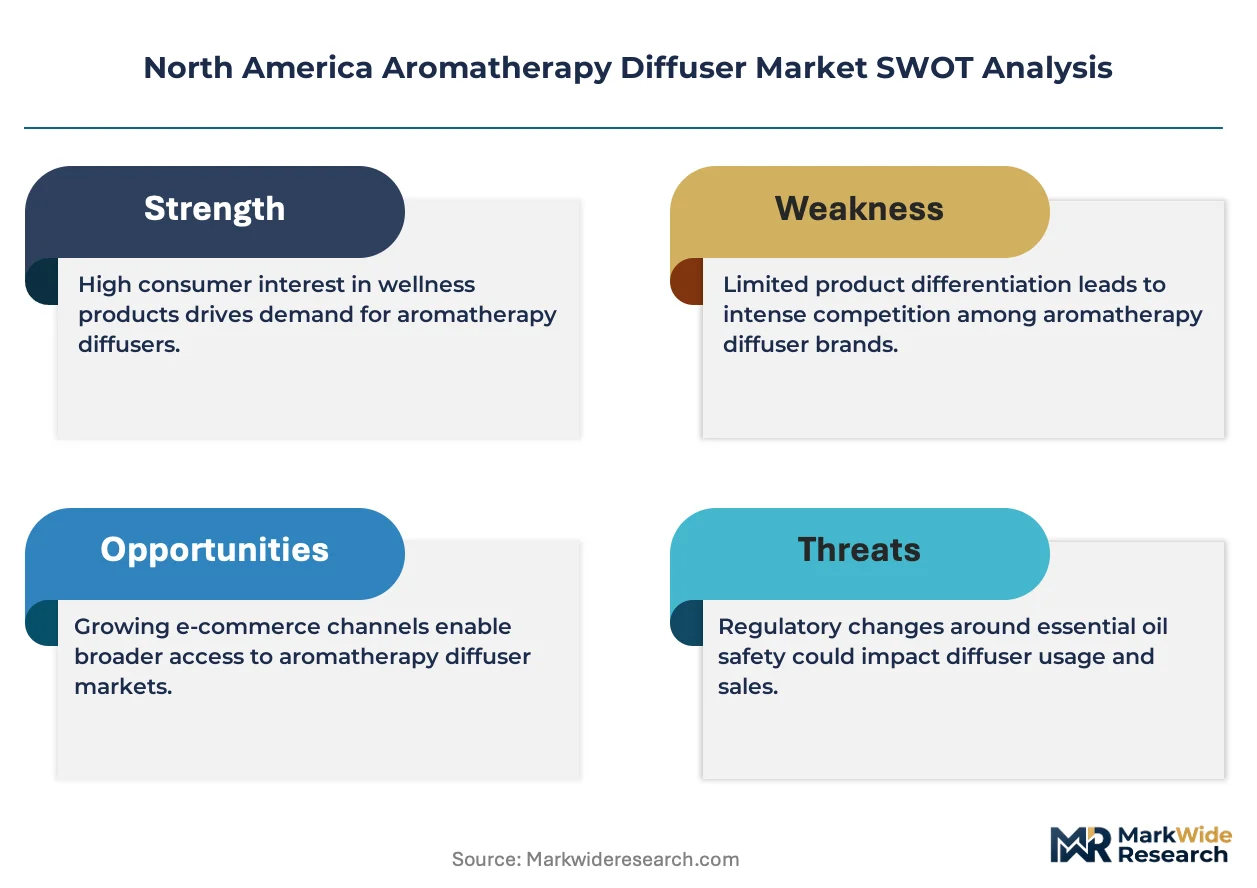
- California Proposition 65 compliance:Chemical disclosure mandates for essential oil bundles are accelerating transparency investments that premium brands convert into consumer trust premiums.
- Ultrasonic frequency optimization:1-2 MHz vibration engineering preserves volatile compound integrity, extending replacement cycles while validating therapeutic efficacy claims.
- Urban wellness retail density:California and New York cluster direct-to-consumer subscription models that compress hardware replacement intervals through bundled oil replenishment.
Market Restraints
- Electrical safety certification costs:U.S. Consumer Product Safety Commission low-voltage standards impose testing burdens that disproportionately burden smaller hardware importers.
- Essential oil supply concentration:Proprietary oil sourcing from limited cultivation regions creates input volatility for bundle-dependent manufacturers.
- Therapeutic claim constraints:FDA monitoring of health outcome marketing restricts differentiation strategies for clinical-positioned diffuser brands.
Strategic Opportunities
- Canadian hospitality expansion:Underserved resort and spa chains across British Columbia and Quebec present white space for certified commercial-grade deployments.
- Workplace wellness mandates:Corporate stress-reduction programs are adopting portable battery units for open-floor environments without HVAC integration.
- Health Canada electrical harmonization:Joint safety standard alignment with U.S. CPSC reduces dual-certification costs for cross-border product launches.
Industry Challenges
- Fragrance ingredient transparency skill gaps:Formulation chemists capable of Proposition 65-compliant oil profiling command scarcity premiums, constraining R&D velocity.
- Multi-jurisdiction labeling complexity:California chemical disclosure叠加 Health Canada bilingual requirements fragments packaging workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aromatherapy Diffuser Market |
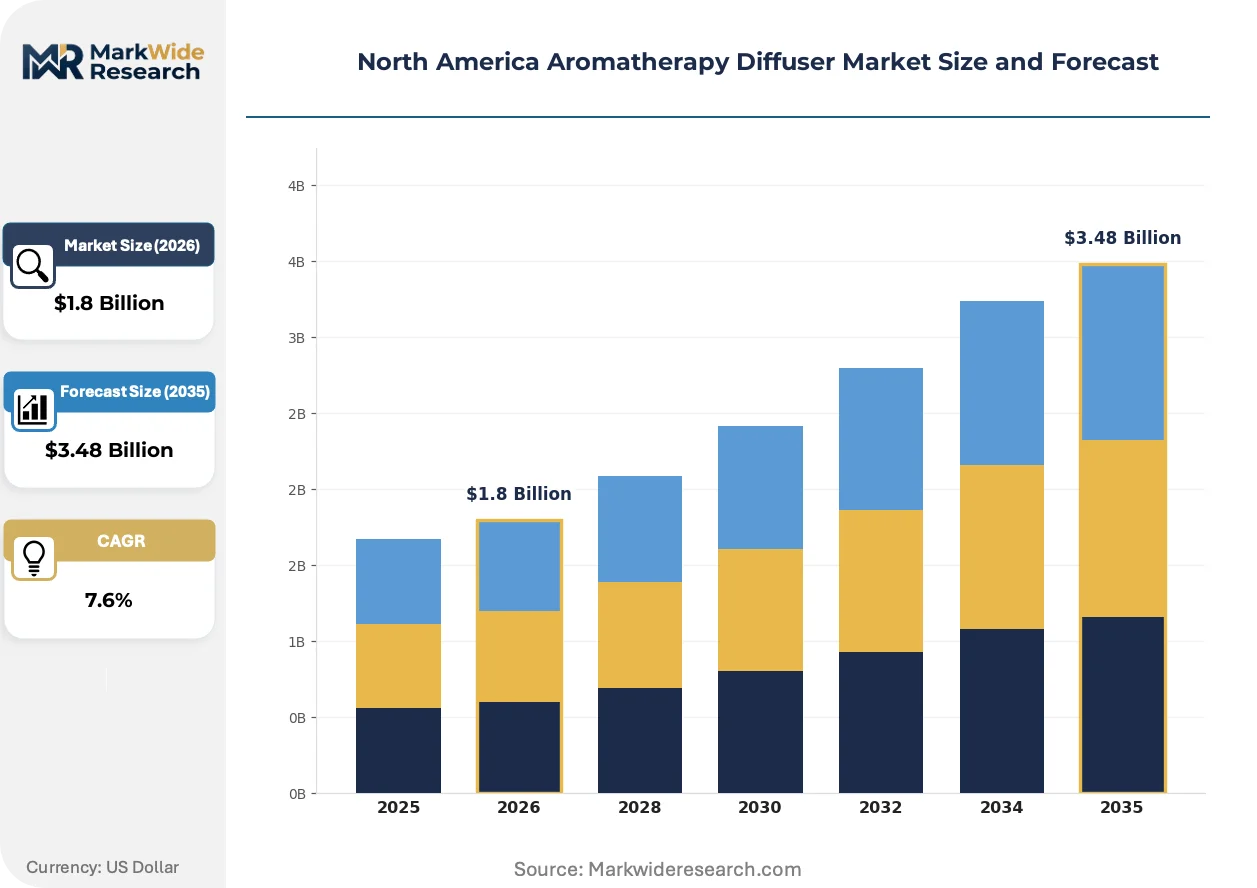
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Nebulizing, Heat Diffuser, Reed Diffuser End User: Residential, Commercial, Healthcare, Spa Technology: Electric, Solar, Battery-Powered, Manual Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Young Living Essential Oils, doTERRA, Newell Brands, S.C. Johnson & Son, NOW Foods, InnoGear, Edens Garden, Scentsy, Saje Natural Wellness, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aromatherapy Diffuser Market Evolving Landscape
Portable battery architectures are disrupting stationary diffuser dominance as mobility requirements penetrate commercial wellness contracts and residential travel segments simultaneously.
Ultrasonic vibration technology operates at 1-2 MHz frequencies to aerosolize water-diluted essential oils without thermal degradation. Hospitality procurement teams are specifying these units for guest room retrofits at accelerating pace. Nebulizing compression systems is overtaking heat-based evaporation in clinical and luxury spa environments where compound integrity commands price premiums.
The U.S. Consumer Product Safety Commission's updated electrical appliance safety standards are mandating certified low-voltage designs across all imported diffuser hardware. Manufacturers are absorbing third-party testing costs or exiting the market. California and New York retailers face the steepest compliance acceleration as state-level enforcement resources concentrate in high-volume import corridors.
Direct-to-consumer essential oil subscription models are compressing hardware replacement cycles by bundling ultrasonic units with proprietary starter sets. Wellness-focused hospitality chains are unbundling spa-grade nebulizing systems from amenity budgets and shifting to operational leases. This procurement restructuring is most visible in California's urban corridor, where property management platforms integrate diffuser maintenance into facility service contracts.
North America Aromatherapy Diffuser Market Segmentation
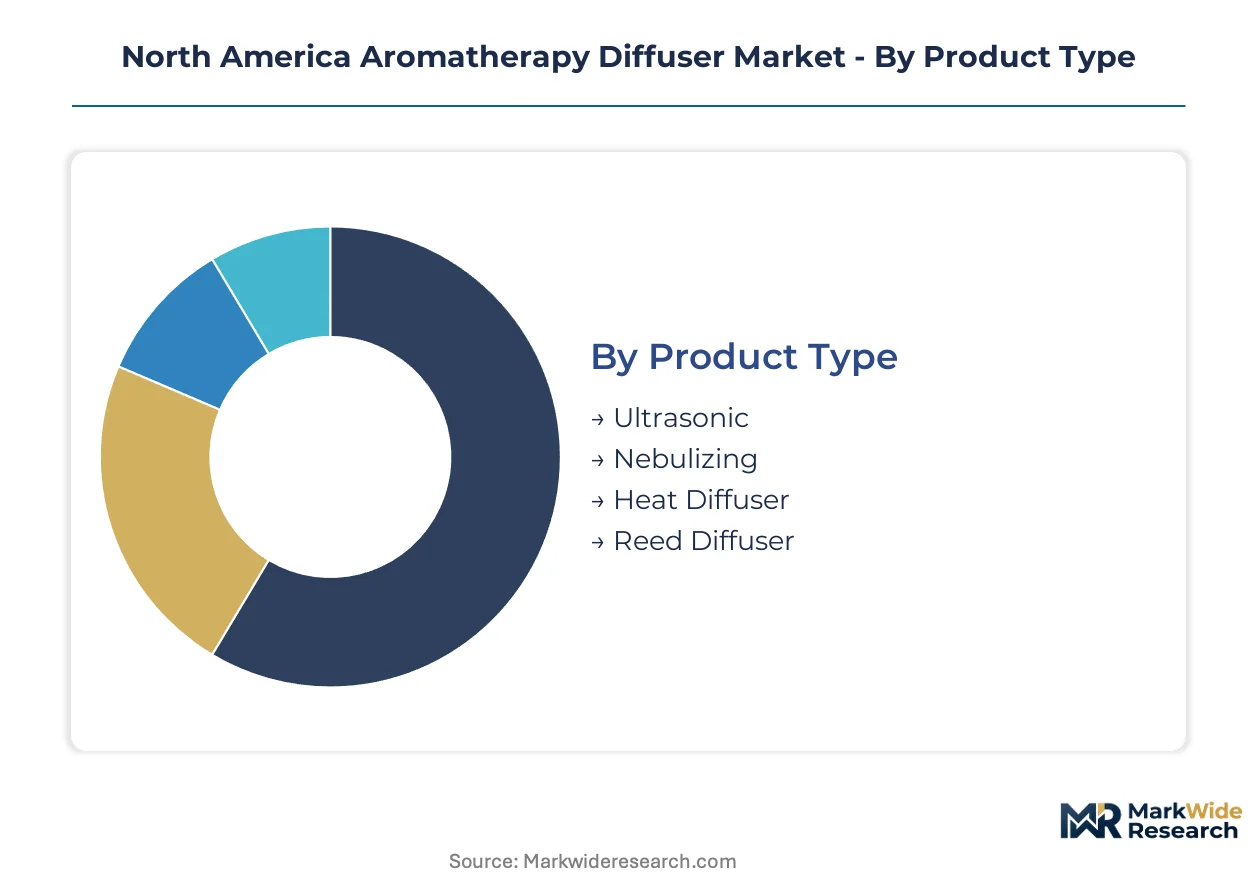
Segmentation in the North America aromatherapy diffuser market reveals how hardware specifications, end-use environments, and procurement channels create distinct margin pools and replacement cycle dynamics. Manufacturers configure product architectures around these boundaries to capture recurring revenue through oil-bundle economics or commercial service contracts.
Product Type:
Ultrasonic variants dominate unit volumes while nebulizing systems capture premium margin concentration in clinical and hospitality settings.
- Ultrasonic:These devices aerosolize water-diluted essential oils through 1-2 MHz piezoelectric vibration, preserving volatile compound integrity without thermal degradation. California and New York wellness retail clusters drive replacement cycles through bundled subscription models that embed hardware refresh into oil replenishment schedules.
- Nebulizing:Pure oil compression systems atomize undiluted extracts through pressurized air streams, commanding price premiums in luxury spa and clinical environments where therapeutic efficacy validation matters. Health Canada and U.S. CPSC electrical safety certifications impose testing burdens that filter out low-cost competitors from this tier.
- Heat Diffuser:Thermal evaporation units use low-wattage warming plates to accelerate oil volatilization, typically positioned at entry price points for residential trial purchases.
- Reed Diffuser:Passive capillary absorption through natural fiber reeds requires no electrical power, appealing to cord-averse hospitality designers and travel retail segments.
Today's leader: Ultrasonic. Tomorrow's challenger: Nebulizing.
End User:
Residential procurement concentrates in subscription-driven direct-to-consumer channels while commercial buyers prioritize service-integrated deployment models.
- Residential:Individual consumers purchase through Amazon and brand-direct websites, with California and New York urban clusters showing highest subscription attachment rates for oil-bundle hardware refresh programs.
- Commercial:Workplace wellness programs and hospitality chains specify battery-powered portable units for open-floor environments without HVAC integration, compressing procurement decisions into facility management contracts.
- Healthcare:Clinical settings demand nebulizing systems with compound integrity documentation, constrained by FDA monitoring of therapeutic marketing claims that limits brand differentiation strategies.
- Spa:Resort and wellness center procurement teams unbundle amenity budgets into operational leases, with British Columbia and Quebec resort chains presenting expansion white space for certified commercial-grade deployments.
Commercial applications are expanding most quickly as corporate stress-reduction mandates institutionalize diffuser deployment.
Technology:
Power architecture choices determine mobility profiles and safety certification pathways across the U.S. and Canadian regulatory environments.
- Electric:Corded AC-powered units dominate stationary installations in residential and hospitality settings, subject to U.S. CPSC low-voltage safety standards that push manufacturers toward certified designs.
- Solar:Photovoltaic-powered diffusers serve outdoor hospitality environments and eco-positioned wellness retreats, though limited energy storage constrains runtime in northern latitudes.
- Battery-Powered:Lithium-ion architectures enable cord-free mobility for workplace and travel segments, with thermal management redesigns absorbing R&D investment as hospitality chains mandate portable formats.
- Manual:Hand-operated nebulizers and reed systems eliminate electrical compliance entirely, appealing to import-constrained small retailers and off-grid applications.
Battery-powered formats are gaining share fastest as mobility requirements penetrate commercial contracts simultaneously with residential travel segments.
Distribution Channel:
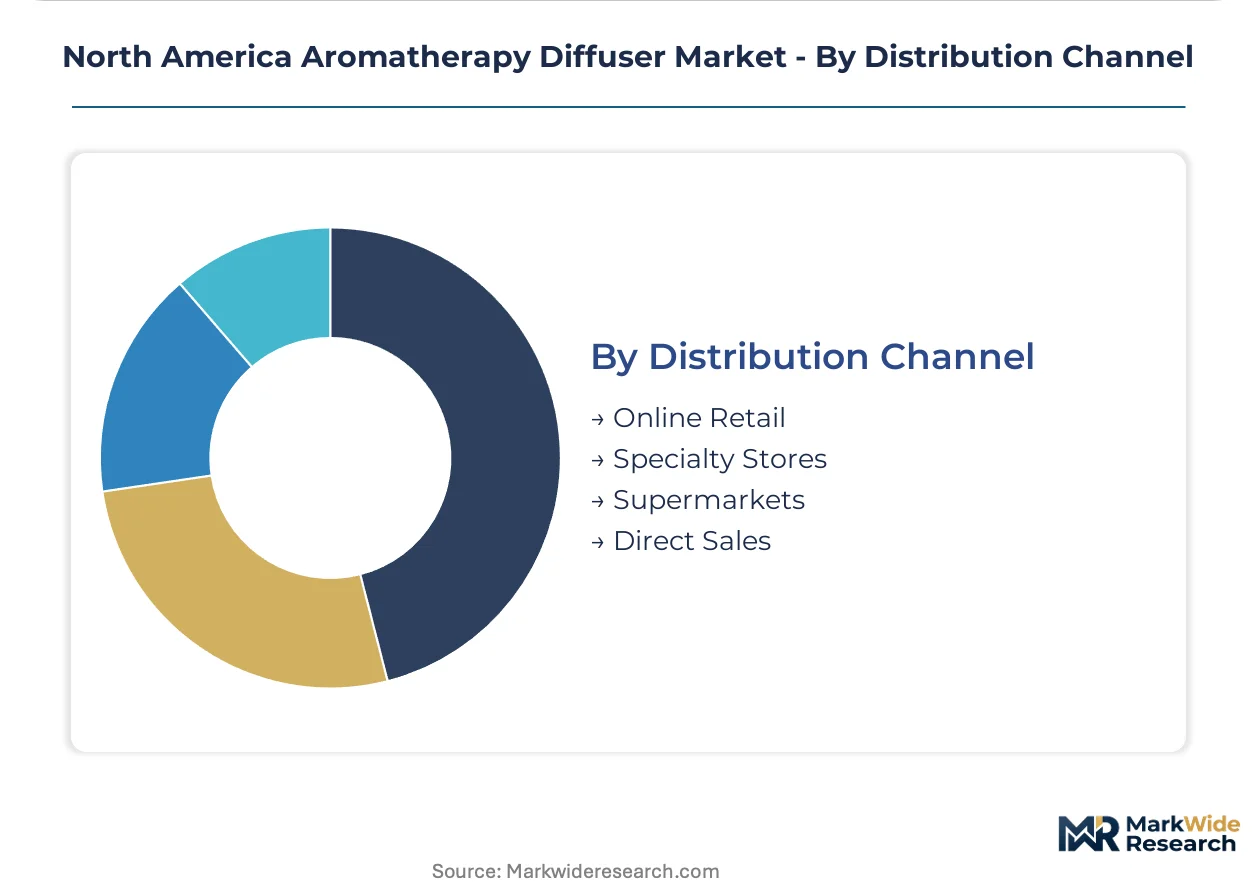
Channel selection determines margin capture versus volume scale, with direct models enabling proprietary oil-bundle economics.
- Online Retail:Amazon and brand-direct websites dominate residential volume, with InnoGear-style value-tier specialists capturing search-driven purchases through algorithmic visibility.
- Specialty Stores:Urban wellness retail clusters in California and New York enable tactile evaluation and subscription enrollment, supporting premium bundle pricing through consultative sales.
- Supermarkets:Mass-market placement drives impulse trial purchases of entry-tier heat and ultrasonic units, though oil-bundle attachment rates lag specialty retail.
- Direct Sales:Wellness advocate networks sustain high-margin personal selling, with doTERRA-style multi-level structures embedding hardware into oil loyalty programs.
Direct sales commands margin concentration. Online retail drives volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aromatherapy diffuser industry traces its commercial scaling to the United States, where direct-to-consumer wellness networks and hospitality procurement standards established category infrastructure before Canadian and Mexican markets developed parallel demand channels.
United States
California and New York urban wellness retail clusters drive replacement cycles through bundled oil subscription models that embed hardware refresh into replenishment schedules. The U.S. Consumer Product Safety Commission's low-voltage electrical safety standards filter uncertified imports from major distribution corridors. Los Angeles and Manhattan property management platforms now integrate diffuser maintenance into facility service contracts.
Canada
British Columbia and Quebec resort chains present expansion white space for certified commercial-grade deployments as hospitality procurement teams unbundle amenity budgets into operational leases. Health Canada's electrical safety harmonization with U.S. CPSC standards reduces dual-certification costs for cross-border product launches. Toronto and Vancouver workplace wellness programs are adopting portable battery units for open-floor environments.
Mexico
Mexico City Metro hospitality operators are initiating diffuser pilot programs following U.S. wellness hotel chain expansions into the capital region. The country's national consumer protection regulator monitors electrical appliance imports for safety compliance alongside customs documentation requirements. Guadalajara manufacturing clusters are developing assembly capacity for value-tier ultrasonic hardware destined for North American retail channels.
North America Aromatherapy Diffuser Market Competitive Landscape
Premium-margin players sit above commodity-margin players across bundle economics and direct sales channel control, with the vendor base fragmenting across hardware specialists, oil-integrated wellness networks, and mass-market consumer goods conglomerates. Three strategic archetypes dominate: captive oil supply bundlers, value-tier Amazon-native hardware brands, and multi-level wellness advocate networks. Competitive moves concentrate on strategic partnerships between oil suppliers and hospitality chains, plus portfolio diversification into battery-powered portable formats.
Within the captive supply archetype, Young Living Essential Oils and doTERRA exemplify premium-margin positioning through proprietary oil sourcing that anchors bundle economics. InnoGear occupies a position at the value-tier end, representing Amazon-native hardware specialists that capture search-driven volume through algorithmic visibility rather than oil-integrated recurring revenue models.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| doTERRA |
| Newell Brands |
| S.C. Johnson & Son |
| NOW Foods |
| InnoGear |
| Edens Garden |
| Scentsy |
| Saje Natural Wellness |
| Others |
Value Network & Pricing Analysis
Hospitality procurement teams in California and New York anchor pricing power through volume-scale contracts that compress supplier margins while rewarding certified low-voltage designs with preferred-vendor status. Bundle economics tie hardware refresh cycles to proprietary oil replenishment schedules, creating recurring revenue lock-in that shields premium tiers from commoditization pressures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and oil-bundle integration depth. Premium tiers command margin concentration through Health Canada and U.S. CPSC electrical safety validations, while value-tier ultrasonic units face cost compression from Amazon-native competitors. California Proposition 65 compliance investments filter out low-cost importers, tightening supply at the economy tier where price sensitivity concentrates among residential trial purchasers.
Supply Chain Analysis
Trans-Pacific freight costs from Shenzhen and Dongguan manufacturing clusters absorb margin at entry price points, forcing value-tier specialists toward sea-air hybrid routing. Piezoelectric transducers and lithium-ion battery cells draw from South Korean and Japanese component suppliers, creating single-source vulnerability for portable format manufacturers. Distribution runs through Los Angeles and Vancouver port corridors into Amazon fulfillment centers and specialty retail clusters, with Canadian customs harmonization reducing cross-border friction for certified hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on battery-powered portable formats displacing stationary units in commercial contracts, while Proposition 65 compliance costs filter out low-cost competitors and concentrate pricing power among certified incumbents.
For Market Incumbents: Hedge against commodity-tier erosion by deepening captive supply of essential oil formulations and securing Health Canada electrical certifications ahead of cross-border hospitality expansion. Battery thermal management R&D represents the critical capability gap as workplace wellness mandates institutionalize portable procurement specifications. For New Entrants and Emerging Players: Health Canada electrical harmonization with U.S. CPSC standards opens a window for British Columbia and Quebec resort chains seeking certified commercial-grade deployments without dual-certification burden. Target spa-grade nebulizing systems for operational lease procurement restructuring, leveraging formulation chemist scarcity to anchor premium service contracts. For Investors and Strategic Acquirers: Wellness-focused hospitality chains are the most active acquirer in this space, unbundling amenity budgets into facility management platforms that integrate diffuser maintenance. Acquisition targets with proprietary oil sourcing and battery-powered R&D pipelines offer the strongest long-term viability as mobility requirements penetrate commercial contracts. Watch for FDA therapeutic claim enforcement actions as an inflection signal that would compress clinical-positioned brand differentiation strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Architecture Redesign | Thermal management investments enable cord-free workplace deployments under California electrical safety standards. |
| Proprietary Oil Bundle Integration | Starter set anchoring extends replacement cycles through subscription-driven hardware refresh programs in New York retail clusters. |
| Health Canada Certification Pre-Positioning | Dual-standard alignment reduces launch costs for British Columbia and Quebec hospitality expansion. |
| Direct-to-Consumer Channel Migration | Algorithmic visibility on Amazon displaces specialty retail for value-tier ultrasonic volume capture. |
| Operational Lease Restructuring | Facility service contract integration shifts spa procurement from capital expenditure to recurring operational budgets. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market's regulatory and commercial stakeholders. Interviews with hospitality procurement directors, wellness retail category managers, essential oil formulation chemists, and electrical safety compliance officers combined with secondary validation from U.S. CPSC enforcement databases, Health Canada product safety listings, California Proposition 65 chemical disclosure filings, and Amazon retail analytics. Bottom-up channel volume estimates triangulated against top-down market sizing from customs import records and hospitality capital expenditure disclosures.
Granularity extends to product type, end user, technology, and distribution channel dimensions, with additional modeling of certification tier and oil-bundle attachment rates. CAGRs derived from regression analysis of historical replacement cycles and subscription penetration curves, incorporating ultrasonic frequency optimization R&D timelines and battery energy density improvement trajectories across the projection horizon.
Revisions become necessary when FDA therapeutic claim enforcement intensifies, Health Canada electrical standards diverge from U.S. CPSC harmonization, or essential oil supply disruptions from concentrated cultivation regions materialize. Forecasts reflect documented assumptions about subscription model retention rates and hospitality procurement contract durations. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Windows Market
Home Products & Utilities
Mosquito Screen Doors Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Netherlands Sustainable Mattress Market