
 Europe Aromatherapy Diffuser Market | 2026-2036
Europe Aromatherapy Diffuser Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aromatherapy Diffuser Market Foresight
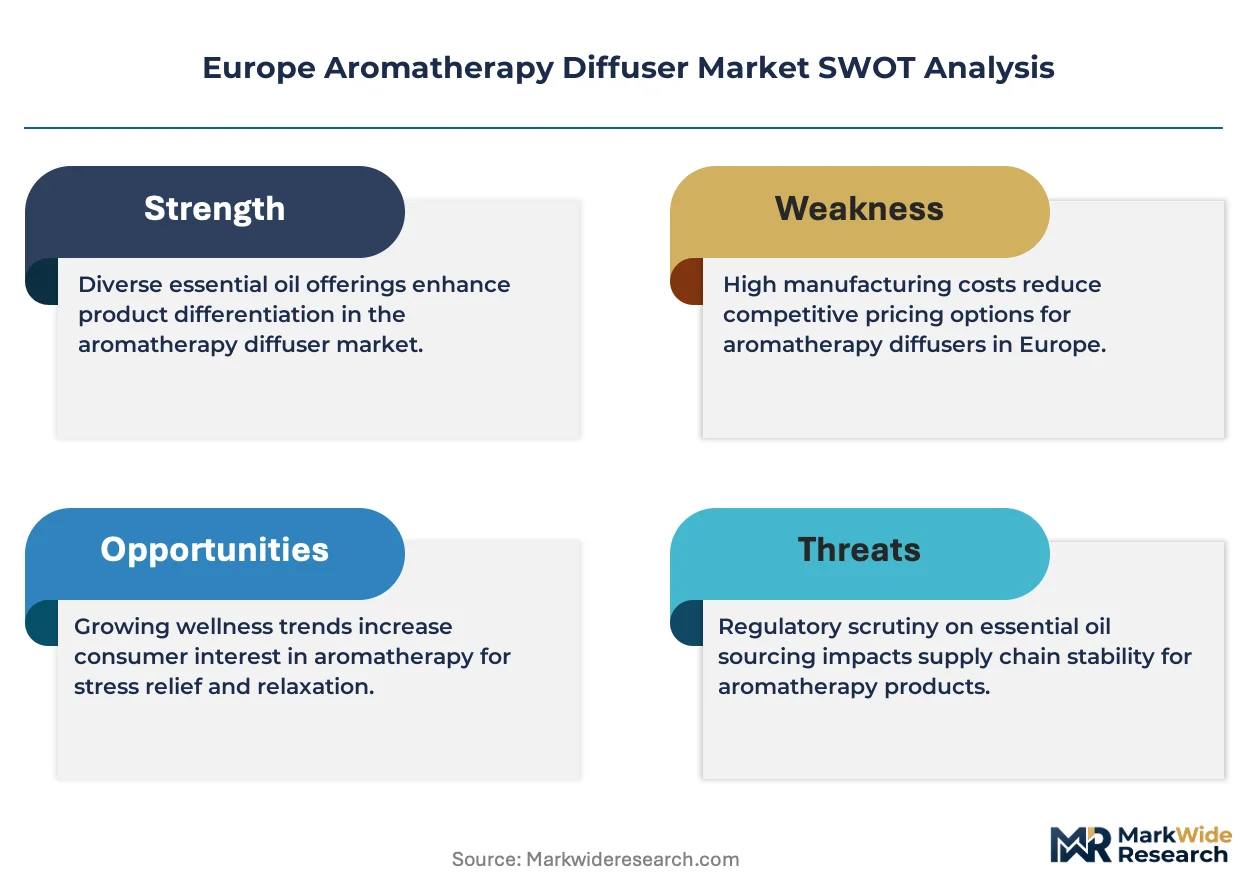
CE marking under the EU Medical Devices Regulation is bifurcating the competitive landscape into clinical-grade and wellness-grade suppliers. Stadler Form Aktiengesellschaft leverages Swiss engineering heritage to dominate premium ultrasonic designs across German-speaking markets. doTERRA International sustains its position through captive sourcing of therapeutic-grade oils paired with proprietary diffuser hardware. Muji Europe Holdings anchors volume in minimalist evaporative units sold through controlled retail footprints.
An aromatherapy diffuser disperses essential oils into ambient air through ultrasonic vibration, nebulizing pressure, controlled heat, or passive evaporation, typically operating at frequencies between 1.6 and 2.4 MHz to preserve volatile compound integrity without thermal degradation. Ultrasonic units command the broadest installed base due to silent operation and humidification dual-function, while nebulizing systems capture the highest margin pool in clinical and luxury spa applications. Distribution through specialty stores retains outsized influence in European purchasing decisions, though online retail channels are displacing wholesale for mid-tier individual buyers.
REACH compliance through ECHA governs chemical safety in essential oil formulations, while the EU F-Gas Regulation constrains refrigerant-based cooling in nebulizing systems and the CSRD mandates supply-chain disclosure for sustainability claims. These frameworks elevate compliance costs for entrants but protect incumbent positions for companies with established testing protocols. Stakeholders must monitor evolving MDR classification thresholds that could reclassify therapeutic claim diffusers as regulated medical devices.
Market Dynamics
The EU Medical Devices Regulation is bifurcating the competitive landscape into clinical-grade and wellness-grade suppliers, forcing manufacturers to choose between CE-marked therapeutic positioning and lifestyle marketing.
Growth Catalysts
- EU Green Deal synthetic fragrance restrictions:Wellness centers across Germany and France are expanding aromatherapy programs as emissions limits tighten. This redirects institutional procurement toward essential oil-based systems.
- Lavender cultivation clusters:Provence-Alpes-Côte d'Azur concentration supports local diffuser manufacturing and captive essential oil sourcing, reducing import dependency for French producers.
- Ultrasonic humidification dual-function:Silent operation and ambient moisture delivery expand residential adoption beyond pure aromatherapy use cases.
Market Restraints
- REACH compliance costs:ECHA chemical safety testing elevates barriers for essential oil formulation entrants, protecting incumbents with established protocols.
- F-Gas Regulation constraints:Refrigerant-based cooling in nebulizing systems faces phase-down schedules, compressing margins for clinical-grade hardware suppliers.
- Glass reservoir fragility:Nebulizing systems require precision-machined glass components with concentrated European supplier bases, creating single-source vulnerability.
Strategic Opportunities
- CSRD supply-chain disclosure mandates:Sustainability reporting requirements favor brands with transparent sourcing narratives and captive lavender cultivation relationships.
- Clinical wellness convergence:Spa chains in Austria and Switzerland are integrating diffusers into preventive health protocols, opening reimbursement-adjacent revenue streams.
- Smart home integration:Voice-controlled diffuser systems paired with air quality sensors capture premium positioning in connected home ecosystems.
Industry Challenges
- MDR classification uncertainty:Therapeutic claim thresholds remain ambiguous, forcing manufacturers to maintain dual compliance pathways pending regulatory clarification.
- Volatile compound preservation expertise:Ultrasonic frequency calibration requires specialized formulation chemistry talent scarce outside Grasse and Swiss fragrance clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aromatherapy Diffuser Market |
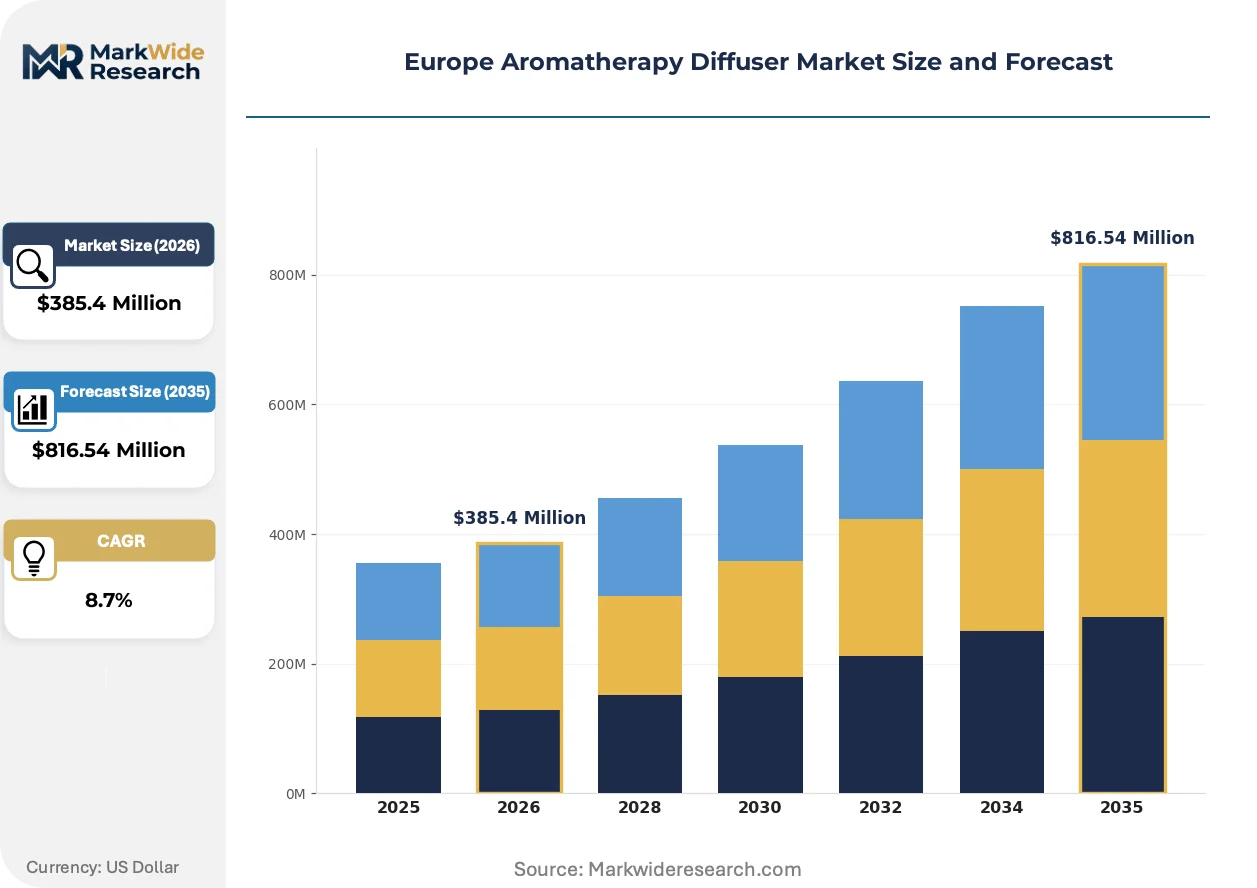
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic, Nebulizing, Heat, Evaporative Application: Home, Spa, Clinics, Wellness Centers End User: Individuals, Businesses, Healthcare Providers, Corporations Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Young Living Essential Oils, Stadler Form Aktiengesellschaft, Procter & Gamble, Edens Garden, Muji Europe Holdings, Reckitt Benckiser, doTERRA International, Diptyque, S. C. Johnson & Son, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aromatherapy Diffuser Market Shifts & Advancements
Product architecture is fragmenting around three distinct vectors: hardware miniaturization for portability, sensor integration for automated dosing, and materials substitution to reduce glass dependency. Each vector carries diverging margin and certification implications.
Ceramic atomization plates are decomposing the traditional ultrasonic transducer supply chain. Swiss and German sensor manufacturers are adopting piezoelectric ceramic substrates for nebulizing precision at lower wattage. This convergence is compressing the addressable market for legacy piezoelectric disk suppliers while enabling battery-powered portable designs previously constrained by power draw.
CSRD sustainability disclosure requirements are forcing ingredient traceability investments across the value chain. Manufacturers must document essential oil provenance from cultivation through formulation. French and Italian suppliers with vertically controlled lavender estates capture first-mover advantage in audit-ready supply architectures.
Specialty retail influence persists despite channel displacement toward direct-to-consumer platforms. German and Austrian consumers still validate purchase decisions through in-store scent testing, sustaining flagship footprint requirements even as transaction volume shifts online. This hybrid pattern elevates experiential retail costs without eliminating physical presence obligations.
Europe Aromatherapy Diffuser Market Segmentation
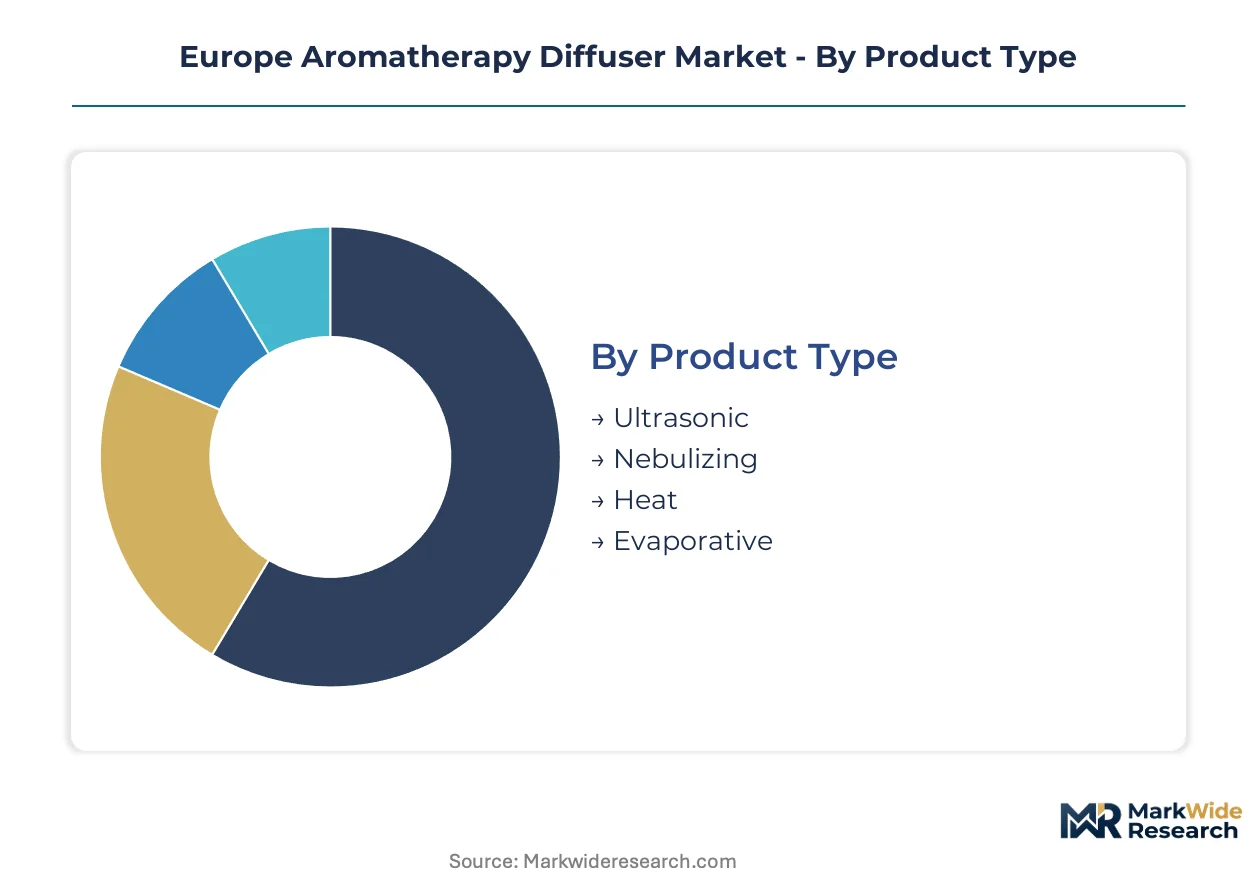
CE marking requirements under EU MDR create divergent compliance pathways across product categories, while REACH obligations fragment essential oil sourcing by provenance traceability. Channel configuration in Germany and France reflects persistent experiential retail preferences alongside accelerating digital procurement.
Product Type:
MDR classification thresholds split hardware categories into wellness-grade and clinical-grade compliance tiers, with ultrasonic and nebulizing technologies occupying opposite ends of this regulatory spectrum.
- Ultrasonic:Ceramic piezoelectric plates vibrate at 1.6–2.4 MHz to atomize water-oil suspensions without thermal degradation. Silent operation and humidification dual-function concentrate residential demand in German-speaking markets, where Stadler Form dominates premium positioning through Swiss engineering heritage.
- Nebulizing:Pressurized air streams through precision-machined glass reservoirs to disperse pure essential oils without dilution. Clinical and luxury spa applications in Austria and Switzerland capture the highest margin pool, though F-Gas Regulation constraints on refrigerant-based cooling compress hardware economics.
- Heat:Controlled thermal plates accelerate volatile compound release through gentle warming. Compact designs serve price-sensitive individual buyers, though thermal degradation limits therapeutic positioning.
- Evaporative:Passive airflow through absorbent pads or reeds enables silent, unpowered operation. Muji Europe anchors volume in minimalist designs through controlled retail footprints across French and Benelux markets.
Established volume favors Ultrasonic; emerging adoption favors Nebulizing.
Application:
Institutional procurement patterns diverge sharply between reimbursement-adjacent clinical settings and discretionary wellness spending, with EU Green Deal emissions restrictions redirecting facility budgets toward essential oil systems.
- Home:Residential units prioritize silent operation, aesthetic integration, and smart home connectivity. Voice-controlled systems paired with air quality sensors capture premium positioning in connected home ecosystems across Nordic markets.
- Spa:Preventive health protocol integration in Austrian and Swiss spa chains opens reimbursement-adjacent revenue streams. CSRD disclosure mandates favor suppliers with transparent lavender provenance from Provence-Alpes-Côte d'Azur cultivation clusters.
- Clinics:CE-marked therapeutic positioning requires MDR compliance, elevating barriers for wellness-grade suppliers. Glass reservoir fragility creates single-source vulnerability in precision-machined component supply.
- Wellness Centers:Corporate and municipal facilities across Germany and France expand aromatherapy programs as synthetic fragrance emissions limits tighten. Institutional procurement favors ultrasonic humidification dual-function for ambient moisture delivery.
Volume concentrates in Home; steepest expansion trajectory sits with Wellness Centers.
End User:
Procurement authority separates direct individual purchasers from centralized facility buyers, with healthcare providers facing distinct MDR classification scrutiny on therapeutic claims.
- Individuals:Direct consumers validate purchase decisions through in-store scent testing at specialty retailers, sustaining flagship footprint requirements even as transaction volume shifts online.
- Businesses:Hospitality and corporate wellness programs prioritize bulk procurement with standardized scent branding across property portfolios.
- Healthcare Providers:Clinical positioning demands CE marking and formulation chemistry expertise scarce outside Grasse and Swiss fragrance clusters.
- Corporations:Enterprise facilities integrate diffusers into employee wellness amenities, with CSRD supply-chain disclosure requirements favoring brands with audit-ready sourcing narratives.
Transaction frequency favors Individuals; contract value expansion favors Corporations.
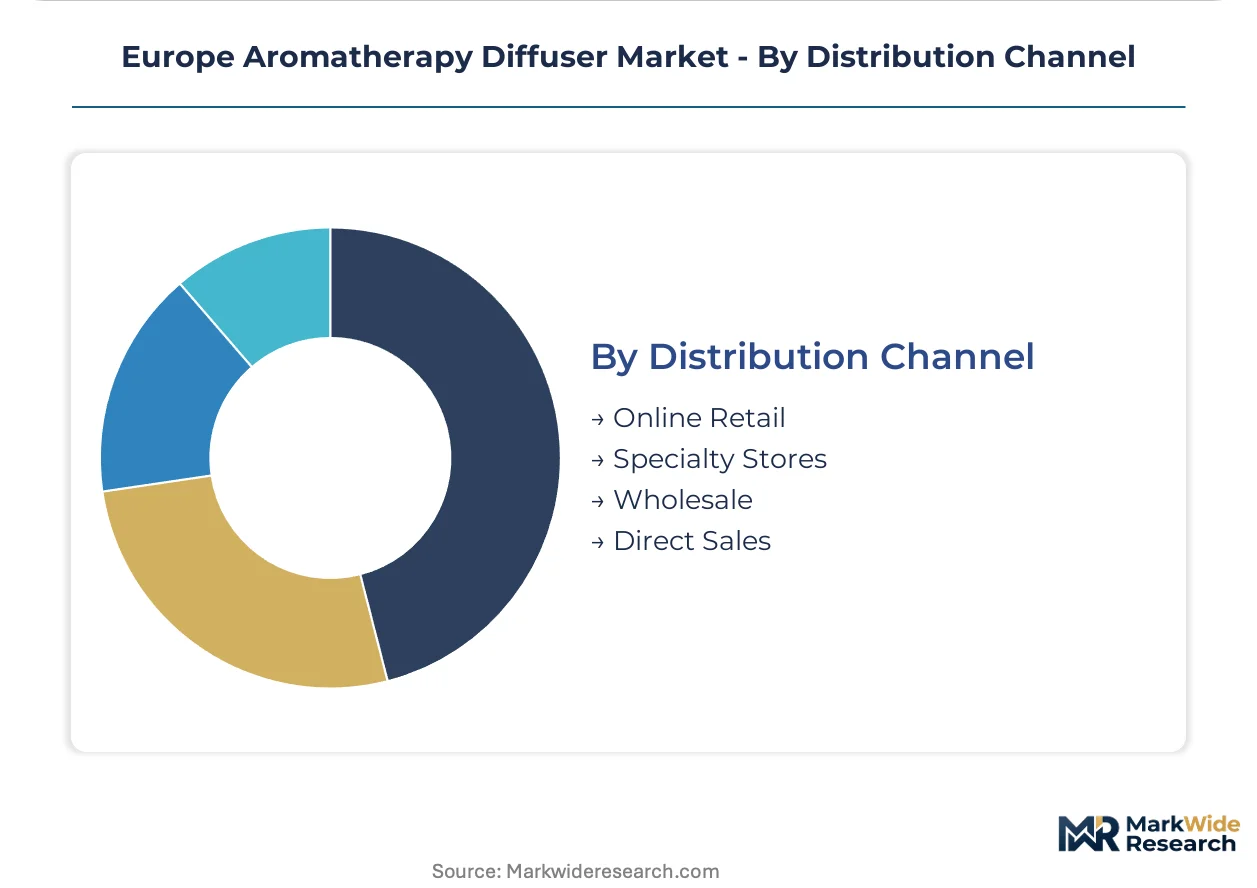
Distribution Channel:
Customer acquisition economics bifurcate between high-touch experiential validation and low-touch digital convenience, with hybrid patterns elevating cost structures without eliminating physical presence obligations.
- Online Retail:Direct-to-consumer platforms displace wholesale for mid-tier individual buyers, though German and Austrian consumers still require in-store scent confirmation before digital repurchase.
- Specialty Stores:Controlled retail footprints enable formulation chemistry consultation and brand narrative immersion, sustaining outsized influence in European purchasing decisions.
- Wholesale:Institutional procurement through distributor networks retains relevance for clinic and wellness center bulk orders with service-level requirements.
- Direct Sales:doTERRA International leverages captive therapeutic-grade oil sourcing paired with proprietary hardware through consultant networks.
Channel margin favors Specialty Stores; volume scaling favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal synthetic fragrance restrictions are redirecting institutional procurement budgets toward essential oil-based systems across wellness centers and corporate facilities. REACH compliance through ECHA elevates barriers for new entrants while protecting established testing protocols. The analysis examines five countries where regulatory alignment and industrial clustering concentrate market activity.
Germany
Wellness centers in Bavaria and North Rhine-Westphalia are expanding aromatherapy programs as emissions limits tighten under the EU Green Deal. CE marking requirements under MDR bifurcate procurement between clinical-grade and wellness-grade suppliers. Stuttgart engineering clusters support precision ultrasonic transducer manufacturing for premium residential units.
France
Provence-Alpes-Côte d'Azur lavender cultivation clusters enable captive essential oil sourcing and local diffuser assembly. ANSM oversight of therapeutic claims intersects with CSRD supply-chain disclosure mandates for sustainability reporting. Grasse fragrance chemistry expertise provides scarce formulation talent for volatile compound preservation.
Switzerland
Swissmedic classification thresholds shape therapeutic positioning for spa chains integrating diffusers into preventive health protocols. Zürich and Geneva sensor manufacturers adopt piezoelectric ceramic substrates for nebulizing precision. Alpine wellness tourism drives institutional procurement with reimbursement-adjacent revenue expectations.
United Kingdom
Post-Brexit regulatory divergence creates dual compliance pathways for suppliers serving both UK and EU markets. London specialty retail footprints sustain experiential validation requirements despite accelerating online transaction volume. Midlands distribution hubs handle cross-channel logistics for essential oil formulations.
Italy
Tuscany and Piedmont essential oil cooperatives supply regional diffuser manufacturers with traceable provenance for CSRD disclosure. Lombardy design studios drive aesthetic differentiation in ceramic and glass reservoir components. Italian spa chains in South Tyrol mirror Austrian preventive health integration patterns.
Europe Aromatherapy Diffuser Market Competitive Landscape
Player mix skews toward diversified consumer goods conglomerates with fragrance portfolios alongside specialized wellness hardware fabricators. Mid-tier specialists concentrate in Swiss and German engineering clusters with ceramic transducer capabilities. Two strategic archetypes dominate: vertically integrated essential oil suppliers with proprietary hardware, and design-forward appliance specialists leveraging regional engineering heritage. Competitive moves center on M&A for captive lavender cultivation assets and strategic partnerships for smart home ecosystem integration.
Within the diversified conglomerate tier, Procter & Gamble and Reckitt Benckiser represent scale-driven entrants with existing home fragrance infrastructure and retail distribution leverage. Among specialized fabricators, Stadler Form Aktiengesellschaft exemplifies Swiss engineering heritage positioning in premium ultrasonic designs, while doTERRA International occupies a position as a vertically integrated essential oil supplier with proprietary diffuser hardware. Muji Europe Holdings anchors the minimalist design archetype through controlled retail footprints.
| Leading Market Players |
|---|
| Young Living Essential Oils |
| Stadler Form Aktiengesellschaft |
| Procter & Gamble |
| Edens Garden |
| Muji Europe Holdings |
| Reckitt Benckiser |
| doTERRA International |
| Diptyque |
| S. C. Johnson & Son |
| Others |
Supply & Pricing Matrix
Ceramic piezoelectric plates replacing legacy ultrasonic transducers are redrawing manufacturing geography toward Swiss and German engineering clusters while compressing margins for established disk suppliers. This substitution simultaneously elevates precision requirements and fragments component sourcing across ceramic substrate specialists and traditional glass reservoir fabricators.
Pricing Analysis
Certification level under EU MDR creates the primary spread between clinical-grade and wellness-grade hardware tiers. Three-tier pricing structure across premium ultrasonic, mid-range evaporative, and economy heat-based units reflects compliance investment differentials. Pricing pressure stems from REACH testing cost absorption in essential oil formulations. Individual residential buyers exhibit highest price sensitivity, while Austrian and Swiss spa chains prioritize therapeutic positioning over unit economics.
Supply Chain Analysis
Inventory lead times for precision-machined glass nebulizing reservoirs stretch due to concentrated European supplier bases in Bavaria and Lombardy. Manufacturing gravity centers on Germany, France, and Switzerland, with ceramic atomization plates drawing from Zürich sensor manufacturers. Single-source vulnerability pervades clinical-grade glass component sourcing. Distribution runs through hybrid specialty retail footprints paired with direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Aromatherapy Diffuser Market sits in early-cycle expansion as EU Green Deal synthetic fragrance restrictions redirect institutional procurement budgets toward essential oil systems.
For Market Incumbents: Compound defensive positioning through captive lavender cultivation acquisitions in Provence-Alpes-Côte d'Azur and CE marking investment ahead of MDR classification threshold revisions. Ceramic transducer substitution threatens legacy piezoelectric disk suppliers with margin compression. Vertical integration into essential oil formulation chemistry scarce outside Grasse protects therapeutic-grade positioning. For New Entrants and Emerging Players: Lead with smart home ecosystem integration partnerships targeting Nordic residential markets where voice-controlled air quality sensor pairing commands premium positioning. Corporate wellness programs in German-speaking markets offer the most penetrable white-space for bulk procurement contracts. Direct-to-consumer digital channels with subscription oil replenishment models bypass specialty retail footprint requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wellness hardware fabricators in Swiss and German engineering clusters lacking essential oil vertical integration. Long-term viability hinges on CSRD-compliant supply-chain disclosure capabilities and MDR therapeutic claim licensing. Watch for ANSM clarification on medical device classification thresholds as inflection signal for clinical-grade valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Lavender Cultivation Acquisition | Secures CSRD-audit-ready provenance for French and Italian essential oil sourcing. |
| CE Marking Pathway Investment | Pre-positions hardware portfolios for potential MDR therapeutic reclassification. |
| Smart Home Ecosystem Partnership | Enables voice-controlled premium positioning in Nordic connected home markets. |
| Ceramic Transducer Manufacturing Scale-Up | Captures cost advantages from piezoelectric substrate substitution in ultrasonic designs. |
| Specialty Retail Footprint Optimization | Sustains experiential validation requirements as transaction volume shifts online. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA registration databases, EU MDR guidance documents, and customs trade records for essential oil formulations. Interviews with wellness center procurement directors, Grasse-based formulation chemists, ceramic transducer engineers, and specialty retail category buyers inform demand-side validation. Bottom-up unit shipment modeling triangulates against top-down essential oil consumption estimates.
Segmentation dimensions span product architecture, application setting, end-user procurement authority, and distribution channel configuration across the analysis window. CAGRs derive from regression against historical ultrasonic and nebulizing adoption curves, adjusted for EU Green Deal regulatory tailwinds. Forecast inputs incorporate lavender cultivation yield variability and F-Gas Regulation phase-down schedules for refrigerant-based cooling systems.
Underlying assumptions cover sustained EU Green Deal enforcement, stable REACH compliance cost structures, and continued MDR classification ambiguity, with deviation risk concentrated in therapeutic claim regulatory reinterpretation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
Mosquito Screen Doors Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
Windows Market
Home Products & Utilities
Netherlands Sustainable Mattress Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Storage Basket Rack Market