
 Windows Market | 2026-2036
Windows Market Size, Share, and Industry Trends Forecast 2026-2036
Windows Market Intelligence
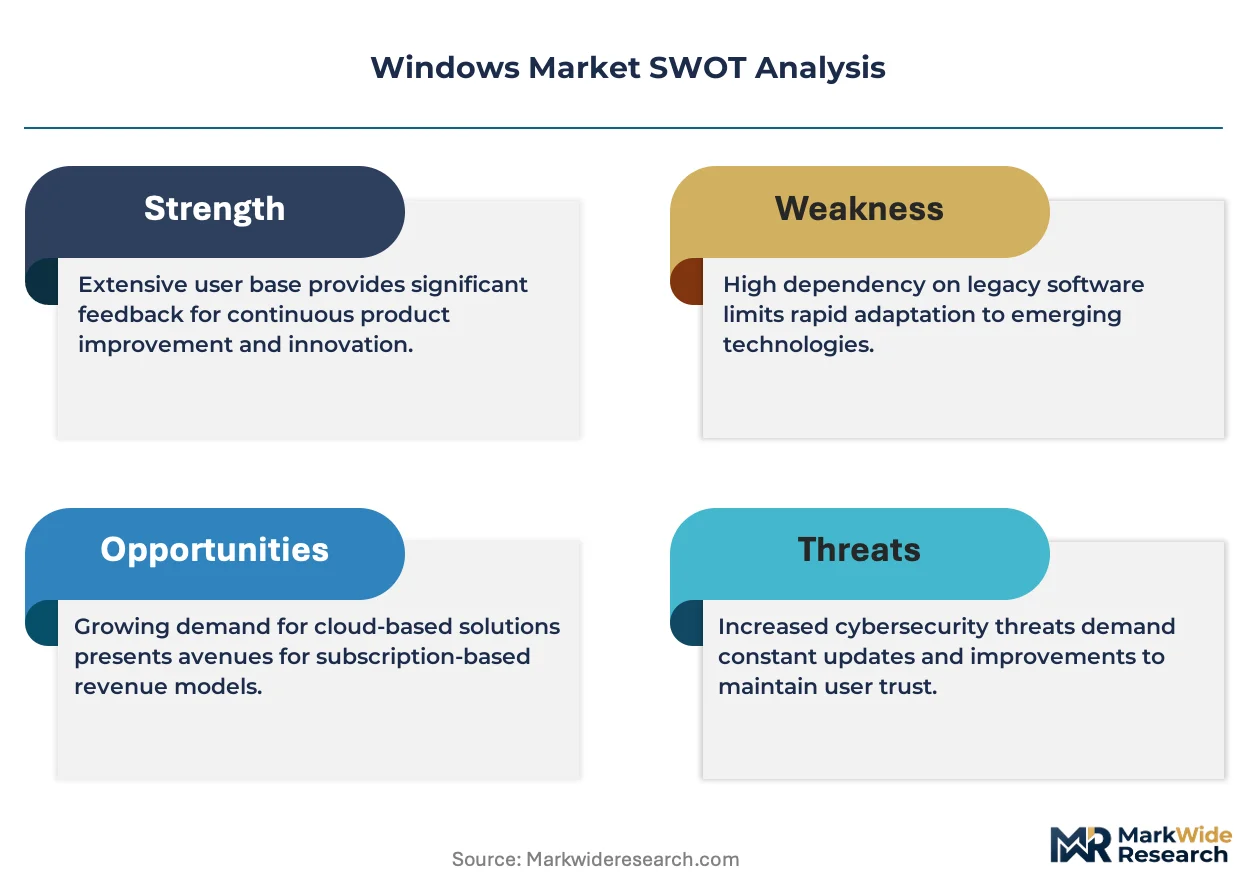
The ISO 27500 standard for integrated fenestration electronics is collapsing the barrier between traditional building materials and high-technology sectors. Technology firms like Microsoft Corporation are positioning their IoT platforms as the operating system for smart building envelopes. Hardware specialist Intel develops low-power processors specifically for embedding into window frames. Meanwhile, Hewlett-Packard leverages its expertise in display technology to explore interactive glass surfaces for commercial applications.
Windows, in this context, refer to architectural fenestration products integrated with electronic components like sensors, processors, and dynamic glazing. Their primary purpose is to dynamically control light, heat, and privacy while connecting to a building's central management system. While vinyl and aluminum frames remain dominant in residential applications due to cost, the commercial buildings sector shows a clear preference for advanced composite and fiberglass materials. This creates a value split, with higher margins concentrated in technically complex commercial projects.
Product development is heavily influenced by energy efficiency mandates, including the US EPA's ENERGY STAR program and the EU's Energy Performance of Buildings Directive. Concurrently, data privacy rules like GDPR in Europe and state-level regulations in the United States govern the information collected by smart window sensors. Manufacturers must now decide whether to develop proprietary electronics in-house or partner with established technology firms to remain competitive.
Market Dynamics
The convergence of building materials with high-technology electronics, driven by energy efficiency regulations and IoT integration, is the central force structuring the market. This creates a clear value split between commoditized residential applications and advanced, high-margin commercial projects.
Growth Catalysts
- Energy Mandates:The EU's Corporate Sustainability Reporting Directive and the US EPA's ENERGY STAR program compel commercial building owners to invest in high-performance fenestration to meet new reporting and performance standards.
- Smart Building Integration:Demand for connected buildings in high-tech commercial real estate within the United States, Japan, and Germany accelerates adoption of windows with embedded sensors that link to central management systems.
- Material Science Advances:The development of advanced composite and fiberglass frames provides the structural integrity and thermal performance required for larger, more complex smart glass installations in premier commercial buildings.
Market Restraints
- High Initial Cost:The significant price premium for smart glass and advanced composite frames compared to traditional vinyl or aluminum limits adoption in cost-sensitive residential and building retrofit projects.
- Integration Complexity:A lack of standardization across building management system protocols creates significant technical hurdles and costs for integrating smart windows from different vendors into a unified building envelope.
- Data Privacy Compliance:Navigating disparate data privacy rules, such as GDPR in Europe and various state-level laws in the US, adds complexity and liability risk to the deployment of sensor-equipped windows.
Strategic Opportunities
- Commercial Building Retrofits:Targeting the vast stock of existing commercial buildings for energy efficiency upgrades with smart fenestration offers a substantial growth avenue beyond the new construction segment.
- Interactive Surface Applications:Leveraging display technology to develop interactive glass surfaces for retail, corporate, and advertising applications opens new, high-margin revenue streams beyond traditional window functions.
- Proprietary Electronics Platforms:Developing in-house electronics and software platforms allows manufacturers to capture more value, control the user experience, and create a competitive moat against pure-play technology firms.
Industry Challenges
- Hybrid Skill Requirements:A shortage of technicians and engineers skilled in both building science and embedded electronics hinders installation, maintenance, and product development across the industry.
- Certification and Compliance Delays:The lengthy and expensive process of securing certifications like ENERGY STAR for new, technologically complex window systems can slow down time-to-market for innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Windows Market |
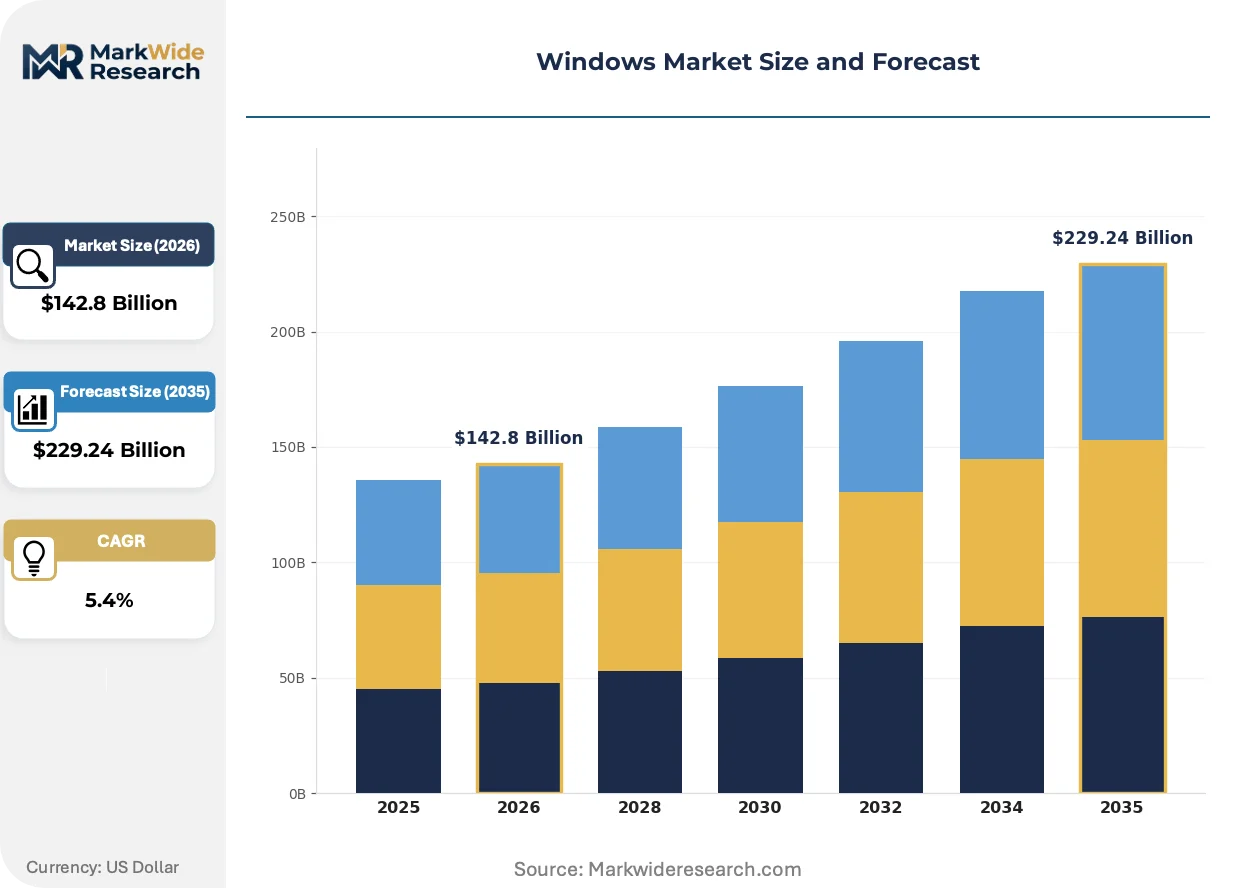
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $229.24 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement, Sliding, Awning, Bay, Fixed Material: Vinyl, Aluminum, Wood, Fiberglass, Composite Application: Commercial Buildings, Residential Homes, Educational Facilities, Institutional Establishments Distribution Channel: Specialty Stores, Home Improvement Centers, Online Retailers, Direct Sales |
| Companies Covered | Dell Technologies, Lenovo, Microsoft Corporation, Acer, ASUS, Intel, Hewlett-Packard, MSI, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Windows Market Strategic Shifts & Innovations
The transformation of architectural windows from passive building components into active, data-generating nodes of a smart building envelope is the defining trend. This shift redefines product value, competitive dynamics, and the required core competencies for manufacturers.
Integrated fenestration electronics combine sensors, low-power processors, and dynamic glazing into a single unit. The commercial real estate sector is the primary adopter, seeking dynamic control over light and heat. This convergence is decomposing the traditional barrier between building material suppliers and high-technology firms, forcing new partnerships and competitive alignments.
Regulatory frameworks such as the European Union's Corporate Sustainability Reporting Directive (CSRD) create direct financial incentives for energy efficiency. This regulation directly incentivizes investment in auditable, high-performance building technologies, including smart windows that can provide verifiable energy savings data. Commercial building projects in the EU are most affected, prioritizing fenestration with documented performance.
A shift from component-based purchasing to solution-based procurement is evident. Instead of buying windows as standalone products, developers of high-tech commercial properties now specify integrated facade systems that include dynamic glazing, controls, and software. This trend is most pronounced in new commercial developments in Germany and the United States.
Windows Market Segmentation
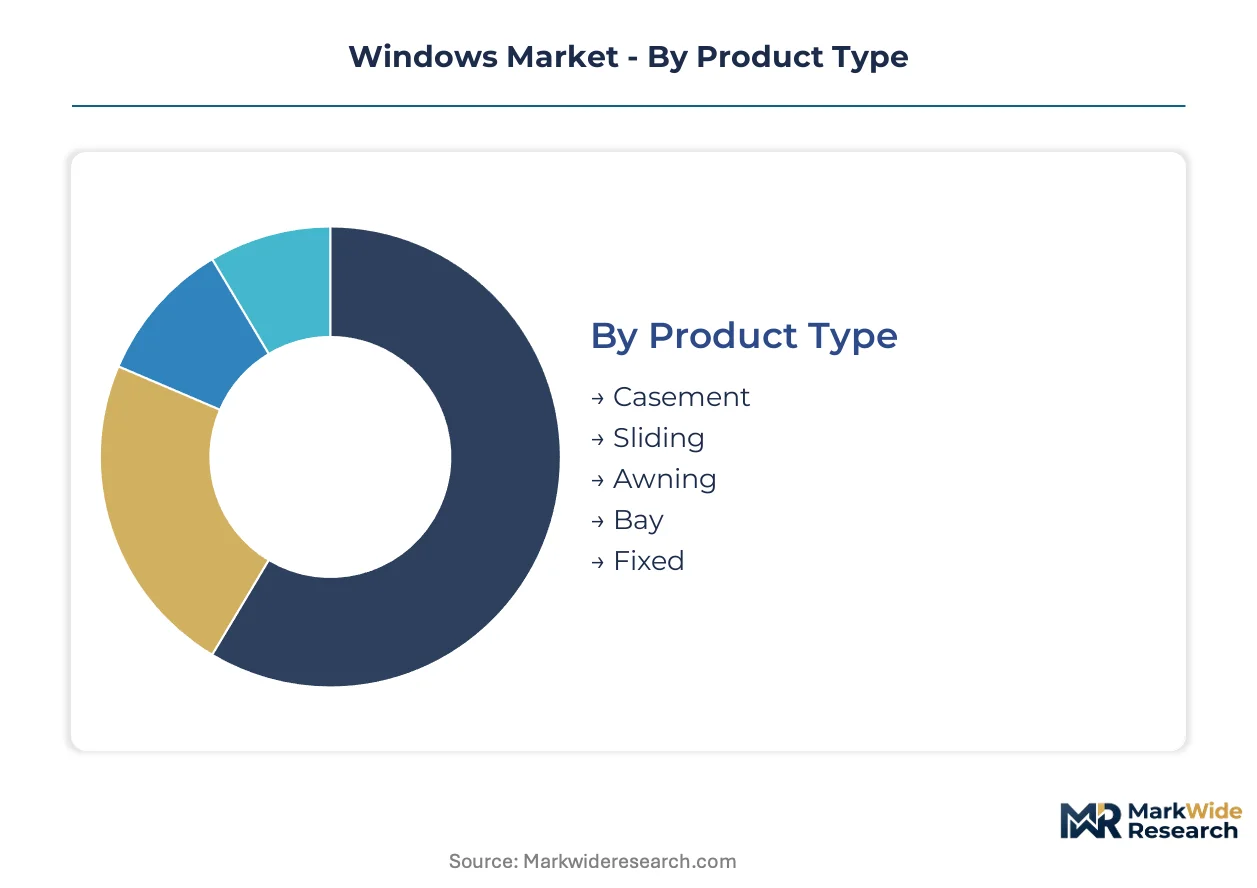
Understanding the varied segments within the windows market allows manufacturers and suppliers to precisely target product development and sales strategies. This granular view reveals where value concentrates across different product types, materials, applications, and distribution channels. Strategic alignment with these segments drives market penetration and profitability.
Product Type:
The diverse product types for windows are supplied through varied channels, each catering to specific aesthetic and functional demands across building projects.
- Casement:These windows feature a hinge on one side, opening outward like a door, offering excellent ventilation and airtight seals when closed. Demand concentrates in energy-efficient commercial buildings and high-end residential renovations in Germany, driven by stringent thermal performance requirements.
- Sliding:Characterized by sashes that slide horizontally or vertically within the frame, sliding windows are common in both residential and commercial applications due to their space-saving design. Their adoption in US residential housing is significant, favored for ease of operation and cost-effectiveness.
- Awning:Hinged at the top, awning windows open outward from the bottom, providing ventilation while protecting interiors from light rain.
- Bay:Projecting outward from the main wall of a building, bay windows create additional interior space and enhance natural light.
- Fixed:Fixed windows are non-operable units designed solely for admitting light and providing an unobstructed view.
By volume, Sliding windows lead. By growth pace, Casement windows are ahead.
Material:
Material choices for window frames directly influence their suitability across different building applications, impacting durability, insulation, and maintenance requirements.
- Composite:Formed from a blend of materials such as wood fibers and polymers, composite frames offer superior strength, thermal performance, and moisture resistance. High-tech commercial real estate developments in Japan increasingly specify composite frames for their longevity and integration with smart glazing systems.
- Fiberglass:Constructed from glass fibers and resin, fiberglass frames exhibit exceptional strength-to-weight ratios, dimensional stability, and resistance to extreme temperatures. Commercial building projects in the United States prioritize fiberglass for its durability and minimal thermal expansion.
- Vinyl:Made from polyvinyl chloride (PVC), vinyl frames are a popular choice for residential applications due to their affordability and low maintenance.
- Aluminum:Known for its strength and slim profiles, aluminum frames are often used in modern architectural designs and commercial storefronts.
- Wood:Traditional wood frames offer natural aesthetics and good insulation properties, frequently chosen for historical renovations and premium residential homes.
Commercial projects favor advanced materials for performance, while residential applications prioritize cost-effective solutions.
Application:
The application segments reflect distinct margin profiles, with specialized installations commanding higher returns for integrated window solutions.
- Commercial Buildings:This segment includes office complexes, retail spaces, and hospitality venues, where demand for energy-efficient smart glass and integrated building management systems is paramount. Projects in major urban centers across the United States and Germany drive significant value due to stringent energy mandates like the EU's CSRD.
- Residential Homes:Encompassing single-family homes and multi-unit dwellings, this segment focuses on balancing cost-effectiveness with aesthetic appeal and basic thermal performance. Cost-sensitive homeowners typically select standard window solutions, limiting advanced technology adoption.
- Educational Facilities:Schools and universities require durable, secure, and energy-efficient windows that contribute to a comfortable learning environment.
- Institutional Establishments:This segment covers hospitals, government buildings, and other public facilities, demanding robust security features and specific performance standards.
Commercial building demand represents the fastest-growing segment for integrated fenestration solutions.
Distribution Channel:
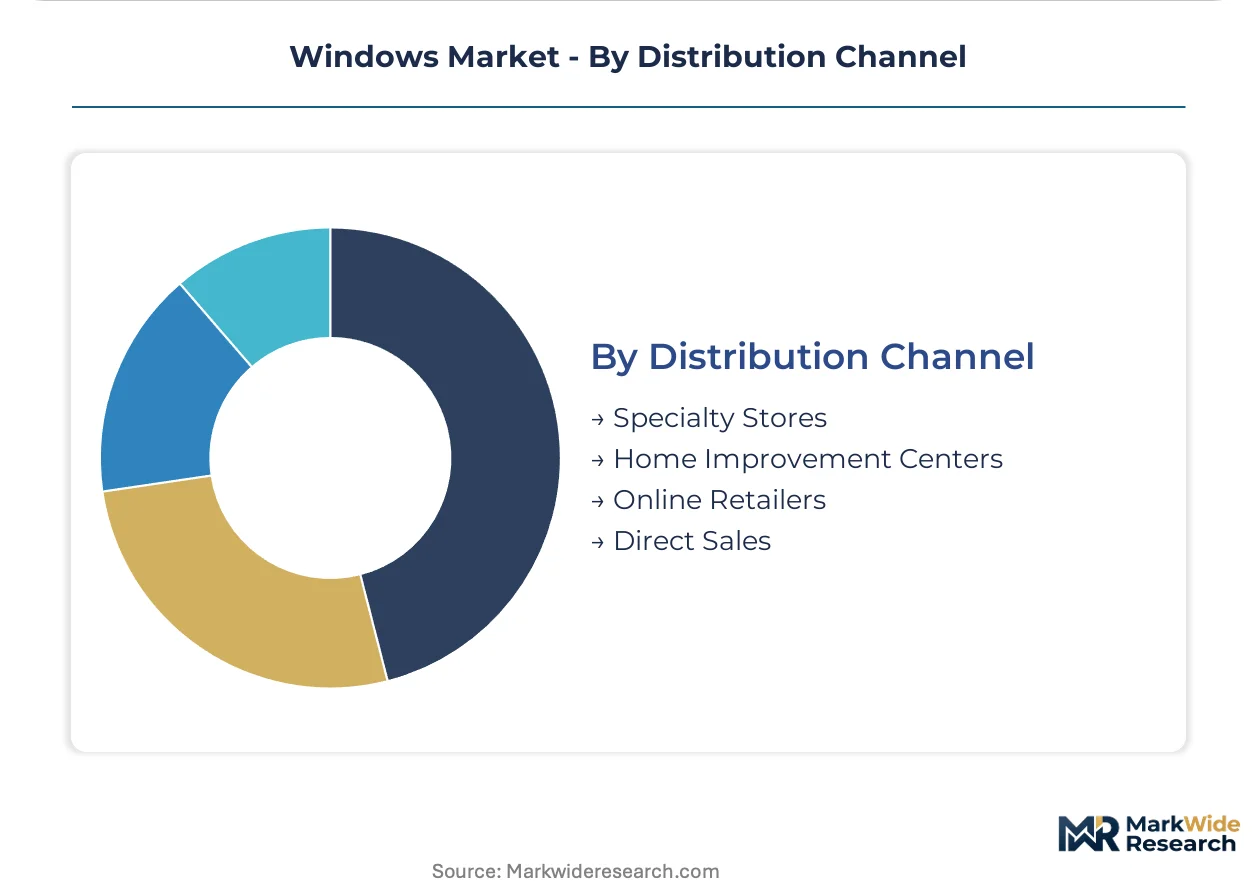
Different customer types prefer specific distribution channels for window procurement, influencing sales volume and service expectations.
- Direct Sales:Manufacturers engage directly with commercial developers, architects, and large-scale builders for custom projects, offering tailored solutions and technical support. This channel captures high-value, complex installations for smart building envelopes in major commercial hubs.
- Home Improvement Centers:These retail outlets cater primarily to residential customers and small contractors, offering a range of standard window products for DIY installations or smaller renovation projects. Volume sales for vinyl and aluminum windows are substantial through these channels.
- Specialty Stores:These retailers focus on niche markets, providing high-end, custom, or architecturally specific window solutions.
- Online Retailers:E-commerce platforms offer convenience and a broad product selection, appealing to budget-conscious consumers and those seeking specific product configurations.
Direct sales channels capture high-value commercial projects, while retail outlets service broader residential demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-tech commercial real estate developers, particularly those focused on smart building envelopes, drive concentrated demand for advanced fenestration solutions across key global markets. These buyers prioritize integrated electronic components and energy efficiency to meet stringent performance metrics. Regulatory frameworks significantly influence market dynamics, creating distinct growth opportunities in specific geographies.
United States
The United States market exhibits strong demand for smart windows in new commercial developments, particularly in high-tech real estate. US EPA's ENERGY STAR program encourages the adoption of energy-efficient fenestration, providing incentives for high-performance products. Major urban centers like New York City are seeing significant investment in integrated facade systems for corporate campuses.
Germany
German commercial buildings require advanced fenestration due to strict energy efficiency mandates and a focus on sustainable construction. The EU's Corporate Sustainability Reporting Directive (CSRD) compels businesses to invest in auditable, high-performance building technologies. Frankfurt's financial district consistently adopts smart glass solutions for its premier office towers.
Japan
Japanese commercial property developers seek durable and technologically integrated window solutions, emphasizing longevity and advanced composite frames. METI's energy efficiency targets drive investment in high-performance building envelopes for new and existing structures. Tokyo's commercial districts are at the forefront of implementing interactive glass surfaces in modern architecture.
China
China's rapid urbanization and ambitious green building initiatives fuel substantial demand for energy-efficient fenestration in commercial projects. The nation's dual carbon goals incentivize developers to integrate advanced smart window technologies for verifiable energy savings. Shanghai's Pudong New Area showcases numerous high-rise developments featuring dynamic glazing systems.
United Kingdom
United Kingdom commercial building owners increasingly invest in smart windows to meet decarbonization targets and enhance operational efficiency. UK Building Regulations Part L mandates improved energy performance for new and refurbished non-domestic buildings. London's Canary Wharf district frequently integrates advanced fenestration into its iconic commercial towers.
Windows Market Key Industry Players
Player mix skews toward established technology firms and traditional building material manufacturers, creating a hybridized competitive environment. This market structure reflects a tension between high-tech innovation and established construction practices. Strategic archetypes include IoT platform providers, hardware specialists for embedded electronics, and integrated fenestration solution providers. Dominant competitive moves involve strategic partnerships between tech giants and window manufacturers, alongside the development of proprietary electronics platforms.
Within the high-technology segment, Microsoft Corporation exemplifies the strategy of positioning IoT platforms as the operating system for smart building envelopes, connecting various building components. Hardware specialist Intel develops low-power processors specifically for embedding into window frames, enabling advanced data collection, local processing, and connectivity for dynamic glazing. Meanwhile, Hewlett-Packard leverages its extensive expertise in display technology, representing the exploration of interactive glass surfaces for novel commercial applications. These firms collectively underscore the critical role of technology integration in redefining traditional fenestration products and expanding their functional capabilities within smart infrastructure.
| Leading Market Players |
|---|
| Dell Technologies |
| Lenovo |
| Microsoft Corporation |
| Acer |
| ASUS |
| Intel |
| Hewlett-Packard |
| MSI |
| Samsung Electronics |
| Others |
Cost & Logistics Intelligence
The EU's Corporate Sustainability Reporting Directive (CSRD) gates both supply qualification and price differentiation for advanced fenestration solutions in European commercial markets. This regulatory framework compels manufacturers to provide auditable performance data, influencing material sourcing and technology integration.
Pricing Analysis
Project-based contracts with material cost indexation dominate pricing for complex commercial smart window installations. Price differentiation stems from the integration of smart glazing systems, advanced composite materials, and specific certification levels like ENERGY STAR. Pricing pressure on standard vinyl and aluminum windows for residential applications is high, driven by cost-effectiveness. Commercial developers, seeking integrated facade systems, exhibit the least price sensitivity, valuing long-term energy savings and building performance.
Supply Chain Analysis
Specialized glass fabrication capacity underwrites the supply chain for smart windows, particularly for dynamic glazing. Raw material dependencies include advanced glass, low-power processors, and composite resins. Geographic supply concentration for these critical components centers on Japan for advanced composites and Germany for high-tech electronics, alongside broader glass manufacturing in China. Single-source vulnerability for highly specialized embedded electronics represents a structural risk. Direct sales channels manage distribution for high-value commercial projects, while home improvement centers serve the broader residential market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires an integrated expertise, blending traditional building science with advanced embedded electronics. This hybrid skill gap creates a scarcity of talent across the value chain, impacting product development and complex installations.
For Market Incumbents: Fortify core competencies in building materials by strategically partnering with technology firms specializing in IoT platforms and embedded electronics. This mitigates the threat from pure-play tech companies entering the fenestration space. Invest in hybrid R&D programs that integrate advanced glass with low-power processors, leveraging existing manufacturing scale. Develop internal certification expertise to streamline compliance with evolving energy efficiency mandates.
For New Entrants and Emerging Players: Anchor in niche applications within the commercial building retrofit segment, focusing on verifiable energy savings for older structures. Target specific geographies like emerging urban centers in the United States and Germany that are prioritizing sustainable redevelopment. A go-to-market angle emphasizing solution-based procurement, bundling smart windows with installation and ongoing system management, offers a compelling value proposition.
For Investors and Strategic Acquirers: The EU's Corporate Sustainability Reporting Directive reshapes the acquisition landscape, favoring firms with robust data-gathering and reporting capabilities for energy performance. Long-term viability rests on companies capable of delivering integrated smart building envelope solutions. Target acquisition archetypes include specialized manufacturers of dynamic glazing or embedded electronics firms with established partnerships in the construction sector. Watch for increasing vertical integration efforts by either building material or technology giants as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Strategic Partnerships | Collaboration between tech firms and manufacturers accelerates integrated solution development for smart buildings. |
| R&D in Integrated Systems | Investment in smart glass, sensors, and processors enhances dynamic control and energy efficiency. |
| Talent Development Programs | Cultivating hybrid skill sets in building science and electronics addresses critical industry shortages. |
| Certification Investment | Achieving ENERGY STAR and ISO 27500 compliance validates product performance for commercial buyers. |
| Expansion into Retrofits | Targeting existing commercial building stock unlocks substantial growth beyond new construction. |
Research Approach
Operator-level perspectives from commercial developers, architects, building material manufacturers, and technology firm product managers anchored the qualitative base for this analysis. These primary insights were rigorously validated against secondary data sources, including industry reports, company financial filings, government energy mandates from the US EPA and EU, and building codes. The research employed both bottom-up and top-down triangulation to ensure comprehensive data consistency.
Sensitivity analysis framed the quantitative projections across the analysis window, integrating various market scenarios. Segmentation dimensions modeled included product type, material, application, distribution channel, and regional demand across key geographies like the United States, Germany, and Japan. Compound annual growth rates were derived from historical data trends and projected adoption rates, with smart glass penetration and commercial construction spending serving as key forecast inputs.
Decision-makers should treat outputs as directional under continued energy efficiency regulation and sustained investment in smart building technology; material deviation would warrant model refresh. Forecasts reflect these base assumptions. Practitioners should keep alternative scenarios live as economic downturns impacting commercial construction or rapid shifts in data privacy laws evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Products & Utilities
Wine Cabinets Market
Home Products & Utilities
US Aromatherapy Diffusers Market
Home Products & Utilities
Photo Frame Market
Home Products & Utilities
Europe Aromatherapy Diffuser Market
Home Products & Utilities
Mosquito Screen Doors Market
Home Products & Utilities
Storage Basket Rack Market
Home Products & Utilities
North America Aromatherapy Diffuser Market
Home Products & Utilities
Middle East and Africa Aromatherapy Diffuser Market
Home Products & Utilities
Global Stair Lifts Market
Home Products & Utilities
Netherlands Sustainable Mattress Market